
 Italy Lubricants Market | 2026-2036
Italy Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Lubricants Market Foresight
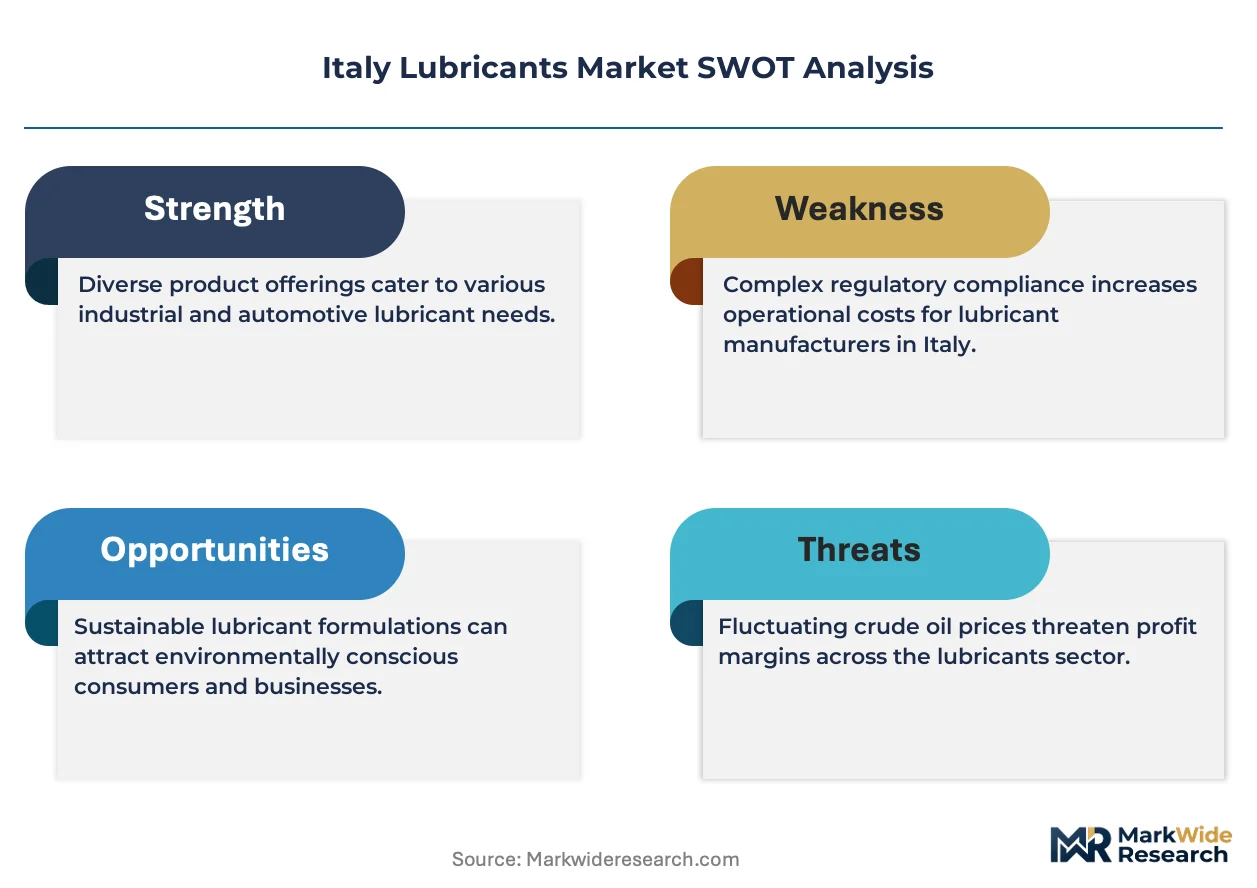
Automotive electrification is restructuring lubricant demand across Italy's transport sector, reducing engine oil volumes while expanding thermal management fluid needs. Eni leverages its Ravenna refinery complex and synthetic base oil capacity to anchor supply security for domestic OEMs. Shell Plc competes through its Milan technical center, where formulation R&D targets extended-drain intervals for commercial fleets. Fuchs specializes in metalworking and industrial gear lubricants, occupying a defensible position among Emilia-Romagna's machine tool builders.
Lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with viscosity grades typically spanning ISO VG 32 through 680 for industrial applications and SAE 5W-30 through 15W-40 for automotive engines. Their primary commercial purpose centers on extending equipment life and optimizing energy efficiency across powertrain and manufacturing systems. Engine oil retains the largest revenue share within the product type dimension, though biodegradable oil and ester base stocks are gaining traction as REACH restrictions on mineral oil discharges tighten. Within the application dimension, industrial machinery lubrication generates stable aftermarket demand from Italy's fragmented metalworking and packaging equipment base, while marine applications face structural pressure from Mediterranean port emission controls.
Italy's lubricant sector operates under REACH chemical registration requirements, EU F-Gas Regulation constraints on fluorinated lubricant components, and national transpositions of the EU Green Deal industrial decarbonization framework. These standards elevate compliance costs for mineral oil formulations while creating preferential market access channels for synthetic and bio-based alternatives certified through ECHA-recognized assessment protocols. Stakeholders must monitor the interaction between EU ETS carbon pricing expansion and base oil import sourcing economics to anticipate margin compression points in the Italian blending value chain.
Market Dynamics
Fleet electrification across Italy's automotive and transport sectors is compressing traditional engine oil volumes while simultaneously expanding demand for thermal management fluids and specialized e-axle lubricants.
Growth Catalysts
- EU Green Deal industrial decarbonization:Mandates for carbon-intensive manufacturing sectors are accelerating adoption of synthetic and bio-based lubricant formulations that reduce Scope 3 emissions across Italian industrial supply chains.
- Lombardy machinery corridor concentration:Dense clustering of metalworking, packaging, and textile equipment manufacturers generates stable aftermarket demand for high-performance industrial lubricants with extended service intervals.
- REACH chemical registration requirements:Compliance pressures on mineral oil discharges are redirecting formulator R&D investments toward biodegradable ester base stocks and lower-viscosity synthetic alternatives.
Market Restraints
- Base oil import dependency:Italy's blending sector relies heavily on Group II and III base stock imports from Middle Eastern and Asian refiners, exposing margins to shipping cost volatility and currency fluctuation.
- Fluorinated component constraints:EU F-Gas Regulation phase-down schedules are restricting availability of perfluoropolyether lubricants critical for aerospace and semiconductor manufacturing applications.
- Mineral oil substitution acceleration:Synthetic and bio-based alternatives are capturing formulation share in premium segments, eroding volume economics for traditional paraffinic base stock producers.
Strategic Opportunities
- Emilia-Romagna machine tool builder networks:Specialized metalworking fluid requirements among precision machining OEMs create defensible niches for high-performance neat cutting oils and micro-emulsion coolants.
- Extended-drain interval technology:Additive packages enabling 50,000+ kilometer service intervals for commercial fleets align with total cost of ownership reduction priorities among logistics operators.
- Mediterranean marine emission controls:Port of Genoa and Port of Venice enforcement of IMO 2020 sulfur limits is stimulating demand for cylinder lubricants compatible with ultra-low sulfur fuel operations.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in tribology and additive chemistry is concentrating among retiring professionals, constraining R&D pipeline velocity for domestic blenders.
- ECHA registration timelines:Novel bio-based base stock substances face 18-24 month assessment windows, delaying product commercialization and first-mover advantage capture.
- Legacy equipment compatibility:Lower-viscosity synthetic formulations require seal material upgrades in aging Italian industrial machinery, complicating retrofit economics for small and mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Lubricants Market |
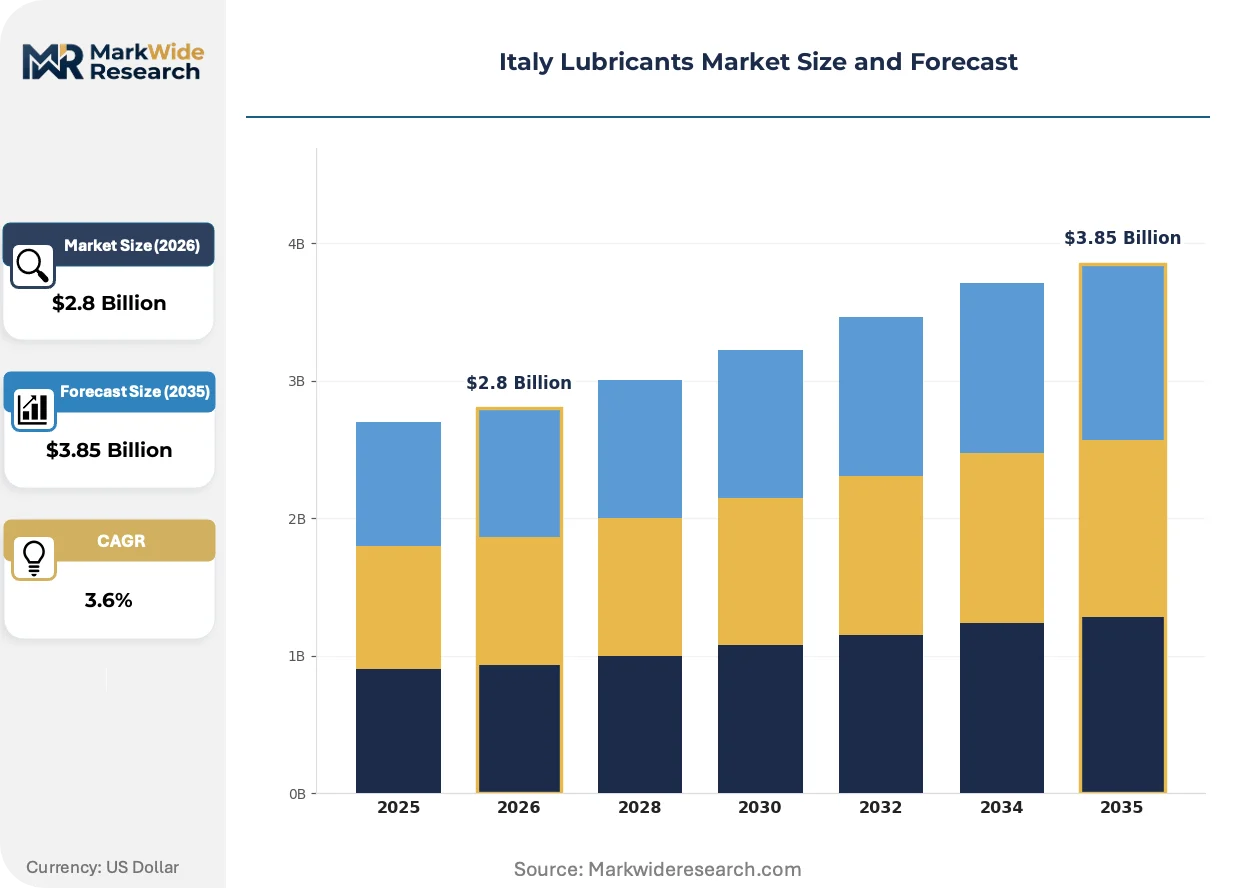
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.85 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluid, Grease Application: Automotive, Industrial Machinery, Marine, Aerospace Base Oil: Mineral Oil, Synthetic Oil, Biodegradable Oil, Esters End User: OEMs, Aftermarket Providers, Retailers, Service Stations |
| Companies Covered | Shell Plc, Fuchs, Eni, Repsol, Kuwait Petroleum Corporation, BP Plc (Castrol), TotalEnergies SE, Liqui Moly, Exxon Mobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Lubricants Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine competitive advantage in Italy's lubricant sector, with sustainability credentials and performance metrics now inseparable in procurement decisions.
Polyalkylene glycol synthetic base stocks are rewriting thermal stability benchmarks for electric vehicle battery cooling systems and power electronics. Tier 1 automotive suppliers in Turin's supplier network are qualifying these fluids for 150,000-kilometer lifetime requirements. The technology is compressing conventional glycol-water mixture volumes while commanding formulation premiums in OEM specification programs.
REACH restrictions on mineral oil aromatic content are forcing reformulation of metalworking fluids across Lombardy's manufacturing belt. The regulation's 2025 sunset dates for certain polycyclic aromatic hydrocarbon classifications are accelerating blender transitions to hydrotreated Group III and gas-to-liquid base stocks. Metalworking segments serving aerospace and medical device sub-suppliers face the steepest compliance cost escalations.
Fleet maintenance contracts are consolidating lubricant procurement authority among Italy's largest transport and logistics operators. Third-party fleet management providers are displacing decentralized workshop purchasing, centralizing volume commitments and demanding performance guarantees. This concentration is most visible in the Milan-Bologna freight corridor where multi-brand service networks are standardizing fluid specifications across mixed European and Asian truck fleets.
Italy Lubricants Market Segmentation
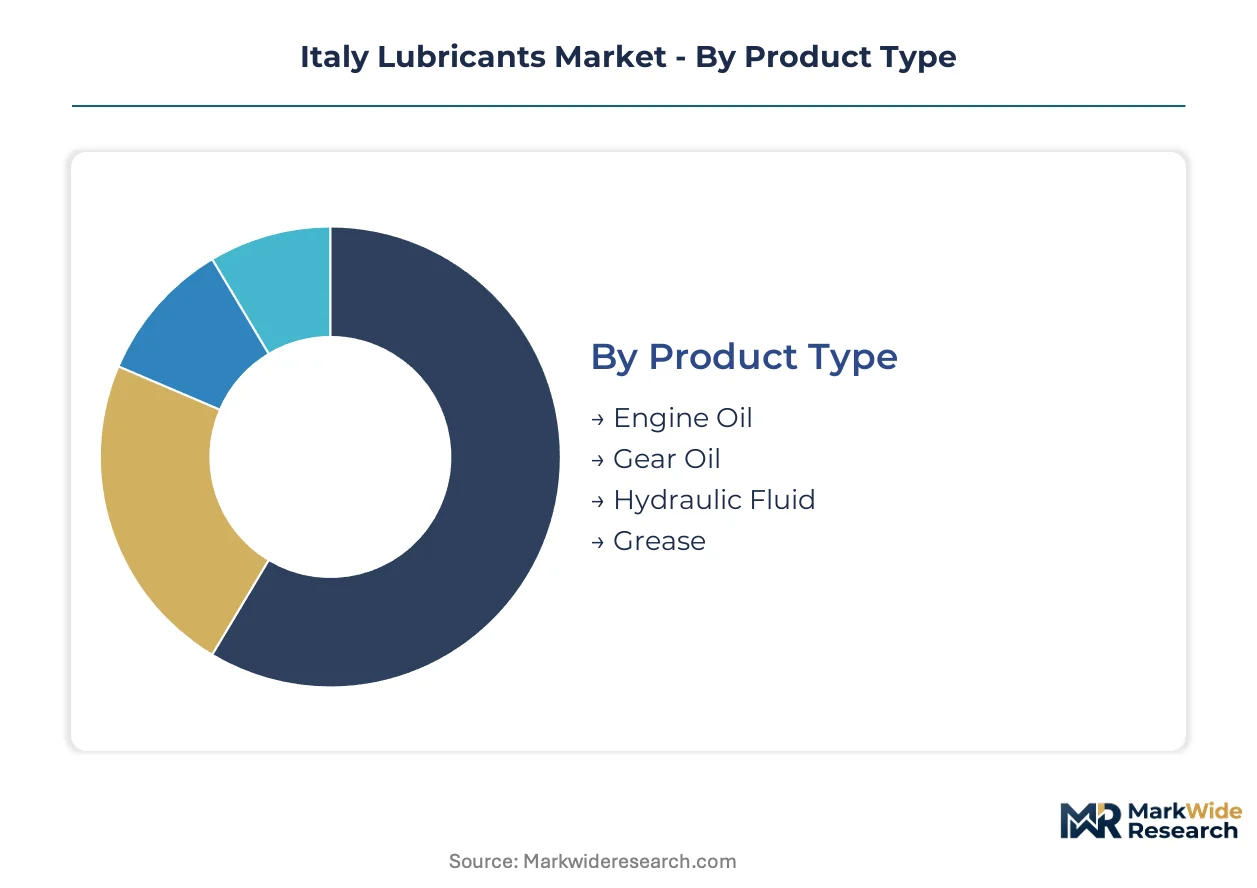
Segmentation reveals how electrification and REACH compliance are fragmenting Italy's lubricant demand across incompatible technical specifications. Each dimension exposes distinct margin pressures and capital allocation priorities for blenders navigating synthetic transition costs.
Product Type:
Capital intensity varies sharply across formulation categories, with synthetic base stock requirements and additive complexity driving investment thresholds.
- Engine Oil:Blends of base oils with detergent, dispersant, and anti-wear additive packages meeting ACEA and API service categories. Demand concentrates in Turin's automotive supplier corridor where electrification is compressing volumes for internal combustion powertrains while extending drain intervals.
- Hydraulic Fluid:Anti-wear formulations with viscosity index improvers and oxidation inhibitors for power transmission systems. Lombardy's metalworking and plastics machinery clusters generate stable aftermarket demand for ISO VG 32-68 grades with extended service life requirements.
- Gear Oil:Extreme-pressure lubricants with sulfur-phosphorus additive chemistry for enclosed gearboxes. Emilia-Romagna's precision machine tool sector specifies synthetic polyalphaolefin grades for high-load cutting operations.
- Grease:Thickened lubricants combining base oils with metallic soap or complex thickener structures for bearings and chassis points. Italian railway maintenance depots and agricultural equipment service networks drive volume for lithium and calcium sulfonate formulations.
Most installed capacity flows through Engine Oil. Expansion is steepest in Hydraulic Fluid.
Application:
Customer procurement authority determines margin capture, with fleet consolidation concentrating volume among fewer decision-makers.
- Automotive:Light-duty and commercial vehicle lubrication spanning engine, transmission, and axle applications. The Milan-Bologna freight corridor's third-party logistics operators are standardizing specifications across mixed European and Asian truck fleets through centralized maintenance contracts.
- Industrial Machinery:Metalworking, packaging, and textile equipment lubrication across manufacturing value chains. Lombardy's dense clustering of machinery OEMs generates recurring aftermarket demand for high-performance neat cutting oils and synthetic hydraulic fluids.
- Marine:Cylinder and system lubricants for Mediterranean commercial shipping. Port of Genoa and Port of Venice enforcement of IMO sulfur limits is stimulating demand for formulations compatible with ultra-low sulfur fuel operations.
- Aerospace:Specialized lubricants for turbine engines, landing gear, and control systems. EU F-Gas Regulation constraints on perfluoropolyether availability are restricting supply for semiconductor and precision aerospace manufacturing applications.
Automotive commands the largest revenue pool. Industrial Machinery is gaining share fastest.
Base Oil:
Regulatory chemistry is redefining competitive positioning, with REACH compliance costs fragmenting the supplier landscape.
- Mineral Oil:Refined petroleum distillates classified as Group I, II, or III per API base oil categories. REACH restrictions on polycyclic aromatic hydrocarbon content are accelerating substitution in metalworking and marine segments serving aerospace and medical device sub-suppliers.
- Synthetic Oil:Manufactured base stocks including polyalphaolefins, polyalkylene glycols, and gas-to-liquids products. Polyalkylene glycol thermal stability benchmarks are qualifying these fluids for electric vehicle battery cooling systems in Turin's Tier 1 automotive supplier network.
- Biodegradable Oil:Vegetable oil and synthetic ester formulations meeting OECD 301B biodegradability thresholds. Lombardy packaging machinery operators are specifying these grades to comply with discharge permits in water-stressed manufacturing zones.
- Esters:Organic compounds from acid-alcohol reactions providing high lubricity and low-temperature flow. REACH registration timelines of 18-24 months for novel bio-based ester substances are delaying commercialization for domestic blenders.
Mineral Oil retains the largest production footprint. Synthetic Oil is climbing the fastest.
End User:
Channel structure determines pricing power, with specification authority shifting from decentralized workshops to consolidated procurement functions.
- OEMs:Original equipment manufacturers specifying factory-fill and service-fill lubricants for warranty compliance. Turin-based automotive assemblers and Bologna-area packaging machinery builders are qualifying suppliers through extended-drain interval performance guarantees.
- Aftermarket Providers:Independent service networks and fleet maintenance contractors. Third-party fleet management providers in the Milan-Bologna corridor are displacing workshop-level purchasing through centralized volume commitments.
- Retailers:Automotive parts distributors and consumer-facing channels. Do-it-yourself maintenance decline among Italian passenger car owners is compressing volume through traditional retail formats.
- Service Stations:Quick-lube and commercial vehicle service points. Network consolidation among major fuel retailers is standardizing fluid specifications and compressing supplier margins through scale-based procurement.
Aftermarket Providers channel the highest volume velocity. OEMs are expanding specification control most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping lubricant blending economics as REACH compliance costs diverge across European jurisdictions. Formulators face divergent cost structures depending on national transpositions of EU chemical registration requirements.
Lombardy
Metalworking fluid demand concentrates in Milan's machinery belt where packaging and textile OEMs specify extended-drain synthetic hydraulic fluids. Lombardy's regional environmental agency enforces stricter discharge permits than national baselines, accelerating biodegradable oil adoption among water-stressed manufacturers. Brescia's tooling clusters are qualifying polyalkylene glycol grades for precision machining operations.
Piedmont
Turin's automotive supplier network generates specification authority for e-axle lubricants and battery thermal management fluids. The metropolitan government's industrial decarbonization incentives reward synthetic base stock transitions in Tier 1 supplier contracts. Stellantis' Mirafiori complex is driving qualification timelines for 150,000-kilometer lifetime fluid guarantees.
Emilia-Romagna
Machine tool builders in Bologna and Modena specify high-performance neat cutting oils for aerospace and medical device sub-suppliers. The region's implementation of REACH aromatic restrictions precedes national deadlines, forcing earlier reformulation among metalworking fluid blenders. Parma's packaging machinery OEMs are consolidating lubricant procurement through extended service contracts.
Veneto
Port of Venice marine lubricant demand responds to IMO 2020 sulfur limit enforcement on Mediterranean shipping routes. The regional port authority's emission control area designation stimulates cylinder lubricant formulation compatible with ultra-low sulfur fuel operations. Vicenza's goldsmithing and precision manufacturing clusters generate niche demand for specialized industrial greases.
Lazio
Rome's centralized government procurement influences national lubricant standards through public fleet maintenance contracts. The metropolitan area's logistics operators are piloting centralized fluid management systems across multi-brand commercial vehicle fleets. Fiumicino airport's ground service equipment specifications drive demand for aviation-grade hydraulic fluids and greases.
Italy Lubricants Market Competitive Landscape
Portfolio diversification dominates the current landscape as blenders restructure around electrification-driven demand shifts. The supplier base concentrates among integrated oil majors with captive base oil production and specialized industrial formulators with deep metalworking expertise. Three archetypes define competitive positioning: refinery-integrated majors leveraging synthetic base stock capacity, industrial specialists occupying defensible machinery niches, and import-dependent blenders exposed to shipping cost volatility. M&A activity targets biodegradable formulation capabilities while capacity expansion focuses on polyalkylene glycol production for thermal management applications.
Among refinery-integrated majors, Eni anchors domestic supply security through its Ravenna synthetic base oil complex. Shell Plc occupies a position exemplifying technical center-driven formulation R&D, with its Milan facility targeting extended-drain interval development. Fuchs represents the industrial specialist archetype, concentrating metalworking and gear lubricant expertise among Emilia-Romagna's machine tool builders.
| Leading Market Players |
|---|
| Shell Plc |
| Fuchs |
| Eni |
| Repsol |
| Kuwait Petroleum Corporation |
| BP Plc (Castrol) |
| TotalEnergies SE |
| Liqui Moly |
| Exxon Mobil Corporation |
| Others |
Supply & Pricing Matrix
Polyalkylene glycol synthetic base stock adoption for electric vehicle thermal management is simultaneously elevating formulation costs and concentrating procurement leverage among Turin's Tier 1 automotive suppliers. This technology transition compresses margins for import-dependent blenders while rewarding integrated producers with captive synthetic capacity.
Pricing Analysis
Distributor margin capture dominates the Italian lubricant value chain, with industrial fluid resellers commanding 15-25 point markups over refinery gate prices. Three-tier pricing structure across premium synthetic, standard Group III, and economy mineral oil grades reflects REACH compliance cost differentials and OEM certification requirements. Pricing pressure stems from fleet procurement consolidation along the Milan-Bologna corridor, where third-party logistics operators centralize volume and demand performance guarantees. Small and mid-sized metalworking shops exhibit highest price sensitivity, while Stellantis and Ferrari powertrain specifications tolerate substantial premiums for extended-drain validation.
Supply Chain Analysis
Base oil supply rests on Middle Eastern Group II and III refinery output from Saudi Arabia, Kuwait, and Qatar, with Asian Group III capacity from South Korea and Singapore providing swing volumes. Hydrotreated naphthenic feedstocks, polyalphaolefin monomers, and ester base alcohols constitute critical input dependencies. Single-source vulnerability concentrates in polyalkylene glycol specialty grades, where limited European production creates bottleneck risk for EV thermal fluid qualification programs. Distribution runs through Ravenna port terminals and Milan hub warehouses, with just-in-time delivery contracts dominating Lombardy machinery corridor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's lubricant sector functions as a stable compounder anchored by irreplaceable industrial machinery aftermarket demand across Lombardy's dense manufacturing belt. REACH compliance costs and electrification-driven specification shifts create durable competitive moats for integrated formulators.
For Market Incumbents: Lock in synthetic base stock security through backward integration or long-term offtake agreements with Ravenna and European gas-to-liquids producers. Secure OEM qualification timelines for 150,000-kilometer fluid guarantees before Stellantis and Tier 1 suppliers freeze specifications. Defend against biodegradable ester entrants by accelerating ECHA pre-registration of novel base stock substances to extend assessment timelines for competitors. For New Entrants and Emerging Players: Battery thermal management fluid qualification gaps present the most penetrable wedge, as incumbent PAO capacity constraints delay OEM approval cycles. Target Emilia-Romagna precision machine tool builders with REACH-compliant metalworking fluids ahead of 2025 aromatic hydrocarbon sunset dates. Pursue direct technical service relationships with Bologna-area packaging machinery OEMs rather than distributor channel dependence. For Investors and Strategic Acquirers: Roll-up economics work for regional Italian blenders with established Lombardy industrial customer relationships because fleet procurement consolidation is displacing fragmented workshop purchasing. Five-to-ten year viability hinges on synthetic formulation capability positioning ahead of mineral oil substitution acceleration. Monitor ECHA registration timeline compression for novel bio-based esters as inflection indicator for first-mover advantage capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Oil Production | Captive PAO supply secures margin control for Turin EV thermal fluid qualifications. |
| ECHA Pre-Registration Acceleration for Bio-Based Esters | Early filing extends competitive moats through 18-24 month assessment window delays. |
| Extended-Drain Interval Additive Package Development | 50,000+ kilometer guarantees align with Milan-Bologna fleet TCO reduction priorities. |
| Regional Blender Acquisition in Emilia-Romagna | Machine tool builder relationships provide defensible niche against refinery-integrated majors. |
| Direct Technical Service Model Deployment | On-site fluid management displaces distributor markups in Lombardy packaging machinery accounts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant plant managers, OEM procurement leads at Stellantis and Ferrari suppliers, distribution channel partners, and technical R&D directors with secondary validation through customs trade data, UNIDO industrial statistics, SEC filings of listed oil majors, and ECHA registration databases. Bottom-up volume modeling across product type, application, base oil, and end-user segments was triangulated against top-down macroeconomic indicators.
Historical reference periods anchored the projection horizon through backward-looking demand elasticity analysis and forward-looking specification transition timelines. Segmentation dimensions modeled include product viscosity grade, end-use industry cluster, base oil API classification, and regional production hub concentration. CAGRs were derived from trend extrapolation adjusted for electrification-driven demand displacement rates and REACH compliance cost pass-through assumptions, with EV thermal fluid adoption curves and marine sulfur limit enforcement schedules serving as key forecast inputs.
The model holds under stable EU regulatory enforcement and base oil import flow continuity; deviation in Middle Eastern refinery output disruptions or ECHA registration timeline acceleration would shift volume and value trajectories. Forecasts reflect documented assumptions regarding synthetic substitution elasticity and fleet procurement consolidation velocity. A small set of named triggers—ECHA assessment window compression, Stellantis platform electrification pace, and Ravenna refinery synthetic capacity expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Europe Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Mining Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Plastic Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Friction Reducers Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Angola Lubricants Market