
 Singapore Automotive Lubricants Market | 2026-2036
Singapore Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Automotive Lubricants Market Analytics
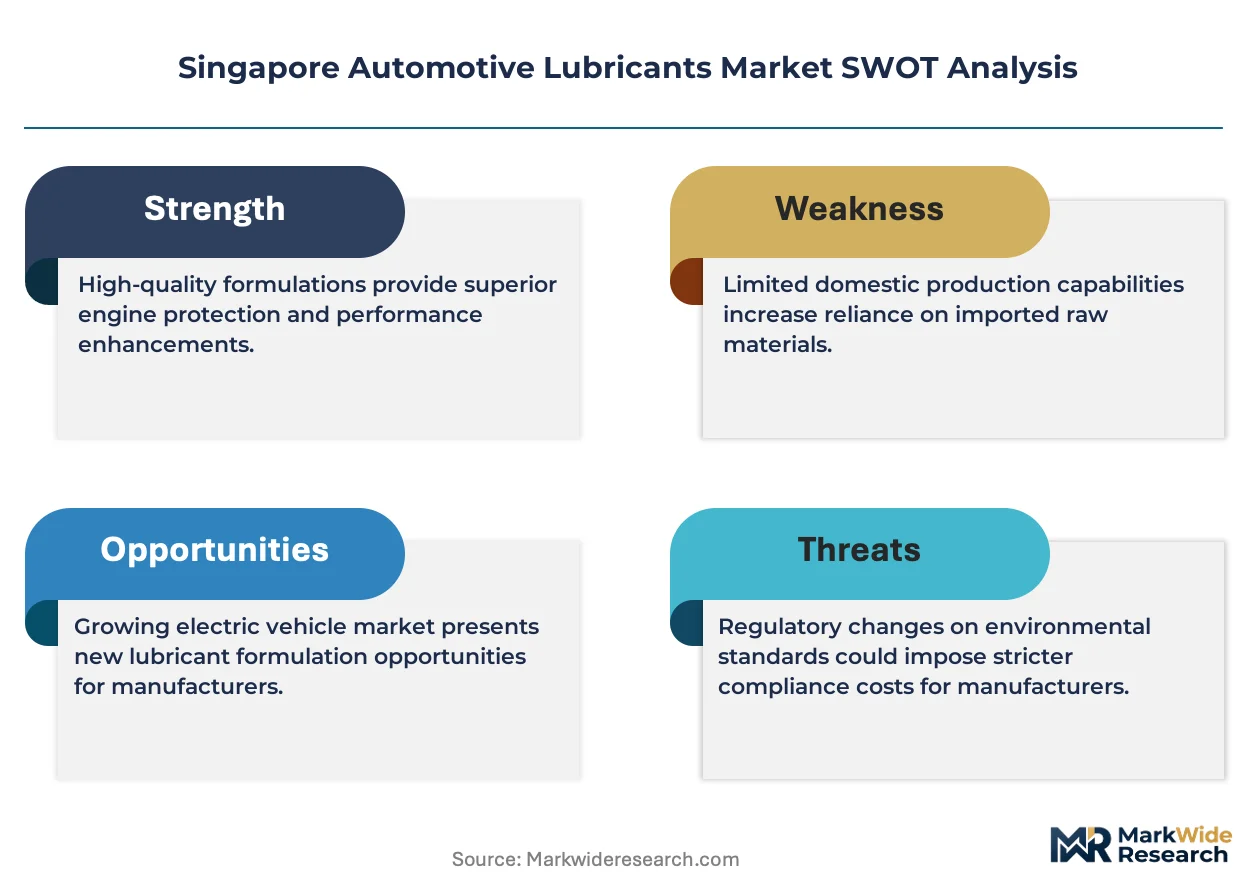
Singapore's Green Plan 2030 is consolidating demand for lower-viscosity, fuel-efficient lubricant formulations across the national vehicle fleet. Shell Singapore Pte Ltd leverages its integrated refining and blending infrastructure on Pulau Bukom to sustain supply continuity for OEM service fill programs. ExxonMobil Singapore anchors its position through backward integration into Group II/III base oil production at its Jurong complex. Chevron Corporation competes via specialized high-performance synthetic offerings targeting premium passenger vehicle segments.
Automotive lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in internal combustion and electric powertrain systems, with viscosity grades typically ranging from 0W-16 to 15W-40 under SAE J300 classification. Engine oil dominates volume consumption as Singapore's aging passenger vehicle parc requires more frequent drain intervals, while synthetic formulations capture margin expansion from fleet operators seeking extended service life. Biodegradable lubricants represent a nascent but structurally significant category as industrial buyers near sensitive marine ecosystems face discharge compliance pressures.
Singapore's National Environment Agency enforces fuel quality and emissions standards that indirectly mandate lubricant performance thresholds, while the country's national chemical regulator administers hazard classification and labeling rules under the Globally Harmonized System. The Land Transport Authority's vehicle inspection regime creates recurring demand for specification-compliant fluids through authorized service channels. Stakeholders must monitor how ASEAN harmonized automotive technical regulations and Singapore's carbon tax trajectory reshape formulation requirements and sourcing economics for base oil imports.
Market Dynamics
Singapore's Land Transport Authority emissions benchmarks are compressing drain intervals and forcing fleet operators toward synthetic formulations with higher performance thresholds. This regulatory compression is reshaping procurement economics across commercial vehicle segments.
Growth Catalysts
- Group III base oil capacity expansion:Local refining infrastructure upgrades enable domestic production of high-viscosity-index feedstocks that reduce import dependency for synthetic blendstocks.
- Jurong Island petrochemical clustering:Proximity of blending facilities to base oil production creates logistics efficiencies that lower working capital requirements for lubricant formulators.
- Carbon tax trajectory under Singapore's Green Plan 2030:Fuel efficiency mandates indirectly elevate lubricant performance specifications, extending synthetic penetration into mid-tier fleet segments previously served by mineral oils.
Market Restraints
- API Group II/III base oil supply concentration:Singapore's dependence on regional refinery output creates input cost volatility when Asian cracking margins tighten.
- Electric powertrain lubricant specification immaturity:Absence of standardized thermal conductivity and dielectric property requirements delays volume scaling for EV-optimized fluids.
- Marine discharge compliance layering:Biodegradable lubricant certification costs from the country's national chemical regulator constrain margin recovery in industrial segments near sensitive coastal zones.
Strategic Opportunities
- Tuas industrial zone fleet densification:Concentration of logistics and construction equipment creates dedicated demand pools for bulk synthetic delivery programs with telemetry-enabled consumption tracking.
- ASEAN harmonized automotive technical regulations:Alignment of lubricant performance classifications across neighboring markets enables Singapore-based blenders to serve export demand with single-specification production runs.
- Extended-drain synthetic formulations:OEM service fill partnerships with commercial vehicle distributors capture lifetime fluid revenue streams through authorized maintenance networks.
Industry Challenges
- Formulation chemist specialization scarcity:Expertise in friction modifier synergy for hybrid thermal management systems remains concentrated among a limited pool of experienced practitioners.
- Used oil re-refining infrastructure capex:Circular economy mandates require investment in vacuum distillation and hydrotreating capacity that strains mid-tier blender balance sheets.
- Multi-standard certification complexity:Simultaneous compliance with SAE J300, ACEA sequences, and OEM proprietary approvals extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Automotive Lubricants Market |
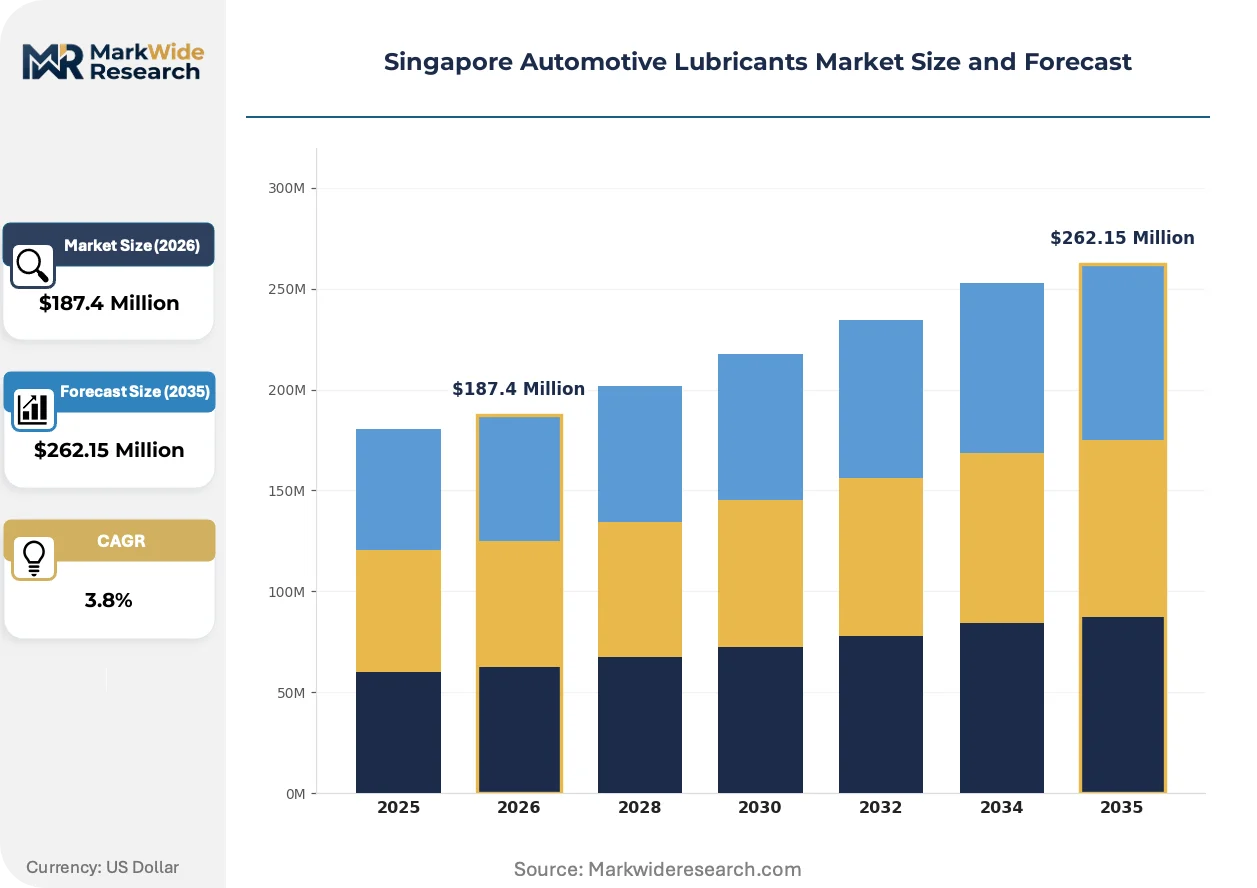
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Fluids, Transmission Fluid End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery Formulation: Synthetic, Semi-Synthetic, Mineral, Biodegradable Distribution Channel: Online Retail, Auto Parts Stores, Service Stations, Supermarkets |
| Companies Covered | Chevron Corporation, Fuchs, Shell Singapore Pte Ltd, Idemitsu Kosan Co Ltd, Motul, ExxonMobil Singapore, TotalEnergies SE, United Oil Company Pte Ltd, BP PLC (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Automotive Lubricants Market Evolving Landscape
Formulation chemistry is pivoting toward thermal stability optimization as powertrain electrification fragments traditional lubricant performance hierarchies. Three distinct vectors are compressing established technical and commercial patterns.
Polyalkylene glycol-based thermal management fluids are absorbing heat rejection loads in hybrid electric vehicle gearboxes that conventional mineral formulations cannot sustain. Fleet maintenance divisions at Singapore's port terminal operators are piloting these chemistries in heavy-duty auxiliary systems. The technology is absorbing service interval extension targets that OEM warranty departments are now writing into powertrain coverage terms.
Singapore's National Environment Agency enforcement of fuel quality standards indirectly mandates lubricant performance thresholds through combustion efficiency requirements. Industrial buyers near the Tuas port district face layered compliance obligations that elevate specification documentation burdens. Commercial fleet procurement departments are responding by consolidating supplier relationships to reduce certification audit complexity.
Telemetry-enabled bulk delivery systems are displacing drum-based procurement for high-volume industrial accounts with predictable consumption patterns. Authorized distributor networks serving Jurong Island process plants are installing tank-level monitoring infrastructure. Singapore's dense geographic footprint makes this channel economics viable at smaller scale thresholds than regional comparators.
Singapore Automotive Lubricants Market Segmentation
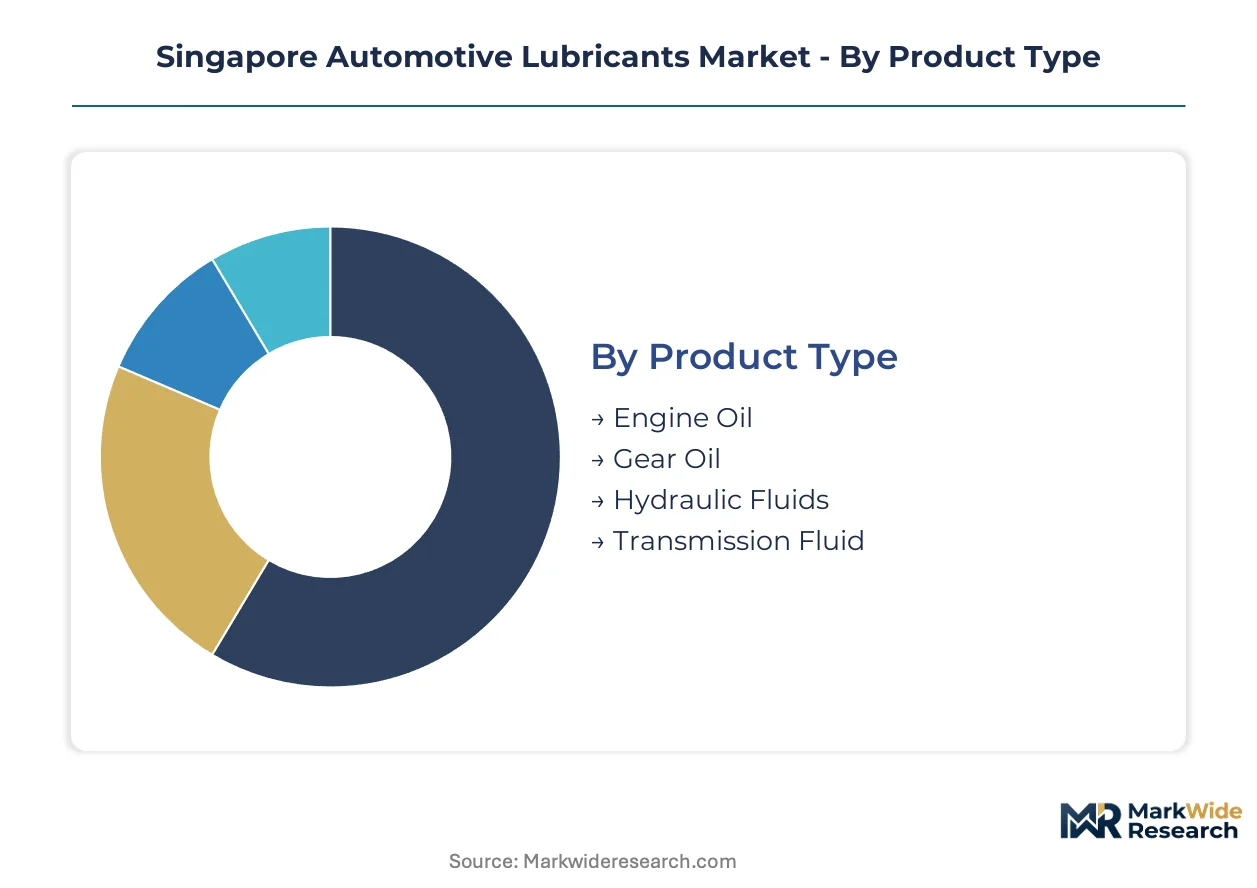
Segmentation in Singapore's automotive lubricants market reveals how procurement patterns fragment across vehicle parc age, fleet ownership structure, and regulatory exposure. Understanding these divisions exposes where formulation premiums collect and where volume concentrates.
Product Type:
Upgrade cycles vary dramatically by product category, with drain interval extension and equipment complexity driving replacement frequency divergence.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages meeting ACEA C sequences or API SP specifications. Demand concentrates in Singapore's aging passenger vehicle parc where OEM warranty requirements enforce specification compliance through authorized service networks.
- Gear Oil:Extreme-pressure lubricants carrying GL-4 or GL-5 ratings for hypoid gear protection under high-torque loads. Fleet operators in Jurong Island's logistics corridors specify synthetic variants for axle differentials exposed to tropical humidity and stop-start duty cycles.
- Hydraulic Fluids:Anti-wear formulations with viscosity grades ISO 32-68 for construction and port equipment power transmission systems.
- Transmission Fluid:Friction-modified blends for automatic and dual-clutch gearboxes, with OEM-specific approvals dominating service fill procurement.
Volume placements concentrate in Engine Oil; the faster expansion belongs to Transmission Fluid as dual-clutch penetration rises in premium passenger segments.
End User:
Cost tier stratification separates price-sensitive owner-operators from fleet procurement departments with total-cost-of-ownership mandates.
- Passenger Vehicles:Individual owners and lease operators maintaining sedans, SUVs, and hatchbacks under Singapore's Certificate of Entitlement regime. Service interval compression from Land Transport Authority emissions enforcement drives synthetic conversion in vehicles over five years old.
- Commercial Vehicles:Light and heavy-duty trucks, buses, and delivery vans operating under fleet management contracts. Procurement centralization at Tuas industrial zone logistics hubs enables bulk synthetic programs with telemetry-monitored consumption.
- Two-Wheelers:Motorcycles and scooters dominated by 2-stroke and 4-stroke engine configurations, with JASO MA/MA2 friction specifications for wet clutch compatibility.
- Heavy Machinery:Construction, mining, and port handling equipment requiring specialized high-viscosity formulations with soot-handling capacity for severe duty cycles.
Procurement scale peaks with Commercial Vehicles; margin capture concentrates in Heavy Machinery where equipment downtime costs justify premium formulation expenditure.
Formulation:
Supply concentration in Group III base oil production at Jurong Island refineries shapes formulation economics and import substitution feasibility.
- Synthetic:Polyalphaolefin (PAO) and Group III+ formulations engineered for thermal stability across extended drain intervals. Land Transport Authority emissions benchmarks are compressing fleet procurement toward this category as warranty compliance and fuel efficiency mandates tighten.
- Semi-Synthetic:Blends combining mineral base stocks with synthetic components, positioned between performance tiers for cost-conscious fleet segments transitioning from conventional oils.
- Mineral:Solvent-refined Group I and hydrocracked Group II formulations serving legacy equipment and price-sensitive owner-operators outside warranty coverage.
- Biodegradable:Vegetable oil ester and synthetic ester base stocks with aquatic toxicity compliance for equipment operating near Singapore's marine protected zones.
Production volume tilts toward Synthetic; the steepest expansion trajectory belongs to Biodegradable as National Environment Agency discharge enforcement intensifies near coastal industrial facilities.
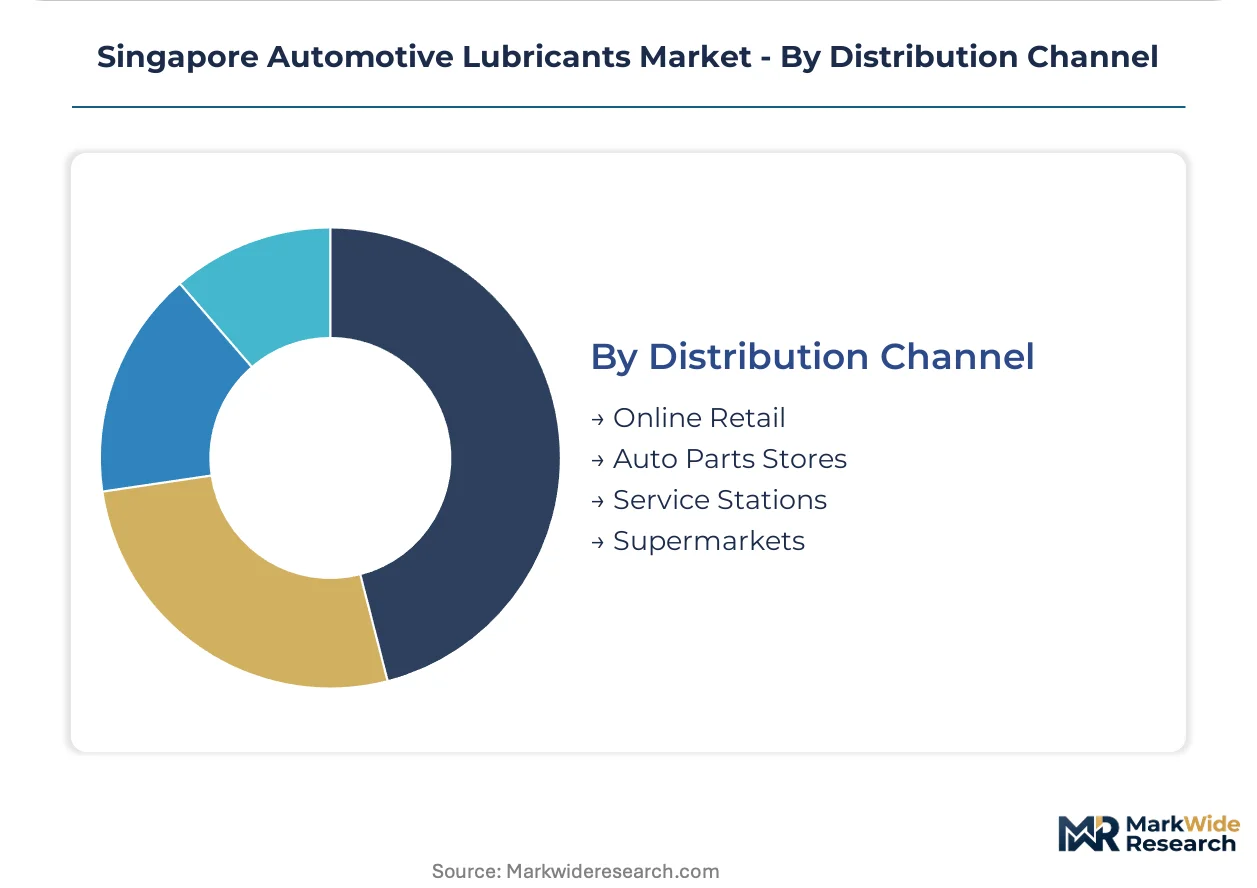
Distribution Channel:
Channel maturity separates established service networks from emerging digital procurement platforms, with geographic density determining economics.
- Online Retail:E-commerce platforms and direct-to-consumer lubricant portals, gaining traction among enthusiast segments seeking specific OEM approval codes.
- Auto Parts Stores:Independent retailers and chain outlets stocking mainstream viscosity grades for DIY maintenance and small workshop supply.
- Service Stations:Authorized workshop networks and quick-lube facilities performing specification-compliant drain-and-fill services under OEM or insurer partnerships.
- Supermarkets:Mass retail channels carrying commodity-grade engine oils for emergency top-up and basic maintenance needs.
Transaction frequency peaks at Service Stations; digital penetration is climbing fastest in Online Retail as fleet procurement departments pilot B2B platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's production capacity for Group II/III base oils substantially exceeds domestic lubricant consumption, positioning the city-state as a net exporter to Southeast Asian markets. Jurong Island refineries supply blenders across the region while local demand concentrates in high-specification synthetic formulations for commercial fleets.
Jurong Island
Integrated refining and blending operations on Jurong Island anchor Singapore's automotive lubricants supply base. ExxonMobil Singapore operates Group II/III base oil production at its Jurong complex, feeding adjacent formulators with reduced logistics overhead. Shell Singapore Pte Ltd maintains blending infrastructure on nearby Pulau Bukom, serving OEM service fill programs for commercial vehicle distributors.
Tuas Industrial Zone
Logistics and construction equipment fleets in Tuas generate concentrated demand for bulk synthetic lubricant delivery programs. The Land Transport Authority's emissions benchmarks compress drain intervals for heavy-duty vehicles operating in this corridor. Telemetry-enabled consumption tracking systems are displacing drum-based procurement for high-volume accounts with predictable maintenance schedules.
Central Business District Corridor
Passenger vehicle service intervals shorten as aging vehicles in Singapore's Certificate of Entitlement parc require more frequent maintenance. Authorized workshop networks in the CBD perform specification-compliant drain-and-fill services under insurer partnerships. Synthetic penetration rises in vehicles exceeding five years of age as warranty compliance pressures mount.
Port Terminal Districts
Heavy machinery and port handling equipment near Singapore's marine terminals face layered compliance obligations from the National Environment Agency. Biodegradable lubricant specifications gain traction as discharge enforcement intensifies near sensitive coastal zones. Fleet maintenance divisions pilot polyalkylene glycol-based thermal management fluids in auxiliary systems.
Singapore Automotive Lubricants Market Competitive Landscape
The competitive structure tilts toward integrated refining specialists with captive base oil supply. Major players cluster around Jurong Island's petrochemical infrastructure, leveraging proximity to reduce working capital requirements. Two strategic archetypes dominate: multinational majors with backward integration into base oil production, and regional blenders serving niche specification requirements. Capacity expansion and OEM service fill partnerships represent the primary competitive moves as fleet procurement centralizes.
Within the integrated multinational tier, Shell Singapore Pte Ltd and ExxonMobil Singapore exemplify the backward-integrated model with refining assets on Jurong Island and Pulau Bukom. Chevron Corporation occupies a position emphasizing high-performance synthetic formulations. Among regional specialists, United Oil Company Pte Ltd represents the independent blender archetype serving specification-diverse industrial accounts without captive base oil supply.
| Leading Market Players |
|---|
| Chevron Corporation |
| Fuchs |
| Shell Singapore Pte Ltd |
| Idemitsu Kosan Co Ltd |
| Motul |
| ExxonMobil Singapore |
| TotalEnergies SE |
| United Oil Company Pte Ltd |
| BP PLC (Castrol) |
| Others |
Value Network & Pricing Analysis
Group III base oil capacity expansion at Jurong Island refineries simultaneously compresses formulation costs and concentrates supply leverage among integrated producers. This production-method transition reshapes procurement economics as captive feedstock access separates price-setters from price-takers across Singapore's lubricant value chain.
Pricing Analysis
Margin tightening in mid-tier synthetic blends reflects feedstock cost volatility when Asian cracking margins compress. Pricing stratifies across premium, standard, and economy tiers based on base oil Group classification and OEM approval certification levels. Cost-down pressure on mineral formulations accelerates because fleet operators consolidate procurement around extended-drain synthetics. Owner-operators outside warranty coverage remain most price-sensitive; OEM-authorized service networks show lowest elasticity.
Supply Chain Analysis
Regional distribution centers on Jurong Island and Pulau Bukom anchor hub-and-spoke patterns serving blenders across Southeast Asia. Supply concentrates in Singapore, South Korea, and Japan for Group II/III base oil production. Formulators draw from polyalphaolefin imports, additive packages from specialty chemical suppliers, and packaging materials from regional converters. Single-source vulnerability persists in high-performance friction modifier supply. Distribution runs through authorized distributor networks with telemetry-enabled bulk delivery displacing drum logistics for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's automotive lubricants market is consolidating around integrated refining specialists as carbon tax enforcement and specification complexity force independent blenders toward exit or acquisition.
For Market Incumbents: Lock in OEM service fill partnerships with commercial vehicle distributors to capture lifetime fluid revenue streams. Deepen backward integration into Group III+ base oil production through Jurong Island capacity upgrades. Defend against regional blender competition by controlling certification documentation for ASEAN harmonized technical regulations. For New Entrants and Emerging Players: E-commerce platforms serving enthusiast segments seeking specific OEM approval codes offer lowest barrier entry. Target biodegradable lubricant supply to port terminal operators facing National Environment Agency discharge enforcement. Pursue white-label manufacturing partnerships with established Jurong Island blenders lacking marine certification expertise. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated majors seeking Singapore hub positioning. Five-to-ten year viability favors blenders with captive base oil supply or specialized marine certification capabilities. Monitor Land Transport Authority emissions benchmark tightening as inflection indicator for synthetic penetration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Captive feedstock supply from Jurong Island refineries reduces import cost volatility for formulators. |
| Extended-Drain Synthetic Formulation Development | Land Transport Authority emissions benchmarks compress drain intervals and elevate performance specifications. |
| Telemetry-Enabled Bulk Delivery Infrastructure | Tuas industrial zone fleet operators demand consumption tracking for predictive maintenance scheduling. |
| Biodegradable Lubricant Certification Investment | National Environment Agency enforcement near marine terminals creates compliant product premiums. |
| ASEAN Harmonized Technical Regulation Alignment | Single-specification production runs enable Singapore-based blenders to serve regional export demand. |
Research Methodology
Trade flow databases, refinery capacity disclosures, and customs import records formed the secondary backbone for supply-side calibration. Primary interviews with lubricant formulation chemists, fleet procurement managers at Tuas logistics operators, and aftermarket distributor principals provided demand-side validation. The analysis triangulated bottom-up consumption estimates against top-down production capacity assessments across the analysis window.
Historical trendline analysis of base oil production volumes and lubricant consumption patterns anchored the projection framework. Segmentation modeling captured product type, formulation chemistry, end-user category, and distribution channel dynamics. CAGRs derived from regression analysis of feedstock cost trajectories and regulatory enforcement intensity. Forecast inputs incorporated Singapore's carbon tax trajectory and Land Transport Authority emissions benchmark schedules.
The model holds under stable refinery operating rates and continued regulatory enforcement; deviation in Asian cracking margin volatility or ASEAN harmonization delays would shift volume projections. Forecasts reflect documented assumptions on synthetic penetration rates and fleet procurement centralization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Food Grade Lubricant Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Hydraulic Fluids and Process Oil Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Automotive Die Casting Lubricants Market
Lubricants
Qatar Automotive Engine Oils Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Philippines Commercial Vehicles Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market