
 South America Lubricants Market | 2026-2036
South America Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
South America Lubricants Market Analytics
Subscription-based oil analysis and predictive maintenance programs is restructuring how lubricant suppliers capture recurring revenue from fleet and industrial accounts. Petrobras leverages its captive refinery network to dominate base oil supply across Brazil. Royal Dutch Shell Plc competes through premium synthetic formulations targeting OEM fill specifications. YPF anchors its position in Argentina by controlling downstream distribution through integrated retail and direct sales channels.
Lubricants are formulated fluids comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades typically spanning ISO VG 32 to 680 for industrial applications and SAE 0W-16 to 60 for automotive engines. Automotive Oils commands the largest revenue pool due to Brazil's extensive vehicle parc and mandatory drain intervals, while Industrial Lubricants represents the fastest-expanding category as Chilean and Colombian mining operations scale equipment utilization. Greases maintains stable margins in specialty applications despite slower volume growth relative to fluid lubricants.
Brazil's ANP regulates fuel and lubricant quality standards, including biofuel compatibility requirements that directly shape additive chemistry investments. Argentina's Secretariat of Energy oversees lubricant import tariffs and local content rules that affect foreign supplier market access. Chile's Ministry of Mining enforces environmental discharge standards for open-pit operations, driving demand for biodegradable hydraulic fluids. Stakeholders must monitor how evolving national biofuel mandates and carbon accounting rules will redefine product certification requirements and reformulation timelines across the region.
Market Dynamics
ANP biofuel blending mandates are forcing reformulation of base stocks and additive packages across Brazil's lubricant supply chain, compressing product development cycles while elevating technical barriers for suppliers without captive refinery capacity.
Growth Catalysts
- ANP biofuel compatibility mandates:Brazil's petroleum regulator requires lubricant formulations that withstand higher ethanol and biodiesel concentrations, driving additive chemistry investments and product line refreshes.
- Chilean mining equipment utilization:Open-pit copper and lithium operations are extending operating hours, expanding consumption of hydraulic fluids and gear oils in the Atacama Desert extraction zones.
- Fleet preventive maintenance expansion:Brazilian logistics operators are adopting oil analysis programs to reduce unplanned downtime, creating recurring service revenue streams for lubricant suppliers.
Market Restraints
- Petrobras base oil concentration:Brazil's state-controlled refinery network supplies over half of regional Group I and II base stocks, creating supply vulnerability for independent blenders.
- Group III+ base oil import dependency:Synthetic and semi-synthetic formulations require imported high-viscosity-index feedstocks, exposing margins to currency volatility and freight cost swings.
- Argentina import tariff friction:The Secretariat of Energy maintains local content rules that elevate landed costs for foreign lubricant suppliers serving Buenos Aires industrial corridors.
Strategic Opportunities
- Colombian mining logistics underpenetration:Cerrejón coal operations and emerging gold projects in Antioquia lack established lubricant service infrastructure, opening direct-sales channels.
- Subscription-based predictive maintenance:Remote oil monitoring platforms are enabling suppliers to bundle fluid sales with equipment health analytics, locking in multi-year fleet contracts.
- Chilean biodegradable hydraulic fluid mandates:Ministry of Mining environmental discharge standards are creating premium product categories for open-pit operations in environmentally sensitive watersheds.
Industry Challenges
- Formulation chemist scarcity:Brazil's technical universities produce limited graduates specialized in tribology and additive chemistry, constraining R&D throughput for local blenders.
- Legacy equipment compatibility:Aging Brazilian manufacturing machinery operates on obsolete viscosity specifications, forcing suppliers to maintain discontinued product lines.
- Multi-jurisdiction certification complexity:Separate ANP, INMETRO, and state-level environmental approvals extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Lubricants Market |
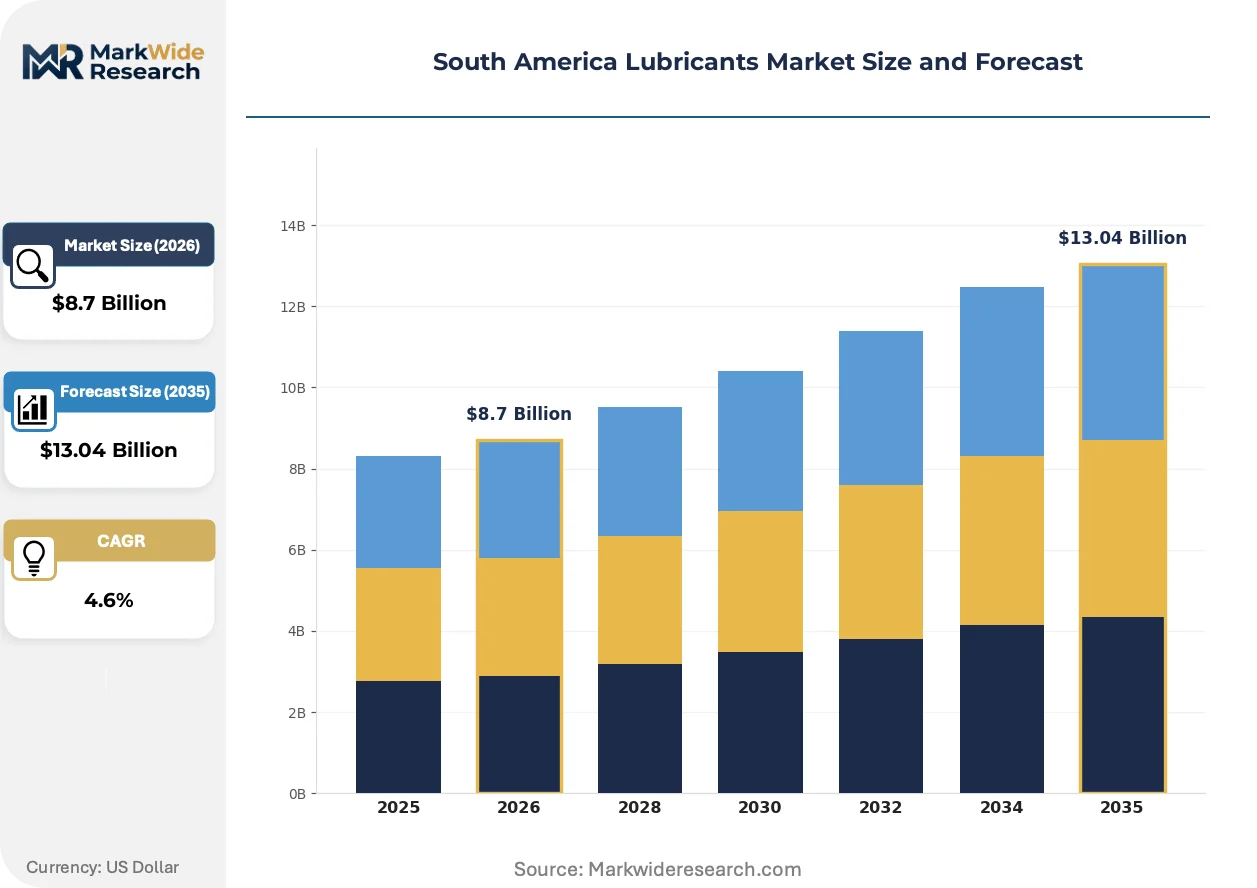
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automotive Oils, Industrial Lubricants, Process Oils, Greases End User: Manufacturing, Automotive, Marine, Construction Application: Engine Lubrication, Hydraulic Systems, Gear Oils, Metalworking Distribution Channel: Retail, Wholesale, Direct Sales, E-commerce |
| Companies Covered | Iconic Lubrificantes, Royal Dutch Shell Plc, Petrobras, TotalEnergies, BP Plc (Castrol), YPF, ExxonMobil Corporation, Gulf Oil International, Terpel, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Lubricants Market Evolving Landscape
Synthetic base oils and digital service platforms are restructuring competitive advantage in South American lubricants, compressing the traditional separation between fluid manufacturing and equipment maintenance.
Group III and PAO synthetic base stocks are overtaking Group II mineral oils in Brazilian OEM fill specifications and fleet drain-interval extensions. Mining operators in Chile and Colombia are specifying synthetics for equipment operating above 85 degrees Celsius ambient temperature. This technology shift is overtaking conventional mineral formulations in premium segments while forcing price compression in mid-tier product lines.
Brazil's ANP has tightened biofuel compatibility testing protocols for lubricants sold in states with elevated ethanol blending requirements. The regulation mandates oxidative stability testing under 20% ethanol exposure conditions, disqualifying older additive packages. Automotive OEMs serving São Paulo's vehicle assembly plants are now requiring lubricant suppliers to submit ANP certification documentation prior to contract bidding.
Fleet operators are consolidating lubricant purchasing through integrated maintenance contracts rather than spot-buying from distributors. Large Brazilian logistics companies are negotiating direct supply agreements with blenders, disintermediating traditional wholesale channels. This purchasing consolidation is most visible in São Paulo state's freight corridors, where three fleet operators account for a disproportionate share of heavy-duty diesel engine oil volume.
South America Lubricants Market Segmentation
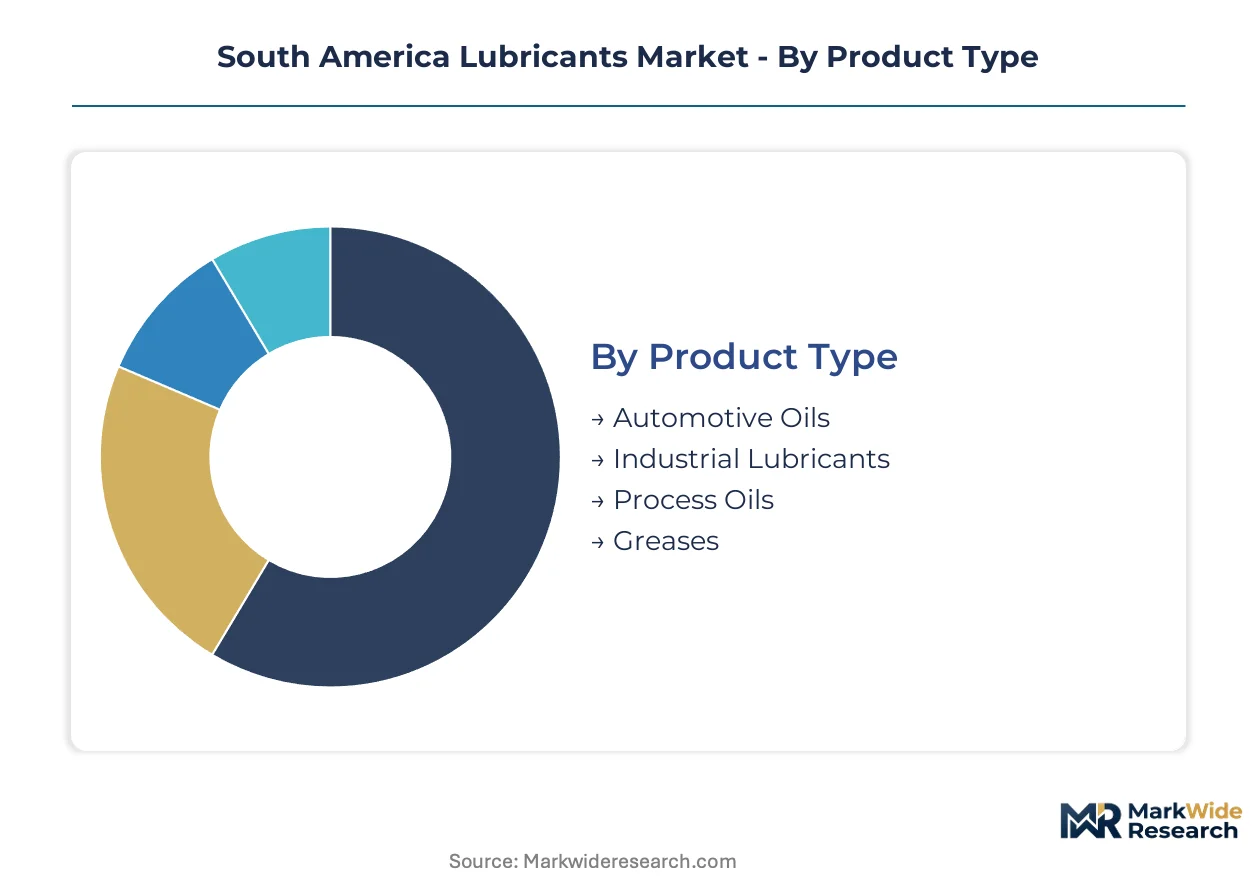
Segmentation in South American lubricants reveals how formulation chemistry, equipment specifications, and procurement channels create distinct competitive battlegrounds. Suppliers must align product portfolios with the technical demands of Brazilian fleet operators, Chilean mining contractors, and Argentine manufacturing clusters.
Product Type:
The customization-to-standardization spectrum runs from application-specific industrial formulations to mass-market automotive grades with regional specification harmonization.
- Automotive Oils:Engine lubricants formulated to SAE viscosity grades and OEM fill specifications, with additive packages engineered for ANP biofuel compatibility mandates. Brazilian vehicle parc density in São Paulo state corridors concentrates demand, while mandatory drain intervals create predictable replacement cycles.
- Industrial Lubricants:Hydraulic fluids, compressor oils, and turbine lubricants spanning ISO VG 32 to 680 viscosity ranges, formulated for extended service intervals in continuous-process manufacturing. Chilean copper and lithium mining operations in the Atacama Desert are expanding consumption of high-temperature hydraulic formulations.
- Process Oils:Technical white oils and rubber extender oils used in tire manufacturing and polymer processing. Brazilian petrochemical complexes along the São Paulo-Rio de Janeiro industrial axis represent the primary demand concentration.
- Greases:Thickened lubricants combining base oils with metallic soap or complex thickeners for sealed-for-life bearings and extreme-pressure applications. Specialty mining and steel mill applications maintain stable margin structures despite lower volume velocity.
Most installed capacity flows through Automotive Oils. Expansion is steepest in Industrial Lubricants.
End User:
Cost tier segmentation separates commodity procurement patterns in high-volume manufacturing from premium specification requirements in specialized extraction operations.
- Manufacturing:Metalworking, plastics processing, and food packaging operations consuming hydraulic fluids, compressor oils, and food-grade lubricants. São Paulo state's industrial belt concentrates demand, with preventive maintenance programs extending replacement intervals.
- Automotive:Vehicle assembly plants, aftermarket service chains, and fleet operators specifying OEM fill and drain-interval-optimized formulations. Brazilian light vehicle production and heavy-duty freight corridors drive specification complexity.
- Marine:Coastal shipping, inland waterway vessels, and offshore support operations requiring high-base-number cylinder oils and environmentally acceptable lubricants. Argentine Paraná-Paraguay waterway traffic and Brazilian offshore pre-salt logistics create niche demand pockets.
- Construction:Earthmoving equipment, concrete production, and road building machinery operating in abrasive, high-dust environments. Colombian infrastructure projects and Brazilian urban expansion are expanding hydraulic fluid consumption in mobile equipment.
Volume concentrates in Manufacturing end users. Margin expansion is strongest in Marine applications.
Application:
Application segmentation tracks equipment criticality, with failure-cost economics determining willingness to pay for synthetic formulations and predictive maintenance integration.
- Engine Lubrication:Crankcase oils for internal combustion engines, formulated with detergent-dispersant and anti-wear additive packages. Brazilian fleet operators are consolidating procurement through integrated maintenance contracts with direct blender relationships.
- Hydraulic Systems:Power transmission fluids for construction, mining, and industrial machinery, with fire-resistant and biodegradable variants gaining specification in environmentally sensitive watersheds. Chilean Ministry of Mining discharge standards are accelerating biodegradable hydraulic fluid adoption.
- Gear Oils:Extreme-pressure lubricants for transmissions, differentials, and industrial gearboxes, formulated with sulfur-phosphorus additive chemistry. Open-pit mining equipment in Chile and Colombia operates above 85 degrees Celsius ambient, specifying synthetic base stocks.
- Metalworking:Cutting fluids, forming lubricants, and rust preventives for machining and stamping operations. Brazilian automotive component suppliers in São Paulo state's manufacturing belt represent concentrated demand for soluble oil and synthetic coolant formulations.
Equipment-hour intensity is highest in Engine Lubrication. Technology substitution is accelerating fastest in Hydraulic Systems.
Distribution Channel:
Channel segmentation reflects customer scale and technical service requirements, from self-service retail to embedded technical support in direct supply relationships.
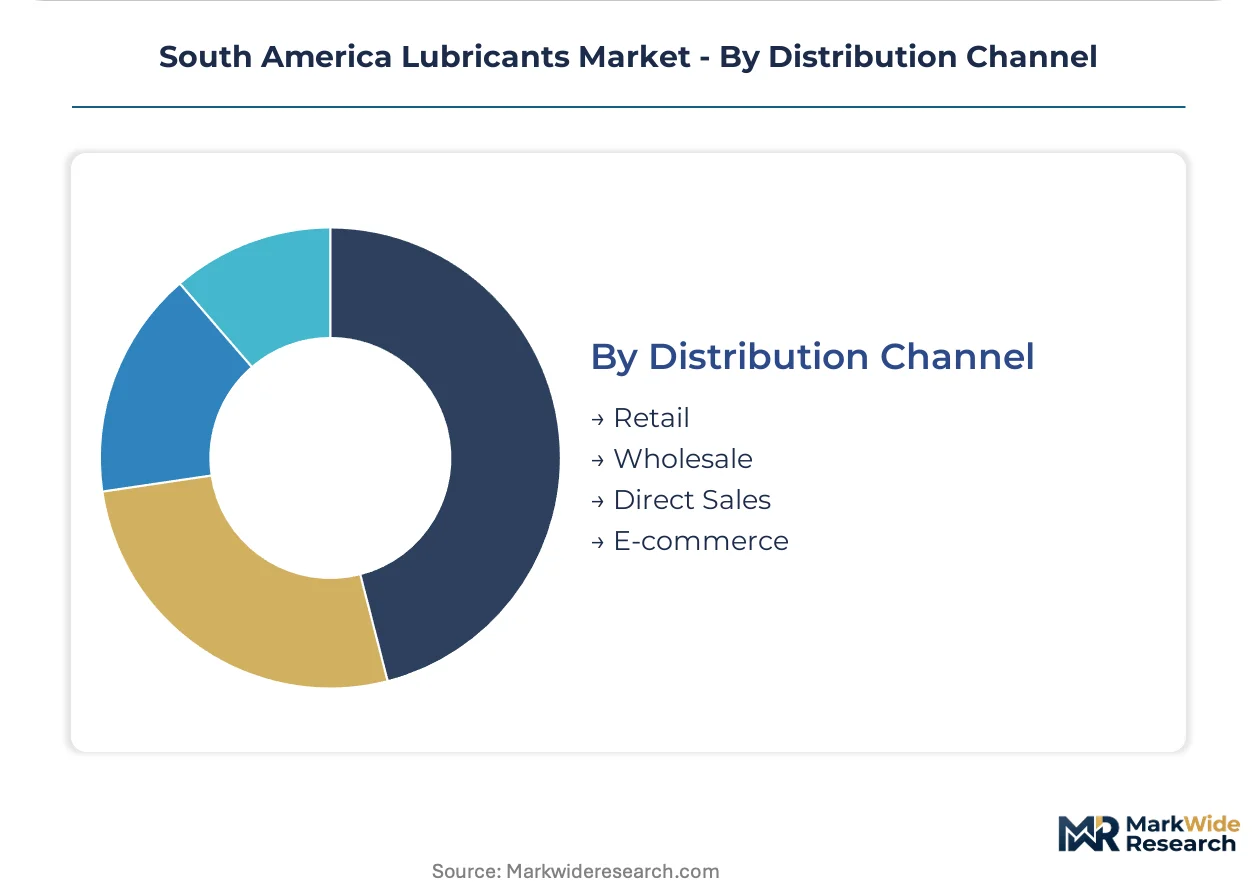
- Retail:Branded lubricant sales through automotive parts stores, service stations, and farm supply cooperatives. Brazilian independent workshops and owner-operator truckers sustain volume through spot purchasing.
- Wholesale:Bulk fluid distribution through regional distributors serving jobbers and smaller industrial accounts. Traditional channel position is eroding as large fleet operators and mining contractors consolidate procurement.
- Direct Sales:Supply agreements between blenders and large end users, bundling fluid delivery with oil analysis and technical service. Brazilian logistics operators in São Paulo freight corridors are disintermediating wholesale channels through direct blender negotiations.
- E-commerce:Digital procurement platforms for standardized grades and replenishment purchasing. Penetration remains limited by technical consultation requirements and bulk logistics constraints.
Transaction volume flows predominantly through Wholesale. Channel capture is advancing most rapidly in Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's lubricant consumption exceeds Argentina's by a substantial margin, yet Chilean mining corridors generate higher per-tonne fluid intensity than either market. The region's regulatory fragmentation forces suppliers to maintain separate formulation certifications across national boundaries.
Brazil
Fleet operators across São Paulo state's manufacturing belt are consolidating procurement through direct supply agreements with blenders. ANP biofuel compatibility mandates require oxidative stability testing under elevated ethanol exposure, disqualifying legacy additive packages. The São Paulo-Rio de Janeiro industrial axis concentrates demand for process oils and automotive lubricants serving vehicle assembly plants.
Argentina
YPF controls downstream distribution through integrated retail and direct sales channels, limiting foreign supplier market access. The Secretariat of Energy maintains local content rules and import tariffs that elevate landed costs for international blenders. Buenos Aires industrial corridors sustain demand for metalworking fluids and hydraulic oils in automotive component manufacturing.
Chile
Open-pit copper and lithium operations in the Atacama Desert are extending equipment operating hours above 85 degrees Celsius ambient, specifying synthetic base stocks. The Ministry of Mining enforces environmental discharge standards that accelerate biodegradable hydraulic fluid adoption in environmentally sensitive watersheds. Antofagasta and Calama mining logistics clusters lack established lubricant service infrastructure, opening direct-sales channels.
Colombia
Cerrejón coal operations and emerging gold projects in Antioquia are expanding consumption of hydraulic fluids in mobile extraction equipment. National environmental regulators are tightening discharge standards for mining operations in high-altitude watersheds. Bogotá-based industrial distributors serve manufacturing accounts while mining contractors in northern departments negotiate direct blender relationships.
Peru
Copper concentrate operations in the southern Andes are scaling equipment utilization, expanding demand for gear oils and extreme-pressure lubricants. The Ministry of Energy and Mines oversees environmental compliance standards for extractive industries in sensitive ecological zones. Arequipa and Tacna mining corridors represent underpenetrated service infrastructure relative to Chilean operations of comparable scale.
South America Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with state-controlled refiners dominating base oil supply while international oil companies compete on formulation technology. The market structure concentrates around three archetypes: integrated national oil companies with captive refinery networks, global majors leveraging synthetic formulation expertise, and regional distributors controlling last-mile access. Consolidation is accelerating through direct supply agreements that disintermediate wholesale channels, while portfolio diversification into predictive maintenance services is restructuring supplier-customer relationships.
Among integrated national oil companies, Petrobras anchors the Brazilian supply base through its captive refinery network, while YPF occupies a comparable position in Argentina's downstream distribution. Royal Dutch Shell Plc exemplifies the global major archetype competing through premium synthetic formulations. These three entities represent distinct strategic positions: state-backed vertical integration, regional distribution control, and technology-led premium positioning.
| Leading Market Players |
|---|
| Iconic Lubrificantes |
| Royal Dutch Shell Plc |
| Petrobras |
| TotalEnergies |
| BP Plc (Castrol) |
| YPF |
| ExxonMobil Corporation |
| Gulf Oil International |
| Terpel |
| Others |
Value Network & Pricing Analysis
Brazilian fleet operator consolidation into direct supply agreements is compressing distributor margins and forcing blenders to absorb logistics costs or surrender price competitiveness. ANP biofuel compatibility mandates add formulation cost layers that suppliers must either pass through or offset via captive refinery economics.
Pricing Analysis
Capacity additions in Brazil's synthetic base oil blending are reshaping price floors for Group III formulations serving OEM fill specifications. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral economy levels stratifies by ANP certification tier and drain-interval performance. Cost compression in mid-tier mineral grades is intensifying because Petrobras refinery output floods Group I and II supply. Fleet operators in São Paulo freight corridors exhibit lowest price sensitivity due to total-cost-of-ownership contracting, while independent workshops remain highly price-sensitive spot buyers.
Supply Chain Analysis
Argentina's Secretariat of Energy local-content mandates are reshaping sourcing patterns for foreign suppliers serving Buenos Aires industrial corridors. Base oil supply concentrates in Brazil, with Group I and II feedstocks drawing from Petrobras captive refinery network and Group III+ synthetics anchored in imported high-viscosity-index stocks from South Korea and the Middle East. Raw material dependencies span additive packages from US and European specialty chemical suppliers, metallic soap thickeners for greases, and biodegradable ester base stocks for Chilean mining compliance. Single-source vulnerability runs through Petrobras refinery dominance, which supplies over half of regional feedstocks. Distribution runs through direct sales agreements with large fleet and mining accounts, disintermediating traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American lubricants function as a stable compounder anchored by mandatory drain intervals and biofuel-driven reformulation cycles that sustain recurring revenue streams.
For Market Incumbents: Hedge against Petrobras supply disruption by securing alternative Group III+ import arrangements from Asian refiners. Deepen backward integration into additive chemistry partnerships to capture margin from ANP-mandated formulation upgrades. Channel control through embedded oil analysis services locks in multi-year fleet contracts before competitors replicate predictive maintenance platforms. For New Entrants and Emerging Players: Remote oil monitoring platforms offer a technology-first wedge into Brazilian logistics operator procurement consolidation. Colombian mining logistics in Cerrejón and Antioquia gold projects represent the most penetrable white space, lacking established lubricant service infrastructure. A direct-sales model bundling fluid delivery with equipment health analytics bypasses entrenched wholesale channels. For Investors and Strategic Acquirers: Asymmetric upside sits with regional blenders possessing ANP certification capabilities and established mining contractor relationships. Long-term viability over a five-to-ten-year window favors suppliers with captive base oil access or locked-in synthetic import arrangements. Watch Chilean Ministry of Mining discharge standard enforcement as the signal for biodegradable hydraulic fluid premiumization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Captures margin from ANP-mandated oxidative stability package investments. |
| Predictive Maintenance Platform Launch | Locks recurring revenue from Brazilian fleet operator consolidation. |
| Biodegradable Hydraulic Fluid Certification | Secures premium positioning under Chilean Ministry of Mining discharge rules. |
| Direct Sales Channel Expansion | Disintermediates wholesale erosion in São Paulo freight corridors. |
| Group III+ Import Arrangement Diversification | Reduces currency and single-source exposure for synthetic formulations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lubricant blenders, fleet maintenance directors, mining procurement leads, and ANP regulatory officials with secondary validation. Bottom-up triangulation drew from customs trade data on base oil imports, ANP certification registries, and SEC filings of listed oil majors, while top-down cross-checks referenced production capacity databases and refinery output disclosures.
Segment-weighting approaches modeled volume and value across the projection horizon by product type, end-use industry, application equipment criticality, and distribution channel structure. CAGRs were derived from equipment-hour intensity projections, biofuel mandate implementation schedules, and mining sector capital expenditure patterns. Forecast inputs incorporated ANP regulatory timeline assumptions and Chilean environmental discharge compliance trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Petrobras refinery utilization shifts and Argentine import tariff regime changes. Forecasts reflect documented assumptions about biofuel blend rate trajectories and mining sector equipment utilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
France Lubricants Market
Lubricants
Bio-Based Lubricants Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Mexico Automotive Engine Oils Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
South Korea Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Friction Reducers Market