
 Africa Heavy Equipment Lubricants Market | 2026-2036
Africa Heavy Equipment Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Heavy Equipment Lubricants Market Outlook
CE marking alignment under the EU Green Deal is decoupling low-specification lubricant suppliers from premium tender pools across African mining and construction contracts. TotalEnergies SE leverages its Angolan refining footprint to sustain captive supply chains for hydraulic fluids in West African ports. Shell PLC anchors its position through backward integration into base oil trading networks serving Lagos and Durban distribution hubs.
Africa heavy equipment lubricants are formulated blends of base oils and additive packages engineered to withstand high load-bearing friction, extreme temperatures, and particulate contamination in off-highway machinery operating across arid and tropical climates. These formulations typically meet API CK-4 or ACEA E9 specifications for diesel engines, with viscosity grades ranging from SAE 15W-40 to SAE 10W-30 depending on ambient operating conditions. Engine oils dominate current volume flows due to the density of diesel-powered excavators and haul trucks, while hydraulic fluids represent the fastest-expanding category as mechanized agriculture spreads across Ethiopia and Tanzania. Mining applications command the deepest margin pools because OEMs and fleet operators there prioritize extended drain intervals and equipment warranty compliance over unit cost.
BIS-equivalent standards in South Africa and Nigeria's SONCAP certification framework are tightening product registration requirements for imported lubricant consignments. Ghana's EPA and Kenya's NEMA are aligning emissions enforcement with lubricant quality audits at major construction sites. Stakeholders must monitor how rapidly national petroleum regulators adopt sulfur limits and biodegradability thresholds that currently govern European and Asian supplier formulations.
Market Dynamics
South Africa's carbon tax mechanism is compressing fleet operator margins and forcing rapid reformulation toward lower-viscosity synthetics, while Copperbelt mining expansion pulls supply chains northward into Zambia and DRC logistics corridors.
Growth Catalysts
- Carbon Tax Pressure:South Africa's carbon tax mechanism penalizes high-emission diesel fleets, creating immediate pull-through for API CK-4 and ACEA E9 synthetic formulations that reduce particulate output and extend drain intervals.
- Copperbelt Fleet Expansion:Mining operations across Zambia and DRC are doubling mechanized extraction capacity, concentrating demand for high-load-bearing hydraulic fluids and engine oils in a narrow geographic band with limited local blending infrastructure.
- Ghana Infrastructure Corridor:Emerging oil and gas infrastructure construction is generating concentrated demand for off-highway lubricants in a market previously served by informal import channels.
Market Restraints
- Base Oil Import Dependency:Group II and Group III base stocks enter Africa through Rotterdam and Singapore trading hubs, exposing blenders to freight rate volatility and currency mismatches against local tender currencies.
- Counterfeit Formulation Penetration:Unregistered consignments bypassing Nigeria's SONCAP certification framework undercut premium pricing in Lagos and Port Harcourt distribution zones.
- Extended Equipment Life Cycles:Mining fleet operators in Zimbabwe and Angola are retaining older Caterpillar and Komatsu haul trucks beyond OEM-recommended service intervals, compressing per-unit lubricant consumption.
Strategic Opportunities
- Ethiopia Mechanized Agriculture:Tractor and combine harvester penetration in the Oromia and Amhara regions is outpacing domestic lubricant distribution networks, creating first-mover advantages for mobile blending units.
- Kenya NEMA Alignment:Construction site emissions audits now incorporate lubricant quality verification, positioning registered suppliers for Nairobi and Mombasa infrastructure tenders.
- Biodegradable Hydraulic Fluids:EU Green Deal biodegradability thresholds are filtering into African mining contract specifications, enabling premium positioning for ester-based formulations in environmentally sensitive extraction zones.
Industry Challenges
- API Certification Backlogs:Testing laboratory capacity in Johannesburg and Lagos cannot match registration application volumes, delaying market entry for new additive packages by 8-14 months.
- Field Technician Scarcity:Proper oil analysis and condition monitoring require trained personnel absent across most Francophone West African mining operations, limiting uptake of extended-drain synthetic products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Heavy Equipment Lubricants Market |
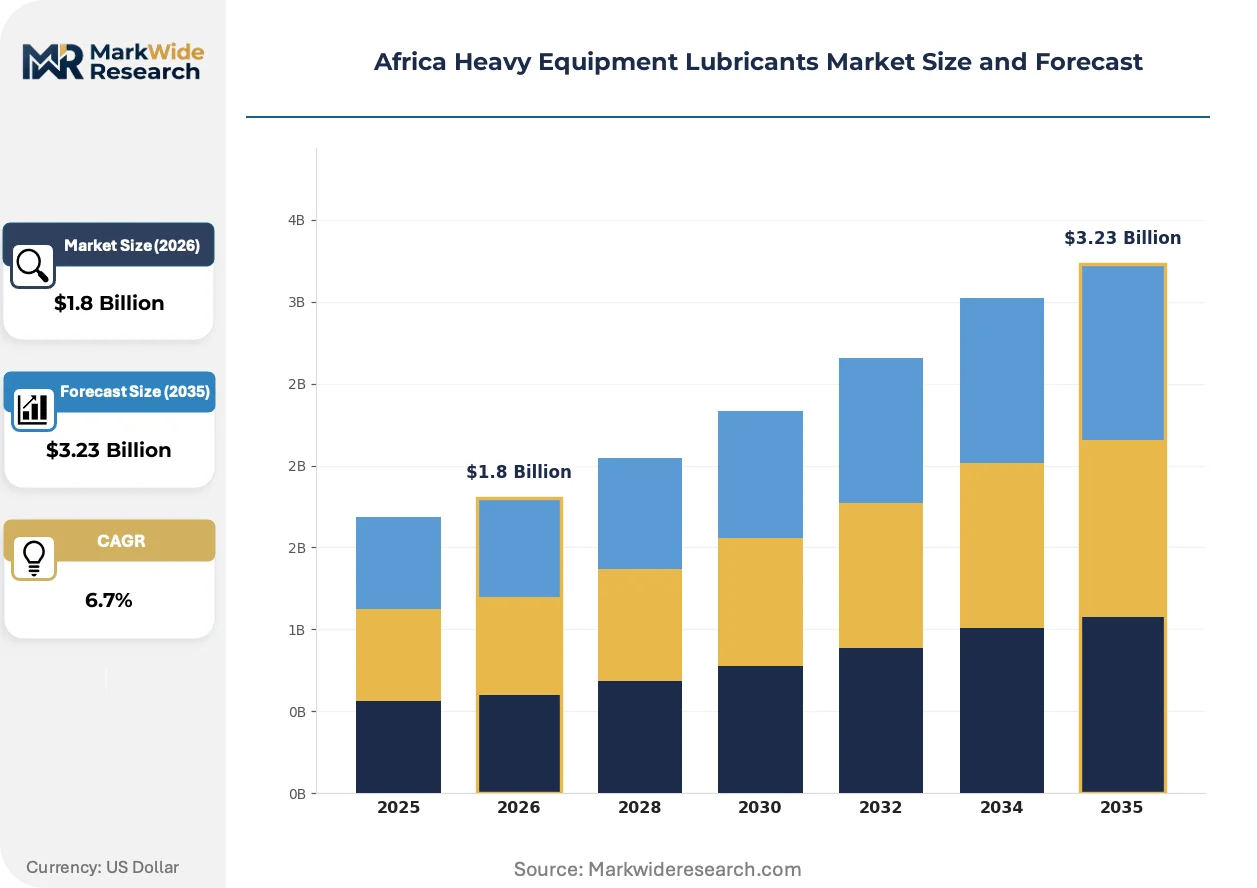
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Hydraulic Fluids, Gear Oils, Greases Application: Construction, Agriculture, Mining, Forestry End User: OEMs, Repair Workshops, Fleet Operators, Industrial Users Distribution Channel: Retail, Wholesale, Online Platforms, Direct Sales |
| Companies Covered | TotalEnergies SE, ExxonMobil Corporation, Shell PLC, BP PLC, FUCHS Lubricants Co., Chevron Corporation, Castrol Limited, Engen Petroleum Ltd, PetroSA Lubricants, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Heavy Equipment Lubricants Market Strategic Shifts
Formulation chemistry and procurement architectures are diverging sharply between premium mining contracts and informal construction supply, with regulatory enforcement density determining which tier captures volume growth.
Synthetic ester base stocks are electrifying hydraulic fluid performance in high-pressure mining applications. Anglo American and Glencore operations in Zambia are specifying these formulations for underground equipment where fire resistance and biodegradability overlap. The technology is electrifying supplier selection criteria, compressing qualification timelines from 18 months to 6 months for approved vendors.
CE marking alignment under the EU Green Deal is decoupling low-specification suppliers from tender pools. African mining and construction contracts now embed REACH-compliant additive packages as mandatory bid prerequisites. Kenyan and Ghanaian EPA audit protocols are the most aggressive in enforcing these thresholds at major project sites.
Fleet operators in South Africa's platinum belt are unbundling lubricant supply from OEM service contracts. Maintenance departments now procure directly from approved distributors, bypassing equipment dealer markups. This pattern is most visible in Rustenburg and Limpopo mining clusters where cost pressure from carbon tax liabilities has intensified procurement scrutiny.
Africa Heavy Equipment Lubricants Market Segmentation
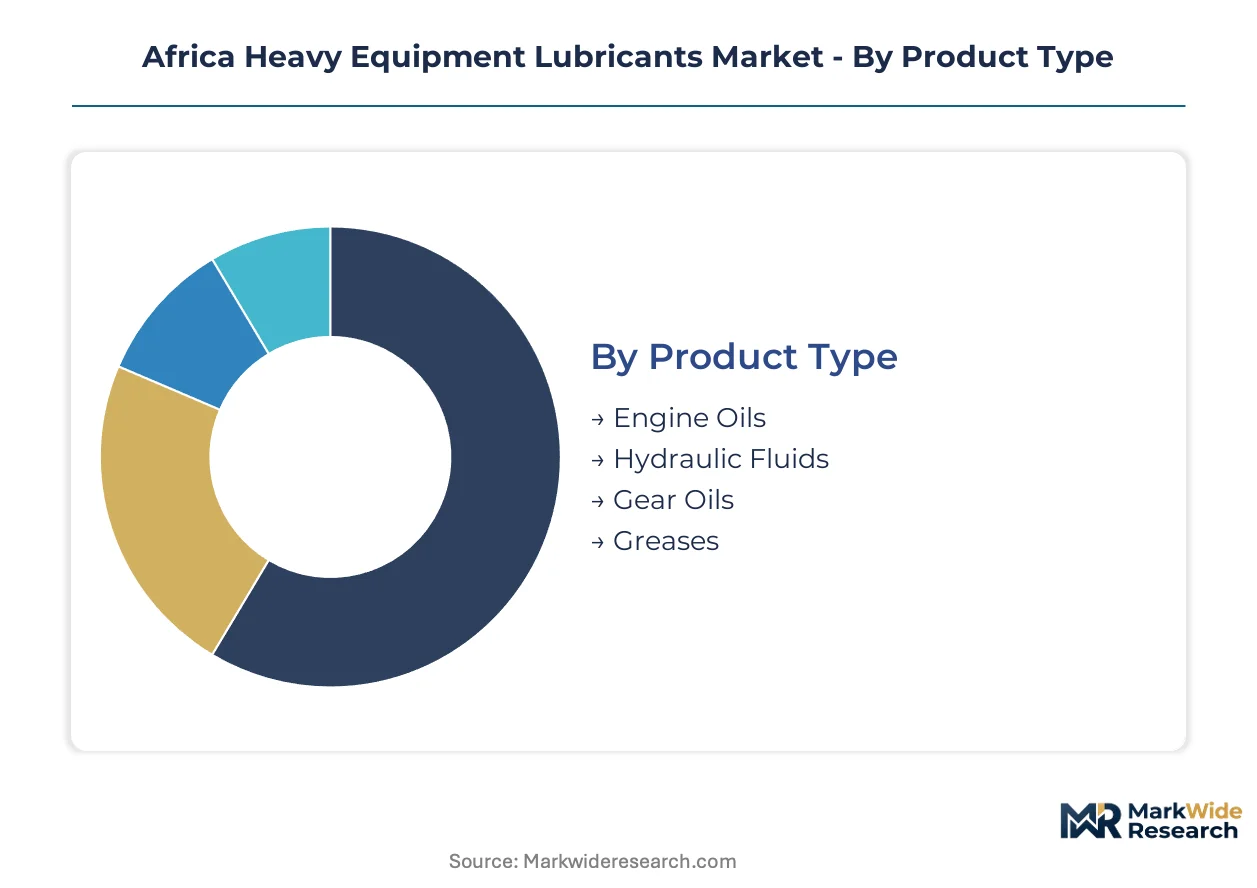
Equipment replacement cycles across African mining and construction fleets create distinct lubricant specification tiers. Understanding how product types, applications, and procurement channels intersect reveals where margin pools concentrate versus where volume flows commoditize.
Product Type:
Upgrade decisions in diesel engine maintenance and hydraulic system overhauls drive lubricant selection more than new equipment purchases.
- Engine Oils:API CK-4 and ACEA E9 formulations dominate diesel-powered excavator and haul truck maintenance. Copperbelt mining operations in Zambia and DRC prioritize extended drain intervals to minimize underground service downtime.
- Hydraulic Fluids:Synthetic ester base stocks are displacing mineral formulations in high-pressure mining equipment. Anglo American and Glencore operations specify these for underground machinery where fire resistance and biodegradability requirements overlap.
- Gear Oils:Heavy-duty transmissions in earthmoving equipment require SAE 80W-90 or 85W-140 grades. Articulated dump trucks operating in Ghana's infrastructure corridor consume bulk volumes through service contracts.
- Greases:Lithium complex and calcium sulfonate thickeners protect pivot points in arid climates. Kenyan construction sites near Nairobi specify NLGI Grade 2 for excavator booms and bucket pins.
Engine oils sit at the top of the volume ranking, with hydraulic fluids climbing the fastest.
Application:
Cost tier differentiation separates premium synthetic formulations from standard mineral products across end-use sectors.
- Mining:OEM warranty compliance and extended drain intervals override unit cost considerations. Fleet operators in South Africa's platinum belt unbundle lubricant procurement from dealer service contracts to reduce carbon tax exposure.
- Construction:Project-based purchasing concentrates demand in Ghana's oil and gas infrastructure corridor and Kenya's Nairobi-Mombasa development axis. NEMA audits now incorporate lubricant quality verification at major sites.
- Agriculture:Mechanization spreads across Ethiopia's Oromia and Amhara regions faster than distribution networks can follow. Tractor and combine harvester penetration creates first-mover opportunities for mobile blending units.
- Forestry:Equipment operates in environmentally sensitive extraction zones where biodegradable hydraulic fluids command premium positioning. Specifications increasingly mirror EU Green Deal thresholds.
Mining commands the deepest margin pools, with agriculture expanding most quickly.
End User:
Customer type determines whether procurement prioritizes technical specification compliance or cost minimization.
- Fleet Operators:Large mining and logistics companies conduct oil analysis programs and condition monitoring. South African carbon tax liabilities intensify scrutiny of synthetic formulation ROI.
- OEMs:Equipment manufacturers specify factory-fill and warranty-service lubricants. Caterpillar and Komatsu dealer networks in Zimbabwe and Angola retain captive lubricant revenue streams.
- Repair Workshops:Independent service providers in Lagos and Port Harcourt distribution zones face price pressure from unregistered consignments bypassing SONCAP certification.
- Industrial Users:Cement plants and port operators in Durban and Mombasa maintain bulk storage and in-house blending capabilities.
Fleet operators represent the highest-value customer tier, with repair workshops gaining transaction volume fastest.
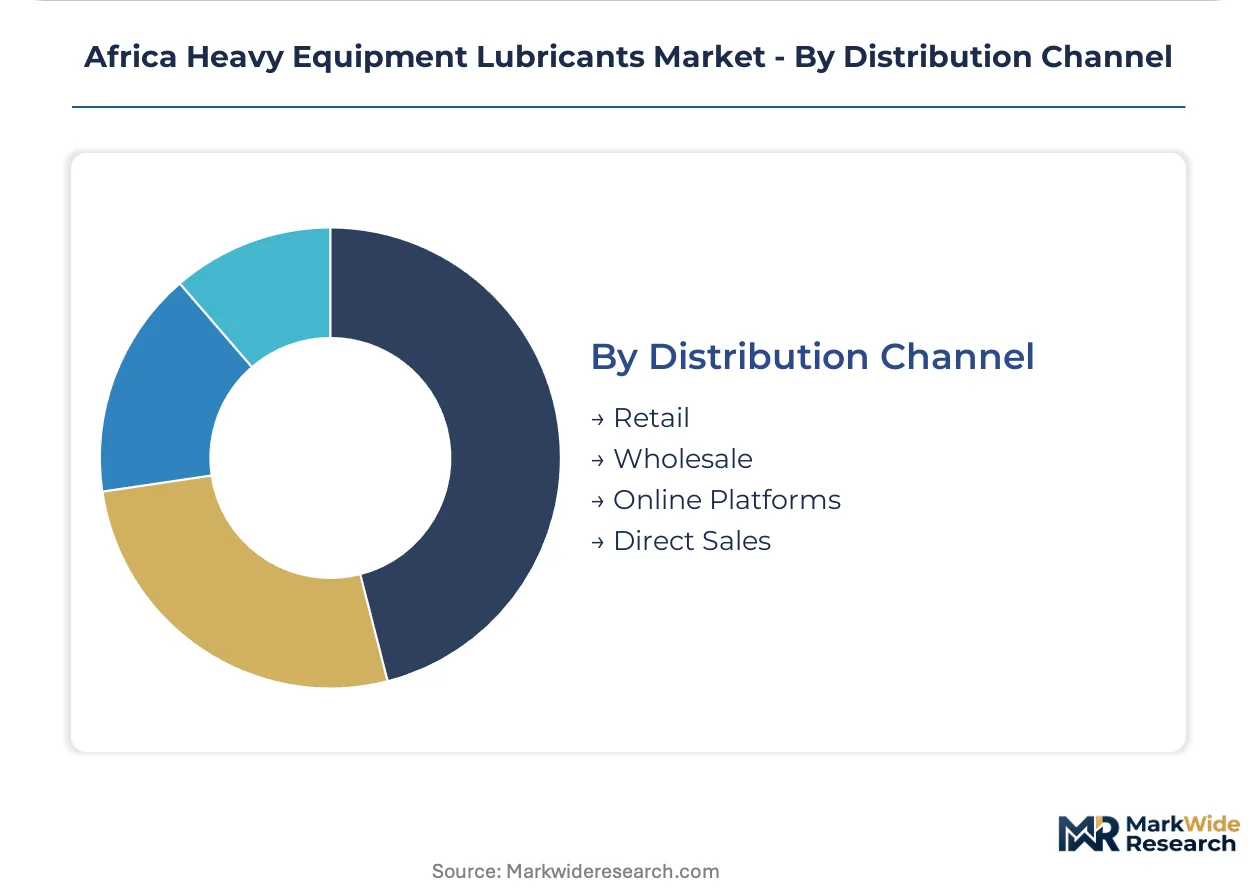
Distribution Channel:
Supply concentration in coastal hub cities shapes how lubricants reach inland equipment clusters.
- Wholesale:Bulk shipments through Rotterdam and Singapore trading hubs feed regional blending operations. Currency mismatches against local tender currencies expose importers to volatility.
- Direct Sales:Major suppliers bypass distributors for mining contracts in the Copperbelt. TotalEnergies leverages Angolan refining capacity to sustain captive supply chains for West African ports.
- Retail:Service stations and parts dealers serve fragmented construction and agricultural demand. Counterfeit formulation penetration undercuts premium pricing in Nigerian distribution zones.
- Online Platforms:Digital procurement penetration remains limited by field technician scarcity and oil analysis capability gaps across Francophone West African operations.
Wholesale channels dominate volume flows, with direct sales capturing margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized lubricant formulation chemists and field service engineers cluster in Johannesburg and Lagos, anchoring technical support networks that extend into hinterland mining and construction zones. These talent concentrations determine where blending operations and distribution hubs locate.
South Africa
The national carbon tax mechanism penalizes high-emission diesel fleets, forcing rapid reformulation toward lower-viscosity synthetics. BIS-equivalent standards tighten product registration requirements for imported consignments. Rustenburg and Limpopo mining clusters unbundle lubricant procurement from OEM service contracts to reduce tax exposure.
Zambia
Copperbelt mining operations double mechanized extraction capacity, concentrating demand for high-load-bearing hydraulic fluids. The country's environmental regulator audits emissions at major construction sites. Kitwe and Ndola logistics corridors face limited local blending infrastructure for synthetic formulations.
Ghana
Emerging oil and gas infrastructure construction generates concentrated demand for off-highway lubricants. The EPA aligns emissions enforcement with lubricant quality audits at project sites. Takoradi and Tema ports receive bulk shipments feeding the infrastructure corridor.
Nigeria
SONCAP certification framework tightens product registration requirements for imported lubricant consignments. Unregistered consignments bypassing certification undercut premium pricing in Lagos and Port Harcourt distribution zones. The petroleum regulator's sulfur limits are converging toward European thresholds.
Kenya
Construction site emissions audits incorporate lubricant quality verification, positioning registered suppliers for Nairobi and Mombasa infrastructure tenders. NEMA enforcement aligns with EU Green Deal biodegradability thresholds. The Nairobi-Mombasa development axis concentrates project-based purchasing.
Africa Heavy Equipment Lubricants Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers. The vendor base stratifies between integrated energy majors with captive base oil supplies and independent blenders reliant on traded feedstocks. Three archetypes dominate: vertically integrated refiners with African production assets, global lubricant marketers leveraging trading network scale, and regional independents serving price-sensitive construction segments. Competitive moves center on backward integration into base oil sourcing and direct sales bypass of distributor markups for mining contracts.
Among integrated majors, TotalEnergies SE leverages Angolan refining capacity to sustain captive supply chains for West African ports. Shell PLC anchors its position through backward integration into base oil trading networks serving Lagos and Durban distribution hubs. ExxonMobil Corporation occupies a position exemplifying the global marketer archetype with formulation standardization across multiple African markets.
| Leading Market Players |
|---|
| TotalEnergies SE |
| ExxonMobil Corporation |
| Shell PLC |
| BP PLC |
| FUCHS Lubricants Co. |
| Chevron Corporation |
| Castrol Limited |
| Engen Petroleum Ltd |
| PetroSA Lubricants |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-sourced Group II base oil quotations cascade through African blending operations into three distinct pricing tiers, with freight differentials and carbon tax exposure separating premium synthetic formulations from mineral-based alternatives across South African and Copperbelt mining contracts.
Pricing Analysis
The bundled-vs-unbundled service split now defines pricing architecture across African mining clusters. Fleet operators in Rustenburg and Limpopo unbundle lubricant procurement from OEM dealer contracts to capture direct distributor pricing, while construction projects in Ghana's infrastructure corridor absorb bundled service premiums. Price differentiation rests on API certification tier and after-sales oil analysis support. Cost compression in the standard mineral tier intensifies as Nigerian unregistered consignments bypass SONCAP fees. Repair workshops in Lagos distribution zones exhibit highest price sensitivity; mining fleet operators with carbon tax liabilities show lowest sensitivity to synthetic premiums.
Supply Chain Analysis
Freight rate volatility on Rotterdam-Durban and Singapore-Mombasa routes compresses blender margins against fixed tender pricing in local currencies. Supply concentrates in Belgium, Singapore, and South Africa as primary base oil sourcing nodes, with Angolan refining capacity serving West African captive supply chains. African blending operations draw from Group II and Group III base stocks, additive packages from European formulators, and specialized ester base stocks for biodegradable hydraulic fluids. Single-source vulnerability runs through the Singapore trading hub for Asia-origin feedstocks. Distribution runs through coastal port cities with inland logistics corridors serving Copperbelt and East African agricultural zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with South Africa's carbon tax mechanism creating synthetic formulation demand at 40-60% price premiums over mineral alternatives sold in unregulated West African corridors.
For Market Incumbents: Hedge carbon tax exposure by accelerating backward integration into Angolan or South African base oil production. Defensive consolidation should prioritize capturing mobile blending capabilities for Ethiopia's mechanized agriculture expansion before distribution networks mature. Counterfeit formulation penetration in Nigerian retail channels demands enhanced SONCAP compliance enforcement as a competitive moat. For New Entrants and Emerging Players: Launch via direct sales contracts for Copperbelt mining operations, bypassing established distributor networks concentrated in coastal hubs. Ethiopia's Oromia and Amhara regions present the most penetrable geography, with tractor penetration outpacing lubricant distribution infrastructure. Position biodegradable hydraulic fluid formulations for forestry and environmentally sensitive mining contracts where EU Green Deal specifications filter into African tender requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with regional independents possessing established blending infrastructure in underpenetrated East African corridors. Long-term viability favors assets with captive base oil sourcing or refining partnerships that insulate against freight rate volatility. Monitor API certification backlog resolution in Johannesburg and Lagos as an inflection indicator for new formulation market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Production | Captive supply from Angolan refining capacity insulates TotalEnergies against Rotterdam freight volatility. |
| Mobile Blending Unit Deployment | First-mover positioning in Ethiopia's Oromia region captures mechanized agriculture demand ahead of fixed infrastructure. |
| Biodegradable Formulation Certification | REACH-compliant additive packages unlock premium tender pools in Kenyan NEMA-audited construction sites. |
| Direct Sales Channel Bypass | Unbundled procurement from OEM service contracts captures margin expansion in South Africa's platinum belt. |
| Regulatory Compliance Investment | SONCAP registration creates defensive moats against counterfeit undercutting in Nigerian distribution zones. |
Study Parameters
Multiple input streams — maintenance director interviews at Copperbelt mining operations, procurement lead discussions with West African construction contractors, and technical R&D director engagements with European additive suppliers — were reconciled against customs trade data, national petroleum regulator filings, and SEC disclosures from integrated energy majors. Bottom-up equipment fleet analysis and top-down lubricant consumption modeling were cross-validated through triangulation.
Data-stream reconciliation anchored volume projections across product type, application sector, and end-user archetype dimensions throughout the forecast period. CAGRs were derived from equipment replacement cycle analysis, mechanization penetration curves in agriculture, and mining fleet expansion schedules. Industry-specific inputs included carbon tax liability calculations for South African operators and biodegradable specification adoption rates in EU-linked mining contracts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged API certification delays or abrupt carbon tax rate adjustments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Mexico Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Yarn Lubricant Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Lube Skid Market
Lubricants
Bulgaria Lubricants Market
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Philippines Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Kenya Lubricants Market