
 Global Compressor Oil Market | 2026-2036
Global Compressor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Compressor Oil Market Foresight
Buyer concentration among manufacturing plants and power generation utilities is realigning procurement leverage toward volume-contract frameworks. ExxonMobil Corporation leverages its integrated base oil network to secure feedstock cost advantages across regions. Shell anchors its position through synthetic formulation leadership for high-pressure gas compression. FUCHS specializes in tailored food-grade lubricants that meet strict contamination protocols for beverage facilities.
Compressor oil is a formulated lubricant comprising base stocks and additive packages designed to reduce friction, dissipate heat, and seal clearances in positive-displacement and dynamic compressors, with viscosity grades typically ranging from ISO 32 to ISO 100 for industrial service. Its primary purpose is extending equipment life and maintaining energy efficiency in continuous-duty machinery. Synthetic oil commands premium positioning due to extended drain intervals and thermal stability under severe operating conditions. Refrigeration systems represent a structurally growing application segment as cold-chain investments expand. Bulk containers dominate packaging for manufacturing plants while drums retain share in maintenance-repair operations.
The EPA regulates volatile organic compound emissions from compressor vents in US industrial facilities, while REACH governs chemical registration and restriction across European supply chains. China's MEE enforces emissions standards that push facilities toward higher-performance lubricant formulations. Stakeholders must monitor regulatory divergence on additive chemistries and base stock classifications to anticipate reformulation costs and compliance timelines.
Market Dynamics
EU F-Gas Regulation is forcing refrigerant system redesigns that cascade into lubricant specification upgrades across industrial supply chains. Compressor oil formulators must now engineer products that maintain performance under tighter containment protocols while serving longer drain intervals demanded by automated manufacturing plants.
Growth Catalysts
- Refrigeration cold-chain buildout:Food and pharmaceutical logistics networks in China and India are scaling industrial refrigeration capacity that requires specialized synthetic lubricant formulations.
- REACH chemical registration:European chemical governance is elevating performance standards for compressor oils used in high-pressure gas applications, creating premium formulation demand.
- Automated manufacturing density:Continuous-duty production lines in automotive and electronics assembly plants are specifying extended-drain synthetic grades to minimize maintenance downtime.
Market Restraints
- Base stock supply concentration:API Group II and III base oil production clusters in the US Gulf Coast and Singapore create feedstock vulnerability for independent blenders.
- Refrigerant-lubricant compatibility lock-in:OEM-approved oil specifications for HFO refrigerant systems limit formulation flexibility and extend qualification timelines.
- Mineral oil substitution economics:Price-sensitive maintenance operations in Southeast Asian textile and small-scale food processing continue specifying conventional mineral grades.
Strategic Opportunities
- Food-grade certification expansion:FSSAI and FDA food-contact approvals for compressor oils serving beverage carbonation and dairy processing open premium positioning in India and North America.
- Carbon intensity accounting:EU Green Deal corporate sustainability reporting requirements create demand for lifecycle-assessed lubricant products with verified emission footprints.
- Predictive maintenance integration:IoT sensor deployment in industrial compressors enables condition-monitoring services bundled with oil supply contracts.
Industry Challenges
- Refrigerant transition qualification:OEM approval processes for new low-GWP refrigerant compatibility require 18-24 month testing cycles that delay product commercialization.
- Additive chemistry registration:Divergent chemical substance inventories between REACH, EPA TSCA, and China's MEE create compliance fragmentation for multinational formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Compressor Oil Market |
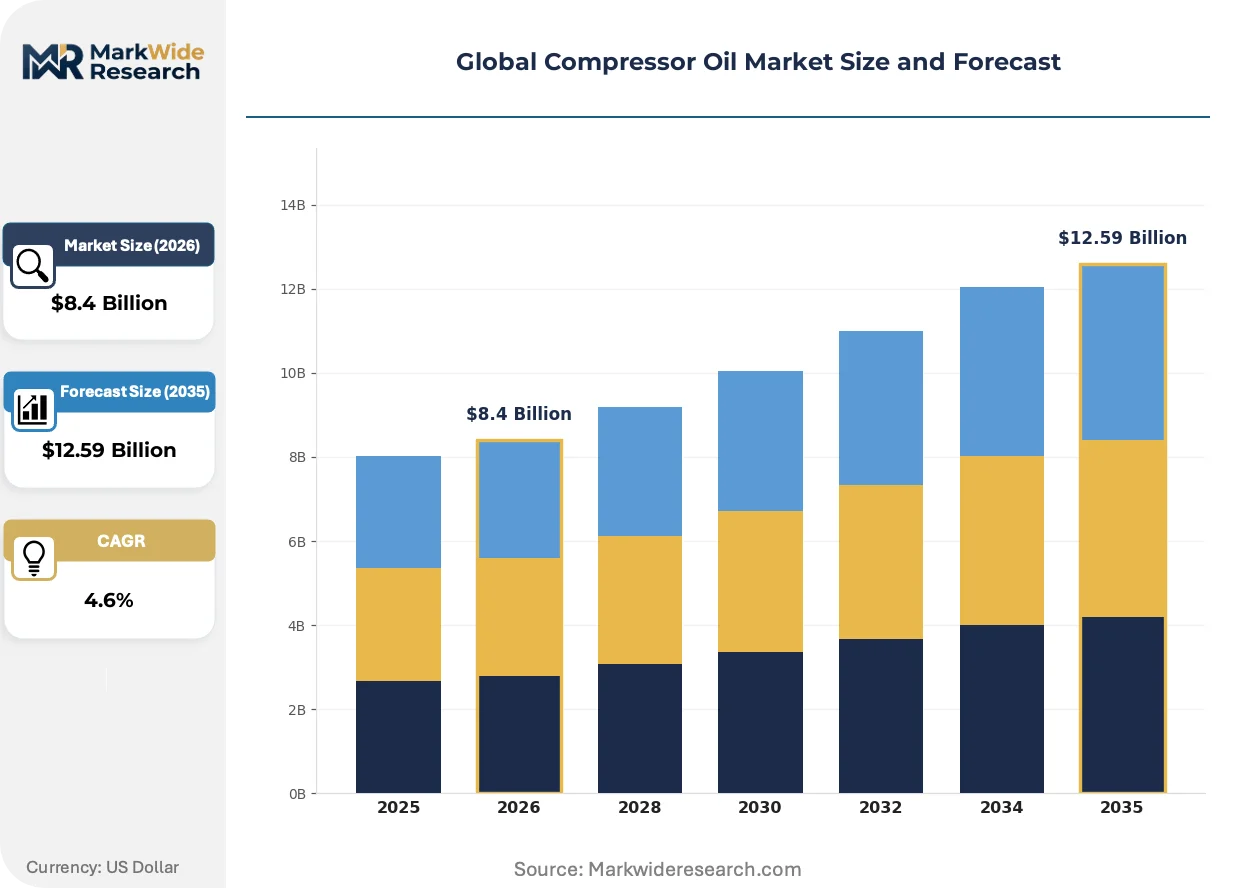
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.59 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-based Oil Application: Refrigeration Systems, Pneumatic Systems, Gas Compression, HVAC Systems End User: Manufacturing Plants, Power Generation, Chemical Processing, Food & Beverage Facilities Packaging Type: Drums, Totes, Bottles, Bulk Containers |
| Companies Covered | Shell, ExxonMobil Corporation, Chevron Corporation, BP, TotalEnergies, FUCHS, Sinopec Corporation, Repsol, Indian Oil Corporation Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Compressor Oil Market Shifts & Advancements
Synthetic base stock technology is overtaking mineral formulations across industrial compressor applications. Formulation science, regulatory chemistry, and service model reinvention are converging to reshape competitive positioning in lubricant supply.
Polyalkylene glycol (PAG) and polyolester (POE) synthetic base stocks are overtaking mineral oil in refrigeration compressor applications due to superior miscibility with HFO refrigerants. Cold-chain operators in Germany and Japan are specifying these grades for new installations. The shift is compressing demand for conventional naphthenic mineral oils in original equipment specifications.
EPA volatile organic compound regulations for industrial vents are tightening emission thresholds for compressor oil mist and blow-by gases. US chemical processing and petrochemical facilities face retrofit obligations for closed crankcase ventilation systems. Synthetic formulations with lower volatility profiles are capturing preference in Texas and Louisiana refining corridors.
Volume-contract procurement is consolidating purchasing power among multinational manufacturing conglomerates. Tier-one automotive and electronics assemblers are unbundling lubricant supply from equipment maintenance agreements. German and South Korean industrial clusters exhibit the strongest concentration of direct sourcing relationships with base oil producers.
Global Compressor Oil Market Segmentation
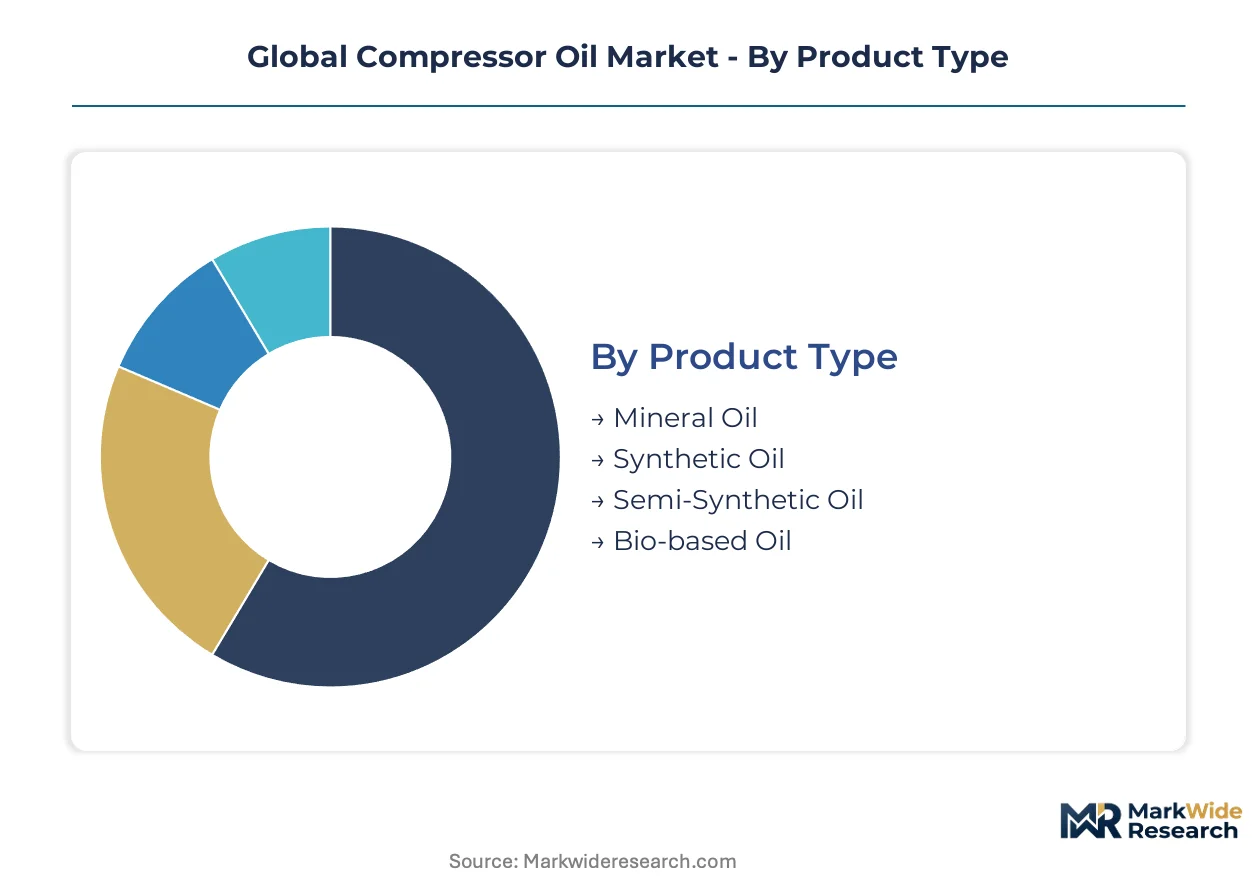
Compressor oil segmentation reveals distinct performance tiers that map directly to equipment duty cycles and regulatory exposure. Product chemistry, application environment, and procurement scale together determine margin structures and supplier positioning across industrial supply chains.
Product Type:
Synthetic formulations integrate deeply into OEM specifications and extended-drain service contracts, while mineral grades remain embedded in legacy maintenance routines and price-sensitive procurement.
- Mineral Oil:Refined petroleum distillates with additive packages for oxidation and rust inhibition. Demand concentrates in Southeast Asian textile mills and small-scale food processors where procurement prioritizes unit cost over drain interval extension. REACH chemical restrictions are gradually narrowing formulation flexibility for European supply.
- Synthetic Oil:Engineered base stocks including polyalphaolefins, esters, and PAGs delivering thermal stability and low volatility. German automotive assembly plants and Japanese electronics fabs specify these grades for continuous-duty automation lines where unplanned downtime carries severe cost penalties. EPA vent emission thresholds in Texas and Louisiana refining corridors accelerate substitution away from higher-volatility mineral alternatives.
- Semi-Synthetic Oil:Blended base stocks balancing performance upgrade against mineral oil economics. Indian chemical processing clusters and Brazilian sugar-ethanol facilities represent concentrated uptake zones.
- Bio-based Oil:Vegetable-derived esters with biodegradability credentials for environmentally sensitive installations. Nordic forestry equipment and Alpine hydropower stations drive niche specification.
Mineral oil leads volumes today; synthetic oil is gaining share fastest.
Application:
Application segmentation tracks refrigerant chemistry transitions and pressure regime demands that reshape lubricant specification authority.
- Refrigeration Systems:Specialized lubricants engineered for miscibility with HFO and natural refrigerants. Cold-chain infrastructure buildout in China and India is scaling industrial refrigeration capacity that requires POE and PAG synthetic formulations. EU F-Gas Regulation containment protocols cascade into lubricant performance upgrades across European food logistics networks.
- Pneumatic Systems:Compressor oils for air compression equipment in manufacturing automation. South Korean automotive component plants and Mexican electronics maquiladoras specify extended-drain synthetics to synchronize with predictive maintenance cycles.
- Gas Compression:High-pressure lubricants for natural gas processing and pipeline transmission. Gulf Coast petrochemical complexes and North Sea offshore platforms anchor demand concentration.
- HVAC Systems:Lubricants for commercial building climate control compressors. US commercial real estate retrofits and Middle East district cooling projects represent primary demand nodes.
Refrigeration systems command premium formulation margins; gas compression offers the steepest expansion trajectory.
End User:
End user segmentation reflects divergent procurement sophistication between integrated operators and fragmented maintenance buyers.
- Manufacturing Plants:High-volume consumers with direct sourcing relationships to base oil producers. German and South Korean industrial clusters exhibit the strongest concentration of unbundled lubricant procurement separate from equipment service agreements.
- Power Generation:Utility-scale operators with extended-drain specifications for turbine and auxiliary compressors. US independent power producers and Saudi combined-cycle facilities anchor regional demand patterns.
- Chemical Processing:Process-critical applications with stringent compatibility requirements for reactive gas environments. Texas and Rotterdam refining corridors represent specification leadership zones.
- Food & Beverage Facilities:Contamination-sensitive operations requiring NSF H1 food-grade certification. FSSAI approvals in India and FDA compliance in North America create dual-registration burdens for suppliers targeting premium positioning.
Manufacturing plants dominate procurement scale; food and beverage facilities deliver the fastest margin expansion.
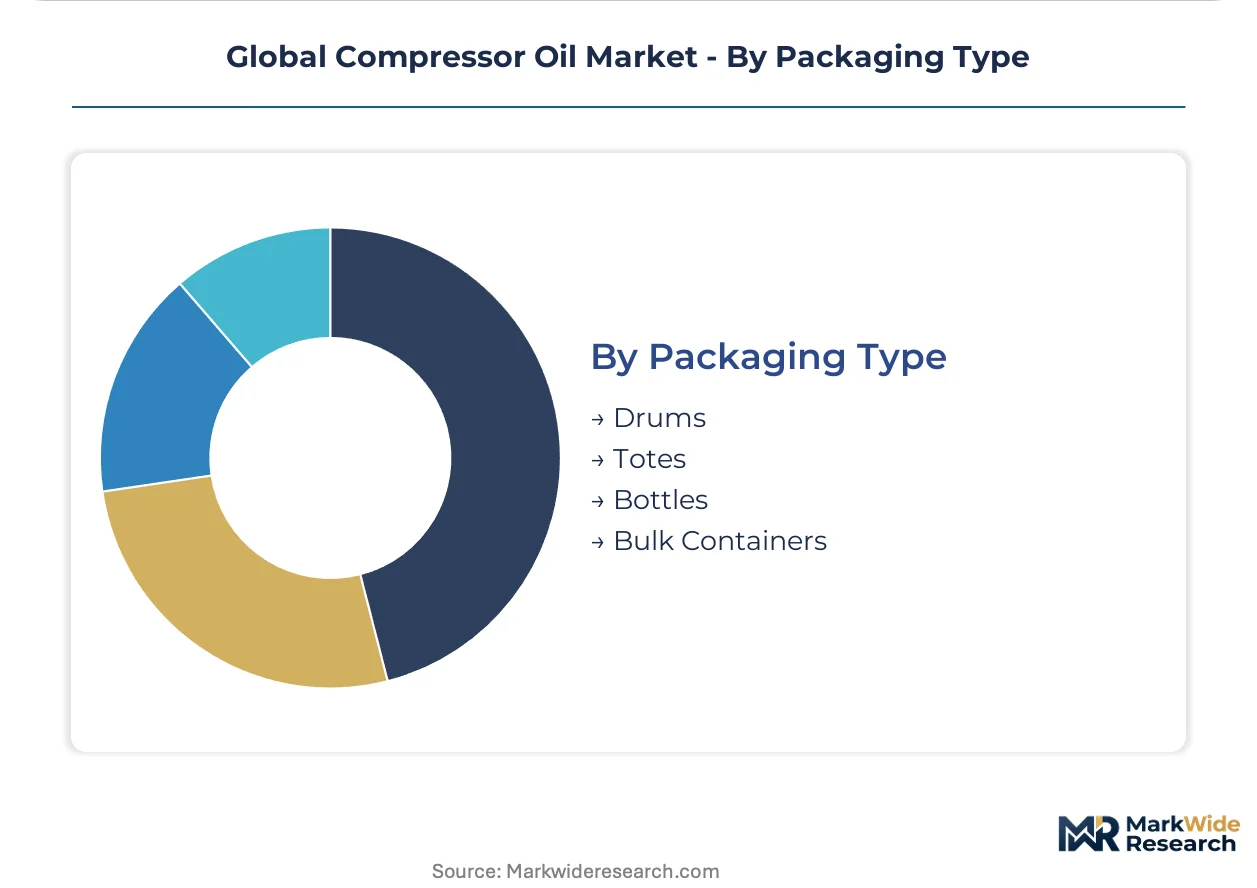
Packaging Type:
Packaging configuration aligns with inventory velocity and handling infrastructure across distinct operational scales.
- Drums:Standard 55-gallon steel containers for maintenance-repair-operations inventory. Independent service contractors and small industrial facilities in Indonesia and Vietnam rely on this format.
- Totes:Intermediate bulk containers for medium-volume consumers with limited tankage. Brazilian mid-tier food processors favor this configuration.
- Bottles:Small-format packaging for portable equipment and field service applications. Mining and construction sectors in Australia and Chile drive specification.
- Bulk Containers:Tank truck and railcar deliveries for integrated manufacturing sites with on-site storage. Chinese chemical processing complexes and US Gulf Coast refineries concentrate demand for this lowest-unit-cost format.
Bulk containers capture the largest volume flows; totes are climbing fastest as mid-tier facilities upgrade from drums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation density contrasts sharply with India's price-sensitive maintenance culture, yet both drive compressor oil procurement through fundamentally different performance specifications. Japan and China anchor synthetic formulation demand in Asia, while Texas refining corridors shape North American emission-compliant lubricant preferences.
United States
Gulf Coast petrochemical complexes and Texas refining corridors anchor gas compression lubricant demand. EPA volatile organic compound regulations for industrial vents tighten emission thresholds for compressor oil mist. Houston-area chemical processors retrofit closed crankcase ventilation systems, accelerating preference for lower-volatility synthetic formulations.
Germany
Automotive assembly plants and industrial automation clusters specify extended-drain synthetic grades. EU F-Gas Regulation containment protocols cascade into lubricant performance upgrades across food logistics networks. Bavarian electronics fabrication facilities and Baden-Württemberg machinery builders unbundle lubricant procurement from equipment service agreements.
China
Cold-chain infrastructure buildout and chemical processing expansion scale industrial refrigeration capacity. MEE emissions standards push facilities toward higher-performance lubricant formulations. Yangtze River Delta chemical complexes and Pearl River Delta manufacturing hubs concentrate bulk container procurement for continuous-duty automation lines.
India
Food and pharmaceutical logistics networks scale industrial refrigeration requiring specialized synthetic formulations. FSSAI food-contact approvals create registration burdens for suppliers targeting beverage carbonation and dairy processing. Maharashtra chemical processing clusters and Gujarat textile mills diverge sharply between premium synthetic specification and mineral grade procurement.
Japan
Electronics fabrication and precision machinery sectors specify thermal-stable synthetics for unplanned downtime avoidance. METI industrial efficiency standards elevate equipment maintenance protocols. Kansai region automotive component plants and Chubu industrial corridors anchor demand concentration for predictive maintenance-integrated lubricant supply contracts.
Global Compressor Oil Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a tiered structure where scale advantages clash with customization agility. Integrated energy majors leverage captive base oil production while independent blenders concentrate on application-specific certifications. Three archetypes dominate: vertically integrated petrochemical majors, specialized lubricant formulators, and regional state-owned oil companies. Competitive moves center on synthetic formulation leadership acquisitions and direct sourcing relationships with high-volume manufacturing conglomerates.
Among integrated energy majors, Shell, ExxonMobil Corporation, and BP occupy positions exemplifying scale-driven formulation science and feedstock cost control. These London-, Houston-, and London-headquartered entities respectively anchor synthetic leadership for high-pressure gas compression, integrated base oil network advantages, and broad geographic coverage. FUCHS represents the specialized formulator archetype, sitting within the tailored certification tier where food-grade and contamination-sensitive applications command premium positioning. Sinopec Corporation anchors the state-owned tier, reflecting Beijing-based resource integration into industrial lubricant supply across Asia-Pacific manufacturing corridors.
| Leading Market Players |
|---|
| Shell |
| ExxonMobil Corporation |
| Chevron Corporation |
| BP |
| TotalEnergies |
| FUCHS |
| Sinopec Corporation |
| Repsol |
| Indian Oil Corporation Ltd |
| Others |
Supply & Pricing Matrix
EU Green Deal corporate sustainability reporting requirements gate qualified supply access and premium-tier pricing power for compressor oil formulators seeking verified emission footprint credentials. Buyers without carbon intensity accounting capabilities face exclusion from German automotive and South Korean electronics procurement frameworks.
Pricing Analysis
Capacity additions in Singapore and the US Gulf Coast are reshaping price floors for API Group II and III base oils. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels stratifies by certification grade and volume scale. Cost compression in mineral grades intensifies as Indian textile mills and Indonesian food processors prioritize unit economics over drain interval extension. Manufacturing plants with direct base oil producer relationships exhibit lowest price sensitivity; independent maintenance contractors in Southeast Asia show highest.
Supply Chain Analysis
Specialty additive packages rest on German and US chemical producers for antioxidant and anti-wear components. Base stock supply draws from Singapore, the US Gulf Coast, and Middle Eastern refining complexes. Single-source vulnerability concentrates in HFO refrigerant-compatible POE and PAG synthetic formulations. Distribution runs through integrated lubricant distributors serving manufacturing clusters, with bulk railcar and tank truck delivery dominating Chinese chemical processing and US petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compressor oil market functions as a regulatory compounder where EU F-Gas Regulation containment protocols cascade through equipment redesigns into lubricant specification upgrades. This regulatory milestone elevates demand for synthetic formulations with extended drain intervals and refrigerant miscibility credentials.
For Market Incumbents: Lock in synthetic formulation leadership through captive base oil supply agreements with Singapore and US Gulf Coast producers. Secure OEM approval pipelines for HFO refrigerant compatibility to forestall emerging pure-play specialists. Invest in predictive maintenance platform integration to bundle condition-monitoring services with volume contracts. For New Entrants and Emerging Players: The mid-tier price-point gap between premium synthetic and economy mineral grades offers white-space targeting for semi-synthetic formulations in Indian chemical processing and Brazilian sugar-ethanol facilities. Food-grade certification expansion in India under FSSAI presents the most penetrable regulatory pathway. Pursue direct sourcing relationships with mid-tier manufacturing conglomerates unbundling lubricant procurement from equipment service agreements. For Investors and Strategic Acquirers: Roll-up economics work for specialized food-grade formulators because contamination-sensitive applications command premium positioning with limited supplier lists. Long-term viability centers on synthetic base stock technology capabilities and refrigerant transition qualification pipelines. Watch for OEM approval completion timelines as inflection indicators for product commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Base Stock Capacity Expansion | Captive POE and PAG production secures feedstock cost advantages for HFO refrigerant formulations. |
| Backward Integration into Additive Chemistry | In-house antioxidant and anti-wear package development accelerates REACH and EPA TSCA compliance timelines. |
| Food-Grade Certification Program | Dual FSSAI and FDA registration opens premium positioning in Indian beverage carbonation and North American dairy processing. |
| Predictive Maintenance Platform Integration | IoT sensor deployment enables condition-monitoring services bundled with extended-drain synthetic supply contracts. |
| Long-Term Supply Agreement with Base Oil Producers | Direct procurement relationships with Singapore and US Gulf Coast refineries secure volume pricing for manufacturing plant customers. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners triangulate against customs and trade data, SEC filings, and ACC industry reports. Bottom-up volume modeling and top-down value reconciliation cross-validate segment-level outputs.
Granularity extends to product chemistry, application environment, end-use industry, and packaging format across the projection horizon. CAGRs derive from equipment installation forecasts, refrigerant transition timelines, and manufacturing automation density indices. Modeled inputs include cold-chain infrastructure investment flows, EU F-Gas Regulation compliance deadlines, and EPA vent emission threshold implementations.
Caveats apply where refrigerant-lubricant compatibility testing cycles or divergent chemical substance inventories between REACH, EPA TSCA, and China's MEE could materially shift the outlook. Material deviation in OEM approval timelines or base stock supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Qatar Automotive Lubricants Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
Drilling Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Indonesia Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
India Lubricants Market
Lubricants
Automotive Die Casting Lubricants Market