
 Qatar Automotive Engine Oils Market | 2026-2036
Qatar Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Automotive Engine Oils Market Outlook
The capital-intensity divergence between fully integrated blenders and toll-mixing operators is reorganizing Qatar's automotive engine oils competitive landscape. ExxonMobil Corporation leverages its integrated base oil supply chain to sustain margin stability across premium synthetic grades. Royal Dutch Shell PLC anchors its position through dedicated technical service teams embedded with fleet operators in Doha's logistics corridors. Qatar Lubricants Company (QALCO) competes on proximity, with local blending capacity enabling rapid replenishment of high-turnover viscosity grades.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and prevent wear in internal combustion engines, with synthetic variants engineered from poly-alpha-olefins to withstand thermal breakdown under Qatar's extreme ambient temperatures exceeding 45°C. The primary commercial purpose centers on extending engine operational life while maintaining fuel efficiency across passenger and commercial vehicle fleets operating in arid conditions. Synthetic formulations command the dominant margin pool as OEM fill specifications trend toward lower-viscosity 0W-20 and 5W-30 grades, while heavy-duty trucks sustain steady offtake of 15W-50 mineral and semi-synthetic products under severe load cycles. Passenger cars represent the volume anchor, though commercial vehicles generate higher per-unit lubricant consumption and more predictable drain-interval revenue.
The Ministry of Municipality and Environment enforces waste oil collection and recycling mandates that elevate compliance costs for independent workshops, while Qatar Standards (QS) alignment with API SN and ACEA sequences shapes product registration requirements for imported formulations. The General Authority of Customs applies Gulf Technical Regulation for lubricating oils, creating a harmonized barrier-to-entry framework across GCC member states. Stakeholders must monitor how Qatar's National Environment and Climate Change Strategy alters extended producer responsibility obligations for lubricant packaging and spent oil recovery infrastructure.
Market Dynamics
Fleet operators in Doha's logistics corridors are consolidating maintenance contracts, compressing procurement cycles and forcing lubricant suppliers to embed technical service teams directly at commercial vehicle hubs. This buyer-side concentration is restructuring margin capture across Qatar's automotive engine oils value chain.
Growth Catalysts
- Scheduled Maintenance Mandates:Fleet operators across Qatar's logistics corridors are expanding preventive service programs, creating predictable drain-interval revenue streams for high-turnover viscosity grades.
- QS Alignment with API SN:Qatar Standards harmonization with international sequences is elevating product registration requirements, filtering out substandard imports and benefiting registered formulation suppliers.
- Synthetic Formulation Migration:OEM fill specifications trending toward lower-viscosity 0W-20 and 5W-30 grades are displacing mineral base stocks in passenger car segments.
Market Restraints
- Group II/III Base Oil Import Dependence:Qatar lacks domestic base oil production, exposing blenders to freight cost volatility and Middle East refinery output fluctuations.
- Waste Oil Compliance Burden:The Ministry of Municipality and Environment's tightening disposal protocols elevate operational costs for independent workshops, compressing their purchasing power for premium lubricants.
- Extended Drain Interval Technology:Advanced additive packages enabling longer service intervals reduce per-vehicle lubricant consumption volume over fleet lifecycles.
Strategic Opportunities
- Ras Laffan Industrial Zone Penetration:Heavy equipment fleets operating Qatar's energy infrastructure represent underdeveloped demand for severe-duty 15W-50 and 20W-50 formulations.
- Technical Service Embedding:Lubricant suppliers can capture fleet loyalty by stationing fluid analysis laboratories and drain-interval optimization specialists at major commercial vehicle depots.
- Packaging EPR Pre-Positioning:The National Environment and Climate Change Strategy's anticipated extended producer responsibility mandates create first-mover advantage for suppliers building spent oil recovery infrastructure.
Industry Challenges
- API SN Plus Certification Timelines:New low-speed pre-ignition protection standards require reformulation cycles that strain local blending capacity and delay product launches.
- Additive Package Sourcing Complexity:Proprietary additive systems from Lubrizol, Infineum, and Afton require long-term offtake commitments that constrain formulation flexibility for mid-scale blenders.
- Workforce Fluid Analysis Capability:Independent service centers lack technicians trained in used oil spectroscopy, limiting upsell of condition-based maintenance programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Automotive Engine Oils Market |
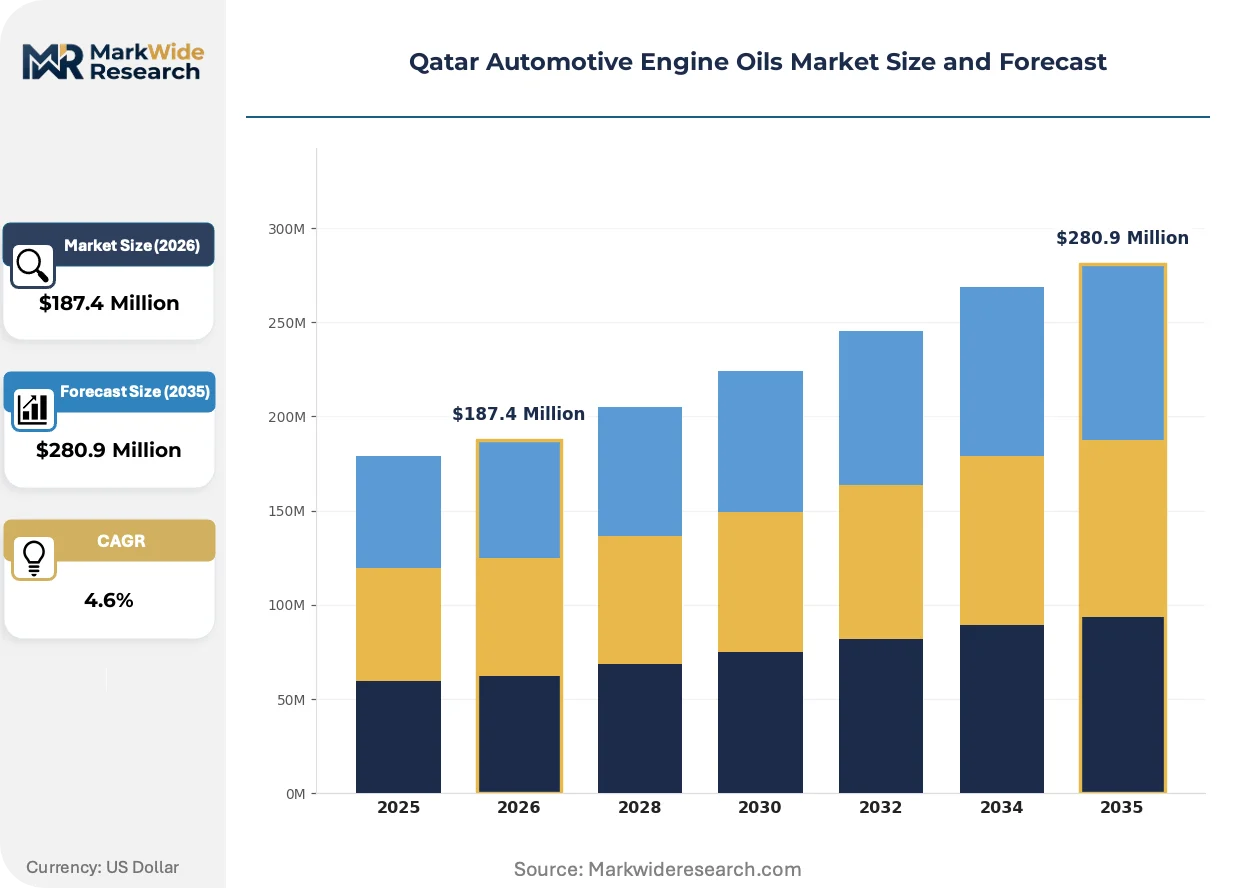
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Bio-Based End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 API Rating: SN, SM, SL, SJ |
| Companies Covered | ExxonMobil Corporation, Royal Dutch Shell PLC, BP PLC (Castrol), TotalEnergies, Chevron Corporation, Qatar Lubricants Company (QALCO), Valvoline Inc., Dana Lubricants Factory LLC, Gulf Continental Oil and Grease Factory (GulfCon), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Automotive Engine Oils Market Strategic Shifts
Formulation chemistry and procurement patterns are diverging simultaneously in Qatar's automotive engine oils market, creating tension between premium synthetic migration and cost-pressured fleet maintenance models.
Poly-alpha-olefin synthetic base stocks are fragmenting the traditional mineral-dominant supply structure. OEM service fill specifications now specify 0W-20 and 5W-30 grades for new passenger vehicles, forcing importers to reconfigure inventory toward lower-viscosity synthetics. This chemistry shift is fragmenting workshop storage requirements and splitting technical training investments across incompatible product categories.
The Ministry of Municipality and Environment's waste oil handling directives are tightening collection and recycling mandates. Independent workshops now face elevated compliance documentation burdens and certified disposal contractor requirements. Commercial vehicle service hubs in Doha's industrial areas are responding fastest, integrating waste oil storage infrastructure to maintain operating licenses.
Fleet procurement is consolidating around multi-year lubricant supply agreements with embedded technical service provisions. Large logistics operators are displacing spot purchasing from independent distributors, instead negotiating direct relationships with blenders offering fluid analysis and drain-interval optimization. This concentration is most visible among temperature-controlled freight operators running refrigerated units under Qatar's extreme ambient thermal load.
Qatar Automotive Engine Oils Market Segmentation
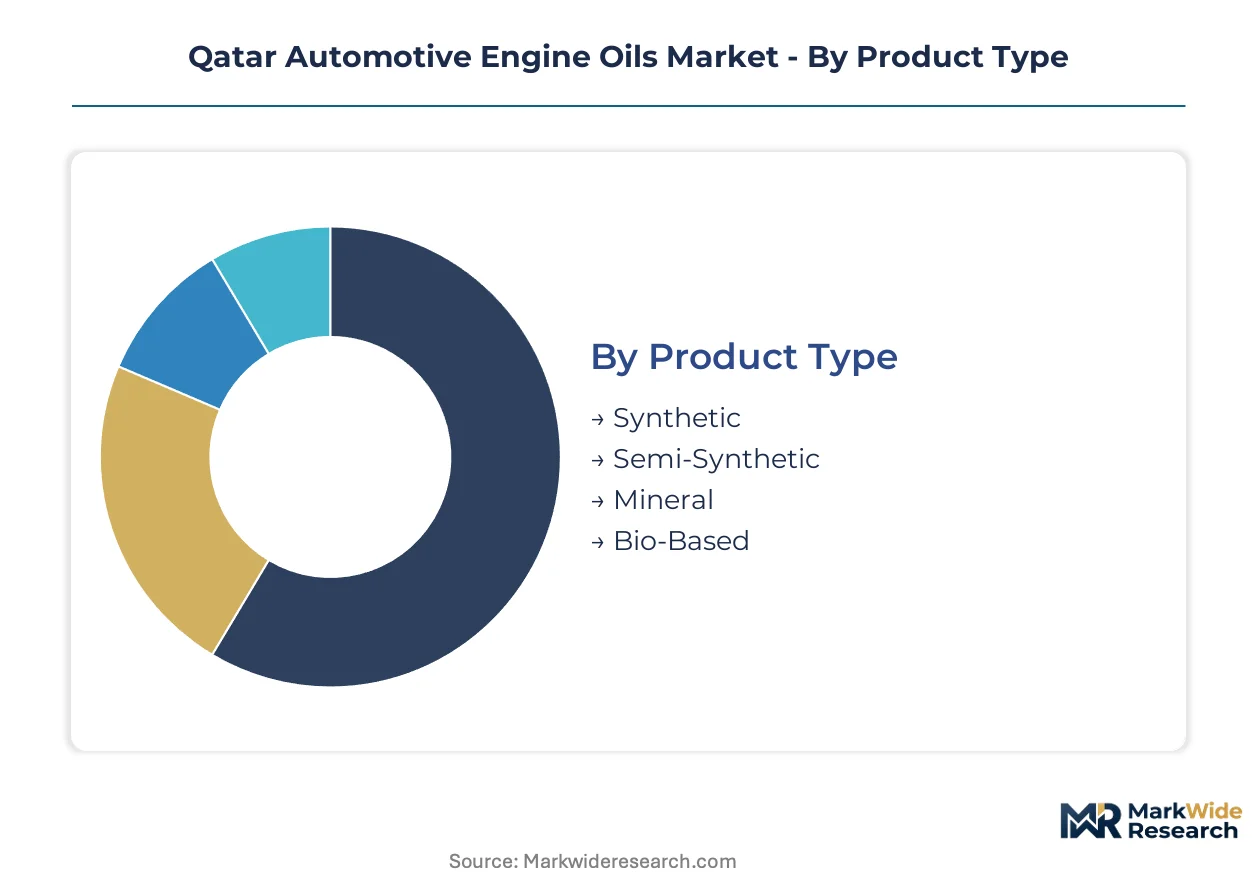
Qatar's automotive engine oils market fragments along technical specifications and duty-cycle demands. Each segmentation dimension carries distinct margin structures and procurement patterns shaped by fleet operator consolidation and OEM service mandates.
Product Type:
Synthetic formulations face substitution pressure from advancing semi-synthetic chemistry that narrows performance gaps at lower price points.
- Synthetic:Engineered from poly-alpha-olefins to withstand thermal breakdown exceeding 45°C ambient temperatures. Demand concentrates in Doha's premium passenger car service centers where OEM fill specifications mandate 0W-20 and 5W-30 grades.
- Semi-Synthetic:Blends Group II/III base oils with synthetic additives to balance cost and performance. Fleet operators in Qatar's logistics corridors favor these formulations for mid-duty commercial vehicles seeking extended drain intervals without full synthetic premiums.
- Mineral:Conventional refined petroleum base stocks serving legacy vehicle populations and price-sensitive independent workshops.
- Bio-Based:Renewable feedstock formulations emerging under Qatar's National Environment and Climate Change Strategy circular economy directives.
Synthetic retains volume leadership; bio-based holds the steepest expansion curve.
End User:
Customer-type segmentation reveals divergent procurement power between consolidated fleet buyers and fragmented retail channels.
- Passenger Cars:Individual vehicle owners and dealership service networks generating high-frequency but low-volume transactions. Ras Laffan commuter corridors and Doha residential districts anchor this segment's geography.
- Commercial Vehicles:Temperature-controlled freight operators and logistics fleets negotiating multi-year supply agreements with embedded technical service provisions. These buyers command pricing leverage through consolidated maintenance contracts.
- Two-Wheelers:Delivery couriers and personal mobility users in Doha's dense urban core.
- Heavy-Duty Trucks:Severe-load operators sustaining steady offtake of 15W-50 formulations under extended haul cycles between industrial zones.
Passenger cars anchor absolute volume; commercial vehicles capture margin concentration.
Viscosity Grade:
Grade specification directly determines additive package requirements and blending complexity across Qatar's supply base.
- 0W-20:Ultra-low viscosity synthetic mandatory for newer passenger vehicle OEM fill specifications. Qatar Standards alignment with API SN elevates registration barriers for non-compliant imports.
- 5W-30:Versatile synthetic grade spanning passenger cars and light commercial duty. Fleet operators in Doha's logistics corridors specify this grade for mixed-vehicle maintenance programs.
- 10W-40:Traditional multi-grade serving older vehicle populations and moderate climate operation.
- 15W-50:Heavy-duty formulation for severe-load engines operating under Qatar's extreme thermal conditions and dust exposure.
5W-30 dominates procurement volume; 0W-20 climbs fastest on OEM specification migration.
API Rating:
Performance tier segmentation filters market access through Qatar Standards harmonization with international sequences.
- SN:Current top-tier specification delivering low-speed pre-ignition protection and turbocharger deposit control. The Ministry of Municipality and Environment's waste oil directives favor registered SN-compliant suppliers with established recovery infrastructure.
- SM:Preceding generation specification sustaining relevance in legacy fleet maintenance and price-competitive service tiers.
- SL:Older passenger car and light truck applications with reduced additive treat rates.
- SJ:Obsolescent rating limited to vintage vehicle preservation and non-critical industrial equipment.
SN commands premium positioning; SM retains transitional volume as fleets upgrade drain intervals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Doha's commercial vehicle service corridors while procurement leverage fragments across Qatar's northern industrial zones. Fleet consolidation in the capital generates volume premiums unavailable to distributors serving scattered retail workshops. The Ministry of Municipality and Environment's waste oil directives apply uniformly, yet compliance infrastructure gaps favor established suppliers in metropolitan clusters.
Doha Metropolitan Area
Temperature-controlled freight operators anchor lubricant demand through multi-year maintenance contracts with embedded technical service provisions. Qatar Standards alignment with API SN elevates registration barriers for non-compliant imports entering through Hamad Port. Doha's logistics corridors concentrate fleet service hubs where fluid analysis laboratories and drain-interval optimization specialists capture buyer loyalty.
Ras Laffan Industrial Zone
Heavy equipment fleets operating Qatar's energy infrastructure sustain offtake of severe-duty 15W-50 and 20W-50 formulations under extended haul cycles. The Ministry of Municipality and Environment enforces waste oil collection mandates that elevate compliance costs for independent contractors serving remote sites. Industrial lubricant demand concentrates around petrochemical processing facilities and LNG export infrastructure.
Al Wakrah and Southern Corridor
Passenger car service centers along the Doha-Al Wakrah expressway generate high-frequency transactions for 0W-20 and 5W-30 synthetic grades. Qatar Standards harmonization with ACEA sequences shapes product registration requirements for workshop chains expanding southward. Residential district clusters sustain independent distributors competing on rapid replenishment of high-turnover viscosity grades.
Al Khor and Northern Industrial Belt
Construction equipment fleets and quarry operators drive demand for mineral and semi-synthetic products under severe dust exposure conditions. The General Authority of Customs applies Gulf Technical Regulation for lubricating oils, creating harmonized entry protocols for formulations crossing from Saudi Arabia and Kuwait. Northern zone workshops lack trained technicians in used oil spectroscopy, limiting condition-based maintenance program penetration.
Al Rayyan and Western Suburbs
Mixed-vehicle maintenance programs spanning passenger cars and light commercial fleets favor versatile 5W-30 synthetic formulations. The National Environment and Climate Change Strategy's anticipated extended producer responsibility mandates prompt suppliers to pre-position spent oil recovery infrastructure. Suburban service centers face compressed margins from buyer-side procurement consolidation while competing for individual vehicle owner traffic.
Qatar Automotive Engine Oils Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across Qatar's automotive engine oils supply base. Fully integrated blenders command formulation chemistry advantages while toll-mixing operators compete on inventory velocity and local replenishment speed. Three archetypes dominate: multinational integrated suppliers with captive base oil supply chains, regional blenders leveraging proximity to Gulf refining capacity, and local toll-mixers serving high-turnover workshop segments. Competitive dynamics center on technical service embedding with fleet operators and pre-positioning compliance infrastructure for tightening waste oil mandates.
Within the multinational integrated tier, ExxonMobil Corporation and Royal Dutch Shell PLC exemplify players sustaining margin stability through backward integration into base oil production and additive package supply chains. Royal Dutch Shell PLC anchors a position through dedicated technical service teams, while Qatar Lubricants Company (QALCO) occupies a distinct archetype as a proximity-focused regional blender enabling rapid replenishment cycles for high-turnover viscosity grades demanded by Doha's commercial vehicle service hubs.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Royal Dutch Shell PLC |
| BP PLC (Castrol) |
| TotalEnergies |
| Chevron Corporation |
| Qatar Lubricants Company (QALCO) |
| Valvoline Inc. |
| Dana Lubricants Factory LLC |
| Gulf Continental Oil and Grease Factory (GulfCon) |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day base oil replenishment cycles from Middle East refineries concentrate procurement leverage among integrated blenders with captive storage, fragmenting pricing power for toll-mixing operators dependent on spot Group II/III cargoes. This inventory-band asymmetry rewards ExxonMobil and Shell with margin stability while compressing mid-scale competitors during freight volatility spikes.
Pricing Analysis
Configured-to-order technical service bundles command 15-25% premiums over standard bulk formulations in Qatar's fleet procurement channels. Contract-based long-term offtake agreements dominate commercial vehicle segments, with price differentiation driven by API SN certification tier and embedded fluid analysis services. Pricing pressure stems from fleet consolidation compressing procurement cycles, while independent workshops remain most price-sensitive due to Ministry of Municipality and Environment compliance cost burdens.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Doha's commercial vehicle service hubs, whereas strategic stockpiling characterizes Ras Laffan energy infrastructure operators facing remote site access constraints. Geographic supply concentrates in Saudi Arabia, Kuwait, and the UAE for Group II/III base oils, with additive packages drawing from Lubrizol and Infineum facilities in Singapore and the US. Single-source vulnerability around proprietary additive systems elevates risk, as distribution runs through Hamad Port clearance and bonded warehouse networks serving industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's automotive engine oils market sits in early-cycle expansion as synthetic formulation migration accelerates across OEM service networks and fleet operators consolidate maintenance contracts. This adoption tailwind rewards players pre-positioning technical service infrastructure and compliance-ready waste oil recovery systems.
For Market Incumbents: Consolidate fleet relationships through embedded fluid analysis laboratories at Doha's logistics corridors, defending against toll-mixing operators undercutting on spot pricing. Deepen backward integration into additive package supply chains to reduce Infineum and Afton offtake commitment constraints, while expanding Ras Laffan industrial zone coverage to capture underdeveloped severe-duty demand.
For New Entrants and Emerging Players: Technical service capability gaps among northern zone independent workshops present white-space entry points for condition-based maintenance programs. Target Al Khor and Al Rayyan suburban service centers with spectroscopy training partnerships, penetrating through rapid-replenishment 5W-30 inventory models rather than competing on synthetic formulation chemistry.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-infrastructure play because extended producer responsibility mandates under Qatar's National Environment and Climate Change Strategy will restructure competitive moats around spent oil recovery capabilities. Acquisition targets should blend local toll-mixing velocity with pre-built waste handling certifications; the signal to watch is Ministry of Municipality and Environment licensing thresholds for independent workshop networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Embedding | Fluid analysis laboratories at Doha fleet depots capture multi-year contract loyalty from temperature-controlled freight operators. |
| Backward Integration into Additives | In-house additive blending reduces Lubrizol offtake commitment constraints and accelerates API SN Plus certification timelines. |
| Waste Oil Recovery Infrastructure | Pre-positioned collection networks secure operating licenses ahead of National Environment and Climate Change Strategy EPR mandates. |
| Ras Laffan Zone Penetration | Severe-duty 15W-50 formulations serve underpenetrated energy infrastructure equipment fleets under extended haul cycles. |
| Workforce Spectroscopy Training | Used oil analysis capability upgrades enable condition-based maintenance upsell at Al Khor and northern belt workshops. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across Qatar's automotive engine oils value chain, combining primary interviews with fleet maintenance directors, blending plant managers, and Ministry of Municipality and Environment compliance officers with secondary validation. Secondary sources included Qatar Standards technical specifications, Gulf Technical Regulation harmonization documents, Hamad Port customs data, and API licensing registries. Bottom-up triangulation across viscosity grade demand and top-down reconciliation with base oil import flows anchored volume estimates.
Across the analysis window, forecasts employed a segmented growth framework modeling synthetic-semi-synthetic-mineral product migration, passenger-commercial-heavy-duty end-use splits, and 0W-20 through 15W-50 viscosity grade trajectories. CAGRs derived from drain-interval frequency modeling tied to fleet expansion rates and OEM specification evolution, with thermal stress coefficients calibrated to Qatar's ambient temperature profiles exceeding 45°C.
Forecasts assume regulatory continuity in Qatar Standards alignment with API SN and ACEA sequences; material policy shifts in extended producer responsibility obligations would require re-modeling. Revision becomes warranted when base oil freight cost volatility or Ministry of Municipality and Environment enforcement intensity crosses thresholds altering independent workshop purchasing power.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Singapore Commercial Vehicles Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
US Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Iran Passenger Vehicles Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Hydropower Lubricants Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Synthetic Ester Lubricants Market