
 Specialties of Lube Oil Refinery Market | 2026-2036
Specialties of Lube Oil Refinery Market Size, Share, and Industry Trends Forecast 2026-2036
Specialties of Lube Oil Refinery Market Intelligence
The rise of asset-light refining models, often enabled through joint ventures and third-party processing agreements, is reconfiguring competitive positioning among specialty lube oil producers. Shell leverages its extensive refining network and integrated supply chain to maintain a dominant market presence. In contrast, specialists like Kluber and Nye Lubricants, Inc. differentiate through deep expertise in high-performance synthetic lubricants for niche industrial applications.
Specialties of lube oil refining encompass advanced processes that convert crude oil fractions into highly purified base oils and finished lubricants. Technologies such as hydrocracking and solvent dewaxing are critical for removing impurities and achieving specific viscosity and thermal stability properties. Synthetic lubricants, often used in demanding engine oil and gear oil applications, represent a high-value product category. Industrial oils for specialized uses like turbine oils provide higher margins compared to commodity automotive grades.
Regulations from the US Environmental Protection Agency (EPA) and Europe's REACH framework govern the chemical composition and environmental impact of lubricants. China's GB standards impose strict performance and quality requirements for lubricants sold within its domestic market. Producers must therefore navigate a complex and diverging set of international standards while investing in formulations that meet future efficiency and sustainability mandates.
Market Dynamics
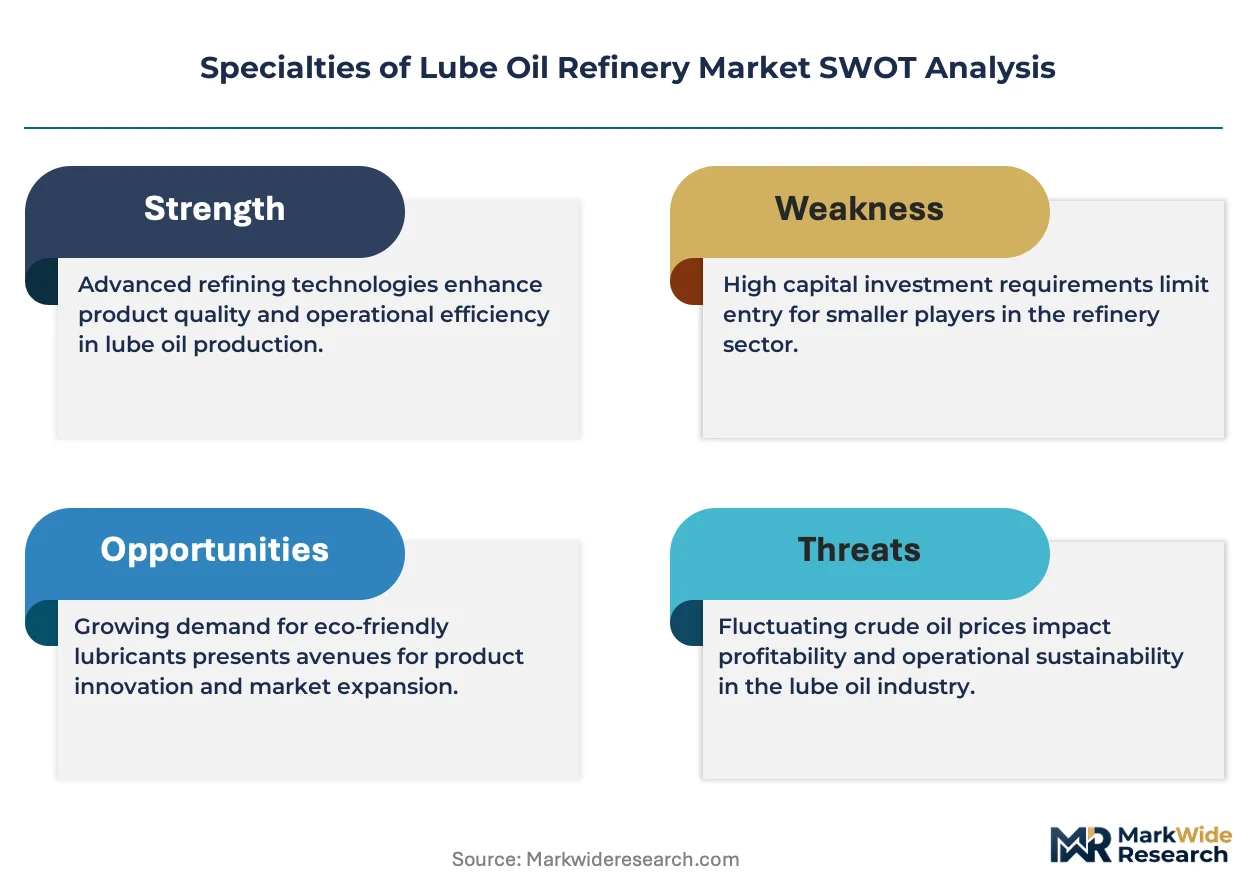
The central structural tension for specialty refiners is the capital-intensive pivot to high-purity base oils, a move necessitated by stringent global emissions standards. This requires significant investment in hydroprocessing technologies to meet performance demands while navigating volatile crude oil feedstock costs.
Growth Catalysts
- Emissions Regulations:Increasingly strict standards, including the EPA's Tier 3 in the US and Euro 7 in Europe, compel the use of advanced Group II and Group III base oils to reduce sulfur and aromatic content in finished lubricants.
- Industrial Automation:The expansion of automated manufacturing and robotics requires high-performance hydraulic fluids and gear oils with superior thermal stability and longevity, creating demand for synthetic and semi-synthetic formulations.
- Aviation Sector Expansion:Growth in commercial air travel, particularly in Asia, fuels requirements for specialized jet engine oils that can perform under extreme temperature and pressure conditions, supporting a high-margin product segment.
Market Restraints
- Feedstock Price Volatility:Fluctuations in the price of crude oil, the primary feedstock, directly impact the production costs and margin stability for specialty lube refineries, making long-term planning difficult.
- Electric Vehicle Transition:The long-term substitution threat from battery electric vehicles reduces the total addressable market for traditional passenger car motor oils, a foundational demand pillar for many refiners.
- High Capital Intensity:Upgrading refineries from producing Group I base oils to advanced Group II/III stocks requires substantial capital expenditure on hydrocracking and catalytic dewaxing units, posing a barrier for smaller operators.
Strategic Opportunities
- Bio-based Lubricants:Developing and marketing biodegradable base oils derived from renewable feedstocks presents an opportunity to capture demand from environmentally conscious customers and meet corporate sustainability mandates.
- EV Thermal Management Fluids:The electric vehicle market creates a new frontier for specialized fluids designed for battery cooling, e-axles, and drivelines, offering a high-value alternative to declining engine oil volumes.
- Data Center Cooling:Formulating immersion cooling fluids for high-density data centers provides a novel, high-performance application for highly refined, dielectric base oils, tapping into a rapidly growing technology sector.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of chemical engineers and formulation scientists with deep expertise in lubricant chemistry and advanced hydroprocessing technologies hinders innovation and operational efficiency.
- Complex Compliance Pathways:Navigating the divergent and often conflicting chemical registration requirements of frameworks like Europe's REACH and China's MEE adds significant cost and time to new product introductions.
- Legacy Asset Modernization:Integrating advanced digital process controls and predictive analytics into older refinery infrastructure is a complex and costly challenge, limiting potential efficiency gains for established facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialties of Lube Oil Refinery Market |
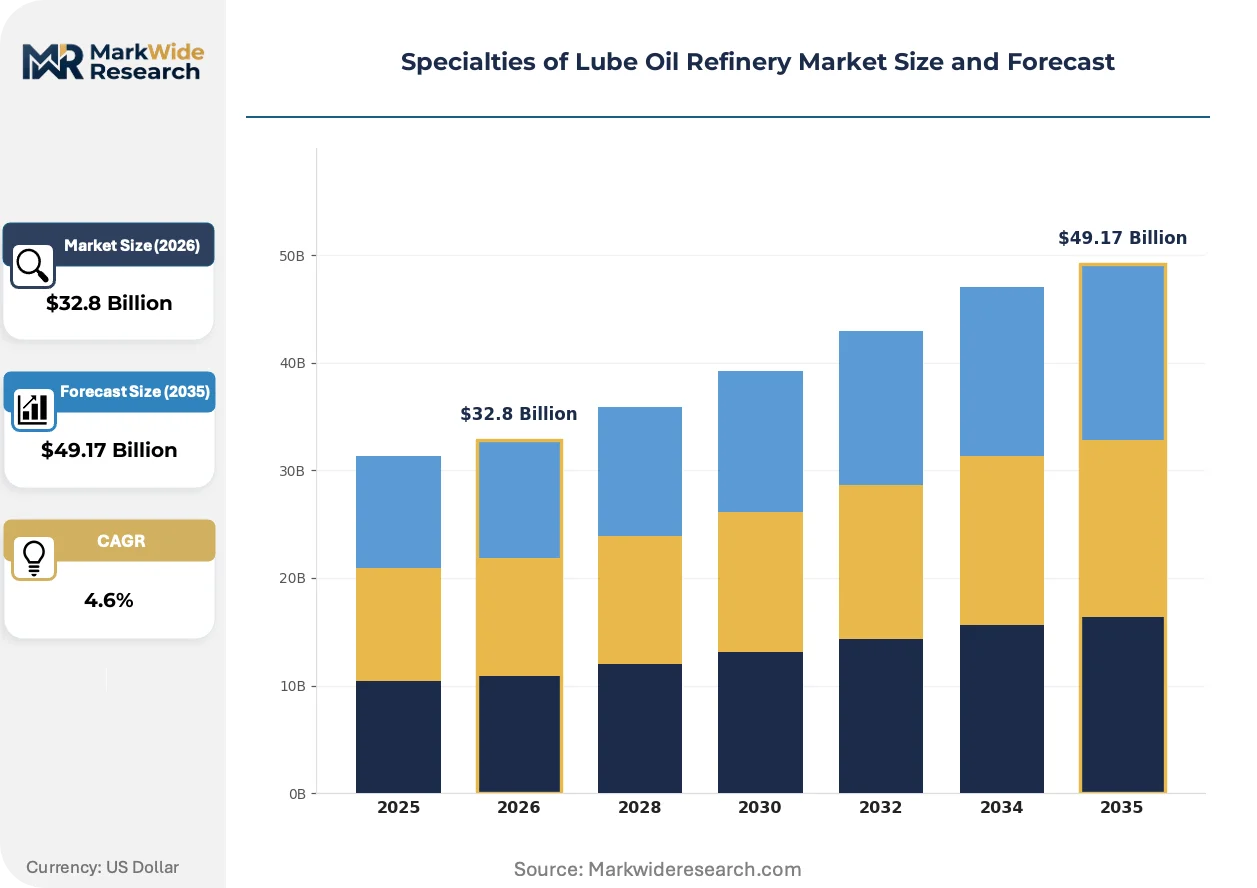
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Oil, Additives, Synthetic Lubricants, Greases, Automotive Oils, Industrial Oils Refining Technology: Hydrocracking, Solvent Extraction, Dewaxing, Clay Treatment, Solvent Refining, Catalytic Hydrogenation Application: Engine Oil, Gear Oil, Metalworking Fluids, Hydraulic Fluids, Compressor Oils, Turbine Oils End User Industry: Power Generation, Marine, Construction Equipment, Agriculture Machinery, Mining Operations, Textile Manufacturing |
| Companies Covered | Exxon Mobil Corporation, Shell, BP plc, Chevron Corporation, TotalEnergies, FUCHS, Sinopec Corporation, Nye Lubricants, Inc., Kluber, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialties of Lube Oil Refinery Market Strategic Shifts & Innovations
A fundamental shift from volume-based production to value-driven formulation defines the current market. Performance, efficiency, and sustainability mandates are altering product development and commercial strategies for specialty refiners.
Gas-to-Liquids (GTL) technology converts natural gas into exceptionally pure, paraffinic synthetic base oils with virtually zero sulfur content. Lubricant blenders serving the premium automotive and aerospace sectors are steadily adopting these materials. The superior performance and consistency of GTL base oils is collapsing the traditional performance gap between conventional Group III oils and more expensive polyalphaolefins (PAOs).
The European Union's Corporate Sustainability Reporting Directive (CSRD) creates new pressures for transparency. This regulation compels lubricant producers to quantify and disclose the lifecycle environmental impact of their products, from feedstock sourcing to end-of-life disposal. The industrial oils segment, particularly products used in heavy manufacturing, faces the most immediate need to adopt more sustainable base stocks and improve formulation efficiency.
Industrial customers are transitioning from transactional lubricant purchases toward comprehensive fluid management agreements. This shift favors on-site service models where providers handle oil analysis, filtration, and fluid maintenance, replacing the traditional role of bulk distributors. This trend is most visible within the metalworking and heavy equipment sectors in Germany and the United States, where equipment uptime is a critical operational priority.
Specialties of Lube Oil Refinery Market Segmentation
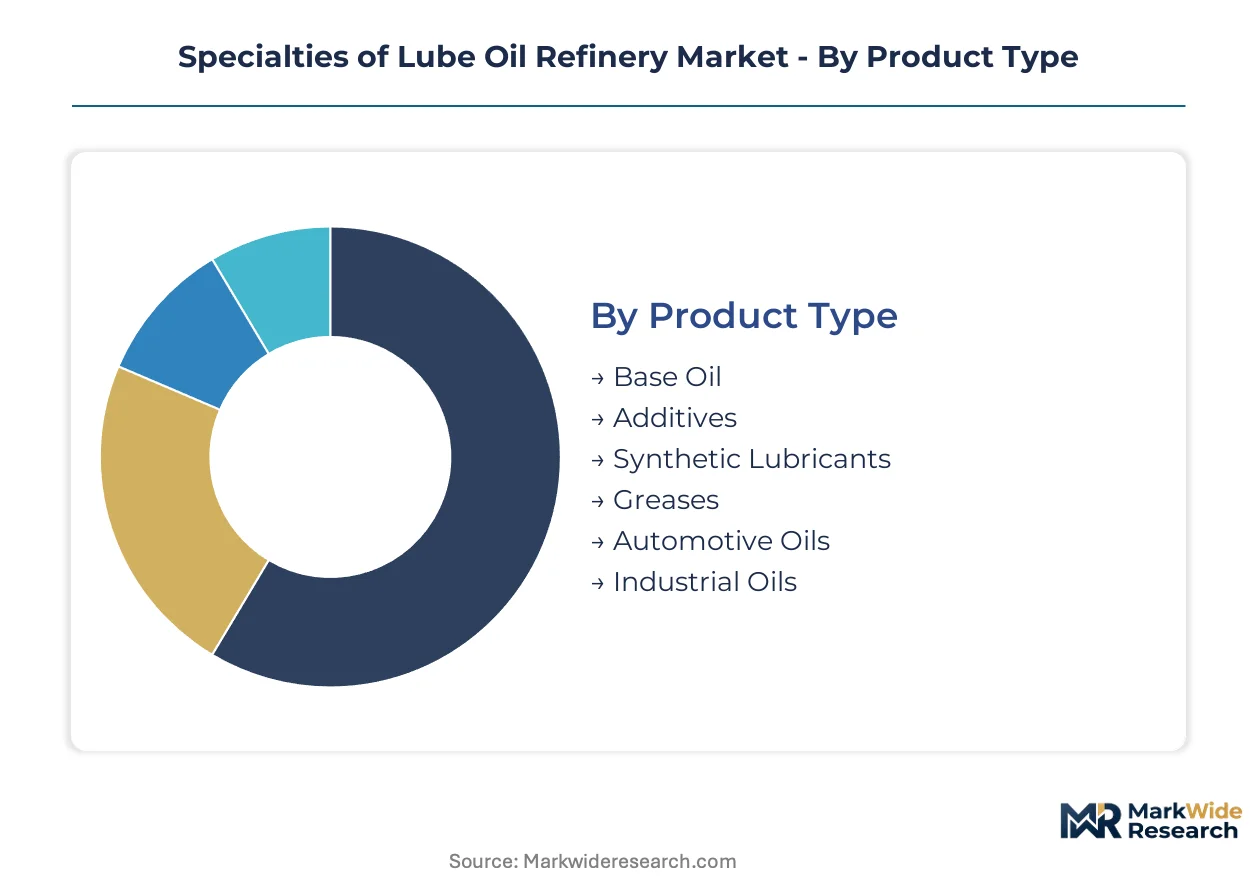
The specialties of lube oil refinery market is highly diversified, reflecting the broad array of performance requirements across various industrial and automotive applications. Understanding this segmentation is crucial for producers to strategically allocate R&D resources and tailor product portfolios to specific market demands. Each segment demands unique formulation expertise and often distinct refining processes.
Product Type:
The use-case spectrum for specialty lube oil products ranges from foundational base stocks to highly engineered finished lubricants. Each product type serves distinct functions and addresses varying performance criteria across end-user industries.
- Base Oil:These are the primary components of lubricants, derived from crude oil or synthetic processes, providing fundamental lubrication properties and viscosity characteristics. Advanced Group II and Group III base oils are increasingly critical for meeting stringent emissions standards in the United States and Europe.
- Synthetic Lubricants:Chemically engineered for superior performance, synthetic lubricants offer enhanced thermal stability, oxidation resistance, and extended drain intervals in demanding applications. Their adoption is expanding in high-performance engine oil and aerospace sectors due to extreme operating conditions.
- Additives:Chemical compounds enhance lubricant performance, providing anti-wear, anti-corrosion, and viscosity modification properties.
- Greases:Semi-solid lubricants combining a base oil with a thickener, ideal for applications requiring continuous lubrication and sealing.
- Automotive Oils:Formulations specifically designed for internal combustion engines, transmissions, and other vehicle components, adhering to standards like Euro 7.
- Industrial Oils:Lubricants tailored for machinery in manufacturing, power generation, and construction, offering specialized protection and efficiency.
The dominant share belongs to Base Oil, while Synthetic Lubricants is closing the gap fastest.
Refining Technology:
The capital intensity and operational sophistication of refining technologies define the cost tier of base oils and finished lubricants produced. These processes are essential for achieving the purity and performance characteristics required by modern specifications.
- Hydrocracking:This advanced process breaks down heavier crude oil fractions into lighter, higher-quality base oils while removing impurities like sulfur and nitrogen. Significant investment in hydrocracking units is driven by the need for Group II and Group III base oils to comply with emissions regulations in Germany.
- Solvent Extraction:This method removes undesirable aromatic and polar compounds from base oils, improving their viscosity index and oxidation stability. It remains a foundational technology for producing quality Group I base oils for various industrial applications.
- Dewaxing:Processes like solvent dewaxing or catalytic dewaxing remove paraffin waxes from base oils, lowering their pour point and improving low-temperature fluidity. This is crucial for lubricants operating in cold climates, such as those used in Canada's mining sector.
- Clay Treatment:A finishing step that uses activated clay to remove trace impurities, color, and odor from base oils, enhancing their aesthetic and stability.
- Solvent Refining:An older but still relevant process that uses solvents to extract undesirable components, contributing to the purity of conventional base oils.
- Catalytic Hydrogenation:A severe hydrotreating process that saturates aromatic compounds and removes sulfur, producing very high-purity base oils.
Hydrocracking holds the largest market share, with Catalytic Hydrogenation experiencing the most significant expansion.
Application:
Specific application demands dictate the formulation and performance attributes of specialty lubricants, influencing product development and market focus. Each application requires a precise balance of properties to ensure optimal equipment function and longevity.
- Engine Oil:Lubricates internal combustion engines, reducing friction, cooling components, and preventing corrosion. The automotive sector's continuous innovation in engine design drives demand for advanced synthetic and semi-synthetic engine oils.
- Turbine Oils:Specialized lubricants for power generation turbines, requiring exceptional thermal stability, oxidation resistance, and water separation properties. The power generation industry in the United States relies on these oils for critical equipment uptime and efficiency.
- Gear Oil:Designed to lubricate gears in transmissions, differentials, and industrial machinery, providing extreme pressure protection and wear reduction.
- Metalworking Fluids:Used in machining and grinding operations to cool, lubricate, and remove swarf, enhancing tool life and surface finish.
- Hydraulic Fluids:Transmit power in hydraulic systems, requiring specific viscosity, anti-wear, and anti-foaming characteristics for industrial automation.
- Compressor Oils:Lubricate air and gas compressors, needing high thermal stability and resistance to oxidation to maintain efficiency.
Engine Oil constitutes the primary revenue source, while Turbine Oils demonstrates the steepest expansion trajectory.
End User Industry:
The diverse volume requirements and operational environments of various end-user industries shape the demand patterns for specialty lube oils. Each industry presents unique challenges and opportunities for lubricant manufacturers.
- Power Generation:This industry requires high-performance turbine oils and specialized lubricants for generators and auxiliary equipment to ensure continuous operation and efficiency. The need for reliable energy supply in India drives consistent demand for these critical fluids.
- Construction Equipment:Heavy machinery used in construction, such as excavators and bulldozers, demands robust engine oils, hydraulic fluids, and greases capable of withstanding extreme loads and harsh environments. Infrastructure development projects in China significantly contribute to this segment's consumption.
- Marine:Lubricants for marine engines, propellers, and auxiliary systems, designed to perform under saline conditions and varying temperatures.
- Agriculture Machinery:Oils and greases for tractors, harvesters, and other farm equipment, needing durability and protection against dust and moisture.
- Mining Operations:Heavy-duty lubricants for excavators, haul trucks, and drilling equipment, operating in abrasive and high-stress conditions.
- Textile Manufacturing:Specialized oils for high-speed textile machinery, requiring non-staining properties and excellent wear protection.
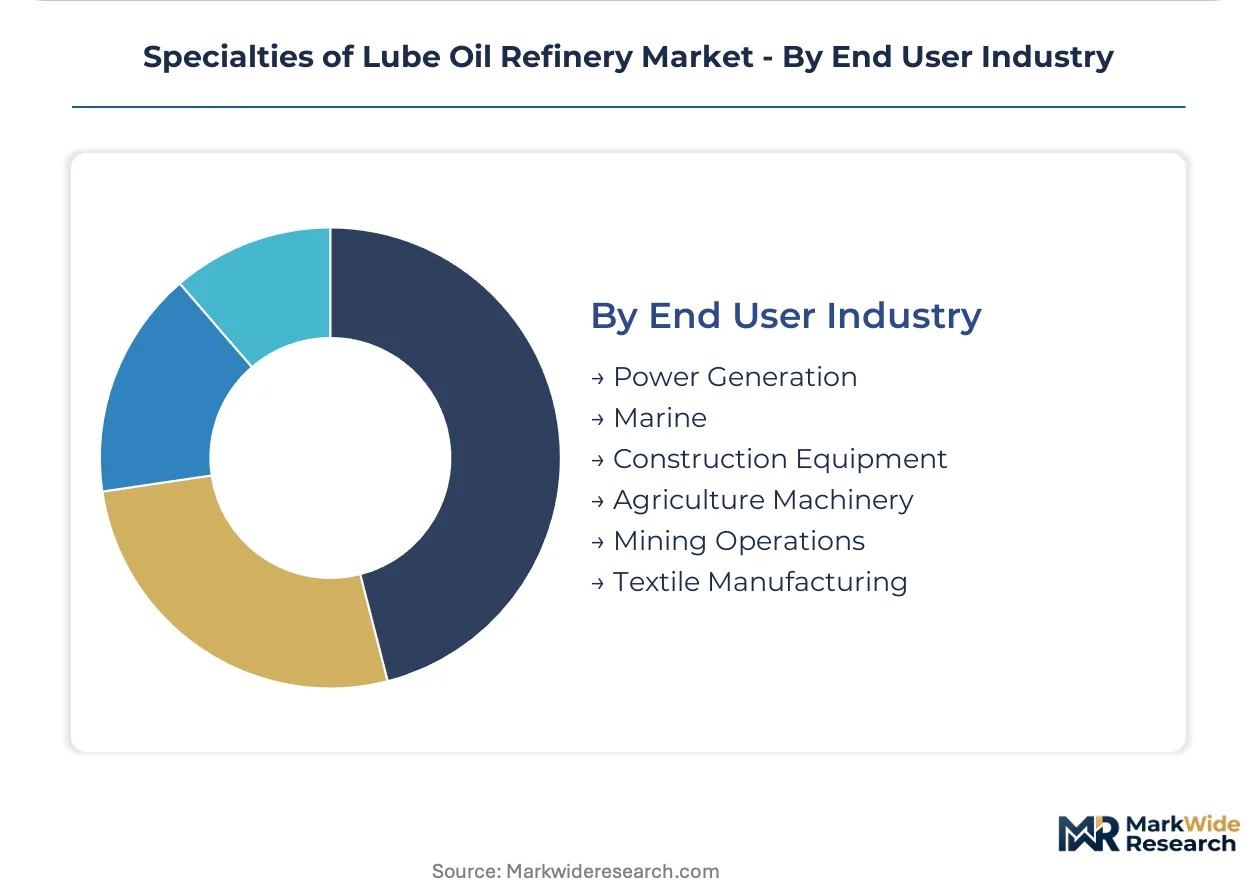
Power Generation accounts for the largest consumption volume, with Mining Operations showing the most rapid increase in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in specialties of lube oil refining exhibits regional asymmetry, with distinct market dynamics shaping profitability. Countries like China, driven by vast manufacturing output, emphasize volume and cost-efficiency in industrial oil consumption. Conversely, highly regulated markets such as Germany prioritize advanced formulations and sustainability, enabling premium pricing for specialized products.
United States
The power generation industry's requirement for high-performance turbine oils drives significant demand for specialized lubricants in the United States. EPA Tier 3 standards compel the use of advanced Group II and Group III base oils to reduce sulfur content. Refineries along the Gulf Coast concentrate production of these high-purity base oils, serving both domestic and export markets.
China
China's extensive manufacturing activity and construction equipment sector generate substantial demand for industrial oils and specialized lubricants. The country's GB standards impose strict performance and quality requirements for all lubricants sold domestically. Industrial hubs like the Yangtze River Delta region anchor a substantial portion of the nation's industrial oil consumption.
Germany
Germany's automotive and advanced manufacturing sectors require high-performance industrial oils and synthetic lubricants for precision machinery. Euro 7 emissions standards and the REACH framework necessitate the adoption of advanced base oils and sustainable formulations. The Rhine-Ruhr area, a major industrial heartland, sees significant adoption of comprehensive fluid management agreements.
India
India's expanding power generation sector requires specialized turbine oils to ensure continuous operation and efficiency of critical equipment. The country's National Electricity Policy supports infrastructure development, driving consistent demand for these fluids. Industrial clusters in Gujarat and Maharashtra exhibit a growing need for high-performance industrial lubricants across various applications.
Canada
Canada's mining sector and cold climate conditions create specific demand for heavy-duty lubricants and specialized base oils with low pour points. Environmental regulations from Health Canada influence the formulation of lubricants to ensure ecological compliance. The Alberta oil sands region drives substantial demand for robust engine oils and dewaxed base oils for heavy equipment.
Specialties of Lube Oil Refinery Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the specialties of lube oil refinery market. This market exhibits a tiered structure, with large integrated energy companies leveraging extensive refining networks. Niche specialists differentiate through deep expertise in high-performance synthetic formulations for demanding applications. Key competitive moves include strategic partnerships for technology access and focused portfolio diversification into high-margin segments.
Specialists in high-performance synthetic lubricants, Kluber and Nye Lubricants, Inc., exemplify companies focusing on niche industrial applications. These firms differentiate through deep expertise, targeting segments that demand superior thermal stability and longevity. Conversely, Shell, as an integrated major, leverages its extensive refining network and integrated supply chain to maintain a dominant market presence across various product categories. Its strategic positioning allows for broad market coverage, from foundational base oils to finished lubricants, catering to diverse industrial and automotive needs.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell |
| BP plc |
| Chevron Corporation |
| TotalEnergies |
| FUCHS |
| Sinopec Corporation |
| Nye Lubricants, Inc. |
| Kluber |
| Others |
Cost & Logistics Intelligence
Refineries along the US Gulf Coast concentrate high-purity base oil production, influencing global pricing power for advanced lubricant feedstocks. This capacity concentration impacts downstream finished lubricant costs and availability.
Pricing Analysis
Configured-to-order pricing for specialized synthetic lubricants commands a premium over standard, high-volume base oils. Value-based and long-term contract models dominate high-performance segments, driven by stringent application requirements and technical expertise. Performance specifications, such as thermal stability and oxidation resistance, along with integrated fluid management services, differentiate pricing. Volatile crude oil feedstock costs exert pricing pressure on base oil producers, while automotive OEMs show higher price sensitivity than specialized industrial end-users like power generation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the capital-intensive base oil refining sector. Base oil production concentrates in the US Gulf Coast and Europe, with significant finished lubricant blending and consumption hubs in China and Germany. Crude oil and natural gas for Gas-to-Liquids base oils constitute primary feedstocks, alongside various chemical additives. Volatility in crude oil prices presents a constant supply chain risk, impacting production costs. Distribution for integrated companies involves extensive networks, while specialists often utilize direct sales and comprehensive fluid management agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialties of lube oil refinery market necessitates a robust substitution defense strategy. Incumbents must navigate the long-term threat posed by battery electric vehicles displacing traditional passenger car motor oils.
For Market Incumbents: Build a technological moat by aggressively investing in advanced hydroprocessing capabilities. Diversify product portfolios into EV thermal management fluids and bio-based lubricants to counter the electric vehicle transition threat. Strengthen market leadership in high-performance industrial oils by leveraging deep expertise in turbine oils and gear oils. Strategic partnerships for Gas-to-Liquids technology access can also enhance base oil purity.
For New Entrants and Emerging Players: Establish a beachhead in high-growth, specialized segments with unmet performance needs. Target the electric vehicle market with thermal management fluids or data center cooling applications, leveraging advanced dielectric base oils. Focus on niche industrial applications requiring high-performance synthetic lubricants, such as those for robotics. A go-to-market strategy emphasizing sustainability credentials and superior technical support can differentiate offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-driven innovation play because stringent emissions standards continuously reshape product requirements. Target niche specialists in high-performance synthetic lubricants or companies with proprietary hydroprocessing technologies. These firms possess deep expertise for demanding applications like aerospace. The signal to watch is accelerated adoption of advanced Group II/III base oils and EV thermal management fluid penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Hydrocracking | This ensures supply of Group II and Group III base oils for compliance with EPA and Euro 7 standards. |
| Product Diversification into EV Fluids | Captures new revenue streams from battery cooling and e-axle lubrication, offsetting declining engine oil demand. |
| Strategic Partnership for GTL Technology | Accesses ultra-pure paraffinic base oils for premium automotive and aerospace lubricant blenders. |
| Green Manufacturing Transition | Develops bio-based lubricants to meet corporate sustainability mandates and environmentally conscious customer demand. |
| Service Model Innovation | Expands comprehensive fluid management agreements, particularly within German and US heavy equipment sectors. |
Research Approach
Initial hypotheses were tested against primary input from refinery operations managers, R&D chemists, procurement leads, and end-user maintenance directors. Secondary validation drew upon EPA and REACH regulatory documents, industry association reports, company annual reports, and technical journals. Bottom-up market sizing from production capacities and top-down validation from application demand ensured robust data triangulation.
Demand-supply balance models projected market evolution across the analysis window, considering both consumption and production capacities. The analytical framework segmented data by product type, refining technology, application, and end-user industry. Compound annual growth rates were derived from volume and value projections, incorporating crude oil price forecasts and regulatory compliance timelines.
Sensitivities concentrate around feedstock price volatility, evolving emissions standards, and the pace of electric vehicle adoption. Forecasts reflect underlying assumptions regarding these dynamic market forces. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Arab Emirates Lubricants Market
Lubricants
Lube Skid Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
ASEAN Lubricants Market
Lubricants
Jordan Lubricants Market
Lubricants
United States Automotive Lubricants Market
Lubricants
Malaysia Automotive Engine Oils Market
Lubricants
Gun Lubricant Market
Lubricants
Global Engineered Fluids Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Global Compressor Oil Market
Lubricants
Thailand Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
North America Lubricants Market