
 Norway Automotive Lubricants Market | 2026-2036
Norway Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Automotive Lubricants Market Analytics
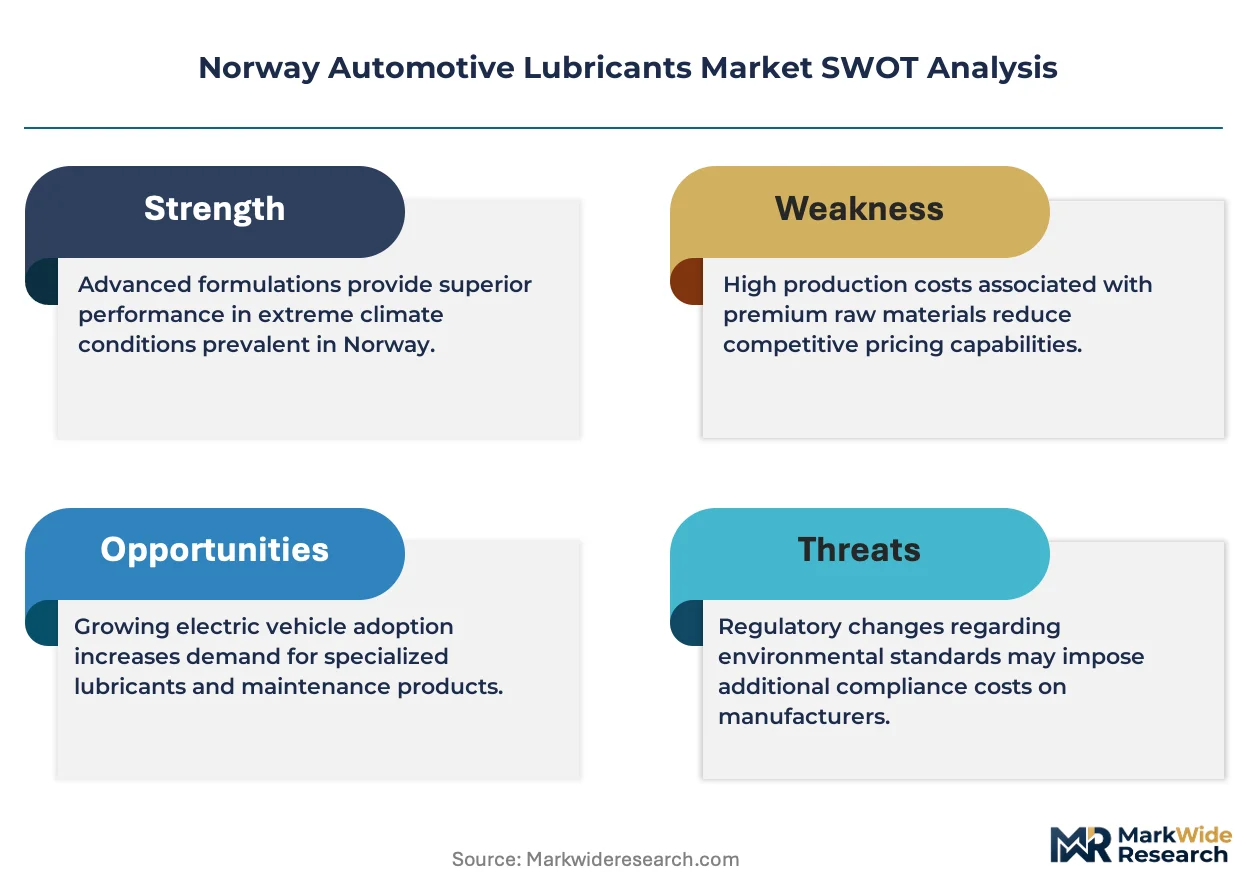
The gap between premium synthetic formulations and commodity mineral blends is hardening as Norwegian vehicle parc electrifies. Shell PLC leverages its Arctic-grade R&D capabilities to dominate cold-climate viscosity segments. FUCHS anchors its position through specialized industrial-to-automotive crossover formulations. TotalEnergies SE differentiates via renewable base oil integration aligned with Nordic environmental preferences.
Automotive lubricants are formulated mixtures of base oils and performance additives designed to reduce friction, dissipate heat, and prevent wear in powertrain components, with synthetic variants typically achieving viscosity indices above 140 for sub-zero operational stability. Engine oil retains the largest volume share across Norwegian applications, though synthetic oil is capturing margin pools as OEM service intervals extend. Passenger vehicles absorb the majority of formulated demand, while commercial vehicle fleets concentrate purchasing through direct OEM and service station contracts.
The Norwegian Environment Agency enforces strict waste oil recovery mandates, while EU REACH regulations govern additive chemical composition across imported formulations. Norway's alignment with EU vehicle emission standards through the EEA agreement ensures parallel lubricant performance specifications with continental suppliers. Stakeholders must monitor how battery electric vehicle penetration reshapes remaining internal combustion service demand and which blenders secure bio-based feedstock certifications first.
Market Dynamics
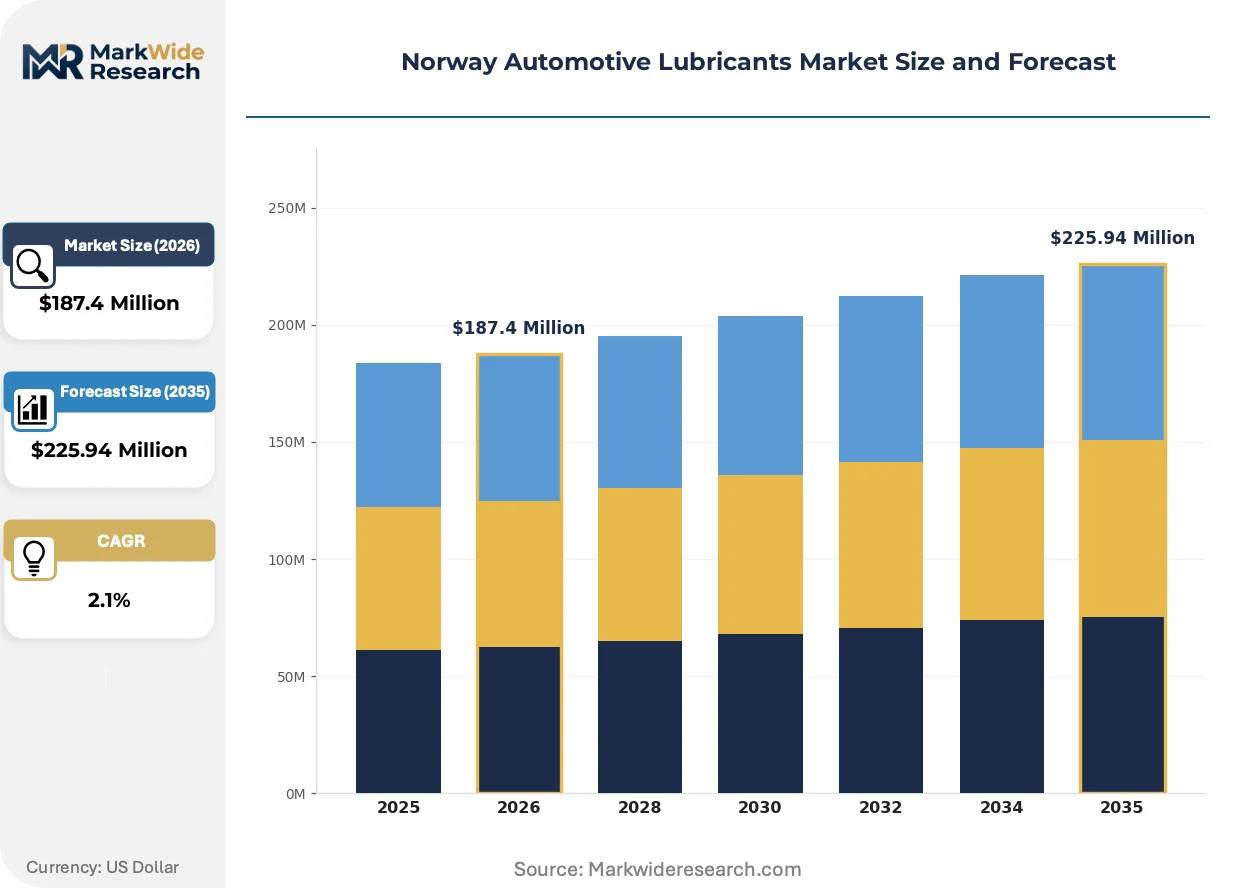
The Norwegian automotive lubricants sector confronts a fundamental demand contraction as battery electric vehicles capture passenger car sales. Internal combustion engine service intervals lengthen while synthetic formulations command premium positioning in the remaining addressable market.
Growth Catalysts
- EU Green Deal alignment:Norway's EEA obligations accelerate bio-based base oil mandates across transport sectors. Refiners reformulate product portfolios to meet carbon neutrality timelines.
- Arctic-grade viscosity demand:Sub-zero operational requirements in Tromsø and Finnmark drive specialized synthetic adoption. Cold-climate performance specifications exceed standard European formulations.
- Extended OEM service intervals:Premium synthetic lubricants enable 30,000+ kilometer maintenance cycles. Workshop operators consolidate purchasing around high-durability formulations.
Market Restraints
- Group III base oil import dependency:Norway lacks domestic API Group III+ production capacity. Supply concentrates on Rotterdam and Antwerp refining corridors.
- BEV fleet penetration:Battery electric powertrains eliminate engine oil consumption entirely. Oslo's municipal vehicle fleet already operates lubricant-free.
- REACH additive compliance costs:ECHA substance authorization timelines extend 18-24 months for novel friction modifier chemistries. Smaller blenders exit rather than absorb regulatory burden.
Strategic Opportunities
- Industrial-to-automotive formulation crossover:Marine and offshore lubricant expertise transfers to heavy-duty commercial vehicle segments. Stavanger's oil services cluster anchors technical development.
- Waste oil re-refining infrastructure:Norwegian Environment Agency collection mandates create circular feedstock pools. Re-refined base oils qualify for public procurement preferences.
- Hybrid powertrain lubrication:Plug-in hybrid thermal management requirements sustain demand for specialized coolants and transmission fluids. Bergen's automotive service corridor captures early adoption.
Industry Challenges
- Technical workforce transition:Lubricant formulation chemists require retraining in thermal fluid engineering for electric drivetrains. Vocational programs lag market structure shifts.
- Service network reconfiguration:Traditional quick-lube outlets face volume collapse. Physical footprint rationalization demands capital restructuring.
- Certification timeline compression:ACEA and API specification updates accelerate faster than blender validation cycles. Concurrent OEM approvals strain technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Automotive Lubricants Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $225.94 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Brake Fluid, Grease Form: Mineral Oil, Synthetic Oil, Semi-Synthetic Oil, Bio-Based Oil Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Customer Type: OEMs, Aftermarket, Service Stations, Retail |
| Companies Covered | Shell PLC, Chevron Corporation, BP PLC (Castrol), Valvoline Inc., Motul, FUCHS, TotalEnergies SE, PETRONAS Lubricants International, ExxonMobil Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Automotive Lubricants Market Evolving Landscape
Formulation chemistry and distribution architecture undergo simultaneous transformation. Synthetic base stocks displace conventional mineral oils while digital procurement platforms restructure buyer-supplier relationships.
Polyalphaolefin (PAO) synthetic base stocks deliver viscosity stability across Norway's -30°C winter extremes. Commercial fleet operators in Trøndelag prioritize PAO-based engine oils for cold-start protection. This technology is electrifying premium segment positioning as mineral formulations retreat to price-sensitive niches.
EU REACH Annex XIV authorization requirements now govern zinc dialkyldithiophosphate additive packages. ECHA substance evaluation compresses approved chemistries to lower-sulfur, lower-phosphorus alternatives. Norwegian importers reformulate stocked inventory ahead of 2027 sunset dates for legacy friction modifiers.
Direct-to-workshop digital procurement platforms displace traditional distributor intermediaries. Independent service operators in Rogaland bypass regional wholesalers for manufacturer-direct supply agreements. Bergen's consolidated fleet management sector pioneered this channel shift, now diffusing southward toward Oslo's fragmented garage network.
Norway Automotive Lubricants Market Segmentation
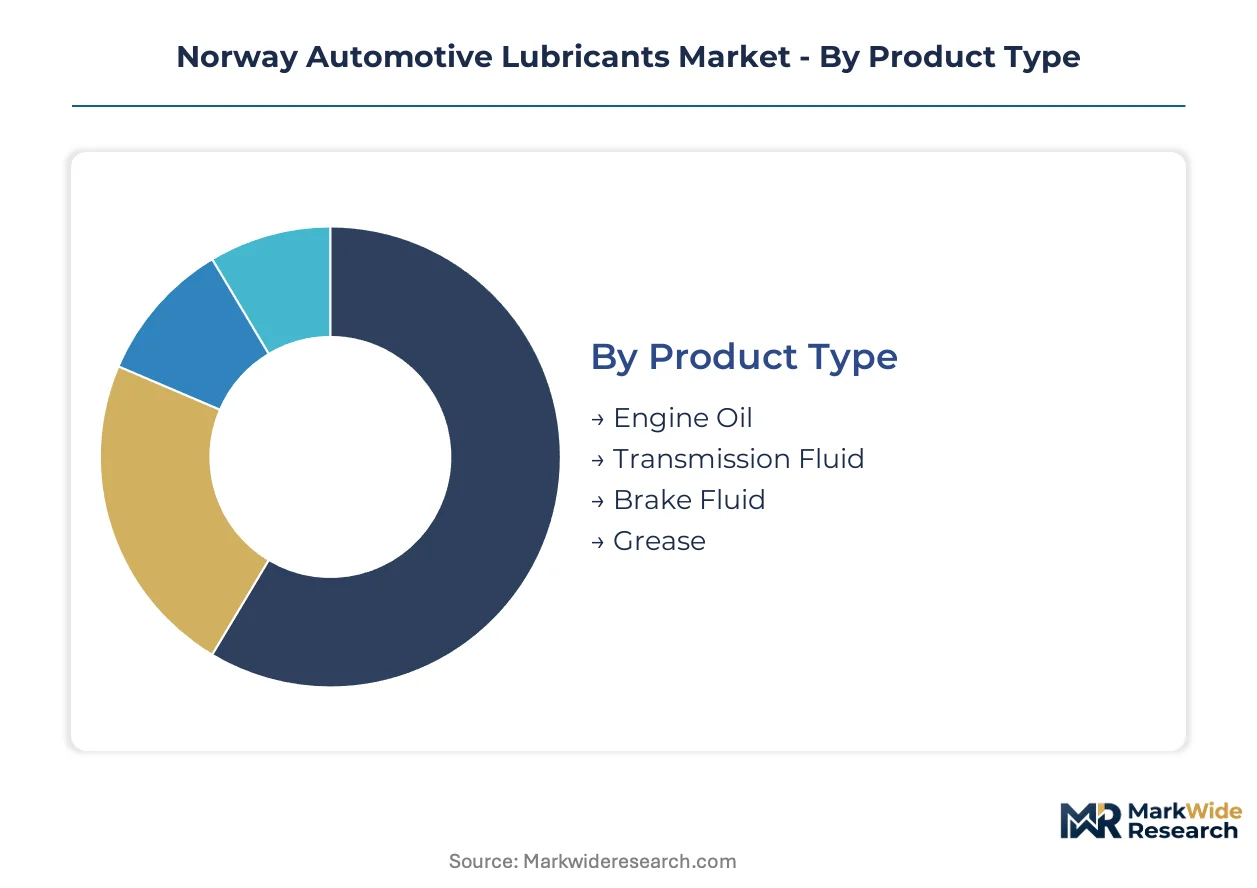
Norwegian fleet electrification fragments lubricant demand across thermal management and legacy combustion applications. Segment boundaries blur as hybrid powertrains create formulation crossover requirements between conventional engine oils and specialized coolants.
Product Type:
Replacement cycles stretch as synthetic formulations extend drain intervals, concentrating revenue in fewer but higher-value transactions.
- Engine Oil:Formulated from Group III+ base stocks with ACEA C3/C5 additive packages for extended drain intervals. Oslo's passenger vehicle service corridors absorb the majority of volume as synthetic penetration displaces mineral blends in routine maintenance.
- Transmission Fluid:ATF and CVT-specific formulations with friction modifier packages calibrated to Nordic cold-start requirements. Bergen's commercial fleet operators specify premium variants for automated manual transmissions in distribution vehicles.
- Brake Fluid:DOT 4 and DOT 5.1 glycol-ether formulations with elevated dry boiling points for mountainous terrain.
- Grease:Lithium-complex and calcium-sulfonate thickeners for chassis and wheel bearing applications in Tromsø's Arctic operating conditions.
Engine oil sits at the top of the volume ranking, with transmission fluid climbing the fastest as dual-clutch and CVT penetration expands.
Form:
Cost tier stratification reflects base oil group economics and additive package sophistication rather than simple brand positioning.
- Mineral Oil:Group I and Group II solvent-refined base stocks dominate price-sensitive commercial fleet segments in rural Trøndelag. Older vehicle parc in Finnmark sustains residual demand for conventional 15W-40 formulations despite synthetic conversion in urban corridors.
- Synthetic Oil:PAO and Group III+ hydrocracked base stocks achieve viscosity indices above 160 for -30°C cold-crank performance. Stavanger's oil services cluster anchors technical development of Arctic-grade 0W-20 and 0W-16 formulations for hybrid thermal management.
- Semi-Synthetic Oil:Group II+ blends with synthetic content between 10-30% occupy the mid-market transition segment.
- Bio-Based Oil:Estolide and vegetable-derived base stocks from re-refined feedstocks qualify for Norwegian Environment Agency procurement preferences.
Synthetic oil commands the premium tier by margin, with bio-based oil gaining share fastest under EU Green Deal alignment pressure.
Application:
Customer concentration patterns diverge sharply between fragmented retail demand and consolidated fleet procurement.
- Passenger Vehicles:Individual owners in Oslo, Bergen, and Stavanger metropolitan corridors drive synthetic adoption through authorized service networks. Extended OEM drain intervals compress transaction frequency while elevating per-unit value.
- Commercial Vehicles:Regional distribution and logistics fleets in Rogaland negotiate direct supply agreements bypassing traditional distributor tiers. Volvo and Scania dealer networks consolidate lubricant procurement across southern Norway.
- Heavy-Duty Trucks:Long-haul operators on E6 and E39 corridors prioritize 10W-40 synthetic formulations for engine protection under variable load conditions.
- Motorcycles:Seasonal demand concentration in Oslo and Bergen metropolitan areas with JASO MA2 specification requirements for wet clutch compatibility.
Passenger vehicles anchor volume concentration, with commercial vehicles expanding most quickly through fleet consolidation and direct procurement channel shifts.
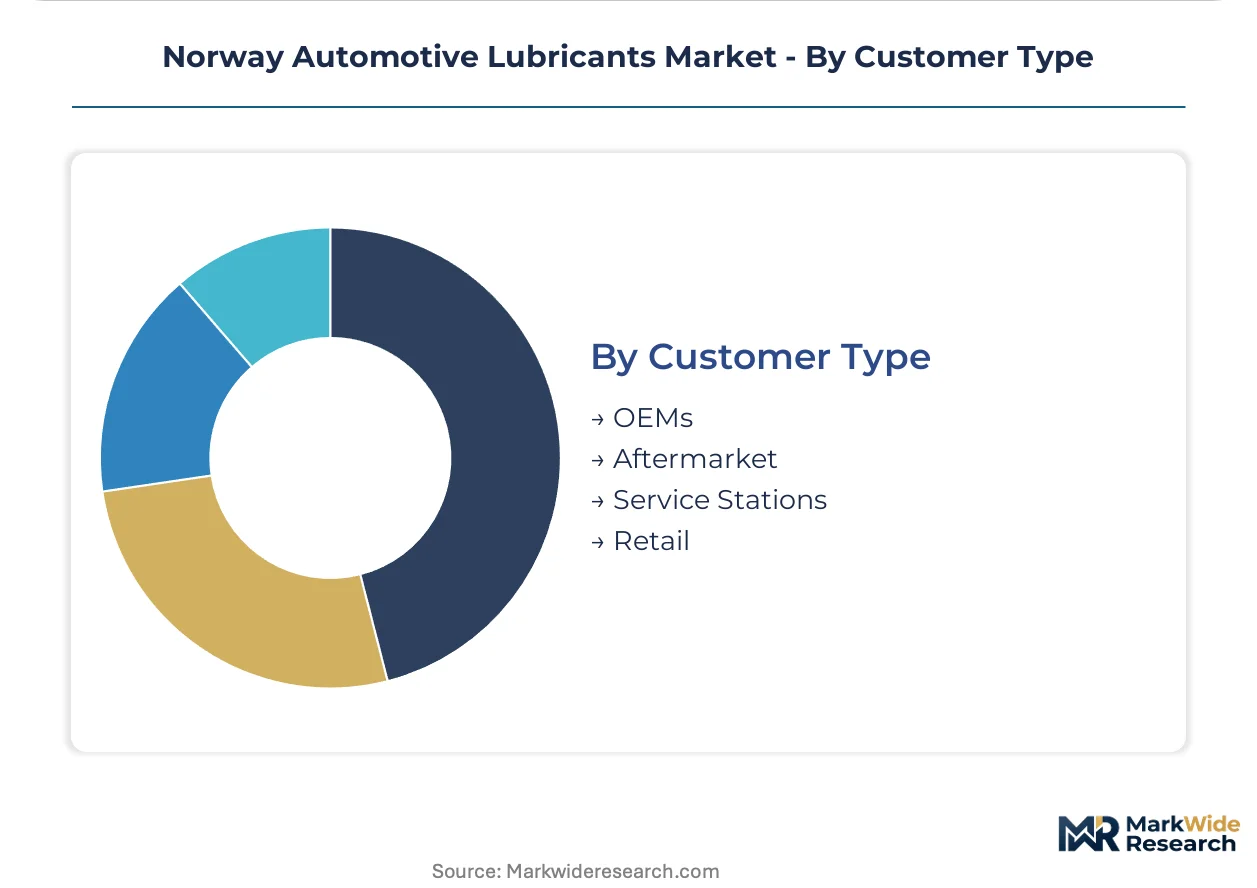
Customer Type:
Channel structure reconfiguration accelerates as digital platforms displace traditional wholesale intermediaries.
- OEMs:Factory-fill specifications from domestic Volvo and imported marques mandate ACEA C5 0W-20 formulations for warranty compliance. Assembly plant contracts concentrate volume with approved blender networks.
- Aftermarket:Independent workshops in Oslo's fragmented garage network migrate to manufacturer-direct digital procurement platforms. Bergen's consolidated fleet management sector pioneered this channel shift now diffusing nationally.
- Service Stations:Statoil, Shell, and YX retail networks bundle lubricant sales with fuel transactions in highway corridor locations.
- Retail:DIY consumers in suburban and rural municipalities purchase through Biltema, Mekonomen, and specialist automotive parts channels.
Aftermarket channels dominate transaction frequency, with OEM factory-fill representing the steepest expansion trajectory as service interval extension compresses replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive lubricant demand outpaces France's by volume, yet both markets confront electrification-driven contraction. Nordic cold-climate specifications create premium formulation opportunities absent in Mediterranean basins. Rotterdam and Antwerp refining corridors supply base stocks across Northern European blending networks.
Oslo Metropolitan Corridor
Passenger vehicle electrification exceeds national averages, compressing engine oil demand while elevating synthetic premiumization. Norwegian Environment Agency waste oil recovery mandates enforce circular collection infrastructure. Oslo's authorized service networks consolidate purchasing around ACEA C5 0W-20 formulations for hybrid thermal management.
Bergen and Western Fjord Region
Commercial fleet operators prioritize automated manual transmission fluids for distribution vehicles serving maritime logistics. EU REACH Annex XIV authorization timelines pressure importers to reformulate zinc dialkyldithiophosphate additive packages. Bergen's consolidated fleet management sector pioneered manufacturer-direct digital procurement platforms now diffusing nationally.
Stavanger and Rogaland Oil Services Cluster
Marine and offshore lubricant expertise transfers to heavy-duty commercial vehicle segments under industrial-to-automotive crossover strategies. Norway's EEA alignment with EU vehicle emission standards ensures parallel lubricant performance specifications. Stavanger's technical development centers anchor Arctic-grade 0W-16 formulation R&D for sub-zero operational requirements.
Trøndelag and Central Norway
Rural commercial fleets sustain residual mineral oil demand for older vehicle parc despite synthetic conversion in urban corridors. Norwegian Environment Agency procurement preferences favor re-refined base oils from circular feedstock pools. Trondheim's regional distribution networks negotiate direct supply agreements bypassing traditional wholesale intermediaries.
Tromsø and Arctic Norway
PAO synthetic base stocks achieve viscosity stability across -30°C winter extremes in Finnmark operating conditions. Cold-climate performance specifications exceed standard European formulations, driving specialized adoption. Tromsø's municipal and commercial operators prioritize lithium-complex greases for chassis applications in extreme environments.
Norway Automotive Lubricants Market Competitive Landscape
Top-tier vendors anchor premium synthetic and factory-fill segments, while mid-tier blenders occupy price-sensitive commercial fleet niches. The vendor base stratifies across integrated majors with Arctic-grade R&D capabilities, specialized industrial-to-automotive crossover formulators, and regional distributors facing digital disintermediation. Three archetypes dominate: integrated energy majors leveraging refining scale, lubricant specialists with technical formulation depth, and industrial chemical crossover players. Competitive moves concentrate on bio-based feedstock certification races and waste oil re-refining infrastructure partnerships.
Within the integrated major tier, Shell PLC and BP PLC (Castrol) represent scale-driven positioning anchored by cold-climate viscosity development. Among specialized formulators, FUCHS occupies a position exemplifying industrial-to-automotive technical crossover, while TotalEnergies SE sits within the renewable base oil integration archetype. These three companies illustrate how competitive differentiation converges on sustainability-aligned formulation chemistry and Arctic operational performance.
| Leading Market Players |
|---|
| Shell PLC |
| Chevron Corporation |
| BP PLC (Castrol) |
| Valvoline Inc. |
| Motul |
| FUCHS |
| TotalEnergies SE |
| PETRONAS Lubricants International |
| ExxonMobil Corporation |
| Others |
Value Network & Pricing Analysis
Ace-certified synthetic-mineral bifurcation splits Norwegian procurement patterns between premium Arctic-grade formulations and residual commodity blends, concentrating margin capture among Rotterdam-supplied blenders while rural distributors absorb inventory risk on aging mineral stocks. This tier divergence feeds directly into supply chain configuration: premium synthetic channels bypass wholesale intermediaries through digital direct-to-workshop platforms, whereas mineral oil distribution retains traditional multi-tier markups through Trøndelag regional distributors.
Pricing Analysis
Capacity additions in Antwerp and Rotterdam refining corridors are reshaping price floors for Group III+ base stocks entering Norwegian blending networks. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels stratifies around ACEA certification grades and cold-climate viscosity performance. Cost compression in mineral tiers is intensifying because BEV fleet penetration collapses addressable volume for conventional 15W-40 formulations. Rural commercial fleet operators in Trøndelag and Finnmark exhibit highest price sensitivity, while Oslo's authorized service networks absorb premium synthetic markups with minimal elasticity.
Supply Chain Analysis
Waste oil collection mandates under Norwegian Environment Agency regulations create reverse-logistics infrastructure that feeds re-refined base stocks back into circular procurement pools. Geographic supply concentration centers on Netherlands, Belgium, and Germany as dominant Group III+ production hubs serving Nordic blending operations. Raw material dependencies rest on polyalphaolefin synthetic base stocks, zinc dialkyldithiophosphate additive packages, and bio-based estolide feedstocks. Single-source vulnerability runs through Rotterdam-Antwerp corridor concentration for API Group III+ supply. Distribution runs through manufacturer-direct digital platforms displacing traditional wholesale intermediaries in urban corridors, while rural networks retain regional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's automotive lubricants sector operates as a regulatory compounder where EU Green Deal bio-based mandates and EEA-aligned REACH authorization timelines continuously reshape formulation economics and procurement specifications.
For Market Incumbents: Deploy backward integration into re-refined base oil feedstocks to secure circular supply pools qualifying for Norwegian Environment Agency procurement preferences. Consolidate channel control through direct-to-workshop digital platforms capturing Oslo and Bergen service network volume before mid-tier distributors recover. Battery electric vehicle penetration eliminates engine oil demand entirely in municipal fleets; anchor residual revenue in hybrid thermal management fluids and Arctic-grade transmission formulations. For New Entrants and Emerging Players: Fleet management operators in Rogaland and Trøndelag represent the most penetrable buyer segment, consolidating lubricant procurement through direct supply agreements that bypass established wholesale tiers. Target hybrid powertrain lubrication white space where specialized coolant and transmission fluid requirements outpace incumbent formulation development. Pursue bio-based certification pathways under EU Green Deal alignment to differentiate in public procurement channels. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs exceed smaller blender operating margins, forcing exit and creating acquisition opportunities for technical formulation assets with Arctic-grade R&D capabilities. Five-to-ten year viability hinges on successful transition from combustion-engine lubricants to thermal fluid engineering for electric drivetrains. Monitor BEV penetration rates in Oslo's passenger vehicle parc as early signal for residual internal combustion service demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Feedstock Certification | EU Green Deal alignment secures Norwegian Environment Agency procurement preferences for circular formulations. |
| Waste Oil Re-Refining Partnership | Circular feedstock pools reduce import dependency on Rotterdam-Antwerp Group III+ supply corridors. |
| Arctic-Grade Formulation R&D | PAO-based 0W-16 viscosity specifications capture premium positioning in Tromsø and Finnmark sub-zero operating conditions. |
| Direct-to-Workshop Digital Platform | Manufacturer-direct procurement displaces traditional distributor intermediaries in Oslo and Bergen metropolitan corridors. |
| Hybrid Thermal Management Fluids | Plug-in hybrid powertrain lubrication sustains demand as battery electric vehicles eliminate conventional engine oil consumption. |
Research Methodology
Bottom-up passenger vehicle and commercial fleet modeling reconciled against top-down base oil import tracking forms the analytical core of this study. Primary interviews with lubricant formulation chemists, aftermarket procurement managers at fleet operators, technical directors at blending facilities, and Norwegian Environment Agency compliance officers combined with secondary validation from customs trade data, ECHA substance authorization databases, ACEA specification documentation, and vehicle registration statistics. Triangulation across supply-side capacity assessments and demand-side consumption patterns ensures dimensional consistency in volume and value outputs.
Historical trendline analysis of synthetic penetration rates, service interval extension patterns, and BEV fleet substitution establishes baseline trajectory parameters across the projection horizon. Segmentation dimensions modeled include product type, base oil group tier, vehicle application class, and customer channel structure, with additional weighting for Arctic-climate viscosity requirements specific to Nordic operating conditions. CAGRs derive from fitted trend extrapolation moderated by regulatory milestone impacts and technology substitution elasticities. Forecast inputs incorporate OEM drain interval specifications, EU REACH authorization sunset timelines, and hybrid powertrain penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery electric vehicle adoption velocity and bio-based feedstock cost curves. Practitioners should monitor Oslo metropolitan BEV registration shares, ECHA Annex XIV authorization amendments, and Rotterdam-Antwerp refinery capacity utilization for early signals of structural demand shift.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Japan Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
India Industrial Lubricants Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
Singapore Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Turkey Automotive Engine Oils Market
Lubricants
Friction Reducers Market
Lubricants
Industrial Gear Oil Market
Lubricants
Mexico Automotive Lubricants Market