
 Neat Cutting Oil Market | 2026-2036
Neat Cutting Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Neat Cutting Oil Market Analytics
Multi-source procurement from regional base-oil refiners is expanding as metalworking shops diversify supply risk away from single-source mineral oil dependence. ExxonMobil leverages its integrated base-oil network to secure feedstock continuity across North American and Asian blending facilities. FUCHS Petrolub SE anchors its position through specialized metalworking formulations developed in close collaboration with German automotive OEMs. Castrol competes on brand recognition and technical service density in high-precision machining segments.
Neat cutting oil is a straight, undiluted metalworking fluid composed of mineral, synthetic, or bio-based base stocks with extreme-pressure and anti-wear additive packages, typically applied directly to the cutting zone without water dilution. Its primary industrial purpose is to reduce friction between tool and workpiece, dissipate heat, and prolong tool life in precision machining operations. Synthetic formulations command premium positioning due to thermal stability and extended sump life in high-speed CNC applications, while biodegradable variants represent the fastest-growing category as European manufacturers face ECHA scrutiny on mineral oil mist exposure. Mineral oil remains the volume foundation across price-sensitive metalworking shops in emerging manufacturing economies.
REACH restrictions on chlorinated paraffins and ECHA classifications on mineral oil mist carcinogenicity are forcing European blenders toward additive-rich synthetic and aliphatic formulations with lower occupational exposure profiles. EPA and OSHA workplace exposure limits in the United States similarly shape product development priorities for suppliers serving American aerospace and automotive machining contracts. Stakeholders must monitor evolving biocide regulations under the EU Biocidal Products Regulation and anticipate reformulation costs that could reshape competitive economics between mineral and synthetic base stocks.
Market Dynamics
REACH restrictions on chlorinated paraffin additives are forcing European blenders to reformulate neat cutting oil portfolios, compressing product development cycles and elevating synthetic base stock demand across precision machining corridors.
Growth Catalysts
- ECHA mineral oil mist reclassification:Carcinogenicity rulings accelerate synthetic and aliphatic formulation adoption in German aerospace machining clusters, creating premium positioning for low-mist products.
- India precision manufacturing corridors:Tool room density expansion around Pune and Bangalore drives volume demand for high-performance neat oils in CNC turning and grinding operations.
- Multi-source procurement normalization:Metalworking shops diversify away from single-source mineral oil dependence, expanding regional base-oil refiner relationships across North American and Asian blending networks.
Market Restraints
- Base oil supply concentration:API Group II/III capacity tightness in select refining regions creates feedstock volatility for mineral oil-dependent blenders.
- Biocide regulatory friction:EU Biocidal Products Regulation approval timelines extend reformulation costs and complicate additive package sourcing for European formulators.
- Water-miscible fluid substitution:Semi-synthetic coolants capture share in rough machining applications where precision finishing requirements are less stringent.
Strategic Opportunities
- Bio-based formulation white space:Biodegradable neat oils represent underdeveloped capacity as European manufacturers face escalating ECHA scrutiny on mineral oil mist occupational exposure.
- EPA-OSHA alignment tailwind:Tightening American workplace exposure limits create parallel demand pull for low-mist synthetic formulations in US aerospace and automotive machining contracts.
- Technical service density gaps:High-precision machining segments in secondary Indian manufacturing cities lack Castrol-equivalent application engineering support, opening channel expansion potential.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in extreme-pressure additive synergy and tribological testing constrains European blender R&D throughput.
- REACH compliance timeline compression:Accelerated substance evaluation schedules force rapid portfolio rationalization without full performance validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neat Cutting Oil Market |
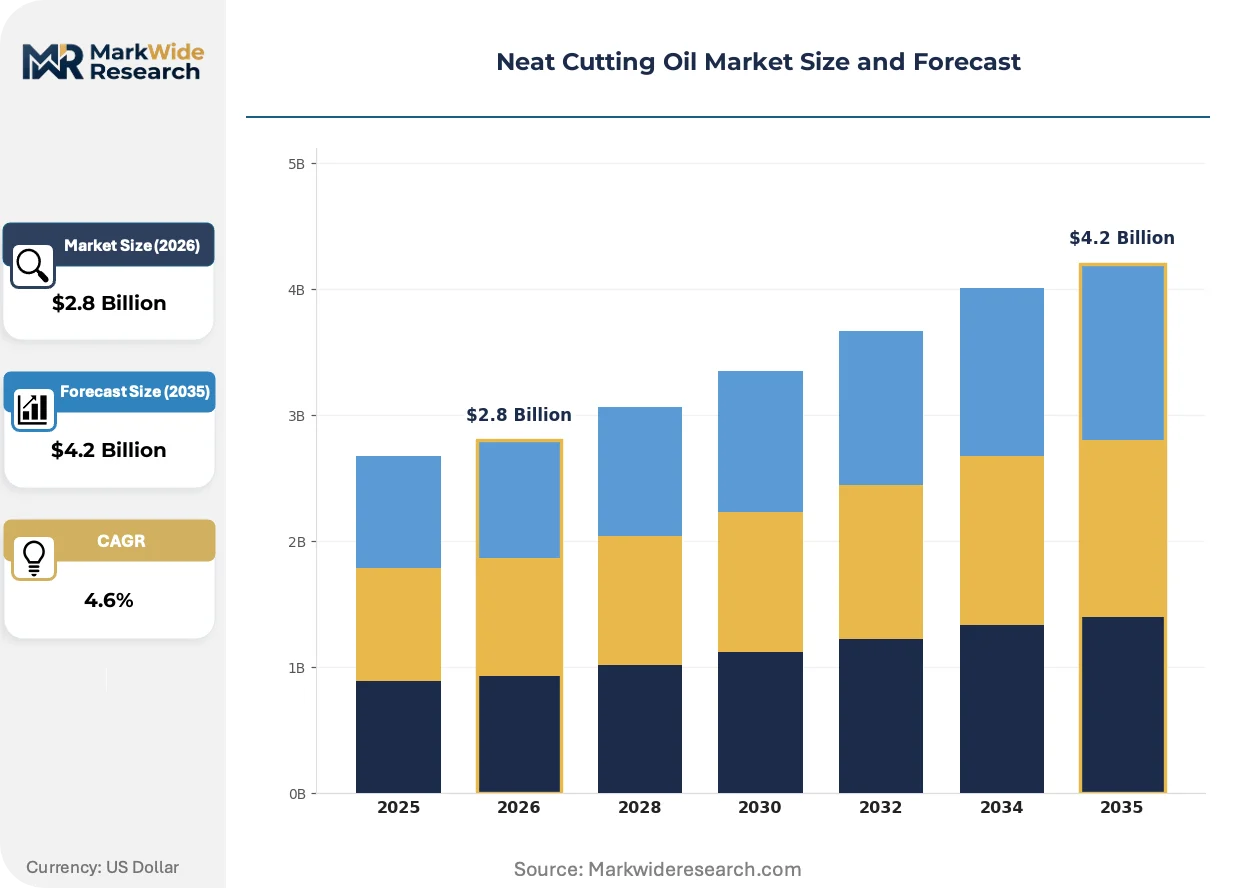
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Biodegradable, Hybrid Application: Machining, Grinding, Drilling, Tapping End User: Aerospace, Automotive, Metalworking, Agriculture Formulation: Aromatic, Aliphatic, Additive-Rich, Low Viscosity |
| Companies Covered | ExxonMobil, TotalEnergies, Sasol, Eastern Petroleum, Ashburn Chemical Technologies, Castrol, Quaker Houghton, Paras Lubricants, FUCHS Petrolub SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neat Cutting Oil Market Evolving Landscape
Formulation chemistry is fragmenting across mineral, synthetic, and bio-based pathways as regulatory pressure and performance requirements diverge. Technical service models and procurement patterns are restructuring in parallel.
Synthetic ester base stocks are modularizing neat cutting oil product architectures. Aerospace tier suppliers in Germany adopt these thermal-stable formulations for high-speed titanium machining. The technology is modularizing supplier value chains, separating premium synthetic blending from commodity mineral oil operations.
REACH authorization requirements for short-chain chlorinated paraffins are eliminating legacy extreme-pressure additives from European formulations. Metalworking fluid blenders substitute sulfur-phosphorus and polymer ester packages. German automotive OEM supplier specifications now exclude chlorinated chemistry, forcing tier-wide reformulation.
Consolidated procurement by multi-site machining groups is compressing supplier relationships toward integrated fluid management contracts. Distributor technical service teams lose specification influence to centralized metallurgy engineering functions. This concentration is most visible in Indian precision component export manufacturers around Bangalore.
Neat Cutting Oil Market Segmentation
Neat cutting oil purchasing cycles track closely with machine tool replacement and regulatory compliance deadlines. Metalworking shops upgrade fluid specifications when installing new CNC equipment or when REACH substance evaluations force additive package changes.
Product Type:
Replacement cycles for neat cutting oils accelerate as shops modernize equipment and face tighter workplace exposure limits.
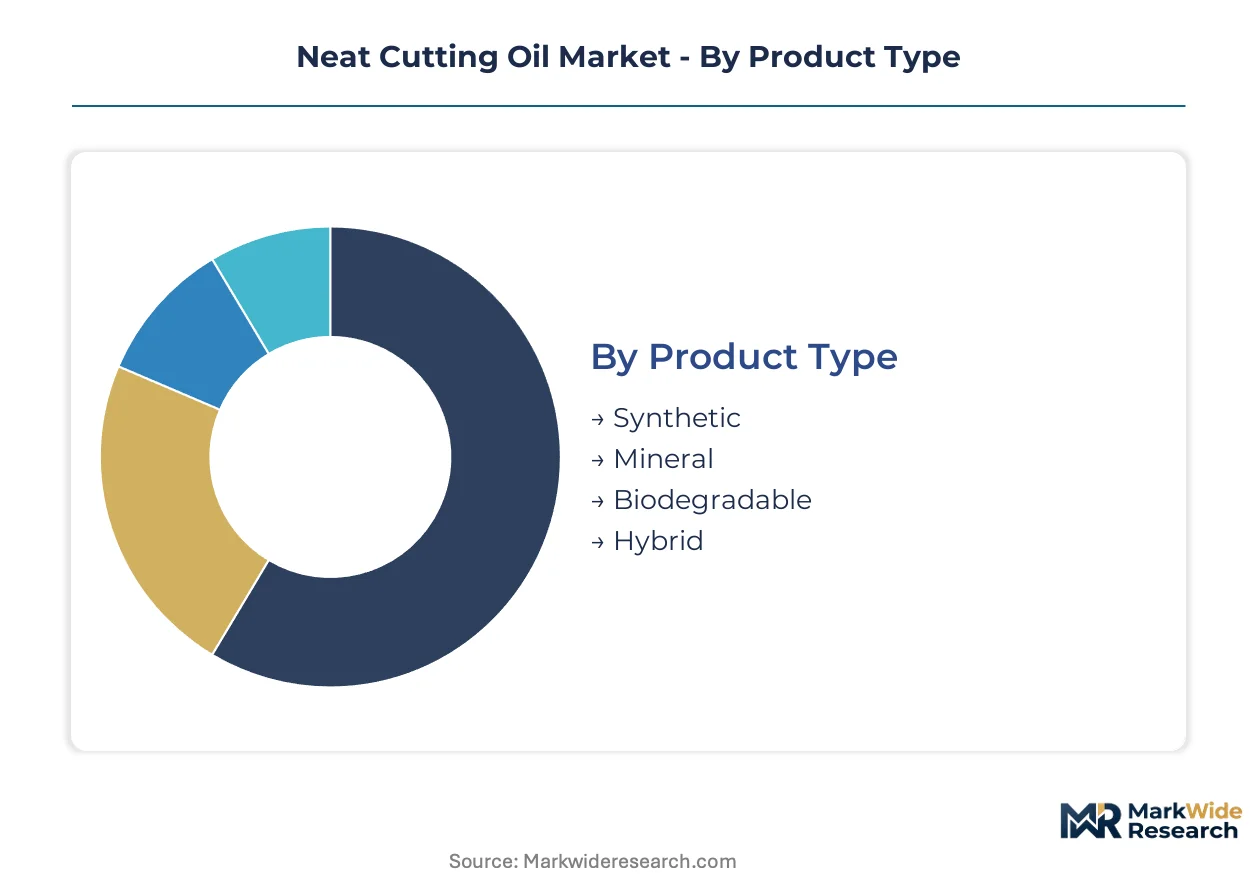
- Synthetic:Formulated from polyalphaolefins and synthetic esters with superior thermal stability and extended sump life. German aerospace manufacturers around Munich and Hamburg specify these for titanium machining as ECHA mineral oil mist restrictions tighten. Premium positioning reflects extreme-pressure additive packages optimized for high-speed CNC applications.
- Mineral:Derived from API Group I/II/III base stocks with conventional sulfur-chlorine additive systems. Price-sensitive metalworking shops in India's Pune corridor rely on these for general-purpose turning and milling operations where thermal demands remain moderate.
- Biodegradable:Vegetable oil and synthetic ester base stocks with rapid environmental degradation profiles.
- Hybrid:Blended mineral-synthetic formulations balancing cost and performance.
Mineral oil sits at the top of the volume ranking, with biodegradable formulations climbing the fastest.
Application:
Process-specific fluid requirements concentrate demand in precision finishing operations where tool life and surface quality command premium formulation costs.
- Machining:Turning, milling, and boring operations with continuous chip formation and high heat generation. Automotive transmission component manufacturers in Stuttgart specify low-mist synthetics for automated production lines.
- Grinding:Precision surface and cylindrical grinding with fine abrasive contact and critical surface finish requirements. Bearing manufacturers around Bangalore demand specialized formulations with enhanced flushing and cooling characteristics.
- Drilling:Deep-hole and conventional drilling with chip evacuation challenges.
- Tapping:Thread cutting with high friction and adhesive wear conditions.
Machining commands the largest volume share, while grinding applications expand most quickly as precision component exports from India accelerate.
End User:
Customer concentration patterns follow aerospace certification requirements and automotive supplier consolidation trends.
- Aerospace:Tier-1 and tier-2 suppliers machining aluminum, titanium, and nickel superalloys. Airbus suppliers in Toulouse and Hamburg enforce strict fluid specifications with full traceability and low-mist certification.
- Automotive:Powertrain and transmission component manufacturers with high-volume automated lines. German OEM supplier networks around Wolfsburg and Munich drive formulation standardization through consolidated procurement.
- Metalworking:Independent job shops and contract manufacturers serving multiple industries.
- Agriculture:Equipment manufacturers with seasonal production patterns and corrosion-sensitive storage requirements.
Automotive end-use generates the highest absolute volumes, with aerospace specifications gaining share fastest as certification requirements proliferate.
Formulation:
Additive chemistry selection determines regulatory compliance trajectory and occupational exposure profiles.
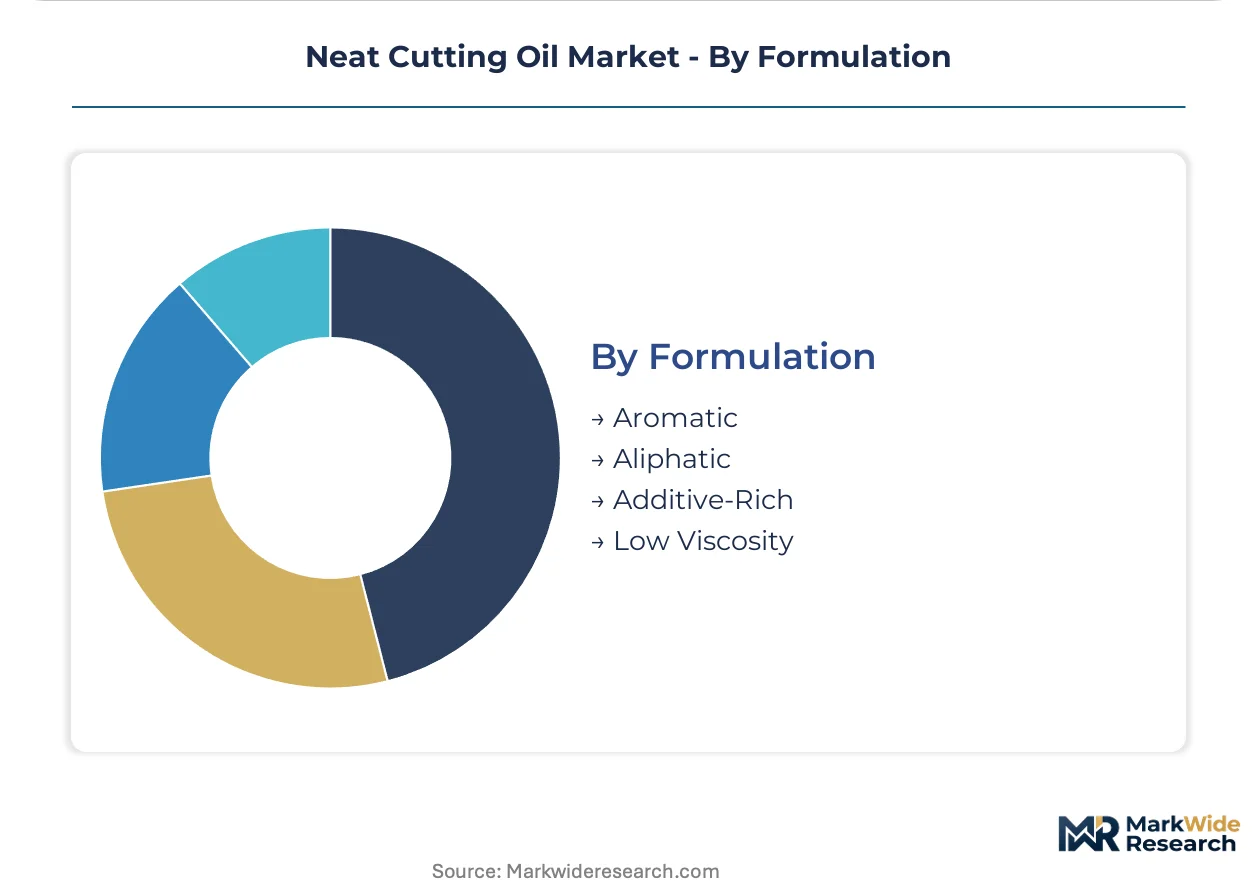
- Aromatic:Traditional solvent-refined base stocks with high solvency and compatibility with legacy additive systems. Declining share in Europe as ECHA classifications restrict mineral oil mist exposure limits.
- Aliphatic:Hydrotreated base stocks with lower aromatic content and reduced carcinogenicity concerns. German blenders promote these for automotive supplier compliance with workplace safety regulations.
- Additive-Rich:High-treatment formulations with sulfur-phosphorus and polymer ester extreme-pressure packages replacing banned chlorinated paraffins.
- Low Viscosity:ISO VG 15-32 grades for mist control and improved heat transfer in high-speed applications.
Aliphatic formulations lead current volume distribution, with additive-rich synthetics showing the steepest expansion trajectory as REACH authorization deadlines eliminate legacy chemistries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerospace machining clusters around Munich and Hamburg anchor neat cutting oil demand as REACH compliance tightens on chlorinated paraffin additives. Regional procurement patterns diverge sharply between European regulatory pressure and Asian volume expansion.
Germany
Airbus tier suppliers in Hamburg and Bavaria drive specification-grade synthetic demand. ECHA mineral oil mist carcinogenicity rulings force rapid reformulation toward aliphatic base stocks. Stuttgart automotive transmission manufacturers now mandate low-mist neat oils for automated production lines.
United States
EPA and OSHA workplace exposure limits reshape aerospace machining contracts in Washington State and Connecticut. Boeing supplier networks in Seattle-Tacoma consolidate procurement toward integrated fluid management agreements. Wichita Kansas aviation cluster demands full formulation traceability for defense subcontracting compliance.
India
Precision component exporters around Pune and Bangalore expand CNC tool room density for European automotive contracts. BIS quality certification requirements push job shops toward branded synthetic formulations. Tamil Nadu bearing manufacturers in Hosur specialize in grinding-specific neat oils with enhanced flushing characteristics.
China
MIIT industrial upgrading programs accelerate synthetic adoption in Yangtze River Delta machining centers. Ningbo and Suzhou precision component makers face dual pressure from domestic environmental inspections and EU export compliance. GB standards on metalworking fluid emissions tighten formulation requirements for state-owned automotive suppliers.
Japan
METI carbon neutrality roadmaps drive bio-based neat oil pilot programs in Nagoya automotive machining corridors. Toyota supplier keiretsu in Aichi Prefecture test synthetic ester formulations for hybrid powertrain component finishing. JIS standards on occupational exposure create specification premiums for low-mist products in precision grinding applications.
Neat Cutting Oil Market Competitive Landscape
Global majors compete with regional champions across formulation technology and technical service density. Market structure concentrates around three tiers: integrated petrochemical majors with captive base-oil supply, specialized metalworking fluid blenders with OEM co-development relationships, and regional distributors serving price-sensitive job shops. Strategic moves center on additive package reformulation partnerships and fluid management contract consolidation.
Among integrated petrochemical majors, ExxonMobil anchors the upstream-integrated archetype through base-oil network control. Castrol occupies brand-recognition positioning in high-precision machining segments. FUCHS Petrolub SE exemplifies the European specialist model with automotive OEM collaborative development. These three represent distinct competitive vectors rather than direct substitution alternatives.
| Leading Market Players |
|---|
| ExxonMobil |
| TotalEnergies |
| Sasol |
| Eastern Petroleum |
| Ashburn Chemical Technologies |
| Castrol |
| Quaker Houghton |
| Paras Lubricants |
| FUCHS Petrolub SE |
| Others |
Value Network & Pricing Analysis
API Group II base oil spot indices cascade through neat cutting oil supply chains into three distinct pricing tiers, with German aerospace buyers absorbing premium synthetic markups while Indian job shops optimize around mineral oil cost floors.
Pricing Analysis
Input-cost pass-through from base oil volatility stratifies neat cutting oil pricing across premium, standard, and economy tiers. Synthetic ester formulations command premium positioning due to thermal stability certification and extended sump life, while mineral oil grades compete on volume scale in price-sensitive metalworking corridors. Cost compression in the mineral tier is intensifying because API Group II/III capacity tightness elevates feedstock volatility. Job shops in India's Pune corridor exhibit highest price sensitivity, whereas Airbus tier suppliers in Hamburg demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke distribution patterns for neat cutting oil blending networks. Supply concentrates in the United States, Germany, and India, with base stock production drawing from Group I/II/III refinery complexes along the US Gulf Coast and Northwestern Europe. Formulation chemistry rests on sulfur-phosphorus additive packages, synthetic ester base stocks, and corrosion inhibitor systems. Single-source vulnerability in chlorinated paraffin substitutes creates reformulation bottlenecks for European blenders. Distribution runs through authorized distributor networks with technical service attachments, though consolidated procurement by multi-site machining groups is compressing channel influence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neat cutting oil procurement functions as a geographic-arbitrage play, with ECHA-driven synthetic adoption in Germany creating cost premiums that Indian mineral oil buyers avoid through BIS-grade substitution.
For Market Incumbents: Hedge against REACH authorization timelines by accelerating sulfur-phosphorus additive package validation in parallel with synthetic ester capacity expansion. Secure backward integration into regional base oil refining to defend margin position against API Group II supply volatility. Prioritize fluid management contract consolidation with Indian precision component exporters around Bangalore. For New Entrants and Emerging Players: Capture bio-based formulation white space as European manufacturers face escalating ECHA scrutiny on mineral oil mist exposure. Target secondary Indian manufacturing cities lacking Castrol-equivalent technical service density. Lead with application engineering partnerships rather than price competition. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized metalworking fluid blenders possessing automotive OEM co-development relationships and REACH-compliant additive portfolios. Five-to-ten year viability hinges on reformulation agility rather than scale. Monitor ECHA substance evaluation acceleration as the critical inflection signal for portfolio rationalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | ExxonMobil's captive API Group II supply secures feedstock continuity across North American blending facilities. |
| Synthetic Ester Capacity Expansion | FUCHS Petrolub SE anchors German automotive OEM specifications through thermal-stable formulation development. |
| Fluid Management Contract Consolidation | Castrol's technical service density in high-precision machining segments captures multi-site procurement rationalization. |
| Bio-Based Formulation Pilot Programs | Toyota supplier keiretsu in Aichi Prefecture test vegetable oil base stocks under METI carbon neutrality roadmaps. |
| REACH-Compliant Additive Package Partnerships | European blenders substitute polymer ester extreme-pressure systems ahead of chlorinated paraffin authorization deadlines. |
Research Methodology
Direct dialogue with metalworking fluid plant managers, procurement leads at German automotive OEMs, aerospace tier supplier metallurgy engineers, and Indian precision component export manufacturers grounded this analysis. Secondary validation drew from ECHA substance evaluation databases, SEC 10-K filings of integrated petrochemical majors, BIS quality certification registries, and customs trade data on base oil imports. Bottom-up demand modeling across CNC tool room density and machine tool replacement cycles triangulated against top-down base oil consumption trends.
Segment-level volume and value estimates emerged from modeling across product type, application process, end-use industry, and formulation chemistry dimensions throughout the projection horizon. CAGRs derived from regression analysis of historical base oil price elasticity, regulatory compliance deadline clustering, and precision manufacturing capital expenditure patterns. Forecast inputs incorporated REACH authorization timelines, MIIT industrial upgrading program implementation, and EPA-OSHA workplace exposure limit revision trajectories.
Underlying measurement precision varies by segment; synthetic and biodegradable categories carry tighter precision than mineral oil volumes given consolidated supplier disclosure. Forecasts reflect documented assumptions around regulatory enforcement intensity and machine tool replacement cycle timing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Spain Lubricants Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
France Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Cutting Fluid Market
Lubricants
Global Commercial Vehicles Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Biolubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Global Mineral Oil Market