
 Global Fire Resistant Hydraulic Fluid Market | 2026-2036
Global Fire Resistant Hydraulic Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fire Resistant Hydraulic Fluid Market Foresight
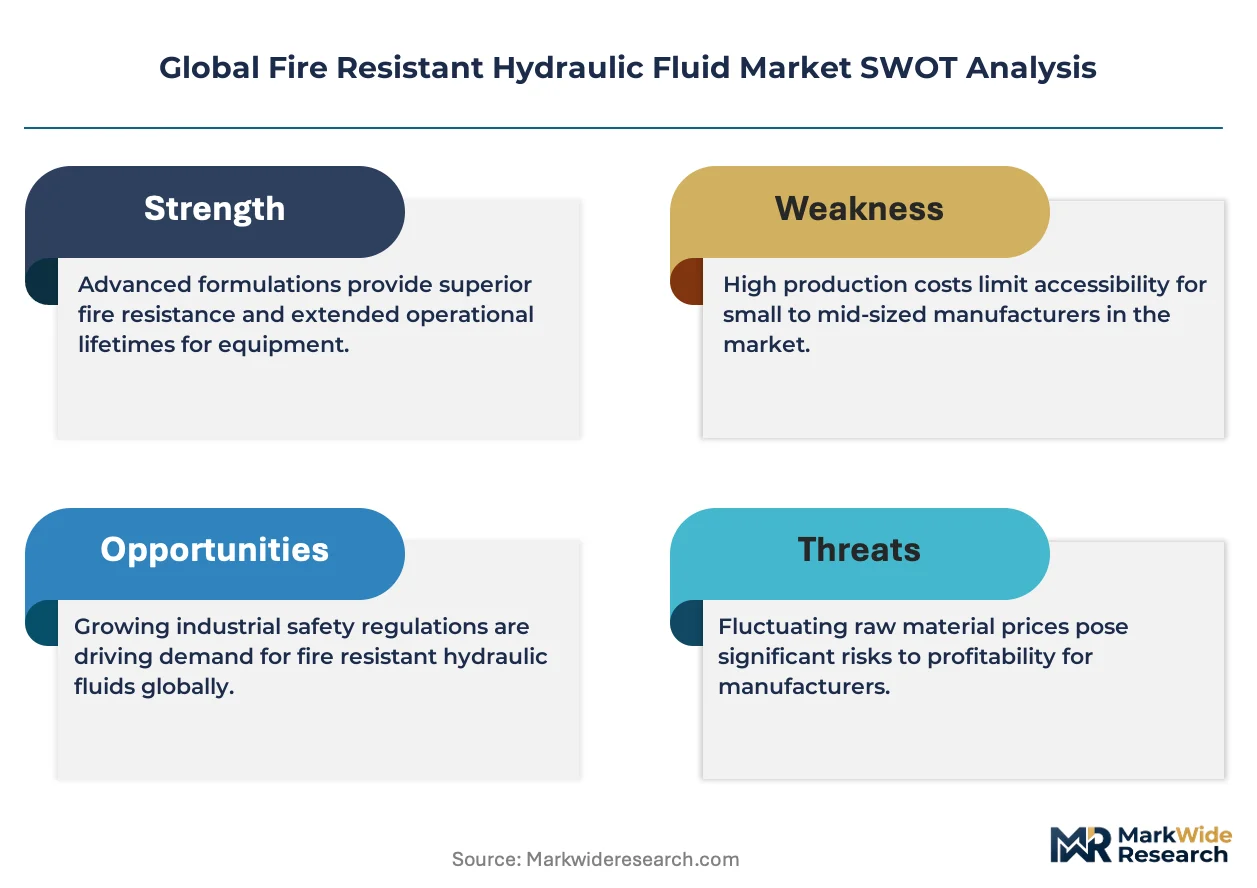
Germany's Rhineland-Palatinate chemical complex is reshaping supply geography for fire resistant hydraulic fluid production in Europe. ExxonMobil Corporation leverages its integrated base oil and additive manufacturing to sustain cost advantages across phosphate ester and polyol ester lines. Shell plc anchors its position through specialized synthetic hydrocarbon formulations designed for high-temperature steel mill circuits. FUCHS SE differentiates via deep technical service relationships with German automotive press shops and foundries.
Fire resistant hydraulic fluids are formulated lubricants engineered to resist ignition and flame propagation when exposed to high-temperature sources near hydraulic systems, typically achieving flash points above 300°C through phosphate ester, water-glycol, or synthetic base stock chemistry. Their primary purpose is maintaining operational continuity in steel mills, foundries, power generation turbines, and aircraft landing gear where mineral oil ignition would cascade into catastrophic equipment loss or facility fires. Phosphate esters occupy the premium tier due to inherent self-extinguishing chemistry and compatibility with legacy aviation and power generation hardware. Water-glycol formulations compete aggressively on cost in stationary metalworking and mining machinery where dilution tolerance offsets lower lubricity. Polyol esters are capturing incremental share in closed circuit marine equipment as shipbuilders navigate IMO-aligned fire safety mandates.
The U.S. Mine Safety and Health Administration and OSHA enforce strict fire resistance ratings for underground hydraulic machinery, compelling mining operators toward certified water-glycol and synthetic hydrocarbon replacements. ECHA's REACH restrictions on halogenated additives and the EU F-Gas Regulation are redirecting formulation investment toward phosphorus-based and bio-derived chemistries without compromising ignition resistance. Stakeholders must monitor regulatory divergence between EPA industrial fire codes and EU hazard classification revisions, as compliance fragmentation threatens to segment product portfolios and inflate qualification costs for multinational fluid suppliers.
Market Dynamics
Steel mill furnace proximity intensification is compressing fluid replacement cycles and forcing specification upgrades across phosphate ester and water-glycol formulations. This thermal exposure dynamic is restructuring supplier-buyer relationships around technical service intensity rather than commodity pricing.
Growth Catalysts
- EU F-Gas Regulation:European metalworkers face mandatory transition away from halogenated chemistries, directing capital toward phosphorus-based hydraulic formulations in Germany's Ruhr industrial belt.
- Steel mill furnace expansion:Continuous casting operations in India's Maharashtra and Karnataka states require fire resistant fluid upgrades as induction furnace density increases thermal hazard exposure.
- Aviation landing gear modernization:Legacy phosphate ester specifications in commercial aerospace maintenance programs sustain premium formulation demand despite stationary industrial substitution.
Market Restraints
- Phosphate ester feedstock concentration:Triphenyl phosphate supply concentrates among Chinese specialty chemical manufacturers, exposing European blenders to freight cost volatility and customs processing delays.
- Water-glycol lubricity ceiling:Dilution-tolerant formulations face technical barriers in high-pressure forging presses above 350 bar, restricting penetration in heavy closed-die operations.
- REACH registration burden:ECHA's substance evaluation timeline extends 18-24 months for novel bio-derived base stocks, freezing formulation innovation pipelines for mid-tier suppliers.
Strategic Opportunities
- Brazilian mining underpenetration:ANVISA alignment with ISO 6743-4 fire resistance categories remains incomplete, creating first-mover advantage for certified water-glycol suppliers in Minas Gerais iron ore extraction.
- Marine IMO 2020 spillover:SOLAS fire safety mandates for engine room hydraulics are redirecting shipyard specification toward polyol esters in South Korean and Japanese newbuild contracts.
- Digital fluid monitoring convergence:IoT sensor integration with phosphate ester condition monitoring enables predictive replacement scheduling, opening subscription revenue streams for technical service providers.
Industry Challenges
- Tribology specialist scarcity:Formulation chemists with simultaneous expertise in fire resistance testing and hydraulic system engineering command premium compensation, constraining R&D team expansion for regional blenders.
- Legacy aviation certification timelines:FAA and EASA qualification cycles for new phosphate ester variants extend 4-7 years, compressing returns on development investment for aerospace-focused product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fire Resistant Hydraulic Fluid Market |
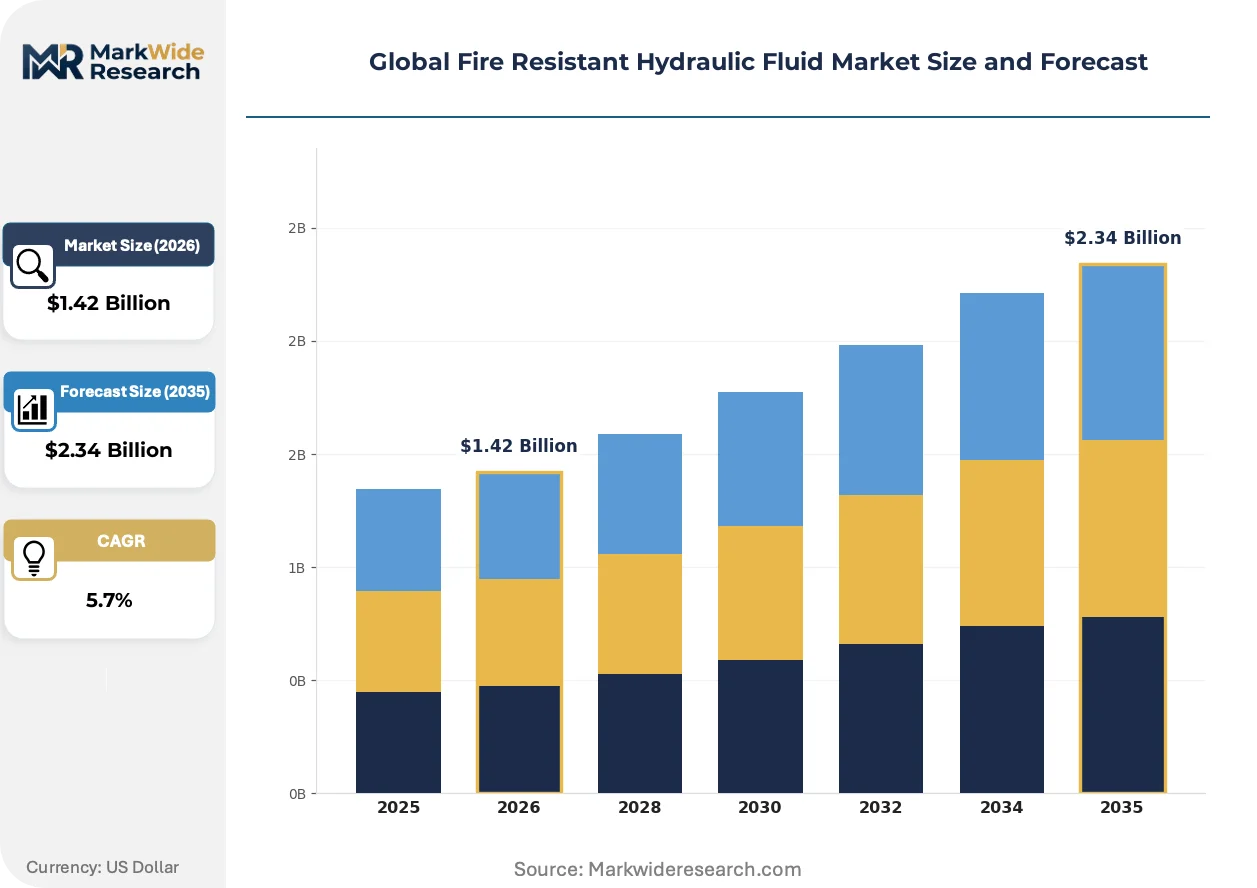
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.34 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Esters, Water Glycol, Polyol Esters, Fluorinated Fluids, Synthetic Hydrocarbons Application: Power Plants, Marine Equipment, Metalworking, Aviation, Mining Machinery End User: Energy Producers, Shipbuilders, Aerospace Manufacturers, Mining Operators, Industrial Fabricators Deployment Type: Open Circuit Systems, Closed Circuit Systems, Mobile Equipment, Stationary Equipment |
| Companies Covered | ExxonMobil Corporation, Shell plc, TotalEnergies SE, BASF SE, Quaker Chemical Corporation, FUCHS SE, Castrol Ltd., American Chemical Technologies Inc., Houghton International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fire Resistant Hydraulic Fluid Market Shifts & Advancements
Synthetic base stock chemistry is advancing faster than equipment specification cycles, creating specification drift between available technology and installed base compatibility requirements.
Phosphate ester formulations with enhanced hydrolytic stability are rendering obsolete conventional maintenance intervals in power generation turbine hydraulic circuits. Combined cycle plant operators in Texas and Florida are adopting these extended-life fluids to reduce outage frequency. The technology is rendering obsolete traditional 3-year replacement schedules, compressing aftermarket volume while elevating unit margins.
ECHA's 2023 REACH restriction proposal on medium-chain chlorinated paraffins is forcing reformulation of secondary plasticizer packages in European water-glycol blends. German and Dutch metalworking fluid suppliers are accelerating bio-derived polyol testing to maintain fire resistance ratings without restricted additives. Steel service centers in the Benelux region are experiencing 6-9 month qualification delays as blenders validate replacement chemistries.
Buyer consolidation among North American forging groups is consolidating specification authority into centralized procurement functions. Tier-one automotive stampers now mandate ISO 12922 compliance certification as a bid prerequisite, displacing informal supplier relationships. This concentration is most visible in Michigan and Ohio, where three buying groups control 60% of regional hydraulic fluid volume.
Global Fire Resistant Hydraulic Fluid Market Segmentation
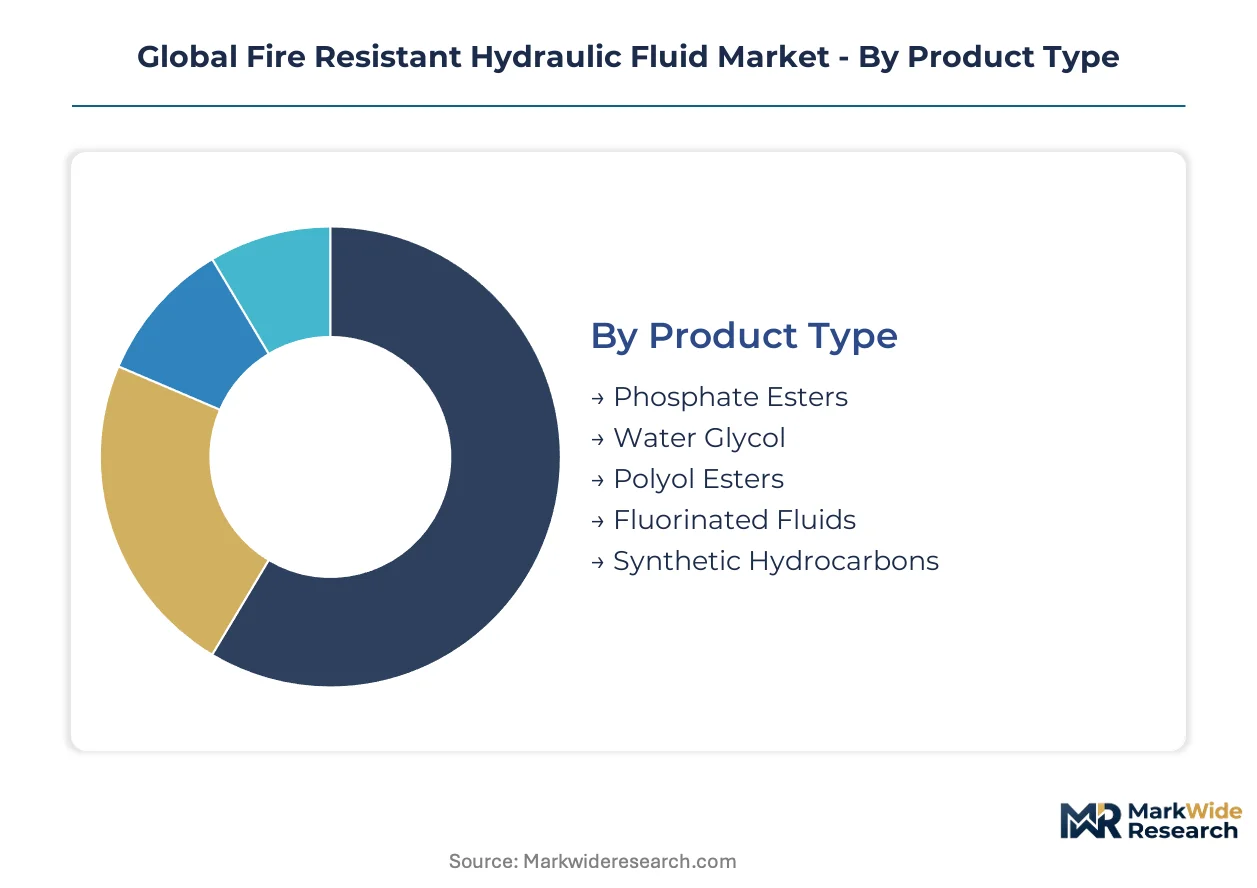
Fire resistant hydraulic fluid specification varies sharply across thermal exposure profiles, pressure regimes, and regulatory jurisdictions. Segmentation reveals how formulation chemistry, equipment architecture, and end-use risk tolerance combine to structure supplier pricing power and technical service intensity.
Product Type:
Use-case spectrum spans legacy aviation hardware requiring phosphate ester compatibility through cost-driven mining machinery running water-glycol dilutions.
- Phosphate Esters:Self-extinguishing synthetic base stocks formulated from triphenyl phosphate derivatives achieve flash points exceeding 300°C without halogenated additives. Demand concentrates in German power generation turbine hydraulics and Texas combined cycle plants where FAA and EASA legacy specifications govern maintenance protocols. REACH compliance and EU F-Gas Regulation enforcement sustain premium positioning against fluorinated alternatives.
- Water Glycol:Dilution-tolerant formulations blending deionized water with polyglycol thickeners and corrosion inhibitors compete aggressively on cost-per-liter in underground mining and metal forging. India's Maharashtra steel mills specify these fluids for induction furnace proximity applications where 40-50% water content provides inherent fire suppression. Lubricity limitations above 350 bar restrict penetration in high-pressure closed-die forging.
- Polyol Esters:Biodegradable synthetic esters gaining specification in South Korean and Japanese shipyard contracts under SOLAS fire safety mandates.
- Fluorinated Fluids:Perfluoropolyether chemistry facing regulatory pressure from EPA industrial fire codes and ECHA restrictions on persistent organic pollutants.
- Synthetic Hydrocarbons:PAO-based formulations serving OSHA-compliant underground mining machinery in US Appalachian coal operations.
Established volume favors phosphate esters; emerging adoption favors polyol esters.
Application:
Cost tier stratification separates premium-specified aviation maintenance from commodity-priced metalworking procurement.
- Metalworking:Continuous casting and forging operations in Germany's Ruhr industrial belt and India's Karnataka state drive specification upgrades as furnace density intensifies thermal hazard exposure. Procurement concentrates among centralized buying groups in Michigan and Ohio automotive stampers mandating ISO 12922 certification.
- Aviation:Commercial aerospace landing gear and flight control hydraulics sustain phosphate ester demand through 4-7 year FAA/EASA qualification cycles that freeze formulation substitution. Legacy fleet maintenance programs in Texas and Florida generate recurring aftermarket volume despite stationary industrial substitution trends.
- Power Plants:Combined cycle turbine hydraulics adopting extended-life phosphate esters with enhanced hydrolytic stability.
- Marine Equipment:Engine room systems redirecting toward polyol esters under IMO-aligned fire safety mandates.
- Mining Machinery:Underground hydraulic equipment regulated by MSHA fire resistance ratings compelling water-glycol and synthetic hydrocarbon adoption.
Specification authority concentrates in metalworking procurement functions; qualification barriers protect aviation margins.
End User:
Customer type segmentation maps to regulatory exposure intensity and technical service requirements.
- Industrial Fabricators:Steel service centers and automotive press shops in Germany's Rhineland-Palatinate and Benelux regions require continuous hydraulic protection with 6-9 month qualification delays for REACH-compliant reformulations.
- Mining Operators:Iron ore extraction in Brazil's Minas Gerais state presents underpenetration opportunity as ANVISA alignment with ISO 6743-4 fire resistance categories remains incomplete.
- Energy Producers:Texas and Florida combined cycle plant operators adopting predictive fluid monitoring subscriptions.
- Shipbuilders:South Korean and Japanese newbuild contracts specifying polyol esters for engine room hydraulics.
- Aerospace Manufacturers:Maintenance, repair, and overhaul providers locked into legacy phosphate ester specifications.
Procurement consolidation favors industrial fabricators; regulatory fragmentation favors mining operators.
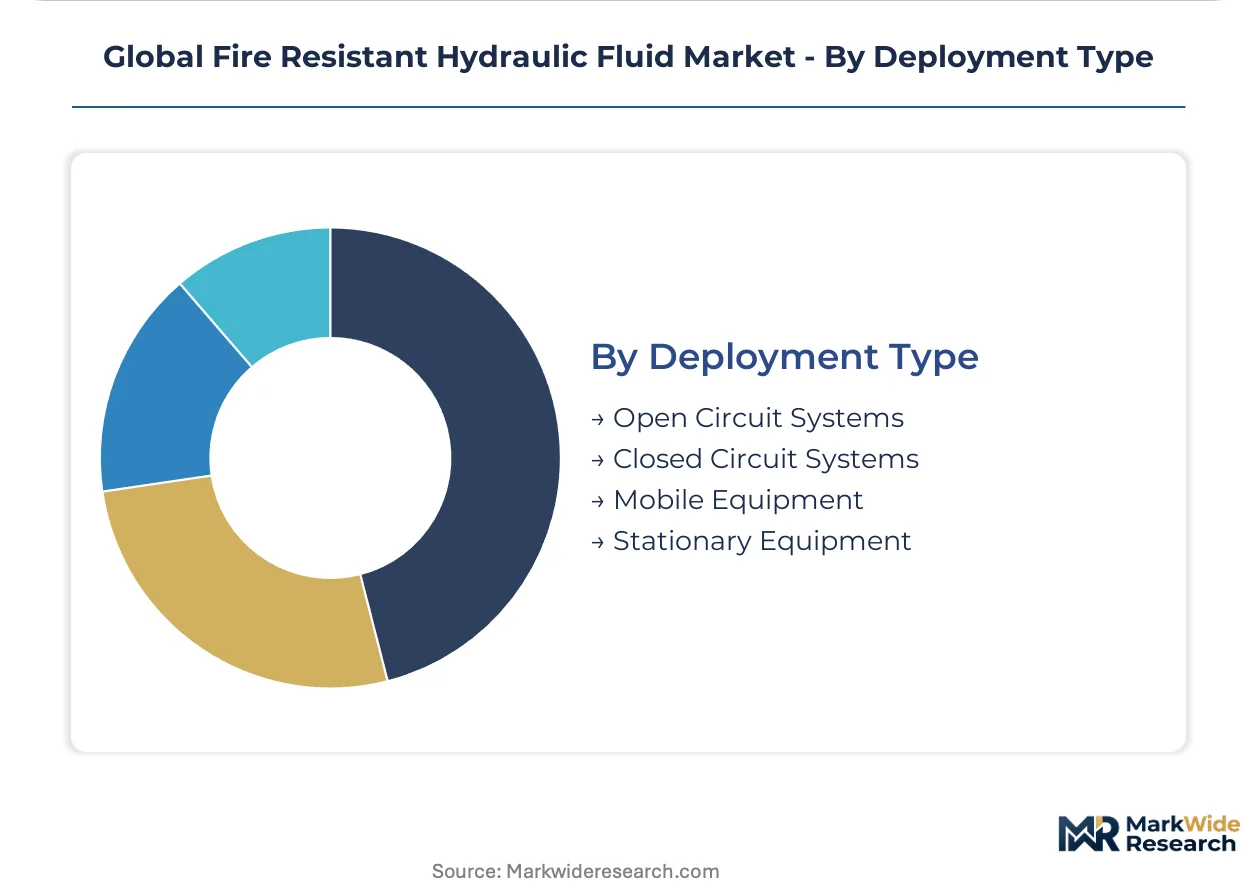
Deployment Type:
Equipment architecture determines fluid stress factors and replacement cycle economics.
- Closed Circuit Systems:High-pressure forging presses and marine engine room hydraulics where contamination control extends fluid life. Polyol esters capture incremental share as shipbuilders navigate IMO mandates.
- Stationary Equipment:Steel mill furnace proximity applications in Germany and India compressing replacement schedules and forcing specification upgrades.
- Open Circuit Systems:Metalworking machinery with higher contamination exposure and shorter maintenance intervals.
- Mobile Equipment:Underground mining machinery regulated by MSHA and OSHA fire resistance requirements.
Technical service intensity concentrates in closed circuit deployments; volume scale concentrates in stationary equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Triphenyl phosphate feedstock concentration among Chinese specialty chemical manufacturers exposes European blenders to freight cost volatility and customs processing delays. Fluid demand geography tracks steel production corridors, power generation clusters, and mining jurisdictions with strict fire resistance enforcement.
United States
OSHA and MSHA enforce strict fire resistance ratings for underground hydraulic machinery in Appalachian coal operations and Arizona copper extraction. EPA industrial fire codes pressure fluorinated fluid formulations toward phosphorus-based alternatives. Texas and Florida combined cycle plant operators adopt extended-life phosphate esters with enhanced hydrolytic stability.
Germany
EU F-Gas Regulation and REACH compliance standards push metalworkers toward phosphate ester formulations in the Ruhr industrial belt. ECHA's 2023 restriction proposal on medium-chain chlorinated paraffins forces reformulation of water-glycol plasticizer packages. Rhineland-Palatinate's chemical complex reshapes supply geography for European production.
India
Maharashtra and Karnataka steel mills specify water-glycol fluids for induction furnace proximity applications where thermal hazard exposure intensifies. BIS standards alignment with ISO 6743-4 fire resistance categories remains incomplete, creating qualification complexity for multinational suppliers. Continuous casting operations compress fluid replacement cycles.
China
Triphenyl phosphate derivative manufacturing concentrates among domestic specialty chemical producers serving both captive demand and export markets. MEE enforcement of industrial fire safety standards tightens specification requirements in coastal steel provinces. Yangtze River Delta heavy forging clusters drive phosphate ester consumption.
Brazil
ANVISA alignment with ISO 6743-4 fire resistance categories remains incomplete, creating first-mover advantage for certified water-glycol suppliers. Minas Gerais iron ore extraction operations present underpenetrated demand as fire resistance certification becomes procurement prerequisite. Underground mining expansion intensifies regulatory scrutiny.
Global Fire Resistant Hydraulic Fluid Market Competitive Landscape
Integrated petrochemical majors and specialized lubricant blenders split the market between scale-driven base stock advantages and technical service intensity. ExxonMobil and Shell anchor the upper tier through captive supply chains and aviation certification heritage. Mid-cap regional blenders compete on formulation flexibility and customer proximity. Competitive moves concentrate on backward integration into additive manufacturing and predictive fluid monitoring service bundling.
Among integrated petrochemical majors, ExxonMobil Corporation and Shell plc exemplify scale-driven positioning through combined base oil and additive manufacturing capabilities. FUCHS SE occupies the specialized blender archetype with deep technical service relationships. These three anchors demonstrate how market structure favors either upstream integration or downstream service intensity as distinct competitive vectors.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| TotalEnergies SE |
| BASF SE |
| Quaker Chemical Corporation |
| FUCHS SE |
| Castrol Ltd. |
| American Chemical Technologies Inc. |
| Houghton International Inc. |
| Others |
Supply & Pricing Matrix
Rhineland-Palatinate's chemical complex capacity dynamics directly determine downstream pricing power for European phosphate ester blenders, as captive additive manufacturing at integrated majors compresses margins for independent formulators serving Ruhr steel mills.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across the European metalworking segment, separating REACH-certified phosphate esters from uncertified water-glycol alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale. Price differentiation hinges on ECHA registration status and ISO 12922 compliance. Cost compression in water-glycol tiers is intensifying because feedstock substitution timelines extend 18-24 months. Mining operators in Brazil exhibit highest price sensitivity; aviation MRO providers show least.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk calculus for triphenyl phosphate derivatives. Manufacturing concentrates in China's Yangtze River Delta, Germany's Rhineland-Palatinate, and US Gulf Coast petrochemical corridors. Formulation draws from triphenyl phosphate, polyglycol thickeners, and corrosion inhibitor packages. Single-source vulnerability concentrates in Chinese specialty chemical producers. Distribution runs through regional blending facilities co-located with steel production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbents through 4-7 year aviation certification cycles that freeze formulation substitution and erect prohibitive qualification barriers.
For Market Incumbents: Insulate phosphate ester margins through backward integration into triphenyl phosphate additive manufacturing, eliminating Chinese feedstock exposure. Anchor capacity expansion in Texas combined cycle corridors where extended-life formulations command premium positioning. Certification investment in FAA/EASA legacy specifications remains the critical lever against bio-derived substitute technologies. For New Entrants and Emerging Players: Brazilian iron ore extraction in Minas Gerais represents the most penetrable entry point, as ANVISA alignment gaps with ISO 6743-4 categories delay incumbent certification. South Korean shipyard polyol ester specifications under SOLAS mandates offer second white-space target. Go-to-market angle: technical service bundling with IoT condition monitoring subscriptions to bypass commodity pricing. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized blenders with captive aviation certification heritage over integrated petrochemical majors facing feedstock volatility. Long-term viability rests on regulatory entrenchment durability through REACH and F-Gas enforcement. Acquisition target archetype: regional formulators with deep OEM technical relationships. Signal to watch: EASA acceleration of bio-derived fluid qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive triphenyl phosphate production insulates German blenders from Chinese supply volatility. |
| Long-term Supply Agreement | Ruhr steel mills lock in phosphate ester volumes through furnace expansion cycles. |
| Joint Venture | Rhineland-Palatinate chemical partnerships accelerate REACH-compliant water-glycol reformulation. |
| Capacity Expansion | Texas combined cycle plant density supports extended-life phosphate ester demand. |
| Geographic Expansion | Minas Gerais mining corridors offer first-mover positioning as ANVISA alignment completes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this study's primary research phase, encompassing maintenance directors at German automotive press shops, procurement leads at Maharashtra steel mills, technical R&D directors at Rhineland-Palatinate blending facilities, and aftermarket service heads at Texas power generation operators. Secondary validation drew from ECHA substance registration databases, SEC 10-K filings of integrated petrochemical majors, customs trade data on triphenyl phosphate derivatives, and ISO 6743-4 certification registries. Bottom-up volume modeling triangulated against top-down industry spend estimates.
Calibration against historical replacement cycle compression in steel mill applications and aviation fleet maintenance schedules anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry tier, end-use thermal exposure profile, equipment architecture type, and regional regulatory cluster. CAGRs derived from installed base growth rates and specification upgrade intensity. Industry-specific forecast inputs incorporated furnace proximity density indices and REACH registration pipeline status.
Practitioners should monitor ECHA bio-derived base stock evaluation timelines and FAA qualification cycle acceleration for early signals of technology substitution risk. Forecasts reflect assumptions regarding regulatory enforcement continuity and feedstock supply stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Contact Lubricants Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Vietnam Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Global Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Construction Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
India Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Global Refrigeration Lubricants Market