
 Europe Grease Market | 2026-2036
Europe Grease Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Grease Market Foresight
A shortage of tribology specialists and lubricant chemists is reorganizing how European grease manufacturers allocate technical resources. FUCHS leverages its German R&D base to sustain premium formulation capabilities. Royal Dutch Shell competes through integrated supply chains spanning base oil production to finished grease distribution.
Grease is a semi-solid lubricant consisting of a base oil, thickener, and functional additives, typically exhibiting a worked penetration of 220-340 mm per tenth per ASTM D217, designed to reduce friction and prevent wear in components where oil retention or infrequent relubrication is required. Lithium complex greases dominate volume due to their elevated dropping points and multi-purpose compatibility across automotive and industrial machinery end uses. Biodegradable performance grades are gaining structural importance as marine and construction equipment operators face tightening environmental discharge rules.
REACH, the EU F-Gas Regulation, and ECHA chemical restriction frameworks are elevating compliance costs while accelerating substitution toward bio-based and low-toxicity formulations. CE marking requirements under the EU Machinery Directive further standardize grease performance claims for industrial equipment integration. Stakeholders must weigh regulatory compliance investments against the margin compression risk from commoditized mineral-oil-based products.
Market Dynamics
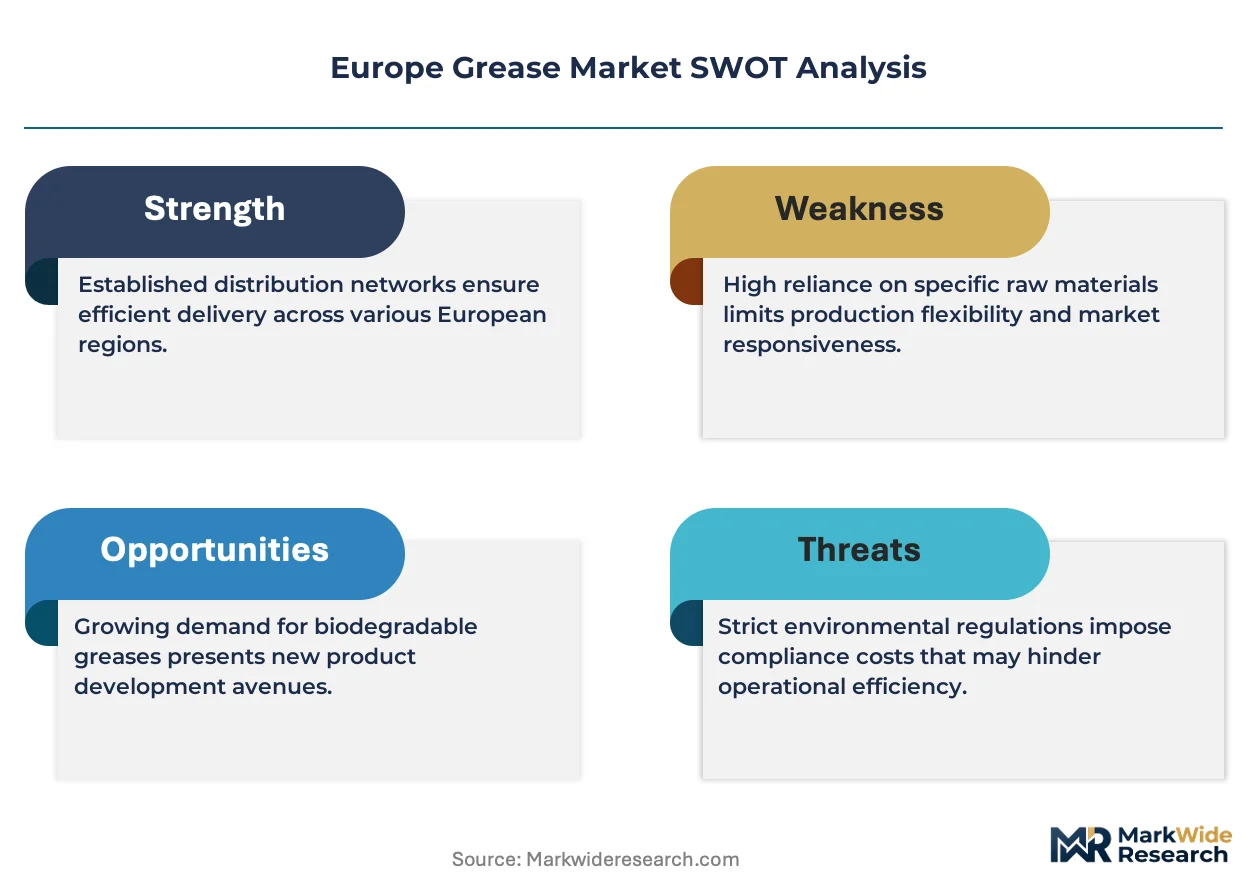
REACH chemical restriction frameworks and the EU F-Gas Regulation are forcing European grease manufacturers to rebuild formulation portfolios around bio-based thickeners and low-toxicity base oils, compressing margins on legacy mineral-oil products while opening premium positioning for compliant alternatives.
Growth Catalysts
- Electric vehicle drivetrain demand:Germany and France are expanding grease consumption for EV motor bearings and gearboxes, requiring specialized thermal stability grades that command formulation premiums.
- REACH substitution mandates:ECHA restrictions on persistent organic pollutants are pulling demand toward polyurea and calcium sulfonate thickeners that bypass lithium supply constraints.
- Marine discharge regulations:Biodegradable performance grades are gaining structural importance as North Sea and Mediterranean vessel operators face tightening environmental compliance deadlines.
Market Restraints
- Base oil supply concentration:European refiners control Group I and Group II feedstock availability, exposing compounders to feedstock volatility when crude differentials widen.
- Thickener technical limitations:Bio-based alternatives struggle to match lithium complex dropping points above 260°C, constraining high-temperature industrial applications.
- Regulatory friction from F-Gas:Fluorinated grease formulations face phase-down schedules that compress product lifecycles before R&D amortization completes.
Strategic Opportunities
- Poland industrial corridor expansion:Central European manufacturing investment is creating demand for multi-purpose maintenance greases with extended relubrication intervals.
- EU Green Deal procurement incentives:Public infrastructure tenders now weight environmental product declarations, favoring bio-based and carbon-accounted formulations.
- Wind turbine bearing convergence:Mainshaft and pitch bearing applications are merging specifications, enabling volume production of single high-performance grades.
Industry Challenges
- Tribology specialist scarcity:European universities produce insufficient lubricant chemists, forcing manufacturers to poach talent or dilute technical service capabilities.
- CE marking compliance timelines:EU Machinery Directive performance claims require extended validation cycles that delay new product launches by 12-18 months.
- Legacy system integration:Industrial end-users operate mixed-equipment fleets with incompatible grease specifications, complicating single-grade consolidation efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Grease Market |
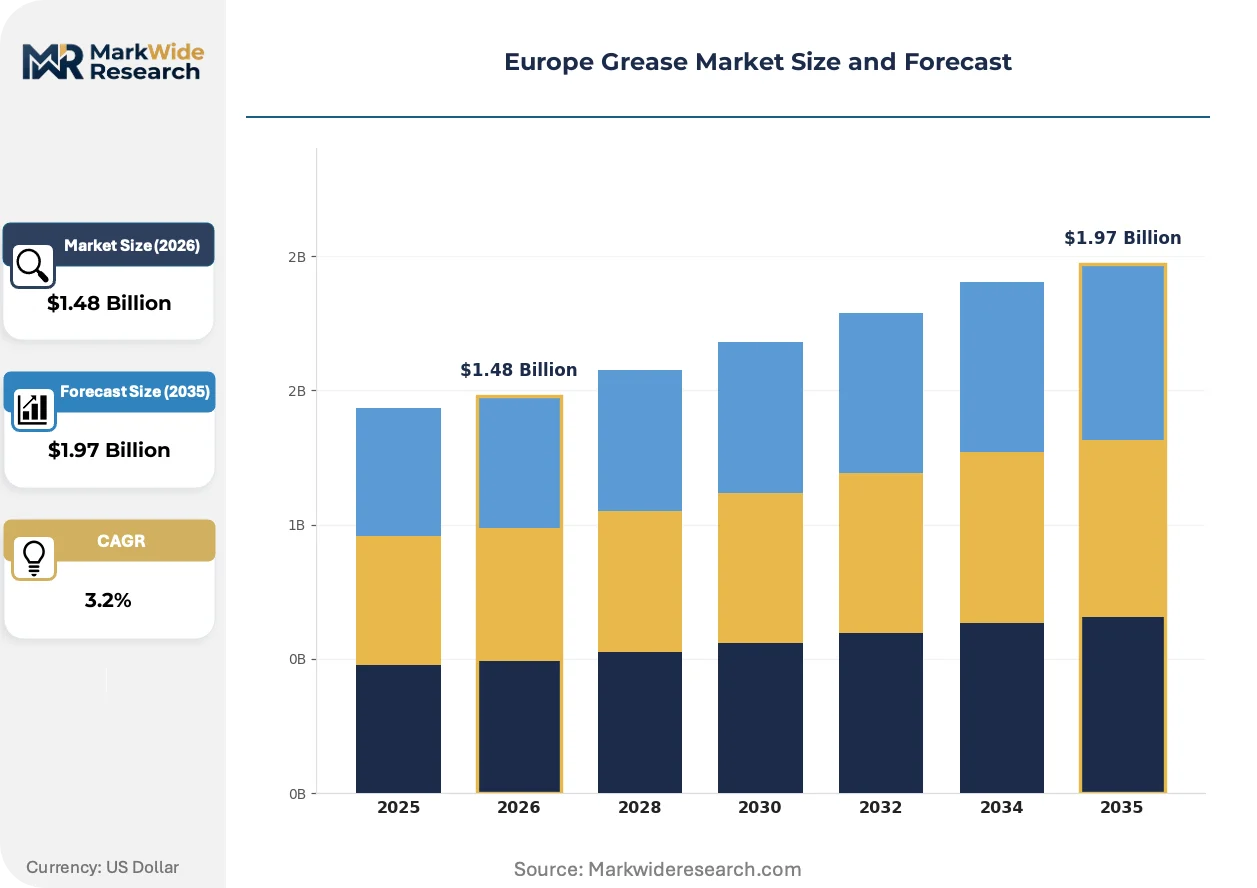
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium, Calcium, Aluminum, Complex End User: Aerospace, Automotive, Industrial Machinery, Marine Application: Bearings, Gearboxes, Chassis, Construction Equipment Performance Grade: High Temperature, Low Temperature, Biodegradable, Water Resistant |
| Companies Covered | FUCHS, Royal Dutch Shell, Lukoil, Lubrita, Axel Christiernsson International AB, ExxonMobil Corporation, TotalEnergies SE, Kluber Lubrication, Chevron Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Grease Market Shifts & Advancements
Formulation chemistry, regulatory compliance architecture, and procurement behavior are converging to reshape competitive positioning across European grease supply chains.
Polyurea thickeners are displacing lithium complex dominance in electric motor applications due to superior oxidation stability and lower noise characteristics. German automotive suppliers are accelerating adoption for EV drivetrain bearings. This displacement is compressing lithium grease volume in premium segments while elevating polyurea pricing power.
REACH authorization requirements for polycyclic aromatic hydrocarbons are forcing reformulation of rubber-compatible greases used in sealing applications. Industrial compounders must resubmit safety data sheets and performance claims. The construction equipment segment faces the steepest compliance burden, with Italian and Spanish manufacturers accelerating supplier audits.
Consolidated procurement by European fleet operators is compressing supplier counts and extending contract durations. Maintenance managers at German logistics companies now specify single-source grease programs with technical service attachments. This concentration is most visible in the Rhine-Ruhr industrial cluster, where integrated supply agreements are displacing spot purchasing.
Europe Grease Market Segmentation
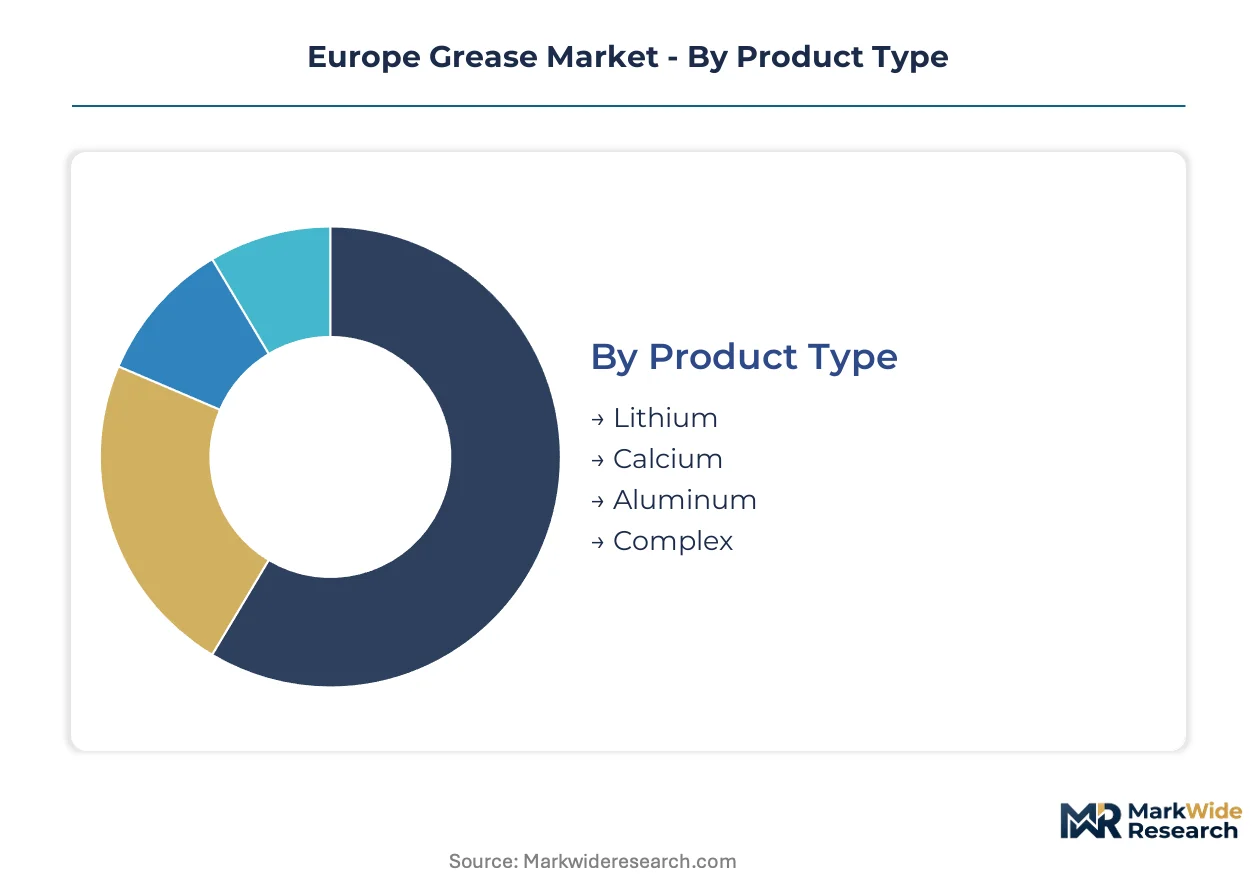
European grease manufacturers must align formulation portfolios with divergent technical requirements across thickener chemistries, end-use specifications, and regulatory compliance tiers. Segmentation strategy determines which product lines absorb REACH-driven reformulation costs and which capture premium positioning from EV drivetrain and marine discharge mandates.
Product Type:
Calcium and aluminum thickeners face the most acute substitution pressure as ECHA restrictions on lithium supply constraints and REACH compliance costs reshape thickener selection criteria.
- Lithium:Lithium soap and lithium complex formulations deliver dropping points above 260°C and multi-purpose compatibility across automotive wheel bearings and industrial gearboxes. German automotive suppliers specify lithium complex grades for EV drivetrain applications, though ECHA chemical restrictions are accelerating polyurea displacement in premium motor bearing segments.
- Complex:Lithium complex and calcium sulfonate complex thickeners combine elevated thermal stability with enhanced water resistance for construction equipment and marine deck machinery. French industrial compounders are expanding calcium sulfonate production to bypass lithium raw material volatility while maintaining high-temperature performance claims.
- Calcium:Anhydrous calcium and hydrated calcium soap greases serve lower-temperature chassis and general machinery applications with cost-sensitive formulation economics.
- Aluminum:Aluminum complex thickeners provide shear stability and water resistance for food-grade and specialty sealing applications under EFSA compliance frameworks.
Lithium retains volume leadership across European automotive and industrial maintenance segments; complex thickeners hold the steepest expansion curve as manufacturers substitute away from supply-constrained lithium feedstocks.
End User:
Cost tier stratification separates specification-intensive aerospace and automotive programs from price-sensitive industrial maintenance procurement.
- Automotive:EV drivetrain bearings and gearboxes demand specialized thermal stability grades with extended relubrication intervals. German OEMs specify polyurea-thickened formulations for electric motor applications, commanding formulation premiums over legacy lithium greases.
- Industrial Machinery:Maintenance managers at Rhine-Ruhr manufacturing clusters specify single-source grease programs with technical service attachments, consolidating procurement around multi-purpose lithium complex grades.
- Marine:North Sea and Mediterranean vessel operators face tightening environmental discharge rules, pulling demand toward biodegradable performance grades with Ecolabel certification.
- Aerospace:Aircraft wheel bearings and airframe applications require MIL-PRF-23827 certified formulations with extreme temperature ranges and low-torque starting characteristics.
Automotive applications retain volume leadership across European grease consumption; marine end-use holds the steepest expansion curve as regulatory deadlines accelerate biodegradable grade adoption.
Application:
Customer type divergence separates specification-driven OEM bearing programs from aftermarket maintenance procurement with extended relubrication requirements.
- Bearings:Rolling element and plain bearing applications dominate grease consumption volume, requiring rheological stability under shear and contamination resistance. Wind turbine mainshaft and pitch bearing specifications are converging, enabling volume production of single high-performance grades for Polish and German onshore installations.
- Gearboxes:Enclosed gear systems demand adhesiveness and EP additive packages to prevent micropitting under boundary lubrication conditions.
- Chassis:Steering linkages, suspension joints, and brake hardware require water washout resistance and compatibility with elastomer seals.
- Construction Equipment:Italian and Spanish manufacturers face the steepest REACH compliance burden for rubber-compatible greases, accelerating supplier audits and reformulation timelines.
Bearing applications retain volume leadership across European formulation output; gearbox applications hold the steepest expansion curve as EV drivetrain architecture multiplies gear mesh lubrication points.
Performance Grade:
Supply concentration in base oil refining and thickener manufacturing shapes which performance tiers achieve cost-competitive scale.
- Biodegradable:Vegetable oil and synthetic ester base stocks with polyurea or calcium thickeners serve marine deck equipment and construction machinery in environmentally sensitive zones. EU Green Deal procurement incentives now weight environmental product declarations, favoring bio-based formulations in public infrastructure tenders.
- High Temperature:Polyurea and complex soap thickeners with synthetic base oils maintain structural integrity above 180°C operating temperatures for electric motor bearings and industrial oven equipment.
- Water Resistant:Calcium sulfonate and aluminum complex formulations prevent washout in wet operating environments including pulp mills and offshore platforms.
- Low Temperature:PAO and ester base oils with lithium or calcium thickeners maintain pumpability below -40°C for cold climate aerospace and arctic industrial applications.
High temperature grades retain volume leadership across premium industrial segments; biodegradable formulations hold the steepest expansion curve as marine discharge regulations tighten across North Sea and Mediterranean jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German grease manufacturers command formulation premiums that Polish compounders cannot match, creating a pricing-power asymmetry across the continent's industrial corridor.
Germany
EV drivetrain bearings and wind turbine mainshafts pull demand for polyurea-thickened grades with thermal stability above 180°C. REACH authorization timelines under ECHA compress product development cycles for rubber-compatible formulations. The Rhine-Ruhr cluster consolidates procurement around single-source grease programs with attached technical service agreements.
France
Marine deck equipment operators in Mediterranean ports accelerate biodegradable grade adoption ahead of discharge regulation deadlines. The EU Green Deal weights environmental product declarations in public infrastructure tenders. Industrial compounders around Lyon expand calcium sulfonate production to bypass lithium supply constraints.
Poland
Central European manufacturing investment creates demand for multi-purpose maintenance greases with extended relubrication intervals. CE marking requirements under the EU Machinery Directive delay new product launches by 12-18 months. The Silesian industrial corridor attracts German logistics companies consolidating fleet lubrication programs.
Italy
Construction equipment manufacturers face the steepest REACH compliance burden for sealing greases containing polycyclic aromatic hydrocarbons. EFSA frameworks govern food-grade aluminum complex formulations for processing machinery. Emilia-Romagna's agricultural machinery sector audits suppliers for reformulated rubber-compatible grades.
Spain
Automotive suppliers in Catalonia specify lithium complex grades for conventional drivetrains while monitoring polyurea displacement in EV motor bearings. The EU F-Gas Regulation phases down fluorinated grease formulations before R&D amortization completes. Basque Country industrial clusters prioritize biodegradable alternatives for marine equipment serving North Atlantic routes.
Europe Grease Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European grease supply chain. The market structure concentrates around integrated petrochemical majors, specialized lubricant compounders, and regional blending operations serving price-sensitive maintenance segments. German R&D-intensive specialists and integrated oil majors represent distinct strategic archetypes with divergent margin profiles. Competitive moves center on backward integration into base oil refining and portfolio substitution toward bio-based thickeners.
Among Germany-based lubricant specialists, FUCHS and Kluber Lubrication exemplify the premium formulation archetype, while Royal Dutch Shell occupies a position spanning integrated feedstock control to finished grease distribution. These three companies represent contrasting approaches to REACH compliance investments, with specialists absorbing reformulation costs through technical service premiums and majors leveraging scale economies across European refining networks.
| Leading Market Players |
|---|
| FUCHS |
| Royal Dutch Shell |
| Lukoil |
| Lubrita |
| Axel Christiernsson International AB |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Kluber Lubrication |
| Chevron Corporation |
| Others |
Supply & Pricing Matrix
Sixty-day lithium hydroxide inventory buffers at German compounders now separate formulation premiums from spot-feedstock volatility, concentrating pricing power with integrated refiners while forcing independent blenders into cost-pass-through contracts. This lead-time asymmetry rewards backward integration into base oil production and penalizes reliance on Rotterdam spot markets for Group II feedstock.
Pricing Analysis
Configured-to-order polyurea formulations for EV drivetrain bearings command 35-50% premiums over standard lithium complex grades, with thermal stability certification and ECHA compliance documentation as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels separates REACH-authorized biodegradable marine grades from commodity mineral-oil chassis greases. Cost compression in standard lithium complex tiers is intensifying because ECHA substitution mandates are accelerating thickener chemistry shifts before R&D amortization completes. Fleet operators in the Rhine-Ruhr corridor exhibit lowest price sensitivity due to technical service bundling, while Polish industrial maintenance buyers drive spot-market volatility.
Supply Chain Analysis
Rotterdam-Antwerp refining concentration controls 60% of European Group I and Group II base oil availability, exposing compounders to feedstock volatility when crude differentials widen. Manufacturing gravity centers on Germany, France, and the Netherlands, with thickener production drawing from Belgian lithium processing and Italian calcium sulfonate specialization. Single-source vulnerability runs through Russian-origin Group I feedstock substitution timelines under sanctions compliance. Distribution runs through integrated petrochemical majors with captive blending networks, regional compounders serving automotive OEMs directly, and maintenance distributors consolidating spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH-driven formulation fragmentation is creating specialist niches as ECHA chemical restrictions splinter demand across polyurea, calcium sulfonate, and bio-based thickener camps faster than integrated majors can consolidate portfolios.
For Market Incumbents: Secure lithium complex volume positions in Rhine-Ruhr fleet contracts before polyurea displacement accelerates in EV motor bearings. Backward integration into bio-based thickener production in France and Benelux captures EU Green Deal procurement premiums while insulating margins from REACH-driven reformulation cycles. For New Entrants and Emerging Players: Anchor in Polish industrial maintenance corridors where CE marking delays have created 12-18 month supply gaps for multi-purpose grades with technical service attachments. Target biodegradable marine formulations for Mediterranean port operators facing discharge regulation deadlines, leveraging Ecolabel certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors divesting non-core grease blending assets under portfolio rationalization pressures. Five-to-ten year viability favors specialists with captive bio-based thickener chemistry and ECHA pre-authorization dossiers. Monitor ECHA SVHC candidate list expansions as the inflection signal for accelerated lithium substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Thickeners | Captures EU Green Deal premiums while bypassing lithium supply constraints under ECHA frameworks. |
| REACH Pre-authorization Dossier Investment | Secures 10-year market access for calcium sulfonate and polyurea formulations ahead of competitor submissions. |
| Single-source Fleet Contract Consolidation | Rhine-Ruhr logistics operators now bundle technical service with volume commitments, displacing spot purchasing. |
| Biodegradable Marine Grade Ecolabel Certification | North Sea and Mediterranean discharge rules are pulling demand toward certified formulations with procurement preference. |
| Poland Industrial Corridor Distribution Buildout | Central European manufacturing investment creates demand for maintenance greases with extended relubrication intervals. |
Research Methodology
The analysis maps lithium complex, polyurea, calcium sulfonate, and bio-based thickener sub-sectors, each validated through formulation chemists at FUCHS and Kluber, procurement directors at German automotive OEMs, maintenance managers at Rhine-Ruhr logistics fleets, and marine equipment operators in Mediterranean ports. Secondary sources include ECHA restriction proposal databases, EU Green Deal procurement tender records, Cefic chemical production statistics, and SEC filings from integrated petrochemical majors. Bottom-up volume builds from end-use consumption models triangulate against top-down refinery output data.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include thickener chemistry, end-use industry, performance grade tier, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating EV drivetrain penetration rates, REACH compliance cost pass-through coefficients, and marine discharge regulation implementation timelines.
Decision-makers should treat outputs as directional under stable ECHA authorization timelines and lithium hydroxide supply continuity assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and bio-based thickener performance validation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Spain Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Textile Machine Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Malaysia Lubricants Market
Lubricants
Industrial Gear Oil Market
Lubricants
Open Gear Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Synthetic Lubricants and Functional Fluids Market
Lubricants
Anti-Static Oil Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Poland Automotive Engine Oils Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Saudi Arabia Automotive Engine Oils Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Singapore Commercial Vehicles Lubricants Market