
 Anti-Wear Additives Market | 2026-2036
Anti-Wear Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Wear Additives Market Analysis
Aftermarket service revenue from lubricant analysis and drain-interval optimization is rewriting margin capture across the value chain. BASF leverages its integrated phosphorus chemistry portfolio to supply ashless anti-wear precursors at scale. Lubrizol anchors North American demand through backward integration into alkylated diphenylamine intermediates. Afton Chemical specializes in zinc dialkyldithiophosphate formulations for heavy-duty diesel fleets.
Anti-wear additives are surface-active chemical compounds, typically organometallic or ashless phosphorus-sulfur complexes, that form protective tribofilms on ferrous and non-ferrous substrates under boundary lubrication regimes; zinc dialkyldithiophosphate remains the benchmark chemistry, though boron- and molybdenum-based alternatives are displacing legacy formulations in passenger car motor oils. Metallic additives still occupy the largest volume share in engine oils, while non-metallic variants represent the fastest-expanding category as OEMs pursue compatibility with exhaust aftertreatment systems. Industrial lubricants concentrate margin pools where extreme-pressure agents command specification premiums from mining and wind turbine operators.
EPA emission standards and the EU F-Gas Regulation shape lubricant formulation requirements by mandating lower SAPS levels that restrict traditional zinc and sulfur chemistries. China's MEE enforces dual carbon compliance timelines that push domestic blenders toward additive packages with reduced metallic ash content. Stakeholders must monitor regulatory divergence between sulfur-restricted European specifications and the API SP/ILSAC GF-6 framework in North America to anticipate reformulation cycles.
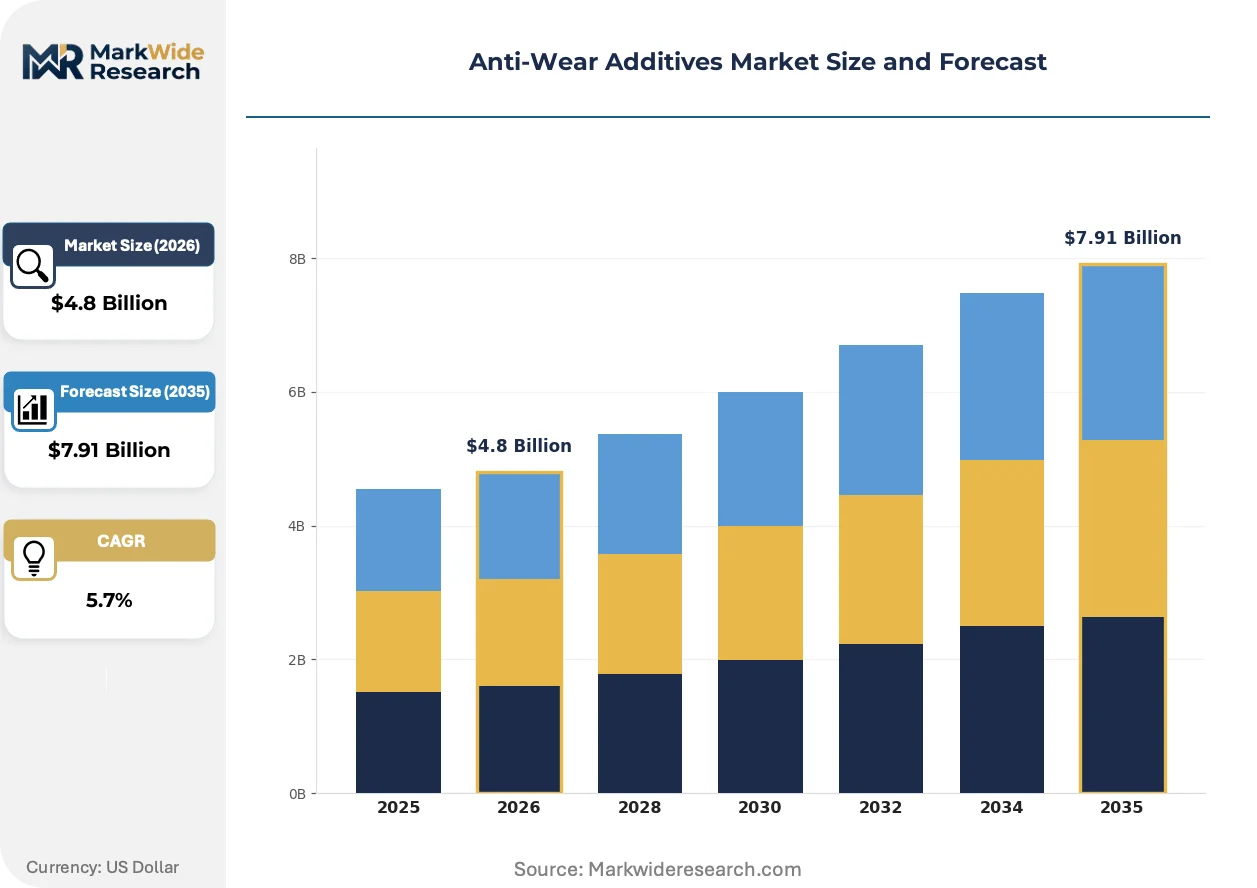
Market Dynamics
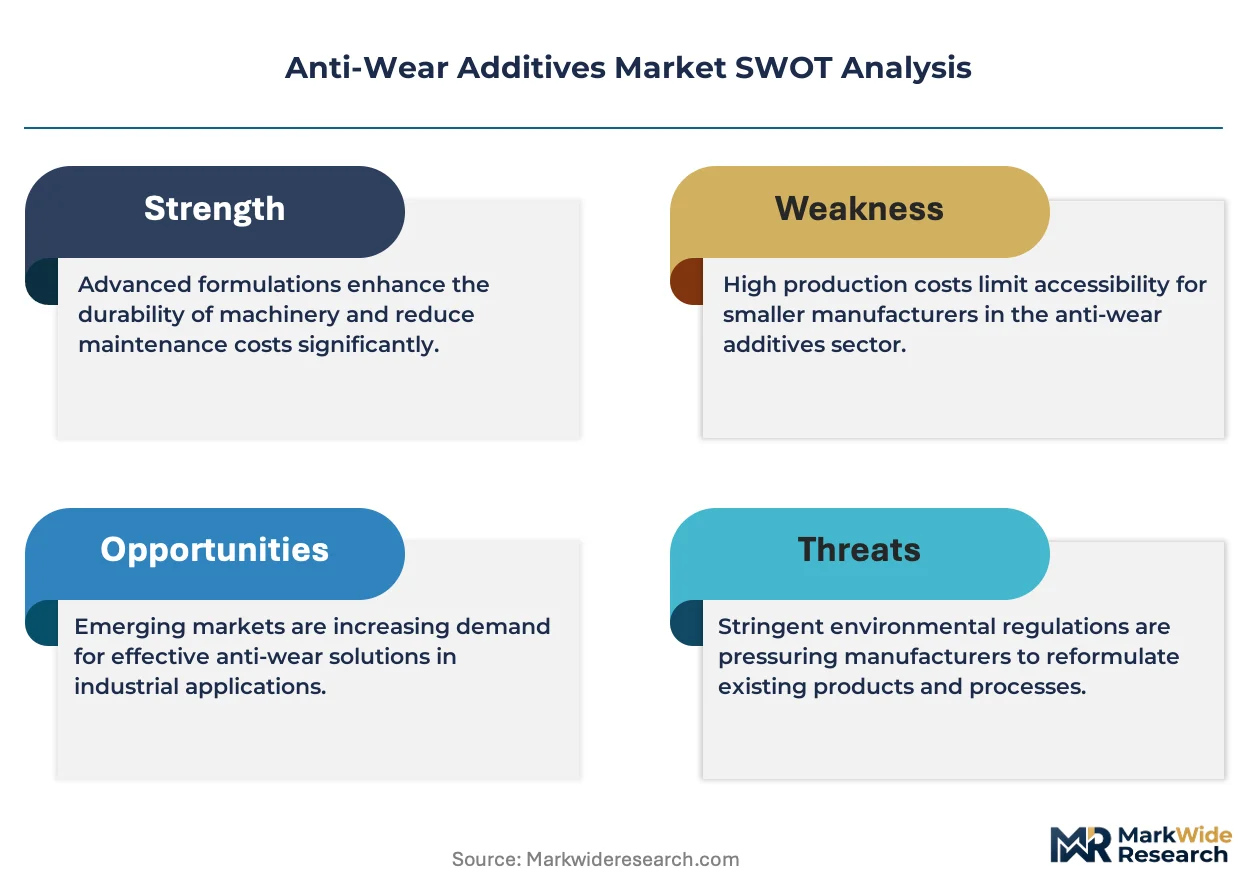
Formulation chemistry divergence between low-SAPS European specifications and higher-ash North American engine oil standards is fragmenting additive procurement strategies across multinational lubricant blenders.
Growth Catalysts
- Extended drain intervals:OEM specifications stretching oil change cycles to 15,000+ miles intensify demand for thermally stable ashless anti-wear chemistries in passenger car motor oils.
- China's dual carbon compliance:MEE enforcement timelines accelerate domestic refiner adoption of boron-free, reduced-metallic additive packages to meet 2030 carbon intensity targets.
- Exhaust aftertreatment protection:Diesel particulate filter and selective catalytic converter compatibility requirements pull formulators away from zinc dialkyldithiophosphate toward phosphorus-sulfur ashless alternatives.
Market Restraints
- Phosphorus supply concentration:Integrated phosphate rock-to-specialty chemical production clusters in Morocco and China create input vulnerability for Western additive manufacturers.
- REACH registration cost barriers:ECHA data requirements and substance evaluation timelines extend commercialization cycles for novel ashless molecules beyond 48 months.
- Base oil Group III+ substitution:Higher-quality hydrocracked stocks with intrinsically better boundary lubrication properties reduce additive treat rates in premium formulations.
Strategic Opportunities
- Wind turbine gearbox fluids:Extreme-pressure anti-wear specifications for 10+ MW offshore turbines open specification premiums beyond traditional industrial lubricant margins.
- India's BIS lubricant standards:Mandatory quality certification for automotive engine oils creates first-mover advantage for additive suppliers with pre-approved packages.
- Electrified powertrain thermal management:E-axle and reduction gear lubricants require novel anti-wear chemistries compatible with copper windings and electrical insulation materials.
Industry Challenges
- Tribochemistry modeling capability gaps:Limited industrial expertise in molecular dynamics simulation of tribofilm formation slows formulation optimization cycles.
- API SP/ILSAC GF-6 sequence test access:Proprietary engine test hardware and fuel supply constraints bottleneck certification timelines for new additive packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Wear Additives Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Additives, Non-Metallic Additives, Organic Additives, Inorganic Additives End Use Industry: Automotive, Aerospace, Marine, Heavy Machinery Application: Engine Oils, Gear Oils, Hydraulic Oils, Industrial Lubricants Additive Function: Friction Modifier, Extreme Pressure Agent, Viscosity Modifier, Detergent |
| Companies Covered | Afton Chemical, BASF, Lubrizol, Vanderbilt Chemicals, Croda, Infineum, Evonik, Tianhe Chemicals Group, Chevron Oronite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Wear Additives Market Emerging Trajectories
Anti-wear additive development is pivoting from performance maximization toward systems compatibility, driven by electrified powertrains and tightened emission controls.
Ionic liquid anti-wear additives based on phosphonium and ammonium chemistries deliver superior steel-steel friction reduction under mixed lubrication regimes. Formulators at European OEMs are screening these materials for 800V e-axle applications where electrical conductivity and copper corrosion resistance matter equally. Conventional zinc dialkyldithiophosphate is rendering obsolete for next-generation electrified drivelines due to conductivity and thermal stability limitations.
EPA's updated greenhouse gas standards for heavy-duty engines tighten particulate matter limits that cascade into lubricant SAPS restrictions. The agency's Phase 3 rule compresses allowable sulfated ash content, forcing additive suppliers to reformulate CK-4/FA-4 diesel engine oils with reduced zinc and calcium detergents. Fleets operating in California face additional CARB constraints that accelerate ashless chemistry adoption ahead of federal timelines.
Direct procurement of additive components by national oil companies is bypassing traditional lubricant blender intermediaries. Saudi Aramco and Chinese state refiners now negotiate directly with BASF and Lubrizol for base additive packages, compressing margin pools for independent blenders. This disintermediation is most advanced in China, where Sinopec and PetroChina captive additive manufacturing reduces import dependency for core anti-wear chemistries.
Anti-Wear Additives Market Segmentation
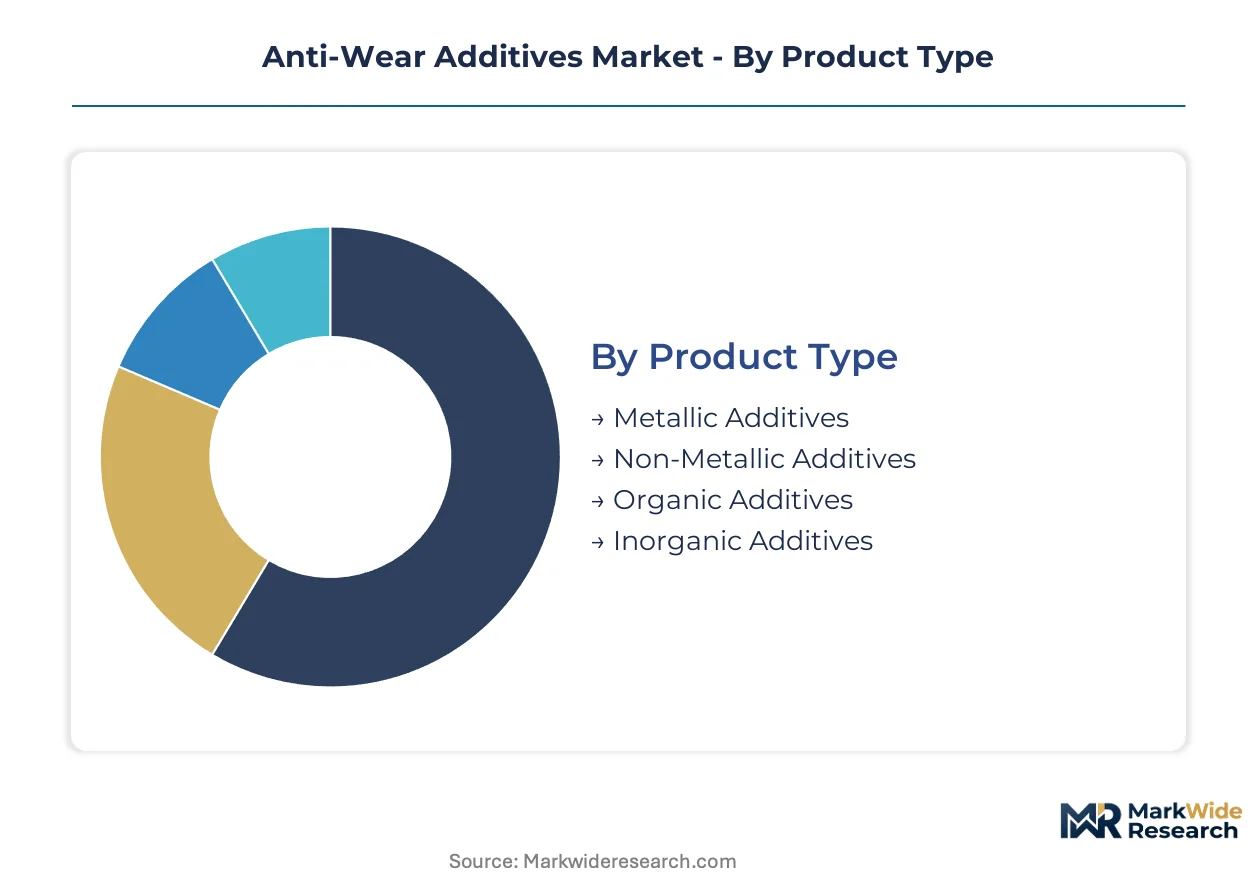
Anti-wear additive procurement diverges sharply across end-use specifications, with automotive OEMs demanding SAPS-compliant formulations while industrial buyers prioritize extreme-pressure performance. Understanding these segment boundaries clarifies where formulation investments concentrate and which chemistries face displacement risk.
Product Type:
Mature metallic chemistries dominate volume positions while emerging ashless alternatives capture specification premiums in aftertreatment-sensitive applications.
- Metallic Additives:Zinc dialkyldithiophosphate remains the benchmark organometallic chemistry, forming sacrificial tribofilms on ferrous surfaces. Demand concentrates in heavy-duty diesel fleets across North America where API CK-4 specifications still tolerate moderate sulfated ash levels; EPA Phase 3 greenhouse gas standards are tightening these limits and forcing gradual reformulation.
- Non-Metallic Additives:Ashless phosphorus-sulfur complexes and boron-free alternatives eliminate metallic ash content entirely. European OEMs in Germany and France specify these chemistries for passenger car motor oils under ACEA C-sequence low-SAPS standards; exhaust aftertreatment protection requirements pull formulators away from zinc-based solutions.
- Organic Additives:Ionic liquid formulations based on phosphonium chemistries deliver friction reduction under mixed lubrication regimes.
- Inorganic Additives:Molybdenum disulfide and graphite suspensions serve niche high-temperature applications.
Metallic Additives retains volume leadership; Non-Metallic Additives holds the steepest expansion curve.
End Use Industry:
Application maturity spreads from established automotive specifications to emerging electrified powertrain requirements.
- Automotive:Passenger car motor oils and heavy-duty diesel formulations represent the dominant demand channel. OEM specifications stretching drain intervals to 15,000+ miles intensify demand for thermally stable chemistries; China's MEE dual carbon compliance timelines accelerate domestic refiner adoption of reduced-metallic additive packages.
- Aerospace:Synthetic ester-based lubricants for turbine engines require anti-wear additives with exceptional thermal stability above 200°C. Demand concentrates in US and French military procurement specifications; FAA airworthiness directives constrain formulation changes and extend certification cycles.
- Marine:Cylinder oils for two-stroke engines face IMO 2020 sulfur cap implications.
- Heavy Machinery:Mining and construction equipment lubricants prioritize extreme-pressure protection over thermal longevity.
Automotive commands absolute volume; Aerospace maintains the highest specification premiums per kilogram.
Application:
Volume concentration follows engine oil specifications while margin pools concentrate in industrial lubricant specialties.
- Engine Oils:Passenger car motor oils and diesel engine formulations absorb the majority of anti-wear additive production. API SP and ILSAC GF-6 sequences in the United States, ACEA standards in Europe, and China's GB specifications create fragmented certification requirements; proprietary engine test hardware bottlenecks constrain new additive package commercialization.
- Industrial Lubricants:Hydraulic fluids and compressor oils for wind turbine gearboxes command specification premiums beyond traditional margins. Offshore turbine operators in Denmark and the United Kingdom demand 10+ MW extreme-pressure formulations; REACH registration timelines extend novel molecule commercialization beyond 48 months.
- Gear Oils:Hypoid axle lubricants require extreme-pressure agents for boundary lubrication conditions.
- Hydraulic Oils:Anti-wear additives protect pumps and valves in construction and agricultural equipment.
Engine Oils retains volume leadership; Industrial Lubricants holds the steepest expansion curve.
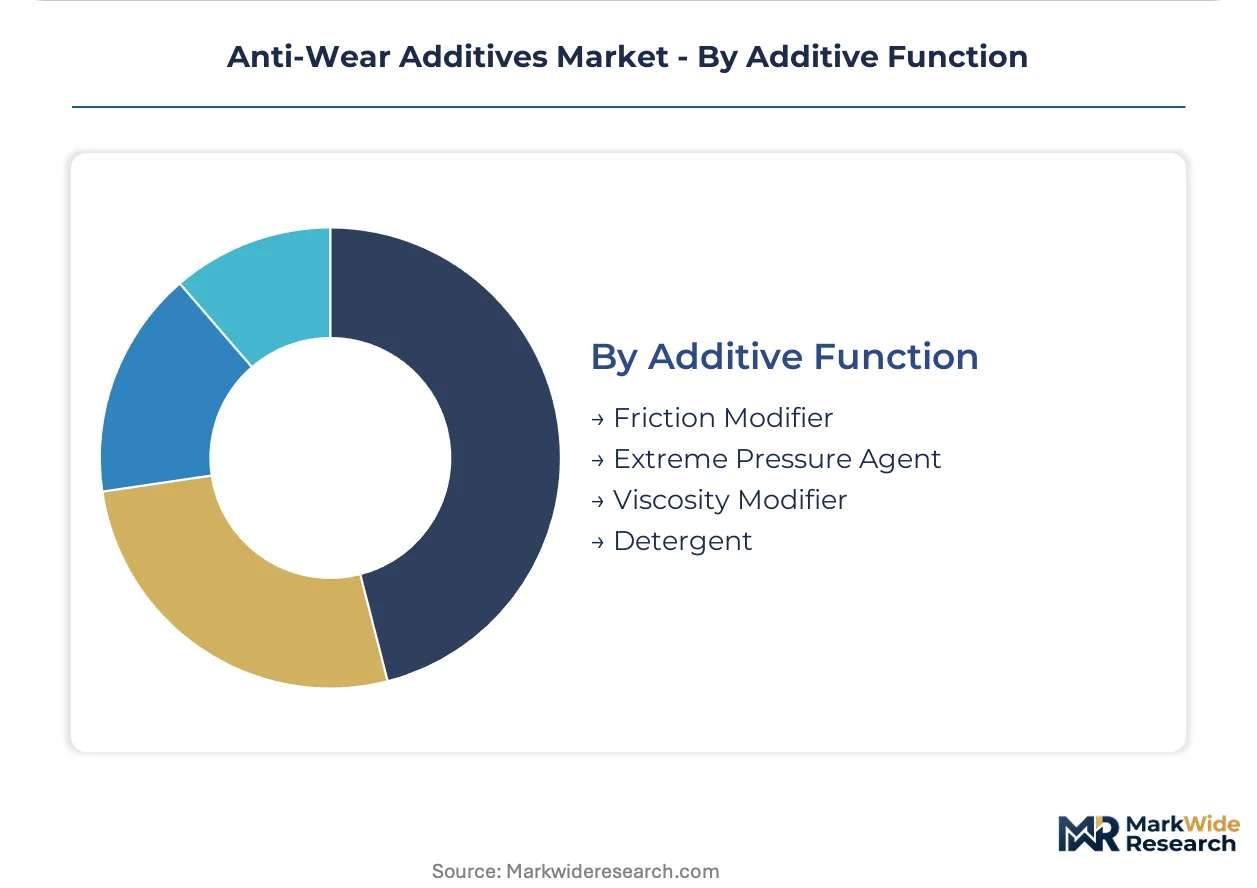
Additive Function:
Function specialization separates commodity friction reduction from premium extreme-pressure protection.
- Extreme Pressure Agent:Sulfurized olefins and phosphate esters form protective films under high-load boundary conditions. Mining operators in Australia and Chile specify these chemistries for open-gear applications; sulfur content restrictions in European specifications limit formulation flexibility.
- Friction Modifier:Organic molybdenum compounds and fatty acid esters reduce energy losses in mixed lubrication regimes. Japanese OEMs in Toyota and Honda specifications prioritize these additives for fuel economy certification; METI energy efficiency standards reinforce adoption.
- Viscosity Modifier:Polymeric additives extend operational temperature ranges.
- Detergent:Metallic soaps neutralize acidic combustion byproducts.
Extreme Pressure Agent retains volume leadership; Friction Modifier holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: China and India prioritize cost-optimized metallic formulations for fleet markets, while Germany and the United States specify premium ashless chemistries for aftertreatment compatibility and extended drain intervals.
China
Sinopec and PetroChina captive additive manufacturing reduces import dependency for core anti-wear chemistries. MEE dual carbon compliance timelines accelerate domestic refiner adoption of boron-free, reduced-metallic additive packages to meet 2030 carbon intensity targets. Yangtze River Delta lubricant blenders expand production capacity for ACEA-equivalent low-SAPS formulations.
United States
Heavy-duty diesel fleets across Texas and the Midwest sustain demand for API CK-4 formulations with moderate sulfated ash levels. EPA Phase 3 greenhouse gas standards tighten particulate matter limits that cascade into lubricant SAPS restrictions, forcing gradual reformulation toward ashless alternatives. Gulf Coast petrochemical corridors anchor integrated phosphate rock-to-specialty chemical production for Western additive manufacturers.
Germany
ACEA C-sequence low-SAPS standards mandate ashless phosphorus-sulfur complexes for passenger car motor oils. ECHA REACH registration requirements extend commercialization cycles for novel ashless molecules beyond 48 months. Rhineland chemical clusters concentrate formulation R&D for next-generation electrified powertrain lubricants.
India
BIS mandatory quality certification for automotive engine oils creates first-mover advantage for additive suppliers with pre-approved packages. Domestic lubricant blenders in Maharashtra and Gujarat expand captive additive sourcing to reduce import costs. Commercial vehicle operators in Tamil Nadu specify extended drain interval formulations to minimize fleet downtime.
Japan
METI energy efficiency standards reinforce adoption of organic molybdenum friction modifiers for fuel economy certification. Toyota and Honda specifications prioritize these additives in passenger car motor oils. Kanto region lubricant formulators develop ionic liquid anti-wear additives for 800V e-axle applications where electrical conductivity and copper corrosion resistance matter equally.
Anti-Wear Additives Market Vendor Landscape
Capability concentration sits with integrated phosphorus chemistry specialists; scale advantage sits with diversified petrochemical conglomerates. The vendor base stratifies across three tiers: global additive package suppliers with backward integration into alkylated intermediates, regional blenders with captive manufacturing, and specialty chemical houses focused on niche ionic liquid formulations. Dominant competitive moves include direct procurement negotiations between national oil companies and additive suppliers, plus capacity expansion in China to serve domestic refiner demand.
Within the integrated chemistry tier, BASF leverages its phosphorus portfolio to supply ashless precursors, while Lubrizol anchors North American demand through in-house production of alkylated diphenylamine intermediates. Afton Chemical occupies a position specializing in zinc dialkyldithiophosphate formulations for heavy-duty diesel fleets. Among Asia-Pacific-based suppliers, Tianhe Chemicals Group represents the captive manufacturing archetype serving domestic Chinese refiners.
| Leading Market Players |
|---|
| Afton Chemical |
| BASF |
| Lubrizol |
| Vanderbilt Chemicals |
| Croda |
| Infineum |
| Evonik |
| Tianhe Chemicals Group |
| Chevron Oronite |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta additive manufacturing clusters concentrate captive production capacity for Sinopec and PetroChina, compressing margin pools for Western suppliers and amplifying pricing power asymmetries between integrated phosphorus chemistry specialists and independent blenders.
Pricing Analysis
Long-term offtake contracts dominate procurement between national oil companies and integrated additive suppliers, though spot purchases persist for specialty ashless formulations. Price differentiation rests on REACH registration status and ACEA C-sequence certification tier, with unregistered molecules trading at substantial discounts. Cost compression in metallic additive tiers is intensifying because Chinese captive manufacturing reduces import dependency. Fleet operators in heavy-duty diesel segments exhibit highest price sensitivity; European OEMs specifying low-SAPS formulations show lowest sensitivity due to aftertreatment protection requirements.
Supply Chain Analysis
Contract manufacturing concentration sits with Tianhe Chemicals Group and domestic Chinese refiners holding captive capacity, while BASF and Lubrizol retain integrated phosphate rock-to-specialty chemical production. Raw material dependencies center on phosphate rock from Morocco and China, alkylated diphenylamine intermediates, and sulfur-based extreme-pressure agents. Single-source vulnerability concentrates in phosphorus supply chains where Moroccan OCP and Chinese producers control upstream mining. Distribution runs through lubricant blender intermediaries in North America and Europe, though direct procurement by Saudi Aramco and Chinese state refiners is disintermediating traditional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct procurement negotiations between national oil companies and additive suppliers, fragmenting traditional blender intermediaries and compressing margin capture across the value chain.
For Market Incumbents: Entrench phosphorus chemistry integration through backward control over alkylated diphenylamine intermediates and ashless precursor manufacturing. Expand REACH-registered molecule portfolios to defend against Chinese captive manufacturing substitution. Prioritize certification investment in API SP/ILSAC GF-6 sequence tests to bottleneck competitor commercialization timelines. For New Entrants and Emerging Players: Pursue electrified powertrain thermal management applications where ionic liquid formulations for 800V e-axle systems face limited incumbent penetration. Target India's BIS pre-approved package segment before mandatory quality certification hardens competitive barriers. Lead with copper corrosion resistance and electrical conductivity specifications as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated phosphorus chemistry specialists with REACH-registered ashless portfolios over metallic additive pure-plays facing regulatory displacement. Long-term viability hinges on electrified driveline compatibility and dual carbon compliance chemistry development. Watch API SP/ILSAC GF-6 sequence test access constraints as inflection indicator for formulation bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Intermediates | BASF's captive alkylated diphenylamine production secures supply continuity against Moroccan phosphate concentration. |
| REACH Registration Investment | ECHA compliance timelines exceeding 48 months create moats for early-registered ashless molecule suppliers. |
| Electrified Powertrain Formulation Development | Toyota and Honda specifications for 800V e-axle ionic liquids open premium positioning beyond engine oils. |
| Direct National Oil Company Procurement | Saudi Aramco and Sinopec negotiations compress independent blender margins and reshape channel economics. |
| Wind Turbine Gearbox Fluid Certification | Denmark and United Kingdom offshore turbine operators pay specification premiums for 10+ MW extreme-pressure formulations. |
Methodological Framework
Initial hypotheses were tested against primary input from lubricant formulators at OEMs and independent blenders, additive R&D directors, procurement leads at national oil companies, and aftermarket service managers, then refined against secondary validation from ECHA REACH registration databases, API licensing documentation, customs trade data for phosphorus chemical flows, and SEC filings from integrated chemical conglomerates. Bottom-up segmentation modeling triangulated with top-down market sizing across metallic, non-metallic, organic, and inorganic additive categories.
Demand-supply-balance framing anchored volume projections across the analysis window, with segmentation dimensions spanning product chemistry type, end-use industry, application specification, and regional regulatory cluster. CAGRs were derived from regression analysis of historical additive treat rate trends and forward projection of OEM drain interval specifications. Industry-specific forecast inputs incorporated EPA Phase 3 SAPS restriction timelines and China's MEE dual carbon compliance enforcement trajectories.
Sensitivities concentrate around REACH registration timeline extensions, phosphorus supply disruptions from Moroccan or Chinese production clusters, and accelerated Group III+ base oil substitution reducing additive treat rates. Forecasts reflect documented assumptions on regulatory enforcement consistency and OEM specification adoption curves. Quarterly review of API sequence test backlog durations and ECHA substance evaluation prioritization lists is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Glass Additives Market
Additives
Tocopheryl Acetate Market
Additives
Silage Additives Market
Additives
Canada Water Enhancer Market
Additives
Dishwashing Additives Market
Additives
Feed Additives Market
Additives
Global Sodium Acetate Market
Additives
Ultraviolet Light Stabilizer Market
Additives
Packaging Coating Additives Market
Additives
Amino Acids Premixes Market
Additives
Global Slip Additives Market
Additives
North America Paints and Coatings Additives Market
Additives
Refining Additives Market
Additives
Metallic Stearate Market
Additives
Impact Modifier Market
Additives
Nucleating and Clarifying Agents Market