
 Global Low Emission Vehicle Market | 2026-2036
Global Low Emission Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Emission Vehicle Market Intelligence
A shift from early-adopter private consumers to large-scale procurement by fleet operators and government agencies is recalibrating sales channel strategies. Tesla Inc. leverages its direct-to-consumer model and Supercharger network to maintain brand loyalty. Volkswagen AG competes on a multi-brand platform strategy to cover diverse market segments. Meanwhile, BYD Auto Co., Ltd. dominates through its deep in-house production of batteries and powertrain components.
Low emission vehicles encompass a range of automobiles designed to produce substantially fewer harmful pollutants than conventional internal combustion engine vehicles. This includes vehicles with tailpipe emissions below a specific threshold, often defined by grams of CO2 per kilometer. While battery electric vehicles represent the fastest-growing vehicle type, plug-in hybrids provide a transitional solution for markets with underdeveloped charging infrastructure. Within powertrain technology, the efficiency of the electric motor and the energy density of the fuel cell stack are key differentiators.
Regulatory mandates such as the EU's Corporate Sustainability Reporting Directive (CSRD) and China's dual carbon goals are compelling fleet upgrades. In the United States, EPA emissions standards directly influence automaker production plans and technology investment. Stakeholder success will depend on navigating the divergent pace of charging infrastructure deployment and grid capacity upgrades across key national markets.
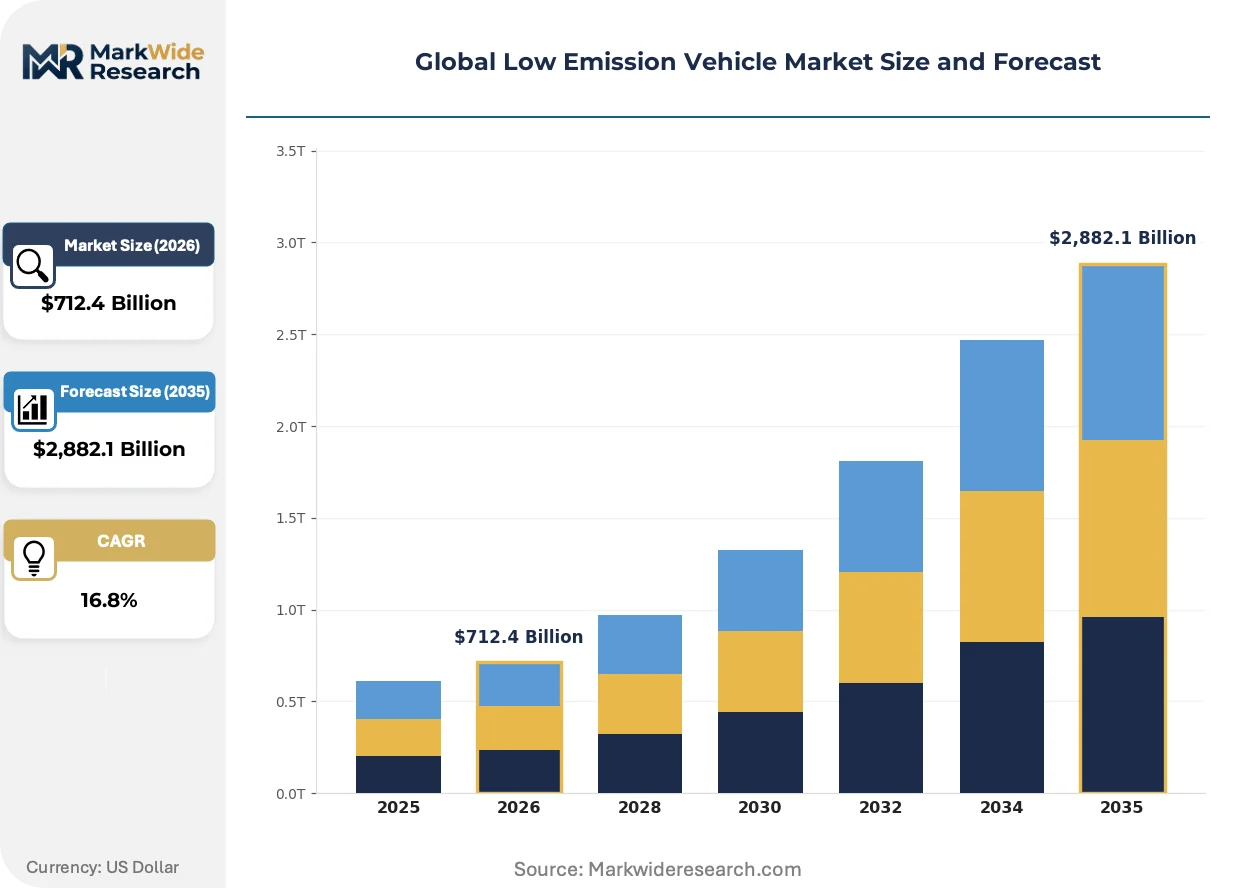
Market Dynamics
The market's central dynamic is the growing divergence between high-performance electric vehicle platforms in developed economies and the proliferation of low-cost models in China, a split driven by battery supply chain control and disparate national subsidy policies.
Growth Catalysts
- Corporate Fleet Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) compels large corporations to decarbonize vehicle fleets, creating predictable, large-volume demand for low emission commercial vans and cars.
- Battery Chemistry Advances:The shift towards lithium iron phosphate (LFP) batteries for standard-range vehicles lowers costs and improves safety, expanding market access for price-sensitive buyers in markets like India and Southeast Asia.
- Public Charging Expansion:Government-supported initiatives in countries like Germany and South Korea are accelerating the build-out of public fast-charging networks, reducing range anxiety for BEV owners.
Market Restraints
- Critical Mineral Volatility:Price fluctuations and supply concentration for key battery minerals like lithium and cobalt, largely processed in China, create significant cost uncertainty for automakers outside the country.
- Grid Capacity Limitations:Inadequate local grid infrastructure and slow approval processes for substation upgrades in many urban areas across the US and Europe constrain the rollout of large-scale fleet charging depots.
- Divergent Charging Standards:The persistence of multiple, incompatible fast-charging standards such as CCS, CHAdeMO, and NACS complicates hardware development and creates consumer confusion, slowing infrastructure investment.
Strategic Opportunities
- Emerging Market Entry:Markets like Brazil and Mexico, with growing urban populations and nascent policy support, offer significant growth potential for manufacturers of smaller, more affordable electric vehicles and plug-in hybrids.
- Vehicle-to-Grid Services:The development of bidirectional charging technology creates new revenue streams for fleet operators by enabling them to sell stored energy back to the grid during peak demand periods.
- Electric Light Commercial Vehicles:The last-mile delivery segment is rapidly electrifying, presenting a major opportunity for specialized platforms optimized for urban logistics, payload capacity, and total cost of ownership.
Industry Challenges
- Software Engineering Scarcity:Automakers face a critical shortage of skilled software engineers needed to develop advanced driver-assistance systems (ADAS), battery management software, and connected vehicle services.
- Semiconductor Sourcing Complexity:Securing long-term supply agreements for automotive-grade semiconductors remains a significant operational hurdle, leading to production delays and forcing costly vehicle redesigns.
- After-Sales Service Transition:Building a qualified technician network capable of servicing high-voltage battery systems presents a major training and investment challenge for legacy dealership networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Emission Vehicle Market |
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $2,882.1 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric, Plug-in Hybrid, Fuel Cell, Hybrid Electric, Compressed Natural Gas Powertrain Technology: Electric Motor, Internal Combustion Engine, Series Hybrid, Parallel Hybrid, Fuel Cell Stack End User: Private Consumers, Fleet Operators, Government Agencies, Delivery Services, Car Rental Companies Charging Infrastructure: Fast Charging, Level 2 Charging, Wireless Charging, Destination Charging, Battery Swapping |
| Companies Covered | Tesla Inc, Volkswagen AG, Toyota Motor Corporation, Hyundai Motor Company, BYD Auto Co., Ltd., AB Volvo, BMW AG, Honda Motor Co., Ltd., Mercedes-Benz Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Emission Vehicle Market Strategic Shifts & Innovations
The market's innovation axis is shifting from standalone vehicle performance to the integration of energy, software, and mobility services. This transition prioritizes the total ecosystem experience over isolated hardware specifications.
Solid-state battery technology promises a step-change in energy density and safety. High-performance vehicle manufacturers are the primary early adopters, funding pilot production lines. This next-generation chemistry is integrating battery cells directly into the vehicle's structural chassis, a concept known as cell-to-chassis, reducing weight and complexity.
Stringent new emissions standards from the United States Environmental Protection Agency (EPA) set tighter limits on tailpipe pollutants. These federal mandates compel automakers to accelerate their transition to zero-emission platforms to meet fleet-wide compliance targets and avoid penalties. The rules particularly affect pickup trucks and SUVs, forcing investment in electric powertrains for these high-margin categories.
A shift towards subscription-based models for electric vehicles is gaining traction among urban consumers. This model disrupts traditional ownership, replacing large upfront outlays with monthly payments bundling insurance and charging. The trend is most visible in European cities like Berlin and Paris, where vehicle-as-a-service platforms offer EV access.
Global Low Emission Vehicle Market Segmentation
The Global Low Emission Vehicle Market segmentation reveals diverse technological pathways and user adoption patterns shaping its expansion. Understanding these distinct categories provides clarity on regulatory compliance, infrastructure requirements, and consumer preferences impacting market dynamics.
Vehicle Type:
Regulatory bodies like the EPA and EU's CSRD impose emissions thresholds, influencing certification burden and market viability across vehicle types.
- Battery Electric:These vehicles operate solely on electric power from onboard battery packs. Demand concentrates in China due to strong government incentives and a mature domestic manufacturing base.
- Plug-in Hybrid:Combining an internal combustion engine with an electric motor and battery, these offer limited all-electric range. They serve as a transitional solution in markets like Mexico.
- Fuel Cell:These vehicles generate electricity from hydrogen and oxygen, emitting only water vapor. South Korea invests in hydrogen refueling infrastructure.
- Hybrid Electric:These vehicles combine a gasoline engine with an electric motor for improved fuel efficiency. They are popular in Brazil for lower upfront cost.
- Compressed Natural Gas:CNG vehicles run on natural gas, offering lower carbon emissions. Fleet operators in India utilize CNG for cost-effective logistics.
Battery Electric sits at the top of the volume ranking, with Plug-in Hybrid climbing the fastest.
Powertrain Technology:
The cost tier of powertrain components significantly impacts vehicle pricing, with advanced technologies commanding a premium due to specialized manufacturing.
- Electric Motor:This component converts electrical energy into mechanical energy, driving the wheels with high efficiency. Its development is central to BEV performance, influencing range.
- Fuel Cell Stack:Composed of multiple individual fuel cells, this stack electrochemically converts hydrogen into electricity. Energy density is a key differentiator for heavy-duty applications in Japan.
- Internal Combustion Engine:This traditional powertrain generates power by burning fuel, present in hybrid vehicles. European markets are phasing out new ICE sales.
- Series Hybrid:An electric motor always drives the wheels, with the ICE acting as a generator. This simplifies the transmission system.
- Parallel Hybrid:Both the electric motor and ICE can directly drive the wheels, independently or together. This offers flexibility for efficiency and performance.
The Electric Motor dominates current market share, while the Fuel Cell Stack represents a critical emerging technology for future heavy transport.
End User:
Application-specific demands dictate vehicle design and procurement, with end-users prioritizing factors like total cost of ownership or cargo capacity.
- Fleet Operators:Businesses managing large vehicle fleets for commercial purposes like logistics or ride-sharing. The EU's CSRD mandates compel decarbonization, creating predictable demand.
- Private Consumers:Individual buyers purchasing vehicles for personal use, influenced by range anxiety, purchase price, and brand loyalty. German incentives encourage private BEV ownership.
- Government Agencies:Public sector entities procuring vehicles for official duties. China's dual carbon goals drive significant government fleet upgrades.
- Delivery Services:Companies specializing in last-mile logistics require vehicles optimized for frequent stops and urban maneuverability. This segment is rapidly electrifying in European cities.
- Car Rental Companies:Businesses offering short-term vehicle rentals are increasingly adding low emission models. These companies face pressure to modernize fleets for sustainability targets.
Demand from Fleet Operators is driven by regulatory mandates, while Private Consumers show evolving preferences for subscription-based ownership models.
Charging Infrastructure:
The volume of charging points required to support widespread EV adoption presents significant challenges and opportunities for infrastructure developers and grid operators.
- Fast Charging:High-power charging stations (DC fast chargers) replenish a significant portion of a battery quickly. Government initiatives in Germany accelerate network build-out, reducing range anxiety.
- Level 2 Charging:These chargers use 240-volt AC power, balancing charging speed and accessibility for homes and workplaces. They form the backbone of everyday BEV charging in the United States.
- Wireless Charging:Technology allowing EVs to charge without physical cables through electromagnetic induction. Pilot projects explore its potential for public transport.
- Destination Charging:Chargers installed where vehicles are parked for extended periods, like hotels or shopping centers. These enhance convenience for long-distance travelers.
- Battery Swapping:A system where a depleted battery is quickly exchanged for a fully charged one, eliminating charging wait times. BYD Auto Co., Ltd. champions this method in China.
Investment in Fast Charging infrastructure remains a primary focus, while Battery Swapping holds significant future potential for specific use cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
A skilled engineering workforce in key automotive hubs across the globe drives low emission vehicle innovation. These regions attract significant investment in advanced manufacturing and battery technology. Government policies and consumer preferences further shape market development.
China
China's extensive manufacturing base and large consumer market drive significant demand for low emission vehicles. The government's dual carbon goals compel rapid adoption across both private and public fleets. Shenzhen, a major technology hub, pioneers electric bus manufacturing and battery swapping infrastructure.
United States
United States demand for low emission vehicles stems from corporate fleet decarbonization targets and consumer interest in advanced electric platforms. EPA emissions standards directly influence automaker production plans and technology investment. California's Silicon Valley cluster drives innovation in EV software and autonomous driving technologies.
Germany
Germany's market for low emission vehicles benefits from corporate fleet mandates and strong private consumer incentives. The EU's Corporate Sustainability Reporting Directive (CSRD) compels large corporations to decarbonize their vehicle fleets. Bavaria, a traditional automotive stronghold, focuses on premium electric vehicle manufacturing and battery research.
South Korea
South Korea exhibits strong demand for low emission vehicles, particularly with government support for a hydrogen economy. Government-supported initiatives accelerate the build-out of public fast-charging networks, reducing range anxiety. Ulsan, a key industrial city, leads in hydrogen fuel cell vehicle production and infrastructure development.
Brazil
Brazil's low emission vehicle market grows with its expanding urban populations and demand for affordable transitional solutions. Nascent policy support for plug-in hybrids provides initial market traction for manufacturers. São Paulo's automotive sector adapts production lines for efficient hybrid and flex-fuel vehicle models.
Global Low Emission Vehicle Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the low emission vehicle market, creating a complex competitive landscape. This market features global automotive giants employing multi-brand platform strategies to cover diverse market segments and consumer preferences. It also includes dedicated electric vehicle manufacturers and vertically integrated battery producers. Key competitive moves involve expanding in-house production capabilities, forming strategic alliances for charging infrastructure development, and investing in advanced software solutions.
EV pure-plays like Tesla Inc. exemplify a direct-to-consumer model, leveraging proprietary charging networks to build brand loyalty and control the customer experience. Volkswagen AG, a German-based automotive group, competes through a multi-brand platform strategy, allowing it to address various market segments and price points globally. Meanwhile, China-based BYD Auto Co., Ltd. dominates via its deep in-house production of batteries and powertrain components, offering a vertically integrated and cost-effective solution that underpins its market leadership.
| Leading Market Players |
|---|
| Tesla Inc |
| Volkswagen AG |
| Toyota Motor Corporation |
| Hyundai Motor Company |
| BYD Auto Co., Ltd. |
| AB Volvo |
| BMW AG |
| Honda Motor Co., Ltd. |
| Mercedes-Benz Group AG |
| Others |
Cost & Logistics Intelligence
Corporate fleet operators' large-volume procurement of low emission vehicles drives a dominant contract-based pricing model, emphasizing predictable total cost of ownership over upfront vehicle price. This structure allows for long-term agreements that often include maintenance and charging solutions.
Pricing Analysis
Bundled service packages, integrating charging and maintenance, contrast with unbundled vehicle sales in the low emission vehicle market. Price differentiation stems from brand premium for advanced platforms and the degree of in-house production of core components like batteries. Pricing pressure intensifies for standard-range battery electric vehicles due to falling lithium iron phosphate battery costs. Private consumers in emerging markets like India and Mexico exhibit the highest price sensitivity, favoring more affordable hybrid or entry-level electric models.
Supply Chain Analysis
Direct-to-consumer models, exemplified by Tesla Inc., coexist with multi-brand dealership networks and vertically integrated production by BYD Auto Co., Ltd. The supply chain draws heavily from China for critical mineral processing, including lithium and cobalt. Key component dependencies include semiconductors for advanced driver-assistance systems and high-voltage battery cells. Commodity price volatility for these critical minerals creates a structural risk for automakers outside China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with predictable, long-term growth driven by ongoing regulatory mandates such as the EU's CSRD and China's dual carbon goals.
For Market Incumbents: Deepen internal software engineering capabilities to reduce reliance on external suppliers for advanced driver-assistance systems and battery management software. Invest strategically in technician training programs to build a qualified after-sales service network for high-voltage battery systems, addressing a critical emerging threat. Explore backward integration into battery cell production to mitigate critical mineral supply chain volatility.
For New Entrants and Emerging Players: Begin with focused market entry into emerging economies like Brazil and Mexico, targeting the underpenetrated segment for affordable plug-in hybrids and smaller battery electric vehicles. Prioritize the electric light commercial vehicle segment, optimizing platforms for last-mile delivery logistics and total cost of ownership. Leverage subscription-based ownership models to attract urban consumers seeking lower upfront outlays.
For Investors and Strategic Acquirers: Original equipment manufacturers are the most active acquirer in this space, seeking to close technology gaps and secure supply. The market offers compelling long-term viability, underpinned by sustained regulatory pressure and rapid technological advancements. Target specialized software firms for battery management systems or advanced driver-assistance capabilities. The signal to watch is the pace of grid capacity upgrades in major urban centers across the United States and Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secure long-term lithium iron phosphate supplies to stabilize production costs for standard-range vehicles. |
| Software-Defined Vehicle Investment | Attract skilled software engineers to develop advanced driver-assistance systems and connected mobility services. |
| Charging Infrastructure Partnership | Accelerate public fast-charging network build-out, reducing range anxiety for battery electric vehicle owners. |
| Electric Light Commercial Vehicle Platform | Optimize vehicle design for last-mile delivery logistics, payload capacity, and urban maneuverability. |
| Solid-State Battery Pilot Production | Fund early pilot lines for next-generation chemistry, enhancing energy density and safety for high-performance models. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary data collection involved conversations with OEM platform engineers, fleet procurement managers, battery chemists, and charging network developers. Secondary sources included EPA emissions standards, EU CSRD reports, national energy agency data, and automotive industry association reports, ensuring a balanced bottom-up and top-down triangulation.
The segment-weighting approach informed the analytical framework across the analysis window, modeling market evolution by vehicle type, powertrain technology, end-user, charging infrastructure, and regional regulatory cluster. Compound annual growth rates were derived from historical trends, projected technological adoption, and anticipated future policy impacts. Key forecast inputs included battery cost trajectory and public charging expansion rates across national markets.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts affecting critical mineral supply and widespread grid capacity failures. Forecasts reflect assumptions regarding stable regulatory environments and continued technological progress within established parameters. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market