
 India CNG Market | 2026-2036
India CNG Market Size, Share, and Industry Trends Forecast 2026-2036
India CNG Market Outlook
BS-VI emission-grade fuel quality is rotating through the India CNG market as fleet operators and personal vehicle buyers upgrade from older compression specifications. Mahanagar Gas Limited leverages its Mumbai-Thane pipeline network to sustain volume leadership in western India. Gujarat Gas Ltd anchors its position through backward integration into gas sourcing and city gate infrastructure. Adani Total Gas Limited competes aggressively across newer geographic authorizations awarded by PNGRB.
Compressed natural gas consists of methane compressed to 200-250 bar for vehicular fuel storage, distributed through dedicated filling station networks designed to displace diesel and gasoline in high-mileage applications. The public transport application dominates current throughput volumes due to fleet conversion mandates and total cost of ownership advantages over conventional fuels. Bio-CNG technology leads growth trajectory within the technology dimension, as agricultural waste feedstock policies from the Ministry of New and Renewable Energy expand production incentives. CNG filling stations represent the highest-margin infrastructure segment, though compression units face capital intensity constraints in remote authorization areas.
PNGRB governs city gas distribution licensing and network rollout obligations, while BIS sets cylinder and dispensing equipment standards that manufacturers must satisfy for market access. The Ministry of Petroleum and Natural Gas coordinates with state nodal agencies to align CNG corridor development with national highway expansion plans. Stakeholders must monitor authorization round outcomes and pipeline interconnection timelines to anticipate regional supply availability shifts.
Market Dynamics
Fleet conversion mandates from the Petroleum and Natural Gas Regulatory Board are compressing diesel displacement timelines across state road transport corporations, while pipeline infrastructure density concentrates supply availability in western India.
Growth Catalysts
- PNGRB authorization rounds:New city gas distribution licenses are expanding CNG network coverage into tier-2 and tier-3 urban centers previously underserved by pipeline infrastructure.
- Bio-CNG feedstock incentives:Agricultural waste-to-fuel policies from the Ministry of New and Renewable Energy are diversifying domestic production away from conventional natural gas sourcing.
- State transport mandates:National Green Tribunal air quality directives are binding Delhi, Mumbai, and other metros to compressed natural gas conversion for public bus fleets.
Market Restraints
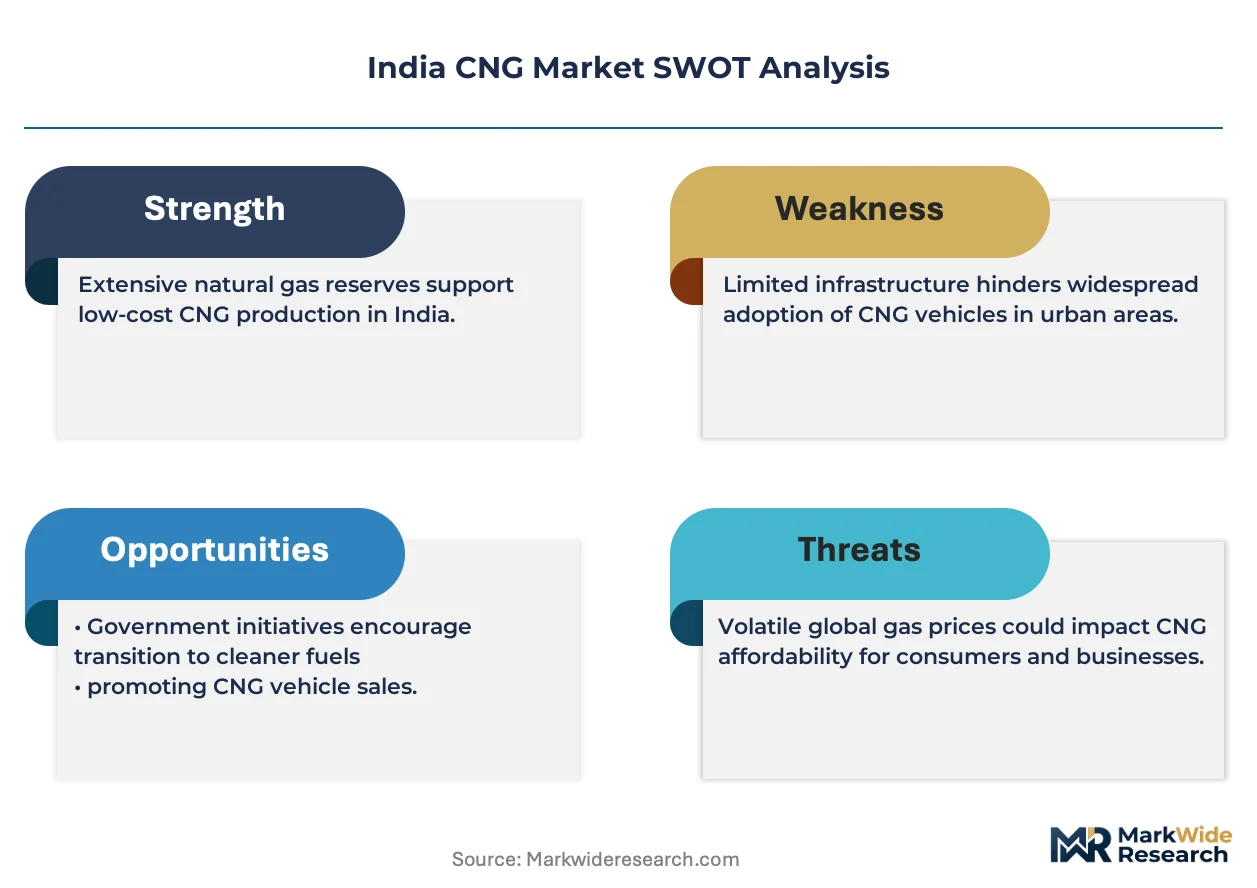
- Pipeline concentration risk:Maharashtra and Gujarat control the majority of operational city gas distribution networks, leaving northern and eastern states dependent on cylinder-based supply chains with higher delivered costs.
- Compression equipment capex:Remote authorization areas face prohibitive capital requirements for daughter booster stations and mobile refueling units.
- Electric vehicle substitution:Battery-electric bus procurement under FAME-II subsidies is diverting some fleet conversion budgets away from CNG in select urban corridors.
Strategic Opportunities
- Highway corridor development:Ministry of Petroleum and Natural Gas coordination with state nodal agencies is aligning CNG station deployment with national highway expansion along Delhi-Mumbai and Mumbai-Chennai freight routes.
- Industrial captive generation:Textile clusters in Surat and ceramic manufacturers in Morbi are piloting compressed natural gas for process heat applications beyond vehicular fuel.
- Blending infrastructure:Bio-CNG injection into existing city gas distribution networks enables renewable certificate stacking under MNRE frameworks.
Industry Challenges
- Skilled technician scarcity:High-pressure cylinder inspection and dispensing equipment maintenance require certified personnel that training institutes have not yet scaled to match network rollout velocity.
- BIS certification timelines:Cylinder and valve testing protocols create bottlenecks for fleet operators seeking to convert older vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India CNG Market |
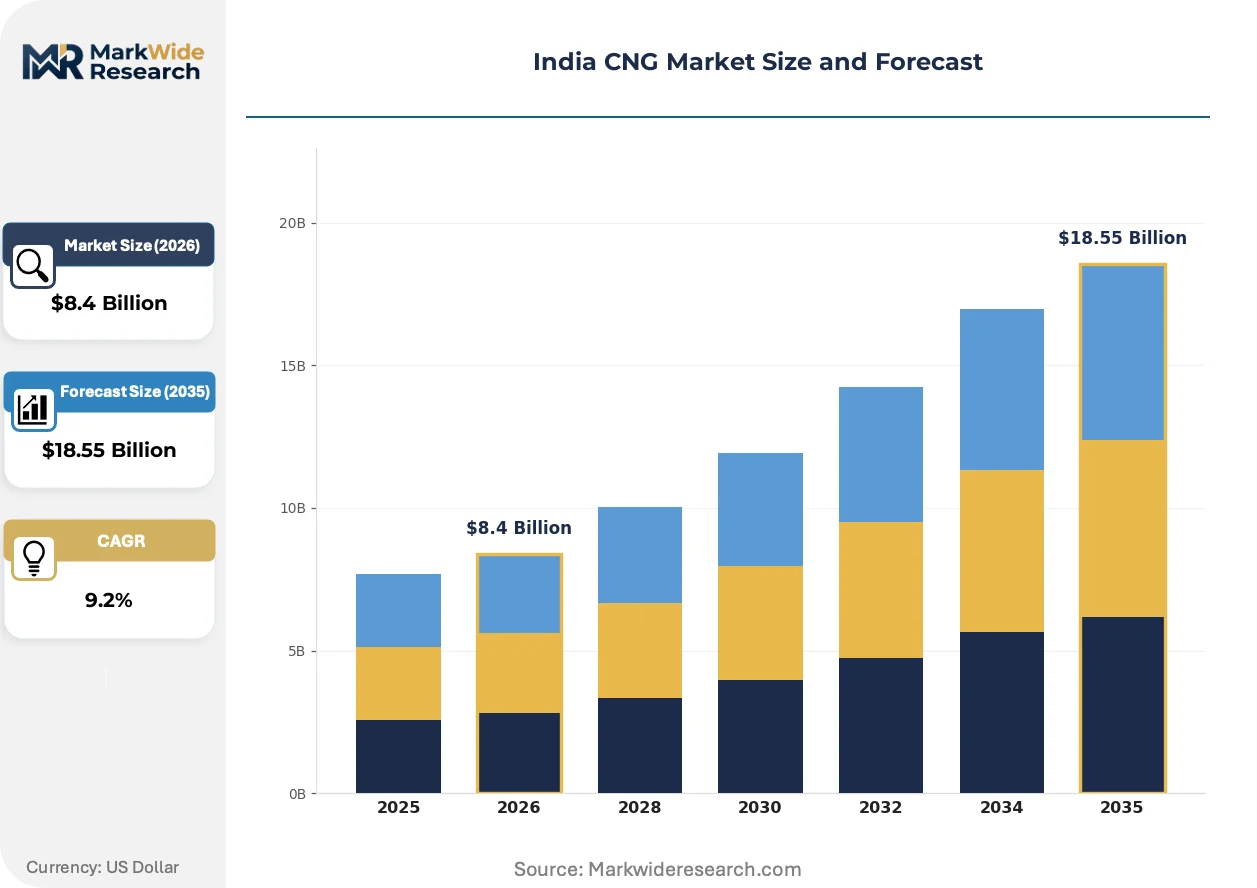
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $18.55 Billion |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Public Transport, Light-duty Vehicles, Industrial Applications, Personal Vehicles Technology: Compressed Natural Gas, Bio-CNG, LNG, Renewable Gas Infrastructure: CNG Filling Stations, Storage Facilities, Distribution Pipelines, Compression Units Customer Type: Government Fleets, Private Operators, Commercial Users, Residential Consumers |
| Companies Covered | Mahanagar Gas Limited, Gujarat Gas Ltd, Bharat Petroleum Corporation Limited, AG&P Pratham (AGP CGD India Private Limited), Gujarat State Petroleum Corporation Limited, Hindustan Petroleum Corporation Limited, Adani Total Gas Limited, Central U.P. Gas Limited, Indraprastha Gas Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India CNG Market Strategic Shifts
Bio-CNG production pathways are maturing from pilot demonstration to commercial scale, while regulatory pressure on particulate emissions intensifies the cost calculus favoring methane over liquid hydrocarbons in heavy transport.
Distributed biomethanation plants using agricultural residue and municipal organic waste are supplanting centralized natural gas compression for fleet operators in Punjab and Haryana. State road transport corporations in Chandigarh and Lucknow are contracting directly with these facilities to secure long-term supply agreements. The shift is compressing the delivered cost spread between conventional CNG and bio-CNG to under ten percent in some procurement zones.
The Ministry of New and Renewable Energy's Sustainable Alternative Towards Affordable Transportation scheme is binding bio-CNG plant approvals to compressed biogas injection into city gas distribution networks. This regulatory architecture is forcing project developers to co-locate production facilities with existing pipeline infrastructure rather than standalone dispensing operations. Fleet operators in Gujarat are responding by negotiating offtake guarantees that span the full project finance tenor.
Long-term fuel supply agreements are displacing spot purchasing for state transport undertakings with fleet sizes exceeding five hundred vehicles. Maharashtra State Road Transport Corporation and Gujarat State Road Transport Corporation have moved to ten-year contracts with price escalation clauses tied to domestic natural gas administered pricing mechanisms. This procurement compression is most visible in western India, where pipeline density enables volume commitments that justify dedicated compression capacity at mother stations.
India CNG Market Segmentation
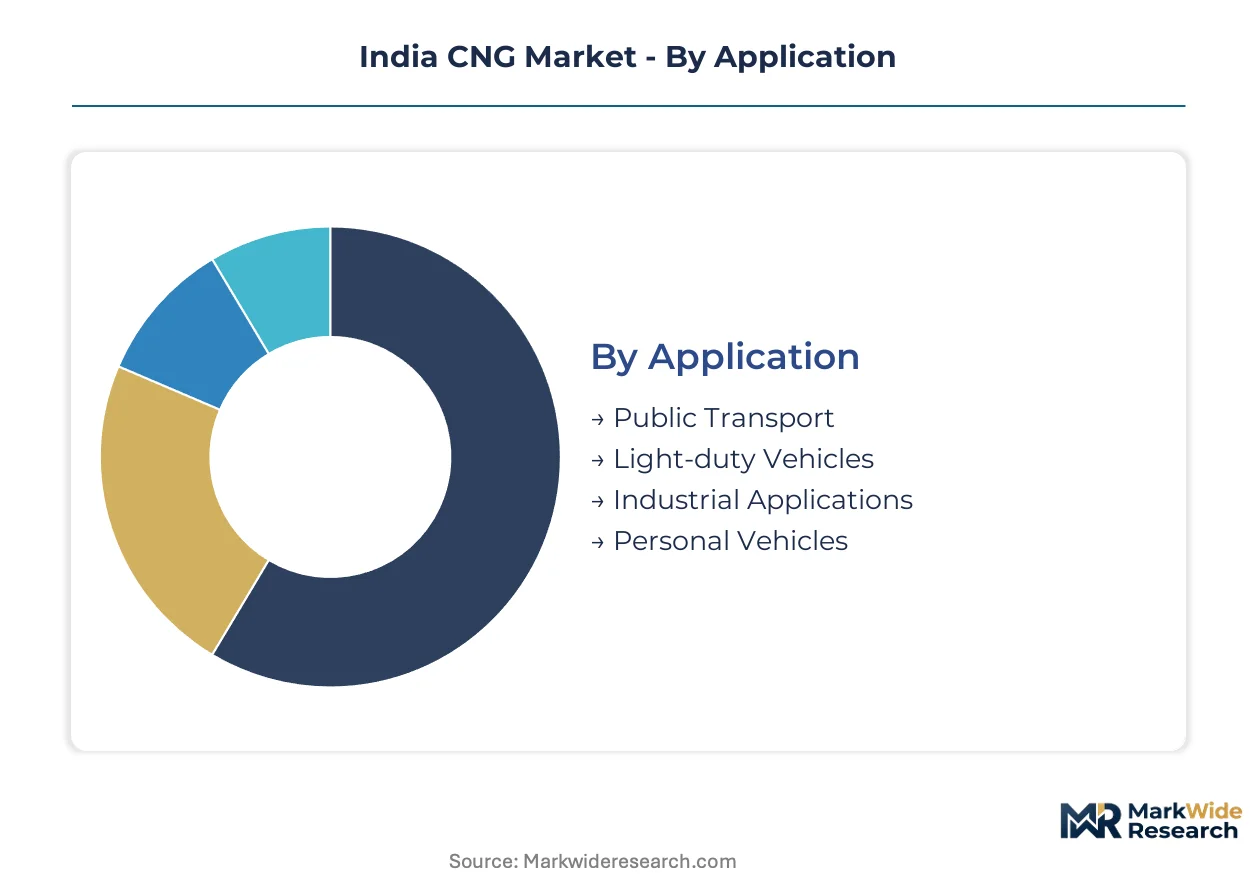
CNG market segmentation reveals how infrastructure constraints and policy mandates concentrate value across distinct customer and technology tiers. Understanding these divides clarifies where capital deployment yields compressed natural gas throughput versus where regulatory pressure overrides pure economics.
Application:
Domestic demand concentrates heavily in public transport corridors, while light-duty and personal vehicle segments expand through city gas distribution network reach.
- Public Transport:State road transport corporations in Delhi and Mumbai operate compressed natural gas bus fleets under National Green Tribunal mandates. Maharashtra State Road Transport Corporation and Gujarat State Road Transport Corporation anchor procurement volume through ten-year supply contracts tied to domestic natural gas administered pricing mechanisms.
- Light-duty Vehicles:Three-wheeler auto-rickshaws and light commercial vehicles in Ahmedabad and Pune convert from gasoline to CNG where mother station density supports fleet refueling economics. Total cost of ownership advantages compress payback periods to under eighteen months for high-mileage operators.
- Industrial Applications:Textile clusters in Surat and ceramic manufacturers in Morbi pilot process heat applications.
- Personal Vehicles:Factory-fitted CNG variants from Maruti Suzuki and Hyundai Motor India expand in Mumbai-Thane and Delhi-NCR markets.
Public transport holds the largest share; momentum sits with light-duty vehicles as city gas distribution networks penetrate tier-2 urban centers.
Technology:
Cost tiers separate mature compression infrastructure from emerging bio-CNG pathways requiring agricultural feedstock aggregation.
- Compressed Natural Gas:Pipeline-delivered methane compressed to 200-250 bar dominates throughput volumes across western India. Mahanagar Gas Limited and Gujarat Gas Limited sustain volume leadership through backward integration into gas sourcing and city gate infrastructure.
- Bio-CNG:Agricultural residue and municipal organic waste feedstocks diversify domestic production away from conventional natural gas sourcing in Punjab and Haryana. The Ministry of New and Renewable Energy's SATAT scheme binds plant approvals to city gas distribution network injection, forcing co-location with existing pipeline infrastructure.
- LNG:Liquefied natural gas serves long-haul trucking corridors where pipeline density remains insufficient.
- Renewable Gas:Hydrogen blending pilots and synthetic methane demonstrations remain pre-commercial.
Compressed natural gas holds the largest share; bio-CNG is climbing the fastest as feedstock policies compress delivered cost spreads to under ten percent in procurement zones.
Infrastructure:
Margin concentration varies sharply between high-throughput mother stations and capital-intensive remote compression units.
- CNG Filling Stations:Mother stations with direct pipeline connectivity generate the highest margins in the infrastructure stack. PNGRB authorization rounds expand network coverage into tier-2 and tier-3 urban centers previously underserved.
- Compression Units:Daughter booster stations and mobile refueling units face prohibitive capital requirements in remote authorization areas of northern and eastern states.
- Storage Facilities:High-pressure cylinder cascades buffer demand surges at high-throughput locations.
- Distribution Pipelines:City gas distribution networks concentrate in Maharashtra and Gujarat, leaving other states dependent on cylinder-based supply chains.
CNG filling stations hold the largest share; momentum sits with compression units as remote authorizations proceed.
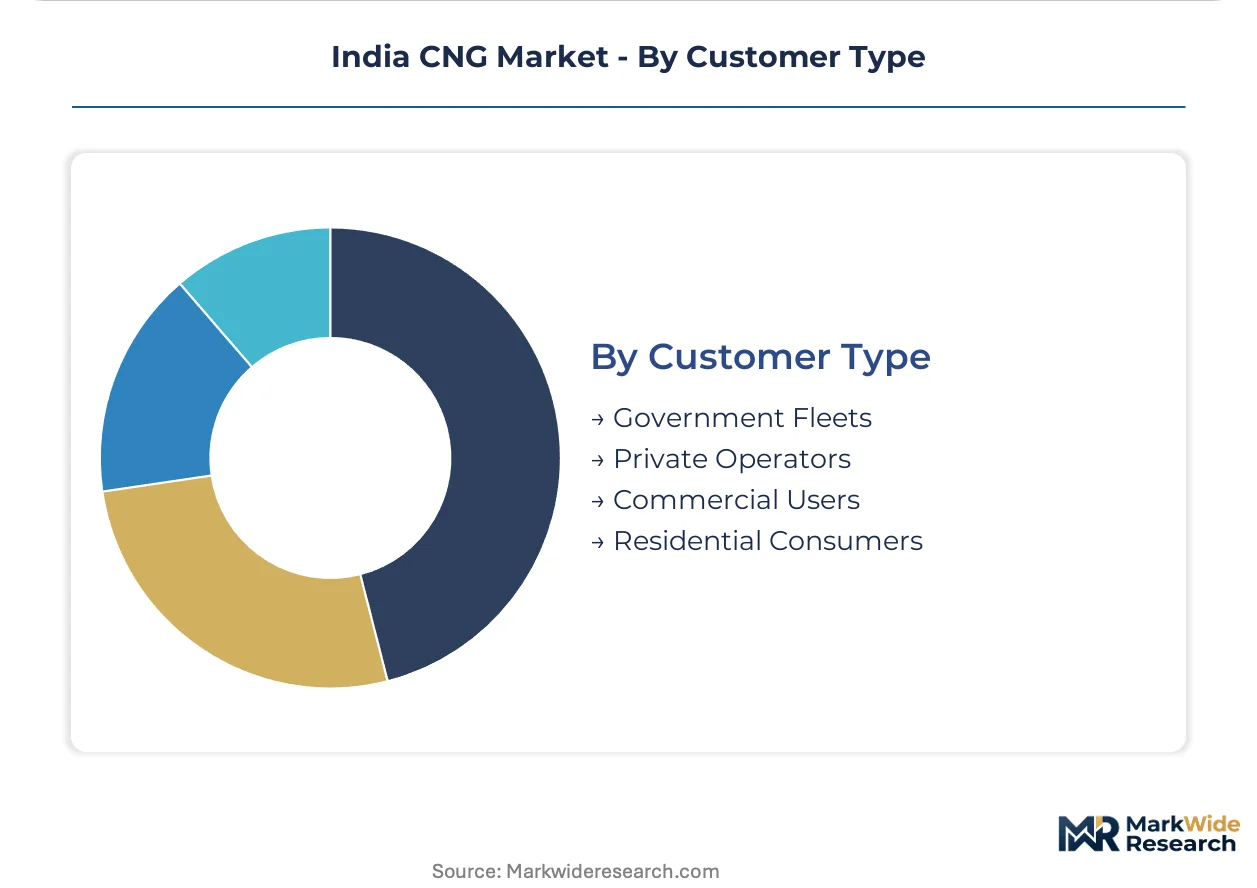
Customer Type:
Procurement patterns diverge between mandated government fleet conversion and price-sensitive private operator spot purchasing.
- Government Fleets:Delhi Transport Corporation and Brihanmumbai Electric Supply and Transport undertake bulk conversions under binding air quality directives. Long-term fuel supply agreements displace spot purchasing for fleet sizes exceeding five hundred vehicles.
- Private Operators:Fleet owners in logistics and intercity bus services negotiate offtake guarantees spanning full project finance tenors for bio-CNG supply security.
- Commercial Users:Three-wheeler aggregators and taxi fleet operators in Bengaluru and Hyderabad optimize refueling around mother station locations.
- Residential Consumers:Piped natural gas households represent latent CNG vehicle demand as dual-fuel factory options expand.
Government fleets hold the largest share; commercial users are gaining share fastest as aggregator platforms consolidate vehicle ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline infrastructure density concentrates CNG supply availability in western India, while northern and eastern states remain dependent on higher-cost cylinder-based distribution chains. State-level mandates from the National Green Tribunal and Petroleum and Natural Gas Regulatory Board authorization rounds are redrawing regional throughput patterns.
Maharashtra
Mumbai and Thane anchor mother station throughput volumes through Mahanagar Gas Limited's pipeline network. PNGRB licensing obligations bind the operator to network expansion into tier-2 urban centers. State Road Transport Corporation fleets in Pune and Nashik convert under binding air quality directives.
Gujarat
Surat textile clusters and Morbi ceramic manufacturers pilot process heat applications beyond vehicular fuel. Gujarat Gas Ltd leverages backward integration into gas sourcing and city gate infrastructure. Bio-CNG plants in Anand and Vadodara districts inject into city gas distribution networks under MNRE SATAT scheme requirements.
Delhi-NCR
Indraprastha Gas Limited operates the densest mother station network among Indian metros. National Green Tribunal orders mandate compressed natural gas conversion for Delhi Transport Corporation bus fleets. Daughter booster stations in Ghaziabad and Faridabad buffer demand surges during peak refueling windows.
Haryana
Agricultural residue feedstocks from paddy straw power distributed biomethanation plants in Karnal and Panipat. State road transport corporations in Chandigarh contract directly with these facilities for long-term supply security. Compression units face skilled technician scarcity as network rollout velocity outpaces training institute output.
Karnataka
Bengaluru three-wheeler aggregators optimize refueling around mother station locations in the tech corridor. PNGRB authorization rounds expand coverage into Mysuru and Hubli-Dharwad. Commercial fleet operators negotiate offtake guarantees spanning full project finance tenors for supply certainty.
India CNG Market Competitive Environment
Concentration sits with integrated city gas distribution operators controlling pipeline infrastructure and mother station networks. The market structure tiers between established western India incumbents with backward integration advantages and newer entrants building position through PNGRB geographic authorizations. Three archetypes dominate: pipeline-integrated gas distributors, petroleum marketing companies diversifying into compressed natural gas retail, and specialized city gas distribution licensees in emerging authorization areas. Competitive moves center on PNGRB bidding rounds for geographic expansion and long-term supply contracting with state transport undertakings.
Among pipeline-integrated operators, Mahanagar Gas Limited and Gujarat Gas Ltd exemplify the incumbent archetype with established city gate infrastructure and mother station density. Adani Total Gas Limited occupies a position representing aggressive geographic diversification through newer PNGRB authorizations. These three anchors illustrate how competitive positioning stratifies between infrastructure-hardened western India concentration and authorization-driven expansion into underserved markets.
| Leading Market Players |
|---|
| Mahanagar Gas Limited |
| Gujarat Gas Ltd |
| Bharat Petroleum Corporation Limited |
| AG&P Pratham (AGP CGD India Private Limited) |
| Gujarat State Petroleum Corporation Limited |
| Hindustan Petroleum Corporation Limited |
| Adani Total Gas Limited |
| Central U.P. Gas Limited |
| Indraprastha Gas Limited |
| Others |
Value Chain & Pricing Dynamics
BIS certification standards for high-pressure cylinders and dispensing equipment gate both supplier qualification and price differentiation simultaneously, compressing fleet conversion timelines for operators unable to clear testing protocols while enabling certified incumbents to command reliability premiums.
Pricing Analysis
PNGRB authorization rounds dictate the pricing tier structure across the India CNG market, separating pipeline-connected mother stations from remote daughter booster operations. Three-tier pricing stratifies across premium pipeline-direct supply, standard city gas distribution network access, and economy cylinder-based delivery for northern and eastern states. Cost compression in the economy tier intensifies as agricultural waste-to-fuel policies from MNRE diversify domestic bio-CNG production. State road transport corporations with fleet sizes exceeding five hundred vehicles demonstrate lowest price sensitivity through ten-year supply contracts, while three-wheeler aggregators in tier-2 urban centers exhibit highest sensitivity to per-kilogram delivered costs.
Supply Chain Analysis
India and Qatar anchor natural gas sourcing for the domestic CNG market, with pipeline infrastructure concentrated in Maharashtra and Gujarat and LNG imports feeding compression capacity elsewhere. Compression equipment draws from German and Japanese manufacturers for high-pressure units, while domestic fabrication supplies storage cascades and dispensing infrastructure. Single-source vulnerability sits with specialized cylinder valve components subject to BIS certification bottlenecks. Distribution runs through city gas distribution networks in western states and cylinder-based logistics chains in underserved authorization areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service layers including cylinder inspection, valve recertification, and dispensing equipment maintenance are expanding faster than compression hardware sales as network rollout velocity outpaces skilled technician supply.
For Market Incumbents: Secure long-term bio-CNG offtake agreements with agricultural waste aggregators in Punjab and Haryana before feedstock competition intensifies. Anchor position through backward integration into city gate infrastructure for tier-2 authorization areas awarded in recent PNGRB rounds. Battery-electric bus procurement under FAME-II subsidies threatens fleet conversion budgets in select urban corridors; defend throughput by locking state transport undertakings into price-escalation contracts tied to administered natural gas pricing mechanisms. For New Entrants and Emerging Players: Lead with distributed biomethanation plant development in agricultural residue-rich districts of Uttar Pradesh and Madhya Pradesh, targeting direct supply contracts with state road transport corporations bypassing city gas distribution network injection requirements. The most penetrable segment sits with light-duty three-wheeler fleet operators in tier-2 urban centers where mother station density remains insufficient and mobile refueling units can capture first-mover economics. Pursue asset-light compression partnerships with existing petroleum retail networks to accelerate station deployment without capital-intensive greenfield infrastructure. For Investors and Strategic Acquirers: Carve-out targets emerge from petroleum marketing companies diversifying into compressed natural gas retail where CNG operations represent non-core revenue streams requiring dedicated infrastructure investment. Long-term viability frames around bio-CNG integration capacity and pipeline interconnection timelines rather than standalone compression asset positions. Watch PNGRB authorization round outcomes as inflection indicators for regional supply availability shifts and corresponding margin compression or expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-CNG Plant Development | MNRE SATAT scheme bindings force co-location with city gas distribution networks, securing renewable certificate stacking. |
| Long-term Supply Contracting | Maharashtra and Gujarat State Road Transport Corporations anchor procurement volume through ten-year agreements with price escalation clauses. |
| Highway Corridor Station Deployment | Ministry of Petroleum and Natural Gas coordination aligns CNG infrastructure with Delhi-Mumbai and Mumbai-Chennai freight expansion. |
| Skilled Technician Training Scale-up | PNGRB authorization velocity outpaces certified personnel supply, creating bottleneck for cylinder inspection and dispensing maintenance. |
| Industrial Process Heat Piloting | Surat textile clusters and Morbi ceramic manufacturers test compressed natural gas applications beyond vehicular fuel demand. |
Study Parameters
Initial hypotheses were tested against primary input from city gas distribution operations managers, state transport corporation procurement heads, bio-CNG plant developers, and PNGRB regulatory officials and refined through secondary validation against Petroleum and Natural Gas Regulatory Board authorization round documentation, Ministry of New and Renewable Energy SATAT scheme filings, BIS cylinder and valve standards, and city gas distribution network rollout disclosures. Bottom-up fleet conversion modeling triangulated against top-down natural gas allocation data from the Ministry of Petroleum and Natural Gas.
Variance decomposition across the projection horizon isolates volume drivers by application segment, technology pathway, infrastructure type, and customer archetype. Segmentation dimensions modeled include public transport, light-duty vehicles, industrial applications, and personal vehicles crossed with compressed natural gas, bio-CNG, and LNG technology tiers. CAGRs were derived from infrastructure deployment schedules tied to PNGRB authorization obligations and pipeline interconnection timelines. Industry-specific forecast inputs incorporate administered natural gas pricing mechanism adjustments and MNRE feedstock incentive trajectories.
Forecasts assume regulatory continuity in PNGRB licensing frameworks and MNRE bio-CNG production incentives; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated battery-electric bus procurement diverting fleet conversion capital, BIS certification timeline extensions delaying cylinder fleet deployment, and pipeline infrastructure construction delays in northern and eastern authorization areas. Recalibration cycles align with material shifts in PNGRB authorization round outcomes and national highway corridor development milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Zero Emission Trucks Market