
 China Zero Emission Vehicle Market | 2026-2036
China Zero Emission Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
China Zero Emission Vehicle Market Insights
Chinese battery cell manufacturers is repositioning capacity toward LFP and solid-state chemistries to secure cost advantages in mass-market electric mobility. BYD Company Ltd leverages vertical integration across battery and semiconductor production to control input costs. NIO Inc. sustains premium positioning through battery-swapping infrastructure and direct-to-user service models. XPeng Motors differentiates via advanced driver-assistance systems and software-defined vehicle architecture.
Zero emission vehicles rely on electric drivetrains that eliminate tailpipe emissions through battery-electric or hydrogen fuel cell propulsion, with energy densities now exceeding 180 Wh/kg in mainstream LFP packs for passenger applications. Battery Electric Vehicles dominate unit sales and absorb the majority of cell production capacity, while Hydrogen Fuel Cell Vehicles command premium positioning in heavy-duty commercial segments where payload range requirements exceed 500 kilometers. Commercial Fleets represent the fastest-growing end-user category as logistics operators face tightening municipal emission zones in Beijing, Shanghai, and Shenzhen.
MIIT enforces GB standards for new energy vehicle safety and energy consumption, while MEE implements dual carbon goals that mandate provincial emission reductions and expand carbon trading coverage to automotive manufacturing. SAMR oversees market access certification and anti-monopoly compliance as state-backed consolidation reshapes the competitive field. Stakeholders must monitor how provincial subsidy tapering and charging infrastructure adequacy in third-tier cities will influence replacement-cycle timing for conventional fleet assets.
Market Dynamics
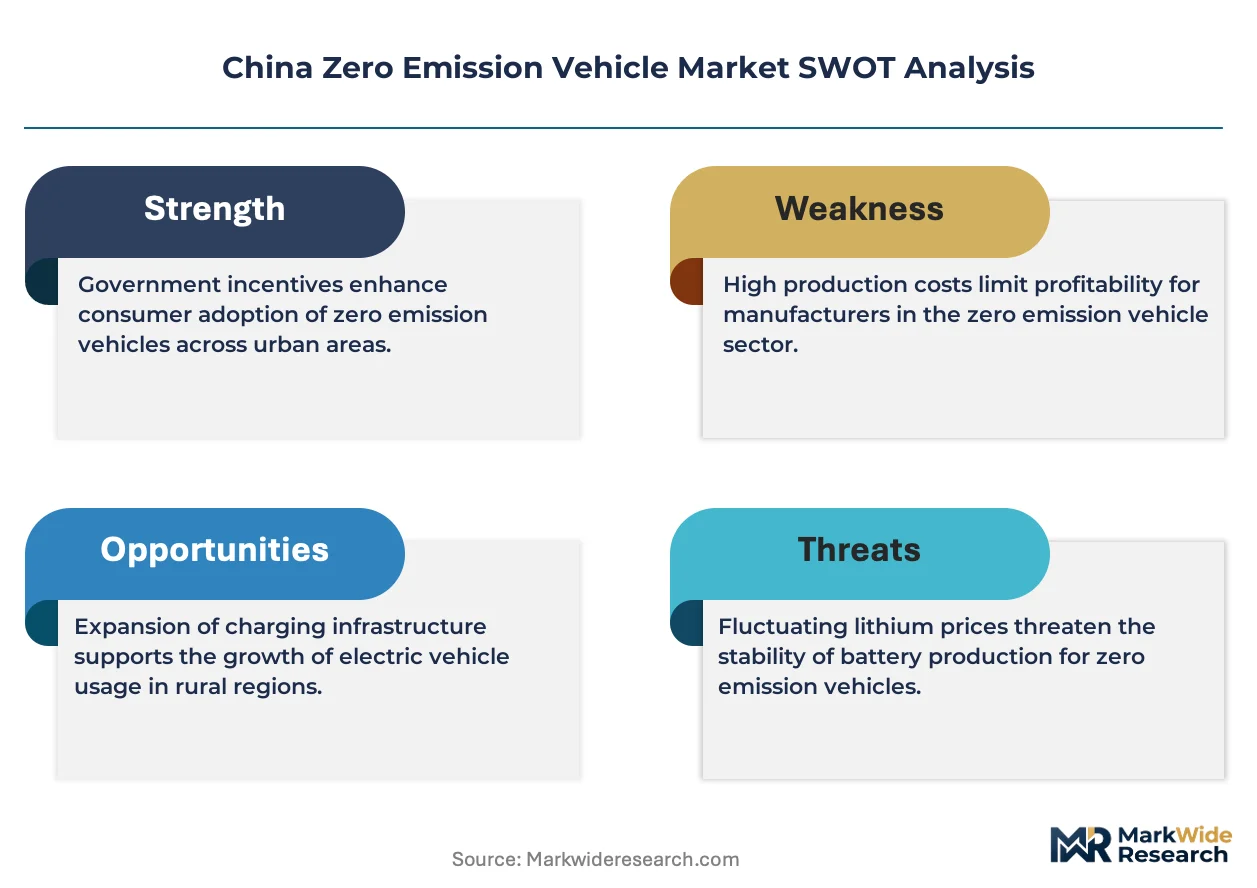
China's zero emission vehicle market operates under the structural pressure of MIIT's tightening GB standards for energy consumption and safety, which force manufacturers to accelerate LFP and solid-state battery transitions while provincial dual carbon mandates compress fleet replacement timelines.
Growth Catalysts
- MIIT NEV Mandates:Binding production quotas for new energy vehicles compel domestic automakers to scale battery-electric and hydrogen fuel cell output, tightening emission benchmarks nationwide.
- Yangtze River Delta Cluster:Concentrated manufacturing and consumption in Shanghai, Suzhou, and Hangzhou generates supplier density advantages and shortens component logistics loops.
- Hydrogen Fuel Cell Buses:Municipal fleet operators in Shenzhen and Beijing deploy fuel cell buses for routes exceeding 500 kilometers, creating anchor demand for heavy-duty commercial segments.
Market Restraints
- Lithium Carbonate Volatility:Raw material price swings for battery-grade lithium carbonate compress cell manufacturer margins and destabilize long-term supply contracts.
- Cathode Concentration Risk:Over-reliance on a narrow supplier base for high-nickel cathode active materials exposes the supply chain to single-source disruption.
- Charging Infrastructure Gaps:Third-tier cities lack adequate DC fast-charging density, constraining consumer confidence and fleet operator range planning.
Strategic Opportunities
- Battery Swapping Networks:Station-based battery exchange systems address apartment-dweller charging constraints and enable commercial fleet rapid turnaround in dense urban corridors.
- Western China Expansion:Underpenetrated markets in Chengdu-Chongqing and Xi'an corridors offer first-mover positioning as provincial subsidy programs extend beyond coastal provinces.
- Solid-State Convergence:Integration of sulfide electrolytes with silicon-anode architectures promises energy density breakthroughs for premium passenger segments.
Industry Challenges
- Power Electronics Talent Scarcity:Shortages of SiC inverter design engineers and BMS firmware specialists delay platform development cycles.
- GB Standard Certification Lag:Extended homologation timelines for revised safety and energy consumption protocols postpone model launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Zero Emission Vehicle Market |
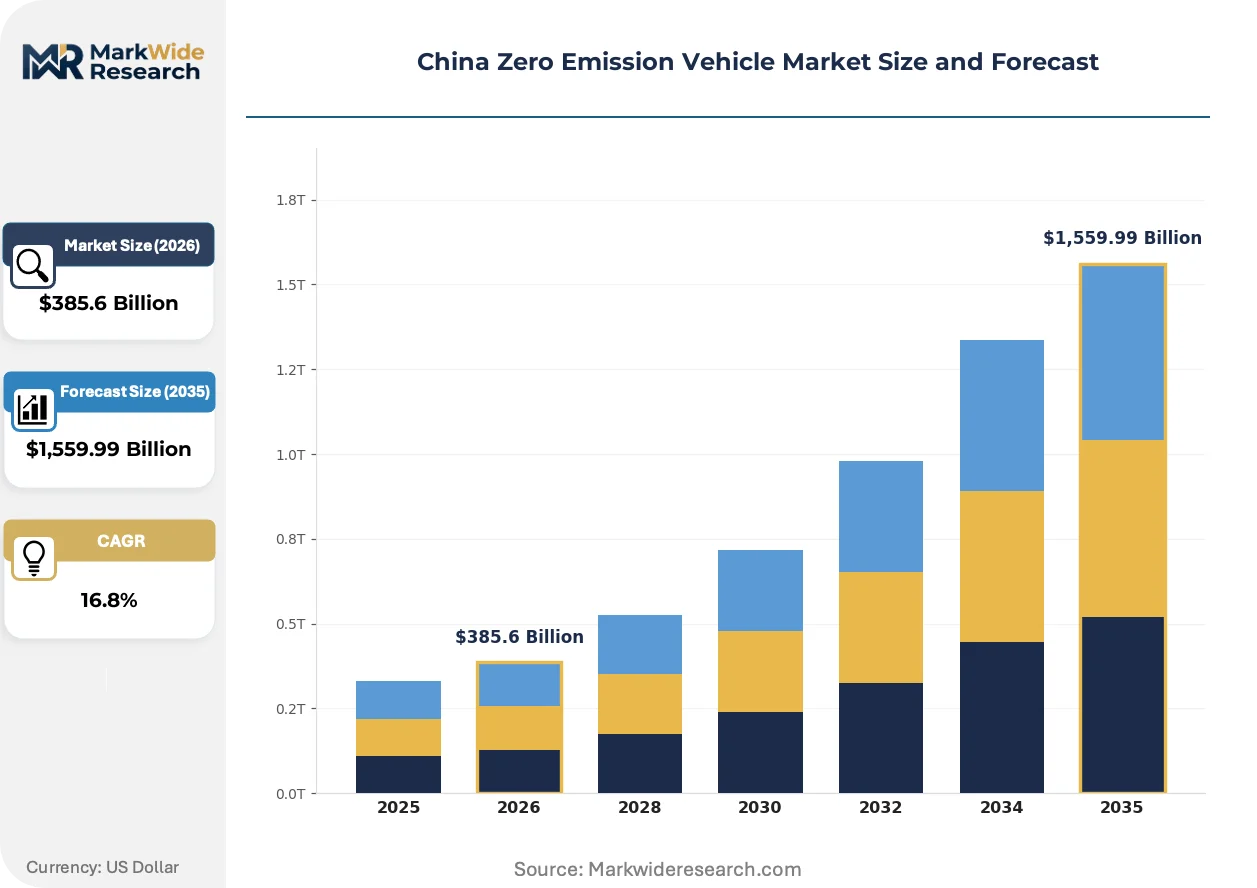
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $1,559.99 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
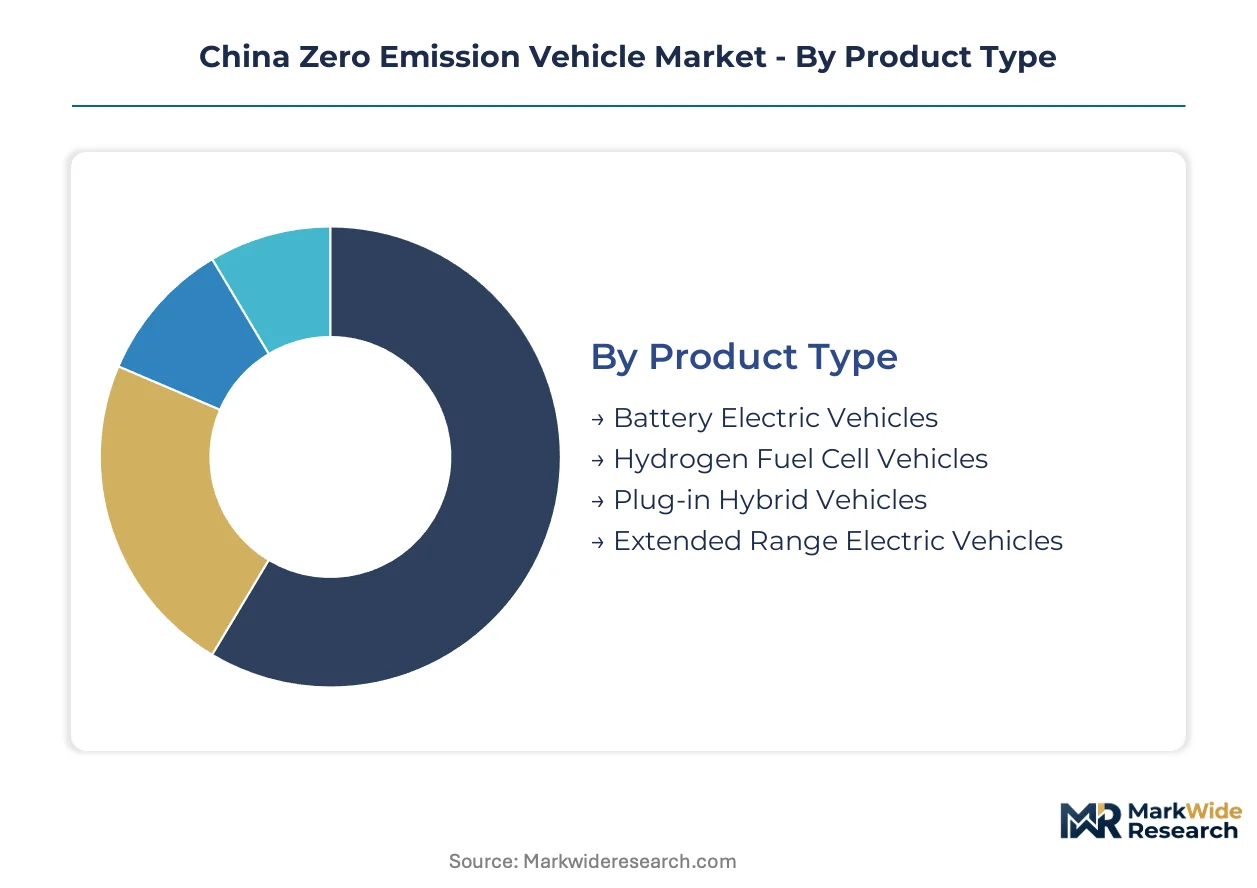
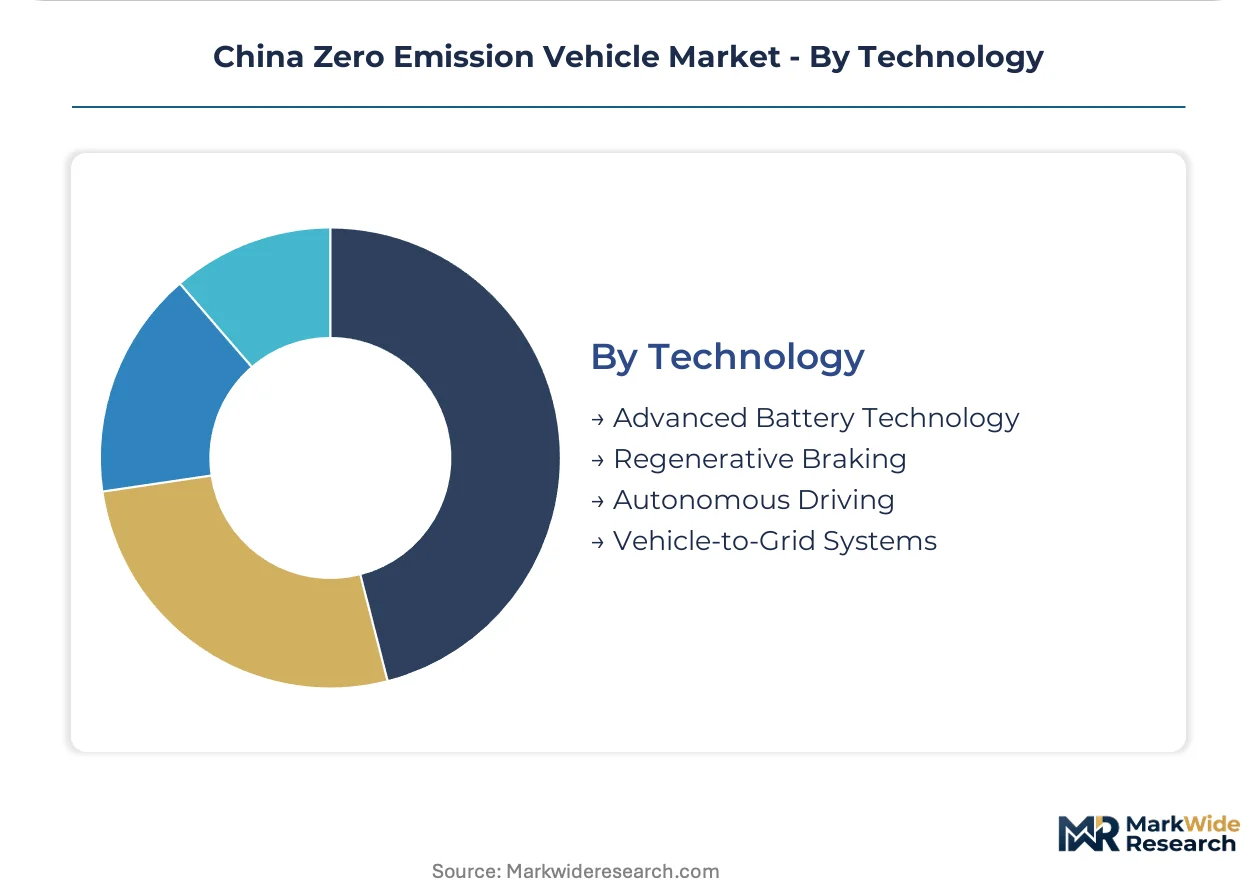
| Segmentation | Product Type: Battery Electric Vehicles, Hydrogen Fuel Cell Vehicles, Plug-in Hybrid Vehicles, Extended Range Electric Vehicles End User: Private Consumers, Government Fleets, Ride-Sharing, Commercial Fleets Charging Infrastructure: Fast Charging Stations, Home Chargers, Public Charging Networks, Wireless Charging Technology: Advanced Battery Technology, Regenerative Braking, Autonomous Driving, Vehicle-to-Grid Systems |
| Companies Covered | BYD Company Ltd, SAIC-GM-Wuling, Tesla Inc., Li Auto, Geely Auto Group, Changan Automobile, Chery Automobile, NIO Inc., XPeng Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Zero Emission Vehicle Market Trends and Innovations
China's zero emission vehicle sector is reconfiguring around cell chemistry diversification, regulatory enforcement intensification, and fleet procurement centralization. These forces compress legacy technology lifecycles while opening new competitive terrain.
Cell-to-pack architectures are modularizing battery system design by eliminating module housings and integrating thermal management directly at the cell level. Commercial fleet operators and mass-market OEMs adopt these platforms to reduce pack weight and assembly complexity. This structural shift is compressing cost curves for LFP-based systems while forcing tier-two module suppliers to reposition toward BMS or thermal component specialization.
MEE's dual carbon implementation rules now extend carbon trading coverage to automotive manufacturing facilities, binding provincial governments to emission reduction trajectories. Industrial consequence includes accelerated phase-out of coal-powered cell production lines in favor of renewable-powered gigafactories. Heavy-duty commercial segments face the steepest compliance cost escalation, driving hydrogen fuel cell adoption in long-haul logistics corridors.
Fleet operators in Beijing, Shanghai, and Shenzhen now consolidate procurement through centralized tendering platforms that unbundle vehicle acquisition from charging infrastructure and after-sales service. Direct OEM relationships displace traditional dealer networks for volume commercial contracts. This channel restructuring concentrates buyer power and compresses margin structures for intermediaries unable to offer integrated mobility solutions.
China Zero Emission Vehicle Market Segmentation
Zero emission vehicle segmentation in China reveals how regulatory pressure and infrastructure maturity create divergent growth trajectories across propulsion systems and user categories. Understanding these divisions exposes where capital is concentrating and which technology bets carry asymmetric upside.
Product Type:
Standalone propulsion architectures dominate mass-market deployment, while embedded hybrid systems serve transitional segments where charging infrastructure remains underdeveloped.
- Battery Electric Vehicles:Full-electric drivetrains with lithium iron phosphate and ternary lithium packs now exceed 180 Wh/kg energy density in mainstream passenger configurations. Demand concentrates in the Yangtze River Delta cluster where Shanghai, Suzhou, and Hangzhou form a contiguous manufacturing and consumption corridor with dense charging infrastructure and MIIT compliance enforcement.
- Hydrogen Fuel Cell Vehicles:Proton exchange membrane fuel cell systems paired with high-pressure hydrogen storage tanks deliver 500+ kilometer range for heavy-duty applications. Municipal bus fleets in Shenzhen and Beijing anchor procurement volumes as dual carbon mandates accelerate fleet replacement timelines for routes exceeding battery-electric practical range.
- Plug-in Hybrid Vehicles:Dual-mode systems combining internal combustion range extenders with modest battery packs serve price-sensitive buyers in third-tier cities.
- Extended Range Electric Vehicles:Series-hybrid architectures with larger battery buffers and dedicated range-extender engines address intercity travel anxiety in western provinces.
Volume placements concentrate in Battery Electric Vehicles; the faster expansion belongs to Hydrogen Fuel Cell Vehicles in commercial segments.
End User:
Procurement patterns split between individual decision-makers optimizing total cost of ownership and institutional buyers executing centralized tendering against emission compliance deadlines.
- Private Consumers:Individual purchasers prioritize purchase subsidies, license plate privileges, and residential charging access in tier-one cities. The segment absorbs the majority of passenger BEV volumes as MIIT NEV mandates tighten manufacturer quotas and provincial dual carbon goals compress replacement cycles for conventional vehicles.
- Commercial Fleets:Logistics operators and delivery platforms face tightening municipal emission zones in Beijing, Shanghai, and Shenzhen that bar internal combustion vehicles from central business districts. Fleet operators now consolidate procurement through centralized tendering platforms that unbundle vehicle acquisition from charging infrastructure and after-sales service, compressing margin structures for traditional intermediaries.
- Government Fleets:Municipal and provincial procurement offices enforce preferential NEV purchasing rules for official vehicles.
- Ride-Sharing:Platform-mediated mobility services optimize for rapid charging turnaround and battery-swapping compatibility in dense urban corridors.
Private Consumers absorb the dominant share of unit volumes; Commercial Fleets are climbing the fastest as logistics electrification mandates harden.
Charging Infrastructure:
Capital deployment intensity varies sharply between asset-heavy public networks and distributed residential installations, with technology maturity determining viable business models.
- Fast Charging Stations:DC rapid chargers delivering 80% state-of-charge in under 30 minutes concentrate along highway corridors and urban commercial zones. The Yangtze River Delta cluster leads deployment density where Shanghai's municipal planning mandates integrate charging infrastructure into new commercial and residential developments.
- Public Charging Networks:Curbside and parking-integrated AC and DC chargers serve apartment-dwellers lacking dedicated residential access. Third-tier cities exhibit critical gaps in DC fast-charging density that constrain consumer confidence and fleet operator range planning despite provincial subsidy programs extending beyond coastal provinces.
- Home Chargers:Level 2 AC wall units installed in private parking spaces dominate total port count but serve narrow demographic segments.
- Wireless Charging:Inductive pad systems embedded in parking surfaces remain pilot-scale with limited commercial deployment.
Fast Charging Stations capture the majority of capital deployment; Public Charging Networks are gaining share fastest as urban apartment-dweller demand intensifies.
Technology:
Technology layers stack from core energy storage through energy recovery and vehicle-grid integration, with each tier carrying distinct supplier concentration and intellectual property intensity.
- Advanced Battery Technology:Cell-to-pack architectures eliminate module housings and integrate thermal management directly at the cell level, reducing pack weight and assembly complexity. Chinese battery cell manufacturers are repositioning capacity toward LFP and solid-state chemistries to secure cost advantages, with sulfide electrolyte and silicon-anode convergence promising energy density breakthroughs for premium passenger segments.
- Vehicle-to-Grid Systems:Bidirectional charging hardware and aggregation software enable parked vehicles to discharge stored energy back to distribution networks. MEE's dual carbon implementation rules extending carbon trading coverage to automotive manufacturing facilities create regulatory pull for grid-interactive assets that can monetize flexibility services in provincial emission reduction trajectories.
- Regenerative Braking:Kinetic energy recovery systems integrated into electric drivetrains capture deceleration energy.
- Autonomous Driving:Advanced driver-assistance systems and software-defined vehicle architectures differentiate premium offerings.
Advanced Battery Technology commands the steepest R&D concentration; Vehicle-to-Grid Systems show the steepest expansion trajectory as grid flexibility markets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate deposits in Qinghai and Sichuan anchor China's battery supply chain geography, concentrating cathode active material production in western provinces while vehicle assembly clusters along the eastern seaboard.
Yangtze River Delta
Shanghai, Suzhou, and Hangzhou form the dominant manufacturing corridor with dense supplier networks and MIIT compliance enforcement. Municipal planning mandates integrate charging infrastructure into new commercial developments. Cell-to-pack production lines concentrate in Jiangsu province to serve BYD and NIO assembly plants.
Pearl River Delta
Shenzhen anchors hydrogen fuel cell bus deployment for municipal fleets exceeding 500-kilometer routes. Guangdong provincial subsidies extend NEV procurement beyond tier-one cities. BYD's headquarters integration controls semiconductor and battery inputs for regional assembly.
Beijing-Tianjin-Hebei
Municipal emission zones bar internal combustion vehicles from central business districts, compressing fleet replacement timelines. MEE dual carbon rules bind Hebei province to emission reduction trajectories. State-backed procurement platforms consolidate government fleet tendering.
Sichuan-Chongqing
Chengdu and Xi'an corridors offer underpenetrated markets as provincial subsidy programs extend beyond coastal provinces. Local lithium refining from Qinghai deposits reduces cathode material transport costs. Western China expansion targets apartment-dwellers lacking residential charging access.
Shandong Peninsula
Qingdao and Jinan host emerging battery swapping network pilots for commercial fleet rapid turnaround. Provincial energy regulators integrate renewable-powered gigafactories into grid flexibility markets. Industrial policy supports solid-state electrolyte R&D consortia.
China Zero Emission Vehicle Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue premium differentiation through service models and software architecture. The market consolidates around vertically integrated battery manufacturers and state-backed automotive groups. Three archetypes dominate: integrated cell-to-vehicle producers, platform-specialist startups, and diversified industrial conglomerates. Capacity expansion and strategic partnerships with charging infrastructure operators constitute the primary competitive moves.
Among China-based producers, BYD Company Ltd exemplifies the integrated archetype through captive battery and semiconductor supply, while NIO Inc. occupies a position within the premium service tier, and XPeng Motors represents the software-defined vehicle specialist segment. These three entities anchor the competitive structure described in this study, with each firm sitting within distinct strategic tiers that reflect divergent bets on battery chemistry, distribution models, and end-user segmentation.
| Leading Market Players |
|---|
| BYD Company Ltd |
| SAIC-GM-Wuling |
| Tesla Inc. |
| Li Auto |
| Geely Auto Group |
| Changan Automobile |
| Chery Automobile |
| NIO Inc. |
| XPeng Motors |
| Others |
Pricing and Supply Chain Analysis
MEE's dual carbon implementation rules gate qualified supply access for battery cell manufacturers and anchor premium-tier pricing for renewable-powered gigafactories. Pricing power concentrates with producers meeting GB standard certification while provincial emission reduction trajectories compress margin structures for coal-dependent suppliers.
Pricing Analysis
Warranty and after-sales service bundling separates fleet procurement contracts from private consumer transactions, with commercial operators negotiating comprehensive maintenance packages against unbundled retail pricing. Three-tier pricing structure across premium, standard, and economy levels reflects battery chemistry grade, with LFP packs commanding volume discounts and solid-state prototypes extracting technology premiums. Cost compression in mass-market passenger segments is intensifying because cathode active material volatility destabilizes long-term contracts. Logistics operators demonstrate lowest price sensitivity due to emission zone compliance deadlines, while third-city private buyers defer purchases awaiting subsidy clarity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from BYD and NIO assembly plants concentrated in Jiangsu and Guangdong provinces. Geographic supply concentration centers on Qinghai and Sichuan for lithium carbonate refining, with cathode active material production feeding from South Korean and Japanese precursor imports. Raw material dependencies rest on battery-grade lithium carbonate, high-nickel cathode formulations, and silicon-anode substrates. Single-source vulnerability for sulfide electrolyte precursors threatens solid-state commercialization timelines. Distribution runs through state-backed procurement platforms consolidating government and commercial fleet tendering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vertically integrated producers as MIIT's tightening GB standards force weaker module suppliers into BMS specialization or exit. Provincial dual carbon mandates accelerate the shakeout timeline.
For Market Incumbents: Anticipate margin compression from centralized fleet tendering platforms by deepening captive battery supply and securing renewable-powered production certification ahead of MEE carbon trading expansion. Lock in long-term cathode material offtake agreements to neutralize lithium carbonate volatility. Prioritize cell-to-pack architecture R&D to maintain assembly cost advantages against emerging solid-state entrants.
For New Entrants and Emerging Players: Direct-to-user digital channels enable bypass of traditional dealer networks for premium passenger segments, particularly battery-swapping subscription models targeting apartment-dwellers in Shanghai and Hangzhou. White-space concentration sits with hydrogen fuel cell range-extender systems for western China logistics corridors exceeding battery-electric practical range. Target Chengdu-Chongqing procurement offices with integrated mobility solutions bundling vehicle, charging infrastructure, and carbon credit monetization.
For Investors and Strategic Acquirers: Provincial subsidy tapering announcements are the leading indicator that replacement-cycle timing is shifting and distressed asset opportunities are emerging. Long-term viability favors producers with backward integration into semiconductor and thermal management components. Target acquisition archetypes include tier-two module suppliers pivoting to BMS firmware and solid-state electrolyte R&D consortia lacking manufacturing scale. Watch for MIIT homologation backlog clearance as capacity utilization inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures LFP cell allocation from Qinghai-refined lithium sources for Yangtze River Delta assembly. |
| Charging Infrastructure Partnership | Integrates DC fast-charging networks with municipal planning mandates in Shenzhen and Beijing. |
| Software-Defined Vehicle Investment | Advances XPeng's autonomous driving differentiation through proprietary BMS firmware development. |
| Geographic Manufacturing Footprint | Positions solid-state pilot lines in Shandong to access provincial electrolyte R&D consortia. |
| Platform Standardization | Enables NIO's battery-swapping compatibility across commercial fleet rapid-turnover operations. |
Research Methodology
Multi-period observation of MIIT NEV mandate compliance rates, provincial subsidy disbursement patterns, and gigafactory capacity utilization anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, commercial fleet operations managers, and SAMR certification officers. Secondary validation drew from MIIT production quota filings, MEE carbon trading registry disclosures, vehicle registration databases, and customs records for lithium carbonate and cathode material trade flows. Bottom-up cell production capacity modeling triangulated against top-down provincial emission reduction trajectory requirements.
Input-output matrices mapped propulsion architecture adoption across vehicle class, battery chemistry tier, end-user category, and regional production cluster throughout the forecast period. CAGRs were derived from segmented demand elasticity modeling against infrastructure deployment curves and regulatory enforcement intensity. Forecast inputs incorporated charging station density thresholds, hydrogen fuel cell bus procurement tender volumes, and solid-state electrolyte pilot production yields.
The model holds under sustained MIIT quota enforcement and lithium carbonate price band stability; deviation in provincial subsidy tapering schedules or GB standard revision timelines would shift replacement-cycle assumptions. Forecasts reflect documented base-case assumptions regarding infrastructure buildout rates and technology cost curves. Periodic stress-testing of base assumptions is recommended against MEE dual carbon rule amendments and cathode material supply disruption scenarios.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Air Powered Vehicle Market