
 Middle East and Africa and India CNG and LPG Vehicle Market | 2026-2036
Middle East and Africa and India CNG and LPG Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa and India CNG and LPG Vehicle Market Foresight
CE marking under the EU F-Gas Regulation is rotating as the de facto qualification threshold for European-origin OEMs supplying into Middle East and Africa markets. Maruti Suzuki India Ltd. leverages its dominance in factory-fitted CNG passenger cars across Indian urban centers. Tata Motors Limited anchors the heavy-duty segment with dedicated CNG bus and truck platforms for state transport undertakings. Hyundai Motor Company competes through dual-fuel LPG variants positioned in price-sensitive private-owner segments.
CNG and LPG vehicles incorporate spark-ignition engines modified with high-pressure fuel storage cylinders, pressure regulators, and dedicated injection systems calibrated for gaseous fuel combustion at compression ratios between 10:1 and 14:1, serving commercial and private transport operators seeking lower per-kilometer fuel expenditure. Passenger cars command volume leadership where factory-fitted CNG trims from mass-market OEMs attract urban commuters facing volatile gasoline pricing. Heavy-duty trucks represent the fastest-expanding category as fleet operators in India and South Africa replace diesel units to meet tightening emissions standards and reduce total cost of ownership across million-kilometer lifecycles.
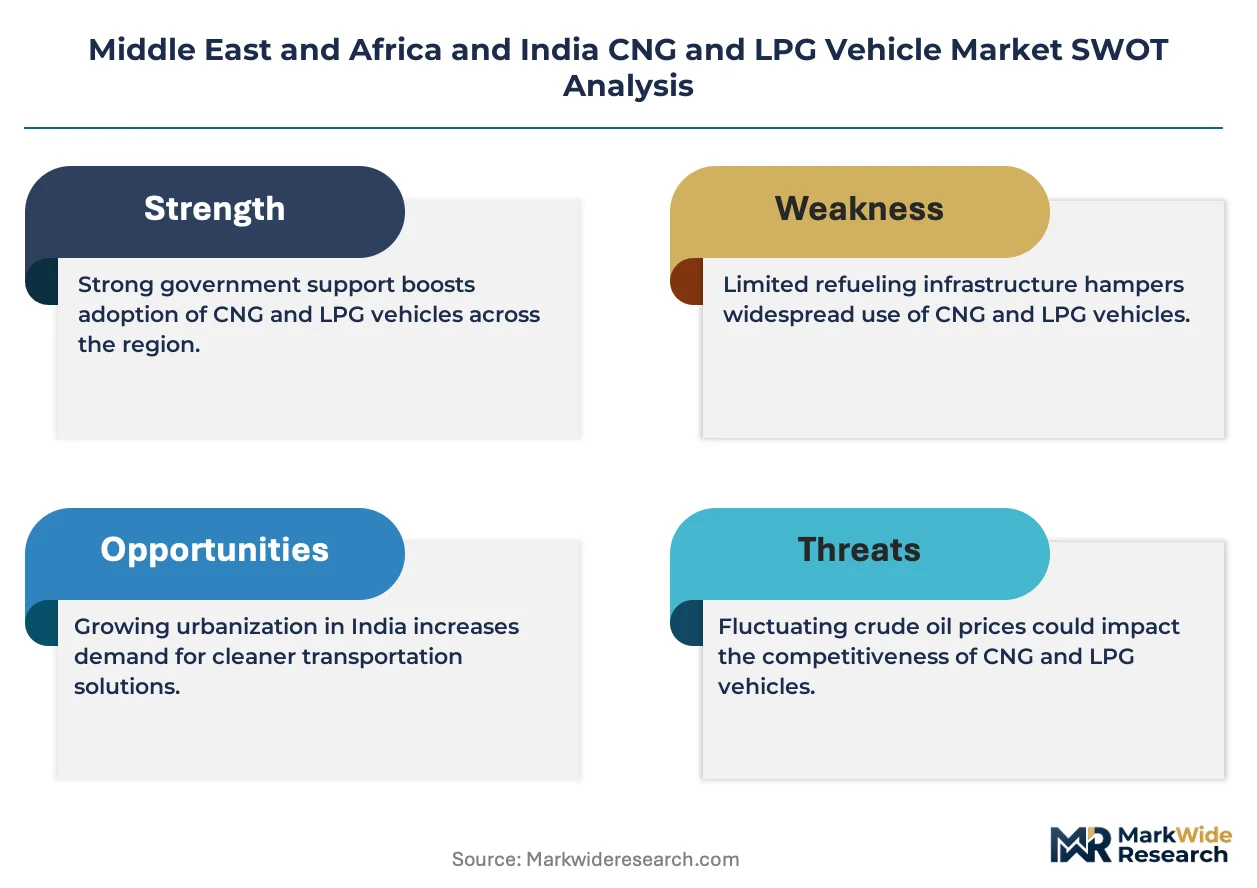
India's CEA mandates CNG station infrastructure buildout under national pipeline expansion directives, while South Africa's Department of Transport enforces bus emissions benchmarks that redirect municipal procurement. The EU F-Gas Regulation shapes component import compliance for European suppliers serving Middle East distributors. Stakeholders must monitor how India's PLI scheme revisions and South Africa's carbon budgeting frameworks alter the relative economics of CNG retrofits versus factory-built platforms across fleet procurement cycles.
Market Dynamics
India's PLI scheme for clean mobility is redirecting capital toward domestic CNG retrofit capacity as fleet operators accelerate diesel displacement timelines. This subsidy architecture is compressing payback periods for commercial vehicle conversions and reshaping procurement patterns across state transport undertakings.
Growth Catalysts
- Pipeline Infrastructure Mandates:India's CEA directs national pipeline expansion that densifies CNG station availability across Gujarat and Maharashtra, reducing range anxiety for commercial fleets.
- Emissions Benchmark Enforcement:South Africa's Department of Transport enforces stricter bus emissions standards that redirect municipal procurement toward CNG platforms.
- Factory-Fitted Platform Economics:Mass-market OEMs are integrating CNG powertrains at original equipment stage, lowering incremental cost versus aftermarket retrofits for urban passenger car buyers.
Market Restraints
- Storage Cylinder Cost Volatility:High-pressure composite cylinder prices fluctuate with carbon fiber feedstock costs, compressing margin structures for retrofit installers.
- Station Network Geographic Concentration:CNG dispensing infrastructure clusters in western Indian states, leaving eastern and southern corridors with sparse coverage that limits fleet route flexibility.
- LPG Energy Density Limitations:Lower volumetric energy content versus CNG restricts LPG adoption to light-duty segments, excluding heavy commercial applications.
Strategic Opportunities
- Eastern India Corridor Development:Odisha and West Bengal present underpenetrated demand as pipeline networks extend eastward from existing Gujarat-Maharashtra hubs.
- Dual-Fuel Technology Convergence:Integration of CNG-diesel dual-fuel systems enables gradual fleet transition without full asset replacement for long-haul operators.
- State-Level Retrofit Subsidies:India's PLI scheme revisions may expand to cover commercial vehicle retrofits, accelerating conversion rates beyond factory-built volumes.
Industry Challenges
- Calibration Technician Shortage:Gaseous fuel injection system tuning requires specialized expertise that outpaces vocational training program output across Indian aftermarket channels.
- Type Approval Timeline Compression:India's BIS certification processes for CNG conversion kits create bottlenecks as retrofit demand surges ahead of testing laboratory capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa and India CNG and LPG Vehicle Market |
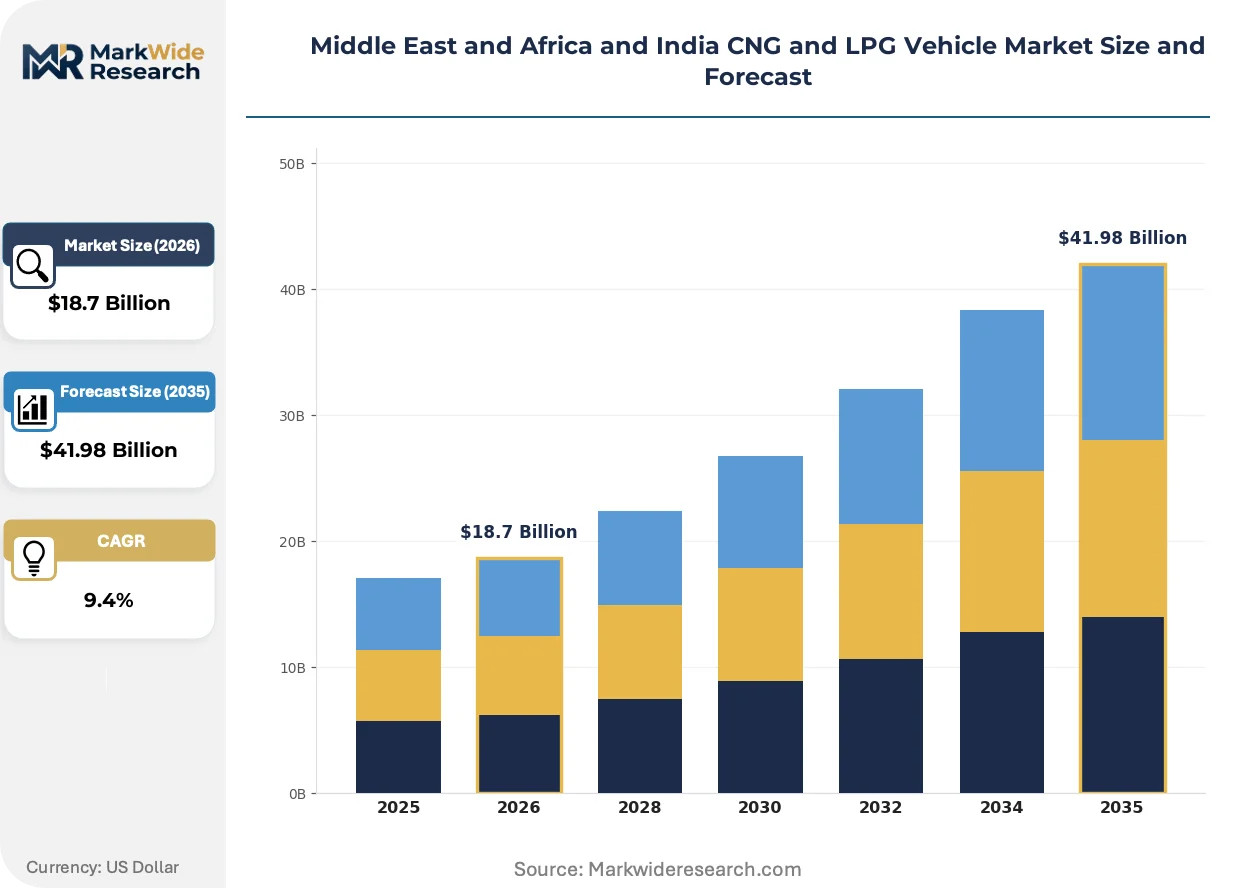
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy-Duty Trucks, Buses Fuel Type: CNG, LPG, Bio-CNG, Other Alternative Fuels End User: Private Owners, Fleet Operators, Government Agencies, Corporations Regulatory Framework: Emissions Standards, Safety Regulations, Incentive Programs, Import Tariffs |
| Companies Covered | Maruti Suzuki India Ltd., Tata Motors Limited, Bajaj Auto Limited, MAN Truck & Bus SE, IVECO S.p.A., Mahindra & Mahindra, Hyundai Motor Company, Honda Motor Co. Ltd., Suzuki Motor Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa and India CNG and LPG Vehicle Market Shifts & Advancements
Technology evolution and regulatory calibration are converging to alter how gaseous fuel vehicles enter service and how operators manage total cost of ownership across vehicle lifecycles.
Sequential multi-point injection systems calibrated for CNG combustion are supplanting older mixer-based conversion approaches in Indian heavy-duty retrofits. Fleet operators at Maharashtra State Road Transport Corporation and Gujarat State Road Transport Corporation are specifying these systems for new bus procurements. The shift is compressing maintenance intervals and enabling longer service lives for high-utilization commercial platforms.
South Africa's Department of Transport emissions benchmarking framework is mandating measurable NOx and particulate reductions for municipal bus fleets. This regulatory architecture is disqualifying aging diesel units from tender eligibility and redirecting capital allocations toward CNG procurement. Bus operators in Johannesburg and Cape Town are restructuring fleet replacement cycles to align with compliance deadlines.
Aggregated fleet procurement consortia are displacing individual operator purchasing across India's logistics sector. Third-party fleet management platforms coordinate volume orders for CNG trucks on behalf of small and mid-sized operators who lack direct OEM negotiation leverage. This channel transformation concentrates most visible in Gujarat's Ahmedabad-Surat freight corridor where fuel cost differentials drive rapid platform switching.
Middle East and Africa and India CNG and LPG Vehicle Market Segmentation
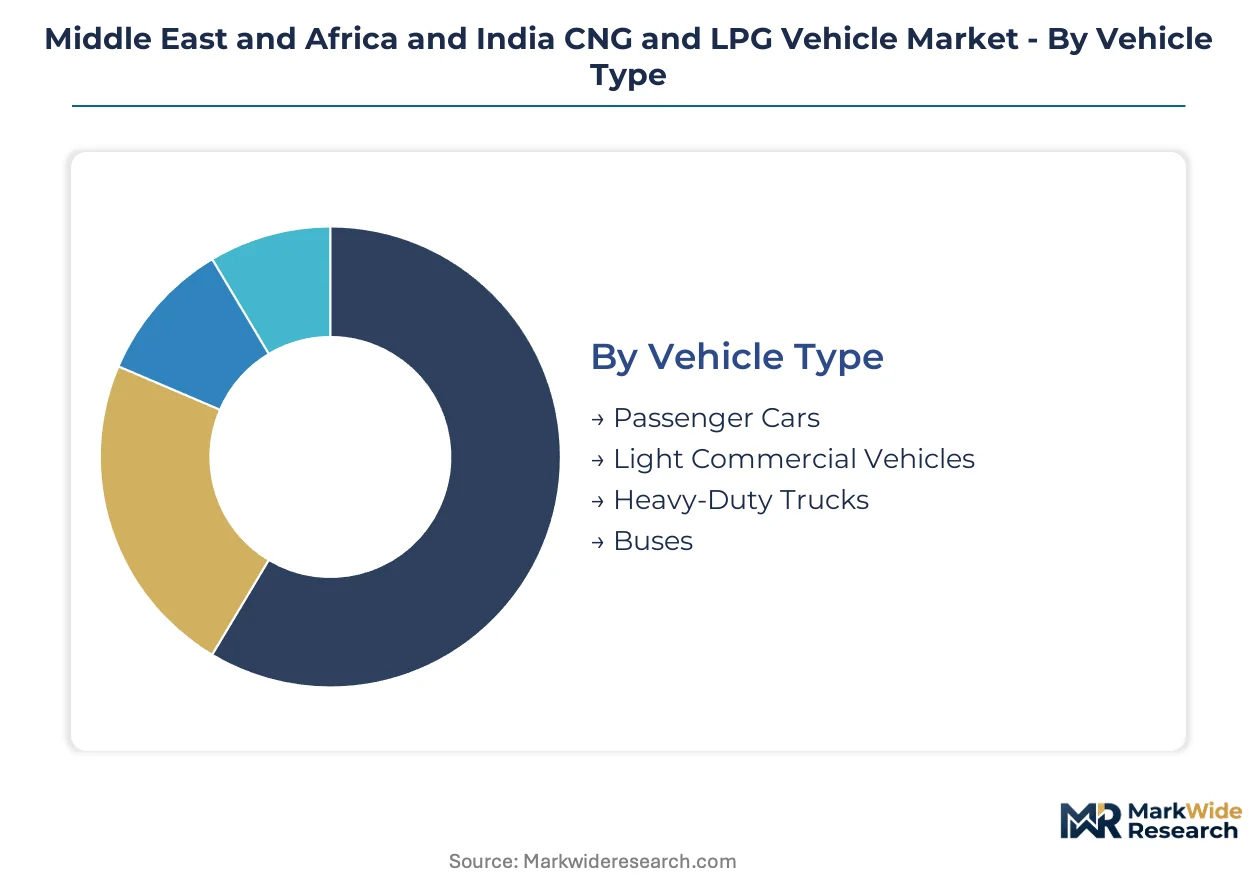
CNG and LPG vehicle procurement patterns diverge sharply across vehicle duty cycles, fuel chemistry, and buyer types. Understanding where margin pools concentrate within each dimension reveals where technology investments and policy interventions reshape competitive outcomes.
Vehicle Type:
Margin pools concentrate in heavy-duty platforms where million-kilometer lifecycles and fuel cost differentials amplify total cost of ownership calculations for fleet procurement officers.
- Passenger Cars:Factory-fitted CNG trims from mass-market OEMs attract urban commuters facing volatile gasoline pricing. Demand clusters in Indian metropolitan centers where CNG station density supports daily refueling routines.
- Heavy-Duty Trucks:Fleet operators in India and South Africa replace diesel units to meet tightening emissions standards and reduce per-kilometer fuel expenditure across extended operational lifecycles. This segment is expanding most quickly as logistics operators accelerate platform switching.
- Light Commercial Vehicles:Urban last-mile delivery fleets favor CNG variants for predictable route economics within established station networks.
- Buses:State transport undertakings in Maharashtra and Gujarat specify dedicated CNG platforms for high-utilization intercity and municipal services.
The dominant share belongs to Passenger Cars, while Heavy-Duty Trucks is closing the gap fastest.
Fuel Type:
Application suitability and infrastructure availability determine where procurement volumes flow across gaseous and liquid alternatives.
- CNG:High-pressure compressed natural gas serves commercial and private transport through dedicated pipeline infrastructure, with India's CEA mandating national network expansion that densifies station availability across western states.
- LPG:Lower volumetric energy content restricts adoption to light-duty segments where storage cylinder packaging constraints matter less for short-haul urban operations.
- Bio-CNG:Upgraded biogas from agricultural and municipal waste streams offers carbon-negative pathway for fleet operators targeting Scope 3 emissions reductions.
- Other Alternative Fuels:Emerging synthetic methane and hydrogen blends remain pre-commercial across Middle East and Africa deployment contexts.
CNG commands procurement volumes, though Bio-CNG is gaining share fastest as sustainability-linked financing reshapes fleet tender evaluation criteria.
End User:
Procurement scale and decision velocity separate individual buyers from institutional purchasers with dedicated technical evaluation capabilities.
- Fleet Operators:Aggregated procurement consortia coordinate volume orders for CNG trucks on behalf of small and mid-sized logistics operators lacking direct OEM negotiation leverage.
- Government Agencies:State transport undertakings anchor heavy-duty bus demand through tender processes tied to emissions compliance deadlines enforced by South Africa's Department of Transport.
- Private Owners:Price-sensitive urban commuters select factory-fitted CNG passenger cars based on payback period calculations against gasoline price volatility.
- Corporations:ESG-mandated fleet procurement policies redirect commercial vehicle acquisitions toward verified low-carbon platforms.
Fleet Operators dominate procurement volumes, while Government Agencies are expanding fastest as municipal compliance deadlines concentrate replacement cycles.
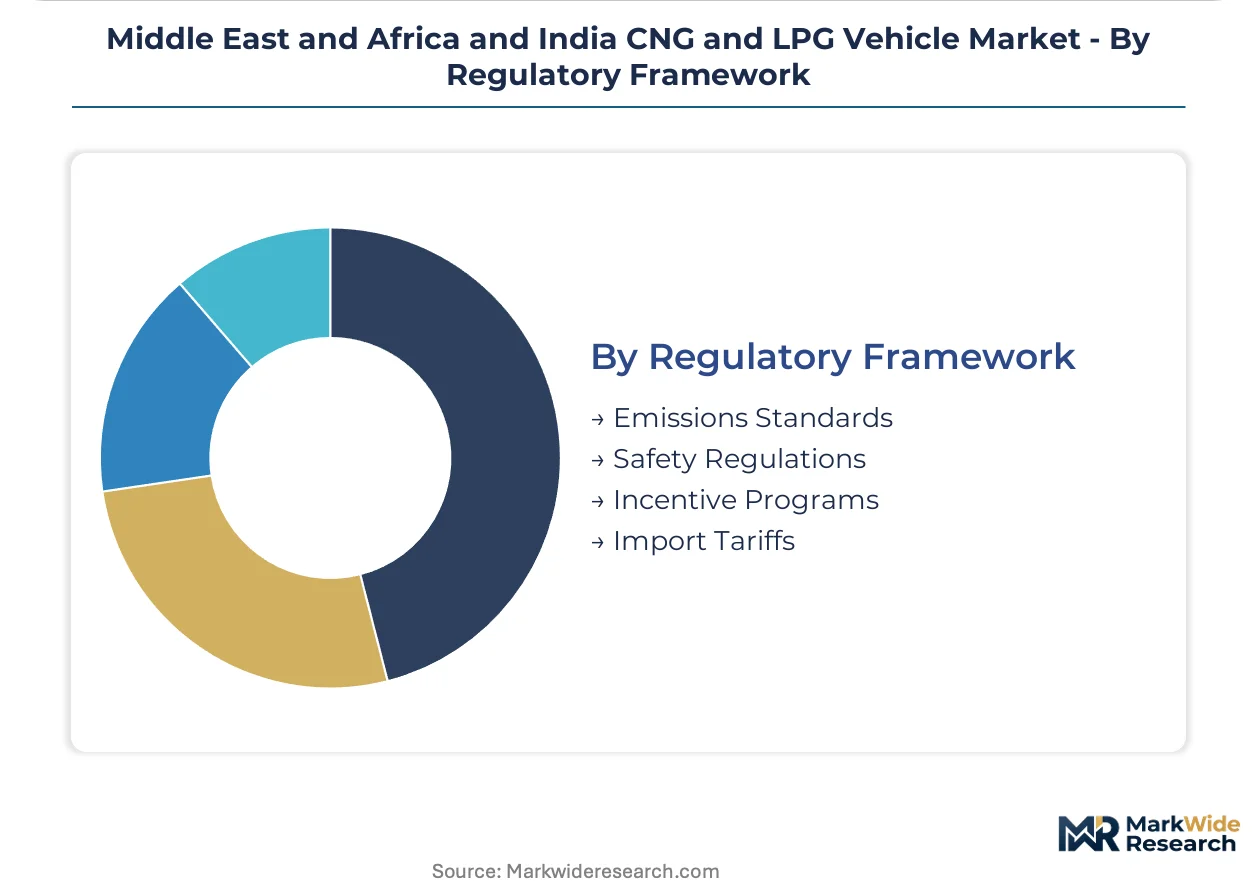
Regulatory Framework:
Compliance architecture determines market access conditions and shapes relative economics of retrofit versus factory-built platform decisions.
- Emissions Standards:South Africa's Department of Transport benchmarking framework mandates measurable NOx and particulate reductions that disqualify aging diesel units from tender eligibility.
- Incentive Programs:India's PLI scheme for clean mobility subsidizes domestic retrofit capacity and compresses payback periods for commercial vehicle conversions.
- Safety Regulations:BIS certification processes for CNG conversion kits create bottlenecks as retrofit demand surges ahead of testing laboratory capacity expansion.
- Import Tariffs:DGFT tariff structures influence component sourcing decisions for European-origin OEMs supplying into Middle East and Africa markets.
Incentive Programs structure the dominant procurement economics, while Emissions Standards are tightening fastest as enforcement mechanisms mature across national jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators anchor procurement volumes across the Middle East and Africa and India CNG and LPG Vehicle Market, with state transport undertakings and logistics consortia driving platform decisions. Government incentive architectures and emissions enforcement timelines compress replacement cycles unevenly across national jurisdictions. Infrastructure density and pipeline availability determine where commercial deployment accelerates fastest.
India
India's PLI scheme for clean mobility subsidizes domestic retrofit capacity, compressing payback periods for commercial vehicle conversions. The CEA mandates national pipeline expansion directives that densify CNG station availability across western states. Gujarat and Maharashtra maintain the densest station networks, with the Ahmedabad-Surat freight corridor witnessing rapid platform switching among aggregated fleet procurement consortia.
South Africa
Municipal bus fleets in Johannesburg and Cape Town restructure replacement cycles to align with compliance deadlines enforced by the Department of Transport. Stricter emissions benchmarking frameworks disqualify aging diesel units from tender eligibility and redirect capital toward CNG procurement. The Western Cape and Gauteng provinces concentrate procurement activity where enforcement mechanisms have matured fastest.
UAE
Federal transport authorities pilot CNG bus deployments across Dubai and Abu Dhabi municipal networks as part of diversified energy strategy implementation. MOHAP-aligned safety standards shape component import compliance for European-origin OEMs supplying through regional distributors. Dubai's logistics corridor operators evaluate dual-fuel platforms for last-mile delivery fleet renewal programs.
Saudi Arabia
SFDA-regulated safety protocols govern high-pressure cylinder certification for commercial vehicle retrofits entering service across Riyadh and Eastern Province transport networks. The kingdom's pipeline infrastructure expansion programs target industrial city connectivity that would enable freight corridor CNG station deployment. Dammam-Jubail industrial cluster operators assess fleet conversion economics against diesel price volatility.
Egypt
Cairo's state transport undertakings specify CNG bus platforms for high-utilization municipal services where fuel cost differentials dominate total cost of ownership calculations. The country's national petroleum regulator enforces cylinder recertification intervals that shape aftermarket service provider economics. Alexandria and Nile Delta freight corridors present underpenetrated demand as pipeline networks extend from existing Cairo hubs.
Middle East and Africa and India CNG and LPG Vehicle Market Competitive Landscape
Player mix skews toward diversified automotive conglomerates with dedicated alternative-fuel divisions alongside specialized commercial vehicle manufacturers. Market structure concentrates around factory-fitted passenger car platforms and heavy-duty retrofit systems, with limited pure-play CNG technology specialists. Two strategic archetypes dominate: mass-market OEMs integrating gaseous fuel powertrains at original equipment stage, and commercial vehicle specialists engineering dedicated bus and truck platforms for state tender processes. Competitive moves center on capacity expansion for domestic retrofit kit production and strategic partnerships with national oil companies for station network co-development.
Within the diversified automotive conglomerate tier, Maruti Suzuki India Ltd. and Tata Motors Limited exemplify contrasting strategic positions. Maruti Suzuki India Ltd. anchors factory-fitted CNG passenger car supply through mass-market distribution channels serving urban commuter demand. Tata Motors Limited occupies a position in heavy-duty commercial platforms, with dedicated CNG bus and truck architectures engineered for state transport undertaking procurement cycles. Hyundai Motor Company represents the dual-fuel LPG variant approach targeting price-sensitive private-owner segments where infrastructure constraints limit CNG penetration. MAN Truck & Bus SE and IVECO S.p.A. sit within the European commercial vehicle specialist archetype, with CE-marked component supply shaping compliance thresholds for Middle East and Africa market entry.
| Leading Market Players |
|---|
| Maruti Suzuki India Ltd. |
| Tata Motors Limited |
| Bajaj Auto Limited |
| MAN Truck & Bus SE |
| IVECO S.p.A. |
| Mahindra & Mahindra |
| Hyundai Motor Company |
| Honda Motor Co. Ltd. |
| Suzuki Motor Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between fleet operators and national oil companies lock in CNG supply access and price visibility across India's western corridor procurement cycles. These arrangements compress margin volatility for commercial vehicle retrofits while tethering aftermarket installers to pipeline expansion timelines mandated by the CEA.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate fleet procurement, linking retrofit kit pricing to pipeline-delivered fuel costs rather than spot market volatility. Price differentiation hinges on BIS certification tier and cylinder composite grade, with Type IV carbon-fiber units commanding premium positioning over Type II steel alternatives. Pricing pressure stems from carbon fiber feedstock cost swings compressing installer margins. Private owner segments exhibit highest price sensitivity, while state transport undertakings prioritize lifecycle cost over upfront outlay.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Indian retrofit installers who lack capital for cylinder stockpiling, while strategic stockpiling characterizes European OEM component sourcing for CE-marked systems. Geographic supply concentration centers on India, China, and South Korea for high-pressure composite cylinders and precision injection components. Raw material dependencies include carbon fiber tow, aluminum liner stock, and electronic pressure regulators. Single-source vulnerability runs through carbon fiber precursor supply. Distribution feeds from Tier 1 OEM captive production through national distributor networks to certified installation workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CNG and LPG vehicle markets increasingly monetize through recurring-revenue service layers, with cylinder recertification and injection system calibration outpacing hardware sales growth. Aftermarket maintenance contracts now anchor profitability for retrofit specialists facing compressed kit margins.
For Market Incumbents: Secure exclusive cylinder recertification partnerships with state transport undertakings before municipal compliance deadlines concentrate replacement cycles. Defend against emerging dual-fuel diesel-CNG technology by deepening backward integration into composite cylinder production in Gujarat manufacturing clusters. Prioritize BIS laboratory capacity expansion to compress type approval bottlenecks that delay retrofit kit deployment.
For New Entrants and Emerging Players: Lead with eastern India corridor penetration as pipeline networks extend from Maharashtra toward Odisha and West Bengal, where station density remains sparse and first-mover positioning is achievable. Target aggregated fleet procurement consortia lacking direct OEM negotiation leverage through third-party fleet management platform partnerships. Emphasize mobile calibration service units addressing technician shortage constraints in aftermarket channels.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated retrofit specialists with captive cylinder production and certified installation networks spanning multiple Indian states. Long-term viability hinges on PLI scheme continuity and carbon budgeting framework maturation across South African municipal procurement. Monitor India's BIS certification backlog as inflection indicator for aftermarket demand-supply imbalance severity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Manufacturing | Captive composite production insulates margin structures from carbon fiber feedstock volatility affecting Tier 2 installers. |
| CE Marking Pathway Investment | EU F-Gas Regulation compliance unlocks Middle East distributor access for European-origin OEM component supply. |
| Dual-Fuel Technology Licensing | CNG-diesel system integration enables gradual fleet transition without full asset replacement for long-haul operators. |
| State Transport Undertaking Partnership | Maharashtra and Gujarat tender alignment secures multi-year bus procurement volumes with emissions compliance certainty. |
| Mobile Calibration Service Deployment | Technician shortage mitigation compresses maintenance intervals and extends high-utilization commercial platform service lives. |
Research Methodology
Operator-level perspectives from fleet procurement managers, state transport undertaking technical directors, aftermarket installation workshop owners, and national oil company commercial officers anchored the qualitative base. Primary interview insights combined with secondary validation from BIS certification records, CEA pipeline expansion directives, South African Department of Transport emissions benchmarking frameworks, and vehicle production registration databases. Bottom-up retrofit kit volume estimates triangulated against top-down fuel consumption projections across the analysis window.
Sensitivity analysis tested forecast robustness across PLI scheme revision scenarios, carbon fiber price volatility bands, and station network expansion pace variations. The analytical framework segmented by vehicle class, fuel chemistry, end-user procurement scale, and regional regulatory cluster throughout the forecast period. CAGRs derived from logistic diffusion modeling of fleet replacement cycles and infrastructure buildout correlation analysis. Industry-specific inputs included cylinder recertification interval compliance rates and aggregated fleet procurement consortium penetration metrics.
The analysis sits within stated boundaries; outcomes outside sustained pipeline infrastructure investment or accelerated BIS laboratory capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding subsidy continuity and emissions enforcement mechanism maturation. Revision becomes warranted when carbon fiber precursor supply constraints or technician training program output shortfalls cross thresholds that compress retrofit market service capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Ethanol Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
Dual Fuel Engine Market