
 Alternative Fuel Vehicle (AFV) Market | 2026-2036
Alternative Fuel Vehicle (AFV) Market Size, Share, and Industry Trends Forecast 2026-2036
Alternative Fuel Vehicle (AFV) Market Insights
China's Jiangsu and Zhejiang provinces is narrowing the cost gap between battery electric and internal combustion platforms through integrated cell-to-pack manufacturing. Tesla leverages its Nevada gigafactory footprint to sustain North American cathode supply. BYD Company Limited anchors vertical integration from lithium refining to finished buses, while Toyota Motor Corporation specializes in solid-state electrolyte research for next-generation fuel cell stacks.
Alternative fuel vehicles employ energy conversion systems that replace or supplement petroleum-derived fuels with compressed natural gas, hydrogen fuel cells, or rechargeable battery packs operating above 400 volts. These platforms serve commercial fleets and individual owners seeking compliance with tailpipe emission ceilings and total cost-of-ownership reductions. Battery electric technology captures the dominant margin pool as cell chemistry shifts toward lithium-iron-phosphate and high-nickel formulations. Hydrogen fuel cell applications concentrate in heavy-duty trucks and municipal buses where payload range requirements exceed pure battery economics. Hybrid architectures retain share among fleet operators balancing infrastructure availability against route predictability.
EPA tailpipe standards and California Air Resources Board mandates force powertrain portfolio diversification across OEM lineups. EU Green Deal carbon-border adjustments and China's MIIT new-energy vehicle credit system shape factory location decisions and export eligibility. Stakeholders must monitor regulatory credit arbitrage between jurisdictions as subsidy phase-outs in mature markets redirect investment toward emerging production clusters.
Market Dynamics
Battery chemistry standardization around lithium-iron-phosphate and high-nickel formulations is compressing module costs and forcing legacy cathode suppliers to retool capacity or exit the supply base entirely.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Municipal transit agencies across Germany, France, and the Netherlands are accelerating fleet electrification to avoid import tariffs on high-carbon automotive components.
- Cell-to-pack manufacturing:China's Yangtze River Delta corridor is achieving 15-20% cost reductions by eliminating module housings and simplifying thermal management architecture.
- Heavy-duty hydrogen corridors:California's H2Hubs program and Germany's national hydrogen strategy are funding dedicated refueling infrastructure for long-haul trucking routes where battery weight penalties exceed economic thresholds.
Market Restraints
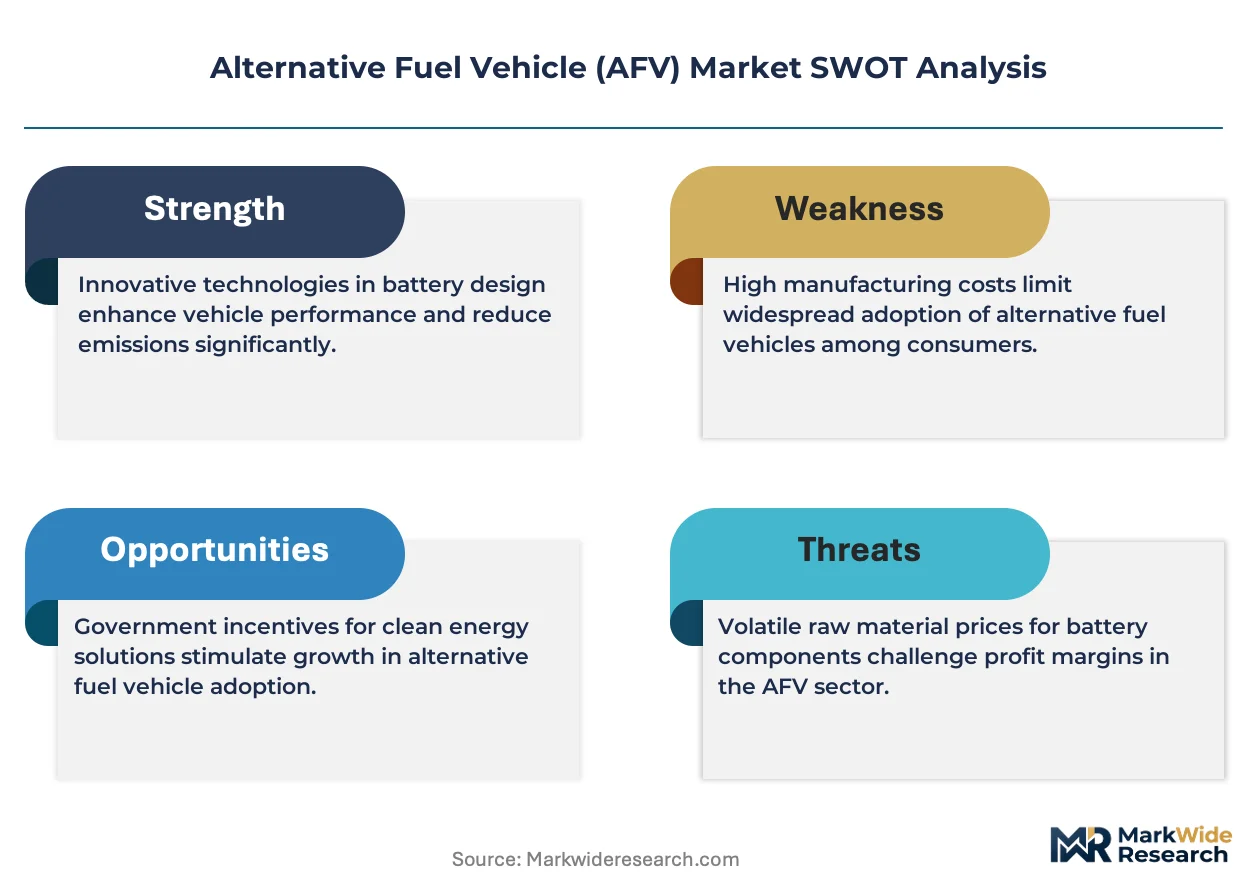
- Lithium carbonate volatility:Spot market prices for battery-grade lithium remain susceptible to Chilean and Australian concentrate supply disruptions, forcing OEMs to absorb margin compression or pass through costs.
- Cathode precursor concentration:Over 70% of refined cobalt and nickel sulfate processing capacity sits within China's Fujian and Hunan provinces, creating single-source vulnerability for non-Chinese cell manufacturers.
- Solid-state electrolyte manufacturability:Ceramic and sulfide-based solid electrolytes face yield challenges at pilot scale, delaying commercialization timelines for next-generation packs targeting 1,000-kilometer range.
Strategic Opportunities
- India's FAME-II subsidy extension:The country's heavy industry ministry is expanding purchase incentives for electric buses and two-wheelers through 2025, opening demand for localized battery assembly.
- Vehicle-to-grid integration:Bidirectional charging hardware and utility software stacks are converging to transform parked electric fleets into grid stabilization assets in deregulated power markets.
- Direct-to-fleet sales channels:Battery OEMs are bypassing traditional dealership networks to contract directly with logistics operators for managed charging and battery-as-a-service arrangements.
Industry Challenges
- Battery thermal runaway containment:Pack designers must satisfy UN 38.3 transport regulations and updated NHTSA crashworthiness protocols while maintaining energy density targets.
- High-voltage technician certification:Maintenance networks face shortages of electricians qualified to service 800-volt architectures, extending vehicle downtime and raising fleet operational risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternative Fuel Vehicle (AFV) Market |
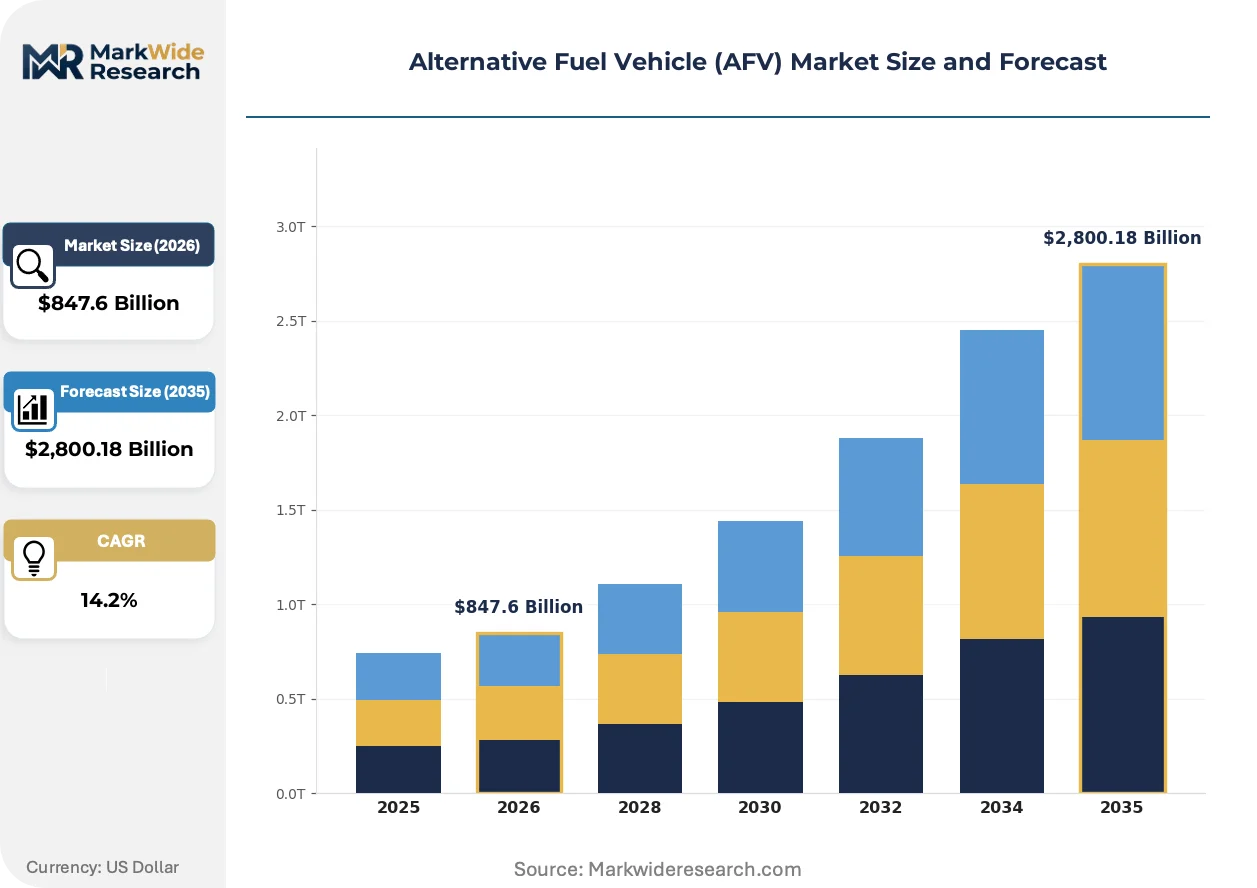
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,800.18 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: CNG, LPG, Hydrogen, Biofuel Vehicle Type: Passenger Cars, Buses, Trucks, Two-Wheelers Technology: Hybrid, Plug-in Hybrid, Battery Electric, Fuel Cell End User: Government, Fleet Operators, Individual Consumers, Public Transport |
| Companies Covered | Tesla, BYD Company Limited, Toyota Motor Corporation, Volkswagen AG, General Motors, BMW Group, Ford Motor Company, Hyundai Motor Company, Mercedes-Benz Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternative Fuel Vehicle (AFV) Market Trends and Innovations
Solid-state prototyping and silicon-anode insertion are compressing charging cycles and extending vehicle range, while regulatory mandates force faster powertrain portfolio turnover than traditional automotive development cycles permit.
Silicon-dominant anodes are replacing graphite in premium cell formulations, increasing volumetric energy density by 20-30% while managing expansion-induced cycle degradation through nano-structured particle architectures. European luxury OEMs are qualifying these cells for 2025-2026 model year platforms. The technology is virtualizing range anxiety as a purchase barrier by delivering 500-kilometer real-world range in C-segment packages.
The EU Green Deal's Fit for 55 package mandates 100% CO2 reduction for new cars and vans by 2035, eliminating internal combustion engine sales in the world's third-largest automotive market. OEMs are diverting R&D budgets from engine development to electric platform engineering and in-house cell manufacturing. Battery electric drivetrains are capturing the dominant margin pool as residual value risk shifts from powertrain durability to battery state-of-health transparency.
Fleet operators are consolidating procurement around total cost-of-ownership models that internalize electricity rates, maintenance avoidance, and residual value guarantees rather than sticker price. Third-party fleet management platforms are displacing traditional OEM captive finance arms as the primary customer interface. This pattern is most visible in California's drayage trucking and last-mile delivery segments, where operators prioritize uptime guarantees over brand loyalty.
Alternative Fuel Vehicle (AFV) Market Segmentation
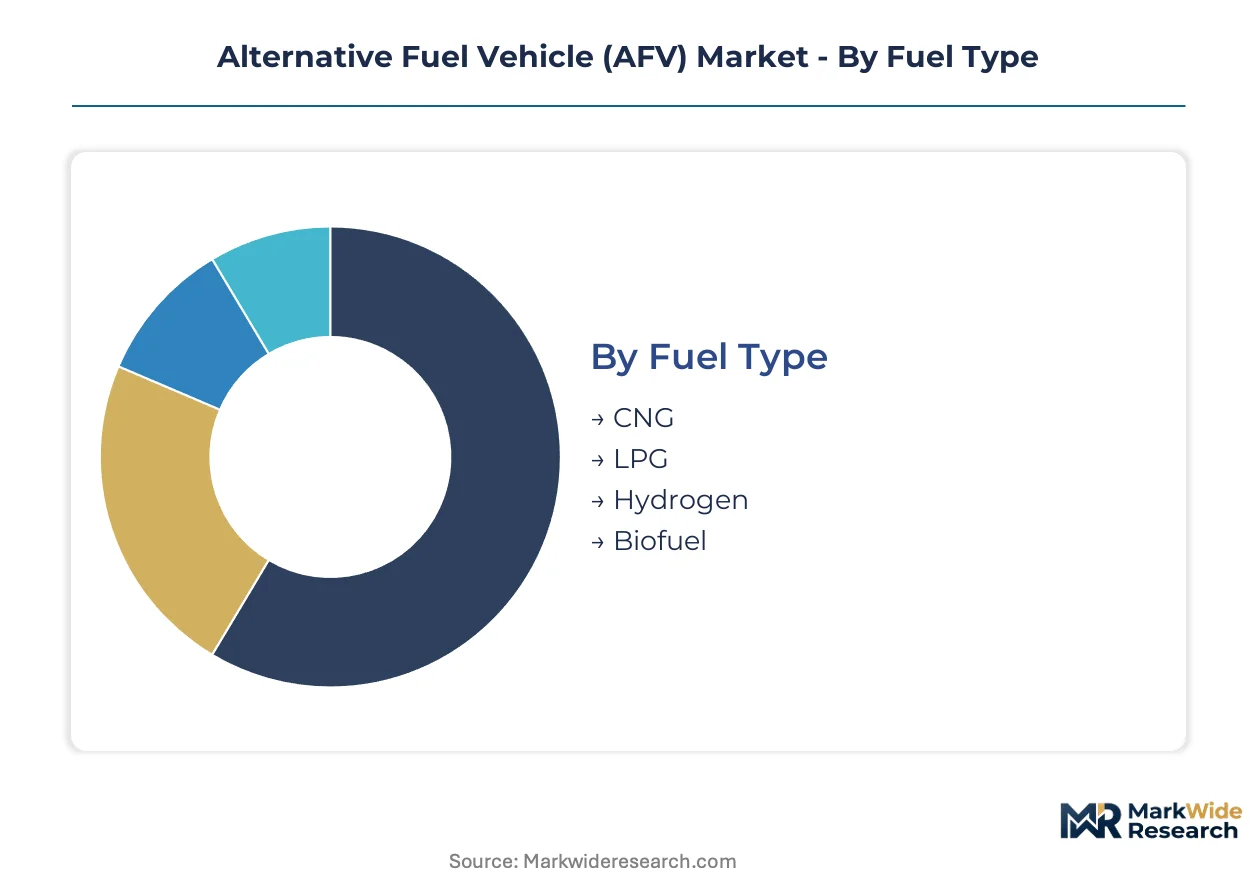
Segmentation in alternative fuel vehicles reveals how powertrain diversity splits procurement decisions across regulatory compliance, route economics, and infrastructure availability. Fleet operators and municipal buyers prioritize different fuel-technology combinations than individual consumers, creating parallel demand curves within the same vehicle categories.
Fuel Type:
Mature pipeline fuels dominate near-term fleet conversions while emerging molecules capture long-haul and heavy-duty niches.
- CNG:Compressed natural gas powers municipal transit and refuse collection fleets through established depot refueling infrastructure. Demand concentrates in Indian urban bus systems and Italian commercial fleets where biomethane injection meets EU Green Deal carbon intensity targets.
- LPG:Liquefied petroleum gas serves aftermarket conversions of light commercial vehicles in markets with limited electric charging density. Korean taxi operators and Turkish delivery fleets favor LPG for its lower per-kilometer fuel cost versus gasoline.
- Hydrogen:Fuel cell-grade hydrogen targets 350-bar and 700-bar storage for heavy-duty trucking corridors where battery weight penalties exceed payload economics.
- Biofuel:Renewable diesel and ethanol blends leverage existing liquid fuel infrastructure while delivering lifecycle carbon reductions for legacy fleet assets.
CNG handles the majority of throughput; hydrogen is climbing the fastest on share as dedicated corridor infrastructure scales.
Vehicle Type:
Commercial applications lead electrification timelines due to predictable duty cycles and centralized depot charging.
- Passenger Cars:Battery electric platforms now dominate OEM engineering budgets, with lithium-iron-phosphate chemistry penetrating mass-market segments. Chinese and European consumers drive volume as model availability expands across C-segment and D-segment offerings.
- Buses:Urban transit agencies specify battery electric or fuel cell powertrains for route electrification mandates. German and Dutch municipal operators are retiring diesel fleets ahead of EU Green Deal deadlines.
- Trucks:Regional distribution and long-haul segments split between battery electric for sub-300km routes and hydrogen fuel cells for extended corridors.
- Two-Wheelers:Electric scooters and motorcycles capture urban mobility demand in dense Asian cities where parking constraints favor compact formats.
Buses carry the dominant procurement volume; two-wheelers are expanding most quickly as battery costs drop below internal combustion parity.
Technology:
Cost tier and infrastructure maturity stratify adoption curves across hybrid, plug-in, and full-electric architectures.
- Hybrid:Parallel and series-hybrid systems bridge infrastructure gaps for fleet operators in markets with unreliable grid capacity. Japanese and Southeast Asian commercial fleets retain hybrid share for route flexibility.
- Plug-in Hybrid:Larger battery packs enable 50-80 kilometer electric-only range for urban commuting while preserving combustion range security. European company car fleets favor plug-in hybrids during benefit-in-kind tax transition periods.
- Battery Electric:Pure electric drivetrains capture manufacturing investment as cell costs compress and charging networks densify. Cell-to-pack designs from China's Yangtze River Delta corridor are accelerating cost parity.
- Fuel Cell:Proton-exchange membrane stacks convert hydrogen to electricity for applications where refueling speed outweighs infrastructure capital requirements.
Battery electric commands the steepest expansion trajectory; hybrid retains defensive positioning in infrastructure-constrained geographies.
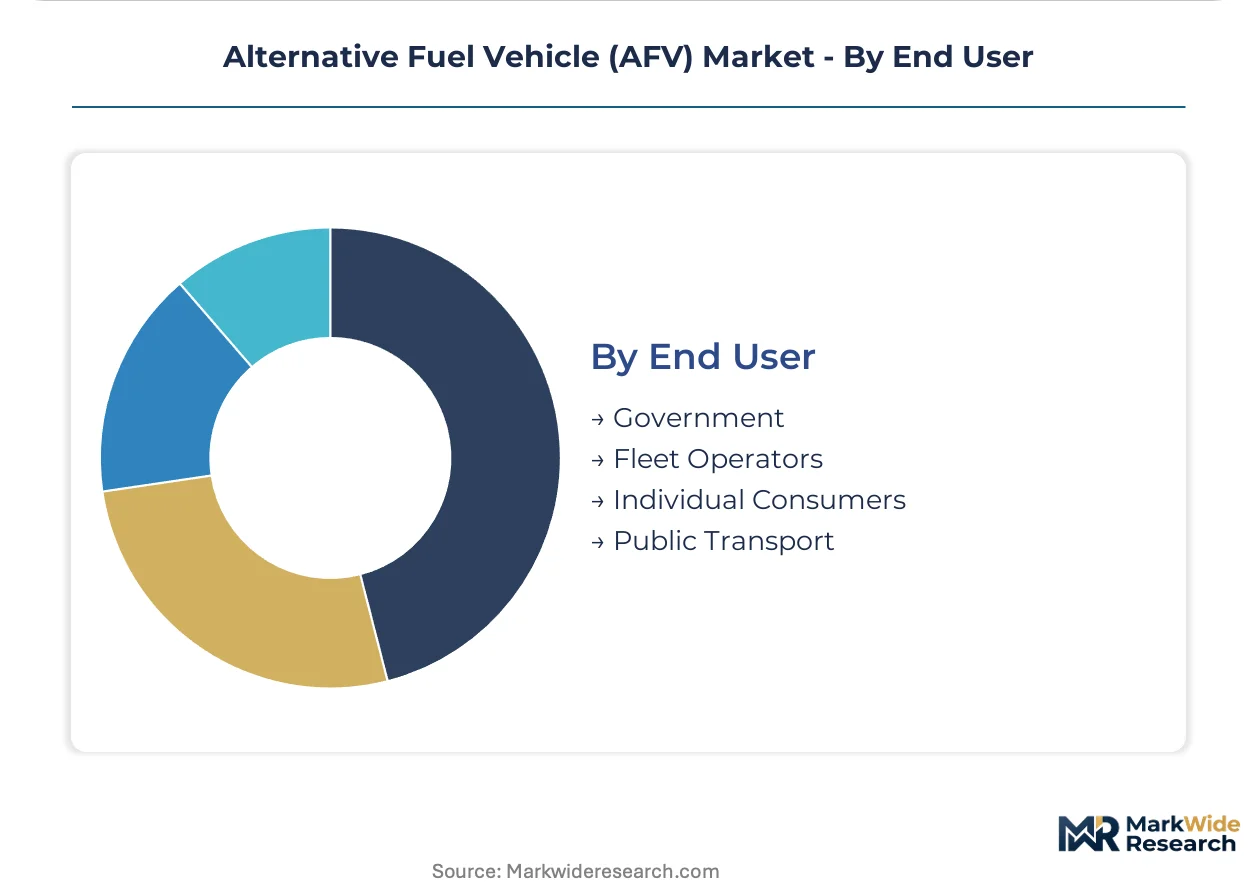
End User:
Procurement authority and total cost visibility determine technology selection across institutional, commercial, and retail buyers.
- Government:Municipal and national procurement mandates specify zero-emission powertrains for public sector fleets. German federal contracts require battery electric or hydrogen fuel cell vehicles for new acquisitions.
- Fleet Operators:Logistics and delivery companies internalize fuel, maintenance, and residual value economics across multi-year holding periods. California drayage operators are consolidating procurement around uptime-guaranteed electric platforms.
- Individual Consumers:Retail buyers prioritize purchase price, charging convenience, and model availability over lifecycle cost optimization. Range anxiety diminishes as 400+ kilometer EPA-rated vehicles enter mass-market segments.
- Public Transport:Transit agencies combine federal formula funds with state clean air subsidies to electrify bus and rail feeder services.
Fleet operators drive the dominant procurement volume; government buyers are gaining share fastest as procurement mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing capacity concentrates in China's Yangtze River Delta, while demand dispersion across Germany, the United States, and India creates parallel investment corridors. Regulatory arbitrage between jurisdictions shapes factory location decisions as subsidy phase-outs redirect capital toward emerging production clusters.
China
Jiangsu and Zhejiang provinces drive cost compression through integrated cell-to-pack manufacturing that eliminates module housings. MIIT's new-energy vehicle credit system mandates minimum production quotas for zero-emission platforms. Shenzhen-based BYD anchors vertical integration from lithium refining to finished buses, while Shanghai-Tesla's gigafactory sustains cathode supply for North American export.
Germany
Municipal transit agencies in Berlin, Hamburg, and Munich accelerate fleet electrification ahead of EU Green Deal deadlines. KBA certification requirements and carbon-border adjustments force powertrain portfolio diversification across OEM lineups. Bavaria's automotive corridor hosts solid-state electrolyte research facilities targeting next-generation fuel cell commercialization.
United States
California's drayage trucking and last-mile delivery segments consolidate procurement around uptime-guaranteed electric platforms. EPA tailpipe standards and NHTSA crashworthiness protocols force pack designers to satisfy thermal runaway containment while maintaining energy density. Nevada's gigafactory footprint sustains North American cathode supply amid reshoring incentives from the Inflation Reduction Act.
India
Maharashtra and Gujarat absorb FAME-II subsidy extensions for electric buses and two-wheelers through 2025. The heavy industry ministry expands purchase incentives as localized battery assembly opens demand for regional cell manufacturing. Delhi-NCR's fleet operators internalize total cost-of-ownership models that prioritize electricity rates over sticker price.
Japan
Commercial fleets in Tokyo and Osaka retain hybrid share for route flexibility amid unreliable grid capacity in peripheral regions. METI funding directs R&D budgets toward solid-state prototyping and silicon-anode insertion. Nagoya's industrial belt specializes in proton-exchange membrane stack conversion for heavy-duty applications where refueling speed outweighs infrastructure capital requirements.
Alternative Fuel Vehicle (AFV) Market Competitive Landscape
Vertically integrated battery specialists and legacy OEM powertrain divisions split the market between captive supply security and portfolio diversification imperatives. The structure favors scale-driven consolidation as module cost compression eliminates marginal cathode suppliers. Three archetypes dominate: integrated cell manufacturers controlling upstream refining, platform-agnostic drivetrain suppliers, and fleet-focused service bundlers. Competitive moves center on backward integration into lithium refining and direct-to-fleet sales channel establishment.
Within the integrated manufacturing tier, BYD Company Limited and Tesla exemplify archetypes of upstream control and gigafactory-scale production respectively. Toyota Motor Corporation occupies a position within the advanced chemistry research segment, anchoring solid-state electrolyte development for next-generation platforms. These three entities represent distinct strategic postures: Chinese vertical integration, American manufacturing footprint expansion, and Japanese materials science specialization.
| Leading Market Players |
|---|
| Tesla |
| BYD Company Limited |
| Toyota Motor Corporation |
| Volkswagen AG |
| General Motors |
| BMW Group |
| Ford Motor Company |
| Hyundai Motor Company |
| Mercedes-Benz Group AG |
| Others |
Pricing and Supply Chain Analysis
China's Fujian and Hunan provinces concentrate over 70% of refined cobalt and nickel sulfate processing capacity, anchoring margin capture upstream while OEMs downstream absorb lithium carbonate volatility through long-term offtake contracts or pass-through pricing clauses.
Pricing Analysis
EU Green Deal carbon-border adjustments dictate the pricing tier structure across the alternative fuel vehicle value chain. Three-tier pricing structure across premium, standard, and economy levels separates solid-state equipped platforms from lithium-iron-phosphate mass-market offerings and legacy hybrid architectures. Cost compression in the standard tier is intensifying because cell-to-pack manufacturing eliminates module housings. Fleet operators exhibit the highest price sensitivity as they internalize total cost-of-ownership models, while luxury OEMs retain pricing power through silicon-anode range differentiation.
Supply Chain Analysis
Lithium spodumene concentrate from Australian hard-rock mines and Chilean brine evaporation ponds feeds cathode precursor production. The supply chain draws from China for cell manufacturing, South Korea for separator films, and Japan for electrolyte formulations. Single-source vulnerability in Chinese refined metal processing creates tariff exposure under carbon-border adjustment mechanisms. Distribution runs through direct-to-fleet contracting channels that bypass traditional dealership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alternative fuel vehicle market operates as a defensive-moat story where regulatory entrenchment through EU Green Deal mandates and California Air Resources Board standards creates switching costs that lock in incumbent positions.
For Market Incumbents: Pre-empt emerging solid-state entrants by accelerating silicon-anode qualification timelines and securing binding lithium offtake agreements with Australian and Chilean concentrate producers. BYD-style backward integration into lithium refining represents the priority defensive lever against cathode precursor concentration risk.
For New Entrants and Emerging Players: Establish a beachhead in India's FAME-II subsidized electric bus segment where localized battery assembly requirements create procurement advantages for regional assemblers. Direct-to-fleet battery-as-a-service contracting offers the most penetrable go-to-market angle against entrenched OEM captive finance arms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed charging infrastructure operators and fleet management platforms consolidating around vehicle-to-grid integration capabilities. Five-to-ten year viability hinges on utility deregulation progress enabling bidirectional revenue streams. Watch California H2Hubs program funding disbursement velocity as the inflection signal for hydrogen corridor commercialization.
| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Manufacturing Scale-Up | Jiangsu and Zhejiang producers achieve 15-20% cost reduction through module elimination. |
| Solid-State Electrolyte R&D Partnership | Toyota's ceramic sulfide research delays commercial timelines but extends range targets. |
| Direct-to-Fleet Sales Channel | Battery OEMs bypass dealerships to contract with California drayage operators directly. |
| Vehicle-to-Grid Software Integration | Bidirectional charging transforms parked electric fleets into grid stabilization assets. |
| Lithium Refining Backward Integration | BYD's captive supply from mine to finished bus insulates against carbonate spot volatility. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, municipal transit fleet managers, and charging infrastructure developers anchored the qualitative base. Primary interviews combined with secondary validation against MIIT production databases, EPA certification filings, EU Green Deal implementation trackers, and IHS Markit vehicle registration data. Bottom-up cell cost modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing around lithium carbonate price bands and subsidy phase-out timelines structured the analytical framework across the analysis window. Segmentation dimensions modeled include propulsion architecture, vehicle class, battery chemistry tier, and regional production cluster. CAGRs derived from installed base turnover rates and fleet replacement cycle analysis incorporated silicon-anode adoption curves and hydrogen corridor infrastructure buildout assumptions.
Sensitivities concentrate around Chilean and Australian concentrate supply disruptions, EU carbon-border adjustment tariff rate finalization, and solid-state electrolyte pilot yield improvements. Cross-checking against IEA global EV outlook benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
India CNG Market