
 Mexico 3PL Market | 2026-2036
Mexico 3PL Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico 3PL Market Outlook
The shift from captive fleet ownership toward multi-source outsourced logistics is realigning capital deployment across Mexican supply chains. CEVA Logistics leverages its automotive sector specialization to dominate contract logistics in Guanajuato and Nuevo León. DHL Supply Chain sustains dense warehousing networks around Mexico City and Tijuana, anchoring cross-border fulfillment capacity. Traxión competes aggressively in dedicated trucking, controlling last-mile lanes that connect Bajío manufacturing clusters to Laredo border crossings.
Third-party logistics in Mexico encompasses transportation management, warehousing operations, freight forwarding, and value-added packaging services executed under contracted service-level agreements with asset-light or hybrid asset ownership structures. The primary purpose centers on reducing logistics costs while improving inventory velocity for manufacturers and retailers operating in nearshored production environments. Transportation services anchor the largest revenue pool given Mexico's extensive over-the-road freight network, though warehousing commands superior margins as industrial vacancy rates tighten in Monterrey and Querétaro. E-commerce client types represent the fastest-expanding demand segment, with digital platforms reshaping fulfillment expectations toward same-day and next-day delivery benchmarks.
Mexico's Federal Economic Competition Commission (COFECE) monitors logistics market concentration, while the Tax Administration Service (SAT) enforces electronic invoicing and customs documentation standards that directly shape 3PL technology investments. NOM standards for cargo security and hazardous materials transport further filter market access, favoring providers with certified operating protocols. Stakeholders must weigh whether to build speculative warehousing in secondary corridors or secure long-term leases in supply-constrained primary markets before infrastructure bottlenecks harden into structural cost disadvantages.
Market Dynamics
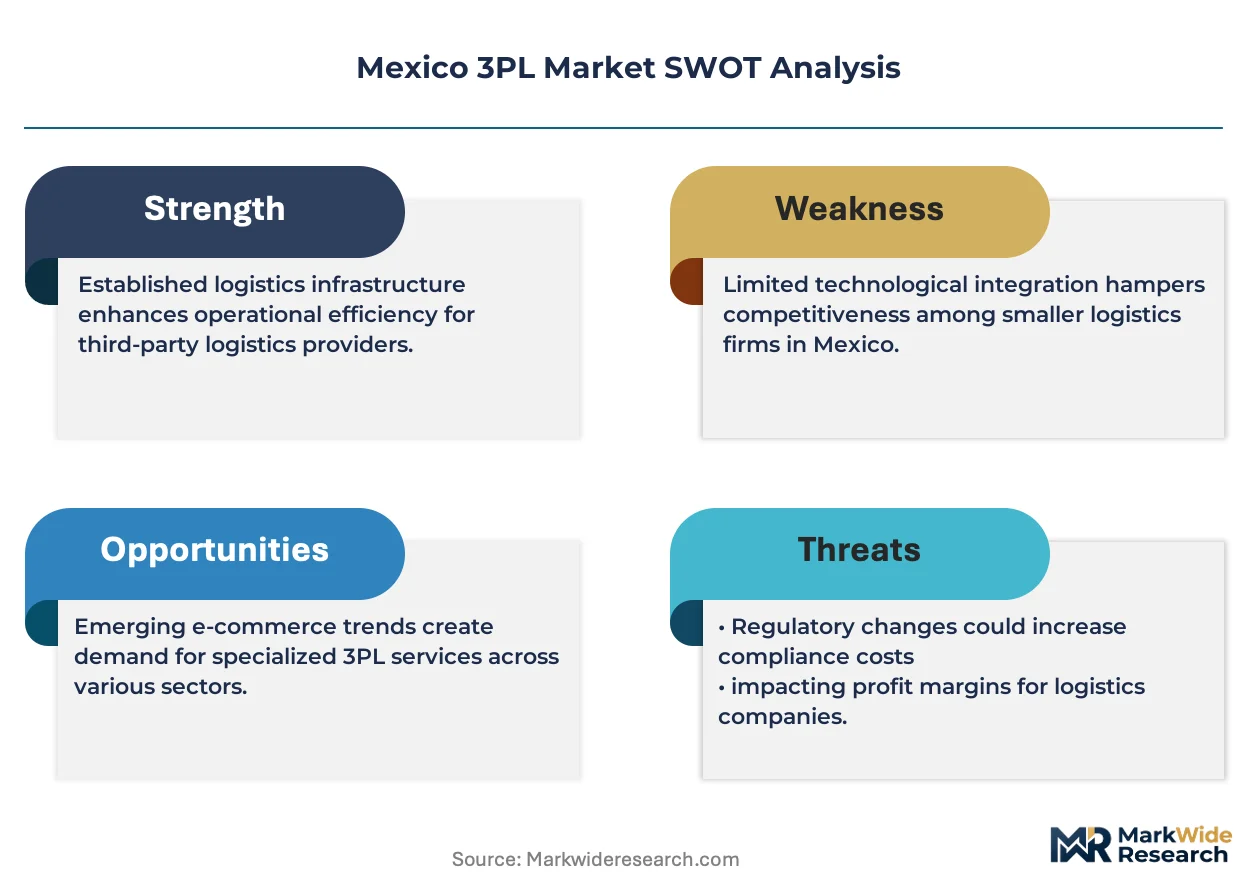
Nearshoring production shifts from Asia are compressing lead times and forcing automotive and electronics manufacturers to rebuild supply chain footprints around Mexican manufacturing clusters. The SAT's customs modernization mandates are simultaneously accelerating digitization investments across freight forwarding and warehousing operations.
Growth Catalysts
- Baja California Automotive Clustering:OEM expansion in Tijuana and Mexicali is generating dedicated contract logistics demand for cross-border component flows and finished vehicle distribution.
- SAT Electronic Invoicing Mandates:The Tax Administration Service's CFDI 4.0 requirements are pushing mid-market freight operators toward certified 3PL platforms with integrated compliance architecture.
- Querétaro-Aeropuerto Corridor Development:Aerospace supplier densification around Querétaro Intercontinental Airport is creating specialized warehousing demand for temperature-controlled and high-value inventory.
Market Restraints
- Diesel Price Volatility:Fuel represents 35-40% of trucking operating costs, and Pemex pricing adjustments transmit directly to contract rate negotiations without hedging mechanisms for smaller carriers.
- Monterrey Warehouse Scarcity:Industrial vacancy rates below 3% in Nuevo León's primary logistics zones are compressing expansion options for providers without pre-secured land positions.
- Driver Shortage Structural Gap:The aging workforce and limited vocational pipeline for commercial license certification are tightening capacity across long-haul lanes to Laredo and Nogales.
Strategic Opportunities
- Guadalajara E-commerce Fulfillment:Jalisco's underdeveloped industrial base relative to demand growth offers first-mover positioning for automated last-mile facilities serving central Mexico.
- CEPAL Logistics Integration Framework:UN Economic Commission for Latin America and the Caribbean regional harmonization initiatives are reducing cross-border friction for multimodal operators.
- IoT-Telematics Convergence:Real-time cargo monitoring combined with predictive maintenance platforms is enabling outcome-based pricing models for high-value automotive and pharmaceutical shipments.
Industry Challenges
- WMS-TMS Integration Complexity:Legacy on-premise warehouse management systems at mid-tier manufacturers resist API connectivity with cloud-based transportation platforms, delaying unified visibility deployments.
- Certified Operator Talent Scarcity:NOM-006-SCT2-2017 hazardous materials certification and SAT customs broker licensing face multi-month backlogs, constraining operational scaling for specialized service lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico 3PL Market |
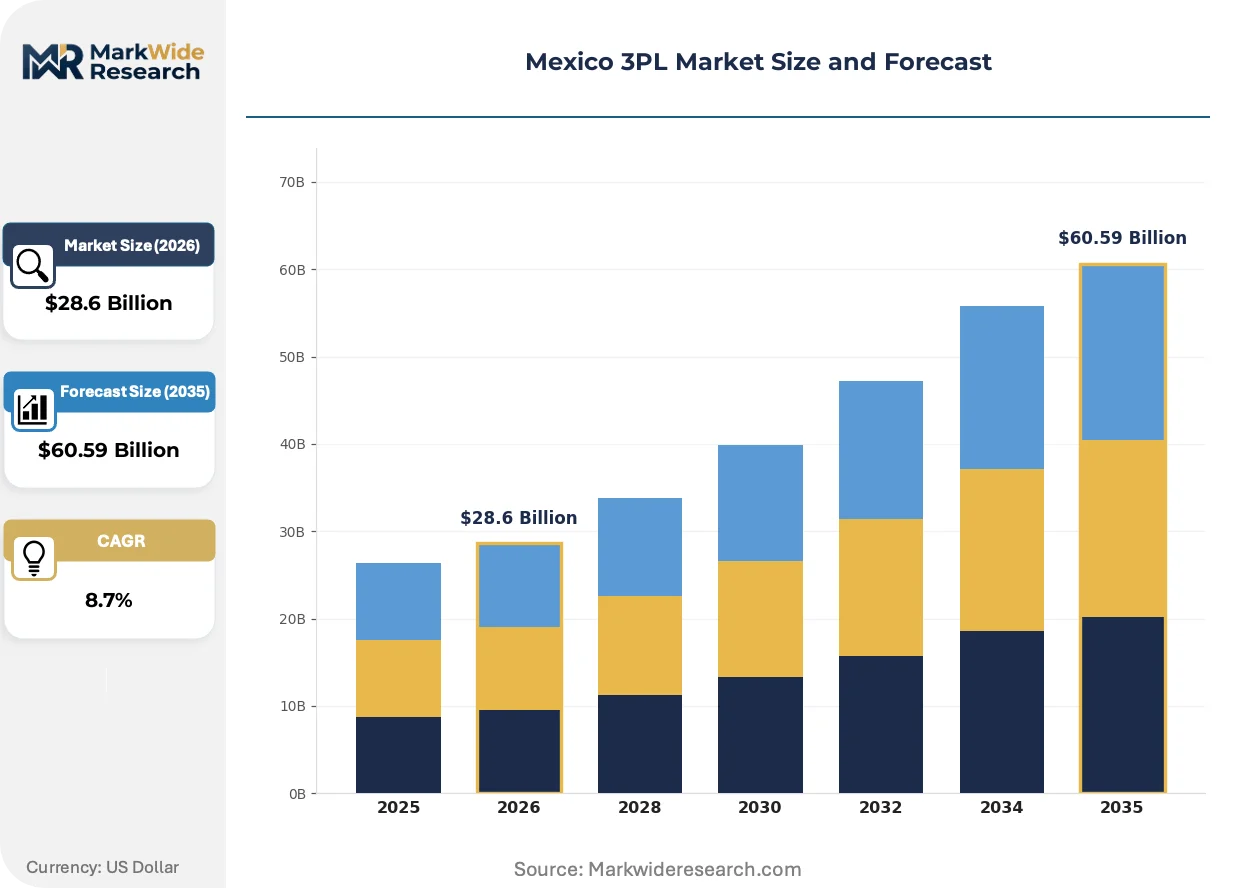
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Freight Forwarding Industry Vertical: Retail, Automotive, Pharmaceuticals, Electronics Client Type: Small Enterprises, Large Corporations, E-Commerce, Manufacturers Distribution Channel: Direct Shipping, Third-Party Logistics, Cross-Docking, Digital Platforms |
| Companies Covered | CEVA Logistics, GEODIS, DHL Supply Chain, XPO Logistics, DSV, Solistica, Kuehne + Nagel, C.H. Robinson, Traxión, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico 3PL Market Strategic Shifts
Digital freight platforms and warehouse automation are compressing cost structures while redefining service-level expectations across Mexican supply chains. Technology deployment is accelerating fastest where nearshoring volumes intersect with customs complexity.
Autonomous mobile robots in warehousing are integrating pallet movement and sortation workflows previously handled by manual forklift operations. E-commerce fulfillment centers in Toluca and Puebla are deploying these systems at 18-24 month payback periods. The technology is integrating pick-and-pack throughput with same-day delivery commitments that manual operations cannot sustain.
SAT's 2023-2024 customs technology modernization roadmap mandates pre-arrival cargo data submission and risk-based inspection protocols. Electronics and automotive manufacturers face accelerated documentation requirements that favor 3PLs with bonded warehouse certifications and dedicated customs brokerage units. The Nuevo León-Coahuila manufacturing belt is responding with concentrated investments in SAT-certified fiscal warehouses.
Shippers are consolidating vendor relationships around integrated service providers capable of managing cross-border freight, customs clearance, and last-mile distribution under single accountability structures. Fragmented single-service trucking contracts are losing share to multi-year managed transportation agreements with penalty-backed performance metrics. This concentration is most visible among medical device manufacturers operating maquiladora facilities in Tijuana and Ciudad Juárez.
Mexico 3PL Market Segmentation
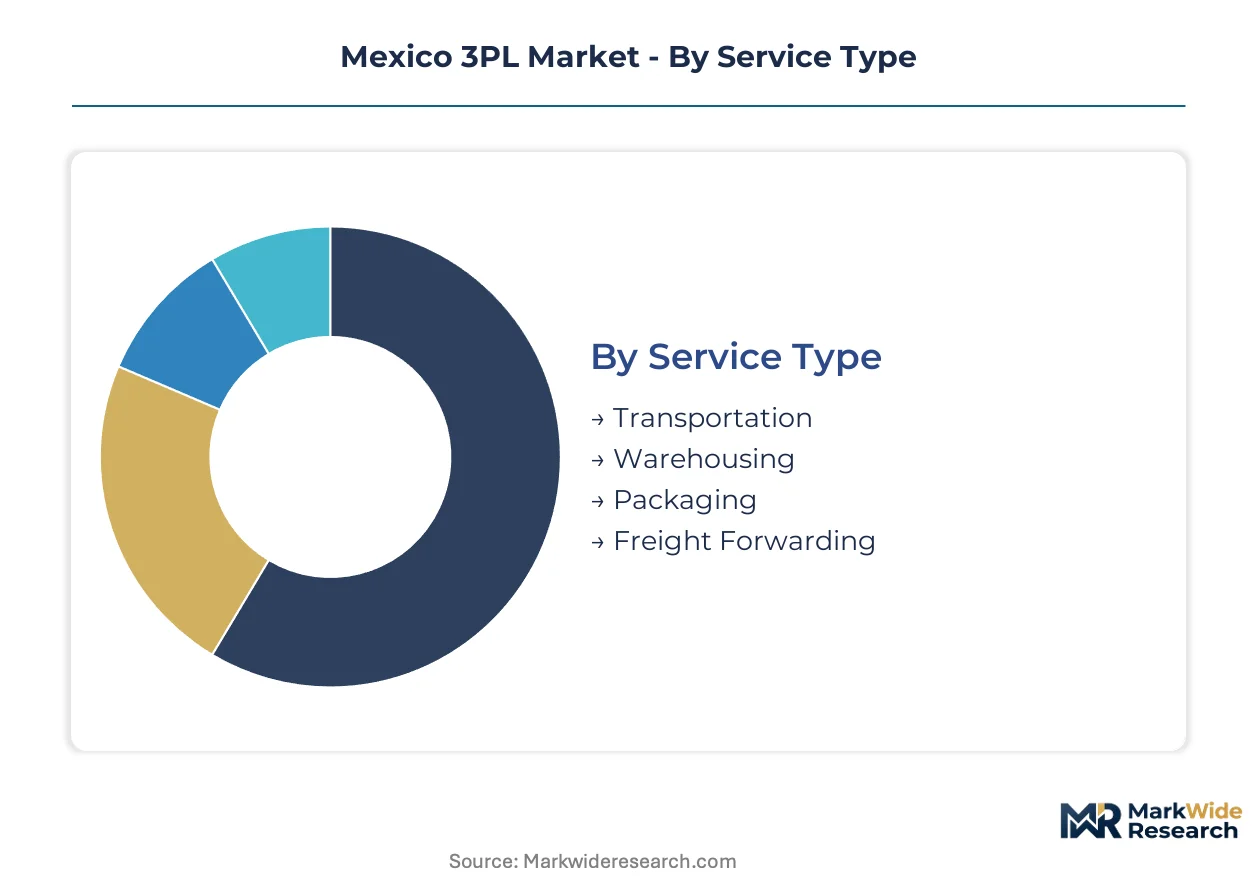
Service specialization determines capital allocation and margin capture across Mexican 3PL operations. Segment boundaries blur where nearshoring clients demand integrated transportation-warehousing bundles rather than standalone contracts.
Service Type:
Transportation and warehousing absorb the heaviest upfront capital, with fleet acquisition and speculative industrial development requiring multi-million-peso commitments before revenue generation begins.
- Transportation:Dedicated trucking and drayage operations dominate revenue pools, with diesel-powered over-the-road networks connecting Bajío manufacturing clusters to Laredo border crossings. Asset-heavy providers face Pemex pricing volatility that transmits directly to contract rate renegotiations without hedging instruments.
- Warehousing:Temperature-controlled and bonded fiscal facilities command premium positioning in supply-constrained Monterrey and Querétaro corridors. SAT-certified operations require integrated CFDI 4.0 compliance architecture that filters out mid-tier competitors lacking technology scale.
- Packaging:Value-added kitting and postponement services support automotive sequencing and medical device sterilization workflows.
- Freight Forwarding:Customs brokerage and cross-border documentation management concentrate around Tijuana and Ciudad Juárez maquiladora zones.
Most installed capacity flows through transportation. Expansion is steepest in warehousing.
Industry Vertical:
Automotive and electronics manufacturers drive contract logistics volume, while pharmaceutical cold chain requirements enforce certification barriers that reshape competitive access.
- Automotive:OEM expansion across Baja California and Nuevo León generates dedicated contract logistics demand for just-in-time component sequencing and finished vehicle distribution. Tier-1 supplier densification around Guanajuato requires synchronized inbound-outbound inventory management.
- Electronics:Maquiladora facilities in Tijuana and Ciudad Juárez demand SAT-compliant bonded warehousing for semiconductor and consumer device flows. Pre-arrival cargo data submission mandates favor 3PLs with dedicated customs brokerage units.
- Retail:Department store and grocery distribution networks concentrate around Mexico City metropolitan demand density.
- Pharmaceuticals:Temperature-validated storage and GDP-compliant distribution face NOM certification requirements that constrain operator qualification pools.
Automotive anchors current revenue concentration. Electronics is climbing the fastest as nearshoring accelerates.
Client Type:
Enterprise scale dictates service model selection, with large corporations demanding multi-year managed transportation agreements while smaller shippers tolerate fragmented single-service contracts.
- Large Corporations:Integrated service requirements spanning cross-border freight, customs clearance, and last-mile distribution consolidate vendor relationships around providers with single-accountability structures and penalty-backed performance metrics.
- E-Commerce:Digital platforms in Guadalajara and Puebla are reshaping fulfillment expectations toward same-day and next-day delivery benchmarks that require automated sortation infrastructure.
- Manufacturers:Industrial shippers prioritize inventory velocity and landed cost reduction over pure transportation rate minimization.
- Small Enterprises:Price-sensitive spot market participation dominates, with limited contract commitment and minimal technology integration requirements.
Large corporations command the deepest contract penetration. E-commerce is gaining share fastest on fulfillment automation investments.
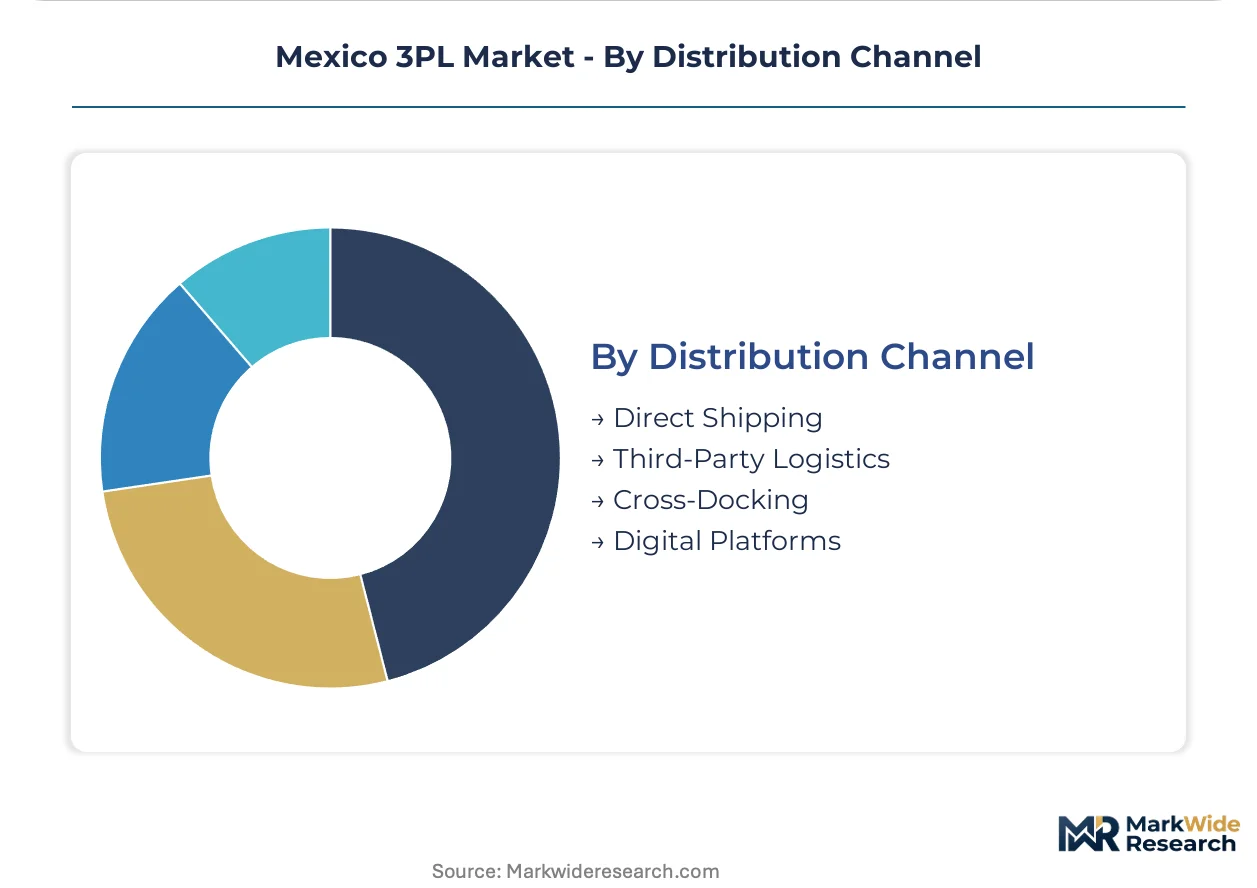
Distribution Channel:
Channel selection reflects inventory velocity requirements and customs complexity tolerance, with direct shipping declining where SAT documentation mandates favor intermediated flows.
- Third-Party Logistics:Multi-year outsourcing agreements consolidate transportation, warehousing, and value-added services under unified service-level frameworks that reduce coordination friction for manufacturers rebuilding supply chain footprints.
- Digital Platforms:Real-time freight matching and dynamic pricing engines are compressing spot market spreads and enabling outcome-based pricing for high-value automotive shipments.
- Direct Shipping:Captive fleet retention persists among Pemex and Cemex with sufficient volume density to justify in-house operations.
- Cross-Docking:Flow-through facilities minimize inventory holding costs for fast-moving consumer goods with predictable demand patterns.
Third-party logistics channels carry the majority of outsourced volume. Digital platforms are expanding most quickly on telematics convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bajío automotive corridor anchors Mexican 3PL demand concentration, with Guanajuato and Querétaro generating contract logistics volume from tier-1 supplier densification. SAT customs modernization and nearshoring production shifts are redistributing warehousing investment across five distinct sub-regional markets.
Mexico City Metropolitan Area
E-commerce fulfillment demand from digital platforms is compressing industrial vacancy rates below 4% across Toluca and Cuautitlán Izcalli. SAT's CFDI 4.0 electronic invoicing mandates favor 3PLs with integrated compliance architecture. Automated sortation facilities in the Mexico State corridor are absorbing capital commitments from providers targeting same-day delivery benchmarks.
Nuevo León
Monterrey's sub-3% industrial vacancy rate is constraining expansion options for providers without pre-secured land positions. The state's proximity to Laredo border crossings generates dedicated trucking demand for automotive and electronics manufacturers. Apodaca and Escobedo warehouse clusters are commanding premium lease rates on bonded fiscal facility scarcity.
Baja California
OEM expansion in Tijuana and Mexicali is generating dedicated contract logistics demand for cross-border component flows. SAT-certified fiscal warehouses are concentrating around maquiladora zones to manage pre-arrival cargo data submission requirements. Electronics manufacturers are consolidating vendor relationships around integrated service providers with customs brokerage units.
Jalisco
Guadalajara's underdeveloped industrial base relative to e-commerce demand growth offers first-mover positioning for automated last-mile facilities. The Querétaro-Aeropuerto aerospace supplier densification is creating specialized warehousing demand for temperature-controlled inventory. Jalisco's central Mexico location is attracting distribution network investments serving secondary corridors.
Northern Border States
Ciudad Juárez and Nuevo Laredo are anchoring cross-border freight consolidation for automotive and medical device manufacturers. Driver shortage pressures are tightening capacity across long-haul lanes connecting Bajío production clusters to US border crossings. Chihuahua and Coahuila are responding with concentrated investments in SAT-certified fiscal warehouses.
Mexico 3PL Market Competitive Environment
Established providers occupy the integrated service tier; emerging entrants pursue specialized vertical niches. The market structures around three distinct maturity tiers: global network operators with Mexican subsidiaries, regional Mexican specialists with asset-heavy fleet positions, and digital freight platforms compressing spot market spreads. Strategic archetypes include automotive-focused contract logistics specialists, cross-border customs brokerage integrators, and e-commerce fulfillment automation providers. Dominant competitive moves center on long-term warehouse lease pre-commitments in supply-constrained corridors and multi-year managed transportation agreements with penalty-backed performance metrics.
Within the integrated global tier, CEVA Logistics and DHL Supply Chain exemplify providers with automotive sector specialization and dense warehousing networks. Among Mexico-based operators, Traxión occupies a position representing dedicated trucking and last-mile lane control. These three anchors illustrate the competitive tension between global compliance scale and regional asset ownership.
| Leading Market Players |
|---|
| CEVA Logistics |
| GEODIS |
| DHL Supply Chain |
| XPO Logistics |
| DSV |
| Solistica |
| Kuehne + Nagel |
| C.H. Robinson |
| Traxión |
| Others |
Value Chain & Pricing Dynamics
Horizontal outsourcing partnerships anchor both supply positioning and pricing power across Mexican logistics networks. Shifting from captive fleet ownership toward multi-source contracted arrangements concentrates volume with providers holding SAT-certified fiscal warehouse assets and bonded customs infrastructure, compressing margins for asset-light operators lacking compliance scale.
Pricing Analysis
Diesel cost pass-through dominates contract rate negotiations, with Pemex pricing adjustments transmitting directly to transportation agreements without hedging mechanisms for smaller carriers. Three-tier pricing structure across premium bonded facilities, standard dry warehousing, and economy spot trucking segments reflects certification level and customs integration depth. Cost compression in economy trucking intensifies because driver shortage pressures constrain capacity expansion. Small enterprises exhibit highest price sensitivity, while automotive OEMs prioritize inventory velocity over pure rate minimization.
Supply Chain Analysis
Direct-to-maquiladora channels handle hyperscale electronics and automotive demand across Tijuana and Ciudad Juárez manufacturing zones. Manufacturing inputs draw from China, South Korea, and Germany for semiconductors, precision components, and production equipment. Single-source vulnerability concentrates in long-haul diesel trucking connecting Bajío production clusters to Laredo border crossings. Distribution runs through SAT-certified fiscal warehouses with integrated customs brokerage units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's logistics market functions as a geographic-arbitrage play capturing US-Mexico cost differentials in labor and transportation, amplified by SAT customs modernization compressing cross-border lead times versus Asian alternatives.
For Market Incumbents: Deepen vertical control over scarce warehousing positions in Monterrey and Querétaro corridors through long-term lease pre-commitments before industrial vacancy rates harden structural cost disadvantages. Secure certified operator talent pipelines for NOM-006-SCT2-2017 hazardous materials and SAT customs broker licensing to constrain emerging competitor scaling. Invest in IoT-telematics convergence platforms enabling outcome-based pricing for high-value automotive shipments.
For New Entrants and Emerging Players: Begin with Guadalajara e-commerce fulfillment automation targeting underdeveloped industrial base relative to central Mexico demand growth. Capture first-mover positioning in automated last-mile facilities serving digital platforms with same-day delivery benchmarks. Pursue aerospace supplier specialization around Querétaro Intercontinental Airport corridor for temperature-controlled warehousing differentiation.
For Investors and Strategic Acquirers: Roll-up economics work for regional Mexican trucking specialists because driver shortage structural gaps and fragmented single-service contracts favor consolidated platforms with technology scale. Target mid-market freight operators facing SAT CFDI 4.0 compliance pressure as acquisition candidates. Watch CEPAL regional harmonization implementation as inflection indicator for cross-border multimodal operator viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Warehouse Lease Pre-Commitment | Secures scarce industrial positions in Monterrey's sub-3% vacancy environment before rate escalation. |
| Customs Brokerage Integration | Captures SAT-certified fiscal warehouse demand from electronics manufacturers facing pre-arrival data mandates. |
| Telematics Platform Deployment | Enables outcome-based pricing models for automotive OEMs requiring real-time cargo visibility. |
| Automated Fulfillment Buildout | Addresses Guadalajara e-commerce demand with 18-24 month robot payback periods. |
| Certified Operator Pipeline | Resolves multi-month NOM and SAT licensing backlogs constraining specialized service scaling. |
Study Parameters
Multiple input streams — executive interviews with 3PL operations directors and customs brokerage heads, freight forwarder transaction records, and SAT regulatory filings — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged logistics procurement managers at automotive OEMs, e-commerce platform supply chain leads, and industrial real estate developers across Mexico City, Monterrey, and Guadalajara corridors. Secondary validation incorporated customs trade databases, COFECE competition monitoring reports, and carrier fleet registration records.
Data-stream reconciliation across service type, industry vertical, and regional production cluster dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by revenue concentration in transportation and warehousing operations. Forecast inputs included nearshoring production shift velocity, SAT technology modernization implementation pace, and industrial vacancy rate elasticity across primary logistics zones.
Several conditions sit outside the modeled scope, including Pemex pricing policy discontinuities, USMCA renegotiation outcomes, and acute peso volatility episodes. Forecasts reflect assumptions about sustained nearshoring momentum and customs digitization compliance timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Chile Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
Latin America Fourth Party Logistics (4PL) Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
US Mexico Cross Border FTL Freight Transport Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
Global Retail 3PL Market
Logistics and Shipping
Cross-Border Logistics Services Market