
 Hydrogen Internal Combustion Engine (ICE) Market | 2026-2036
Hydrogen Internal Combustion Engine (ICE) Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Internal Combustion Engine (ICE) Market Insights
Fleet operator procurement is pivoting from fragmented pilot programs toward consolidated multi-year supply agreements with engine builders. Cummins Inc. leverages its existing diesel service network to position hydrogen ICE retrofit kits for Class 8 trucks. MAN Energy Solutions anchors large-bore marine and stationary applications through dual-fuel architecture development. Toyota Motor Corp. competes in light-duty prototypes by extending its hydrogen combustion expertise from motorsport validation programs.
A hydrogen internal combustion engine burns hydrogen fuel in a modified reciprocating piston assembly, typically operating at compression ratios between 12:1 and 15:1 with port or direct injection to manage pre-ignition and NOx formation. The technology serves as a near-zero-carbon propulsion option for sectors where battery electrification faces weight or duty-cycle constraints. Dual-fuel configurations currently lead commercialization timelines because they preserve diesel fallback capability during hydrogen infrastructure gaps. Marine applications represent the fastest-growing segment category as International Maritime Organization targets harden the business case for ammonia-hydrogen fuel blends in deep-sea vessels. Fleet operators command the deepest margin pools among end-user categories due to volume procurement and total-cost-of-ownership contracting structures.
The EPA and NHTSA shape US demand through heavy-duty greenhouse gas standards that credit hydrogen combustion pathways alongside fuel cells. The EU Green Deal and F-Gas Regulation tighten product standards by mandating CO2 benchmarks that diesel cannot meet without carbon-neutral fuels. Japan's METI supports technology leadership through hydrogen supply chain subsidies that cover ICE validation alongside fuel cell development. Stakeholders must monitor whether infrastructure build-out pace or engine durability certification becomes the binding constraint on deployment scale.
Market Dynamics
Fleet operators in heavy-duty trucking are consolidating fragmented pilot programs into multi-year supply agreements, compressing procurement timelines and forcing engine builders to certify hydrogen ICE platforms before infrastructure maturity. This demand-side concentration is reshaping competitive positioning around service network coverage and total-cost-of-ownership guarantees.
Growth Catalysts
- EU Green Deal emission ceilings:The regulation mandates CO2 benchmarks that diesel engines cannot achieve without carbon-neutral fuels, compelling commercial transport operators to evaluate hydrogen combustion retrofit pathways.
- Marine sector fuel blend demand:International Maritime Organization targets are hardening the business case for ammonia-hydrogen dual-fuel architectures in deep-sea vessels, creating volume anchors for large-bore engine development.
- Japan METI supply chain subsidies:These incentives cover ICE validation alongside fuel cell development, reducing technology risk for domestic manufacturers pursuing hydrogen combustion leadership.
Market Restraints
- Hydrogen production cost volatility:Electrolyzer capacity constraints and renewable electricity price swings create input cost uncertainty that undermines fleet operator total-cost-of-ownership modeling.
- German prototype cluster concentration:MAN Energy Solutions and DEUTZ AG anchor the majority of European large-bore development, creating geographic supply risk if certification delays emerge.
- Battery electrification substitution:Lithium-ion pack cost declines in light-duty segments threaten hydrogen ICE addressable market in applications below Class 6 truck weight classes.
Strategic Opportunities
- US heavy-duty greenhouse gas credit pathways:EPA and NHTSA standards credit hydrogen combustion alongside fuel cells, creating regulatory tailwind for Class 8 truck retrofits in California and Texas freight corridors.
- Dual-fuel distribution innovation:Engine builders can leverage existing diesel service networks for hydrogen ICE retrofit kit deployment, compressing channel establishment timelines versus fuel cell infrastructure requirements.
- Stationary power generation convergence:Hydrogen ICE gensets are penetrating data center backup power applications where battery duration limitations and fuel cell capital costs create white space.
Industry Challenges
- NOx aftertreatment certification timelines:Port and direct injection architectures require emissions validation protocols that lag diesel equivalent approval cycles, delaying fleet operator deployment schedules.
- Hydrogen storage system integration complexity:Cryogenic and compressed gas tank packaging competes for chassis space with existing diesel tank configurations, demanding custom frame rail modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Internal Combustion Engine (ICE) Market |
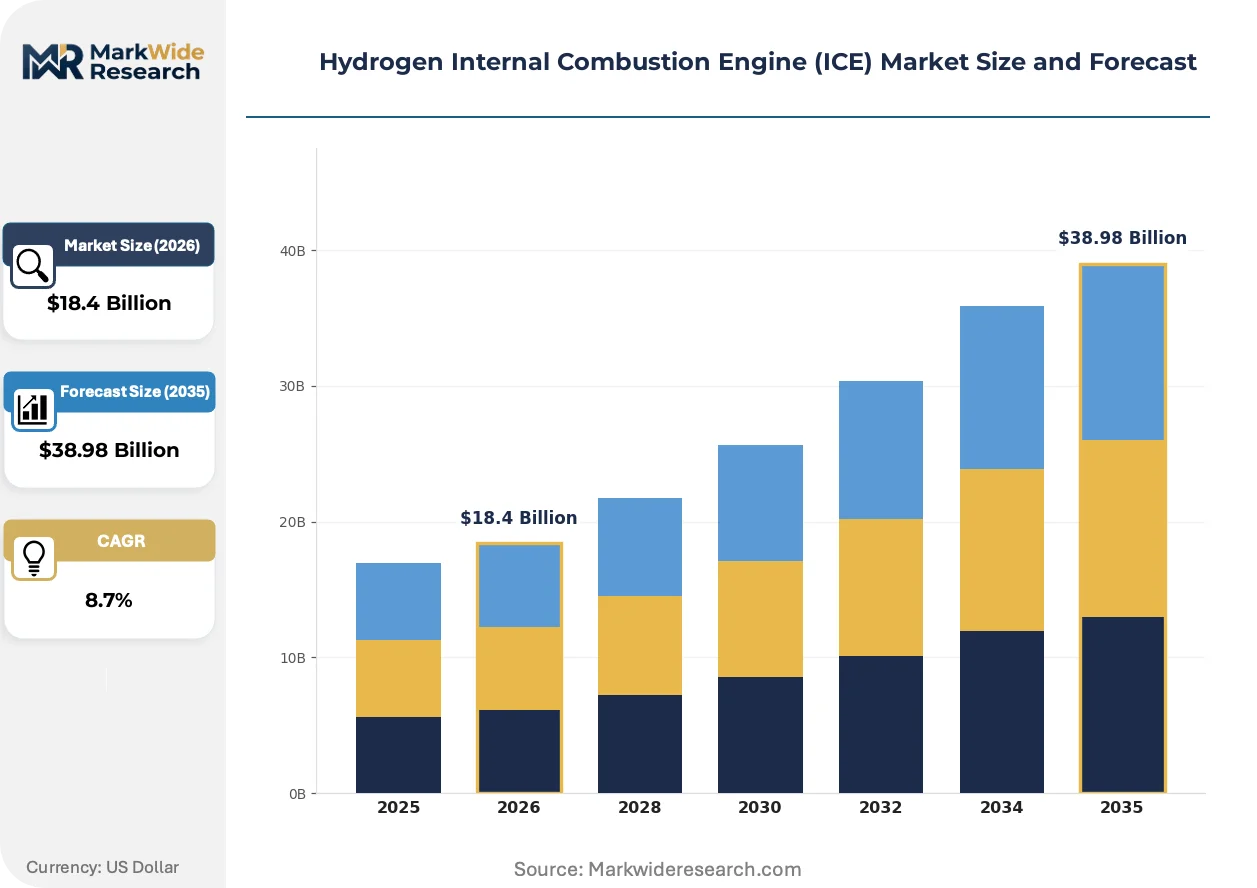
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Dual-Fuel, Conventional, Homogeneous Charge, Direct Injection Application: Automotive, Marine, Power Generation, Industrial End User: Fleet Operators, Private Owners, Public Transport, Agriculture Distribution Channel: Dealerships, Online Platforms, Auctions, Direct Sales |
| Companies Covered | Cummins Inc., MAN Energy Solutions, Honda Motor Co., Toyota Motor Corp., Hyundai Motor Co., DEUTZ AG, Wärtsilä, Garrett Motion Inc., Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Internal Combustion Engine (ICE) Market Trends and Innovations
Engine architecture choices are bifurcating between dedicated hydrogen combustion and dual-fuel fallback systems, with adoption pace determined by infrastructure density in specific freight corridors rather than technology maturity alone.
Dual-fuel hydrogen-diesel injection systems are converging with marine propulsion requirements as ship operators seek compliance flexibility during port fuel availability transitions. Deep-sea vessel operators in European and East Asian routes are piloting these configurations ahead of International Maritime Organization 2030 benchmarks. The technology is converging with ammonia carrier logistics, enabling single-engine platforms to burn hydrogen blends in coastal zones and conventional fuels in open ocean transit.
The EU F-Gas Regulation is tightening product standards for mobile machinery climate systems, indirectly pressuring engine thermal management architectures. Manufacturers must redesign cooling circuits to handle hydrogen combustion's distinct heat rejection profiles while maintaining refrigerant compliance. Marine and heavy-duty truck segments are responding with modular thermal packages that segregate hydrogen-specific components from legacy diesel cooling loops.
Fleet maintenance contracts are unbundling hydrogen ICE service from traditional diesel powertrain coverage, creating separate technician certification tracks. Heavy-duty trucking operators in Germany and the United States are demanding standalone hydrogen combustion service level agreements with guaranteed uptime penalties. This pattern is most visible in long-haul freight corridors where dual-fuel retrofits require specialized diagnostic equipment distinct from standard engine control module tooling.
Hydrogen Internal Combustion Engine (ICE) Market Segmentation
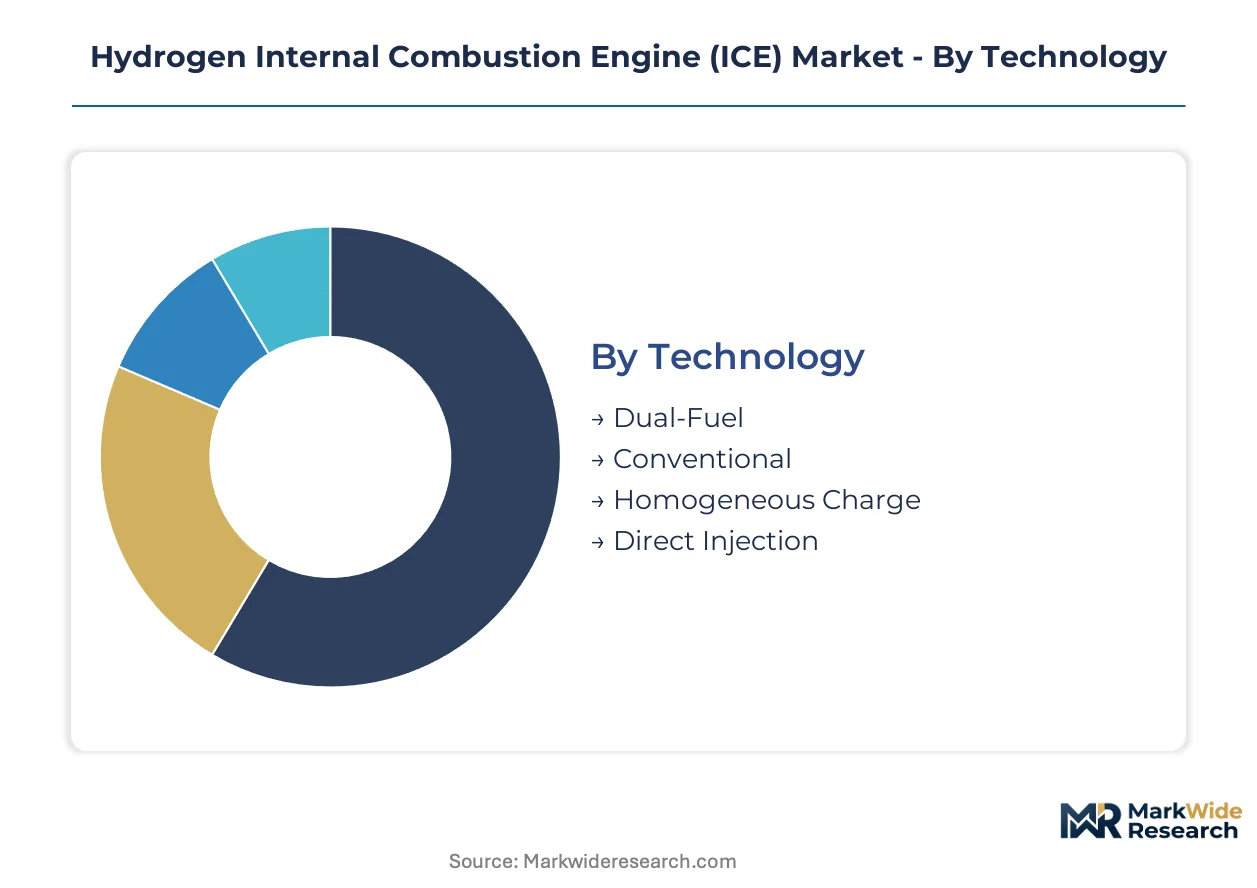
Hydrogen ICE architectures diverge sharply between embedded dual-fuel systems and dedicated hydrogen combustion platforms. Technology choices cascade through application suitability, end-user contracting structures, and channel economics.
Technology:
Standalone hydrogen combustion engines operate independently of diesel fallback, while embedded dual-fuel systems retain fossil compatibility during infrastructure gaps.
- Dual-Fuel:Combines hydrogen port injection with diesel pilot ignition, preserving operational continuity when hydrogen availability fluctuates. Marine operators on European coastal routes concentrate procurement here, driven by International Maritime Organization compliance deadlines that demand fuel flexibility during port transitions.
- Direct Injection:Delivers hydrogen at high pressure directly into the combustion chamber, enabling compression ratios above 14:1 for thermal efficiency gains. Fleet operators in Germany anchor demand for Class 8 truck retrofits, constrained by NOx aftertreatment certification timelines that lag diesel equivalent approval cycles.
- Conventional:Modified spark-ignition architectures adapted from natural gas engine platforms with reduced compression ratios.
- Homogeneous Charge:Premixed hydrogen-air intake systems prioritizing NOx minimization over peak power output.
Volume placements concentrate in Dual-Fuel; the faster expansion belongs to Direct Injection.
Application:
Cost tiers separate heavy-duty long-haul applications from lighter-duty cycles where battery economics compete more aggressively.
- Marine:Large-bore dual-fuel engines burning ammonia-hydrogen blends in deep-sea vessels. Ship operators in East Asian routes pilot these configurations ahead of regulatory benchmarks, with MAN Energy Solutions anchoring prototype clusters in Germany.
- Automotive:Light-duty passenger and commercial vehicles where Toyota Motor Corp. extends motorsport-validated combustion expertise. California freight corridors show contracting concentration, supported by EPA heavy-duty greenhouse gas credit pathways.
- Power Generation:Stationary gensets penetrating data center backup applications where battery duration limitations create white space.
- Industrial:Forklifts, mining equipment, and mobile machinery facing EU F-Gas Regulation thermal management compliance pressures.
Revenue concentration sits with Marine; Automotive climbs the fastest as infrastructure density improves in specific freight corridors.
End User:
Customer type determines contracting sophistication, with fleet operators commanding structured total-cost-of-ownership agreements versus fragmented private ownership.
- Fleet Operators:Heavy-duty trucking and marine shipping companies consolidating pilot programs into multi-year supply agreements. These buyers demand standalone hydrogen combustion service level agreements with guaranteed uptime penalties, compressing procurement timelines for engine builders.
- Public Transport:Municipal bus operators evaluating hydrogen ICE against fuel cell alternatives for route electrification. German cities anchor early deployment, leveraging METI-style supply chain subsidies for technology validation.
- Private Owners:Individual purchasers in light-duty segments where infrastructure immaturity limits addressable market.
- Agriculture:Farm operators seeking diesel alternatives for seasonal equipment with intermittent duty cycles.
Procurement gravity centers on Fleet Operators; Public Transport gains share fastest as municipal decarbonization mandates harden.
Distribution Channel:
Channel selection reflects installation complexity, with technical integration requirements favoring assisted purchase paths over self-service platforms.
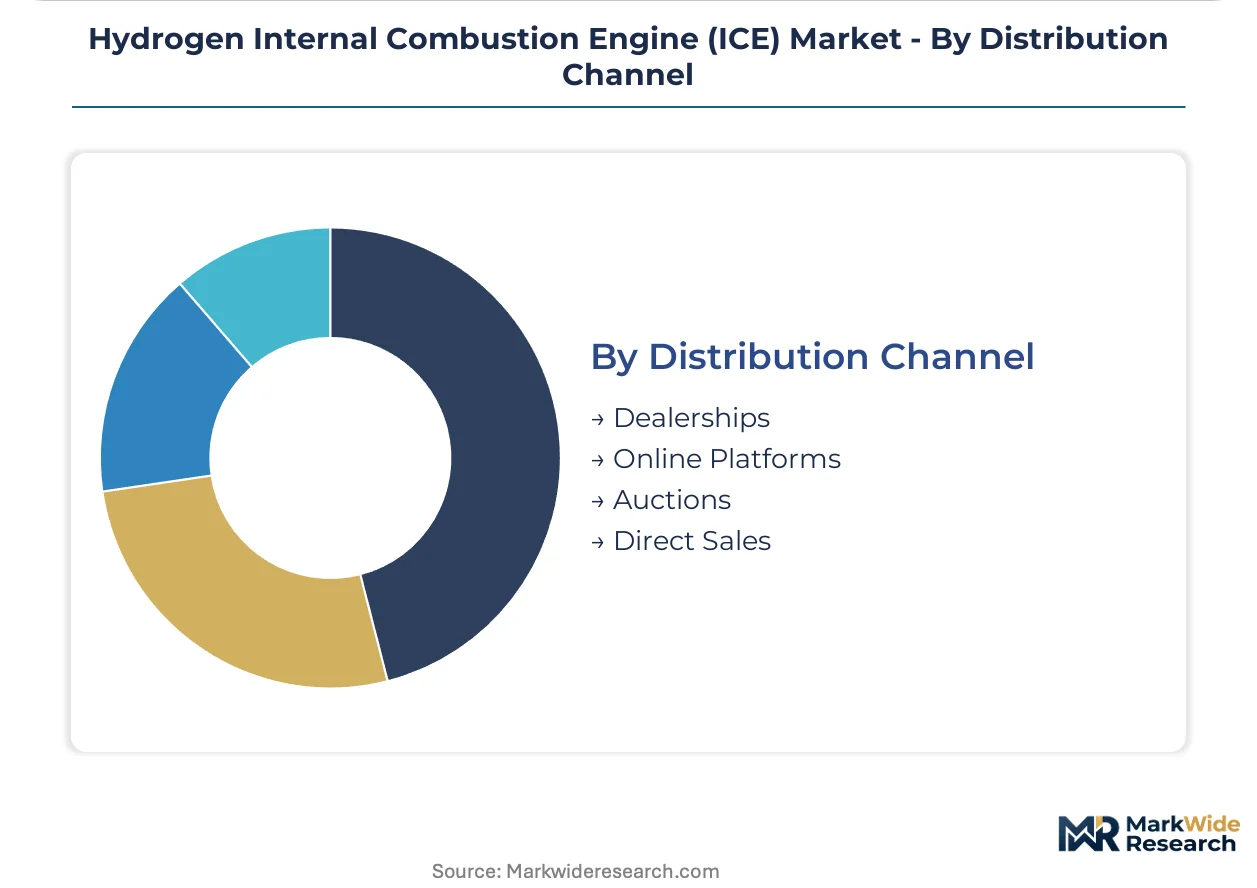
- Dealerships:Authorized service networks where Cummins Inc. leverages existing diesel infrastructure for hydrogen ICE retrofit kit deployment. Channel establishment timelines compress versus fuel cell requirements due to technician familiarity with reciprocating engine architectures.
- Direct Sales:Engine builder relationships with fleet operators for large-bore marine and stationary power applications. MAN Energy Solutions anchors this channel through dual-fuel architecture development contracts.
- Online Platforms:Digital procurement for standardized retrofit components and diagnostic tooling.
- Auctions:Secondary market disposition of prototype and validation fleet assets.
Transaction volume concentrates in Dealerships; Direct Sales expands most quickly as fleet procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Germany and the United States are consolidating procurement into multi-year supply agreements, compressing certification timelines for engine builders. This demand-side concentration is pulling manufacturing investment toward established industrial clusters with hydrogen infrastructure access.
Germany
Heavy-duty trucking fleets in North Rhine-Westphalia and Bavaria anchor European demand for Class 8 retrofit kits. The EU Green Deal and F-Gas Regulation mandate CO2 benchmarks that diesel engines cannot achieve without carbon-neutral fuels. MAN Energy Solutions and DEUTZ AG cluster large-bore prototype manufacturing in Augsburg and Cologne, validating dual-fuel architectures for marine and stationary applications.
United States
California and Texas freight corridors concentrate Class 8 truck pilot programs as fleet operators seek EPA greenhouse gas credit pathways. The EPA and NHTSA heavy-duty standards credit hydrogen combustion alongside fuel cells, creating regulatory tailwind for retrofits. Cummins Inc. leverages its existing diesel service network across the Midwest and Southeast to deploy hydrogen ICE retrofit kits.
Japan
Light-duty prototype development concentrates around Toyota Motor Corp.'s motorsport-validated combustion expertise. METI supply chain subsidies cover ICE validation alongside fuel cell development, reducing technology risk for domestic manufacturers. Nagoya and Tokyo metropolitan areas host validation fleets testing port injection architectures for commercial vehicle applications.
China
Marine engine builders in Shanghai and Dalian pilot ammonia-hydrogen dual-fuel configurations for deep-sea vessels ahead of International Maritime Organization 2030 benchmarks. The country's dual carbon goals pressure state-owned ship operators to evaluate hydrogen combustion pathways. Yangtze River Delta port clusters test bunkering infrastructure for hydrogen-ammonia fuel blends.
South Korea
Hyundai Motor Co. extends hydrogen expertise from fuel cell programs into ICE validation for commercial vehicle segments. The Seoul Capital Area concentrates fleet operator trials for municipal bus and refuse truck applications. Busan-Ulsan shipbuilding corridors evaluate large-bore hydrogen combustion for coastal vessel retrofits under tightening emission standards.
Hydrogen Internal Combustion Engine (ICE) Market Competitive Landscape
German producers anchor one tier of large-bore marine and stationary engine development; Japanese and South Korean specialists hold another tier focused on light-duty automotive validation. The market structure splits between consolidated large-bore engine builders with dual-fuel expertise and fragmented automotive specialists pursuing dedicated hydrogen combustion. Three archetypes dominate: incumbent diesel engine retrofitters leveraging service networks, marine propulsion specialists converging on ammonia-hydrogen blends, and automotive OEMs extending fuel cell adjacent technologies. Competitive moves center on strategic partnerships for hydrogen storage integration and geographic expansion into freight corridor clusters with bunkering infrastructure.
Among Germany-based fabricators, MAN Energy Solutions and DEUTZ AG occupy positions exemplifying the large-bore dual-fuel archetype, while Cummins Inc. represents the incumbent diesel retrofitter model leveraging established service networks. These three anchors illustrate how competitive positioning diverges between marine-stationary applications and on-road heavy-duty trucking, with each archetype demanding distinct certification timelines and channel economics.
| Leading Market Players |
|---|
| Cummins Inc. |
| MAN Energy Solutions |
| Honda Motor Co. |
| Toyota Motor Corp. |
| Hyundai Motor Co. |
| DEUTZ AG |
| Wärtsilä |
| Garrett Motion Inc. |
| Robert Bosch GmbH |
| Others |
Pricing and Supply Chain Analysis
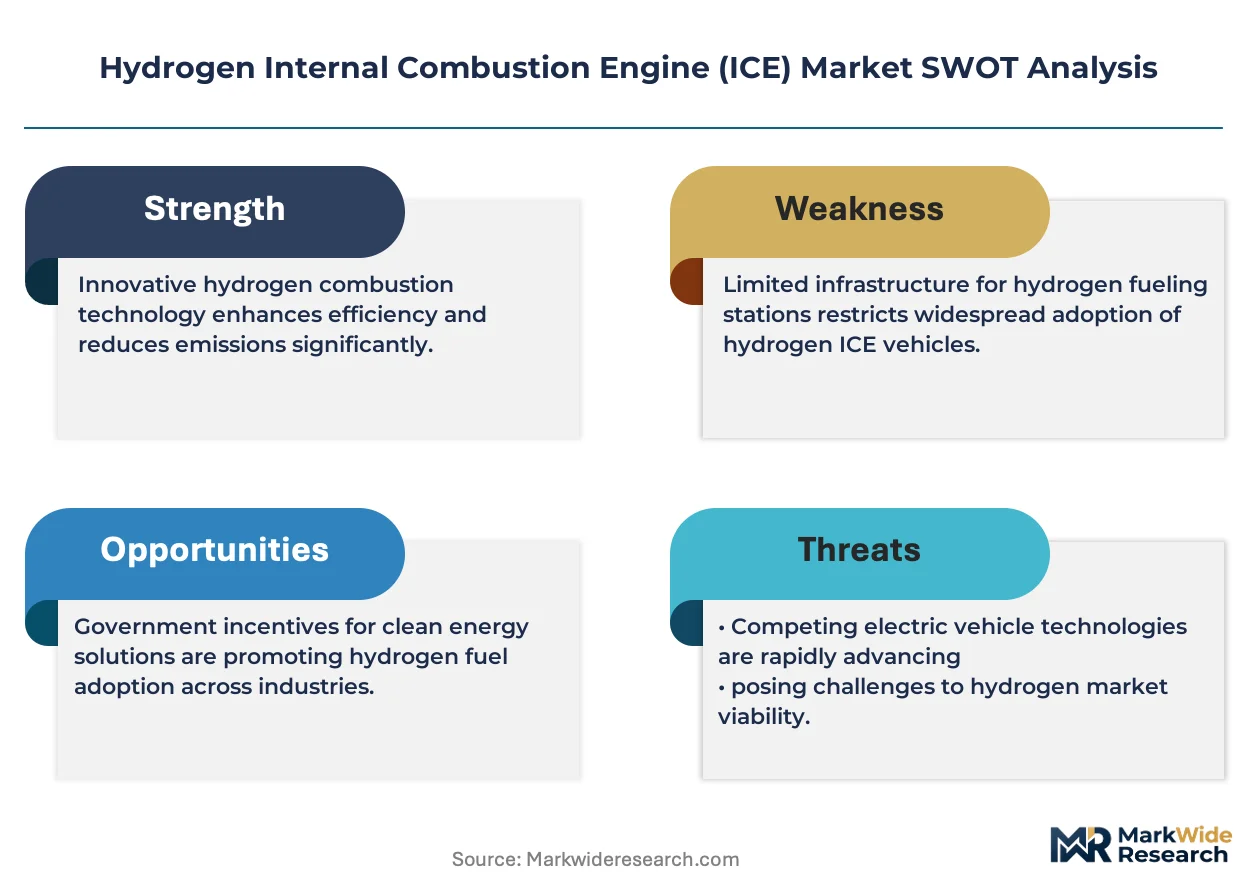
Backward integration into hydrogen storage system manufacturing anchors both supply security and pricing power for engine builders retrofitting Class 8 truck platforms. This captive production of cryogenic tank assemblies insulates procurement costs from electrolyzer capacity volatility while compressing margin leakage to third-party subsystem vendors.
Pricing Analysis
Volume procurement by fleet operators splits from margin-rich marine contracts, with the former compressing unit economics through multi-year supply agreements and the latter preserving premium pricing via dual-fuel certification complexity. Three-tier pricing structure across premium certified, standard validated, and economy pilot tiers reflects NOx aftertreatment compliance tiers rather than raw performance differentiation. Cost compression in the economy tier intensifies because battery electrification substitutes threaten light-duty addressable market. Fleet operators in heavy-duty trucking exhibit highest price sensitivity due to total-cost-of-ownership contracting structures, while marine ship operators accept premium positioning for ammonia-hydrogen blend compatibility.
Supply Chain Analysis
Workforce availability constraints in Augsburg, Cologne, and Nagoya manufacturing clusters limit production scale-up velocity for large-bore engine prototypes. Germany, Japan, and China anchor geographic supply concentration for reciprocating piston assembly fabrication. The supply chain draws from specialized hydrogen injection nozzle suppliers, cryogenic valve manufacturers, and high-pressure fuel rail fabricators. Single-source vulnerability in electrolyzer membrane supply creates structural risk for input cost stability. Distribution runs through authorized dealership networks for retrofit kit deployment and direct sales channels for marine propulsion contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where certification timeline compression forces weaker engine builders into partnership or exit. The binding constraint on deployment scale—whether infrastructure build-out pace or durability validation—determines which archetypes survive independent.
For Market Incumbents: Anchor defensive positioning through captive control of hydrogen storage subsystem production and accelerated EPA NOx certification investment. Battery electrification substitution in light-duty segments threatens margin pools below Class 6 weight classes. Dual-fuel architecture patent portfolios provide channel control leverage against emerging pure-hydrogen specialists. Capacity addition in Texas and California freight corridors compresses response time to fleet operator procurement consolidation.
For New Entrants and Emerging Players: Direct injection thermal efficiency breakthroughs offer technology-first wedge into Class 8 retrofit white space where Cummins service network coverage remains incomplete. Stationary power generation for data center backup applications represents the most penetrable segment given battery duration limitations and fuel cell capital cost barriers. Marine ammonia-hydrogen blend compatibility provides go-to-market angle through IMO compliance deadline urgency on East Asian routes.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by incumbent diesel engine builders seeking hydrogen combustion capability. Long-term viability frames around five-to-ten year infrastructure density maturation rather than near-term volume inflection. Acquisition target archetype: mid-cap dual-fuel specialists with IMO marine certification progress and captive hydrogen storage integration. Electrolyzer cost parity with gray hydrogen production signals demand-side acceleration warranting portfolio re-evaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Architecture Certification | IMO marine compliance deadlines harden business case for ammonia-hydrogen blend compatibility in deep-sea vessels. |
| Backward Integration into Storage Systems | Cryogenic tank captive production insulates margin from electrolyzer capacity constraints and third-party subsystem pricing. |
| EPA NOx Aftertreatment Validation | Emissions certification timeline compression enables fleet operator procurement consolidation into multi-year supply agreements. |
| Dealership Network Retrofit Deployment | Cummins diesel service infrastructure accelerates channel establishment versus fuel cell technician retraining requirements. |
| Marine Propulsion Direct Sales Contracts | MAN Energy Solutions anchors large-bore development through project-based contracting with state-owned ship operators. |
Research Methodology
SEC filings, EIA alternative fuel deployment data, and IMO greenhouse gas strategy documents formed the secondary backbone for market sizing and regulatory trajectory assessment. Primary interviews with fleet procurement directors, marine propulsion engineers, hydrogen infrastructure developers, and EPA certification specialists validated technology readiness timelines and contracting structure evolution. Bottom-up and top-down triangulation reconciled engine builder production disclosures with end-user procurement pipeline aggregation.
Bottom-up volume modeling segmented across technology architecture, application category, and end-user contracting sophistication. The analytical lens weighted direct injection thermal efficiency gains against dual-fuel operational continuity premiums across the projection horizon. Segmentation dimensions included propulsion platform type, vessel duty cycle, fleet ownership structure, and regional hydrogen bunkering density. CAGRs derived from infrastructure build-out pace scenarios and engine durability certification milestone probability. Electrolyzer cost curves and renewable electricity price volatility fed industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including breakthrough battery energy density improvements in heavy-duty applications and abrupt IMO regulatory relaxation. Forecasts reflect assumptions around hydrogen production cost trajectories and port bunkering infrastructure deployment schedules. Material deviation in electrolyzer capacity expansion or NOx certification timeline delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market