
 Fuel Cell Vehicle (FCV) Market | 2026-2036
Fuel Cell Vehicle (FCV) Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Cell Vehicle (FCV) Market Intelligence
Hydrogen refueling network access subscriptions and bundled maintenance packages are pivoting the traditional vehicle sales model toward a total cost of ownership focus. This service-centric approach is critical for commercial fleet operators evaluating FCVs against battery electric and diesel alternatives. Toyota Motor Corporation leverages its early and sustained investment in fuel cell technology across multiple vehicle platforms. Hyundai Motor Company specializes in both passenger FCVs and heavy-duty trucks, while Nikola Corporation competes for market share in the North American commercial freight segment.
A fuel cell vehicle is a type of electric vehicle that generates its own electricity from onboard hydrogen via an electrochemical reaction inside a fuel cell stack. Most current designs utilize Proton Exchange Membrane (PEM) fuel cells, which operate at relatively low temperatures and offer high power density. The primary purpose of FCVs is to provide zero-tailpipe-emission transportation with refueling times and driving ranges comparable to conventional internal combustion engine vehicles. While passenger cars initiated the market, the fastest growth is now found in heavy-duty trucks and buses within the commercial freight and public transportation applications.
Regulatory frameworks are a primary catalyst for market development. The EU Green Deal and the US Inflation Reduction Act (IRA) both contain significant subsidies and investment credits for green hydrogen production and FCV deployment. Similarly, China's dual carbon goals and South Korea's Hydrogen Economy Roadmap create powerful incentives for automakers and fleet operators. The pace of market development now depends on the strategic alignment between vehicle production scale-up and public-private investment in hydrogen refueling infrastructure.
Market Dynamics
The FCV market's expansion depends on the parallel development of hydrogen refueling infrastructure and the scaling of vehicle manufacturing. This interdependence creates a critical coordination challenge between public investment in fueling networks and private sector commitment to mass production, defining the pace of commercial viability.
Growth Catalysts
- Government Mandates:The EU Green Deal and China's dual carbon goals create powerful regulatory drivers for adopting zero-emission vehicles, with specific subsidies and targets for hydrogen mobility in public transport and logistics.
- Technology Maturation:Advances in Proton Exchange Membrane (PEM) fuel cell stack durability and efficiency, combined with lighter and higher-capacity hydrogen storage tanks, improve the performance and economic case for FCVs in heavy-duty applications.
- Infrastructure Incentives:Strong government support in countries like South Korea and Germany for building hydrogen production and refueling stations reduces the investment risk for infrastructure developers and encourages fleet adoption.
Market Restraints
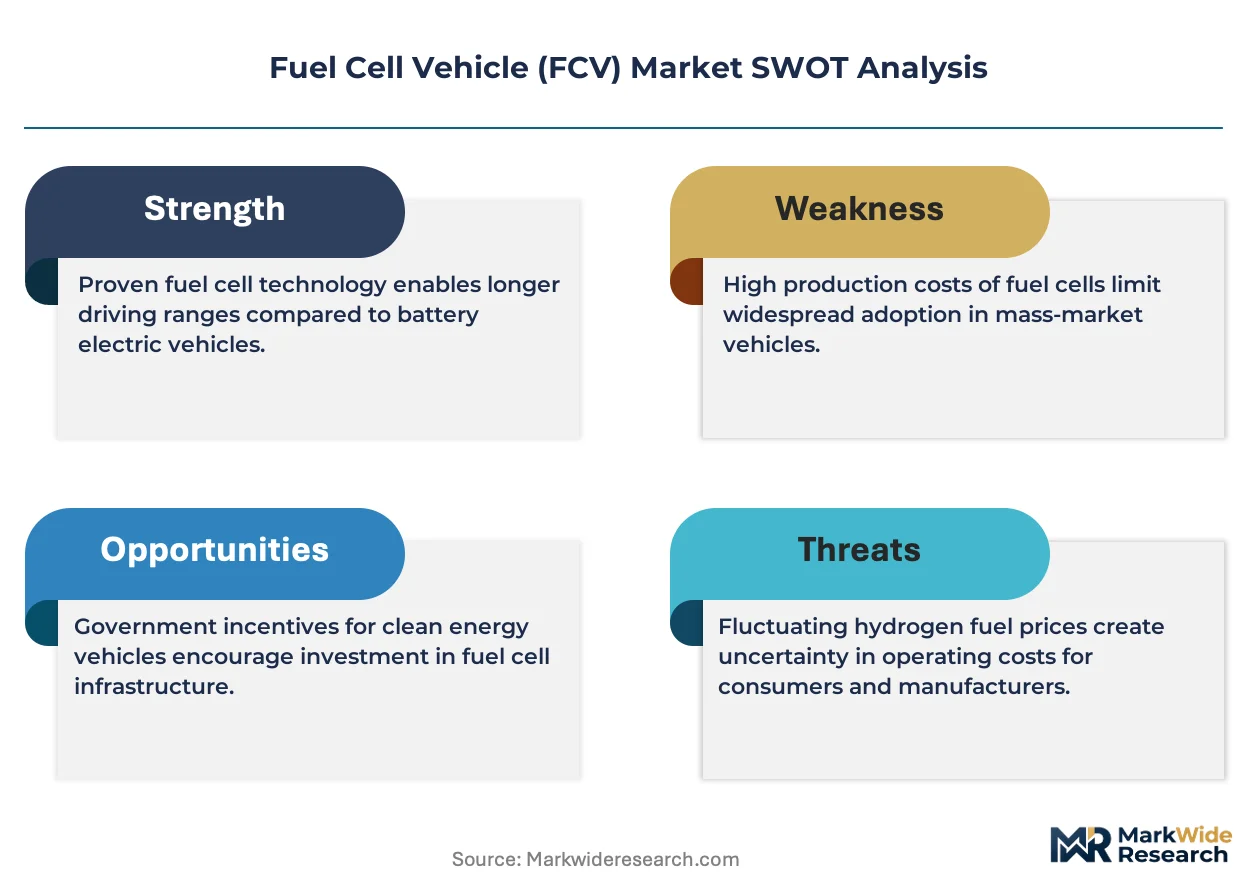
- Hydrogen Infrastructure Scarcity:The limited availability of public and private hydrogen refueling stations remains the single largest barrier to widespread FCV adoption, particularly for passenger cars and small commercial fleets outside of established corridors.
- High Vehicle Cost:The significant cost of fuel cell stacks, which rely on expensive platinum-group metal catalysts, keeps the upfront purchase price of FCVs higher than conventional diesel and battery electric alternatives.
- BEV Competition:Rapid improvements in battery energy density and charging speeds for battery electric vehicles (BEVs) present a strong substitution threat, especially in passenger car and last-mile delivery segments.
Strategic Opportunities
- Maritime and Aviation Applications:Development of high-power fuel cell systems offers a pathway to decarbonize long-haul shipping and aviation, sectors where battery-only solutions face significant weight and range limitations.
- Stationary Power Generation:Leveraging FCV fuel cell technology for stationary power applications, such as data center backup power or off-grid electricity, provides a new market segment and helps achieve economies of scale.
- Hydrogen Economy Integration:FCVs can act as a flexible demand source for emerging green hydrogen production hubs, creating synergies with industrial decarbonization efforts and enabling a more resilient energy system.
Industry Challenges
- Standardization Gaps:A lack of universally adopted standards for hydrogen refueling components, pressures, and communication protocols complicates international logistics and slows down infrastructure interoperability and cost reduction.
- Green Hydrogen Scalability:The capital-intensive process of scaling up green hydrogen production via electrolysis is a significant challenge, with current capacity insufficient to meet projected demand from the transport sector at a competitive cost.
- Specialized Workforce Shortage:A deficit of technicians and engineers trained in the maintenance and repair of high-pressure hydrogen systems and complex fuel cell powertrains constrains after-sales service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Cell Vehicle (FCV) Market |
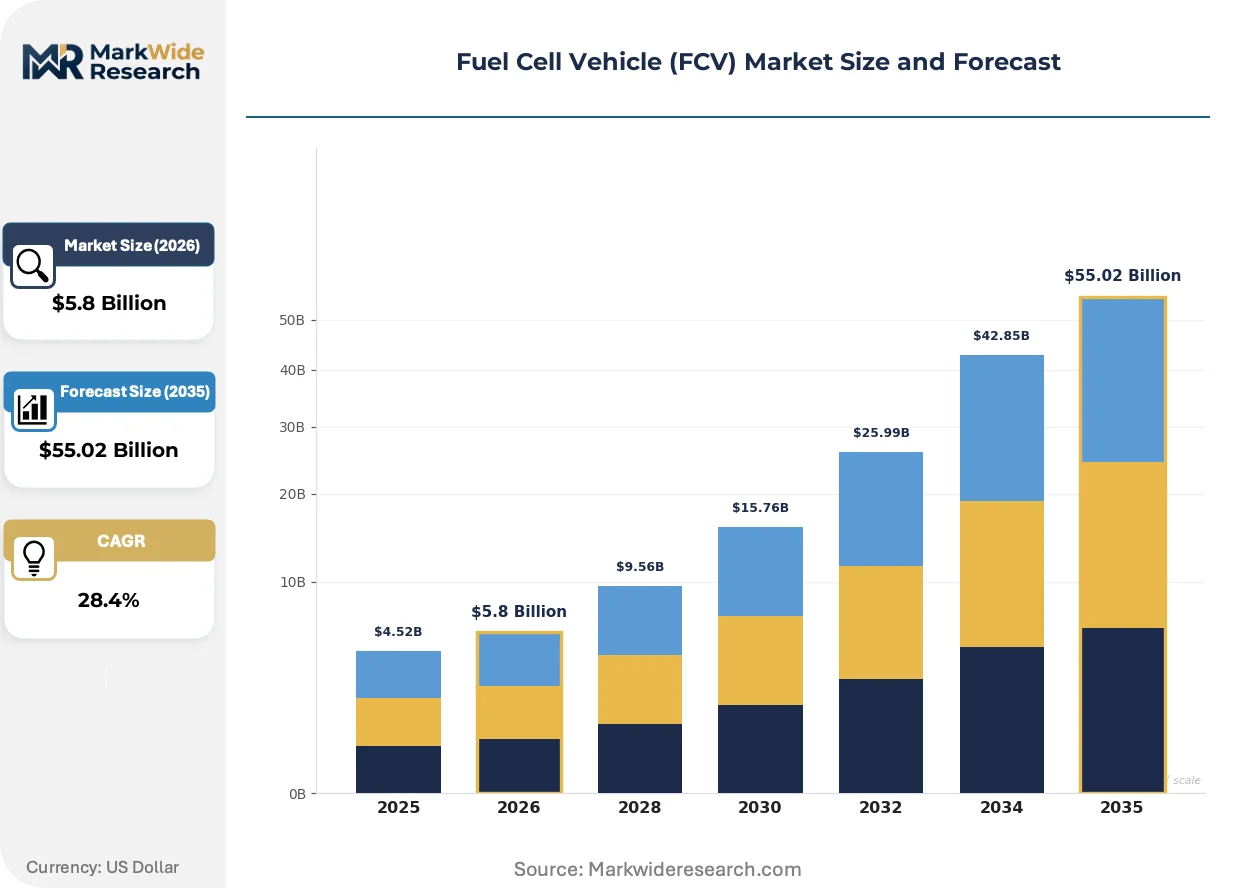
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $55.02 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Buses, Trucks, Two-Wheelers Technology: Proton Exchange Membrane, Solid Oxide Fuel Cell, Alkaline Fuel Cell, Direct Methanol Fuel Cell Power Rating: Small, Medium, Large, Heavy-Duty Application: Public Transportation, Commercial Freight, Personal Use, Industrial |
| Companies Covered | Mercedes-Benz Group, BMW Group, Toyota Motor Corporation, Nikola Corporation, Ballard Power Systems Inc., Hyundai Motor Company, Volkswagen AG, Daimler Truck AG, Honda Motor Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Cell Vehicle (FCV) Market Strategic Shifts & Innovations
The market's evolution is marked by a decisive pivot from passenger vehicle concepts to commercial-grade applications. This strategic shift is reshaping supply chains and business models toward supporting heavy-duty trucks and buses, where the value proposition of fast refueling and long range is most distinct.
High-pressure Type IV composite tanks are a critical enabling technology for hydrogen storage in FCVs. Commercial fleet operators are rapidly adopting these tanks to maximize vehicle range and preserve payload capacity, which are essential for long-haul freight. This technology is consolidating the FCV's competitive advantage in heavy-duty trucking, where battery weight and charging downtime present significant operational hurdles.
Regulatory frameworks like the US Inflation Reduction Act (IRA) are creating substantial financial tailwinds. The IRA's clean hydrogen production tax credit directly reduces the per-kilogram cost of green hydrogen fuel for fleet operators. This incentive structure accelerates the total cost of ownership crossover point for FCV trucks versus diesel incumbents, particularly within North American logistics corridors.
A fundamental shift in acquisition models sees fleet operators favor hydrogen-as-a-service subscriptions over outright vehicle purchases. This model bundles the FCV, fuel, maintenance, and refueling infrastructure access into a fixed rate, de-risking the transition for commercial users. The trend is most visible in Europe and North America, where predictable operational expenditures are a prerequisite for large-scale fleet renewal projects.
Fuel Cell Vehicle (FCV) Market Segmentation
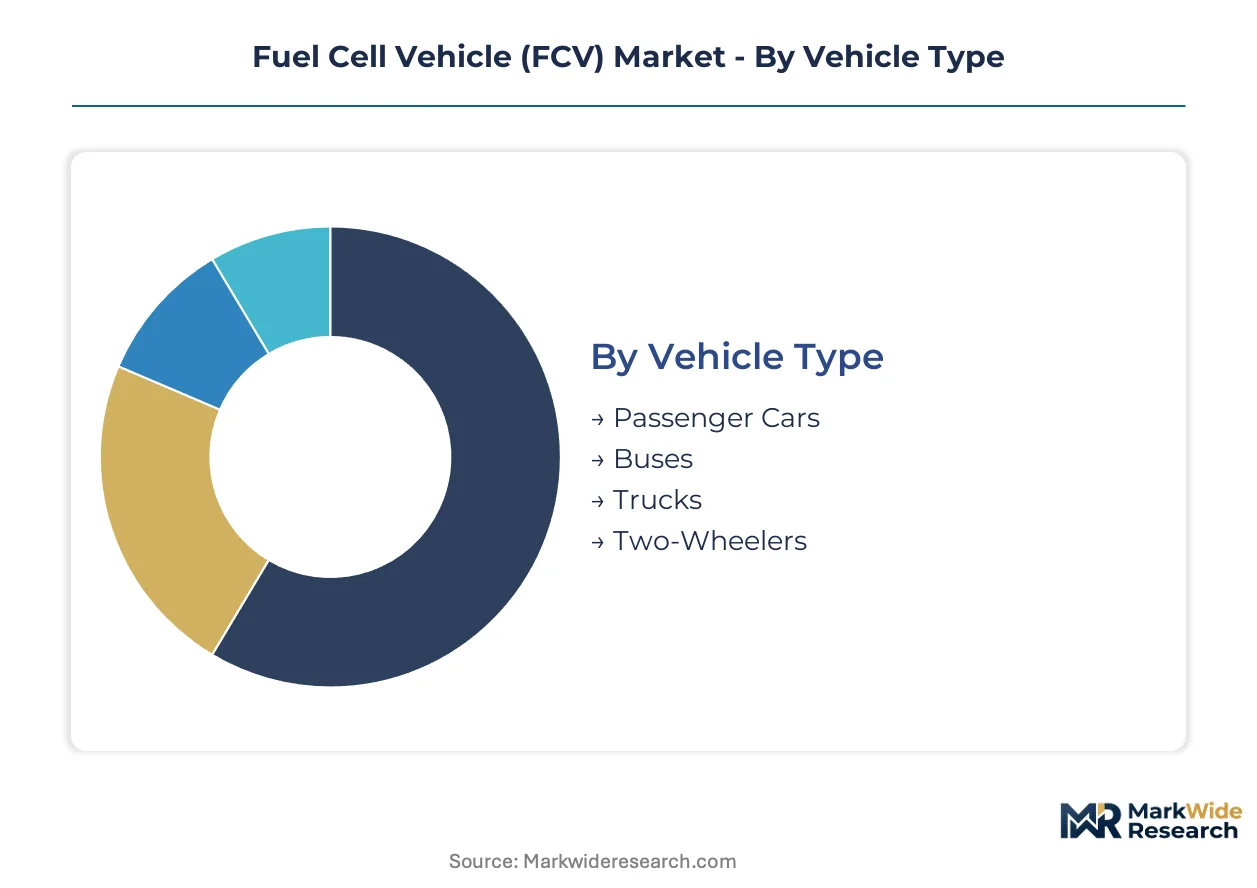
Understanding the Fuel Cell Vehicle (FCV) market through segmentation reveals distinct demand patterns and technological requirements. Each category highlights specific opportunities and challenges for manufacturers and infrastructure developers. This detailed breakdown helps stakeholders align product development and investment strategies with evolving market needs.
Vehicle Type:
The customization-vs-standardization spectrum significantly influences vehicle type development within the FCV market. Passenger vehicles demand high levels of aesthetic integration and user experience, while heavy-duty trucks prioritize ruggedness and operational efficiency.
- Passenger Cars:These FCVs are designed for individual consumer use, typically featuring compact fuel cell systems and hydrogen storage for ranges comparable to gasoline vehicles. Demand is concentrated in South Korea and California, driven by consumer incentives and developing refueling networks.
- Buses:Fuel cell buses offer zero-emission public transportation, often utilizing larger fuel cell stacks and multiple hydrogen tanks for extended routes and high passenger capacity. European cities like London and Cologne are deploying these vehicles for urban and intercity transit.
- Trucks:Heavy-duty FCV trucks are engineered for long-haul commercial freight, offering fast refueling and high payload capacity over extended distances.
- Two-Wheelers:These include fuel cell-powered motorcycles and scooters, targeting urban mobility and last-mile delivery applications with compact hydrogen storage solutions.
Most installed capacity flows through Passenger Cars. Expansion is steepest in Buses.
Technology:
The application requirements for FCVs often dictate the most suitable fuel cell technology, balancing efficiency, operating temperature, and power density. Different technologies cater to diverse operational environments, from automotive to stationary power.
- Proton Exchange Membrane:PEM fuel cells are characterized by low operating temperatures and high power density, making them ideal for automotive applications due to their quick start-up times and dynamic response. This technology dominates FCV deployments in Japan and Germany for both passenger and commercial vehicles.
- Solid Oxide Fuel Cell:SOFCs operate at high temperatures, offering high electrical efficiency and fuel flexibility, often better suited for stationary power generation or auxiliary power units in larger vehicles. Companies are exploring SOFCs for long-haul maritime vessels and data center backup power.
- Alkaline Fuel Cell:AFCs use a liquid electrolyte and operate at lower temperatures, historically used in space applications but facing challenges with CO2 sensitivity for widespread commercial use.
- Direct Methanol Fuel Cell:DMFCs convert liquid methanol directly into electricity, offering advantages in fuel logistics but typically providing lower power output suitable for portable electronics or small-scale power.
The fundamental performance characteristics of Proton Exchange Membrane define its primary market utility, while Solid Oxide Fuel Cell is exploring niche applications.
Power Rating:
Customer type and operational requirements heavily influence the power rating of FCVs, ranging from personal transport to industrial-scale logistics. The power output directly correlates with the vehicle's intended use and energy demands.
- Small:This category includes FCVs with lower power outputs, typically suitable for passenger cars and light commercial vehicles. These vehicles prioritize energy efficiency and compact design for urban driving.
- Medium:Medium power FCVs serve applications like mid-sized buses and delivery vans, balancing power output with range requirements. These are often deployed in regional logistics networks.
- Large:FCVs in the large power rating category are designed for heavy-duty buses and specialized municipal vehicles, requiring substantial power for demanding operational cycles.
- Heavy-Duty:These FCVs feature the highest power outputs, specifically engineered for long-haul trucks and industrial transport, where continuous high power is critical for moving significant cargo.
The market for Heavy-Duty drives the majority of current investment. Future growth is anticipated in Large.
Application:
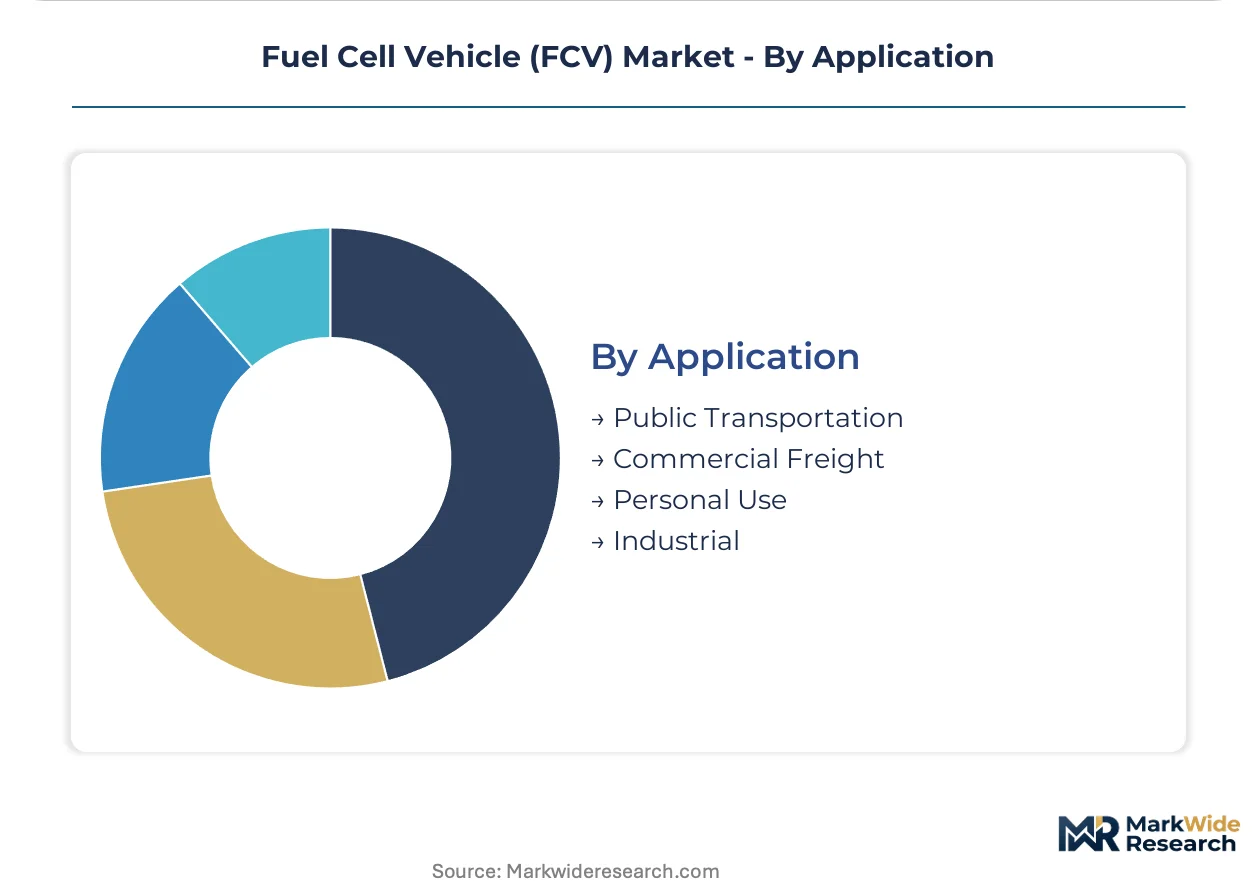
The maturity of various FCV applications varies significantly, with some sectors experiencing rapid deployment while others remain in early development phases. Each application presents unique operational demands and regulatory landscapes.
- Public Transportation:This segment involves the use of FCVs for mass transit systems, primarily fuel cell buses, aiming to decarbonize urban mobility. Government mandates in countries like Germany and South Korea are accelerating adoption in this sector.
- Commercial Freight:FCVs used for goods movement, especially heavy-duty trucks, form this application segment, addressing the need for zero-emission long-haul logistics. North American logistics corridors are seeing increased FCV truck deployments, supported by incentive programs like the US IRA.
- Personal Use:This application covers FCVs purchased by individual consumers for private transportation, primarily passenger cars. Infrastructure scarcity remains a significant barrier to widespread adoption in many regions.
- Industrial:FCVs in industrial applications include forklifts, port equipment, and other specialized vehicles used in controlled environments.
Demand for Commercial Freight applications is robust, whereas Industrial is an emerging sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's aggressive Hydrogen Economy Roadmap contrasts with the United States' Inflation Reduction Act in driving distinct FCV market trajectories. While South Korea focuses on broad consumer and infrastructure incentives, the US prioritizes commercial freight decarbonization. This divergence highlights varied national approaches to zero-emission mobility.
South Korea
Demand for FCVs in South Korea concentrates on both passenger cars and public transportation solutions. The national Hydrogen Economy Roadmap provides substantial consumer subsidies and infrastructure development support. Seoul and Ulsan are centers for FCV adoption, with significant deployments of fuel cell buses and refueling stations.
United States
Commercial freight applications drive FCV demand in the United States, particularly for heavy-duty trucks. The US Inflation Reduction Act offers significant production tax credits for green hydrogen, reducing operational costs for fleets. California's advanced clean truck regulations foster FCV deployment, with logistics corridors around Los Angeles seeing increased activity.
Germany
Public transportation and industrial applications are key demand drivers for FCVs across Germany. The EU Green Deal and national hydrogen strategies provide investment credits for hydrogen production and FCV infrastructure. Hamburg and Cologne are active in deploying fuel cell buses, showcasing urban mobility solutions.
China
China's FCV market focuses on heavy-duty vehicles and public transport, aligning with its dual carbon goals. Government policies incentivize fuel cell vehicle adoption and green hydrogen production, particularly in designated demonstration zones. Provinces like Guangdong and Hebei are developing hydrogen industrial clusters, supporting FCV manufacturing and deployment.
Japan
Hydrogen fuel cell passenger cars and commercial vehicles see consistent demand in Japan, reflecting early technology adoption. The Ministry of Economy, Trade and Industry (METI) supports FCV development through subsidies and infrastructure targets. Tokyo and Aichi Prefecture are hubs for FCV research and deployment, promoting both personal and fleet use.
Fuel Cell Vehicle (FCV) Market Key Industry Players
Top-tier vendors anchor the Fuel Cell Vehicle market, while specialized technology providers and emerging commercial vehicle manufacturers also compete. The market exhibits a tiered structure, with established automotive giants alongside innovative startups. Strategic partnerships between vehicle manufacturers and hydrogen technology developers are common. Companies frequently engage in portfolio diversification to address various FCV applications, from passenger cars to heavy-duty trucks.
Established automotive manufacturers exemplify the market's long-term commitment to FCV technology, leveraging extensive research and development capabilities. Toyota Motor Corporation represents a pioneering force, with sustained investment across multiple vehicle platforms and a focus on technology maturation. Hyundai Motor Company occupies a significant position, specializing in both passenger FCVs and heavy-duty trucks, reflecting a broad market strategy. Nikola Corporation, a North American specialist, anchors competitive positioning within the commercial freight segment, focusing on heavy-duty applications and infrastructure integration. These players collectively demonstrate the diverse approaches to FCV development and deployment across different vehicle types and end-use sectors.
| Leading Market Players |
|---|
| Mercedes-Benz Group |
| BMW Group |
| Toyota Motor Corporation |
| Nikola Corporation |
| Ballard Power Systems Inc. |
| Hyundai Motor Company |
| Volkswagen AG |
| Daimler Truck AG |
| Honda Motor Company Limited |
| Others |
Cost & Logistics Intelligence
Advancements in Type IV composite tank manufacturing simultaneously reshape FCV cost economics and concentrate specialized component supply. This shift impacts both vehicle production expenses and the strategic sourcing decisions for critical high-pressure storage solutions.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for FCV passenger vehicles. The market increasingly favors hydrogen-as-a-service subscriptions, bundling fuel, maintenance, and infrastructure access for commercial fleet operators. Price differentiation stems from vehicle power rating and integrated after-sales support. Pricing softness reflects substantial government subsidies, like the US IRA's clean hydrogen tax credit, making commercial fleet operators highly price sensitive to total cost of ownership.
Supply Chain Analysis
China's dual carbon goals, with their domestic-content mandates, are reshaping FCV supply chain sourcing for critical components. Fuel cell stack manufacturing concentrates in Japan, South Korea, and Germany, drawing from specialized polymer membranes and platinum-group metal catalysts. Single-source vulnerability for platinum supply presents a structural risk. Distribution runs through direct sales to commercial fleet operators and public transportation authorities, with specialized dealership networks serving passenger car segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FCV market presents a geographic-arbitrage play, as the US Inflation Reduction Act's green hydrogen tax credits create a significant cost differential compared to European markets.
For Market Incumbents:To counter the rapid advancements in battery electric vehicle (BEV) technology, FCV incumbents must accelerate fuel cell stack efficiency. Companies should deepen research and development into platinum-free catalyst alternatives to reduce cost dependencies. Securing long-term hydrogen supply agreements in North America, leveraging US IRA incentives, will stabilize operational costs for commercial fleets. Investing in proprietary hydrogen refueling station technology offers a channel control lever against emerging competitors.
For New Entrants and Emerging Players:The US Inflation Reduction Act in North America opens a window for new entrants to specialize in green hydrogen production and FCV component manufacturing. Targeting industrial FCV applications, such as forklifts and port equipment, presents a penetrable segment due to controlled operational environments. Developing modular hydrogen refueling solutions for regional logistics hubs offers a white-space opportunity. A go-to-market angle focusing on hydrogen-as-a-service for industrial parks will de-risk adoption for clients.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized hydrogen infrastructure developers, particularly those focused on mid-scale refueling stations. Long-term viability hinges on sustained regulatory support and cost reduction in green hydrogen production over the next decade. Acquisition targets should include technology providers for advanced PEM fuel cell membranes or high-pressure Type IV tank manufacturers. A critical signal to watch is the consistent expansion of publicly accessible hydrogen refueling points in commercial freight corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Cell Stack Cost Reduction R&D | Reduces FCV upfront purchase price, accelerating commercial fleet adoption in competitive markets. |
| Hydrogen Refueling Network Partnerships | Expands critical infrastructure access, addressing the primary barrier for FCV deployment in key regions. |
| Heavy-Duty Vehicle Platform Standardization | Achieves economies of scale in manufacturing, lowering production costs for FCV trucks and buses. |
| Green Hydrogen Offtake Agreements | Secures a stable supply of low-cost, zero-emission fuel, improving FCV total cost of ownership. |
| Advanced Composite Tank Manufacturing Investment | Increases onboard hydrogen storage capacity, extending FCV range for long-haul commercial freight. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, informing the FCV market analysis. Primary research involved discussions with FCV engineers, commercial fleet procurement managers, hydrogen infrastructure developers, and government policy advisors. This was cross-referenced with secondary data from government energy reports, corporate financial filings, and trade association publications. A bottom-up and top-down triangulation process validated all market data points.
Segment-weighting models underpinned the FCV market forecast, integrating diverse data streams. The analytical framework considered segmentation by vehicle type, technology, power rating, and application across the analysis window. Compound annual growth rates were derived from historical adoption patterns and projected technology maturation rates. Key forecast inputs included green hydrogen production costs and refueling station deployment schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in global energy policy. Forecasts reflect assumptions regarding green hydrogen production scalability and hydrogen infrastructure development pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market