
 CNG Tanks Market | 2026-2036
CNG Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
CNG Tanks Market Analysis
Aftermarket recertification and requalification services is fragmenting as regional inspection networks proliferate and fleet operators seek localized compliance partners. Worthington Enterprises leverages its North American distribution infrastructure to capture recurring revenue from cylinder hydrostatic testing and valve replacement programs. Hexagon Composites ASA differentiates through Type 4 all-composite tank architectures that reduce vehicle weight penalties versus metal alternatives. Luxfer Holdings PLC anchors European aftermarket channels with its legacy aluminum liner installed base requiring periodic inspection cycles.
CNG tanks are high-pressure vessels engineered to store compressed natural gas at service pressures of 200–250 bar, constructed from steel, aluminum, or polymer-composite overwrap configurations, designed to fuel internal combustion engines or stationary power generators. Composite tanks command premium positioning due to their 50–70% weight reduction versus steel equivalents, enabling extended vehicle range without payload sacrifice. Steel tanks retain dominant share in cost-sensitive industrial and stationary applications where weight is immaterial and capital budgets prioritize durability over performance. Marine certification under ISO 11515 represents an emerging specification tier as port authorities in Norway, Germany, and Italy mandate LNG-CNG hybrid fueling for coastal vessels.
The US Department of Transportation enforces FMVSS 304 and 49 CFR standards for cylinder integrity, while the European Union's TPED directive harmonizes portable pressure equipment compliance across member states. India's Petroleum and Explosives Safety Organisation mandates PESO certification for all CNG cylinders deployed in public transport, creating a non-tariff barrier that favors domestic fabricators with established testing relationships. Stakeholders must monitor evolving hydrogen blending thresholds in natural gas pipelines, as compatibility standards for CNG-H2 mixed fuel storage will determine next-generation tank material specifications and retrofit obligations.
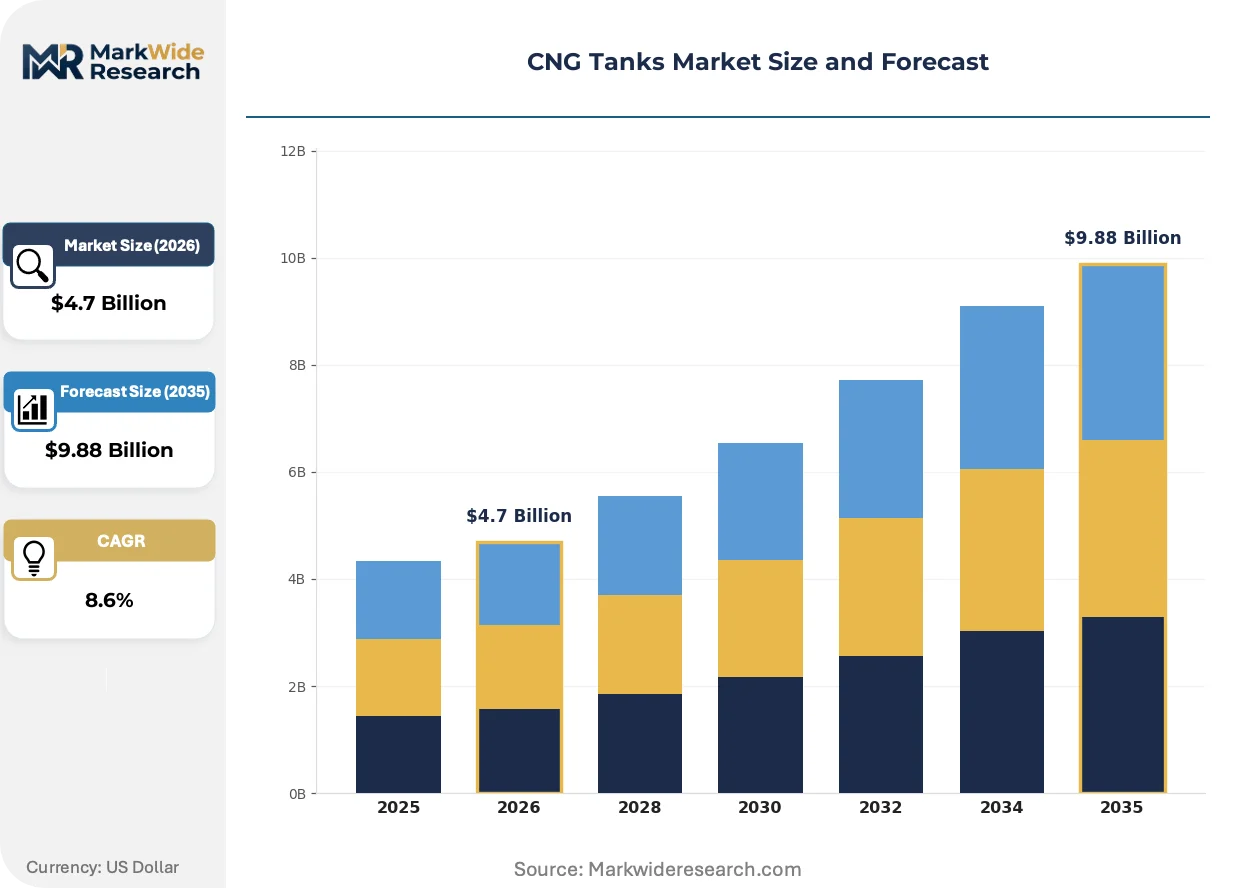
Market Dynamics
Fleet operators in India, the United States, and Germany are accelerating compressed natural gas adoption as municipal transit authorities face binding emissions mandates and volatile diesel pricing. This demand surge is compressing certification timelines and forcing tank fabricators to expand Type 4 composite manufacturing capacity ahead of regulatory deadlines.
Growth Catalysts
- EPA Heavy-Duty Engine Standards:The US Environmental Protection Agency's Phase 3 greenhouse gas rules for medium and heavy-duty vehicles mandate incremental emission reductions through 2032, compelling freight operators to evaluate CNG powertrains and compatible high-pressure storage systems.
- Type 4 Composite Technology:Full-composite tank architectures using carbon fiber overwrap on polymer liners achieve weight reductions exceeding fifty percent versus steel alternatives, enabling bus manufacturers to extend range without sacrificing passenger capacity or payload ratings.
- India State Bus Corporation Tendering:Delhi Transport Corporation, Maharashtra State Road Transport Corporation, and Gujarat State Road Transport Corporation collectively tender for thousands of CNG-powered vehicles annually, creating sustained order flow for cylinder suppliers with PESO certification.
Market Restraints
- Carbon Fiber Supply Concentration:Toray Industries, Mitsubishi Chemical, and Hexcel Corporation control approximately seventy percent of aerospace-grade carbon fiber supply, exposing tank fabricators to allocation risk and input price volatility during defense and aviation demand surges.
- Stationary Steel Tank Substitution:Industrial CNG storage for compressor stations and mother stations continues favoring Type 1 steel cylinders where weight is immaterial and capital budgets prioritize thirty-year service life over vehicle-integrated performance.
- ECE R110 Certification Friction:European OEMs face extended homologation timelines for whole-vehicle type approval when integrating aftermarket tank configurations, slowing fleet retrofit programs relative to factory-installed alternatives.
Strategic Opportunities
- Hydrogen Blending Infrastructure:Pipeline operators in the Netherlands, Germany, and the United Kingdom are piloting twenty percent hydrogen injection into natural gas grids, creating demand for next-generation CNG-H2 compatible tanks with modified liner materials and permeation barriers.
- Marine ISO 11515 Certification:Norwegian port authorities and German coastal regulators are mandating LNG-CNG hybrid fueling for short-sea shipping and harbor craft, opening a specification tier previously dominated by land-based transportation applications.
- Localized Aftermarket Inspection Networks:Regional hydrostatic testing and valve replacement partnerships allow service providers to capture recurring revenue from fleet operators seeking compliance without returning cylinders to original fabricators.
Industry Challenges
- Composite Technician Scarcity:Filament winding and automated fiber placement operations require specialized operators with aerospace or pressure vessel backgrounds, constraining capacity expansion at mid-tier fabricators competing for skilled labor.
- PESO Testing Queue Bottlenecks:India's Petroleum and Explosives Safety Organisation maintains limited accredited laboratory capacity for burst testing and cycle fatigue validation, extending lead times for domestic and imported cylinder approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNG Tanks Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Composite, Steel, Aluminum, Plastic Application: Automotive, Industrial, Stationary, Marine Size: Small, Medium, Large, Extra Large Certification: ISO, DOT, TPED, ASME |
| Companies Covered | Worthington Enterprises, Luxfer Holdings PLC, Hexagon Composites ASA, Everest Kanto Cylinder, Faber Industrie SPA, CIMC Enric, Quantum Fuel Systems, Beijing Tianhai Industry, Rama Cylinders, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNG Tanks Market Emerging Trajectories
Digital thread integration across design, manufacturing, and compliance documentation is compressing tank development cycles while enabling predictive maintenance models for fleet operators. These shifts are reshaping competitive positioning toward data-enabled service providers.
Embedded fiber optic sensing is digitizing structural health monitoring for Type 4 composite tanks. The technology enables real-time pressure, strain, and temperature telemetry throughout cylinder service life. Transit fleet operators in California and New York are piloting sensor-integrated tanks to optimize refueling schedules and predict maintenance windows. This capability is digitizing asset management practices that previously relied on periodic manual inspection.
The European Union's F-Gas Regulation and complementary national building codes are accelerating specifications for leak-tight valve assemblies and permeation-resistant liner materials. Industrial gas suppliers must now document lifecycle emissions for storage equipment alongside the gases themselves. Tank fabricators serving German and French markets are responding with fluoropolymer barrier layers and welded metal seal designs that exceed baseline ISO 11439 requirements.
Aftermarket service unbundling is fragmenting traditional supply relationships. Fleet maintenance departments now separately procure hydrostatic recertification, valve replacement, and cylinder refurbishment from regional specialists rather than returning to OEM channels. This pattern is most visible in North American municipal bus operations where transit agencies face budget pressure to minimize vehicle downtime and extend capital equipment service intervals.
CNG Tanks Market Segmentation
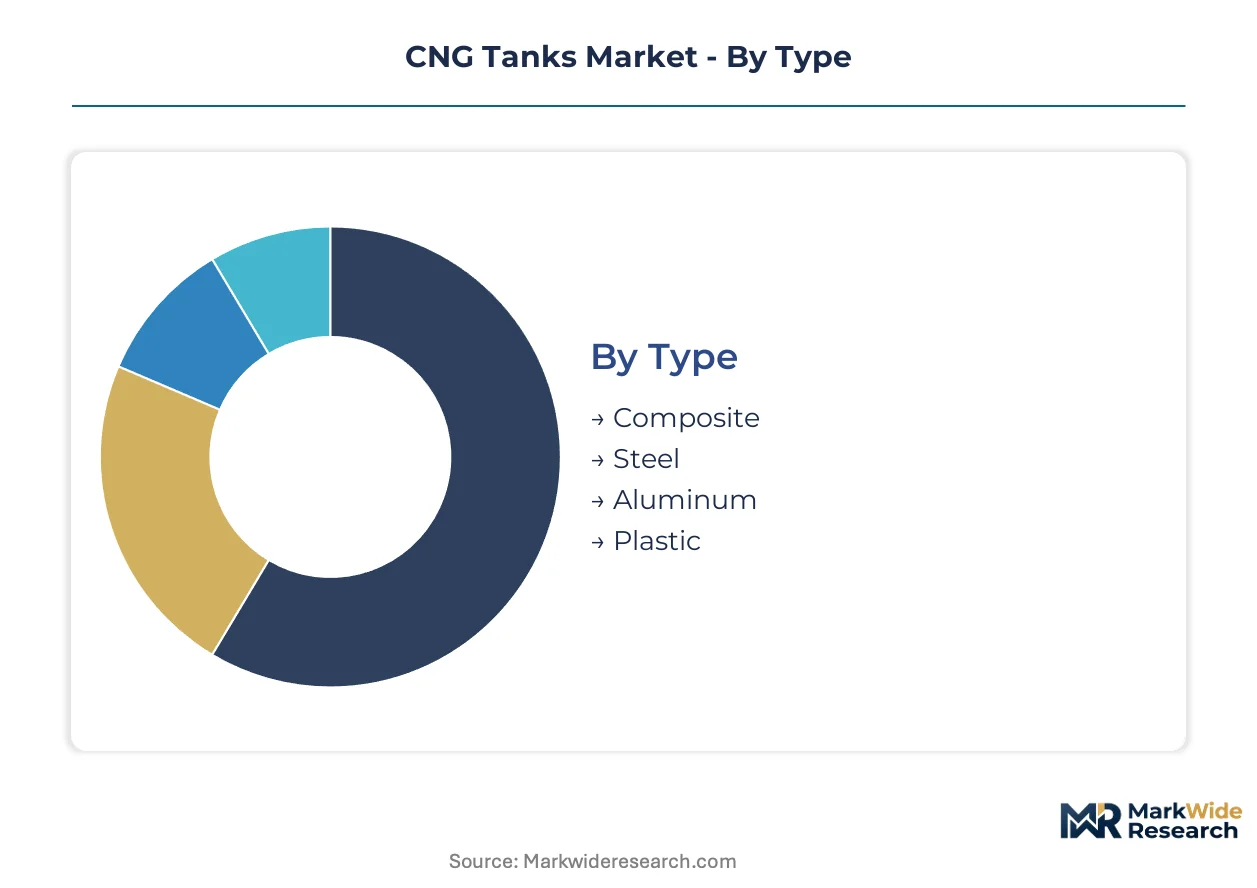
Segmentation in the CNG Tanks Market reveals divergent material economics and certification pathways that determine fabricator specialization. Tank type dictates manufacturing capital intensity while application verticals impose distinct pressure ratings and inspection protocols.
Type:
Material composition stratifies the market across cost-performance tradeoffs where weight sensitivity and service life compete for priority.
- Composite:Carbon fiber overwrap on polymer liners achieves 50–70% weight reduction versus metal alternatives. Transit bus manufacturers in California and New York specify Type 4 composites to maximize passenger capacity without range sacrifice.
- Steel:Solid-wall steel cylinders dominate industrial compressor stations and mother stations where capital budgets prioritize thirty-year durability over vehicle-integrated performance. Indian PESO certification requirements favor domestic steel fabricators with established burst testing relationships.
- Aluminum:Aluminum-lined hybrid designs balance moderate weight savings against lower material costs than full-composite architectures.
- Plastic:Polymer-dominant configurations remain experimental for low-pressure auxiliary storage in hybrid fuel systems.
Composite holds installed capacity. Steel is rotating up the share rankings in stationary applications.
Application:
End-use verticals impose divergent duty cycles and regulatory exposure that reshape tank specification priorities.
- Automotive:On-vehicle storage for buses, trucks, and passenger cars demands crash-resistant mounting systems and rapid-fill thermal management. Indian state transport corporations in Delhi, Maharashtra, and Gujarat tender thousands of CNG-powered vehicles annually.
- Industrial:Forklifts, mining equipment, and port machinery utilize CNG for indoor air quality compliance where diesel particulate emissions face occupational exposure limits.
- Stationary:Buffer storage at refueling stations and power generation facilities favors Type 1 steel cylinders where weight is immaterial.
- Marine:Short-sea shipping and harbor craft in Norway, Germany, and Italy now require ISO 11515 certification for LNG-CNG hybrid fueling systems.
Automotive commands the steepest expansion trajectory. Marine is climbing the fastest among emerging specification tiers.
Size:
Volume capacity segments align with vehicle class and refueling infrastructure scale, from passenger car cylinders to bus multiple-tank arrays.
- Small:Passenger car and light commercial vehicle cylinders typically store 15–20 kg CNG equivalent. Indian urban taxi fleets favor compact tanks for trunk space preservation.
- Medium:Transit bus and medium-duty truck applications utilize 100–150 liter water capacity cylinders in roof-mounted or frame-integrated configurations.
- Large:Heavy-duty freight trucks and regional buses require 200+ liter cylinders with tandem mounting for extended range between refueling.
- Extra Large:Stationary buffer storage and marine applications deploy manifolded cylinder banks exceeding 500 liter individual capacity.
Medium holds installed capacity. Large is gaining share fastest as freight operators convert from diesel.
Certification:
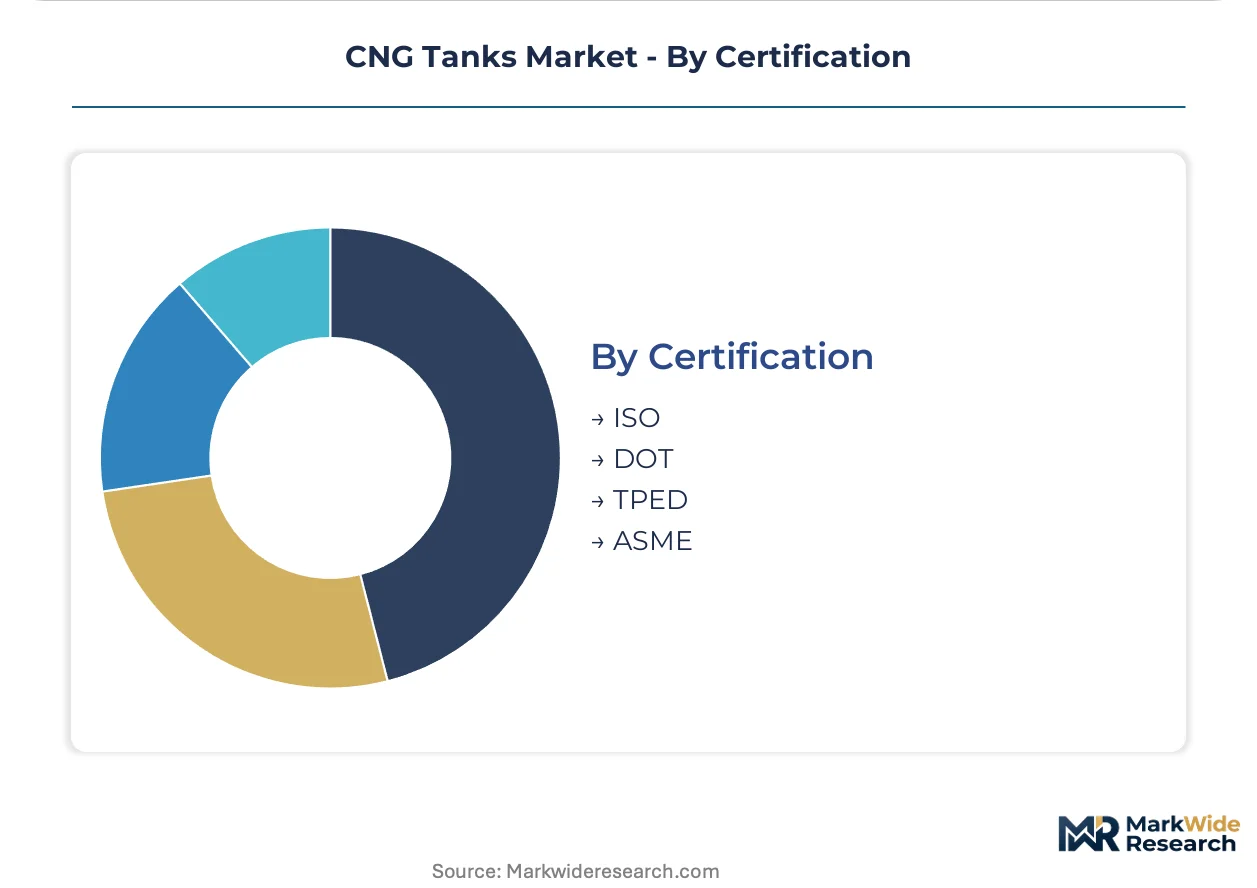
Regulatory jurisdiction determines testing protocols and market access barriers that fragment fabricator compliance investments.
- ISO:ISO 11439 governs high-pressure cylinders for on-board vehicle storage, harmonizing burst testing and cycle fatigue requirements across export markets.
- DOT:US Department of Transportation FMVSS 304 and 49 CFR standards enforce cylinder integrity for interstate commerce, with specific exemptions for NGV2 bus configurations.
- TPED:European Union Transportable Pressure Equipment Directive harmonizes portable pressure equipment compliance across member states, requiring notified body involvement for conformity assessment.
- ASME:American Society of Mechanical Engineers Boiler and Pressure Vessel Code Section VIII applies to stationary storage vessels and refueling station equipment in North American industrial applications.
ISO holds installed capacity. TPED is rotating up the share rankings as European fleet electrification delays boost interim CNG adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates among fabricators with established burst testing relationships and PESO certification in India, while European and North American producers leverage composite expertise for transit bus specifications. This geographic specialization shapes regional competitive dynamics and certification pathway fragmentation.
India
State transport corporations in Delhi, Maharashtra, and Gujarat tender thousands of CNG-powered buses annually, creating sustained order flow for cylinder suppliers. PESO certification requirements under the Petroleum and Explosives Safety Organisation favor domestic fabricators with accredited laboratory relationships. Manufacturing clusters in Pune and Ahmedabad host burst testing facilities and cylinder fabrication lines serving municipal fleet operators.
United States
EPA Phase 3 greenhouse gas standards for medium and heavy-duty vehicles mandate emission reductions through 2032, compelling freight operators to evaluate CNG powertrains. FMVSS 304 and 49 CFR standards enforce cylinder integrity for interstate commerce. Transit agencies in California and New York pilot sensor-integrated Type 4 composite tanks for predictive maintenance optimization.
Germany
Port authorities and coastal regulators mandate LNG-CNG hybrid fueling for short-sea shipping and harbor craft under emerging ISO 11515 certification tiers. The EU's F-Gas Regulation accelerates specifications for leak-tight valve assemblies and permeation-resistant liner materials. Industrial gas suppliers in the Ruhr region document lifecycle emissions for storage equipment alongside gases themselves.
China
MIIT industrial policies support natural gas vehicle deployment as part of dual carbon goals, with GB standards governing high-pressure cylinder safety. CIMC Enric and Beijing Tianhai Industry anchor domestic fabrication capacity for transit and industrial applications. Manufacturing concentrates in coastal provinces with established pressure vessel supply chains and NGV refueling infrastructure.
Italy
Coastal regulators in Mediterranean ports mandate LNG-CNG hybrid systems for harbor craft and short-sea vessels, expanding specification tiers beyond land-based transportation. TPED directive harmonization requires notified body involvement for conformity assessment across EU member states. Fabrication expertise in northern industrial districts serves marine certification demands alongside traditional automotive applications.
CNG Tanks Market Vendor Landscape
Integrated conglomerates and specialized composite fabricators split the market across material technology boundaries. The vendor base stratifies into three tiers: steel cylinder specialists serving cost-sensitive industrial applications, Type 4 composite innovators targeting weight-sensitive transit specifications, and diversified industrial gas equipment providers spanning multiple pressure vessel categories. Dominant competitive moves include capacity expansion in filament winding operations and strategic partnerships with carbon fiber suppliers to secure aerospace-grade material allocation.
Among North American fabricators, Worthington Enterprises leverages established distribution infrastructure for aftermarket hydrostatic testing and valve replacement programs. Hexagon Composites ASA and Luxfer Holdings PLC exemplify the composite-architecture tier, with the former representing full-composite Type 4 specialization and the latter anchoring European aftermarket channels through legacy aluminum liner installed bases requiring periodic inspection cycles.
| Leading Market Players |
|---|
| Worthington Enterprises |
| Luxfer Holdings PLC |
| Hexagon Composites ASA |
| Everest Kanto Cylinder |
| Faber Industrie SPA |
| CIMC Enric |
| Quantum Fuel Systems |
| Beijing Tianhai Industry |
| Rama Cylinders |
| Others |
Supply Flow & Price Mechanics
Toray Industries, Mitsubishi Chemical, and Hexcel Corporation's collective grip on aerospace-grade carbon fiber supply positions them as gatekeepers to margin capture in Type 4 composite tank production. This upstream oligopoly forces fabricators to absorb allocation risk and input price volatility, compressing margins at the cylinder manufacturing tier while downstream fleet operators capture fuel cost savings.
Pricing Analysis
ISO 11439 and ECE R110 certification tiers dictate the pricing structure across the CNG tank market, separating premium Type 4 composite architectures from standard aluminum-lined hybrids and economy steel cylinders. Price differentiation rests on weight reduction performance and regulatory approval breadth, with California transit agencies least sensitive to upfront cylinder costs and Indian state bus corporations most responsive to per-unit capital outlay. Cost compression in steel tank tiers is intensifying because domestic PESO-certified fabricators compete aggressively for municipal tender volumes.
Supply Chain Analysis
Carbon fiber feedstock draws from Japanese and US petrochemical complexes, with precursor acrylonitrile supply anchored in Texas and Louisiana refining corridors. Raw material dependencies center on PAN-based fiber, epoxy resin systems, and polymer liner substrates. Single-source vulnerability concentrates in aerospace-grade fiber allocation during defense procurement surges. Distribution runs through OEM-integrated channels for factory-installed tanks and regional aftermarket networks for recertification services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat story. PESO certification requirements in India and EPA emissions mandates in the United States create entrenched switching costs that protect incumbent positions against unqualified challengers.
For Market Incumbents: Build certification moats by deepening PESO laboratory relationships in Pune and Ahmedabad while expanding Type 4 filament winding capacity ahead of European TPED deadline compression. Threat substitution from battery-electric bus platforms demands accelerated hydrogen-blending compatibility R&D. Channel control through captive aftermarket inspection networks locks in recurring revenue from municipal fleet operators. For New Entrants and Emerging Players: Pursue marine ISO 11515 certification as the most penetrable specification tier, where Norwegian and German port authority mandates outpace qualified supplier counts. Target short-sea shipping retrofit programs with hybrid LNG-CNG tank configurations. A go-to-market angle anchored in coastal vessel compliance partnerships bypasses entrenched automotive supply relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed steel cylinder specialists in India holding PESO accreditation but lacking composite technology migration paths. Long-term viability across the analysis window favors platforms with dual-material capability spanning Type 1 steel and Type 4 composite architectures. The signal to watch is hydrogen blending threshold announcements from Dutch and German pipeline operators, which will trigger retrofit demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Type 4 Composite Capacity Expansion | Carbon fiber winding lines in India and Germany capture EPA Phase 3 and EU fleet conversion demand. |
| PESO Certification Investment | Accredited burst testing relationships unlock Delhi and Maharashtra state bus corporation tender participation. |
| Marine ISO 11515 Pathway | Norwegian port authority mandates create first-mover advantage in coastal vessel hybrid fueling systems. |
| Aftermarket Inspection Network Buildout | Regional hydrostatic testing partnerships secure recurring revenue from North American municipal transit agencies. |
| Hydrogen Blending Compatibility R&D | Modified liner materials position fabricators for Netherlands and UK pipeline injection pilot scale-up. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with cylinder fabrication plant managers, fleet procurement directors at Indian state transport corporations, carbon fiber supply specialists, and aftermarket service technicians combined with PESO certification databases, EPA enforcement records, EMA submissions, and customs trade data. Bottom-up tank shipment tallies triangulate against top-down fueling infrastructure investment forecasts.
Calibration against historical certification queue lengths and capacity utilization rates at filament winding facilities shapes the projection framework across the analysis window. Segmentation dimensions modeled include tank material architecture, vehicle application class, pressure rating tier, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves tied to diesel-CNG price spreads and fleet replacement cycles. Hydrogen blending compatibility standards and marine certification adoption curves serve as scenario-weighted inputs.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, carbon fiber spot markets, or municipal transit budget allocations would shift the trajectory. Forecasts reflect documented assumptions about regulatory deadline adherence and OEM platform standardization timelines. Cross-checking against IEA natural gas vehicle deployment benchmarks and national refueling station buildout data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Ethanol Vehicle Market