
 Automotive Gas Cylinder Market | 2026-2036
Automotive Gas Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Gas Cylinder Market Analysis
Light commercial vehicle fleets is shifting toward dedicated CNG platforms as last-mile logistics operators prioritize total cost of ownership. Hexagon Composites dominates filament-wound Type IV cylinder supply for European bus OEMs. Everest Kanto Cylinder Ltd anchors steel cylinder volumes across South Asian retrofit channels. Luxfer Gas Cylinders specializes in aluminum-lined hybrid designs for North American pickup truck conversions.
Automotive gas cylinders are pressure vessels engineered to store compressed natural gas, liquefied petroleum gas, or hydrogen at service pressures typically ranging from 200 to 700 bar, constructed from all-metal, metal-composite hybrid, or all-composite architectures to achieve weight-specific storage efficiency. Composite cylinders incorporate carbon-fiber overwrap on polymer or aluminum liners through filament winding or tow placement, delivering mass reductions exceeding 60% versus conventional steel while maintaining cyclic fatigue resistance under SAE J1616 or ISO 11439 protocols. OEM procurement of Type IV composite cylinders for dedicated CNG platforms commands premium positioning due to weight-driven fuel economy gains, whereas aftermarket steel cylinder retrofits for LPG vehicles occupy a mature, price-sensitive tier. Dual fuel system applications represent the fastest-growing application segment as engine manufacturers pursue diesel displacement strategies without full powertrain redesign.
The US Department of Transportation FMVSS 304 and EPA certification requirements govern cylinder integrity and evaporative emission performance for alternative fuel vehicle conversions. India's PESO and BIS enforce hydrostatic test cycles and material traceability that effectively exclude uncertified imports. EU ECE R110 and ISO 11439 alignment shapes export qualification costs for Asian manufacturers. Stakeholders must monitor hydrogen storage cylinder standard convergence as fuel cell commercialization blurs traditional CNG supply chain boundaries.
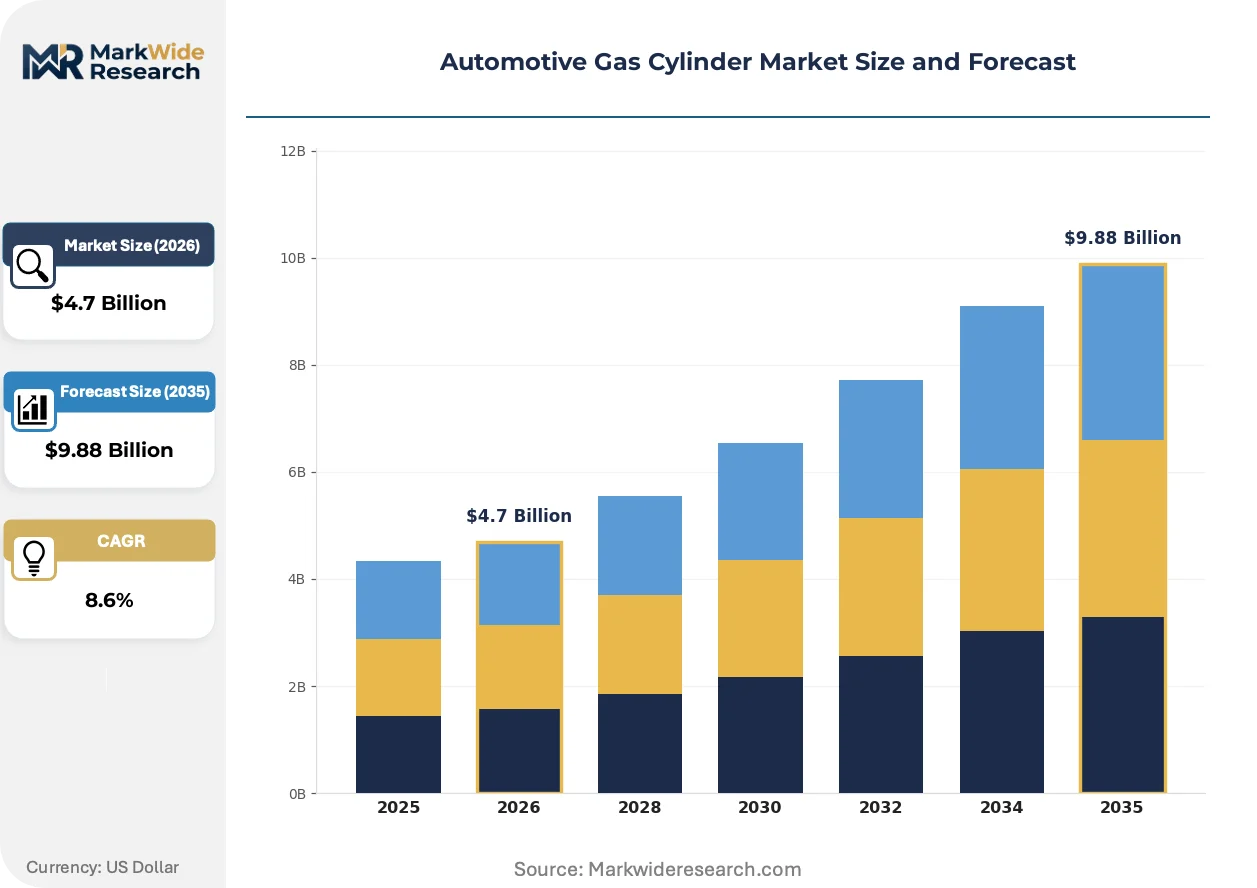
Market Dynamics
Fleet operators are expanding dedicated CNG vehicle procurement as fuel cost differentials against diesel widen, while India's BIS certification mandates for composite cylinders tighten material standards and reshape supplier qualification.
Growth Catalysts
- Type IV Composite Adoption:Carbon-fiber overwrap on polymer liners delivers mass reductions exceeding 60% versus steel, enabling fuel economy gains that OEMs prioritize for dedicated CNG platforms.
- City Gas Distribution Density:Maharashtra and Gujarat anchor demand concentration where pipeline infrastructure supports last-mile logistics conversion to compressed natural gas.
- Dual Fuel System Proliferation:Engine manufacturers pursue diesel displacement without full powertrain redesign, expanding cylinder demand across retrofit channels.
Market Restraints
- Carbon Fiber Supply Concentration:Filament-winding feedstock availability concentrates among specialized chemical producers, creating input cost volatility for Type IV cylinder manufacturers.
- Hydrostatic Test Cycle Burden:India's PESO and BIS enforcement of extended hydrostatic protocols extends certification timelines and excludes uncertified import competition.
- Hydrogen Storage Convergence Risk:Fuel cell commercialization blurs traditional CNG supply chain boundaries as cylinder standards diverge toward higher-pressure hydrogen protocols.
Strategic Opportunities
- North American Pickup Conversion Channel:Aluminum-lined hybrid designs address weight constraints in light truck retrofits where steel cylinders face displacement pressure.
- European Bus OEM Integration:ECE R110 alignment with ISO 11439 creates streamlined export qualification for Asian manufacturers targeting municipal fleet electrification alternatives.
- LPG Aftermarket Standardization:SAE J1616 protocol convergence across regional regulators reduces variant proliferation and enables scale economies in mature retrofit segments.
Industry Challenges
- Fatigue Testing Talent Scarcity:Cyclic validation under SAE J1616 or ISO 11439 protocols requires specialized engineering expertise that outpaces current training pipeline output.
- Multi-Standard Certification Complexity:Simultaneous compliance with US DOT FMVSS 304, EU ECE R110, and India's BIS creates documentation overhead that extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Gas Cylinder Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Cylinders, Steel Cylinders, Aluminum Cylinders, Plastic Cylinders Application: CNG Vehicles, LPG Vehicles, Dual Fuel Systems, Specialty Vehicles End User: OEMs, Aftermarket Providers, Fleet Operators, Rental Services Manufacturing Stage: Raw Material Sourcing, Production, Assembly, Quality Testing |
| Companies Covered | Luxfer Gas Cylinders, Everest Kanto Cylinder Ltd, Hexagon Composites, Worthington Industries, Faber Industrie, CIMC Enric Holdings, CNG Cylinders International, Quantum Fuel Systems LLC, Beijing China Tank Industry Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Gas Cylinder Market Emerging Trajectories
Filament-wound composite architectures are absorbing volume share from all-metal cylinders as weight-driven fuel economy targets harden across commercial vehicle segments. Three interconnected developments are reshaping competitive positioning.
Tow-placement automation is absorbing labor-intensive winding steps in Type IV cylinder production, reducing unit cost variance and enabling European bus OEMs to scale dedicated CNG platform procurement without supplier bottleneck. Quality consistency gains from robotic fiber placement are compressing rejection rates at hydrostatic validation stages.
REACH substance restrictions on resin systems are forcing reformulation of polymer liners used in hybrid cylinder architectures, extending material qualification cycles for manufacturers serving EU export markets. Asian suppliers are responding by establishing captive testing capacity within European economic zones to maintain ECE R110 certification continuity.
Last-mile logistics operators are consolidating cylinder procurement through fleet management platforms that bundle vehicle conversion, cylinder leasing, and maintenance into single-contract structures. This bundling is displacing fragmented aftermarket purchasing in Indian metropolitan clusters where city gas distribution network density supports operational scale.
Automotive Gas Cylinder Market Segmentation
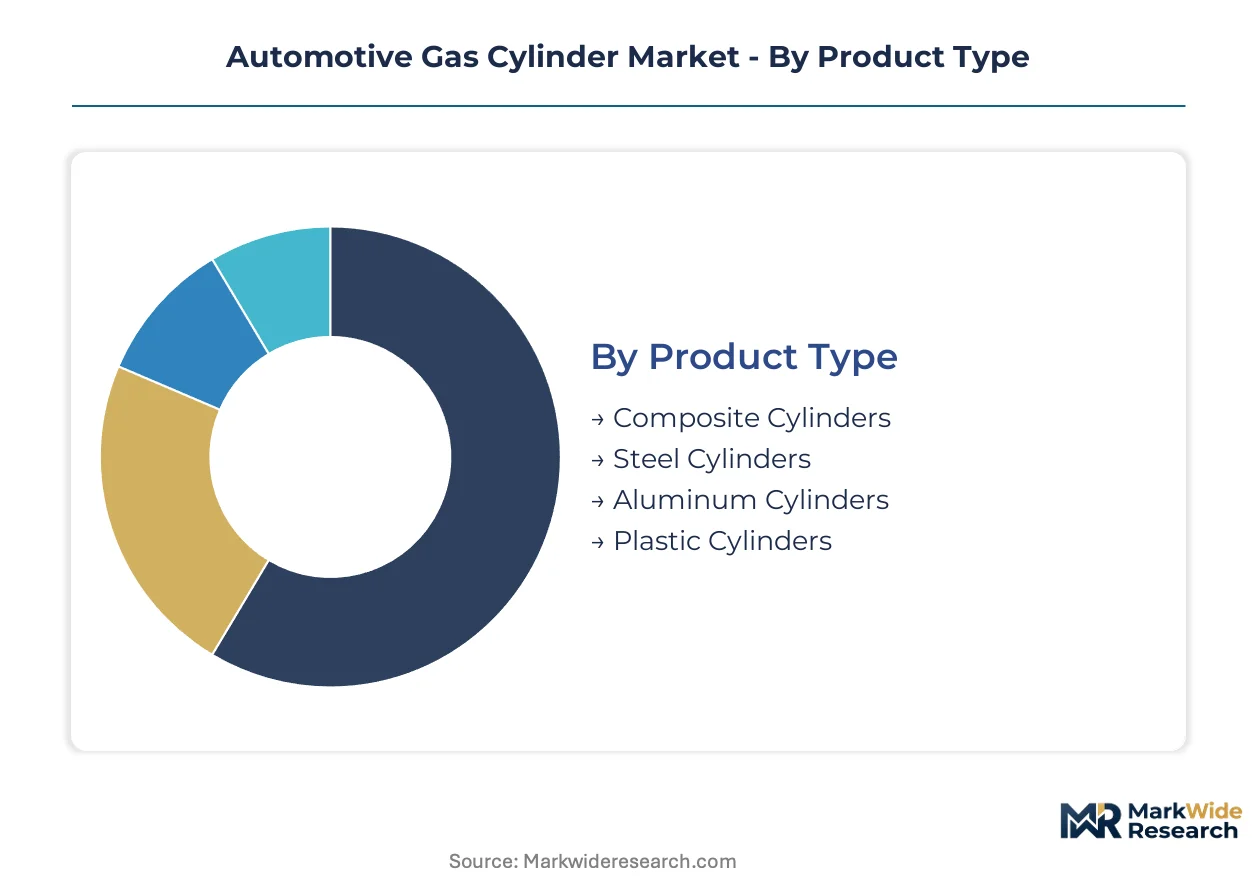
Segmentation in the automotive gas cylinder market reveals how material technology, application requirements, and procurement channels create distinct competitive arenas. Upgrade cycles vary dramatically across these dimensions, from OEM platform redesigns spanning 5-7 years to aftermarket retrofit decisions made on 18-month total cost of ownership calculations.
Product Type:
Upgrade and replacement cycles diverge sharply across cylinder architectures, with composite platforms requiring full system redesigns while steel cylinders enable drop-in retrofits.
- Composite Cylinders:Carbon-fiber overwrap on polymer or aluminum liners achieves mass reductions exceeding 60% versus conventional steel. Fleet procurement in Maharashtra and Gujarat concentrates here as city gas distribution density supports dedicated CNG platform economics.
- Steel Cylinders:All-metal construction dominates retrofit channels where price sensitivity overrides weight considerations. India's BIS certification mandates for hydrostatic test cycles extend replacement timelines but lock in incumbent suppliers.
- Aluminum Cylinders:Hybrid aluminum-lined designs serve North American pickup truck conversions where weight constraints displace steel without full composite cost premiums.
- Plastic Cylinders:Polymer-based architectures remain niche, constrained by pressure rating limitations under SAE J1616 protocols.
Composite Cylinders sits at the top of the volume ranking, with Aluminum Cylinders climbing the fastest.
Application:
Application segmentation tracks how fuel system architecture shapes cylinder specification, certification burden, and procurement channel.
- CNG Vehicles:Compressed natural gas applications command the highest pressure ratings at 200-250 bar for Type I steel through 700 bar for hydrogen-adjacent Type IV designs. OEM procurement dominates as dedicated platform engineering integrates cylinder mounting, valve systems, and refueling protocols.
- Dual Fuel Systems:Diesel displacement strategies without full powertrain redesign are expanding cylinder demand across European bus OEMs and Indian commercial fleets. ECE R110 alignment with ISO 11439 streamlines export qualification for Asian manufacturers targeting this segment.
- LPG Vehicles:Lower pressure requirements at 15-30 bar enable mature steel cylinder supply chains with minimal composite penetration.
- Specialty Vehicles:Off-highway and material handling applications specify custom cylinder geometries outside standard automotive form factors.
CNG Vehicles holds the largest installed base, while Dual Fuel Systems gains share fastest on diesel substitution economics.
End User:
Procurement authority concentration varies dramatically across end user types, from centralized OEM engineering to fragmented aftermarket decision-making.
- Fleet Operators:Consolidated procurement through fleet management platforms bundles vehicle conversion, cylinder leasing, and maintenance into single-contract structures. Last-mile logistics operators in Indian metropolitan clusters drive volume as fuel cost differentials against diesel widen.
- OEMs:Original equipment manufacturers specify Type IV composite cylinders for dedicated CNG platforms where weight-driven fuel economy gains justify premium positioning.
- Aftermarket Providers:Fragmented retrofit channels in South Asia anchor steel cylinder volumes, constrained by price sensitivity and certification complexity.
- Rental Services:Vehicle leasing operators intermediate cylinder procurement decisions, favoring standardized specifications across mixed fleets.
Fleet Operators commands the deepest procurement volume, with OEMs expanding most quickly on dedicated platform adoption.
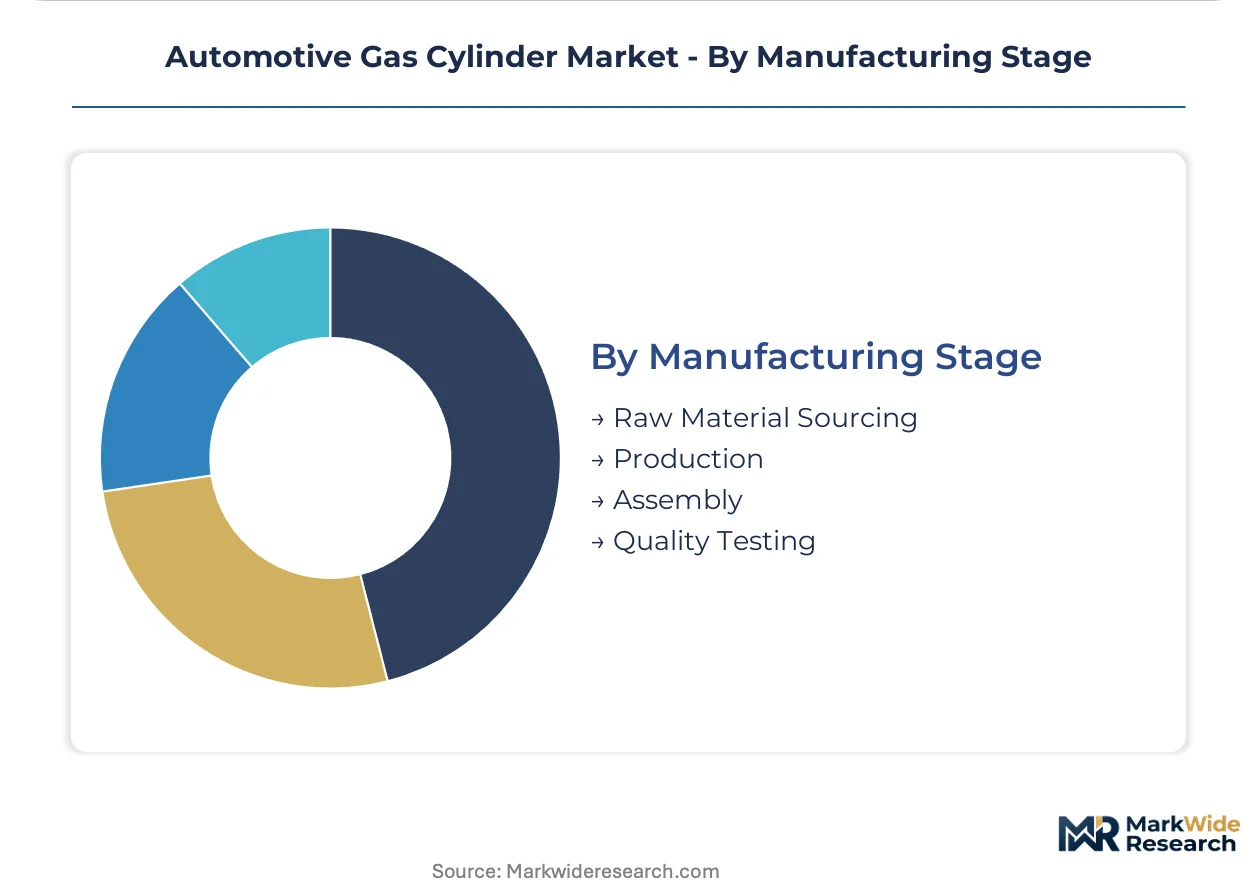
Manufacturing Stage:
Value capture concentration shifts downstream as certification requirements and quality testing create bottlenecks that filter supplier participation.
- Quality Testing:Hydrostatic validation and cyclic fatigue testing under ISO 11439 or SAE J1616 protocols create capability scarcity that extends lead times and concentrates margin. India's PESO enforcement excludes uncertified import competition.
- Production:Filament winding and tow-placement automation absorb labor-intensive steps in Type IV cylinder manufacturing, reducing unit cost variance.
- Raw Material Sourcing:Carbon fiber feedstock availability concentrates among specialized chemical producers, creating input cost volatility.
- Assembly:Valve integration and system packaging finalizes cylinder modules for platform-specific mounting.
Quality Testing captures the steepest margin expansion, with Production automation climbing fastest on labor substitution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate to jurisdictions where certification cost differentials widen competitive advantage. Compliance burden variation between India's BIS hydrostatic protocols and EU REACH substance restrictions creates strategic positioning incentives.
India
Maharashtra and Gujarat concentrate fleet operator procurement where city gas distribution density supports dedicated CNG platform economics. BIS certification mandates for composite cylinders enforce material traceability standards that exclude uncertified import competition. PESO hydrostatic test cycle enforcement extends supplier qualification timelines, locking in incumbent domestic manufacturers around Mumbai and Ahmedabad industrial corridors.
United States
North American pickup truck conversions drive aluminum-lined hybrid cylinder specification where weight constraints displace steel alternatives. DOT FMVSS 304 governs cylinder integrity and evaporative emission performance for alternative fuel vehicle conversions. California and Texas anchor retrofit channel volume as fleet operators prioritize total cost of ownership calculations in last-mile logistics applications.
Germany
European bus OEM integration demands ECE R110 alignment with ISO 11439 for streamlined export qualification. REACH substance restrictions on resin systems force reformulation of polymer liners, extending material qualification cycles for manufacturers serving EU markets. Bavaria-based testing facilities concentrate captive validation capacity to maintain certification continuity under tightening chemical regulations.
China
Filament-winding automation investment absorbs labor-intensive production steps, reducing unit cost variance for Type IV cylinder output. GB standards and MIIT oversight shape domestic certification requirements that diverge from Western protocols. Yangtze River Delta manufacturing clusters scale tow-placement robotics to serve municipal fleet electrification alternatives across provincial transit authorities.
Brazil
LPG aftermarket retrofit channels sustain steel cylinder demand where price sensitivity overrides composite weight advantages. ANVISA alignment with international pressure vessel standards creates qualification pathways for import suppliers. São Paulo state anchors volume concentration as urban fleet operators evaluate dual fuel system economics against diesel displacement targets.
Automotive Gas Cylinder Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scale filament-winding automation to capture Type IV composite volume growth. The vendor base stratifies across three tiers: integrated chemical producers controlling carbon fiber feedstock, specialized cylinder fabricators with captive testing capacity, and regional retrofit distributors serving price-sensitive aftermarket channels. Two strategic archetypes define positioning: technology licensors with patented liner-wrapping processes, and scale operators consolidating regional certification authority. Geographic expansion and backward integration into carbon fiber supply represent the dominant competitive moves.
Among composite specialists, Hexagon Composites and Luxfer Gas Cylinders occupy positions exemplifying divergent regional strategies, while Everest Kanto Cylinder Ltd represents the steel-cylinder incumbent archetype anchoring South Asian retrofit density. These three entities illustrate how material technology specialization maps to procurement channel concentration.
| Leading Market Players |
|---|
| Luxfer Gas Cylinders |
| Everest Kanto Cylinder Ltd |
| Hexagon Composites |
| Worthington Industries |
| Faber Industrie |
| CIMC Enric Holdings |
| CNG Cylinders International |
| Quantum Fuel Systems LLC |
| Beijing China Tank Industry Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Fleet operator procurement consolidation through single-contract bundling concentrates buying power among Indian last-mile logistics platforms, compressing distributor margins and forcing tiered pricing structures that separate Type IV composite premiums from steel cylinder economy tiers.
Pricing Analysis
Distributor margins absorb the steepest compression as OEM direct contracts bypass traditional channel layers for Type IV composite procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence under ECE R110 versus BIS protocols, with aftermarket retrofit channels exhibiting highest price sensitivity due to total cost of ownership calculations. Pricing pressure stems from carbon fiber feedstock volatility transmitted through filament-winding fabricators.
Supply Chain Analysis
Filament-winding automation talent scarcity in Yangtze River Delta and Bavaria clusters constrains Type IV cylinder output scaling despite robotic tow-placement investment. Geographic supply concentration centers on China, India, and Germany for composite architectures, while steel cylinder fabrication draws from South Asian metalworking corridors. Carbon fiber, polymer liner resins, and hydrostatic testing equipment constitute critical input dependencies. Single-source vulnerability concentrates in specialized chemical producers controlling carbon fiber precursor supply. Distribution runs through captive OEM logistics for dedicated platforms and fragmented aftermarket distributors for retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
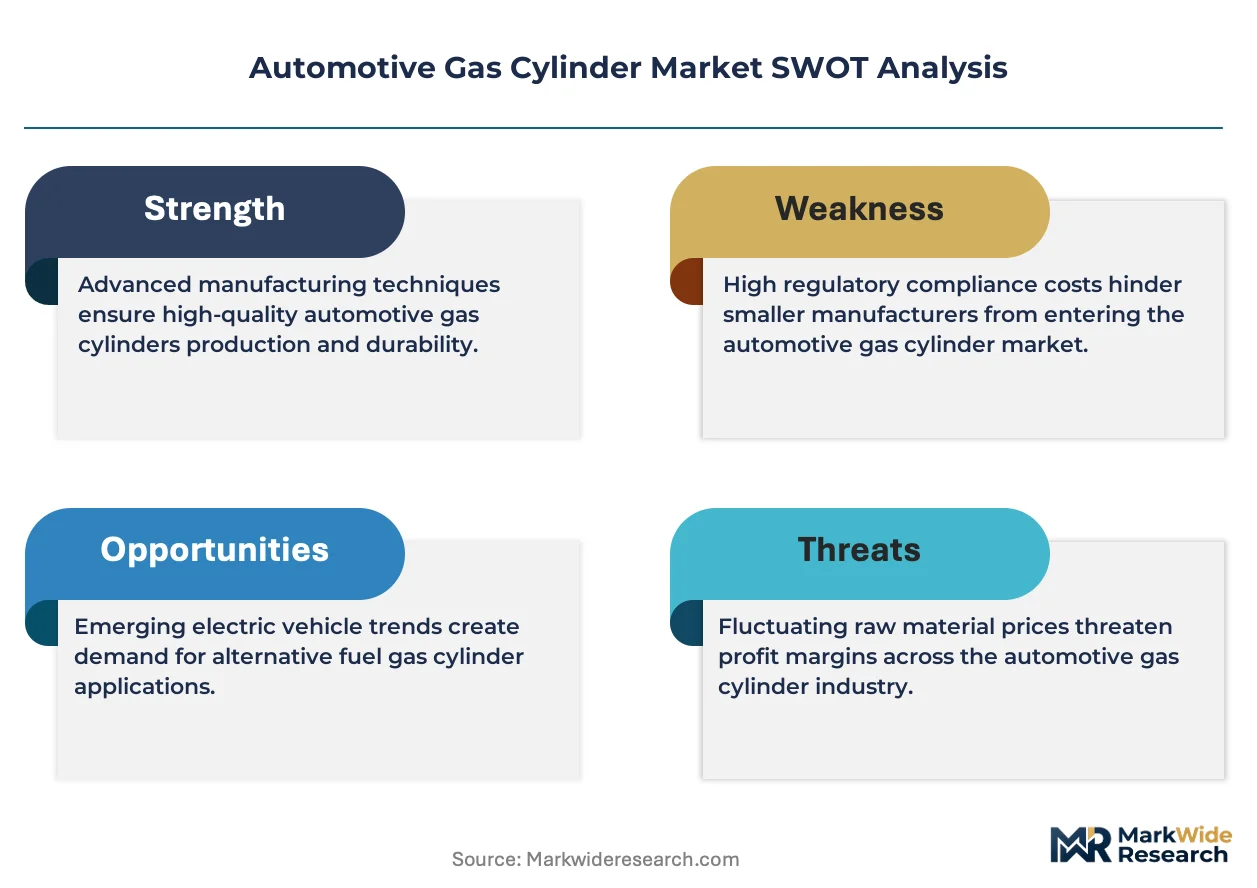
This market reads as a late-cycle quality story where fleet operator specification shifts toward Type IV composite cylinders for dedicated CNG platforms reward certified manufacturers with testing capacity scarcity premiums.
For Market Incumbents: Anticipate hydrogen storage standard convergence by establishing captive validation capacity for 700 bar protocols before fuel cell commercialization accelerates. Defend position through backward integration into carbon fiber precursor supply to neutralize feedstock cost volatility. Prioritize ECE R110 certification continuity under REACH resin reformulation timelines.
For New Entrants and Emerging Players: Begin with aluminum-lined hybrid cylinder specification for North American pickup conversion channels where weight constraints displace steel without full composite cost premiums. Target fleet management platform partnerships in Indian metropolitan clusters bundling conversion, leasing, and maintenance. Pursue tow-placement automation partnerships to compress unit cost variance against established filament-winding specialists.
For Investors and Strategic Acquirers: Chemical producers with carbon fiber precursor assets are the most active acquirer in this space, seeking downstream cylinder fabrication capabilities to capture margin concentration at quality testing stages. Long-term viability favors manufacturers with multi-standard certification authority spanning DOT FMVSS 304, ECE R110, and BIS protocols. Monitor hydrogen storage cylinder standard divergence as inflection indicator for traditional CNG supply chain boundary disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Filament-Winding Automation Scale-Up | Robotic tow-placement reduces unit cost variance for European bus OEM procurement expansion. |
| Captive Testing Capacity Establishment | In-house ISO 11439 validation compresses hydrostatic cycle timelines under India's PESO enforcement. |
| Carbon Fiber Precursor Backward Integration | Upstream control over specialized chemical feedstock neutralizes input cost volatility concentration. |
| Fleet Management Platform Partnership | Single-contract bundling displaces fragmented aftermarket purchasing in dense city gas distribution networks. |
| Multi-Standard Certification Investment | Simultaneous ECE R110 and BIS authority streamlines export qualification for Asian manufacturers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, fleet operator logistics directors, and aftermarket retrofit distributors with secondary validation against SEC filings, vehicle production databases, IHS Markit registration data, and customs trade records. Bottom-up cylinder shipment tallies triangulated against top-down fuel system market sizing.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation modeling across cylinder architecture type, application fuel system, end-user procurement channel, and manufacturing stage value capture. CAGRs derived from regression analysis of fleet conversion rates, city gas distribution network expansion, and OEM platform redesign cycles. Industry-specific inputs included carbon fiber feedstock price indices and hydrostatic testing capacity utilization rates.
Several conditions sit outside the modeled scope, including hydrogen fuel cell commercialization acceleration timelines and REACH substance restriction scope expansion beyond resin systems. Forecasts reflect documented assumptions about certification timeline stability and fleet operator fuel cost differential persistence. Practitioners should monitor BIS composite cylinder mandate enforcement intensity and carbon fiber producer capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Africa CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Ethanol Vehicle Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Dual Fuel Engine Market