
 Automotive Fuel Cell System Market | 2026-2036
Automotive Fuel Cell System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Cell System Market Outlook
Subscription-based hydrogen fueling and predictive maintenance contracts is consolidating revenue streams around lifetime vehicle operating cost rather than upfront hardware sales. Toyota Motor Corporation leverages its captive hydrogen supply partnerships to lock in fleet operators across Japan and California. Hyundai Motor Company anchors its strategy through integrated production of fuel cell stacks and membrane electrode assemblies at its dedicated plant in Chungju, South Korea. Ballard Power Systems specializes in heavy-duty module architectures that dominate North American bus and truck retrofit programs.
An automotive fuel cell system converts hydrogen or hydrogen-rich fuel into electricity through electrochemical reaction, typically operating at 60-80°C for proton exchange membrane configurations and delivering 80-120 kW gross power output for passenger vehicle platforms. Its primary commercial purpose is zero-emission vehicle propulsion with refueling times under five minutes, addressing range and downtime constraints that limit battery-electric alternatives in commercial duty cycles. Proton exchange membrane technology leads installed capacity due to its cold-start capability and power density suited to automotive packaging constraints. Hydrogen fuel cells capture the dominant share of OEM development spending, while methanol fuel cell architectures occupy niche applications in remote or liquid-fuel-constrained environments. Commercial vehicles represent the fastest-growing end-user category as freight operators face tightening well-to-wheel emission accounting.
The EPA and NHTSA in the United States coordinate greenhouse gas and fuel economy standards that effectively mandate zero-emission powertrain penetration in heavy-duty segments by the mid-2030s. The EU F-Gas Regulation and CE marking requirements under the EU Green Deal shape component material selection and system certification pathways for European market entry. Japan's METI hydrogen strategy directs public-private investment into domestic refueling infrastructure that underpins OEM sales commitments. Stakeholders must monitor regulatory timing divergence across these jurisdictions, as misaligned compliance deadlines risk stranding development capital in markets with delayed enforcement.
Market Dynamics
Fleet operators in heavy-duty trucking are consolidating procurement around hydrogen fuel cell platforms as California's Advanced Clean Trucks regulation and Japan's METI hydrogen roadmap force zero-emission compliance timelines. This regulatory compression is redirecting OEM engineering budgets away from incremental battery improvements toward integrated fuel cell system architectures.
Growth Catalysts
- California Advanced Clean Trucks Regulation:Mandates zero-emission truck sales percentages that accelerate fleet turnover and fuel cell vehicle procurement in North American heavy-duty segments.
- Heavy-duty freight operators:Face tightening well-to-wheel emission accounting that disqualifies diesel alternatives and validates hydrogen fuel cells for long-haul duty cycles.
- German Rhineland industrial corridor:Concentrates automotive manufacturing clusters with overlapping refueling infrastructure, creating demand density unmatched elsewhere in Europe.
Market Restraints
- Platinum group metal cost volatility:Membrane electrode assembly production depends on iridium and platinum catalysts with concentrated supply from South African and Russian mining operations.
- Proton exchange membrane technical limitation:Cold-start performance below minus twenty degrees Celsius requires auxiliary battery systems that add weight and complexity.
- EU F-Gas Regulation:Restricts fluorinated polymer use in membrane manufacturing, forcing material substitutions that extend certification timelines.
Strategic Opportunities
- India's PLI scheme for automotive components:Offers production-linked incentives that could localize fuel cell stack assembly for emerging commercial vehicle demand.
- Maritime port drayage applications:Present untapped demand as container terminal operators seek zero-emission alternatives to diesel yard tractors.
- Subscription-based hydrogen fueling contracts:Lock in fleet operators through lifetime operating cost models rather than upfront hardware sales.
Industry Challenges
- Membrane electrode assembly fabrication skill gap:Precision coating and catalyst deposition require specialized technicians scarce outside South Korean and Japanese supplier bases.
- CE marking certification timeline:EU component material selection and system validation pathways extend market entry by twelve to eighteen months for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Cell System Market |
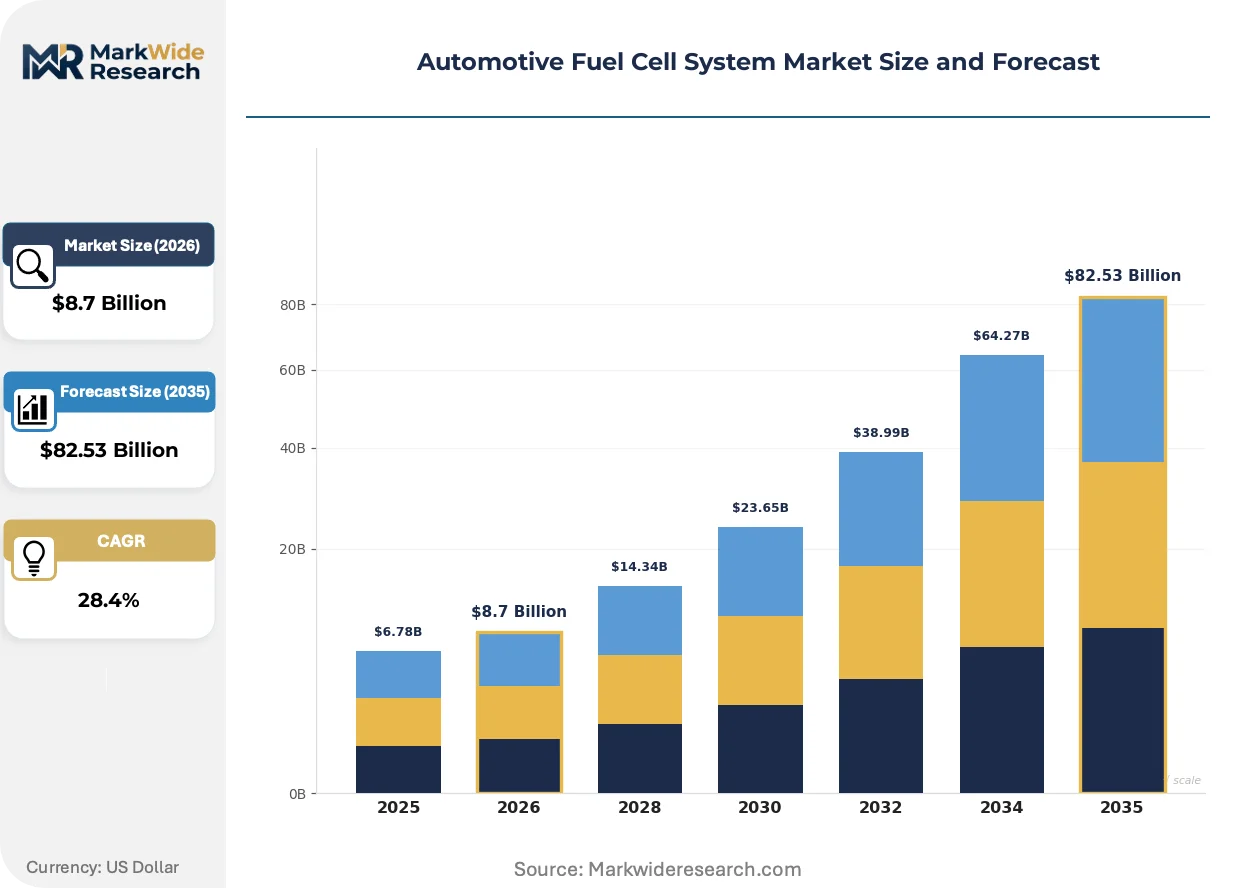
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $82.53 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Exchange Membrane, Solid Oxide, Alkaline, Phosphoric Acid Technology: Hydrogen Fuel Cells, Methanol Fuel Cells, Reformed Fuel Cells, Biogas Fuel Cells End User: Passenger Vehicles, Commercial Vehicles, Public Transport, Construction Equipment Application: Vehicle Propulsion, Backup Power, Stationary Power Generation, Portable Power |
| Companies Covered | Toyota Motor Corporation, Hyundai Motor Company, Honda Motor Co., Ltd., Ballard Power Systems, Plug Power, Cummins Inc., Robert Bosch GmbH, Nuvera Fuel Cells, PowerCell Sweden AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Cell System Market Strategic Shifts
Electrolyzer cost reductions and green hydrogen production scale-up are reshaping fuel cell economics. Three interconnected developments are compressing technology adoption cycles and reconfiguring competitive positioning across passenger and commercial vehicle platforms.
Solid oxide fuel cell auxiliary power units are consolidating range-extender applications in long-haul trucking. Freight operators testing hybrid architectures pair proton exchange membrane primary propulsion with solid oxide units for hoteling loads. This dual-stack approach is consolidating supplier relationships around integrated thermal management and fuel processing subsystems.
Japan's METI hydrogen strategy directs public-private investment into domestic refueling infrastructure that underpins OEM sales commitments. The policy framework mandates station deployment density targets that de-risk fleet operator adoption decisions. Heavy-duty commercial vehicle categories face the tightest compliance deadlines and are responding with binding procurement commitments.
Fleet operators are unbundling vehicle acquisition from fuel supply and maintenance obligations. Traditional outright purchase models lose share to performance-based contracts where suppliers guarantee uptime and per-mile hydrogen cost ceilings. This restructuring is most visible in California's Central Valley agricultural logistics corridors and Japan's Kanto industrial freight networks.
Automotive Fuel Cell System Market Segmentation
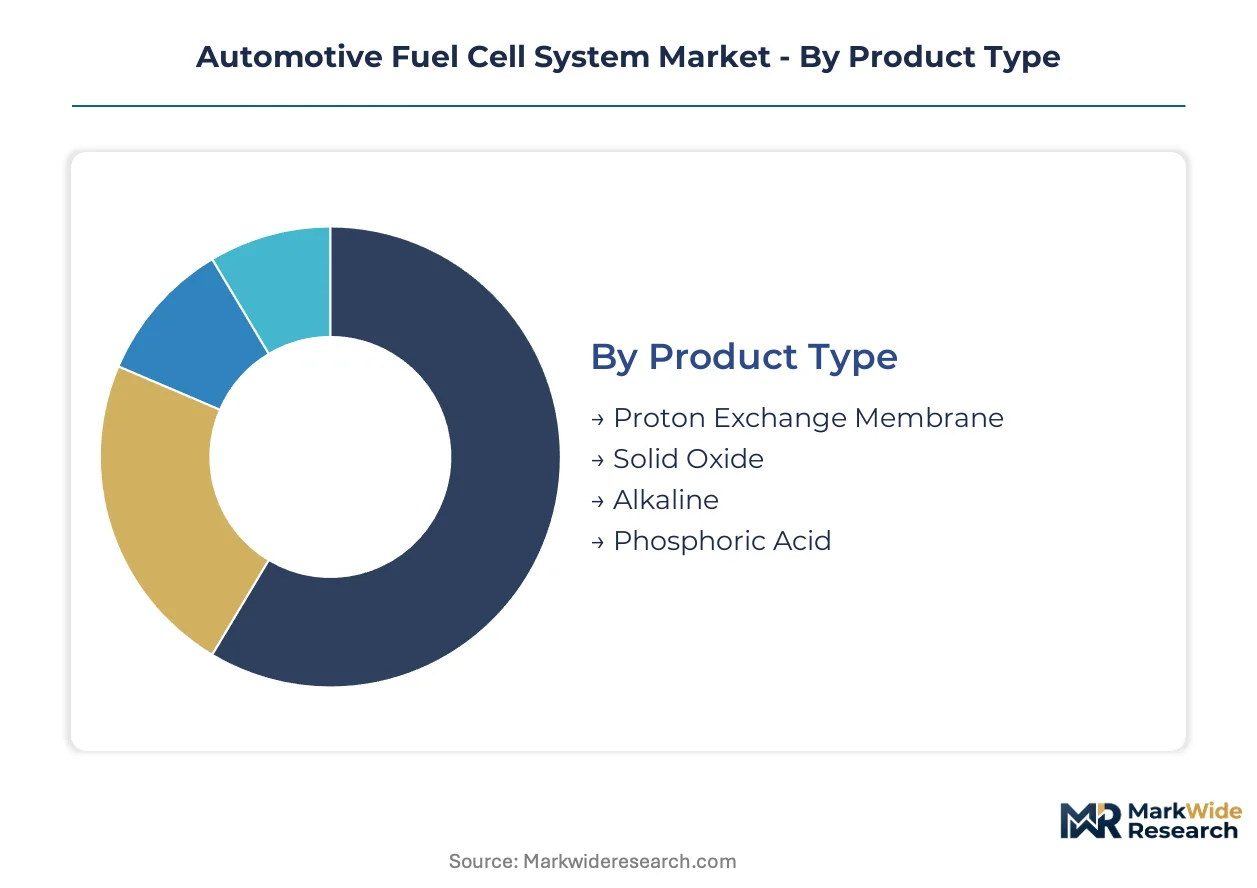
Segmentation in automotive fuel cell systems reveals how certification requirements, duty-cycle demands, and infrastructure availability fragment addressable markets. Each dimension carries distinct regulatory burdens and procurement patterns that shape supplier strategy.
Product Type:
CE marking under EU F-Gas Regulation and EPA certification pathways impose divergent material constraints across membrane technologies. Proton exchange membrane systems face fluorinated polymer restrictions, while solid oxide architectures navigate thermal cycling validation protocols.
- Proton Exchange Membrane:Operates at 60-80°C with 80-120 kW gross output for passenger vehicle platforms. Cold-start capability below freezing temperatures drives adoption in Germany's Rhineland corridor and Japan's Kanto freight networks, though auxiliary battery systems add weight penalties.
- Solid Oxide:Functions at 600-800°C with superior electrical efficiency for range-extender applications in long-haul trucking. Freight operators in California's Central Valley agricultural logistics corridors pair solid oxide auxiliary power units with primary proton exchange membrane propulsion for hoteling loads.
- Alkaline:Uses liquid electrolyte configurations with lower platinum catalyst loading. Niche deployment in stationary power generation applications where packaging constraints relax.
- Phosphoric Acid:Mature technology with established maintenance protocols. Limited automotive penetration due to lower power density and slower transient response.
Leading the category by volume: Proton Exchange Membrane. Growing fastest: Solid Oxide.
Technology:
Feedstock availability and refueling infrastructure density determine technology selection across end-use categories. Hydrogen supply chain maturity concentrates investment in specific geographies while alternative fuels occupy constrained niches.
- Hydrogen Fuel Cells:Captures dominant OEM development spending with refueling times under five minutes. Japan's METI hydrogen roadmap and California's Advanced Clean Trucks regulation mandate deployment timelines that lock in fleet procurement commitments.
- Methanol Fuel Cells:Liquid fuel compatibility suits remote or hydrogen-constrained environments. Maritime port drayage applications in liquid-fuel-dependent terminals present emerging demand pockets.
- Reformed Fuel Cells:On-board fuel processing enables infrastructure flexibility. Limited adoption due to system complexity and reformer maintenance burdens.
- Biogas Fuel Cells:Waste-to-energy pathways align with circular economy mandates in EU Green Deal jurisdictions. Scale constraints restrict automotive applications.
Volume concentration: Hydrogen Fuel Cells. Steepest expansion trajectory: Methanol Fuel Cells in specialized logistics.
End User:
Duty-cycle intensity and emission compliance deadlines stratify procurement urgency across vehicle categories. Heavy-duty segments face the tightest regulatory compression.
- Commercial Vehicles:Long-haul freight operators face tightening well-to-wheel emission accounting that validates fuel cell economics. Binding procurement commitments from North American and European fleet operators redirect OEM engineering budgets toward integrated system architectures.
- Public Transport:Municipal bus fleets with fixed-route predictability support hydrogen station utilization rates. Ballard Power Systems dominates North American bus retrofit programs with heavy-duty module architectures.
- Passenger Vehicles:Range and refueling convenience compete against battery-electric alternatives. Toyota Motor Corporation leverages captive hydrogen supply partnerships to lock in fleet operators across Japan and California.
- Construction Equipment:Intermittent duty cycles and site-based refueling challenges limit adoption. Niche applications in urban emission-restricted zones.
Revenue concentration: Commercial Vehicles. Gaining share fastest: Public Transport.
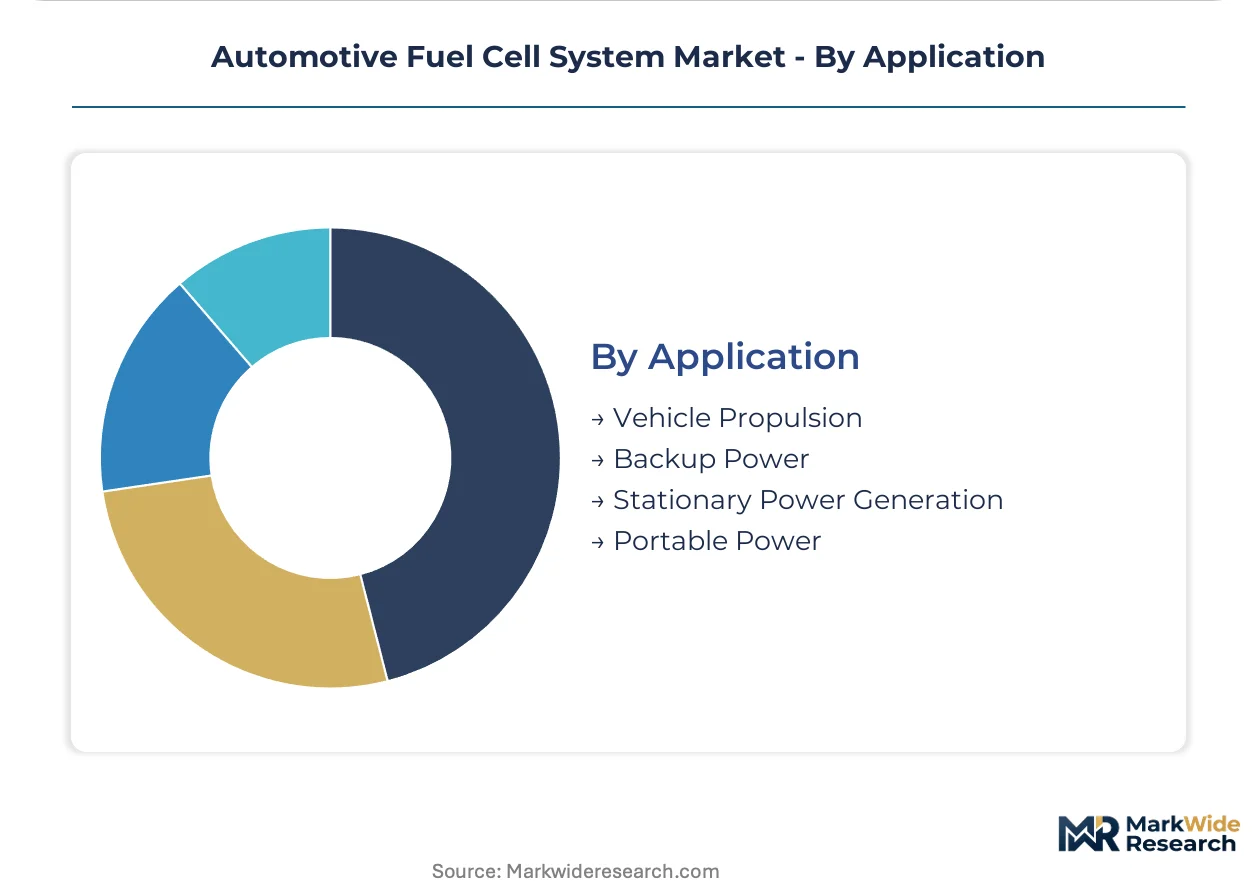
Application:
Performance guarantees and uptime requirements shape contract structures differently across stationary and mobile applications. Subscription-based models concentrate in vehicle propulsion.
- Vehicle Propulsion:Primary commercial purpose with zero-emission mandates driving procurement. Performance-based contracts where suppliers guarantee uptime and per-mile hydrogen cost ceilings restructure traditional outright purchase models.
- Backup Power:Grid resilience applications in data center and critical infrastructure settings. Stationary fuel cell systems compete against diesel generators in emission-restricted jurisdictions.
- Stationary Power Generation:Combined heat and output configurations suit industrial facility baseload. German Rhineland industrial corridor concentrations overlap automotive manufacturing clusters.
- Portable Power:Military and emergency response applications prioritize energy density. Limited scale constrains supplier investment.
Deployment scale: Vehicle Propulsion. Climbing the fastest: Backup Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of membrane electrode assemblies and fuel cell stacks concentrates in South Korea and Japan, while fleet deployment and hydrogen consumption accelerate across Germany, the United States, and California's regulatory corridors.
United States
California's Advanced Clean Trucks regulation mandates zero-emission truck sales percentages that force fleet turnover timelines. The EPA and NHTSA coordinate greenhouse gas standards that effectively require zero-emission powertrain penetration in heavy-duty segments by the mid-2030s. The Central Valley agricultural logistics corridor sees binding procurement commitments from freight operators seeking performance-based fuel contracts.
Germany
The Rhineland industrial corridor concentrates automotive manufacturing clusters with overlapping hydrogen refueling infrastructure, creating unmatched demand density in Europe. The EU F-Gas Regulation restricts fluorinated polymer use in membrane manufacturing, forcing material substitutions that extend certification timelines. Bavaria and North Rhine-Westphalia host OEM engineering centers redirecting budgets toward integrated fuel cell system architectures.
Japan
METI's hydrogen roadmap directs public-private investment into domestic refueling infrastructure with mandated station deployment density targets. The national hydrogen strategy de-risks fleet operator adoption decisions through binding public procurement commitments. The Kanto industrial freight network around Tokyo anchors captive hydrogen supply partnerships that lock in commercial vehicle operators.
South Korea
Chungju hosts dedicated fuel cell stack and membrane electrode assembly production facilities serving both domestic and export markets. The country's national automotive regulator enforces emission benchmarks that accelerate OEM engineering budget reallocation. Busan-Ulsan industrial zones concentrate precision coating and catalyst deposition technician training programs addressing fabrication skill gaps.
China
Dual carbon goals under MIIT direction redirect state-backed investment toward hydrogen fuel cell commercial vehicle deployment in the Yangtze River Delta. The national standards body (GB standards) shapes component material selection pathways distinct from EU or US certification regimes. Sichuan-Chongqing industrial corridors leverage low-cost electrolyzer production to compress fuel cell economics for heavy-duty freight operators.
Automotive Fuel Cell System Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the automotive fuel cell system value chain. Integrated OEMs with captive hydrogen supply partnerships hold structural advantages in fleet operator lock-in, while independent stack suppliers compete on module architecture specialization for retrofit programs. Three archetypes dominate: vertically integrated automakers controlling full fuel cell production, specialized stack and membrane component fabricators, and hydrogen infrastructure operators bundling fuel supply with vehicle procurement. Competitive moves concentrate on strategic partnerships securing platinum group metal supply chains and geographic expansion into regulatory-compressed markets with binding zero-emission deadlines.
Among Japanese and South Korean automakers, Toyota Motor Corporation and Hyundai Motor Company exemplify the integrated OEM archetype through captive production of fuel cell stacks and membrane electrode assemblies. Ballard Power Systems occupies a specialist position in heavy-duty module architectures for North American commercial vehicle applications. These three anchors represent divergent strategic postures: full vertical integration versus component specialization versus regional market focus.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| Hyundai Motor Company |
| Honda Motor Co., Ltd. |
| Ballard Power Systems |
| Plug Power |
| Cummins Inc. |
| Robert Bosch GmbH |
| Nuvera Fuel Cells |
| PowerCell Sweden AB |
| Others |
Value Chain & Pricing Dynamics
Solid oxide fuel cell commercialization at scale is compressing membrane electrode assembly cost curves while concentrating platinum group metal sourcing decisions in South African and Russian mining corridors. This dual transformation simultaneously reshapes stack pricing power and exposes buyers to concentrated catalyst supply risk.
Pricing Analysis
Margin tightening in heavy-duty module tiers reflects platinum group metal cost volatility and membrane fabrication yield losses. Three-tier pricing structure across premium certified, standard OEM-grade, and economy retrofit levels separates fleet operators by compliance deadline urgency. Cost-down pressure on passenger vehicle stacks accelerates as battery-electric alternatives narrow the total-cost-of-ownership gap. Commercial vehicle procurement teams exhibit highest price sensitivity due to lifetime fuel cost guarantees, while municipal bus fleets accept premium pricing for uptime commitments.
Supply Chain Analysis
Dual-sourcing mandates from Toyota and Hyundai procurement teams require qualified membrane electrode assembly suppliers in both South Korea and Japan. Geographic supply concentration centers on South Korea for stack assembly, Japan for precision coating equipment, and South Africa for platinum and iridium catalysts. Raw material dependencies include perfluorinated ionomer membranes, titanium bipolar plates, and carbon fiber gas diffusion layers. Single-source vulnerability in South African platinum mining exposes production schedules to commodity disruption. Distribution runs through captive OEM supply chains for integrated automakers and tiered supplier networks for independent stack producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive fuel cell competition has become a vertical-integration race where captive hydrogen supply partnerships and in-house membrane electrode assembly production determine fleet operator lock-in. Players are pursuing upstream catalyst supply agreements and downstream fueling infrastructure stakes as the decisive levers.
For Market Incumbents: Deploy long-term offtake contracts with South African platinum miners to hedge catalyst cost exposure against Russian supply disruption. Secure dedicated membrane electrode assembly production lines in Chungju or Bavaria to defend yield rates against emerging Chinese stack producers. Cement fleet relationships through subscription-based hydrogen fueling contracts that bundle vehicle procurement with guaranteed per-mile cost ceilings.
For New Entrants and Emerging Players: Solid oxide auxiliary power unit architectures for long-haul trucking hoteling loads offer the most penetrable wedge against established proton exchange membrane incumbents. Target India's PLI scheme production-linked incentives for automotive component localization to access emerging commercial vehicle demand with lower capital intensity. Pursue maritime port drayage applications where liquid methanol compatibility bypasses hydrogen infrastructure constraints.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated OEMs seeking membrane electrode assembly fabrication capabilities. Long-term viability hinges on green hydrogen production cost compression and refueling station deployment density across the analysis window. Acquisition target archetypes include specialized stack suppliers with heavy-duty module certifications and precision coating technicians. Watch electrolyzer capacity buildout announcements as the signal for fuel cell demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Catalyst Supply Agreement | Long-term platinum offtake contracts hedge against South African mining volatility and Russian export restrictions. |
| Membrane Electrode Assembly Capacity Expansion | Dedicated production lines in Chungju or Bavaria defend yield rates and certification timelines against new entrants. |
| Hydrogen Fueling Infrastructure Partnership | Station deployment commitments in California's Central Valley de-risk fleet operator adoption decisions. |
| Solid Oxide Technology Licensing | Range-extender architectures for long-haul trucking hoteling loads open adjacent revenue streams. |
| Precision Coating Technician Training Program | Fabrication skill development in Busan-Ulsan industrial zones addresses scarce membrane deposition expertise. |
Study Parameters
Document review covered EPA certification filings, EU F-Gas Regulation compliance databases, METI hydrogen roadmap progress reports, and OEM engineering budget disclosures, complemented by interviews with fuel cell stack procurement managers, membrane electrode assembly production engineers, fleet operator sustainability directors, and hydrogen station infrastructure developers. Secondary validation drew from vehicle production databases, customs trade records for platinum group metals, and IEA hydrogen supply chain tracking. Bottom-up stack shipment data triangulated against top-down OEM powertrain investment disclosures.
Cross-referencing historical deployment patterns with expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel cell product type, feedstock technology, end-user vehicle category, and application purpose. CAGRs were derived from install-base growth trajectories and replacement cycle analysis. Industry-specific forecast inputs incorporated California Advanced Clean Trucks regulatory compliance deadlines and Japan's METI station deployment density targets.
Several conditions sit outside the modeled scope, including breakthrough solid-state battery commercialization timelines, hydrogen pipeline infrastructure buildout acceleration, and unilateral export restrictions on South African platinum. Forecasts reflect documented assumptions about electrolyzer cost reduction curves and green hydrogen production scale-up. Deviation in platinum group metal supply disruption severity or battery-electric range improvement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
Ethanol Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market