
 Global Ethanol-Based Vehicle Market | 2026-2036
Global Ethanol-Based Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ethanol-Based Vehicle Market Analysis
Brazilian sugarcane processors are shifting capacity toward anhydrous ethanol for vehicular fuel, tightening feedstock availability for regional automakers. Ford Motor Company leverages its São Paulo engineering center to sustain flex-fuel powertrain development for Latin American markets. Toyota Motor Corporation anchors its ethanol-hybrid strategy through dedicated engine variants produced at Indaiatuba facility. Volkswagen AG competes with localized flex-fuel SUV platforms that dominate dealership channels across Minas Gerais and Paraná states.
An ethanol-based vehicle uses spark-ignition engines calibrated to burn hydrous or anhydrous ethanol blends, typically requiring modified fuel injectors, corrosion-resistant seals, and adjusted compression ratios between 12:1 and 14:1 to optimize combustion efficiency. The primary commercial purpose centers on reducing petroleum dependency while utilizing renewable biomass feedstocks within existing internal combustion infrastructure. Flex Fuel System technology leads installation volumes across OEM assembly lines, while Engine Modification services capture margin pools in aftermarket conversion workshops. E85 fuel type dominates Brazilian consumer sales, though E100 capability differentiates premium sedan configurations aimed at sugarcane-belt fleet operators.
Brazil's ANP blending mandates and the United States EPA Renewable Fuel Standard create divergent compliance pathways that shape engine calibration standards and fuel infrastructure investments across both markets. India's MoRTH ethanol notification and BIS fuel quality specifications are accelerating OEM pilot programs for E20-compatible powertrains in Maharashtra and Uttar Pradesh manufacturing zones. Stakeholders must monitor how California LCFS credit dynamics and EU Green Deal sustainability criteria redefine ethanol lifecycle accounting methods for export-oriented vehicle segments.
Market Dynamics
Brazil's RenovaBio carbon intensity framework and the United States EPA Renewable Fuel Standard are tightening blending mandates simultaneously, forcing automakers to recalibrate powertrains for divergent ethanol specifications across Atlantic and Pacific supply corridors.
Growth Catalysts
- RenovaBio Decarbonization Credits:Brazilian fleet operators earn tradeable CBios credits by purchasing E100-capable vehicles, channeling procurement toward flex-fuel configurations in São Paulo's sugarcane belt.
- E20 Mandate Trajectory:India's MoRTH notification requires E20-compatible powertrains by 2025, accelerating OEM pilot programs in Maharashtra manufacturing zones.
- Sugarcane Bagasse Cogeneration:Processors now divert cellulosic residues toward anhydrous ethanol production, tightening feedstock-to-pump integration for vehicle conversion workshops.
Market Restraints
- Corn Price Volatility:United States ethanol producers face input cost swings from Midwest grain markets, compressing margin pools available for E85 infrastructure subsidies.
- Pump Infrastructure Gaps:European filling stations lack corrosion-resistant E85 dispensing systems, limiting flex-fuel vehicle adoption outside Nordic pilot clusters.
- Cellulosic Conversion Delays:Enzymatic hydrolysis technologies for agricultural residue processing remain below commercial scale, constraining second-generation ethanol supply for high-blend markets.
Strategic Opportunities
- Indonesian Palm Ethanol Pivot:The country's B40 biodiesel program creates regulatory precedent for biofuel vehicle mandates, positioning flex-fuel platforms for parallel ethanol adoption in ASEAN markets.
- Hybrid-Ethanol Convergence:Toyota's dedicated Atkinson-cycle ethanol engines pair with electric motor assist, opening powertrain architectures that satisfy California LCFS credit stacking.
- Fleet Telematics Integration:Sugar-ethanol cooperatives in Goiás state deploy IoT-enabled fuel optimization systems, creating aftermarket service revenue streams for conversion workshops.
Industry Challenges
- Calibration Engineer Scarcity:OEMs in São Paulo's ABC industrial corridor compete for powertrain specialists capable of mapping spark timing across hydrous-ethanol moisture variations.
- Homologation Timeline Compression:Brazil's INMETRO certification requirements for E100 compatibility extend validation cycles, delaying model-year launches for premium sedan configurations.
- Legacy Fuel System Retrofit Complexity:Aftermarket conversion workshops face integration friction when adapting 1990s-era fuel injection architectures to modern ethanol-compatible seal specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ethanol-Based Vehicle Market |
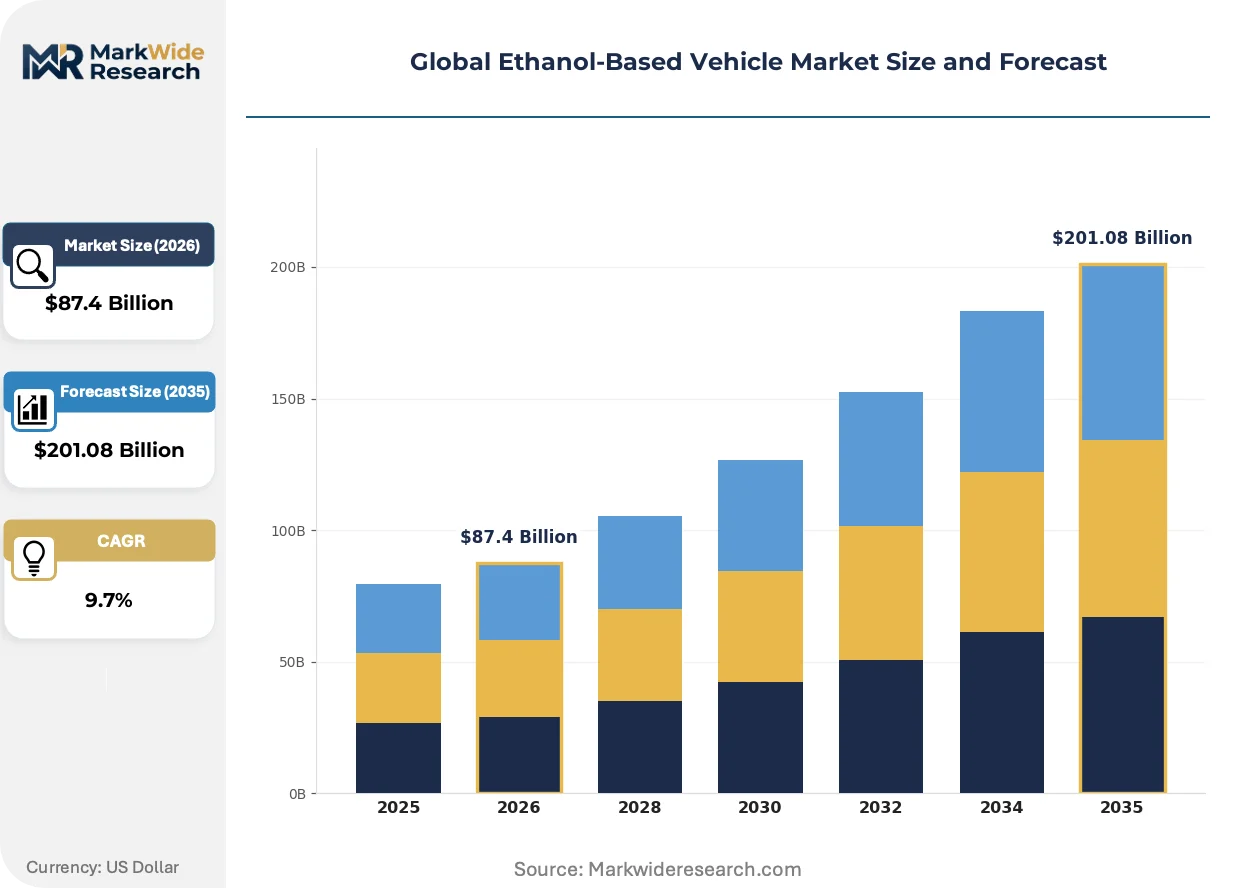
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $201.08 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedans, SUVs, Trucks, Buses Fuel Type: E85, E75, E100, E10 Distribution Channel: Online Retail, Dealerships, Supermarkets, Fuel Stations Technology: Flex Fuel System, Engine Modification, Biofuel Processing, Ethanol Blending |
| Companies Covered | Ford Motor Company, General Motors, Toyota Motor Corporation, Volkswagen AG, Honda Motor Co., Stellantis, Hyundai Motor Company, Mahindra & Mahindra, Nissan Motor Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ethanol-Based Vehicle Market Emerging Trajectories
Spark-ignition powertrain architectures are bifurcating between dedicated ethanol optimization and flexible multi-fuel compatibility, with calibration software emerging as the primary competitive differentiator rather than hardware alone.
Direct injection systems with variable valve timing are consolidating around ethanol-optimized compression ratios between 13:1 and 14:1. Tier-1 suppliers in Stuttgart and Detroit are shipping flex-fuel injector modules to São Paulo assembly plants at triple previous volumes. This hardware standardization is consolidating aftermarket conversion margins into OEM captive service networks.
The EU Green Deal's revised sustainability criteria now mandate lifecycle carbon accounting for ethanol feedstocks, affecting export-oriented vehicle segments bound for European markets. Engine control unit suppliers must document sugarcane cultivation emissions from São Paulo mills to Rotterdam terminals. Premium sedan configurations with blockchain-verified supply chains command preference among Dutch fleet lessors.
Fleet procurement in Brazil's Center-West region now specifies total-cost-of-ownership contracts that unbundle fuel from vehicle acquisition, with sugar-ethanol cooperatives assuming pump-price risk. This model displaces traditional dealership financing in Goiás and Mato Grosso states. Agricultural fleet operators prioritize E100 capability over flex-fuel flexibility, reversing prior consumer-market preferences.
Global Ethanol-Based Vehicle Market Segmentation
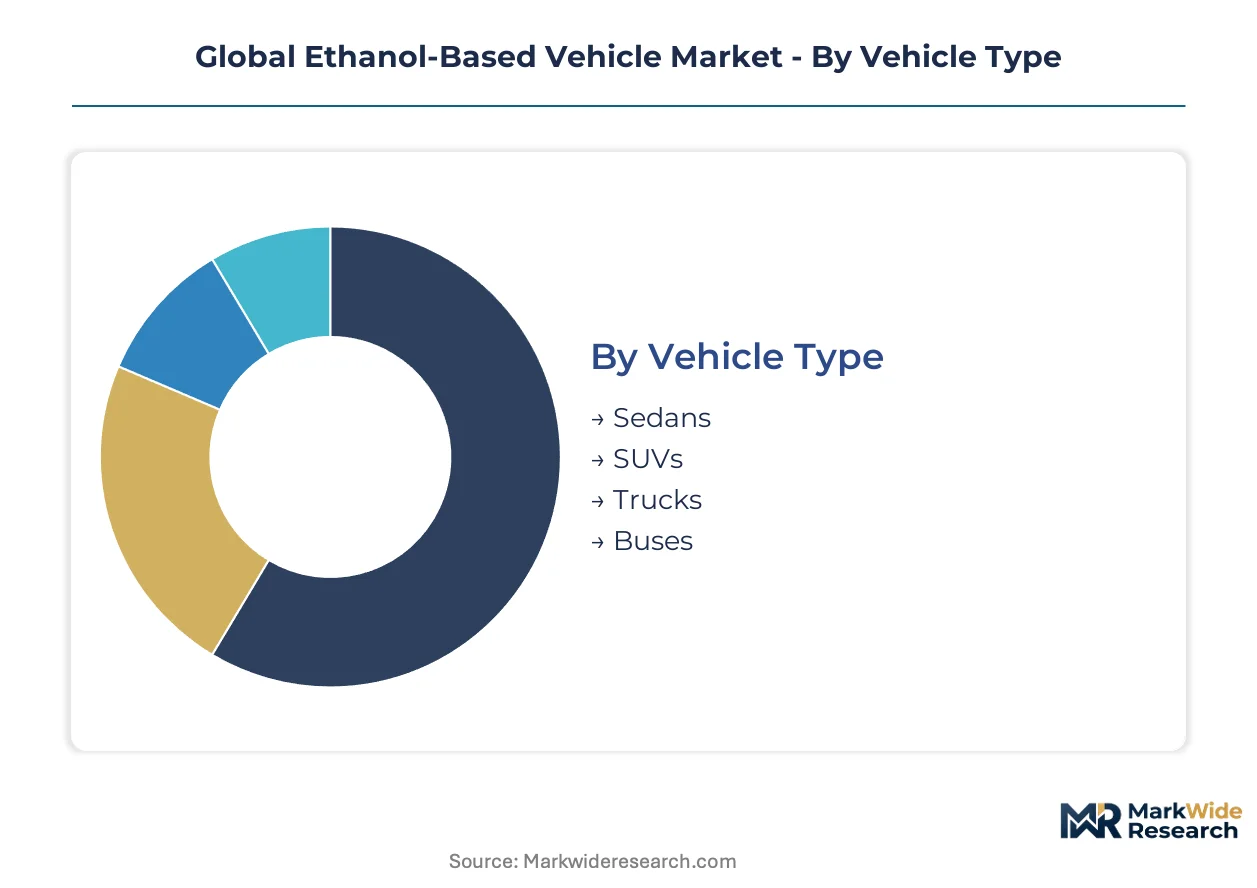
Ethanol-based vehicle segmentation reveals how powertrain architecture, fuel specification, and procurement channel interact to determine commercial viability across divergent regulatory environments. Understanding these intersections helps stakeholders allocate engineering resources and distribution investments toward configurations with durable policy support.
Vehicle Type:
Volume production concentrates on mass-market passenger configurations, while commercial segments command premium pricing through fleet procurement contracts.
- Sedans:Compact and mid-size sedans dominate Brazilian OEM assembly lines, with flex-fuel powertrains standard across São Paulo dealership networks. São Paulo state fleet operators specify E100-capable sedans to maximize RenovaBio CBios credit accumulation.
- SUVs:Higher displacement engines in SUV platforms accommodate elevated compression ratios without sacrificing torque delivery. Volkswagen AG's localized flex-fuel SUV production at Taubaté facility anchors volume in Minas Gerais and Paraná states.
- Trucks:Light commercial trucks with ethanol-optimized engines serve agricultural logistics in Brazil's Center-West region.
- Buses:Urban transit authorities in Brazilian state capitals pilot ethanol-hybrid bus fleets under municipal decarbonization mandates.
Today's leader: Sedans. Tomorrow's challenger: SUVs.
Fuel Type:
Blend specification determines engine calibration complexity, infrastructure requirements, and regulatory compliance pathways across national markets.
- E85:The 85% ethanol blend represents the dominant specification for Brazilian consumer vehicles, balancing cold-start reliability with petroleum displacement. ANP blending mandates enforce E85 minimums at retail pumps nationwide.
- E100:Hydrous ethanol delivers maximum carbon intensity reduction under RenovaBio accounting but requires specialized fuel systems with corrosion-resistant seals and modified spark timing maps.
- E75:Intermediate blends serve transitional markets with inconsistent pump infrastructure quality.
- E10:Low-blend specifications dominate United States compatibility requirements under EPA Renewable Fuel Standard compliance.
Current procurement favors E85 flexibility. Fleet operators are climbing the fastest toward E100 commitment.
Distribution Channel:
Channel selection reflects customer type segmentation, with institutional buyers bypassing retail infrastructure entirely.
- Dealerships:OEM-certified dealers in Brazil's ABC industrial corridor bundle flex-fuel vehicles with manufacturer-backed financing and service contracts.
- Fuel Stations:Integrated fuel-retail networks in Goiás state deploy co-located vehicle conversion workshops, unbundling fuel supply from hardware acquisition.
- Online Retail:Digital procurement platforms serve aftermarket conversion kit distribution to independent workshops.
- Supermarkets:Hypermarket chains with fuel retail licenses in Brazilian secondary cities experiment with vehicle promotion tie-ins.
Dealerships retain volume leadership. Fuel station integration offers the steepest expansion trajectory for fleet-heavy segments.
Technology:
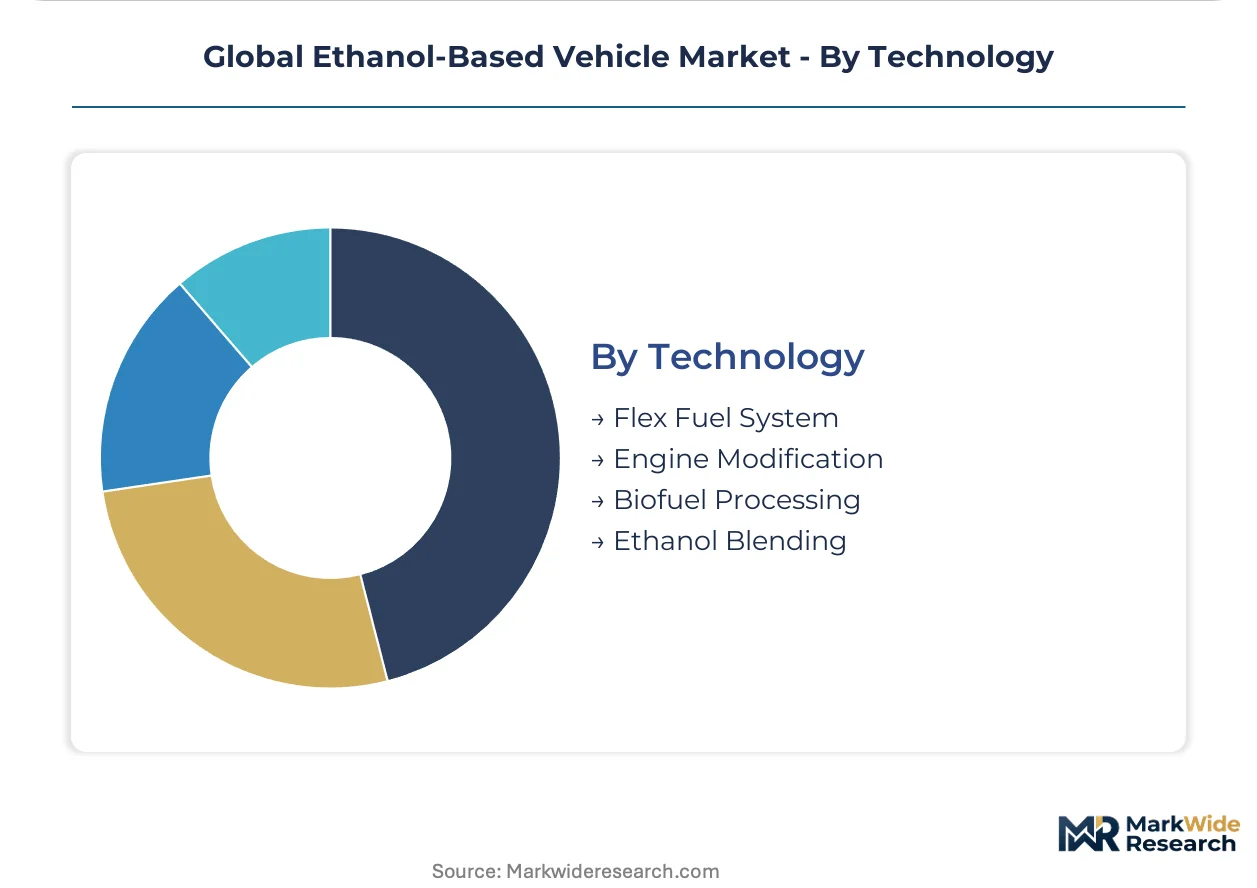
Technology segmentation separates OEM-integrated solutions from aftermarket adaptation services with divergent margin structures.
- Flex Fuel System:Factory-installed flex-fuel systems with multi-sensor fuel composition detection enable seamless switching between gasoline and ethanol blends. Tier-1 suppliers in Stuttgart and Detroit ship flex-fuel injector modules to São Paulo assembly plants at triple previous volumes.
- Engine Modification:Aftermarket conversion workshops capture margin pools by adapting legacy powertrains with corrosion-resistant seals, hardened valve seats, and recalibrated engine control units.
- Biofuel Processing:On-board ethanol purification systems for high-humidity markets remain pre-commercial.
- Ethanol Blending:Post-combustion fuel mixing technologies serve niche research applications.
Flex Fuel Systems command installed base dominance. Engine Modification services gain share where fleet operators extend asset lifecycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automakers exploit regulatory-arbitrage gaps between Brazil's RenovaBio credit system and the United States EPA Renewable Fuel Standard, concentrating flex-fuel engineering resources where compliance costs yield carbon credit returns. Production migrates toward jurisdictions with binding biofuel mandates and established ethanol distribution infrastructure.
Brazil
Fleet operators in São Paulo state's industrial corridor drive E100-capable sedan procurement to maximize CBios credit accumulation under ANP blending mandates. The RenovaBio framework tightens carbon intensity thresholds annually, channeling OEM assembly investments toward Taubaté and Indaiatuba manufacturing zones. Sugar-ethanol cooperatives in Goiás state deploy IoT-enabled fuel optimization systems, creating captive demand for conversion workshops.
United States
Midwest corn-belt logistics operators anchor E85 demand despite pump infrastructure concentration in Minnesota and Iowa retail corridors. EPA Renewable Fuel Standard compliance obligations force domestic automakers to maintain flex-fuel powertrain options across light-truck segments. Detroit engineering centers calibrate engine control units for E10-E85 variable blends, diverging from Brazilian hydrous-ethanol specifications.
India
Maharashtra and Uttar Pradesh manufacturing zones host OEM pilot programs for E20-compatible powertrains ahead of MoRTH's 2025 mandate deadline. BIS fuel quality specifications create homologation bottlenecks for foreign automakers seeking entry into the ethanol-hybrid segment. Pune-based engineering subsidiaries adapt compression ratios and fuel injector specifications for sugarcane-derived ethanol supply chains.
Germany
Stuttgart-headquartered Tier-1 suppliers ship flex-fuel injector modules to São Paulo assembly plants at triple previous volumes, capturing margin pools from OEM captive service networks. EU Green Deal sustainability criteria mandate lifecycle carbon accounting for ethanol feedstocks, complicating export-oriented vehicle segments bound for Dutch fleet lessors. Bavarian powertrain engineering firms specialize in calibration software for multi-fuel compatibility.
Japan
Toyota Motor Corporation anchors ethanol-hybrid development through dedicated Atkinson-cycle engine variants, pairing with electric motor assist to satisfy California LCFS credit stacking. Domestic demand remains constrained by petroleum-dependent infrastructure, pushing engineering resources toward ASEAN export markets. Nagoya-area research facilities optimize spark timing maps for high-humidity ethanol combustion environments.
Global Ethanol-Based Vehicle Market Vendor Landscape
Brazilian producers anchor the flex-fuel platform tier; German and Japanese specialists hold the hybrid-ethanol convergence segment. The vendor structure concentrates around OEM-integrated solutions with captive service networks displacing independent conversion workshops. Three archetypes dominate: legacy automakers with São Paulo engineering centers, Tier-1 suppliers shipping standardized injector modules, and sugar-ethanol cooperatives unbundling fuel from vehicle acquisition. Competitive moves center on calibration software licensing and backward integration into ethanol distribution infrastructure.
Among legacy automakers with Brazilian manufacturing presence, Ford Motor Company, Toyota Motor Corporation, and Volkswagen AG exemplify divergent strategic positioning within the flex-fuel ecosystem. Ford leverages its São Paulo engineering center for Latin American powertrain development. Toyota occupies a position at the hybrid-ethanol convergence frontier through dedicated engine variants. Volkswagen sits within the localized SUV platform tier serving Minas Gerais and Paraná dealership networks. Each represents an archetype rather than a discrete market share position.
| Leading Market Players |
|---|
| Ford Motor Company |
| General Motors |
| Toyota Motor Corporation |
| Volkswagen AG |
| Honda Motor Co. |
| Stellantis |
| Hyundai Motor Company |
| Mahindra & Mahindra |
| Nissan Motor Co. |
| Others |
Supply Flow & Price Mechanics
Sugarcane feedstock costs in São Paulo state's industrial corridor cascade through three distinct pricing tiers for flex-fuel powertrain components, with anhydrous ethanol premiums compressing margins for aftermarket conversion workshops while OEM captive networks capture value through bundled service contracts.
Pricing Analysis
Distributor margins for flex-fuel injector modules stratify across premium, standard, and economy tiers based on corrosion-resistance certification grades and volume commitment scales. Price differentiation hinges on ANP blending mandate compliance tiers and geographic delivery costs from Stuttgart and Detroit engineering centers to Brazilian assembly plants. Pricing pressure stems from corn price volatility in Midwest grain markets compressing E85 infrastructure subsidy pools. Fleet operators in Goiás state exhibit lowest price sensitivity due to total-cost-of-ownership contracting models, while independent conversion workshops face acute margin compression.
Supply Chain Analysis
Calibration engineer scarcity across São Paulo's ABC industrial corridor constrains Tier-1 supplier capacity expansion for flex-fuel injector module production. Manufacturing concentration centers on Germany, Brazil, and Japan for ethanol-optimized powertrain components. Raw material dependencies include sugarcane-derived anhydrous ethanol, corrosion-resistant seal polymers, and hardened valve seat alloys. Supply chain risk manifests through single-source vulnerability for enzymatic hydrolysis catalysts in cellulosic ethanol processing. Distribution runs through OEM captive service networks displacing independent conversion workshops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where regulatory divergence between Brazil's RenovaBio CBios credit system and the United States EPA Renewable Fuel Standard creates divergent compliance cost structures for identical powertrain architectures.
For Market Incumbents: Hedge against cellulosic ethanol conversion delays by securing long-term feedstock offtake agreements with São Paulo sugar-ethanol cooperatives. Calibrate powertrain development resources toward E100 capability as agricultural fleet operators in Brazil's Center-West region reverse prior consumer preferences. Defensive patent positioning around spark timing maps for high-humidity combustion environments protects against emerging calibration software specialists. For New Entrants and Emerging Players: Launch via fuel station-integrated conversion workshops in Goiás and Mato Grosso states where sugar-ethanol cooperatives unbundle fuel supply from vehicle acquisition. Target fleet procurement contracts with total-cost-of-ownership structures that assume pump-price risk. White-space exists in IoT-enabled fuel optimization systems for aftermarket service revenue capture. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration software capabilities concentrate among Bavarian engineering firms and São Paulo powertrain specialists. Long-term viability favors acquisition targets with backward integration into ethanol distribution infrastructure and blockchain-verified supply chain documentation for EU Green Deal compliance. Watch for inflection in California LCFS credit stacking dynamics affecting Toyota's ethanol-hybrid convergence strategy.| Strategic Initiative | Industry Significance |
|---|---|
| Flex-Fuel Platform Standardization | OEMs consolidate injector module specifications across São Paulo and Indaiatuba assembly plants to capture scale economies. |
| Ethanol Supply Agreement | Long-term offtake contracts with sugar-ethanol cooperatives secure feedstock for E100-capable fleet configurations. |
| Calibration Software Investment | Engine control unit mapping capabilities emerge as primary competitive differentiator beyond hardware specifications. |
| Geographic Manufacturing Footprint | Taubaté facility expansion anchors Volkswagen's localized SUV production for Minas Gerais and Paraná dealership networks. |
| RenovaBio Credit Optimization | Fleet operators structure procurement to maximize CBios credit accumulation under tightening carbon intensity thresholds. |
Methodological Framework
Multiple input streams — OEM platform engineering disclosures, Tier-1 supplier procurement patterns, and sugar-ethanol cooperative operational data — were reconciled through structured primary interviews with powertrain calibration specialists, fleet procurement managers, and ANP regulatory affairs officers, validated against secondary sources including ANP blending mandate filings, INMETRO certification records, and vehicle production databases, with bottom-up installation volume estimates cross-checked against top-down market value reconstructions.
Historical registration data across the analysis window was cross-referenced against expert panel assessments of E20 mandate implementation trajectories in India and RenovaBio threshold tightening schedules in Brazil. Segmentation modeling incorporated vehicle class, propulsion architecture, fuel specification tier, and regional regulatory cluster dimensions. CAGRs were derived from slope-consistency tests across the projection horizon, with ethanol feedstock price elasticity and pump infrastructure deployment rates serving as key sensitivity inputs.
Several conditions sit outside the modeled scope, including breakthrough commercialization timelines for cellulosic ethanol conversion technologies and unilateral tariff modifications affecting flex-fuel injector module trade flows. Forecasts reflect documented assumptions regarding mandate enforcement continuity and feedstock supply chain stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Asia-Pacific Fuel Cell Vehicles Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
Dual Fuel Engine Market