
 Air Powered Vehicle Market | 2026-2036
Air Powered Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Air Powered Vehicle Market Analysis
European compressed air engine manufacturing is decoupling from traditional piston-engine supply chains. Motor Development International SA leverages its proprietary engine architecture to sustain R&D leadership in France. Tata Motors anchors its position through integrated development of hybrid air-electric powertrains for commercial platforms. Engineair Pty Ltd differentiates via rotary air motor designs that occupy a distinct niche in lightweight urban delivery vehicles.
Air powered vehicles use compressed air or hybrid pneumatic-electric systems to drive expansion motors or pistons, typically operating at pressures between 200 and 300 bar for propulsion or auxiliary power in urban transport. The technology serves municipalities and fleet operators seeking zero-tailpipe-emission alternatives to battery-electric vehicles for short-radius routes. Compressed air technology dominates current installations due to lower infrastructure requirements, while hybrid systems represent the fastest-expanding segment as operators demand extended range without charging downtime. Urban mobility applications command the deepest margin pools because municipal procurement specifications favor proven emission reductions and predictable total cost of ownership over capital expenditure minimization.
The EPA and NHTSA in the United States enforce tailpipe emission standards and vehicle safety certifications that compressed air platforms must satisfy for highway access, while the EU Green Deal and F-Gas Regulation in Europe constrain refrigerant-based pneumatic alternatives and incentivize pure air-cycle designs. India's CEA and BIS coordinate powertrain testing protocols and component standards that govern domestic manufacturing eligibility. Stakeholders must monitor how evolving crash-test requirements for lightweight vehicles interact with pressure-vessel safety regulations to determine viable market entry timing.
Market Dynamics
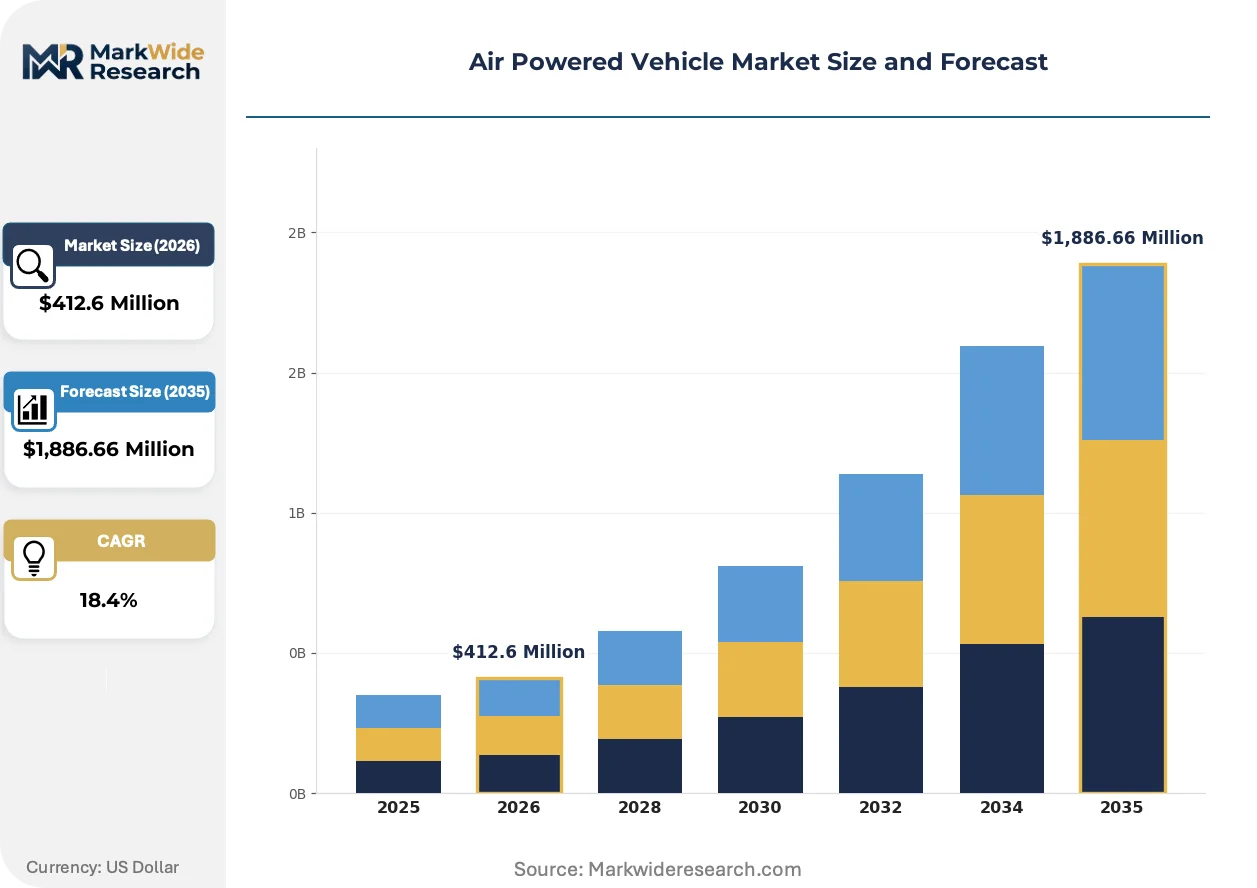
Municipal fleet electrification mandates are compressing procurement cycles for zero-emission commercial vehicles, forcing compressed air powertrain developers to accelerate certification timelines and demonstrate total cost parity with battery-electric alternatives.
Growth Catalysts
- France's low-emission zone mandates:Municipal procurement specifications in Paris and Lyon now prioritize vehicles with zero tailpipe emissions, creating guaranteed demand pools for compressed air urban delivery fleets.
- Hybrid pneumatic-electric architectures:Fleet operators facing route-length variability are adopting dual-powertrain systems that eliminate charging downtime while maintaining emission compliance.
- India's PLI scheme for clean mobility:Domestic manufacturing incentives are drawing component suppliers to commercial vehicle hubs in Pune and Chennai, reducing landed costs for indigenous air-powered platforms.
Market Restraints
- Carbon fiber pressure vessel costs:High-pressure storage systems require aerospace-grade composite materials whose prices fluctuate with carbon fiber supply concentration in China and Japan.
- Range limitations of pure air cycles:Energy density constraints restrict unrefueled operation to sub-100 kilometer routes, excluding intercity logistics applications.
- EU F-Gas Regulation compliance:Refrigerant-based pneumatic expansion systems face phase-out timelines, forcing redesigns of auxiliary climate control subsystems.
Strategic Opportunities
- Germany's automotive engineering clusters:Stuttgart and Munich host specialized tooling suppliers capable of precision-machining rotary air motor housings at prototype-to-production scale.
- Airport ground support equipment:Fixed-base operators at Frankfurt and Amsterdam Schiphol are trialing compressed air tugs and baggage tractors for tarmac emission reduction.
- Convergence with solar-powered compression:Off-grid charging stations using photovoltaic arrays paired with high-efficiency compressors are eliminating grid dependency for rural fleet depots.
Industry Challenges
- Pressure vessel welding certification:ASME and ISO 9809 compliance for 300-bar tanks requires specialized technician training programs that OEMs must build from near-zero base.
- Integration with legacy fleet management software:Compressed air range prediction algorithms lack standardization with existing telematics platforms, forcing custom API development per deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Powered Vehicle Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,886.66 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Compressed Air, Hybrid System, Pneumatic Drive, Electric Air End User: Public Transport, Personal Use, Logistics, Industrial Application: Urban Mobility, Delivery Services, Recreational Vehicles, Fleet Operations Size: Compact, Mid-Sized, Full-Size, Heavy-Duty |
| Companies Covered | Motor Development International SA, Tata Motors, Magnetic Air Car, Inc., Groupe PSA, Engineair Pty Ltd, Honda Motor Co., Ltd., Phinergy, Zero Pollution Motors Private Limited, Air Power Automotive GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Powered Vehicle Market Emerging Trajectories
Compressed air propulsion is transitioning from novelty demonstration to validated fleet architecture, with engineering focus shifting toward thermal efficiency recovery and modular powertrain packaging that accommodates diverse commercial chassis formats.
Rotary air motor designs are rewriting efficiency benchmarks for urban delivery applications. Engineair's orbital motor architecture converts expansion energy to rotational motion with fewer moving parts than piston equivalents. Last-mile operators in Australian and European cities are piloting these systems for parcel van retrofits. The technology is rewriting supplier qualification criteria by rewarding specialized pneumatic engineering over legacy internal combustion expertise.
The EU Green Deal's 2035 combustion phase-out is accelerating regulatory clarity for alternative powertrains. The F-Gas Regulation's refrigerant restrictions are pushing developers toward pure air-cycle climate systems rather than hybrid refrigerant designs. Commercial vehicle OEMs in France and Germany are responding by establishing dedicated air-powertrain engineering centers separate from battery-electric divisions.
Fleet procurement departments are consolidating vendor relationships around integrated powertrain-service contracts. Municipal buyers in India and France now specify ten-year total cost guarantees rather than capital expenditure limits. Compressed air providers in these markets are building captive maintenance networks to capture recurring revenue streams that battery-electric competitors currently dominate through established dealer channels.
Air Powered Vehicle Market Segmentation
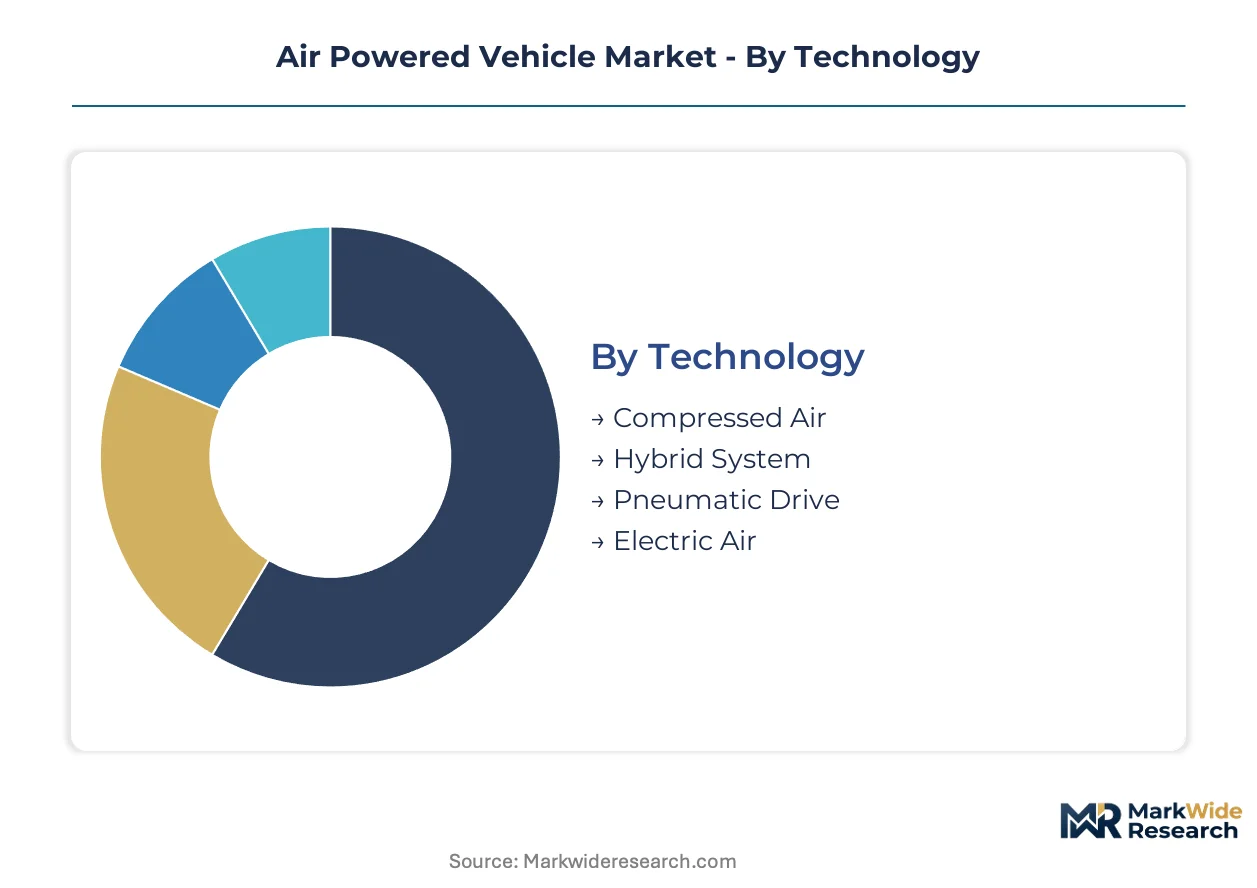
Compressed air powertrain architectures diverge sharply across duty cycles and infrastructure access. Technology selection dictates pressure vessel specifications, motor configuration, and refueling protocols that cascade through procurement decisions.
Technology:
Propulsion architecture determines energy conversion efficiency and infrastructure dependency for fleet operators.
- Compressed Air:Pure pneumatic systems store energy at 200-300 bar in carbon fiber vessels, driving reciprocating or rotary expansion motors. Municipal bus fleets in France's low-emission zones favor this architecture for its zero-tailpipe operation and rapid refueling at fixed depots.
- Hybrid System:Dual pneumatic-electric powertrains pair compressed air storage with battery buffers to extend range and recover braking energy. Logistics operators facing variable route lengths in Germany are adopting these configurations to eliminate charging downtime while maintaining emission compliance.
- Pneumatic Drive:Mechanical transmission systems convert air pressure directly to wheel torque without electrical intermediaries. Industrial yard vehicles and airport ground support equipment in fixed-base environments deploy these simplified drivetrains.
- Electric Air:Electrically assisted compression systems use grid power to recharge onboard air reserves, blurring boundaries with battery-electric architectures. Pilot programs in India are testing these systems for rural fleet depots with unreliable grid access.
Mature deployment sits with Compressed Air. Newer deployment is concentrated in Hybrid System configurations.
End User:
Customer procurement specifications vary by fleet scale, duty predictability, and regulatory exposure.
- Public Transport:Municipal transit authorities specify zero-emission mandates with total cost of ownership guarantees spanning decade-long service contracts. India's PLI scheme eligibility requires domestic assembly certification that favors established commercial vehicle platforms.
- Logistics:Parcel and last-mile delivery operators prioritize route flexibility and rapid turnaround over capital expenditure minimization. Hybrid pneumatic-electric systems are gaining traction fastest in this segment as operators seek to avoid battery-electric charging infrastructure investments.
- Industrial:Manufacturing facilities and warehouse operators deploy captive fleets with fixed circulation patterns. Pure compressed air systems dominate these closed-loop applications where refueling infrastructure can be centralized at single sites.
- Personal Use:Individual consumers represent a marginal addressable market given range constraints and refueling infrastructure gaps. Demonstration programs in France and India are testing compact urban commuter formats.
Procurement volume concentrates in Public Transport. Margin expansion is fastest in Logistics.
Application:
Operating environment shapes powertrain sizing, thermal management requirements, and service interval specifications.
- Urban Mobility:Stop-and-go traffic patterns favor regenerative braking recovery and frequent acceleration cycles. Municipal specifications in Paris and Lyon mandate zero-tailpipe performance that compressed air platforms satisfy without charging infrastructure dependencies.
- Delivery Services:Predictable short-radius routes with high door-to-door frequency match compressed air range envelopes. Last-mile operators in Australian and European cities are piloting rotary air motor retrofits for existing van chassis.
- Fleet Operations:Centralized depot management enables dedicated compression infrastructure and standardized maintenance protocols. Airport ground support equipment at Frankfurt and Amsterdam Schiphol represents an emerging trial category.
- Recreational Vehicles:Leisure applications face range and performance limitations that exclude most current compressed air architectures from serious consideration.
Urban Mobility commands the deepest specification expertise. Delivery Services are climbing the fastest adoption curve.
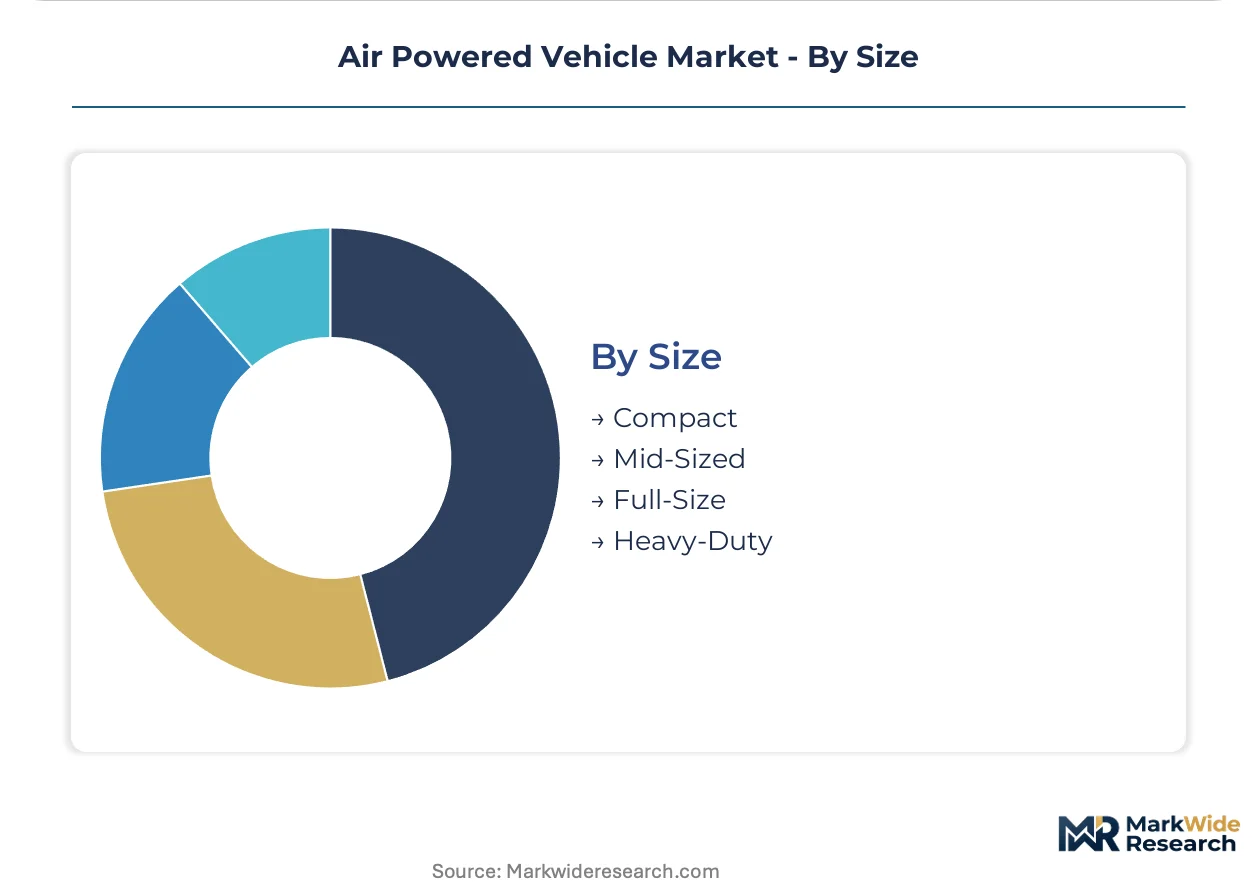
Size:
Vehicle mass dictates pressure vessel volume, structural integration challenges, and crash safety certification pathways.
- Compact:Lightweight urban delivery formats with sub-1,000 kg gross vehicle weight accommodate smaller pressure vessels without chassis redesign. Last-mile parcel vans in European cities are deploying these configurations for curb access advantages.
- Heavy-Duty:Commercial bus and truck platforms require multi-vessel arrays and reinforced frame rails to manage 300-bar storage systems. ASME and ISO 9809 compliance for these pressure ratings demands specialized welding certification programs.
- Mid-Sized:Intermediate commercial van platforms balance payload capacity with maneuverability constraints. Component suppliers in Germany's automotive engineering clusters are developing modular powertrain packages for this format.
- Full-Size:Large passenger and cargo vehicles face range limitations that hybrid architectures must address through battery augmentation.
Engineering validation is most advanced for Heavy-Duty. Compact formats are gaining share fastest in urban deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Carbon fiber supply concentration in China and Japan anchors pressure vessel manufacturing economics for compressed air platforms, while regulatory momentum in France, India, Germany, and Australia shapes fleet deployment geography.
France
Municipal procurement in Paris and Lyon prioritizes zero-tailpipe urban delivery fleets under low-emission zone mandates. The EU Green Deal and F-Gas Regulation constrain refrigerant-based pneumatic alternatives, pushing developers toward pure air-cycle designs. Motor Development International SA maintains R&D leadership from its base near Nice, leveraging proprietary engine architecture for municipal bus trials.
India
Commercial vehicle hubs in Pune and Chennai attract component suppliers through the PLI scheme for clean mobility. The CEA and BIS coordinate powertrain testing protocols that govern domestic manufacturing eligibility. Tata Motors anchors integrated development of hybrid air-electric powertrains from its engineering centers in these clusters.
Germany
Automotive engineering clusters in Stuttgart and Munich host precision-machining suppliers capable of rotary air motor production at scale. KBA certification requirements for pressure vessel safety interact with EU crash-test standards to determine market entry timing. Airport ground support equipment trials at Frankfurt represent an emerging adoption vector for tarmac emission reduction.
Australia
Last-mile delivery operators in Melbourne and Sydney pilot rotary air motor retrofits for existing van chassis. Engineair Pty Ltd's orbital motor designs occupy a distinct niche in lightweight urban delivery vehicles from its Melbourne base. Solar-powered compression pilots in rural Queensland eliminate grid dependency for off-grid fleet depots.
United States
EPA tailpipe emission standards and NHTSA safety certifications govern highway access for compressed air platforms. Municipal fleet electrification mandates in California compress procurement cycles for zero-emission commercial vehicles. Magnetic Air Car, Inc. represents US-based development activity in hybrid pneumatic architectures.
Air Powered Vehicle Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid architectures and specialized motor designs. The vendor base spans integrated automotive OEMs, dedicated pneumatic engineering specialists, and component-focused technology developers. Three archetypes dominate: legacy automakers with air-electric hybrid programs, pure-play compressed air engine developers, and pressure vessel subsystem suppliers. Competitive moves concentrate on strategic partnerships for certification acceleration and geographic licensing agreements to bypass capital-intensive manufacturing buildout.
Among European developers, Motor Development International SA and Air Power Automotive GmbH exemplify the dedicated engineering specialist archetype, each occupying distinct national positions within EU regulatory frameworks. Tata Motors represents the integrated OEM approach, anchoring hybrid powertrain development through captive commercial vehicle platforms. Engineair Pty Ltd sits within the rotary motor specialization tier, demonstrating how orbital architectures can rewrite supplier qualification criteria in urban delivery applications.
| Leading Market Players |
|---|
| Motor Development International SA |
| Tata Motors |
| Magnetic Air Car, Inc. |
| Groupe PSA |
| Engineair Pty Ltd |
| Honda Motor Co., Ltd. |
| Phinergy |
| Zero Pollution Motors Private Limited |
| Air Power Automotive GmbH |
| Others |
Supply Flow & Price Mechanics
Family-owned carbon fiber weaving specialists in Japan and China anchor pressure vessel manufacturing economics, compressing margin structures for compressed air vehicle OEMs while simultaneously constraining pricing flexibility through long-term offtake agreements.
Pricing Analysis
Warranty and service bundling separates premium-tier municipal fleet contracts from economy-tier industrial yard vehicle sales, with Paris transit authorities demanding decade-long total cost guarantees while warehouse operators accept unbundled hardware procurement. Three-tier pricing structure across premium, standard, and economy levels reflects ASME certification grade, volume scale, and after-sales network density. Cost compression in economy-tier pneumatic drive systems is intensifying because India's PLI scheme eligibility requires domestic assembly certification that favors large-volume tenders. Municipal transit authorities exhibit lowest price sensitivity due to decade-long procurement horizons, while last-mile parcel operators prioritize capital expenditure minimization.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns, drawing component suppliers to commercial vehicle hubs in Pune and Chennai. Carbon fiber supply concentrates in Japan, China, and South Korea, while precision-machining capacity for rotary air motor housings rests on Germany's automotive engineering clusters in Stuttgart and Munich. Aerospace-grade composite feedstocks, high-pressure valve assemblies, and specialized welding equipment constitute critical input dependencies. Single-source vulnerability in Toray Industries' carbon fiber supply creates structural risk for 300-bar pressure vessel OEMs. Distribution runs through captive maintenance networks for municipal fleets and direct OEM relationships for industrial captive fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
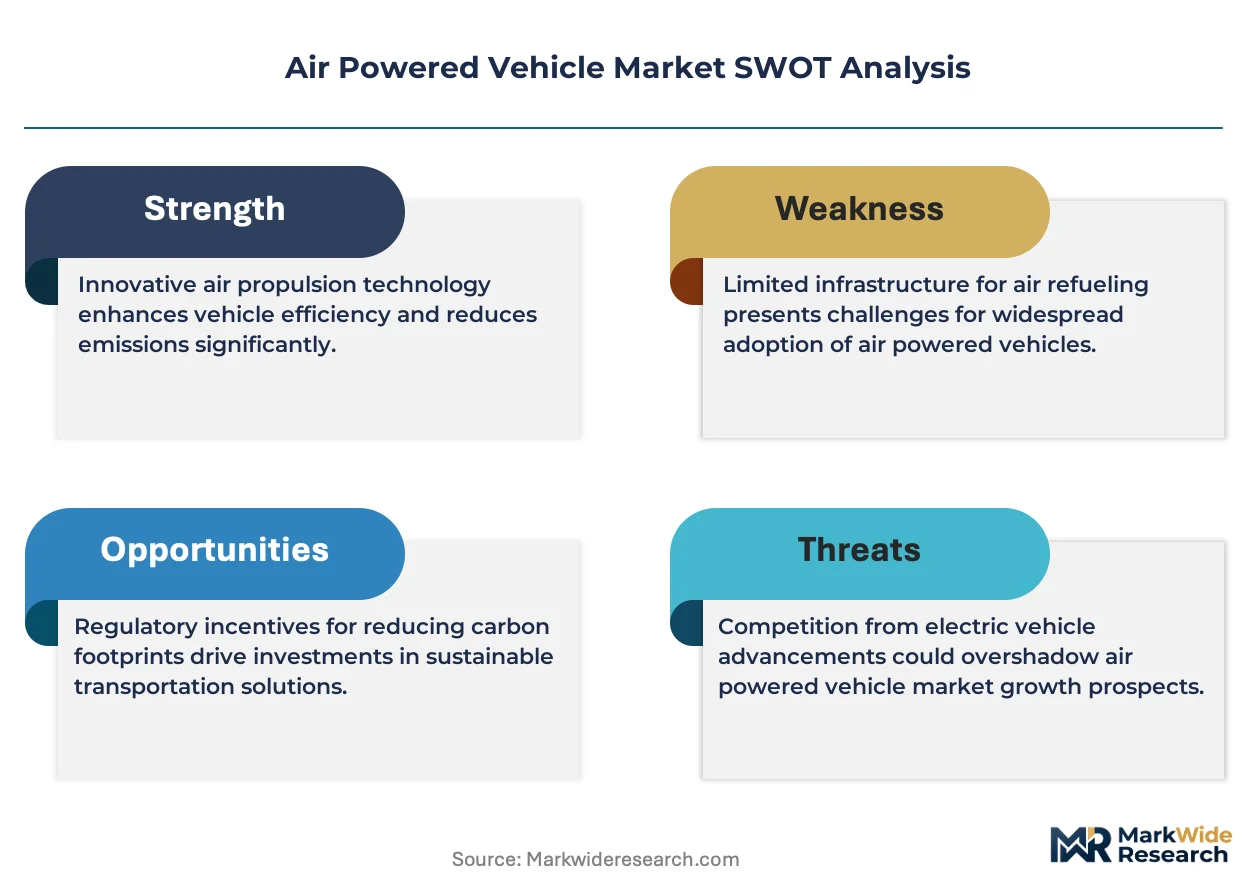
Compressed air vehicle manufacturing is becoming a vertical-integration race, with players pursuing upstream control over carbon fiber pressure vessel production to escape aerospace-grade composite pricing volatility.
For Market Incumbents: Acquire specialized welding certification programs to accelerate ASME and ISO 9809 compliance timelines. Motor Development International SA and Tata Motors must defend against hybrid pneumatic-electric entrants by integrating battery buffer subsystem production in-house, eliminating dual-sourcing complexity for fleet operators demanding extended range without charging downtime. For New Entrants and Emerging Players: The premium-economy price-point gap in last-mile delivery van retrofits creates entry space for rotary air motor specialists. Australian and European cities present the most penetrable geography, with Engineair's orbital architecture demonstrating supplier qualification criteria that reward pneumatic engineering over legacy internal combustion expertise. Target airport ground support equipment trials at Frankfurt and Amsterdam Schiphol as anchor reference customers. For Investors and Strategic Acquirers: Distressed-cycle entries favor component-focused pressure vessel subsystem suppliers in India's PLI scheme beneficiary clusters. Long-term viability hinges on ten-year municipal service contract attach rates rather than hardware margins. Watch India's CEA and BIS powertrain testing protocol evolution as inflection indicator for domestic manufacturing eligibility expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure Vessel Certification Acceleration | ASME and ISO 9809 compliance unlocks municipal fleet procurement in France's low-emission zones. |
| Hybrid Powertrain Integration | Battery buffer subsystem development eliminates charging downtime for German logistics operators. |
| Solar-Powered Compression Infrastructure | Photovoltaic array pairing eliminates grid dependency for rural Indian fleet depots. |
| Rotary Air Motor Specialization | Orbital motor designs rewrite supplier qualification criteria in Australian last-mile delivery. |
| Captive Maintenance Network Buildout | Ten-year total cost guarantees capture recurring revenue streams from municipal buyers. |
Methodological Framework
Document review covered regulatory filings from EPA, NHTSA, EU Green Deal documentation, and India's PLI scheme guidelines, complemented by interviews with fleet procurement directors at municipal transit authorities, compressed air engine R&D leads, carbon fiber composite procurement managers, and pressure vessel welding certification specialists. Secondary validation drew from KBA vehicle safety databases, CEA powertrain testing protocols, BIS component standards, and airport ground support equipment trial reports. Bottom-up unit economics modeling triangulated against top-down market sizing across technology and end-user segments.
Installed base projections and revenue estimates emerged from segment-level penetration modeling across the analysis window. The analytical framework incorporated propulsion architecture, vehicle size class, end-user procurement specifications, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from logistic diffusion curves fitted to fleet operator trial conversion rates and municipal procurement cycle compression patterns. Forecast inputs included carbon fiber price elasticity coefficients and PLI scheme subsidy phase-out schedules.
Underlying measurement precision varies by segment; hybrid pneumatic-electric configurations carry tighter precision than pure compressed air systems due to battery cost transparency. Forecasts reflect assumptions about municipal electrification mandate enforcement intensity and carbon fiber supply concentration stability. Regulatory timeline delays or aerospace composite demand shocks could revise trajectory materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
North America Hydrogen Powered Tractor Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market