
 North America Hydrogen Powered Tractor Market | 2026-2036
North America Hydrogen Powered Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hydrogen Powered Tractor Market Analytics
Canadian fuel cell stack manufacturing is repositioning North American supply chains away from overseas dependency. John Deere anchors Midwest agricultural equipment distribution through its established dealer network. AGCO Corporation differentiates via open-architecture fuel cell integration across multiple tractor platforms. Ballard Power Systems sustains proton exchange membrane stack production for OEM partnerships in the region.
A hydrogen powered tractor employs fuel cell technology to convert hydrogen into electricity for electric drivetrains, typically utilizing proton exchange membrane stacks operating at 60-80°C with 45-65% system efficiency for field operations. These machines eliminate tailpipe emissions during tillage, planting, and harvesting cycles while maintaining comparable torque profiles to diesel equivalents. Liquid hydrogen storage dominates long-duration field applications where energy density outweighs infrastructure complexity, while gaseous hydrogen configurations occupy shorter-duty orchard and vineyard segments. Fuel cell technology leads equipment investment allocations, though dual-fuel systems are gaining traction among contract farmers seeking transitional operational flexibility.
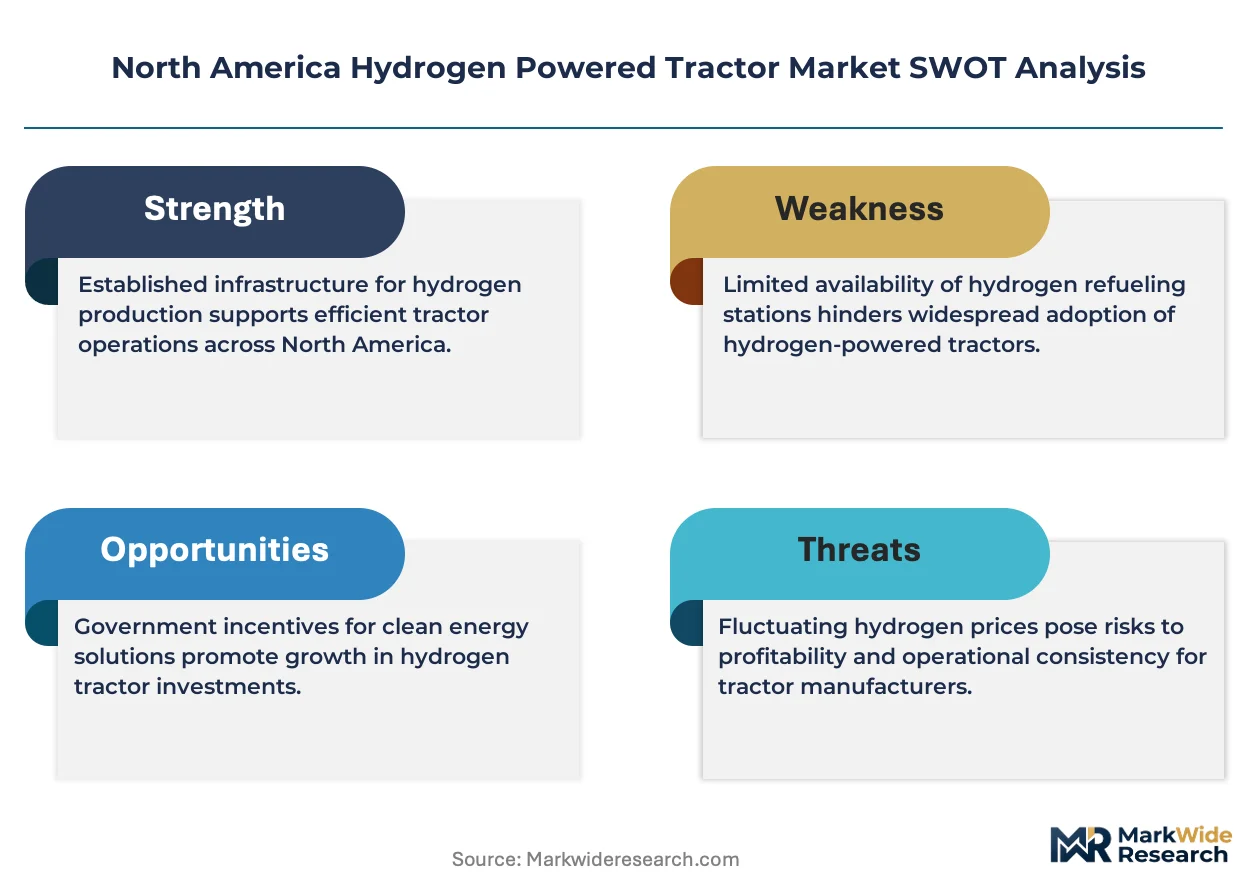
The US Environmental Protection Agency tailpipe emission standards and California Air Resources Board zero-emission mandates shape tractor certification requirements and fleet procurement timelines. Canada's Clean Fuel Regulations and US Department of Energy hydrogen hub funding collectively redirect capital toward domestic fueling infrastructure buildout. Stakeholders must monitor hydrogen station density along agricultural freight corridors as the binding constraint on fleet scaling decisions.
Market Dynamics
The US Inflation Reduction Act hydrogen production tax credits are compressing total cost of ownership differentials between fuel cell tractors and diesel equivalents, accelerating fleet conversion decisions among large-scale agricultural enterprises.
Growth Catalysts
- US Inflation Reduction Act hydrogen production tax credits:The IRA's USD 3.00/kg credit for clean hydrogen production narrows fuel cost gaps with diesel, enabling Midwest grain belt operators to model positive returns on fuel cell tractor investments.
- California Air Resources Board zero-emission mandates:CARB's increasingly stringent off-road equipment standards force Central Valley agricultural fleets to phase out diesel tractors, creating guaranteed demand pull for hydrogen alternatives.
- Proton exchange membrane stack efficiency gains:Advances in membrane electrode assembly durability extend fuel cell operational lifespans beyond 15,000 field hours, reducing replacement cost burdens for high-utilization farming operations.
Market Restraints
- Liquid hydrogen infrastructure concentration:Cryogenic storage and dispensing equipment remains concentrated along coastal corridors, leaving interior agricultural freight routes with inadequate station density for long-haul field operations.
- Platinum group metal cost volatility:Fuel cell catalyst requirements expose tractor OEMs to palladium and iridium price swings that compress manufacturing margins and deter volume production commitments.
- Compressed natural gas substitution threat:CNG-powered tractors offer lower capital costs and established fueling infrastructure across the Corn Belt, capturing transitional buyers unwilling to absorb hydrogen technology premiums.
Strategic Opportunities
- Canadian Prairie Provinces underpenetration:Saskatchewan and Manitoba large-scale wheat operations lack hydrogen tractor penetration despite favorable federal Clean Fuel Regulations incentives, presenting first-mover expansion territory for established suppliers.
- Orchard and vineyard dual-fuel configurations:California's Central Valley tree crop and wine grape segments require shorter-duty cycles where gaseous hydrogen storage suffices, enabling lower-complexity equipment variants.
- US Department of Energy hydrogen hub funding:The DOE's regional clean hydrogen hubs program directs capital toward agricultural corridor fueling infrastructure, de-risking fleet scaling decisions for early adopters.
Industry Challenges
- Fuel cell stack technician scarcity:The specialized electrochemical systems expertise required for field-level maintenance exceeds current agricultural equipment technician training pipelines, constraining service network expansion.
- EPA tailpipe emission certification timelines:The US Environmental Protection Agency's evolving off-road equipment testing protocols create regulatory uncertainty that delays product launch schedules and freezes R&D allocation decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hydrogen Powered Tractor Market |
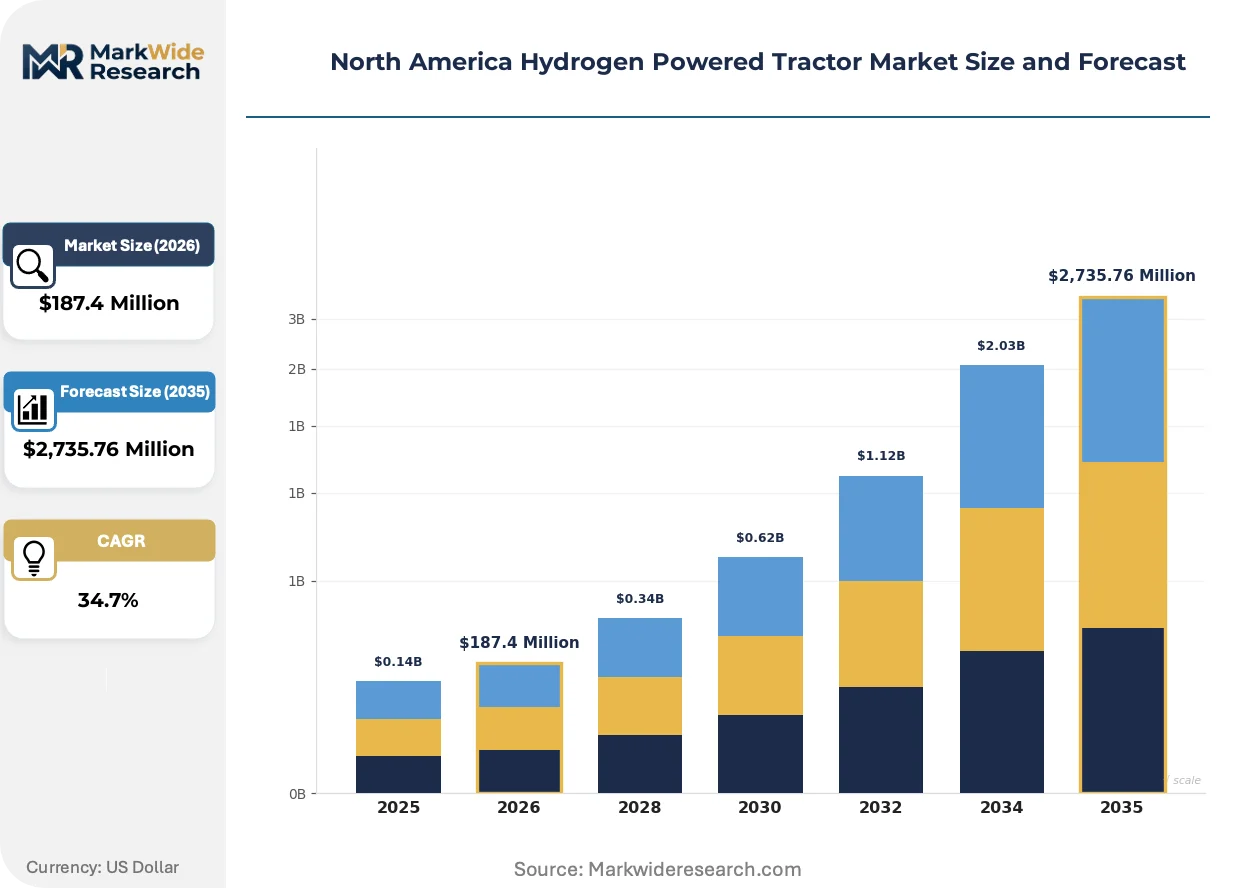
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,735.76 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Towed, Electric Hybrid, Conventional Fuel Type: Liquid Hydrogen, Gaseous Hydrogen, Ammonia, Biohydrogen End User: Agricultural Enterprises, Contract Farmers, Government Agencies, Research Institutions Technology: Fuel Cell Technology, Solid Oxide Fuel Cell, Proton Exchange Membrane, Dual-Fuel Systems |
| Companies Covered | John Deere, AGCO Corporation, CNH Industrial N.V., Ballard Power Systems Inc., Plug Power Inc., Kubota Corporation, Caterpillar Inc., Doosan Fuel Cell America, Inc., Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hydrogen Powered Tractor Market Evolving Landscape
Fuel cell system architecture is undergoing rapid standardization as agricultural OEMs seek supply chain flexibility. Three developments are compressing technology adoption cycles and reshaping competitive positioning across the North American market.
Liquid hydrogen storage systems are consolidating as the dominant configuration for long-duration field applications where energy density requirements outweigh infrastructure complexity. Large-scale corn and soybean operators in Illinois and Iowa are specifying cryogenic tanks for 12+ hour continuous tillage operations. This consolidation is compressing gaseous hydrogen variants into niche orchard and vineyard segments with shorter duty cycles.
The US Environmental Protection Agency tailpipe emission standards are tightening enforcement timelines for off-road agricultural equipment, forcing OEMs to accelerate zero-emission product roadmaps. Manufacturers must certify fuel cell tractors under evolving test protocols that differ from established diesel certification pathways. The Midwest grain belt states face the most acute compliance pressure as their fleet turnover cycles compress under state-level implementation schedules.
Leasing structures are displacing outright purchase models among contract farming operations seeking to transfer technology risk. Equipment finance providers in Nebraska and Kansas are structuring hydrogen tractor leases with fuel-inclusive pricing that bundles hydrogen supply agreements. This shift is most visible among mid-scale operators managing acreage volatility through flexible fleet scaling rather than capital-intensive ownership commitments.
North America Hydrogen Powered Tractor Market Segmentation
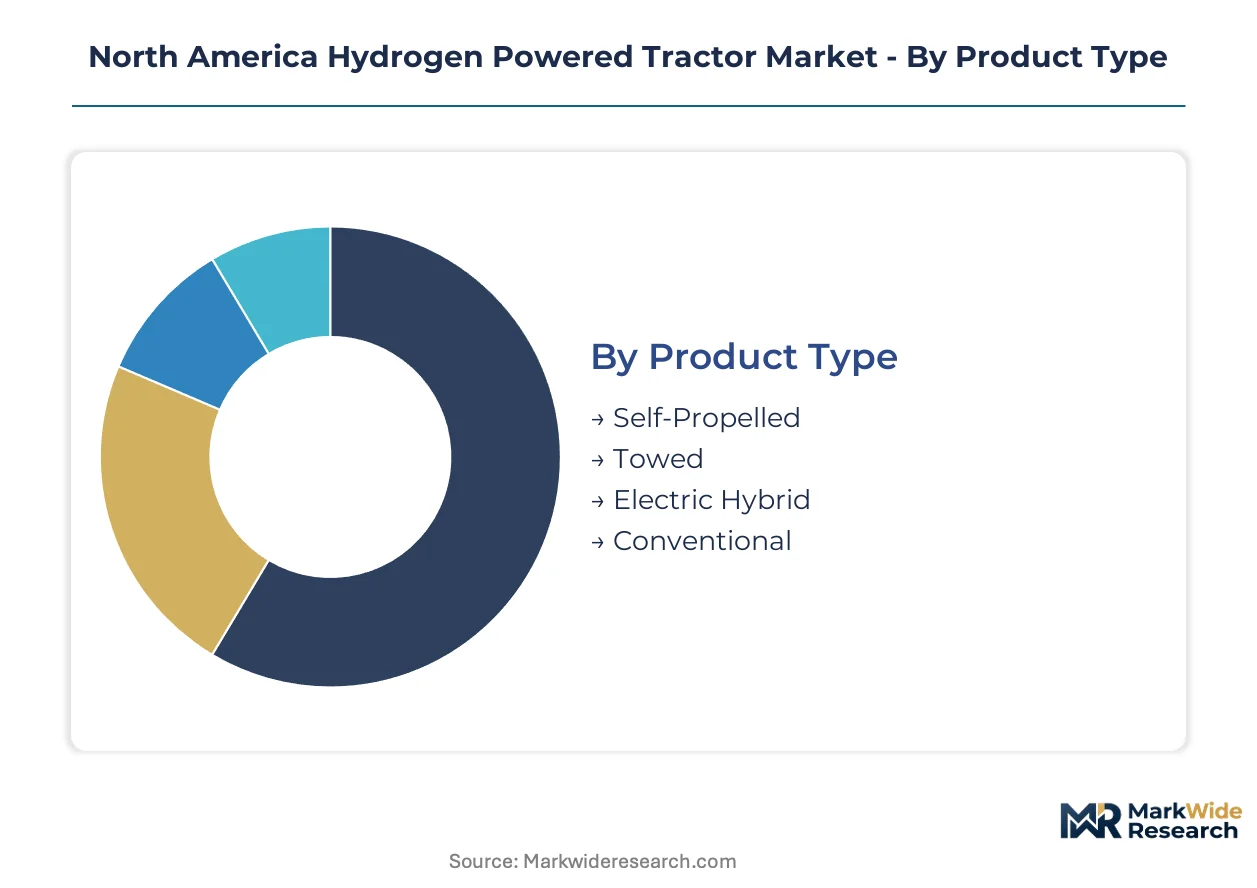
Equipment segmentation in the North America hydrogen powered tractor market reveals how fuel storage density, duty cycle requirements, and operational scale dictate technology selection across the Corn Belt and California's Central Valley. Distinct procurement patterns emerge between large-scale agricultural enterprises optimizing for total cost of ownership and contract farmers prioritizing capital flexibility.
Product Type:
Volume concentration tilts toward self-propelled configurations commanding premium pricing, while towed variants serve specialized applications where existing power units can be retrofitted.
- Self-Propelled:Integrated fuel cell stacks and cryogenic hydrogen tanks mount directly on the chassis, enabling 12+ hour continuous field operations without refueling interruptions. Illinois and Iowa corn operators specify these for spring tillage windows where downtime carries severe yield penalties.
- Towed:Modular hydrogen power units attach to conventional implement frames, allowing gradual fleet conversion without full tractor replacement. Demand clusters among Nebraska wheat growers testing hydrogen viability before committing to integrated platforms.
- Electric Hybrid:Battery-buffered fuel cell architectures smooth power delivery across variable terrain.
- Conventional:Diesel chassis retrofitted with aftermarket hydrogen combustion systems occupy transitional niches.
Today's leader: Self-Propelled. Tomorrow's challenger: Towed.
Fuel Type:
Application geography drives fuel selection, with energy density requirements separating long-duration Midwest grain operations from shorter-cycle California specialty crops.
- Liquid Hydrogen:Cryogenic storage at -253°C delivers 2.4x the energy density of compressed gas, supporting uninterrupted 14-hour planting operations across Kansas and South Dakota. Station infrastructure scarcity along interior freight corridors constrains deployment to hub-and-spoke distribution models.
- Gaseous Hydrogen:350-700 bar compressed tanks suit orchard and vineyard duty cycles under 6 hours where refueling proximity to Central Valley industrial gas suppliers remains practical. Lower tank costs improve capital accessibility for mid-scale operators.
- Ammonia:Liquid storage at ambient pressure leverages existing agricultural distribution networks.
- Biohydrogen:On-farm anaerobic digestion feedstock integration appeals to closed-loop sustainability commitments.
Current deployments favor Liquid Hydrogen for scale operations. Gaseous Hydrogen is expanding most quickly in specialty agriculture.
End User:
Customer type determines financing structure and technology risk tolerance, separating capital-rich enterprises from flexibility-seeking contractors.
- Agricultural Enterprises:Corn Belt operators with 10,000+ acre footprints absorb technology premiums to secure zero-emission compliance advantages and long-term fuel cost hedges against diesel volatility. These buyers negotiate direct OEM partnerships for fleet-standardized maintenance protocols.
- Contract Farmers:Seasonal acreage variability drives lease-preference over ownership, with fuel-inclusive financing structures transferring hydrogen supply risk to equipment providers. Kansas and Nebraska machinery cooperatives aggregate demand to improve station utilization economics.
- Government Agencies:Federal research stations and land management entities pilot demonstration fleets.
- Research Institutions:University agricultural engineering programs validate field performance under controlled conditions.
Commercial momentum sits with Agricultural Enterprises. Contract Farmers represent the steepest expansion trajectory as lease products mature.
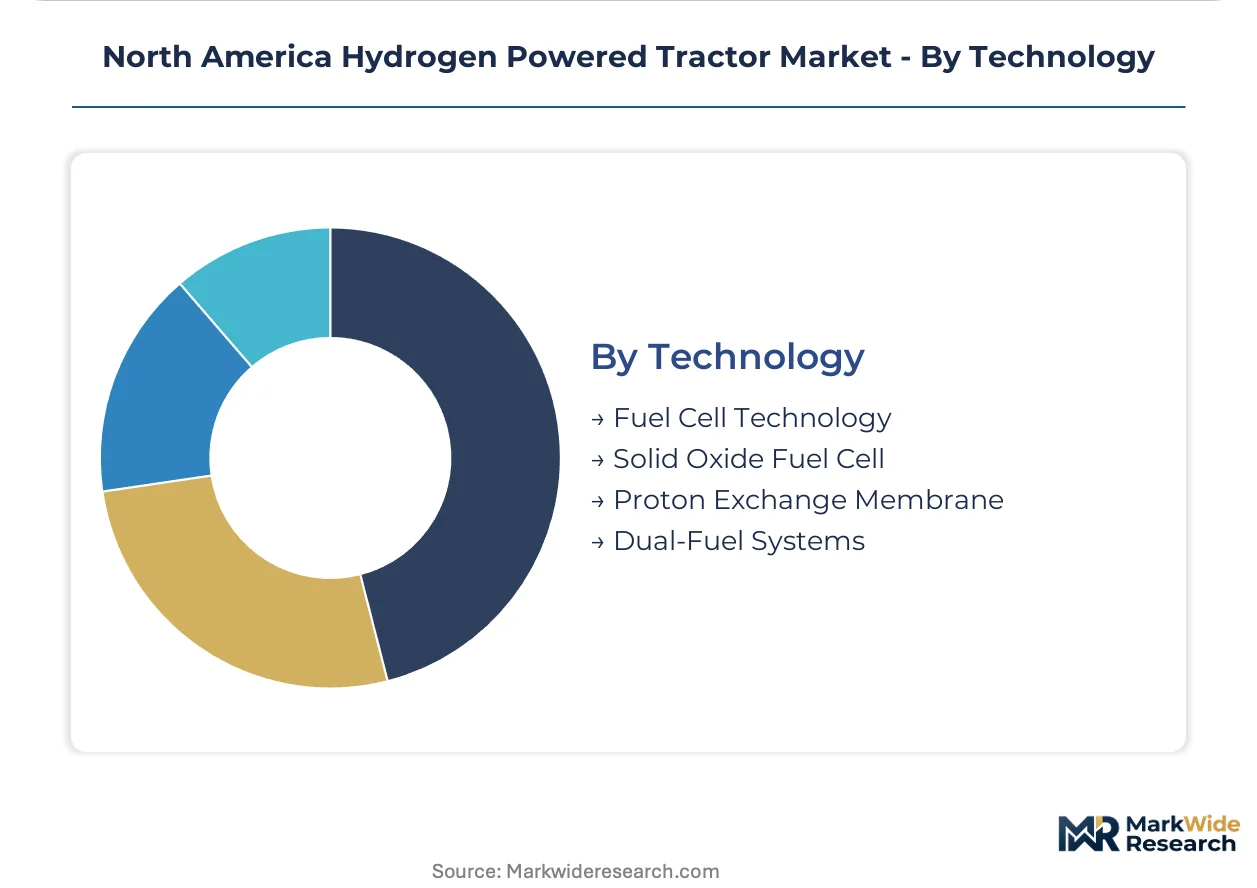
Technology:
Stack architecture selection balances efficiency, durability, and operational temperature against field maintenance capabilities.
- Proton Exchange Membrane:Low-temperature operation at 60-80°C enables rapid cold-start performance essential for dawn-plowing schedules in North Dakota and Minnesota. Membrane electrode assembly degradation beyond 15,000 hours remains the dominant lifecycle cost variable.
- Fuel Cell Technology:Broad category encompassing integrated system architectures where stack, power electronics, and thermal management ship as OEM-validated units.
- Solid Oxide Fuel Cell:High-temperature ceramic electrolyte designs achieve 60% efficiency but require extended warmup periods limiting intermittent-use viability.
- Dual-Fuel Systems:Parallel hydrogen-diesel capability preserves operational continuity during fuel supply disruptions, attracting risk-averse early adopters in station-sparse territories.
Proton Exchange Membrane dominates current procurement. Dual-Fuel Systems are gaining share fastest where infrastructure uncertainty persists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting hydrogen tractor deployment toward jurisdictions where IRA production credits and state-level zero-emission mandates create cost-of-compliance gaps favoring early adoption. Equipment procurement clusters where federal and provincial incentives stack most advantageously.
United States
Midwest grain belt operators in Illinois and Iowa are expanding pilot fleets ahead of EPA enforcement timelines. The Inflation Reduction Act's USD 3.00/kg clean hydrogen credit compresses fuel cost differentials with diesel. California's Central Valley hosts the densest concentration of commercial deployments as CARB mandates force fleet turnover.
Canada
Saskatchewan and Manitoba wheat operations present first-mover expansion territory despite minimal current penetration. Federal Clean Fuel Regulations redirect capital toward domestic fueling infrastructure buildout. Ontario's fuel cell stack manufacturing base is repositioning North American supply chains away from overseas dependency.
Mexico
Northern border states are emerging as testing corridors for cross-border agricultural equipment standards alignment. Limited federal hydrogen policy creates reliance on private infrastructure investment. Sonora and Baja California field trials evaluate tropical and arid-climate fuel cell performance under extended duty cycles.
North America Hydrogen Powered Tractor Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue fuel cell subsystem specialization rather than full-vehicle manufacturing. The vendor base separates between integrated agricultural equipment OEMs with century-long distribution networks and electrochemical technology suppliers seeking OEM partnership channels. Three archetypes dominate: legacy tractor manufacturers retrofitting fuel cell architectures, fuel cell stack specialists licensing powertrain components, and energy infrastructure providers bundling equipment with hydrogen supply contracts. Competitive moves concentrate on strategic partnerships between stack manufacturers and equipment OEMs, plus geographic expansion of service technician training networks.
Among North American-based equipment and technology providers, John Deere anchors Midwest agricultural distribution through its established dealer infrastructure, AGCO Corporation exemplifies open-architecture fuel cell integration across multiple tractor platforms, and Ballard Power Systems occupies the proton exchange membrane stack supplier tier for regional OEM partnerships. These three represent the dominant competitive positioning vectors: integrated manufacturing, modular platform flexibility, and specialized electrochemical component supply.
| Leading Market Players |
|---|
| John Deere |
| AGCO Corporation |
| CNH Industrial N.V. |
| Ballard Power Systems Inc. |
| Plug Power Inc. |
| Kubota Corporation |
| Caterpillar Inc. |
| Doosan Fuel Cell America, Inc. |
| Cummins Inc. |
| Others |
Value Network & Pricing Analysis
Proton exchange membrane stack manufacturing consolidation in Ontario and British Columbia is simultaneously compressing fuel cell system costs and concentrating supplier bargaining power among agricultural OEMs sourcing electrochemical components. This dual restructuring tightens margins for tractor assemblers while rewarding stack specialists with volume pricing leverage.
Pricing Analysis
Dealer markup layers in John Deere's and AGCO's established Midwest networks absorb 12-18% of equipment value, compressing direct-to-fleet pricing flexibility for early hydrogen tractor adopters. Three-tier pricing structure across premium integrated platforms, standard modular configurations, and economy towed units separates buyers by operational scale and fuel storage complexity. Cost compression in gaseous hydrogen variants is intensifying because compressed natural gas substitution threat forces competitive positioning against established alternative fuel equipment. Contract farmers in Kansas and Nebraska machinery cooperatives exhibit highest price sensitivity through lease-preference structures, while 10,000+ acre Corn Belt enterprises absorb technology premiums for zero-emission compliance advantages.
Supply Chain Analysis
Electrochemical systems technician scarcity in Michigan, Ohio, and Ontario manufacturing corridors constrains fuel cell stack assembly expansion despite demand acceleration from agricultural OEM partnerships. Geographic supply concentration centers on Canada for proton exchange membrane production, South Korea for precision membrane electrode assemblies, and Germany for high-pressure hydrogen storage tanks. Raw material dependencies draw from platinum group metal catalysts, carbon fiber composite tanks, and rare earth elements for power electronics. Single-source vulnerability in palladium and iridium sourcing exposes tractor OEMs to commodity price volatility that compresses manufacturing margins. Distribution runs through established agricultural equipment dealer networks with certified fuel cell service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on IRA hydrogen production tax credit durability and proton exchange membrane stack cost-down curves accelerating total cost of ownership parity with diesel equivalents.
For Market Incumbents: Lock in fuel cell stack supply agreements with Ballard Power Systems and Plug Power before Canadian manufacturing capacity saturates, securing volume pricing and service technician training pipeline access. Defend against compressed natural gas substitution threat by bundling hydrogen supply contracts with equipment leases, transferring fuel infrastructure risk from buyers. Prioritize backward integration into cryogenic tank fabrication to capture value from liquid hydrogen storage dominance in long-duration field applications. For New Entrants and Emerging Players: Begin with Saskatchewan and Manitoba wheat operations where federal Clean Fuel Regulations incentives exceed current supplier penetration, offering gaseous hydrogen configurations for shorter-duty Prairie grain cycles. Target orchard and vineyard segments in California's Central Valley with dual-fuel systems that preserve operational continuity during station-sparse periods. Pursue equipment finance partnerships that bundle fuel-inclusive pricing, transferring hydrogen supply risk from risk-averse contract farmers. For Investors and Strategic Acquirers: Valuations sit cheapest among fuel cell stack specialists with established OEM partnerships but limited agricultural sector penetration, offering acquisition entry before sector-specific volume ramps. Long-term viability framing centers on hydrogen station density along agricultural freight corridors as the binding constraint on fleet scaling decisions. Watch DOE hydrogen hub funding disbursement velocity as the inflection indicator for de-risking early adopter capital commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Cell Stack Supply Agreement | Secures proton exchange membrane volume pricing from Canadian manufacturers for OEM partnerships. |
| Hydrogen Station Infrastructure Partnership | Aligns DOE hub funding with agricultural corridor fueling buildout along Midwest grain belt routes. |
| Dual-Fuel System Development | Preserves operational continuity for risk-averse buyers in station-sparse interior territories. |
| Service Technician Training Network | Addresses electrochemical systems expertise scarcity constraining field-level maintenance expansion. |
| Lease-Structure Product Launch | Transfers technology risk from contract farmers through fuel-inclusive financing structures. |
Research Methodology
Bottom-up agricultural enterprise and contract farmer demand modeling reconciled against top-down fuel cell stack production tracking forms the analytical core of this study. Primary interviews with agricultural equipment procurement directors, fuel cell stack manufacturing executives, hydrogen infrastructure developers, and farm cooperative fleet managers combined with secondary validation from EPA off-road equipment certification databases, DOE hydrogen hub funding disclosures, and CARB zero-emission mandate implementation schedules. Triangulation between demand-side fleet conversion timelines and supply-side manufacturing capacity announcements ensures statistical integrity.
Input-output matrices map fuel storage configuration selection against duty cycle requirements, operational scale, and regional hydrogen station density across the projection horizon. Segmentation dimensions modeled include product type integration level, fuel storage state, end user capital structure, and stack architecture thermal regime. CAGRs derive from equipment procurement pipeline analysis and fuel cost differential modeling under IRA credit scenarios. Industry-specific forecast inputs incorporate membrane electrode assembly durability improvements and cryogenic infrastructure deployment velocity.
Several conditions sit outside the modeled scope, including potential repeal or modification of IRA hydrogen production tax credits, platinum group metal supply disruptions from geopolitical events, and breakthrough battery-electric tractor performance that displaces fuel cell alternatives. Forecasts reflect documented assumptions regarding station density buildout schedules and OEM production ramp timelines. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Middle East and Africa and India CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Automotive Hydrogen Fuel Cell Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Brazil Alternative Fuel Vehicles Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market