
 Autonomous Driving Component Market | 2026-2036
Autonomous Driving Component Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Driving Component Market Outlook
Subscription-based over-the-air software updates for perception algorithms is consolidating revenue models around recurring service contracts rather than one-time hardware sales. Robert Bosch GmbH leverages its manufacturing scale across sensor and actuator lines to anchor long-term OEM supply agreements. Continental AG competes through specialized LiDAR and radar portfolios calibrated to SAE Level-2 through Level-4 automation tiers. Aptiv PLC differentiates by controlling end-to-end software-defined vehicle architectures that integrate perception with motion planning.
Autonomous driving components encompass electromechanical and photonic systems—LiDAR emitters at 905 nm or 1550 nm wavelengths, 77 GHz radar front ends, CMOS image sensors exceeding 8 megapixels, and domain control units exceeding 500 TOPS compute density—engineered to perceive, fuse, and act upon real-time vehicular environments without human intervention. LiDAR and control units command the deepest margin pools as OEMs prioritize redundancy and compute headroom for higher automation levels. Sensor fusion technology leads deployment timelines where radar and camera outputs merge through centralized domain architectures, while computer vision applications in passenger vehicles sustain the broadest addressable volume base across consumer automotive programs.
The National Highway Traffic Safety Administration and Environmental Protection Agency in the United States enforce crashworthiness and emissions compliance that shapes how sensor packaging and thermal management systems get engineered for domestic road certification. The European Union's AI Act and type-approval frameworks under the United Nations Economic Commission for Europe regulate algorithmic transparency and functional safety, restricting market access for non-compliant perception stacks. Stakeholders must monitor how regulatory divergence between Washington and Brussels fragments certification pathways and forces dual-track product development investments.
Market Dynamics
Sensor fusion architectures are consolidating compute loads into centralized domain controllers, compressing the number of discrete ECUs per vehicle and redistributing margin pools toward software-defined perception stacks.
Growth Catalysts
- Level-3 Deployment Mandates:China's MIIT safety guidelines for conditional automation are accelerating domestic OEM validation programs for LiDAR and high-resolution camera arrays.
- Logistics Fleet Electrification:Commercial operators in Germany and the Netherlands are procuring redundant sensor suites for hub-to-hub autonomous freight corridors along the Rhine-Alpine corridor.
- Functional-Safety Certification:ISO 26262 ASIL-D compliance is becoming a non-negotiable procurement filter for European premium passenger vehicle programs.
Market Restraints
- Indium Phosphide Supply Concentration:1550 nm LiDAR emitter production depends on Chinese raw material processing, exposing margin structures to export control volatility.
- Edge Case Validation Burden:NHTSA's expanded crash-scenario testing protocols are extending type-approval timelines for perception algorithm updates by 8-14 months.
- Camera-First Substitution:Tesla's vision-only stack is pressuring Tier-1 suppliers to defend LiDAR value propositions against pure computer vision cost benchmarks.
Strategic Opportunities
- India's Automotive PLI Scheme:Component suppliers can capture 18-22% incentive offsets by localizing radar and camera module assembly for domestic OEM export programs.
- V2X Infrastructure Convergence:Integration of C-V2X roadside units with onboard perception is opening service revenue streams for traffic-authority data contracts.
- Subscription Perception Services:Over-the-air algorithm licensing is displacing one-time hardware sales with recurring revenue tied to map update and object-classification accuracy guarantees.
Industry Challenges
- Embedded Software Talent Scarcity:Functional-safety firmware engineers with ROS2 and AUTOSAR expertise command 40-60% compensation premiums, constraining R&D velocity at mid-tier suppliers.
- Multi-Domain Integration Complexity:Fusing LiDAR point clouds with 4D radar tensors and 8-megapixel video streams requires thermal management solutions that exceed legacy HVAC packaging constraints.
- Cross-Border Certification Divergence:The EU AI Act's algorithmic transparency requirements and NHTSA's black-box testing protocols are forcing dual-track validation investments with no harmonization mechanism.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Driving Component Market |
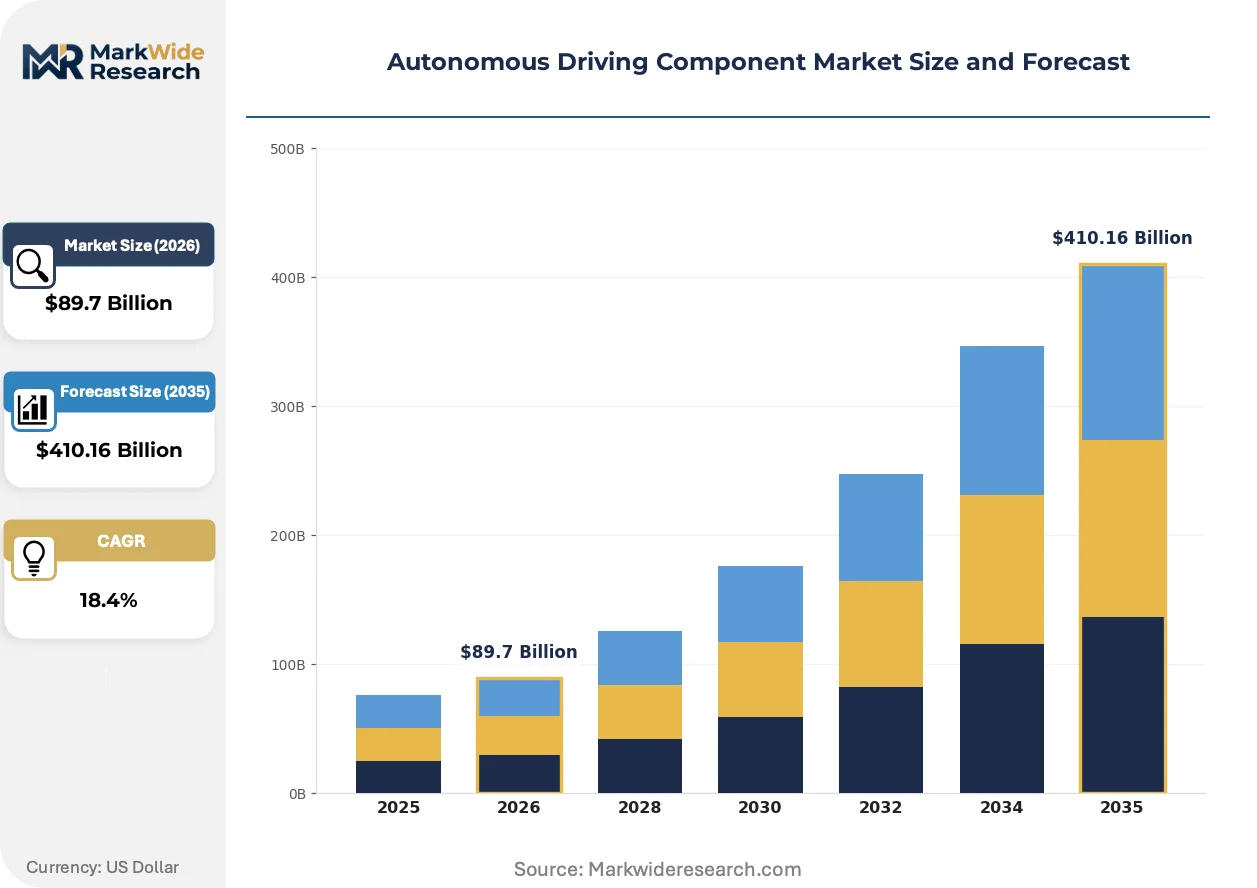
| Market Size in 2026 | $89.7 Billion |
| Market Size in 2035 | $410.16 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: LiDAR, Radar, Cameras, Control Units End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Sensor Fusion, Machine Learning, Computer Vision, V2X Communication Application: Passenger Vehicles, Commercial Trucks, Public Transport, Delivery Vehicles |
| Companies Covered | Continental AG, Autoliv Inc., Aptiv PLC, DENSO Corporation, Magna International Inc, Robert Bosch GmbH, ZF Friedrichshafen AG, Valeo, Murata Manufacturing Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Driving Component Market Strategic Shifts
Compute migration from distributed ECUs to centralized zonal architectures is compressing hardware BOMs while expanding software attach rates. Three force vectors are restructuring competitive positioning.
Domain control units exceeding 500 TOPS are decentralizing perception processing from sensor-integrated edge chips to vehicle-central compute clusters. Tier-1 suppliers are consolidating radar and camera raw data feeds through Ethernet backbone networks. This topology is enabling over-the-air model updates without hardware recalls, compressing supplier switching costs.
The EU AI Act's risk-based classification for autonomous vehicle algorithms is mandating conformity assessments for training data provenance and model explainability. German KBA type-approval offices are rejecting perception stacks lacking documented edge-case coverage matrices. European OEMs are responding by segregating EU-bound software branches from US and Chinese variants, fragmenting development overhead.
Fleet operators are unbundling sensor procurement from vehicle platform purchases, signing direct contracts with LiDAR and radar specialists for multi-OEM retrofit programs. Logistics providers in California and Texas are bypassing traditional Tier-1 integrators to negotiate volume pricing on 905 nm solid-state emitters. This disintermediation is most pronounced in autonomous trucking, where operating cost sensitivity overrides brand loyalty to incumbent suppliers.
Autonomous Driving Component Market Segmentation
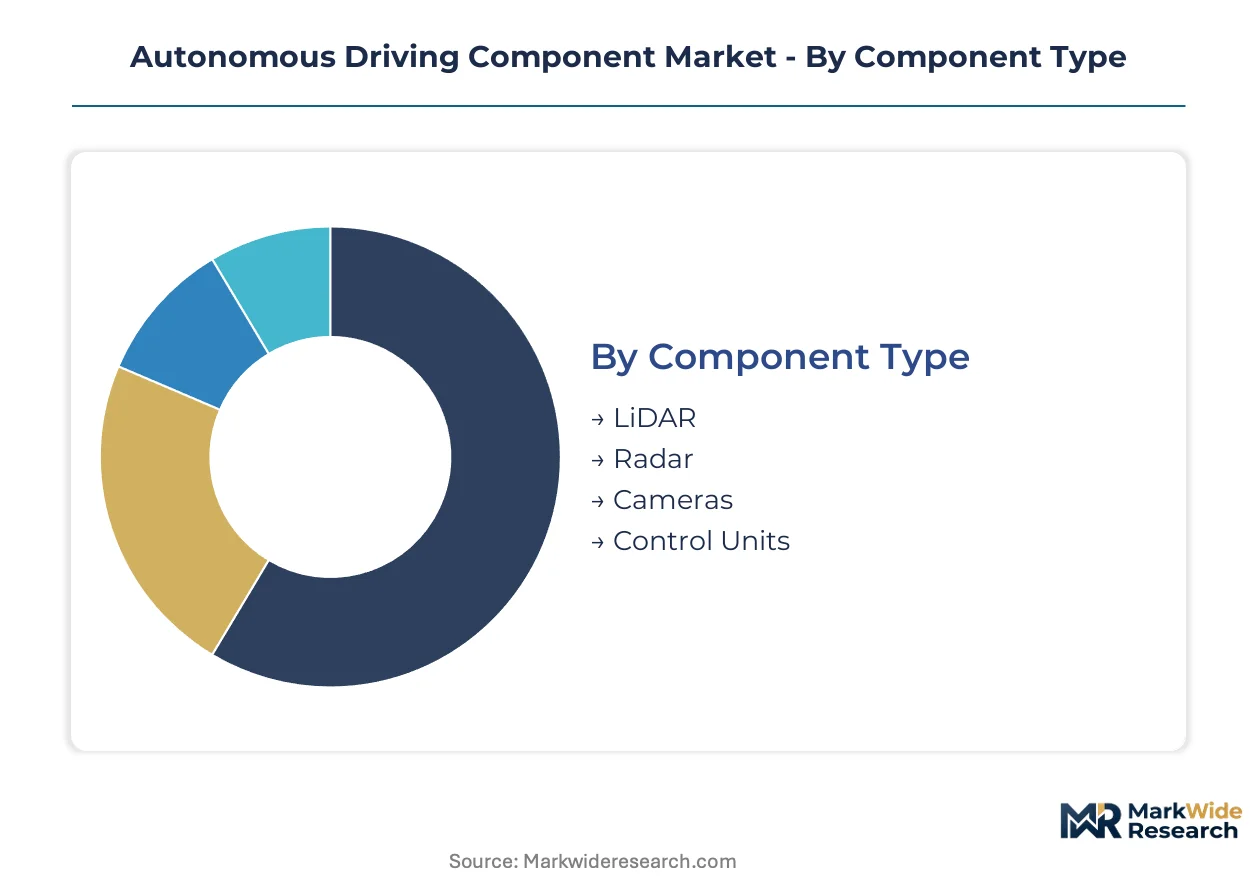
Component segmentation in autonomous driving reveals how procurement power concentrates around specific technology tiers and buyer types. Understanding these divides exposes where margin pools shift as automation levels advance and software-defined architectures mature.
Component Type:
Fleet procurement decisions hinge on redundancy requirements and compute headroom for target automation levels.
- LiDAR:Photonic systems operating at 905 nm or 1550 nm wavelengths generate dense point clouds for 3D environmental mapping. Chinese OEMs dominate demand for solid-state emitters as domestic Level-3 programs accelerate validation timelines. Indium phosphide supply concentration from Chinese processors exposes margin structures to export control volatility.
- Control Units:Domain controllers exceeding 500 TOPS compute density centralize perception processing from distributed edge chips. European premium passenger programs mandate ISO 26262 ASIL-D certification as a non-negotiable procurement filter. These units command the deepest margin pools as OEMs prioritize redundancy and future-proofing for higher automation tiers.
- Radar:77 GHz front-end modules provide velocity measurement and all-weather reliability complementary to optical sensors. German and Dutch logistics fleets procure redundant suites for Rhine-Alpine freight corridors.
- Cameras:CMOS image sensors exceeding 8 megapixels anchor computer vision stacks with lowest unit cost. Tesla's vision-only architecture pressures LiDAR value propositions across cost-sensitive vehicle programs.
Control Units lead on scale; LiDAR leads on momentum.
End User:
Customer type determines contract structure, from long-term supply agreements to spot procurement for retrofit fleets.
- OEMs:Vehicle manufacturers negotiate multi-year framework agreements locking in sensor volumes across platform generations. China's MIIT safety guidelines for conditional automation are accelerating domestic validation programs for integrated LiDAR and camera arrays.
- Fleet Operators:Commercial transport and logistics providers unbundle sensor procurement from vehicle purchases, signing direct contracts with component specialists. California and Texas operators bypass traditional Tier-1 integrators for volume pricing on solid-state emitters.
- Tier-1 Suppliers:System integrators consolidate radar and camera feeds through Ethernet backbone networks for OEM delivery. These intermediaries face disintermediation pressure as fleets seek direct component relationships.
- Aftermarket Providers:Retrofit specialists serve autonomy upgrade demand for existing vehicle parc, constrained by NHTSA's extended type-approval timelines for perception algorithm updates.
OEMs anchor volume commitments; Fleet Operators are gaining share fastest.
Technology:
Technology selection tracks the migration from hardware-centric to software-defined perception architectures.
- Sensor Fusion:Centralized processing of LiDAR point clouds, 4D radar tensors, and video streams through domain controllers. NHTSA and EPA testing protocols compel suppliers to certify systems under stricter functional-safety benchmarks.
- Computer Vision:Deep learning inference on high-resolution camera feeds sustains the broadest addressable volume across consumer automotive programs. Thermal management requirements for multi-sensor integration exceed legacy HVAC packaging constraints.
- Machine Learning:Over-the-air algorithm updates enable subscription revenue models displacing one-time hardware sales. The EU AI Act mandates conformity assessments for training data provenance and model explainability.
- V2X Communication:C-V2X roadside unit integration with onboard perception opens service revenue streams for traffic-authority data contracts.
Computer Vision leads on scale; Sensor Fusion leads on momentum.
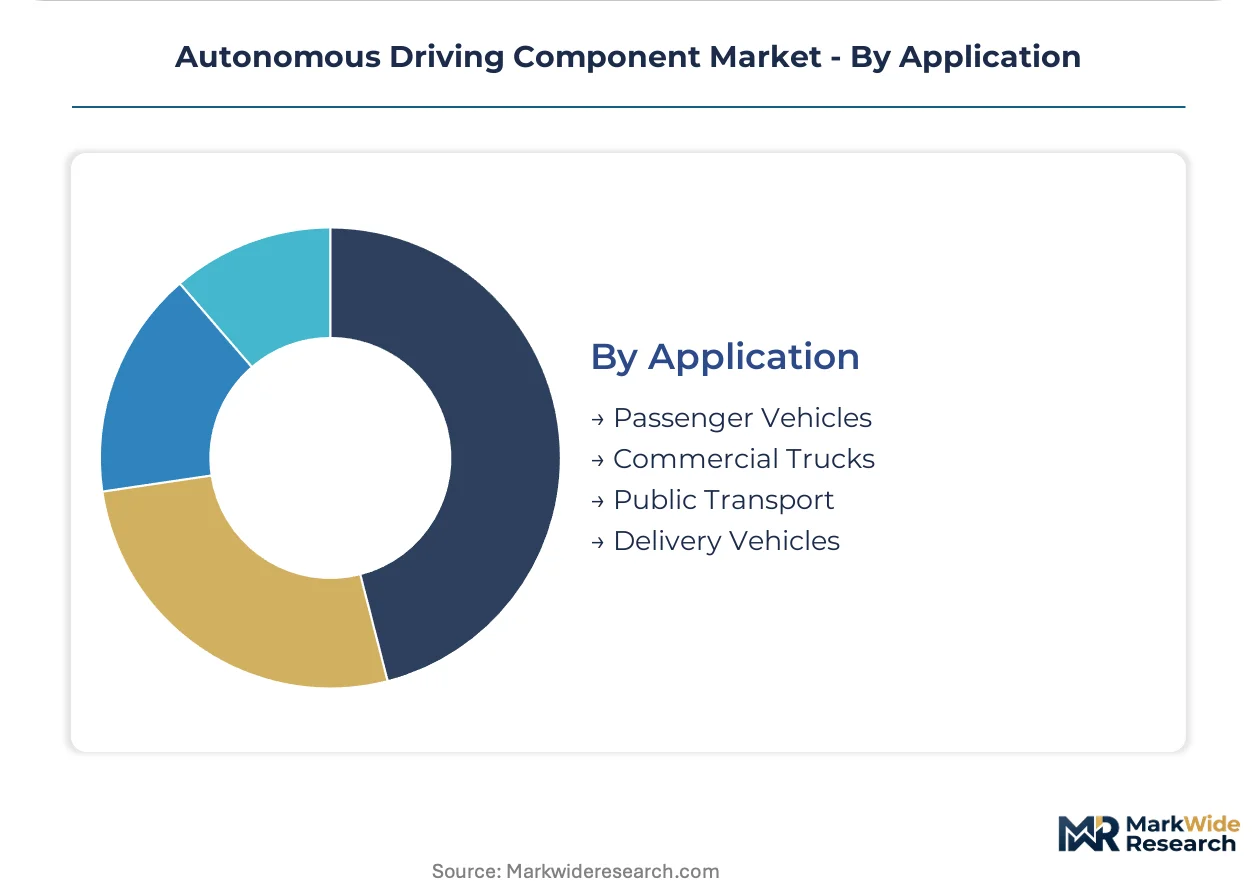
Application:
Application segmentation reflects diverging redundancy requirements and operating cost sensitivities across mobility modes.
- Passenger Vehicles:Consumer automotive programs sustain broadest sensor volume demand, with European premium segments prioritizing ASIL-D certified stacks. The EU AI Act and KBA type-approval frameworks regulate algorithmic transparency for EU-bound software branches.
- Commercial Trucks:Hub-to-hub autonomous freight corridors drive procurement of redundant sensor suites with highest reliability specifications. Operating cost sensitivity in trucking overrides brand loyalty to incumbent suppliers.
- Delivery Vehicles:Last-mile autonomous pods and robotaxis deploy optimized sensor configurations for low-speed urban environments.
- Public Transport:Fixed-route buses and shuttles leverage infrastructure integration for operational design domain constraints.
Passenger Vehicles lead on scale; Commercial Trucks climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's logistics corridors drive sensor suite procurement for autonomous freight, while China's domestic OEMs concentrate LiDAR demand for Level-3 passenger programs. Regulatory divergence between Washington and Brussels fragments certification pathways, forcing suppliers to maintain parallel validation tracks.
United States
NHTSA's expanded crash-scenario testing protocols extend type-approval timelines for perception algorithm updates by 8-14 months. The EPA tightens vehicle automation testing benchmarks, compelling component suppliers to certify thermal management and sensor packaging under stricter functional-safety standards. California and Texas logistics operators bypass traditional Tier-1 integrators to negotiate direct volume contracts for solid-state LiDAR emitters.
Germany
Commercial operators along the Rhine-Alpine freight corridor procure redundant radar and camera suites for hub-to-hub autonomous trucking. The KBA type-approval office rejects perception stacks lacking documented edge-case coverage matrices under EU AI Act conformity assessments. Stuttgart and Munich anchor OEM validation programs for ASIL-D certified domain controllers exceeding 500 TOPS compute density.
China
Domestic OEMs accelerate Level-3 deployment programs, concentrating demand for 905 nm solid-state LiDAR and high-resolution camera arrays. MIIT safety guidelines for conditional automation compress validation timelines for integrated sensor suites. Shanghai and Shenzhen house the deepest supplier ecosystems for photonic emitter production, though indium phosphide processing concentration exposes margin structures to export control volatility.
Japan
Premium passenger programs prioritize sensor fusion architectures merging 4D radar tensors with 8-megapixel video streams. METI promotes standardization for C-V2X roadside unit integration with onboard perception systems. Nagoya and Tokyo metropolitan clusters concentrate Tier-1 system integrator headquarters and embedded software development centers.
India
Radar and camera module assembly localizes under the Automotive PLI scheme, capturing 18-22% incentive offsets for component suppliers serving domestic OEM export programs. BIS certification requirements shape thermal management engineering for tropical operating conditions. Tamil Nadu and Gujarat host the fastest-expanding manufacturing footprints for CMOS image sensor packaging and 77 GHz radar front-end production.
Autonomous Driving Component Market Competitive Environment
Top-tier vendors anchor long-term OEM framework agreements, while mid-scale specialists compete through direct fleet procurement relationships. The market exhibits tiered consolidation around manufacturing scale, software-defined architectures, and specialized photonic portfolios. Two dominant archetypes emerge: diversified industrial conglomerates leveraging cross-product manufacturing scale, and focused sensor specialists capturing fleet disintermediation opportunities. Competitive moves concentrate on strategic partnerships for zonal architecture integration and geographic expansion into PLI-incentivized assembly jurisdictions.
Within the diversified conglomerate tier, Robert Bosch GmbH and Continental AG exemplify manufacturing-scale anchoring across sensor and actuator lines. Aptiv PLC occupies a position representing end-to-end software-defined vehicle architecture integration. These three entities span German and Irish corporate structures, reflecting European regulatory alignment with ISO 26262 functional-safety certification as a non-negotiable procurement filter for premium passenger programs.
| Leading Market Players |
|---|
| Continental AG |
| Autoliv Inc. |
| Aptiv PLC |
| DENSO Corporation |
| Magna International Inc |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Valeo |
| Murata Manufacturing Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Indium phosphide wafer processing costs cascade through 1550 nm LiDAR emitter pricing tiers, concentrating margin pressure on photonic component suppliers tethered to Chinese raw material flows while rewarding integrated players with captive supply arrangements.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for ASIL-D certified domain controllers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 26262 certification grade from compute density and thermal management specifications. Cost compression in solid-state LiDAR is intensifying because Tesla's vision-only stack forces 905 nm emitter suppliers to defend value propositions against pure computer vision benchmarks. Fleet operators exhibit highest price sensitivity due to operating cost mandates, while European premium passenger OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit anchor hub-and-spoke patterns for sensor module fulfillment. Manufacturing concentrates in China, Germany, and Japan for LiDAR emitters, domain controllers, and radar front-ends respectively. The supply chain draws from indium phosphide substrates, 300mm CMOS wafers, and 77 GHz RF substrates as critical inputs. Single-source vulnerability in Chinese rare earth processing exposes margin structures to export control volatility. Distribution runs through Tier-1 system integrators consolidating multi-sensor feeds for OEM delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in software-defined perception stacks where subscription revenue displaces hardware depreciation cycles, enabled by centralized compute architectures reducing sensor-integrated edge chip BOMs.
For Market Incumbents: Deploy backward integration into indium phosphide processing to insulate margin structures from Chinese export control volatility. Anchor long-term OEM framework agreements across sensor and actuator lines to defend against fleet operator disintermediation. Prioritize ASIL-D certification investments as non-negotiable procurement filters tighten in European premium passenger programs. For New Entrants and Emerging Players: Fleet operators in California and Texas present the most penetrable buyer archetype for direct component relationships bypassing traditional Tier-1 integrators. India's Automotive PLI scheme offers 18-22% incentive offsets for radar and camera module assembly localization. Pursue spot procurement contracts for solid-state LiDAR retrofit programs where operating cost sensitivity overrides incumbent brand loyalty. For Investors and Strategic Acquirers: Consolidation pressure builds where embedded software talent scarcity constrains R&D velocity at mid-tier suppliers. Five-to-ten year viability favors specialists with ROS2 and AUTOSAR functional-safety firmware depth over hardware-centric assemblers. Monitor NHTSA type-approval timeline compression as signal for algorithm update service revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Centralized domain architectures exceeding 500 TOPS enable over-the-air perception model updates without hardware recalls. |
| Battery Supply Agreement | Electrified logistics fleets in Germany and the Netherlands procure redundant sensor suites for autonomous freight corridors. |
| Geographic Manufacturing Footprint | Tamil Nadu and Gujarat PLI incentives capture 18-22% offsets for CMOS image sensor and radar module assembly. |
| Platform Standardization | Sensor fusion architectures compress discrete ECU counts while redistributing margin pools toward software stacks. |
| Charging Infrastructure Partnership | C-V2X roadside unit integration with onboard perception opens traffic-authority data contract revenue streams. |
Study Parameters
Multiple input streams — OEM platform engineering disclosures, Tier-1 supplier procurement patterns, and fleet operator retrofit demand signals — were reconciled through primary interviews with autonomous vehicle program directors, functional-safety certification leads, LiDAR module procurement managers, and logistics fleet technology officers, validated against NHTSA type-approval filings, MIIT safety guideline publications, EU AI Act conformity assessments, and vehicle production registration databases, with bottom-up component demand aggregation cross-checked against top-down market sizing.
Data-stream reconciliation across the analysis window applied segmentation by automation level, vehicle class, sensor modality, and regional regulatory cluster, with CAGRs derived from installed base projections and content-per-vehicle trajectories for LiDAR emitter penetration, domain controller compute density migration, and radar-to-camera substitution elasticities under vision-first cost benchmarks.
Underlying measurement precision varies by segment; passenger vehicle sensor volumes carry tighter precision than aftermarket retrofit demand given NHTSA's extended type-approval timeline uncertainty. Forecasts reflect documented assumptions around Level-3 deployment acceleration, indium phosphide supply stability, and algorithmic transparency regulatory divergence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Autonomous Vehicles
Vehicle Intelligence System Market
Autonomous Vehicles
Robotaxi Market
Autonomous Vehicles
Luxury Autonomous Vehicle Market
Autonomous Vehicles
Europe Autonomous Navigation Market
Autonomous Vehicles
Advanced Driver Assistance System (ADAS) Market
Autonomous Vehicles
Middle East and Africa Automated Guided Vehicles Market
Autonomous Vehicles
Automated Valet Parking (AVP) Market
Autonomous Vehicles
L4 Autonomous Driving Market
Autonomous Vehicles
Self-Driving Electric Vehicle Market
Autonomous Vehicles
Autonomous Driving Technology Market
Autonomous Vehicles
Automotive Autonomous Emergency Braking System Market
Autonomous Vehicles
Autonomous Vehicle Management Services Market
Autonomous Vehicles
HD Map for Autonomous Vehicle Market
Autonomous Vehicles
Global Robot Cars and Trucks Market
Autonomous Vehicles
Italy Autonomous Navigation Market
Autonomous Vehicles
Autonomous Ride-Sharing Services Market