
 Brazil Automotive Airfilters Market | 2026-2036
Brazil Automotive Airfilters Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Airfilters Market Outlook
Fleet procurement concentration among Brazil's commercial vehicle operators is hardening as logistics companies centralize maintenance contracts under larger national carriers. Mann+Hummel anchors its position through OEM supply agreements with domestic automakers. K&N Engineering differentiates via performance-oriented aftermarket channels targeting enthusiast segments. Purolator Filters LLC competes on professional installation networks tied to authorized service centers.
Automotive airfilters are engineered media assemblies designed to remove particulate matter, pollen, and gaseous contaminants from intake or cabin airflow, typically constructed from pleated paper, synthetic fiber, or foam substrates with specified micron ratings and pressure-drop thresholds. Engine filters protect combustion systems from abrasive wear, while cabin filters regulate occupant exposure to ambient pollution. Panel filters and engine filters command the largest volume share due to mandatory replacement cycles, yet cabin filters incorporating activated carbon represent the fastest-expanding margin pool as consumer sensitivity to interior air quality intensifies. Synthetic fiber materials are displacing conventional pleated paper in premium tiers where extended service intervals justify higher unit costs.
ANVISA governs material safety standards for cabin filtration media, while the Brazilian Institute of Metrology, Standardization and Industrial Quality (INMETRO) certifies performance claims under national conformity assessment procedures. PROCONVE emission regulations indirectly tighten engine airfilter specifications as cleaner combustion requires optimized intake air quality. Stakeholders must weigh the cost of migrating to synthetic fiber and activated carbon platforms against the risk of exclusion from OEM and fleet contracts as certification thresholds tighten.
Market Dynamics
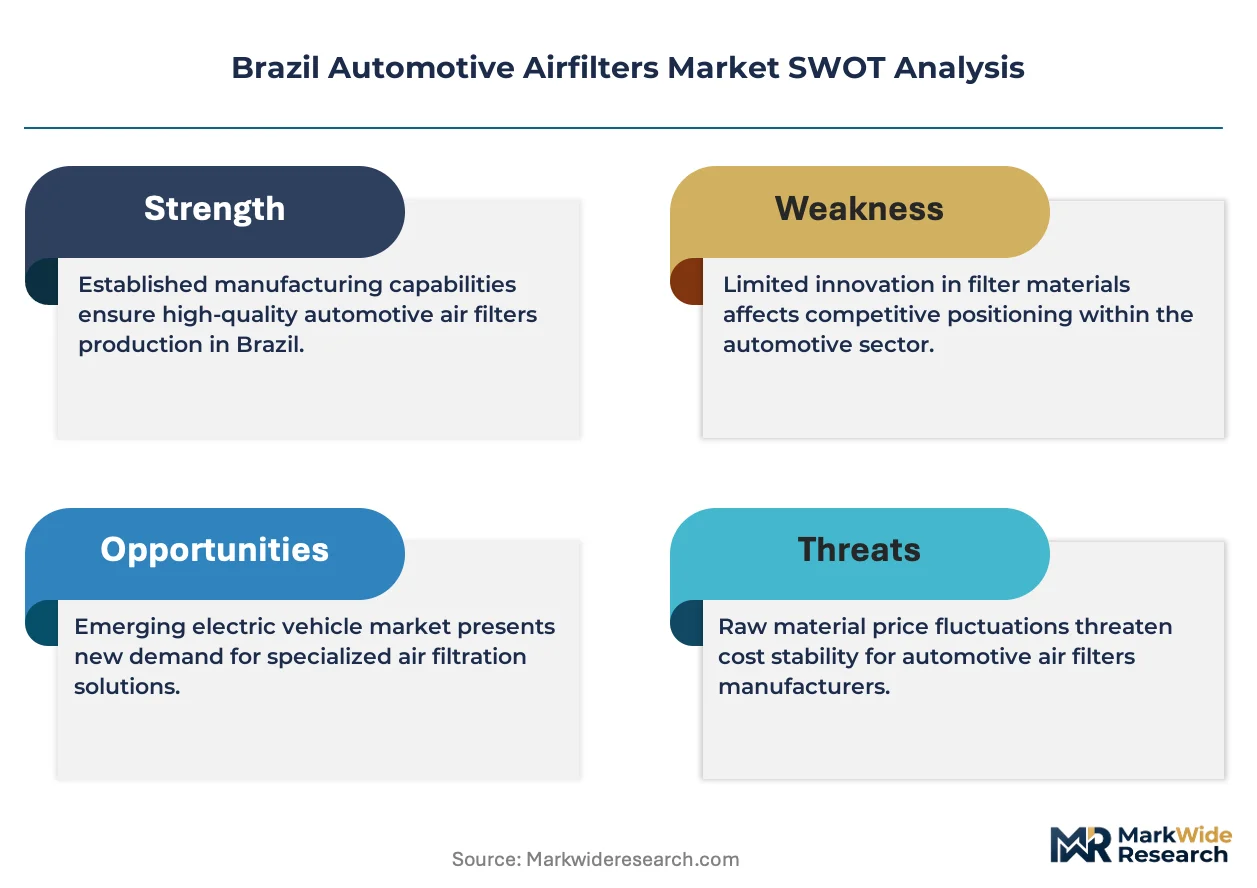
Fleet procurement consolidation among Brazil's logistics carriers is compressing supplier margins while elevating certification requirements for synthetic fiber and activated carbon filtration media under tightening ANVISA standards.
Growth Catalysts
- ANVISA cabin air quality mandates:Evolving standards for vehicle interior contamination are compelling filter suppliers to certify activated carbon and synthetic fiber substrates, creating upgrade cycles across São Paulo's dense service network.
- Commercial fleet centralization:National logistics carriers are consolidating maintenance contracts under single-source agreements, concentrating aftermarket volume with certified suppliers capable of multi-location fulfillment.
- Synthetic fiber displacement:Extended service interval requirements from fleet operators are accelerating adoption of non-woven synthetic media over conventional pleated paper in premium replacement tiers.
Market Restraints
- Petrochemical input volatility:Synthetic fiber and activated carbon production depends on propylene and bituminous coal derivatives subject to exchange-rate-driven cost swings in Brazil's import-dependent chemical sector.
- Southeastern supply concentration:Filter manufacturing and distribution infrastructure clusters disproportionately in São Paulo state, exposing national fulfillment to regional logistics disruptions and state-level tax regime changes.
- INMETRO certification timelines:Conformity assessment procedures for new filtration media formulations impose 12-18 month validation windows that delay product launches and freeze R&D amortization schedules.
Strategic Opportunities
- Northeastern aftermarket underpenetration:Pernambuco and Bahia states lack equivalent service network density to São Paulo, presenting first-mover expansion potential for certified installation partnerships.
- PROCONVE-induced engine filter upgrading:Tightening emission regulations are indirectly mandating higher-specification intake filtration to protect exhaust aftertreatment systems, opening premium engine filter positioning.
- Direct-to-fleet digital procurement:Centralized carrier maintenance departments are piloting vendor-managed inventory platforms that bypass traditional parts distributor markups.
Industry Challenges
- Multi-standard certification complexity:Suppliers must simultaneously satisfy ANVISA material safety protocols, INMETRO performance claims, and OEM-specific durability testing, fragmenting quality assurance resources.
- Legacy paper-to-synthetic retooling:Converting existing pleating and sealing equipment for synthetic fiber handling requires capital outlays that strain mid-tier suppliers with concentrated paper-based revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Airfilters Market |
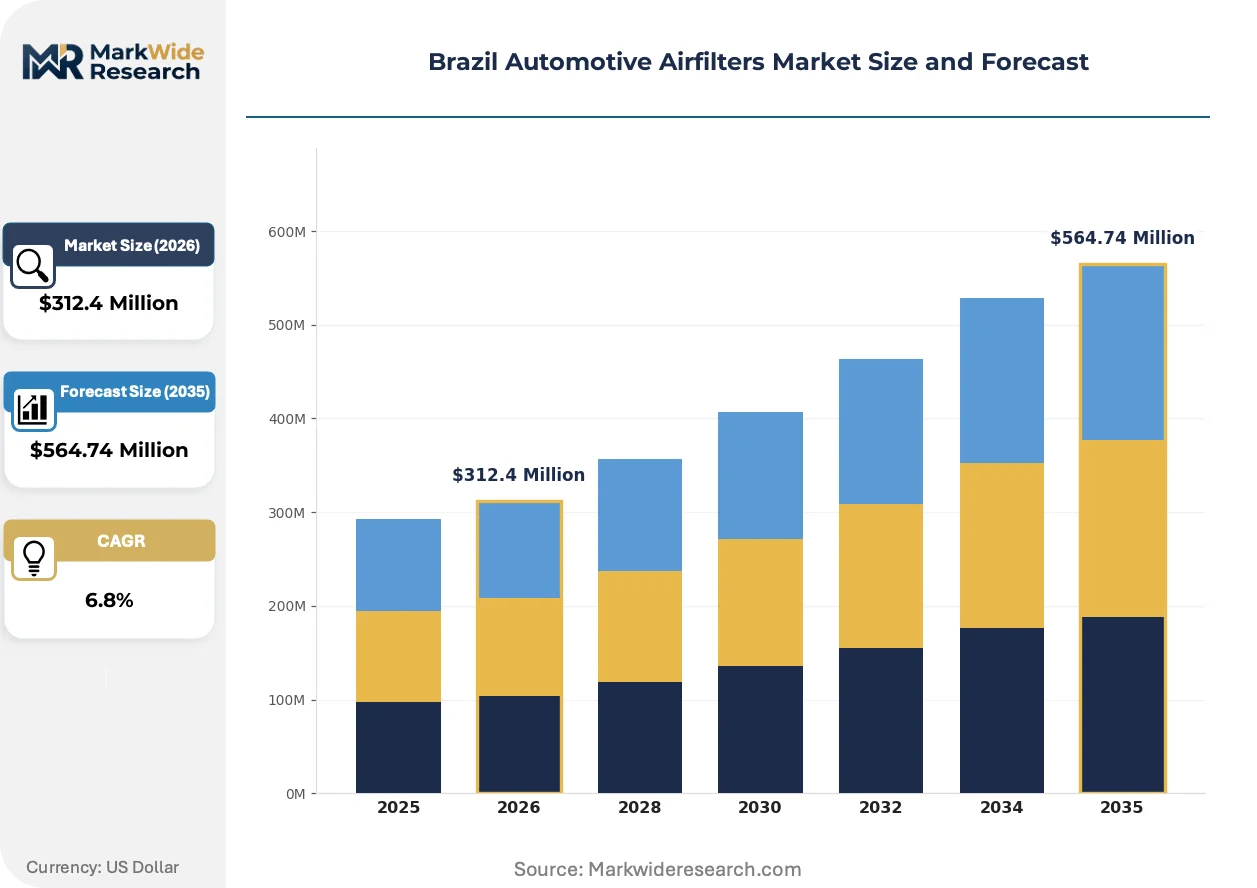
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Filters, Cabin Filters, Engine Filters, Foam Filters Customer Type: OEMs, Aftermarket Providers, Retailers, Distributors Material: Pleated Paper, Synthetic Fiber, Foam, Activated Carbon Installation: DIY, Professional, Semi-Professional, Quick Change |
| Companies Covered | Mann+Hummel, K&N Engineering, JS Automobiles, AL Filters, Allena Group, Wsmridhi Manufacturing Co Pvt Ltd, Purolator Filters LLC, Advanced Flow Engineering Inc, AIRAID, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Airfilters Market Strategic Shifts
Filtration technology evolution in Brazil is converging on automated production systems and regulatory-driven material upgrades, with demand patterns shifting toward consolidated procurement relationships that favor certified national suppliers over fragmented regional distributors.
Pleating and sealing automation is automating filter assembly lines across São Paulo state's manufacturing base. Tier-one suppliers are deploying robotic handling systems for synthetic fiber media to achieve the dimensional precision required by OEM contracts. This automation is compressing unit labor costs and narrowing the viability window for manual-assembly competitors serving price-sensitive aftermarket channels.
ANVISA's expanded material safety protocols for cabin filtration are mandating formaldehyde emission testing and antimicrobial additive disclosure for all new filter submissions. The regulatory burden falls heaviest on import-dependent suppliers lacking domestic laboratory certification partnerships. Aftermarket distributors are responding by consolidating supplier panels to reduce compliance administration overhead.
Fleet maintenance departments are unbundling filter replacement from general service contracts to negotiate direct supply agreements with certified manufacturers. This disintermediation is displacing traditional parts wholesalers in the commercial vehicle segment. São Paulo state's largest logistics operators are pioneering vendor-managed inventory arrangements that transfer stockholding risk upstream to filter suppliers.
Brazil Automotive Airfilters Market Segmentation
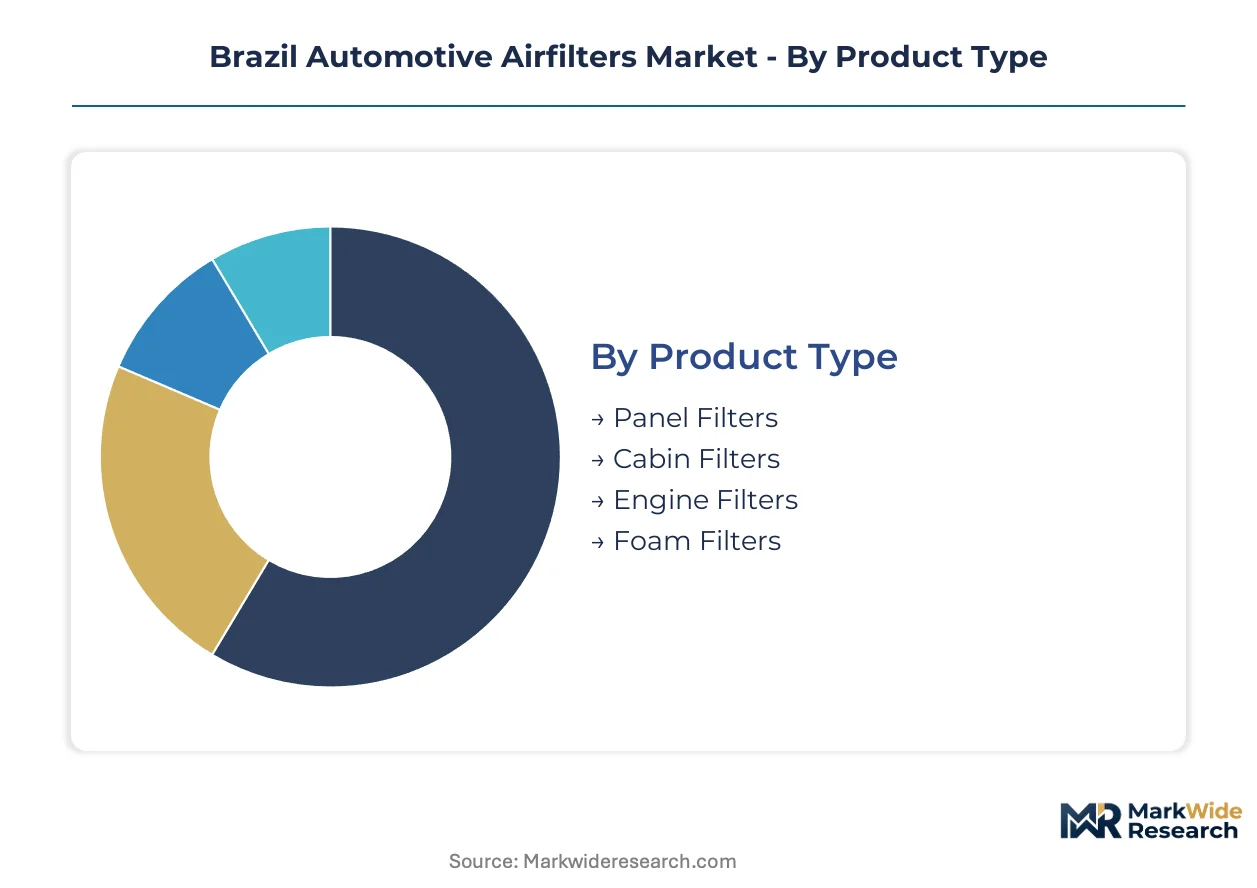
Segmentation in Brazil's automotive airfilter market reveals how procurement power concentrates among fleet operators while material certification requirements fragment supplier tiers. Understanding these divides exposes where margin pools form and which customer relationships command strategic priority.
Product Type:
Fleet procurement teams prioritize replacement interval predictability and compliance documentation when selecting filter formats, with ANVISA certification status now outweighing unit price in bid evaluations.
- Panel Filters:Rectangular pleated media assemblies with standardized dimensions dominate high-volume replacement cycles across São Paulo's commercial service networks. Fleet maintenance contracts in the southeastern state specify panel formats for their compatibility with automated inventory systems and rapid technician training curves.
- Cabin Filters:Multi-layer media designed for HVAC intake systems increasingly incorporate activated carbon substrates to satisfy ANVISA's expanded material safety protocols for formaldehyde emission control. Consumer sensitivity to interior air quality in dense urban corridors accelerates upgrade demand beyond mandatory replacement schedules.
- Engine Filters:Cylindrical or conical configurations protect combustion systems from abrasive particulate ingress, with PROCONVE emission regulations indirectly tightening specifications to preserve exhaust aftertreatment system integrity.
- Foam Filters:Reticulated polyurethane substrates serve specialized off-road and performance applications where washability and reusability offset higher initial acquisition costs.
Panel filters lead on scale; cabin filters lead on momentum.
Customer Type:
Channel power has shifted decisively toward centralized procurement functions that can enforce multi-location certification standards and absorb vendor-managed inventory arrangements.
- OEMs:Domestic automakers specify filtration media through supply agreements that lock in synthetic fiber formulations for extended service intervals, with contract duration now stretching across entire vehicle platform lifecycles.
- Aftermarket Providers:National service chains in São Paulo state consolidate replacement volume under single-source agreements that bypass traditional wholesale distribution, capturing margin through direct manufacturer relationships.
- Retailers:Auto parts stores in secondary Brazilian cities face compression as fleet procurement centralization diverts commercial volume toward certified installation networks.
- Distributors:Traditional wholesale intermediaries are repositioning toward logistics and compliance administration as disintermediation erodes their historical markup capture in the commercial vehicle segment.
OEMs anchor volume concentration; aftermarket providers are climbing the fastest.
Material:
Raw material selection now functions as a regulatory compliance decision rather than purely a cost optimization exercise, with INMETRO certification timelines extending the effective switching cost between substrate platforms.
- Pleated Paper:Cellulose-based media with defined micron ratings retains dominance in price-sensitive replacement tiers where service intervals remain short and labor costs absorb frequent changeout schedules.
- Synthetic Fiber:Non-woven polypropylene or polyester substrates deliver extended durability and moisture resistance, justifying premium positioning in fleet contracts where downtime minimization outweighs unit cost differentials.
- Foam:Open-cell polyurethane structures serve reusable filter applications in agricultural and construction equipment operating in high-dust environments across Brazil's interior states.
- Activated Carbon:Bituminous coal-derived substrates adsorb gaseous contaminants and odors, with ANVISA's cabin air quality mandates accelerating displacement of standard particulate-only media in premium vehicle segments.
Pleated paper leads on scale; activated carbon leads on momentum.
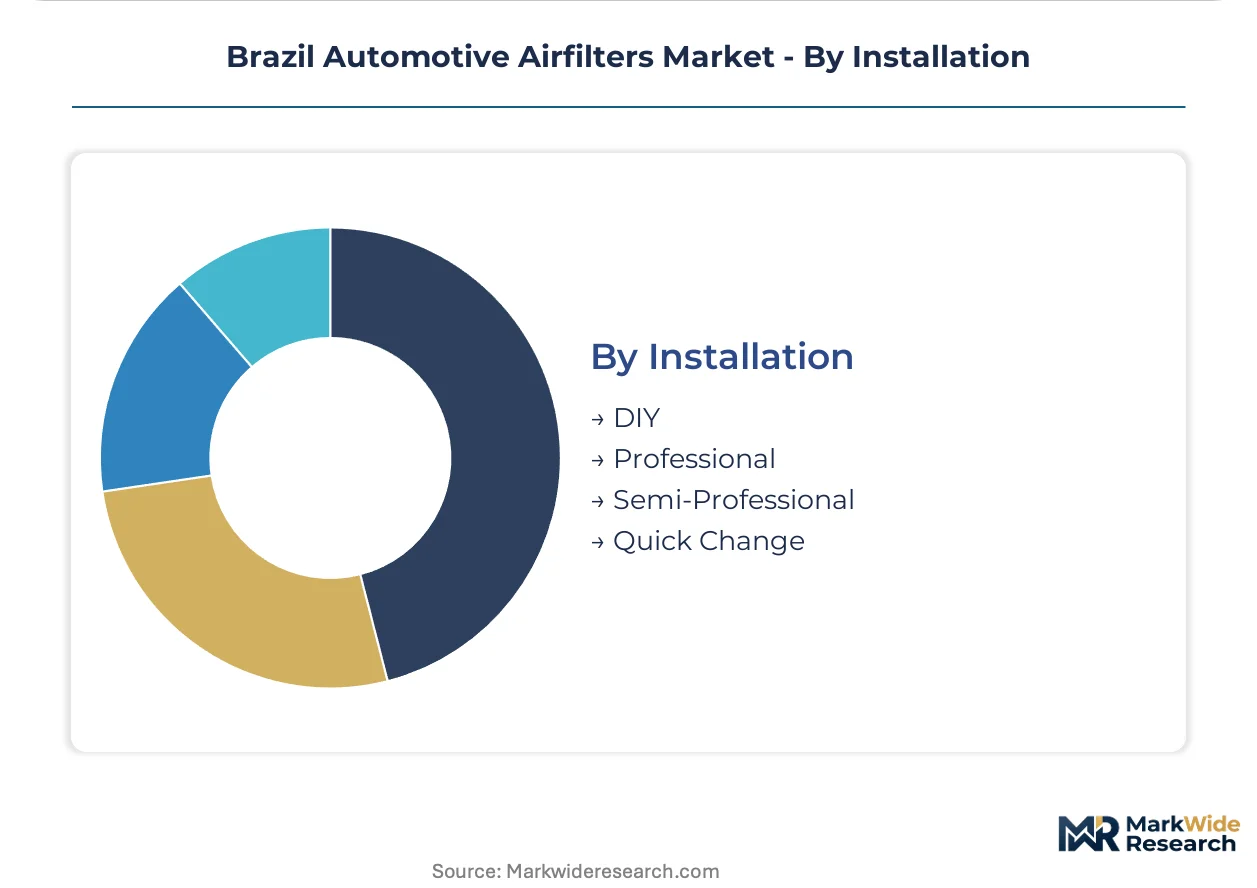
Installation:
Service format selection correlates directly with customer scale, with largest fleet operators internalizing even complex filtration maintenance while individual owners gravitate toward lowest-touch options.
- DIY:Consumer self-installation of panel and engine filters persists in Brazil's independent vehicle owner segment, supported by standardized dimensions and minimal tool requirements.
- Professional:Certified technician installation dominates cabin filter replacement as ANVISA documentation requirements and HVAC system complexity elevate liability exposure for improper sealing.
- Semi-Professional:Quick-lube chains in São Paulo's metropolitan corridor offer intermediate service formats that blend speed with basic compliance verification for fleet light-duty vehicles.
- Quick Change:Express service bays at fuel stations and parking facilities target time-constrained commercial drivers with pre-stocked common filter formats and streamlined documentation.
Professional installation leads on scale; quick change formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates automotive airfilter demand more heavily than any other Latin American market, while Mexico's export-oriented assembly plants generate distinct procurement patterns tied to US supply chains.
São Paulo
Southeastern Brazil's industrial heartland hosts the densest concentration of automotive service networks and filter manufacturing infrastructure. ANVISA's evolving cabin air quality standards receive their strictest enforcement interpretation here, pressuring suppliers to maintain activated carbon certification. The metropolitan corridor's fleet operators pioneer vendor-managed inventory arrangements that bypass traditional wholesale distribution.
Minas Gerais
Belo Horizonte's logistics sector drives aftermarket volume through mining equipment maintenance and heavy-duty commercial vehicle fleets. INMETRO conformity assessment timelines extend product launch cycles for new synthetic fiber formulations entering this market. Regional distributors consolidate supplier panels to reduce compliance administration overhead.
Rio Grande do Sul
Porto Alegre's agricultural machinery base sustains demand for reusable foam filters in high-dust operating environments. PROCONVE emission regulations indirectly tighten engine airfilter specifications as cleaner combustion requirements spread beyond metropolitan centers. Local service networks lag São Paulo in certified installation capacity.
Bahia
Northeastern Brazil's largest state presents underpenetrated aftermarket potential relative to its vehicle population. Fleet procurement centralization has not yet displaced traditional parts wholesalers here. Salvador's emerging logistics corridors attract first-mover expansion from certified installation networks.
Brazil Automotive Airfilters Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Brazil's tiered supply structure. The market exhibits moderate consolidation at the OEM supply tier alongside fragmentation in price-sensitive aftermarket channels. Three archetypes dominate: multinational filtration conglomerates with integrated material science capabilities, regional specialists serving fleet maintenance contracts, and import-dependent distributors repositioning toward compliance administration. Capacity expansion and strategic partnerships represent the dominant competitive moves as certification requirements tighten.
Within the multinational tier, Mann+Hummel anchors OEM supply relationships through synthetic fiber platform agreements spanning domestic automaker platforms. K&N Engineering occupies a position in performance-oriented aftermarket channels where enthusiast segments justify premium positioning. Purolator Filters LLC exemplifies the professional installation network model through authorized service center relationships. These three represent divergent strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| Mann+Hummel |
| K&N Engineering |
| JS Automobiles |
| AL Filters |
| Allena Group |
| Wsmridhi Manufacturing Co Pvt Ltd |
| Purolator Filters LLC |
| Advanced Flow Engineering Inc |
| AIRAID |
| Others |
Value Chain & Pricing Dynamics
Fleet procurement centralization under São Paulo's national logistics carriers is compressing supplier margins and forcing synthetic fiber and activated carbon certification investments that reshape cost structures across the value chain.
Pricing Analysis
Capacity additions in São Paulo state's manufacturing corridor are reshaping price floors for certified filtration media. Three-tier pricing structure across premium synthetic fiber, standard cellulose, and economy pleated paper segments stratifies by ANVISA certification status and volume commitment scale. Cost compression in the mid-tier cellulose segment is intensifying because fleet operators are extending replacement intervals and demanding documented compliance. Small independent workshops show highest price sensitivity, while national carriers with vendor-managed inventory arrangements absorb premium positioning for downtime reduction.
Supply Chain Analysis
Skilled technician availability constraints in Minas Gerais and Bahia states limit certified installation network expansion beyond São Paulo's dense service infrastructure. Manufacturing draws from propylene feedstock imports, bituminous coal derivatives for activated carbon, and domestic cellulose pulp supplies. Single-source vulnerability concentrates in petrochemical inputs subject to exchange-rate volatility. Distribution runs through national service chains and direct fleet agreements that displace traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's automotive airfilter market functions as a geographic-arbitrage play where northeastern underpenetration offers expansion runway against southeastern certification cost escalation.
For Market Incumbents: Deepen synthetic fiber platform investments to defend OEM contract renewals as domestic automakers lock in extended service interval specifications. Secure backward integration into propylene-based non-woven media production to offset import-dependent cost volatility. Anchor position through vendor-managed inventory partnerships with São Paulo's largest fleet operators.
For New Entrants and Emerging Players: Begin with certified installation partnerships in Salvador and Recife logistics corridors where fleet procurement centralization has not yet displaced traditional wholesalers. Target quick-lube chain relationships for semi-professional service formats that bridge DIY and professional installation gaps. Lead with activated carbon cabin filter offerings that satisfy ANVISA's expanding formaldehyde emission protocols.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier synthetic fiber specialists holding INMETRO certification pipelines and underutilized pleating automation capacity. Long-term viability hinges on regulatory compliance infrastructure rather than raw scale. Watch PROCONVE emission tightening timelines as the inflection signal for premium engine filter specification upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Fiber Platform Certification | INMETRO validation unlocks OEM supply agreements spanning entire vehicle platform lifecycles. |
| Vendor-Managed Inventory Expansion | Direct fleet relationships in São Paulo bypass distributor markups and capture aftermarket margin. |
| Northeastern Service Network Buildout | Certified installation partnerships in Bahia and Pernambuco address underpenetrated fleet demand. |
| Activated Carbon Substrate Investment | ANVISA cabin air quality mandates accelerate displacement of particulate-only media. |
| Pleating Automation Deployment | Robotic handling systems achieve dimensional precision required by domestic automaker contracts. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM procurement teams, aftermarket distributor operations heads, fleet maintenance directors, and INMETRO certification specialists alongside secondary validation through ANVISA regulatory filings, vehicle production databases, customs import records for petrochemical feedstocks, and automotive service network density surveys. Bottom-up filter unit demand estimates triangulated against top-down automotive parc and replacement interval assumptions.
Segment-weighted projections applied differential growth rates across product types, customer channels, material substrates, and installation formats over the projection horizon. CAGRs derived from regression analysis of historical replacement cycle compression, fleet centralization trajectories, and regulatory phase-in schedules. Industry-specific inputs included PROCONVE emission roadmap alignment, synthetic fiber adoption curves from European precedent markets, and ANVISA enforcement intensity differentials across state-level environmental agencies.
Several conditions sit outside the modeled scope, including abrupt currency devaluation scenarios affecting propylene import costs, unilateral state tax regime changes disrupting southeastern distribution economics, and accelerated PROCONVE timelines beyond current regulatory announcements. Forecasts reflect documented assumptions regarding fleet operator behavior continuity and certification timeline stability. Material deviation in petrochemical input pricing or ANVISA enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
External Combustion Engine Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Global Automotive Adaptive Suspension System Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Global Bearing Isolators Market
Automotive Parts
Japan Automotive Hydraulic Actuators Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Indonesia Automotive Lubricants Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Morocco Automotive Engine Oils Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Universal Joint Shafts Market