
 Zero Emission Trucks Market | 2026-2036
Zero Emission Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Emission Trucks Market Insights
Battery chemistry diversification is fragmenting the zero emission truck technology stack into competing pathways. Tesla leverages its cylindrical cell format and proprietary thermal management to anchor long-haul range claims. BYD sustains cost leadership through in-house lithium iron phosphate cell production and vertical cell-to-pack integration. Daimler Truck competes across multiple energy architectures, spanning battery electric and hydrogen fuel cell platforms to cover varied duty cycles.
Zero emission trucks are heavy-duty commercial vehicles propelled by electric drivetrains or hydrogen fuel cells, achieving zero tailpipe emissions through energy storage systems typically exceeding 200 kWh or pressurized hydrogen tanks at 350-700 bar, designed primarily for freight movement and urban logistics. Battery electric trucks dominate near-term deployment due to falling cell costs and expanding megawatt charging infrastructure, while hydrogen fuel cell trucks occupy the premium long-haul segment where energy density and refueling speed determine operational viability. Energy management systems represent a critical margin pool as fleet operators prioritize predictive range analytics and vehicle-to-grid integration capabilities.
The EPA's greenhouse gas standards for heavy-duty vehicles and California's Advanced Clean Trucks mandate are reshaping product planning timelines and certification requirements for manufacturers selling into the United States. The EU Green Deal's CO2 performance standards for heavy-duty vehicles, enforced by ECHA and national type-approval authorities, are eliminating diesel truck sales across Germany, France, and the Netherlands by specified phase-out dates. Fleet procurement teams must evaluate total cost of ownership models that incorporate electricity rate structures, hydrogen supply contracts, and residual value risk before committing to platform-specific infrastructure investments.
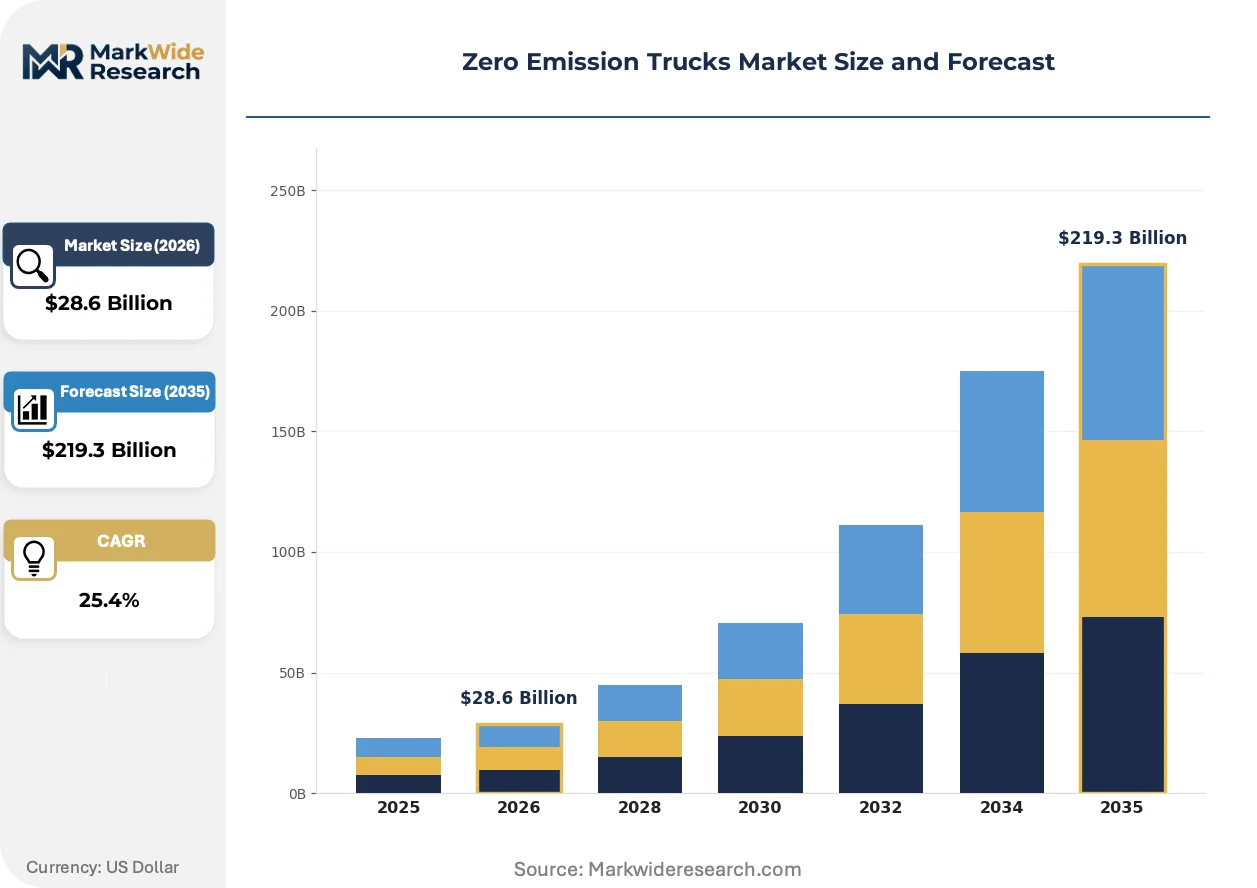
Market Dynamics
Battery chemistry divergence and megawatt charging infrastructure deployment are fragmenting the zero emission truck technology stack into competing pathways with distinct capital requirements and operational envelopes.
Growth Catalysts
- California's Advanced Clean Trucks regulation:Fleet operators face binding zero-emission sales quotas that compress procurement timelines and force early platform commitments before total cost of ownership parity is achieved.
- Urban freight electrification:Last-mile delivery operators in Germany and the Netherlands are converting depots to all-electric fleets to comply with municipal diesel bans and secure preferential loading zone access.
- Lithium iron phosphate cell cost curves:In-house cathode production and cell-to-pack architectures are compressing battery pack costs for regional haul applications with predictable duty cycles.
Market Restraints
- Critical mineral supply concentration:Cobalt and nickel processing capacity concentrates in the Democratic Republic of Congo and Indonesia, exposing battery supply chains to geopolitical disruption and export restriction risk.
- Hydrogen fuel cell capex intensity:Platinum group metal loading in proton exchange membrane stacks and 700-bar tank certification costs sustain premium pricing that limits fuel cell truck deployment to subsidized corridor pilots.
- Grid interconnection queues:Fleet depot electrification projects face multi-year utility approval timelines in jurisdictions with constrained distribution infrastructure, delaying charging infrastructure commissioning.
Strategic Opportunities
- Vehicle-to-grid integration:Bidirectional charging hardware and fleet energy management software create new revenue streams from grid services contracts with regional transmission operators.
- EU Green Deal CO2 standards:Phase-out mandates for internal combustion heavy-duty vehicles in France, Germany, and the Netherlands guarantee demand visibility through 2035 for zero-emission platform manufacturers.
- Autonomous hub-to-hub corridors:Fixed-route highway segments between distribution centers enable supervised autonomous operation that maximizes electric drivetrain efficiency and minimizes driver cost exposure.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance operations lack certified personnel for 800-volt battery system diagnostics and thermal runaway containment protocol execution.
- Residual value underwriting:Secondary market liquidity for battery electric trucks remains undeveloped, forcing lessors to apply punitive depreciation schedules that inflate lease rates.
- Multi-platform certification complexity:Separate type-approval pathways for battery electric and hydrogen fuel cell variants fragment engineering resources and extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Emission Trucks Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $219.3 Billion |
| CAGR (2026 – 2036) | 25.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Trucks, Hydrogen Fuel Cell Trucks, Plug-in Hybrid Trucks, Others End User: Logistics Companies, Delivery Services, Public Transportation, Waste Management Technology: Battery Technology, Fuel Cell Technology, Energy Management Systems, Autonomous Systems Application: Urban Delivery, Long-Haul Transportation, Construction, Freight Logistics |
| Companies Covered | Tesla Inc., BYD Company Limited, Daimler Truck, Volvo Group, Nikola Corporation, Navistar International, Xos Trucks, Rivian Automotive Inc., Iveco Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Emission Trucks Market Trends and Innovations
Energy storage system architecture and charging infrastructure topology are converging to compress refueling time differentials between electric and diesel platforms while fragmenting competitive advantage sources across the value chain.
Solid-state battery prototyping is collapsing the energy density gap that currently constrains battery electric trucks to regional haul duty cycles. Daimler Truck and CATL are validating sulfide electrolyte cells for 2027 production ramps that would enable 500-mile range without payload penalty. This chemistry transition is collapsing the technical justification for hydrogen fuel cell investment in all but the most extreme long-haul corridors.
The EPA's greenhouse gas standards for heavy-duty vehicles are tightening certification thresholds that force engine manufacturers to abandon incremental efficiency improvements in favor of zero-emission platform development. Engine suppliers are redirecting research and development budgets from combustion optimization to thermal management systems for electric drivetrains. California's Advanced Clean Trucks mandate is accelerating this transition by requiring zero-emission sales quotas that outpace federal compliance timelines.
Fleet operators are consolidating procurement authority at the corporate level to standardize charging infrastructure specifications and negotiate electricity rate structures with utilities. Regional haul operators are displacing decentralized depot decisions with centralized energy procurement teams that secure time-of-use tariffs and demand response incentives. This concentration is most visible in Germany, where logistics conglomerates are negotiating directly with transmission system operators for dedicated substation capacity at distribution hubs.
Zero Emission Trucks Market Segmentation
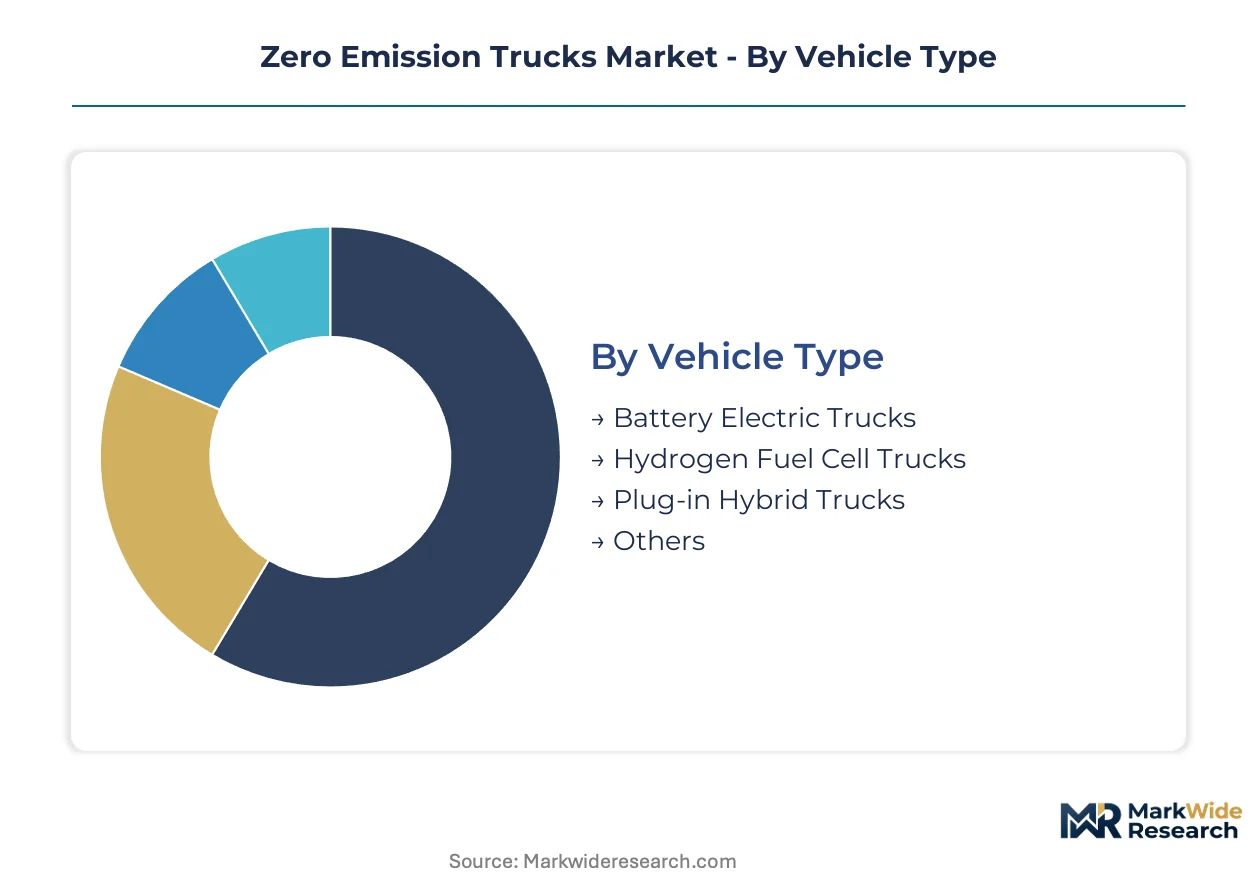
Zero emission truck procurement demands platform-specific service infrastructure, from high-voltage battery diagnostics to hydrogen fueling protocols. Fleet operators select segments based on total cost of ownership models that incorporate energy procurement, maintenance training, and residual value risk across divergent technology pathways.
Vehicle Type:
After-sales service intensity varies dramatically across powertrain architectures, with battery systems requiring thermal management expertise and fuel cell stacks demanding platinum catalyst refurbishment capabilities.
- Battery Electric Trucks:Lithium-ion cell packs exceeding 200 kWh capacity power these vehicles through megawatt charging infrastructure. Logistics operators in Germany and California are consolidating procurement around this segment to leverage falling cell costs and expanding depot charging networks.
- Hydrogen Fuel Cell Trucks:Proton exchange membrane stacks convert pressurized hydrogen into electricity for extended-range duty cycles. Demand concentrates in subsidized corridor pilots across the Netherlands and France where hydrogen supply contracts anchor fleet economics.
- Plug-in Hybrid Trucks:Dual-powertrain configurations bridge diesel dependency and full electrification for operators with unpredictable route profiles.
- Others:Emerging architectures include range-extended electric and catenary-connected systems for fixed-route applications.
Battery Electric Trucks holds the largest share; momentum sits with Hydrogen Fuel Cell Trucks in premium long-haul corridors.
End User:
Cost tier differentiation separates enterprise fleet operators with centralized procurement authority from fragmented owner-operator segments with limited capital access.
- Logistics Companies:Integrated freight operators with dedicated energy procurement teams negotiate time-of-use tariffs and demand response incentives. These entities in Germany are securing direct grid interconnection for megawatt charging hubs.
- Delivery Services:Last-mile operators with predictable urban routes achieve fastest payback periods through overnight depot charging and municipal preferential access programs.
- Public Transportation:Municipal bus fleets with centralized maintenance facilities convert diesel depots to electric infrastructure using federal subsidy programs.
- Waste Management:Stop-start duty cycles with regenerative braking opportunities suit battery electric platforms for urban collection routes.
Logistics Companies dominates current procurement volume; Delivery Services represents the steepest expansion trajectory as e-commerce fulfillment accelerates.
Technology:
Margin concentration shifts toward software-defined energy optimization as hardware commoditization compresses cell and stack pricing.
- Battery Technology:Lithium iron phosphate chemistry and cell-to-pack architectures reduce costs for regional haul applications. CATL and BYD are expanding production capacity to serve European commercial vehicle demand.
- Fuel Cell Technology:Platinum group metal loading in membrane electrode assemblies sustains premium stack pricing that limits deployment scale.
- Energy Management Systems:Predictive range analytics and vehicle-to-grid integration software create recurring revenue streams for platform providers.
- Autonomous Systems:Hub-to-hub highway automation maximizes electric drivetrain efficiency on fixed distribution center routes.
Battery Technology captures the dominant revenue share; Energy Management Systems is climbing the fastest as fleet operators prioritize operational optimization software.
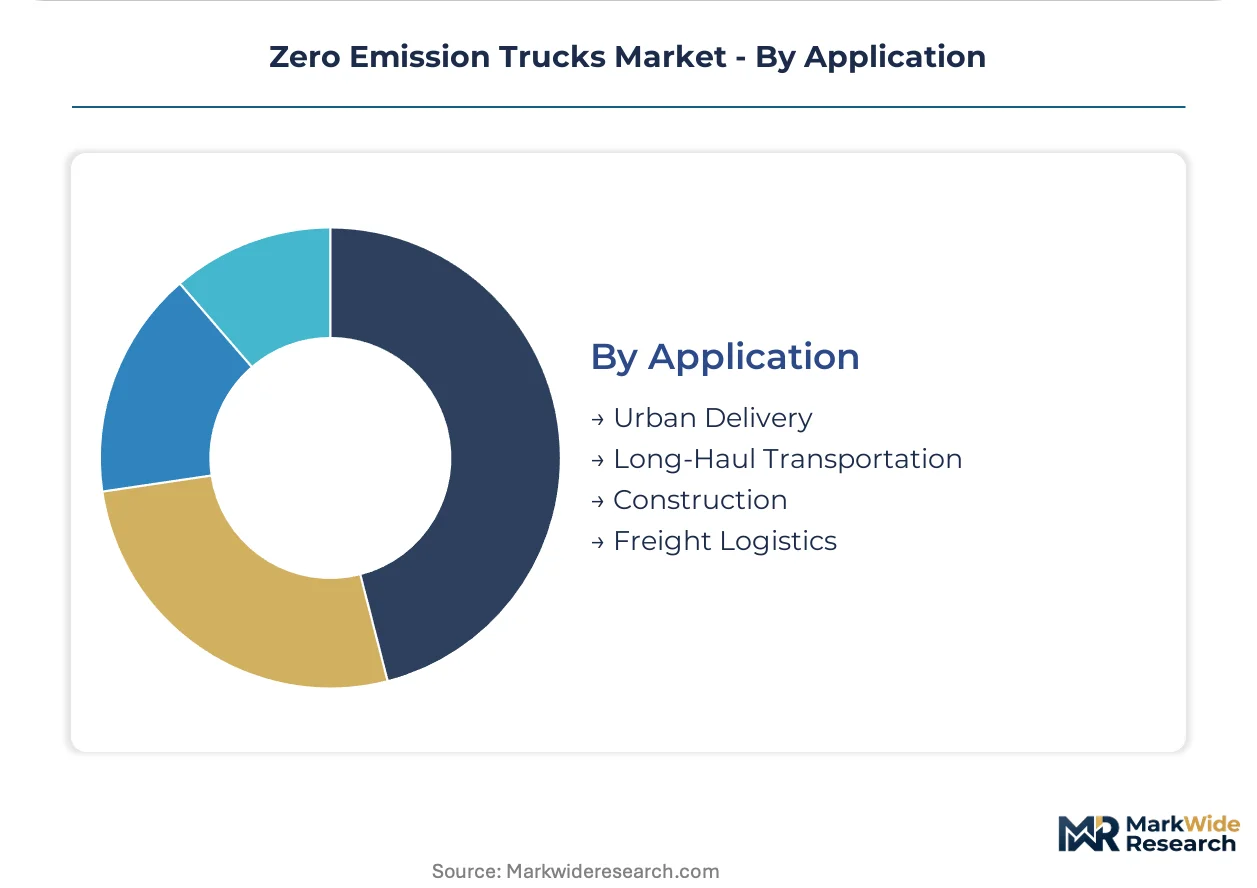
Application:
Geographic deployment patterns follow regulatory stringency, with urban access restrictions accelerating conversion in municipal centers ahead of intercorridor mandates.
- Urban Delivery:Zero-emission zones in Amsterdam, Paris, and London force last-mile electrification for compliance. Depot-based charging infrastructure supports predictable return-to-base operations with minimal range anxiety.
- Long-Haul Transportation:Extended-range duty cycles exceeding 500 miles strain battery energy density, sustaining hydrogen fuel cell viability in transcontinental corridors.
- Construction:Heavy-duty vocational applications with variable load profiles require ruggedized battery enclosures and regenerative braking for downhill material transport.
- Freight Logistics:Intermodal drayage and regional distribution center shuttles balance payload capacity with charging opportunity windows.
Urban Delivery holds the largest share; Long-Haul Transportation is gaining share fastest as megawatt charging networks and solid-state battery prototypes compress range differentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of zero emission trucks concentrate in manufacturing hubs with integrated battery supply chains, while import demand clusters in jurisdictions with stringent diesel phase-out mandates. Germany and China run structural surpluses in heavy-duty electric platforms. The United States, Netherlands, and Japan represent net import markets dependent on foreign cell and stack supply.
United States
Fleet operators in California face binding zero-emission sales quotas under the Advanced Clean Trucks regulation. The EPA's greenhouse gas standards for heavy-duty vehicles compress product planning timelines for manufacturers. Los Angeles and Long Beach ports anchor the nation's largest electric drayage conversion, with logistics operators securing megawatt charging infrastructure through direct utility partnerships.
Germany
Federal purchase incentives and charging infrastructure grants subsidize commercial fleet conversion at scale. The EU Green Deal's CO2 performance standards, enforced by national type-approval authorities, eliminate diesel truck sales by specified phase-out dates. The Rhine-Ruhr logistics corridor hosts concentrated depot electrification projects as conglomerates negotiate dedicated substation capacity with transmission system operators.
China
Domestic battery electric truck deployment dominates urban freight and mining applications through state-backed fleet procurement programs. MIIT certification requirements and GB standards for commercial vehicle electrification shape manufacturer product roadmaps. The Yangtze River Delta manufacturing cluster supplies cell-to-pack architectures for regional haul platforms serving Southeast Asian export markets.
Netherlands
Amsterdam's zero-emission zone and municipal diesel bans force last-mile operator compliance ahead of EU-wide mandates. Subsidized hydrogen corridor pilots across Rotterdam-Antwerp sustain fuel cell truck demand for extended-range duty cycles. The Randstad logistics hub concentrates depot charging infrastructure investment from integrated freight operators with centralized energy procurement authority.
Japan
METI procurement guidelines and national hydrogen supply chain investments sustain fuel cell truck pilot programs for intercity corridors. JIS standards for high-pressure hydrogen tank certification create technical barriers for foreign platform entry. The Kanto region around Tokyo hosts demonstration projects for autonomous hub-to-hub electric freight operations on fixed distribution center routes.
Zero Emission Trucks Market Competitive Landscape
On the supply side, the industry is consolidating around integrated energy system providers with captive battery or fuel cell manufacturing. Tiered competitive positioning separates vertically integrated conglomerates from specialized platform assemblers dependent on outsourced powertrain supply. Two strategic archetypes dominate: full-stack manufacturers controlling cell chemistry and thermal management, and modular integrators sourcing standardized packs and stacks from third-party suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing dedicated cell supply through offtake agreements and joint venture structures.
Within the integrated manufacturer tier, Tesla Inc. and BYD Company Limited exemplify contrasting approaches to cell format and chemistry selection, while Daimler Truck occupies a diversified position spanning multiple energy architectures. These three anchors represent the spectrum from proprietary vertical integration to multi-platform portfolio breadth, with each archetype carrying distinct capital intensity and operational flexibility profiles. Specialists in regional haul battery electric platforms and hydrogen fuel cell corridor pilots populate the mid-tier, competing on application-specific service infrastructure and fleet energy management software capabilities.
| Leading Market Players |
|---|
| Tesla Inc. |
| BYD Company Limited |
| Daimler Truck |
| Volvo Group |
| Nikola Corporation |
| Navistar International |
| Xos Trucks |
| Rivian Automotive Inc. |
| Iveco Group |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Ruhr corridor's fleet conversion economics compress battery pack procurement costs while amplifying price spreads between premium long-haul platforms and standard urban delivery configurations, as supply concentration in cathode materials and cell manufacturing grants pricing power to integrated producers serving divergent buyer segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stabilize input costs for high-volume fleet operators. Price differentiation rests on certification grade and volume scale, with EU type-approval tiers commanding premiums over baseline configurations. Pricing pressure stems from lithium iron phosphate cost compression in regional haul segments. Delivery services exhibit highest price sensitivity due to thin margins, while logistics conglomerates with centralized procurement demonstrate lowest sensitivity through direct utility negotiations.
Supply Chain Analysis
Upstream feedstock concentration in the Democratic Republic of Congo for cobalt, Indonesia for nickel processing, and China for cathode active material production creates structural dependencies for cell manufacturers. Raw material inputs draw from lithium carbonate, graphite anodes, and electrolyte solvents. Single-source vulnerability in refined cobalt sulfate exposes supply chains to export restriction risk. Distribution runs through captive cell-to-pack facilities at OEM assembly plants, with aftermarket service parts flowing through authorized high-voltage technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero emission truck procurement is reconstituting as a service-attach opportunity, with energy management software and vehicle-to-grid integration contracts expanding faster than hardware sales as fleet operators prioritize operational optimization over capital acquisition.
For Market Incumbents: Harden defensive positions by deepening in-house production of lithium iron phosphate cells to neutralize BYD's cost leadership in regional haul segments. Secure dedicated substation capacity at German distribution hubs before grid interconnection queues extend commissioning timelines. Invest in 800-volt thermal management certification to offset high-voltage technician scarcity threatening aftermarket service margins.
For New Entrants and Emerging Players: Establish a beachhead in autonomous hub-to-hub corridor pilots, where fixed-route electrification demands specialized energy procurement software absent from incumbent portfolios. Target Netherlands hydrogen fuel cell pilots as the most penetrable geography, leveraging subsidized Rotterdam-Antwerp infrastructure. Deploy fleet energy management platforms as the primary go-to-market angle, anchoring recurring revenue before hardware scale.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates spinning off commercial vehicle electrification divisions to focus on passenger car platforms. Long-term viability centers on software-defined energy optimization capabilities rather than cell chemistry manufacturing scale. Watch solid-state battery validation milestones as the critical inflection signal for hydrogen fuel cell obsolescence risk in extended-range segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | CATL and BYD offtake contracts secure cathode supply for European assembly plants facing MIIT export constraints. |
| Megawatt Charging Partnership | Direct utility substation investments bypass grid interconnection delays threatening California fleet deployment timelines. |
| Energy Management Platform Launch | Predictive range analytics from Tesla and Rivian create recurring revenue streams beyond vehicle hardware margins. |
| Hydrogen Corridor Joint Venture | Rotterdam-Antwerp infrastructure pilots sustain fuel cell viability while solid-state batteries mature for long-haul displacement. |
| High-Voltage Technician Certification Program | Daimler Truck training networks address maintenance scarcity inflating residual value risk for lessor portfolios. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and vehicle production databases. Primary interviews engaged fleet procurement directors, OEM platform engineers, charging infrastructure developers, and utility interconnection planners. Secondary validation drew from EPA certification records, EU type-approval databases, and MIIT production statistics. Bottom-up cell demand modeling and top-down fleet conversion trajectories were cross-referenced to anchor volume assumptions.
Forecast inputs span propulsion architecture, vehicle class, duty cycle intensity, and regional regulatory cluster across the analysis window. Segmentation dimensions modeled include battery chemistry pathway, energy management system integration depth, and charging topology preference. CAGRs were derived from installed base turnover rates and fleet procurement pipeline visibility. Industry-specific inputs incorporate electricity rate structure evolution and hydrogen supply contract pricing formation.
Stress conditions across lithium carbonate price volatility, cobalt export restriction scenarios, and megawatt charging deployment delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cell cost curves and regulatory phase-out adherence. Cross-checking against IEA heavy-duty vehicle electrification benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Hydrogen Powered Transport Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Fuel Cell System Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Automotive Biofuel Market
Alternative Fuel Vehicles
Air Powered Vehicle Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market