
 Flex-Fuel Vehicle Market | 2026-2036
Flex-Fuel Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Flex-Fuel Vehicle Market Foresight
The flex-fuel vehicle market is consolidating around a widening split between premium powertrain configurations and commodity fleet-grade offerings. Toyota Motor Corporation leverages its hybrid-flex integration expertise to dominate higher-margin segments where electrified ethanol systems command pricing power. Ford Motor Company sustains its North American fleet channel through heavy-duty F-Series flex-fuel variants purpose-built for commercial ethanol contracts. Stellantis NV competes aggressively on volume in Latin America, where its Fiat brand anchors the entry-level passenger car tier with simplified E100-compatible engines.
Flex-fuel vehicles are internal combustion engine automobiles engineered to operate on variable blends of gasoline and alcohol-based fuels, typically employing modified fuel injection systems, corrosion-resistant seals, and ethanol-calibrated engine control units that adjust ignition timing based on real-time fuel composition sensing. Their primary purpose is to reduce petroleum dependency while utilizing domestically produced biofuels within existing refueling infrastructure. The fuel type dimension shows ethanol configurations leading absolute volume while biodiesel blends for heavy-duty applications represent the fastest-expanding margin pool. Vehicle type segmentation reveals light commercial vehicles as the mature revenue base, whereas government fleet procurement of flex-fuel buses is accelerating in jurisdictions with biofuel mandates.
The US EPA administers Renewable Fuel Standard compliance pathways that effectively mandate flex-fuel production volumes for domestic automakers, while Brazil's ANP enforces RenovaBio carbon intensity targets that tighten annually and directly shape ethanol-blending requirements. The EU F-Gas Regulation and REACH chemical standards indirectly constrain alternative fuel system material choices, creating compliance cost differentials across export markets. Stakeholders must monitor how evolving lifecycle carbon accounting rules from EPA and EU frameworks redefine which flex-fuel configurations qualify for preferential treatment under emerging clean fuel standards.
Market Dynamics
The flex-fuel vehicle market is experiencing structural pressure from Brazil's RenovaBio carbon intensity mandates, which force automakers to recalibrate engine management systems for higher ethanol blend ratios without hardware overhauls.
Growth Catalysts
- RenovaBio Compliance Pathways:Brazil's ANP-enforced carbon intensity targets tighten annually, compelling fleet operators to expand ethanol-capable vehicle procurement.
- Engine Management Software Upgrades:Real-time fuel composition sensing now enables broader gasoline-ethanol blending flexibility through calibration updates alone.
- US Renewable Fuel Standard:EPA-administered compliance pathways effectively mandate flex-fuel production volumes for domestic automakers.
Market Restraints
- Corrosion-Resistant Material Costs:Ethanol-compatible seals and fuel injection components require specialized alloys and polymers that inflate bill-of-materials costs versus conventional gasoline systems.
- Retail Infrastructure Gaps:E85 pump availability remains concentrated in the US Corn Belt and Brazilian urban corridors, limiting addressable geography.
- Battery Electric Substitution:Zero-emission vehicle mandates in California and the EU's CO2 fleet standards redirect R&D investment away from combustion-based alternatives.
Strategic Opportunities
- Heavy-Duty Biodiesel Applications:Government fleet procurement of flex-fuel buses is accelerating in jurisdictions with biofuel mandates, opening a margin pool distinct from passenger vehicles.
- Swedish E85 Infrastructure:National biofuel programs and established retail networks create a tested template for Nordic expansion.
- Hybrid-Flex Convergence:Electrified ethanol systems that combine hybrid powertrains with flex-fuel capability command pricing power in premium segments.
Industry Challenges
- Lifecycle Carbon Accounting Expertise:Emerging clean fuel standards from EPA and EU frameworks require specialized compliance teams to document fuel pathway emissions.
- REACH Chemical Compliance:EU F-Gas Regulation and REACH standards constrain alternative fuel system material choices, forcing reformulation of seals and coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flex-Fuel Vehicle Market |
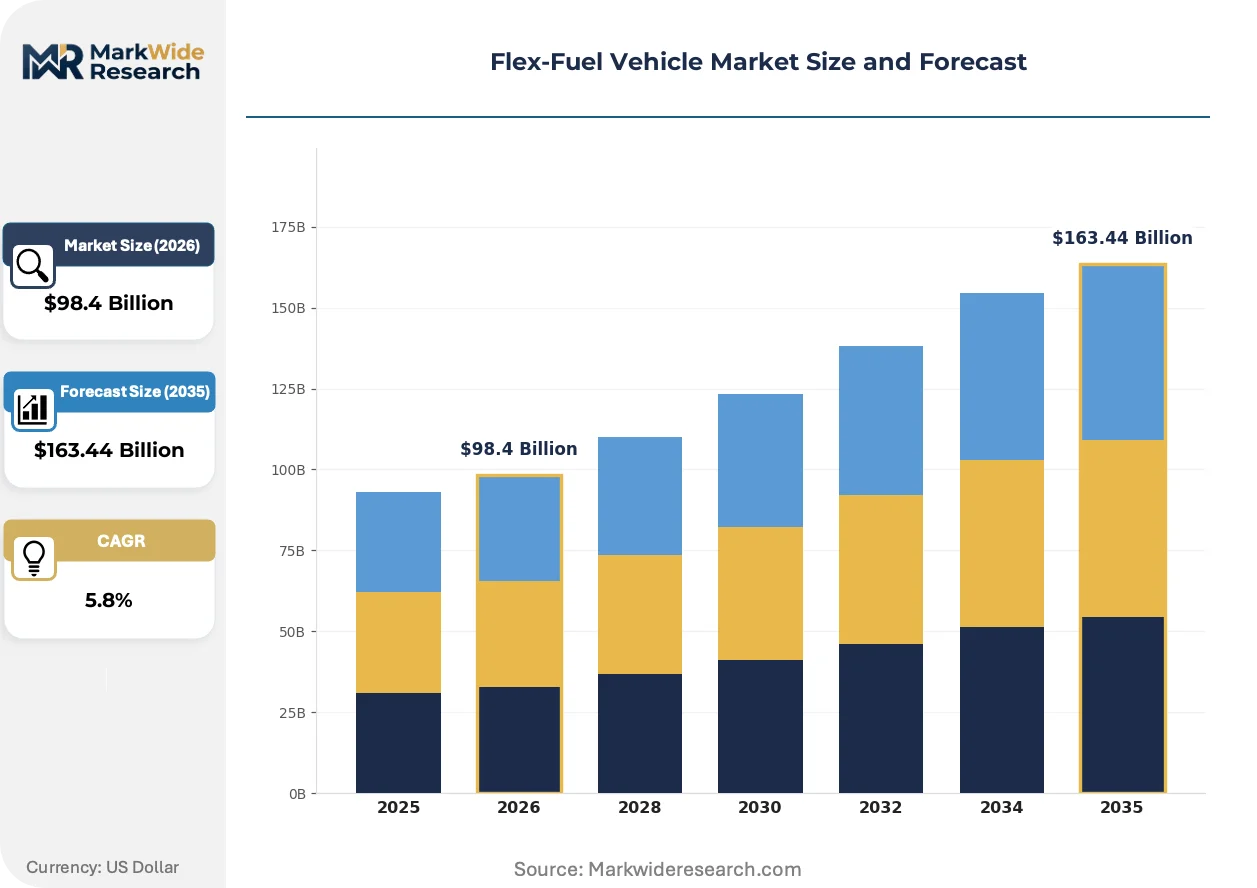
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $163.44 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Ethanol, Methanol, Gasoline, Biodiesel, Compressed Natural Gas Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy-Duty Trucks, SUVs, Buses Technology: Flexible Fuel Injection, Multi-Port Fuel Injection, Direct Injection, Turbocharged Engines, Hybrid Systems End User: Individual Consumers, Government Fleets, Car Rental Services, Corporate Fleets, Taxi Operators |
| Companies Covered | General Motors, Ford Motor Company, Toyota Motor Corporation, Honda Motor Company, Stellantis NV, Volkswagen AG, Nissan Motor Company, BMW Group, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flex-Fuel Vehicle Market Shifts & Advancements
Flex-fuel technology trajectories are diverging between software-defined fuel flexibility and hardware-optimized ethanol tolerance, with regulatory carbon accounting emerging as the decisive design constraint.
Real-time fuel composition sensors paired with adaptive engine control units are consolidating control architecture across flex-fuel powertrains. Fleet operators in Brazil and the US Midwest are adopting these systems to minimize hardware variants while satisfying RenovaBio and Renewable Fuel Standard obligations. This sensor-software integration is consolidating supplier tiers as engine management becomes a software-differentiated capability rather than a mechanical specification.
EPA's evolving lifecycle carbon accounting methodology for renewable fuels is reshaping qualification criteria for preferential treatment under clean fuel standards. Domestic automakers must now document fuel pathway emissions from feedstock cultivation through combustion, altering powertrain development priorities. Light commercial vehicle segments face the steepest compliance cost escalation as they lack the scale to amortize certification overhead.
Commercial buyers are unbundling after-sales service from vehicle procurement, pressuring OEMs to offer ethanol-system maintenance as a separate subscription. Fleet management companies in São Paulo and Chicago are negotiating predictive maintenance contracts tied to fuel quality monitoring data. This service unbundling is most visible in municipal bus procurement, where total-cost-of-ownership calculations now weight ethanol-system uptime guarantees more heavily than initial capital outlay.
Flex-Fuel Vehicle Market Segmentation
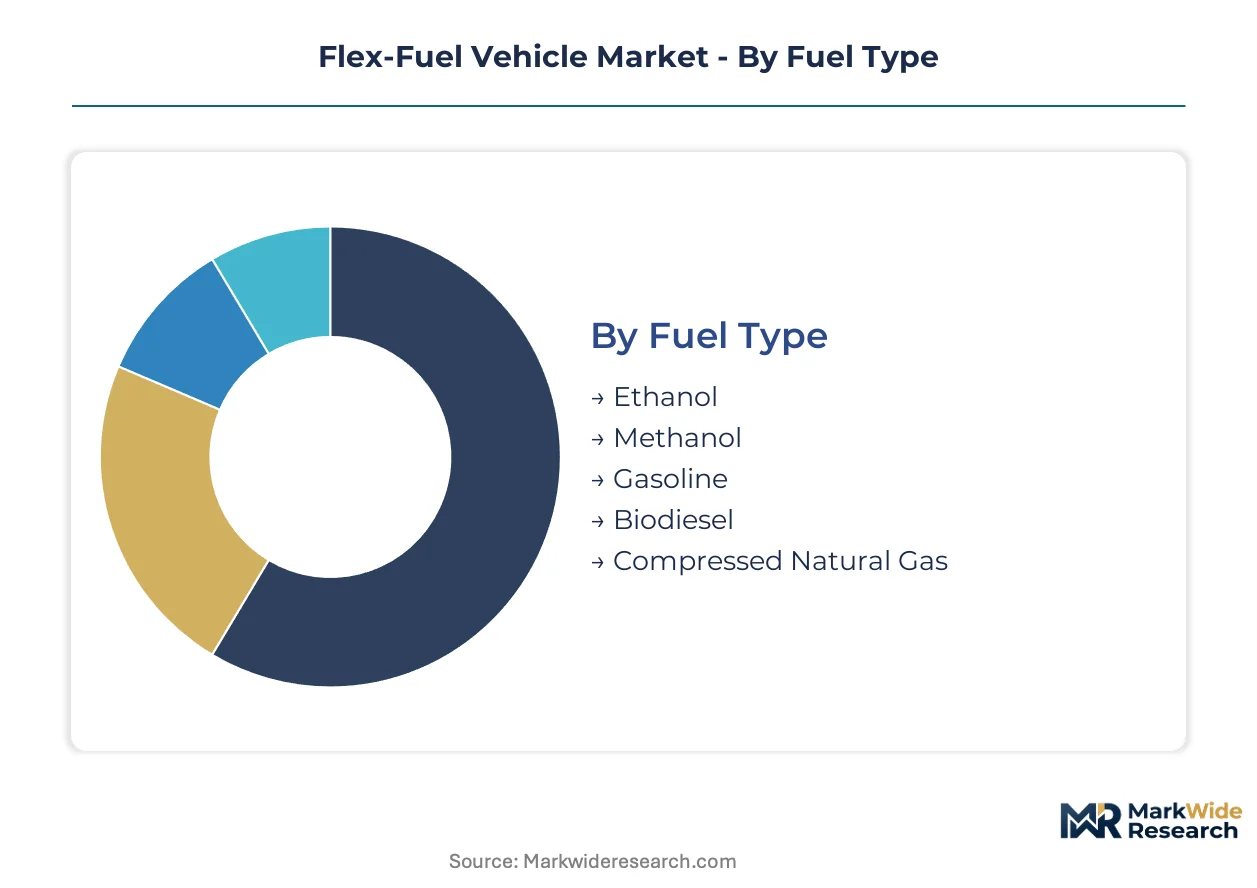
Flex-fuel vehicle segmentation reveals how powertrain configurations align with distinct fuel infrastructure realities and procurement economics. Each dimension carries divergent margin profiles and compliance burdens that shape manufacturer portfolio decisions.
Fuel Type:
Standardization dominates ethanol and gasoline configurations, while biodiesel and methanol systems require bespoke engineering for narrower addressable markets.
- Ethanol:E85-compatible powertrains employ corrosion-resistant seals and ethanol-calibrated engine control units that adjust ignition timing based on real-time fuel composition sensing. Demand concentrates in Brazil under ANP-enforced RenovaBio mandates, where fleet operators expand procurement of E100-capable vehicles to meet tightening carbon intensity targets.
- Biodiesel:Heavy-duty applications utilize B20-B100 blends with modified fuel injection systems and specialized elastomer seals resistant to fatty acid methyl ester degradation. Municipal bus fleets in São Paulo and Chicago are accelerating procurement under biofuel procurement mandates, creating a margin pool distinct from passenger vehicles.
- Methanol:M85 configurations require upgraded fuel system materials and larger fuel injectors to accommodate methanol's lower energy density.
- Gasoline:Baseline E10-E15 compatibility represents the standardized default for conventional powertrains without incremental hardware costs.
- Compressed Natural Gas:Bi-fuel CNG-gasoline systems require high-pressure fuel storage and dedicated injection hardware for fleet operators with captive refueling infrastructure.
Leading the category by volume: Ethanol. Growing fastest: Biodiesel.
Vehicle Type:
Passenger vehicles anchor production scale, while commercial segments concentrate procurement decisions among fleet managers with total-cost-of-ownership discipline.
- Passenger Cars:Compact and mid-size sedans with simplified E100-compatible engines dominate Brazilian volume production. Fiat-branded entry-level models from Stellantis NV anchor this tier with cost-optimized fuel system architectures.
- Light Commercial Vehicles:Mature revenue base encompassing delivery vans and small trucks with flexible fuel injection systems calibrated for variable ethanol blends. US Midwest fleet operators favor these configurations for Renewable Fuel Standard compliance.
- Heavy-Duty Trucks:Biodiesel-optimized powertrains with multi-port fuel injection and reinforced fuel system components for high-blend operation.
- SUVs:Larger displacement engines with adaptive control units managing ethanol-gasoline transitions across temperature ranges.
- Buses:Government fleet procurement is accelerating in jurisdictions with biofuel mandates, with predictive maintenance contracts now standard in municipal tenders.
Passenger cars command absolute unit volume. Buses are climbing the fastest on policy-driven fleet replacement cycles.
Technology:
Software-defined flexibility is displacing hardware differentiation as engine management becomes a calibration rather than mechanical specification.
- Flexible Fuel Injection:Real-time fuel composition sensors paired with adaptive engine control units enable broader gasoline-ethanol blending ratios through software updates alone. This architecture is consolidating supplier tiers as calibration expertise replaces hardware variation.
- Hybrid Systems:Electrified ethanol powertrains combine hybrid architectures with flex-fuel capability, commanding pricing power in premium segments where Toyota Motor Corporation dominates through hybrid-flex integration expertise.
- Multi-Port Fuel Injection:Conventional port-injected architectures with ethanol-compatible injector materials and revised fuel rail specifications.
- Direct Injection:High-pressure ethanol-tolerant injectors with revised combustion chamber cooling strategies for knock suppression.
- Turbocharged Engines:Forced induction with ethanol-optimized boost control and intercooling for higher-octane fuel exploitation.
Flexible fuel injection leads technology deployment by installed base. Hybrid systems are gaining share fastest on electrification convergence.
End User:
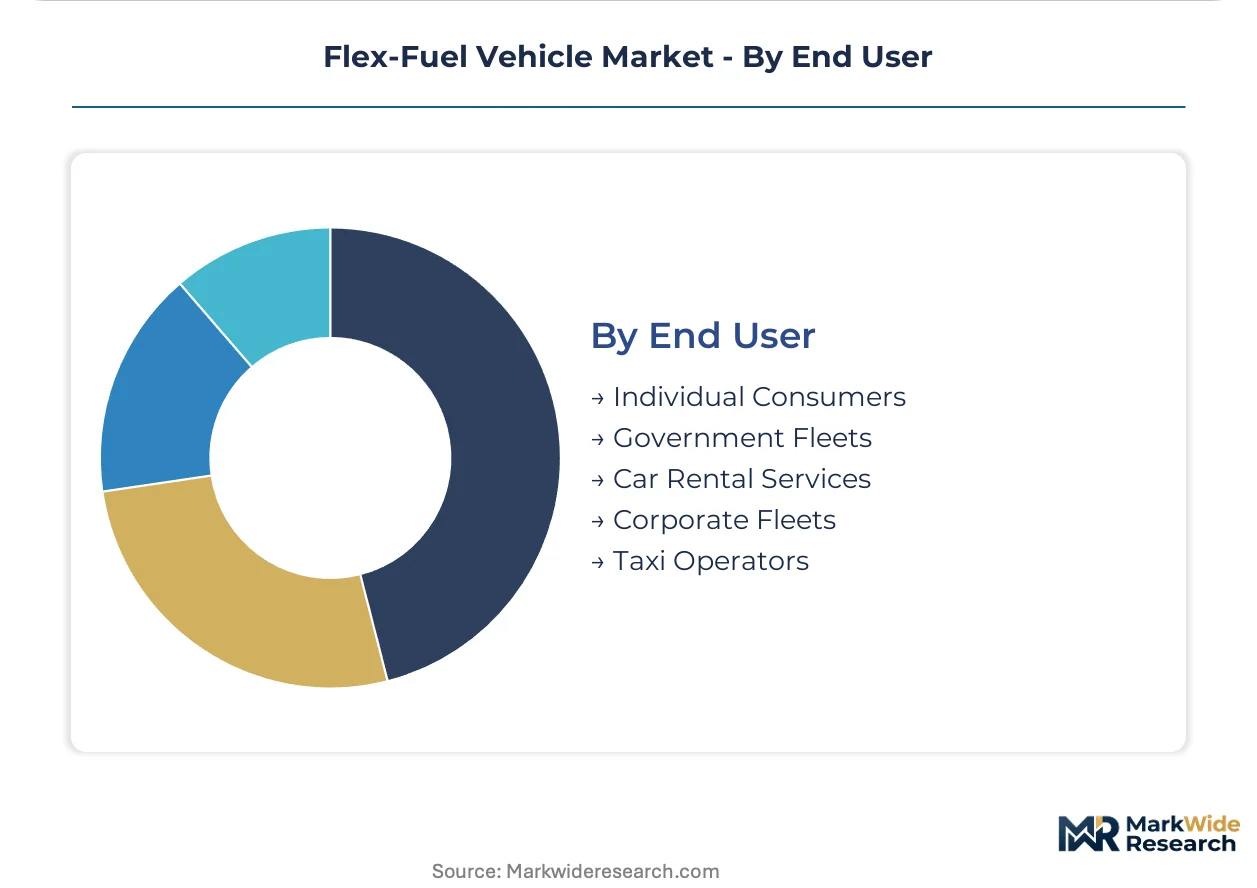
Procurement authority concentrates in fleet managers with fuel contract leverage, while individual consumers respond to pump price arbitrage.
- Government Fleets:Municipal and state procurement departments with biofuel procurement mandates and total-cost-of-ownership calculation frameworks. Brazilian federal fleet standards and US state renewable fuel requirements direct volume toward certified flex-fuel configurations.
- Corporate Fleets:Large employers with centralized fuel management and sustainability reporting obligations under CSRD and similar frameworks.
- Individual Consumers:Price-sensitive buyers responding to ethanol-gasoline pump price spreads, concentrated in Brazil and US Corn Belt corridors with E85 infrastructure density.
- Car Rental Services:Fleet standardization pressures favor gasoline-default vehicles with E85 compatibility as residual value protection.
- Taxi Operators:High-utilization drivers in São Paulo and Stockholm where E85 price advantages compound across mileage intensity.
Government fleets anchor procurement volume. Corporate fleets are expanding most quickly on sustainability reporting integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors flex-fuel vehicle deployment through its dense E85 retail network and municipal fleet procurement programs. The metropolitan corridor concentrates Brazil's ethanol distribution infrastructure and serves as the testing ground for next-generation engine management calibrations.
United States
Midwest fleet operators in Iowa and Illinois expand flex-fuel procurement under EPA Renewable Fuel Standard compliance pathways. The Corn Belt corridor maintains the densest E85 pump availability outside Brazil. Detroit-based automakers calibrate powertrains specifically for regional ethanol blending requirements.
Brazil
Federal fleet standards and ANP-enforced RenovaBio mandates drive ethanol-capable vehicle orders from São Paulo to Brasília. The Southeast industrial corridor houses engine management software development centers. Fiat-branded entry-level production concentrates in Betim for domestic and regional export markets.
Sweden
Stockholm's municipal procurement frameworks prioritize E85-compatible vehicles under national biofuel program targets. The Nordic retail infrastructure provides a tested template for neighboring markets. Scania and Volvo Group anchor heavy-duty flex-fuel development in Södertälje and Gothenburg.
Germany
Bavarian automotive suppliers develop ethanol-tolerant fuel injection components under EU F-Gas Regulation material constraints. Munich-based engineering centers focus on hybrid-flex convergence architectures. The country's central European position shapes REACH-compliant seal formulations for export markets.
Canada
Prairie province fleet operators in Manitoba and Saskatchewan pilot biodiesel-flex configurations for agricultural applications. Federal clean fuel regulations create procurement incentives for ethanol-capable light commercial vehicles. Ontario's manufacturing corridor supplies corrosion-resistant fuel system components to US and Brazilian assemblers.
Flex-Fuel Vehicle Market Competitive Landscape
Premium-margin players sit above commodity-margin players across hybrid-flex integration and fleet-grade ethanol capability. The market consolidates around three strategic tiers: electrified ethanol system specialists, volume producers of simplified E100-compatible engines, and heavy-duty biodiesel powertrain fabricators. Consolidation pressures intensify as software-defined fuel flexibility reduces hardware differentiation. Dominant competitive moves include backward integration into fuel system component production and technology licensing agreements for adaptive engine control calibrations.
Among Detroit-based automakers, Ford Motor Company and General Motors occupy positions across fleet-grade and consumer flex-fuel segments. Toyota Motor Corporation anchors the premium-tier hybrid-flex convergence space. Stellantis NV exemplifies volume-focused ethanol capability through its Latin American passenger car operations. These three archetypes represent divergent responses to regulatory carbon accounting requirements and infrastructure-driven demand concentration.
| Leading Market Players |
|---|
| General Motors |
| Ford Motor Company |
| Toyota Motor Corporation |
| Honda Motor Company |
| Stellantis NV |
| Volkswagen AG |
| Nissan Motor Company |
| BMW Group |
| Hyundai Motor Company |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap component specialists in Brazil and Germany anchor corrosion-resistant seal and fuel injection manufacturing, translating concentrated technical expertise into pricing discipline across ethanol-compatible powertrain tiers.
Pricing Analysis
Value-based pricing anchored to fleet uptime guarantees and RenovaBio compliance outcomes separates government procurement contracts from commodity passenger vehicle sales. Three-tier pricing structure across premium hybrid-flex systems, standard flexible fuel injection architectures, and economy-grade E100-compatible engines reflects certification burden and after-sales bundling intensity. Pricing pressure stems from battery electric substitution redirecting R&D budgets away from combustion calibration teams. Corporate fleet managers exhibit lowest price sensitivity due to sustainability reporting obligations, while individual consumers in Brazil respond aggressively to pump price spreads.
Supply Chain Analysis
Regional distribution centers in São Paulo, Detroit, and Stuttgart coordinate hub-and-spoke patterns for ethanol-tolerant fuel system components. Manufacturing concentrates in Brazil, Germany, and the United States for engine control units, corrosion-resistant polymers, and adaptive sensor modules. Raw material dependencies include specialized elastomer formulations, ethanol-compatible alloys, and semiconductor chips for real-time composition sensing. Single-source vulnerability in ethanol-calibrated engine management software creates chokepoint exposure. Distribution runs through captive OEM supply networks and Tier 1 automotive supplier channels with direct fleet integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA lifecycle carbon accounting and ANP RenovaBio mandates erect barrier-to-entry moats favoring incumbents with documented fuel pathway expertise.
For Market Incumbents: To counter battery electric substitution draining engineering talent pools, deepen backward integration into ethanol-tolerant semiconductor sourcing and expand predictive maintenance subscription attach rates. Capacity addition in São Paulo's industrial corridor secures proximity to ANP regulatory evolution and Brazilian federal fleet procurement.
For New Entrants and Emerging Players: Municipal bus fleet operators with biofuel mandates represent the most penetrable channel partner type for specialized biodiesel powertrain integration. White-space targets include heavy-duty flex-fuel applications in Nordic markets and aftermarket engine management software retrofits for legacy fleet vehicles. Go-to-market execution should prioritize predictive maintenance contracts tied to fuel quality monitoring data.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid-flex integration specialists with EPA certification documentation in the US Midwest manufacturing belt. Long-term viability hinges on regulatory durability of carbon intensity accounting frameworks across multiple electoral cycles. Watch for EPA methodology revisions on renewable fuel lifecycle emissions as the inflection signal for powertrain development priority shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fuel System Components | Captive supply of corrosion-resistant seals insulates margin from polymer price volatility under REACH constraints. |
| Software-Defined Fuel Flexibility Investment | Real-time calibration updates reduce hardware variant proliferation across Brazilian and US fleet channels. |
| Hybrid-Flex Convergence Platform | Electrified ethanol architectures command pricing power in premium segments where Toyota dominates integration. |
| Predictive Maintenance Subscription Launch | Fuel quality monitoring data contracts lock in municipal bus fleet relationships beyond initial vehicle procurement. |
| Geographic Manufacturing Footprint Expansion | São Paulo and Stuttgart production clusters align with ANP and EU F-Gas regulatory evolution trajectories. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across OEM platform engineers, Tier 1 supplier procurement leads, fleet management operators, and ANP compliance officers. Secondary sources included EPA Renewable Fuel Standard dockets, ANP RenovaBio carbon intensity reports, EU REACH substance restriction updates, and vehicle production registration databases. Bottom-up segment modeling and top-down macroeconomic triangulation validated volume and value estimates.
Granularity-level modeling deployed vehicle class, propulsion architecture, and regional production cluster dimensions at the country level, with fuel type and technology tiers analyzed at the sub-regional cluster level. CAGRs were derived from regression analysis against policy mandate trajectories and fleet replacement cycle assumptions across the projection horizon. Industry-specific forecast inputs incorporated RenovaBio carbon intensity target tightening schedules and EPA lifecycle methodology revision probabilities.
Caveats apply where battery electric vehicle mandate acceleration or biofuel subsidy elimination could materially shift the outlook for combustion-based alternatives. Forecasts reflect assumptions on regulatory durability and feedstock price stability that warrant periodic reassessment. Periodic stress-testing of base assumptions against ANP enforcement patterns and EU clean fuel standard evolution is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
India CNG Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Automotive Flex Fuel Engine Market
Alternative Fuel Vehicles
Automotive Low Emission Vehicle Market
Alternative Fuel Vehicles
Automotive Alternative Fuel Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel and Hybrid Vehicle Market
Alternative Fuel Vehicles
Global Low Emission Vehicle Market
Alternative Fuel Vehicles
Zero Emission Trucks Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
Automotive Natural Gas Vehicle Market
Alternative Fuel Vehicles
South America CNG and LPG Vehicle Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Global Ethanol-Based Vehicle Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
Global CNG and LPG Vehicle Market