
 Global Load Monitoring System (LMS) Market | 2026-2036
Global Load Monitoring System (LMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Load Monitoring System (LMS) Market Intelligence
Aftermarket service revenue is tilting toward predictive calibration and remote diagnostics as hardware margins compress across the installed base. Vishay Precision Group leverages its strain gauge heritage to sustain premium positioning in aerospace and medical weighing applications. Flintec anchors European demand through its load cell manufacturing footprint in Sweden and the UK. Spectris competes on software-layer integration, bundling LMS data into broader asset performance management suites for industrial clients.
A load monitoring system measures mechanical force, weight, or tension using transducers that convert physical strain into electrical signals, typically achieving accuracy within fractions of a percent across calibrated ranges. These systems prevent structural overload, optimize material handling efficiency, and enable regulatory compliance in lifting and transport operations. Wireless sensors lead product type adoption where cable routing proves impractical on mobile cranes and offshore platforms, while strain gauge sensors dominate in permanent industrial installations requiring drift stability over decades. IoT-enabled technology commands expanding share as fleet operators demand cloud-connected load histories for insurance and liability documentation.
FAA crane safety bulletins, OSHA hoist inspection standards, and EU Machinery Directive conformity requirements collectively mandate documented load testing and traceable calibration records across commercial lifting operations. ECHA substance restrictions on cadmium-plated components further steer sensor material selection toward stainless steel and aluminum alloy constructions. Stakeholders must weigh the capital cost of full IoT retrofits against the operational risk of remaining on wired, non-connected legacy architectures as enforcement digitizes.
Market Dynamics
Wireless sensor networks are compressing replacement cycles for wired load monitoring architectures as port operators and offshore contractors prioritize cable-free deployments in hazardous lifting environments.
Growth Catalysts
- EU Machinery Directive conformity mandates:Commercial crane operators across Germany, France, and Italy must maintain documented load testing records, forcing sensor retrofits on aging fleet equipment.
- East Asian manufacturing corridor expansion:IoT-enabled predictive maintenance protocols in South Korea and Japan are displacing scheduled inspection cycles with continuous strain monitoring.
- Offshore platform electrification:Floating production facilities in the North Sea and Gulf of Mexico require explosion-proof wireless load cells for subsea lifting operations.
Market Restraints
- Strain gauge supply concentration:Precision foil and semiconductor strain gauge production clusters in Germany and Japan create input vulnerability for mid-tier system integrators.
- ECHA substance restrictions:Cadmium plating bans on sensor housings force stainless steel and aluminum alloy substitutions, elevating raw material costs for corrosion-resistant designs.
- Calibration infrastructure gaps:Remote mining sites and frontier port terminals lack accredited calibration laboratories, extending traceability compliance timelines.
Strategic Opportunities
- India port modernization:Jawaharlal Nehru Port Trust and Mundra Port expansion projects under the Sagarmala initiative create first-install demand for integrated load monitoring systems.
- Telematics convergence:Fleet management platforms from construction equipment OEMs are integrating third-party LMS data streams, opening API licensing revenue for sensor vendors.
- Brazil pre-salt logistics:Heavy-lift vessel operators serving Petrobras offshore installations require certified dynamic load monitoring for subsea equipment deployment.
Industry Challenges
- Embedded firmware expertise scarcity:System integrators struggle to recruit engineers capable of bridging mechanical strain measurement with cloud-native data architectures.
- Multi-standard certification complexity:Simultaneous OSHA, EU Machinery Directive, and ISO 4309 compliance for export-oriented crane manufacturers extends product launch timelines.
- Legacy analog integration friction:Brownfield industrial sites with decades-old 4-20mA instrumentation resist full digital retrofits due to control system replacement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Load Monitoring System (LMS) Market |
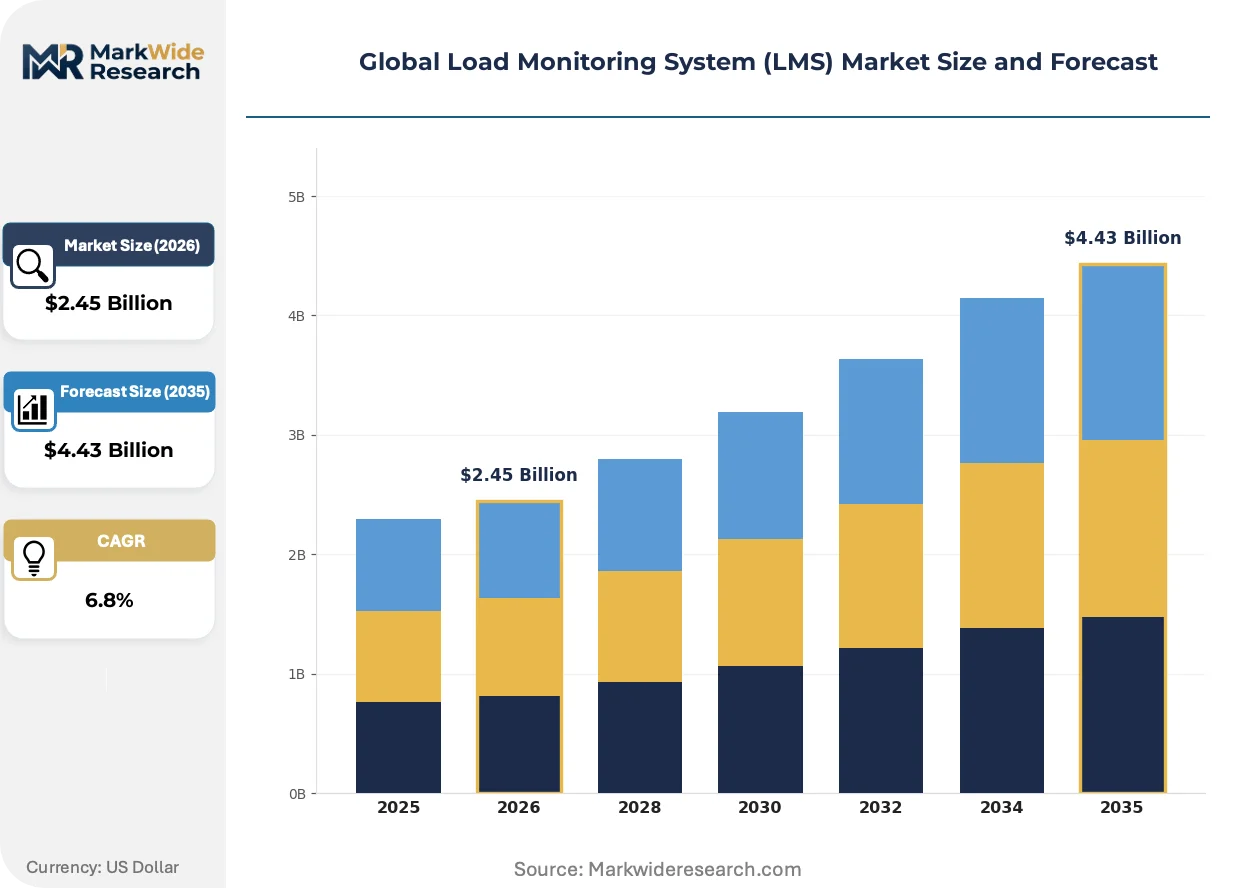
| Market Size in 2026 | $2.45 Billion |
| Market Size in 2035 | $4.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Wired Sensors, Hydraulic Sensors, Strain Gauge Sensors Technology: IoT Enabled, Bluetooth, RFID, Ultrasonic, Optical Application: Cranes, Construction Equipment, Marine Handling, Manufacturing Equipment End User Industry: Heavy Equipment OEMs, Logistic Providers, Port Operators, Infrastructure Maintenance |
| Companies Covered | Vishay Precision Group, Spectris, Flintec, Mettler Toledo, PreciaMolen, LCM Systems, Straightpoint, Mantracourt Electronics, Eilersen Electric Digital Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Load Monitoring System (LMS) Market Strategic Shifts & Innovations
Edge computing architectures are relocating signal processing from centralized controllers to sensor nodes, compressing latency for safety-critical overload detection in autonomous lifting operations.
MEMS-based force transducers are rendering obsolete traditional foil strain gauges in mobile crane applications where vibration tolerance and shock resistance outweigh absolute precision requirements. Rental fleet operators in Australia and the UAE are specifying MEMS sensors for rough-terrain equipment, accepting marginally wider error bands in exchange for reduced calibration frequency and field-replaceable modules. The structural consequence is a bifurcation between premium aerospace/medical segments demanding foil gauge stability and construction/mining segments prioritizing MEMS durability.
OSHA's updated hoist inspection standards are mandating documented load testing at intervals tied to duty cycle intensity rather than calendar time, forcing operators to deploy continuous monitoring or absorb elevated compliance labor costs. The industrial consequence is accelerated adoption of data-logging systems capable of generating audit trails for insurance and liability defense. North American construction contractors and maritime stevedoring firms are most affected, with unionized workforces resisting the shift from manual inspection protocols to automated documentation.
Buyers are unbundling hardware procurement from calibration service contracts, treating sensor systems as capital equipment while sourcing traceability maintenance from third-party metrology laboratories. Industrial distributors in Germany and Japan are responding with marketplace platforms connecting end-users to accredited calibration providers, disintermediating traditional OEM service agreements. This pattern is most visible in automotive stamping plants and steel service centers where procurement functions operate independently from maintenance engineering.
Global Load Monitoring System (LMS) Market Segmentation
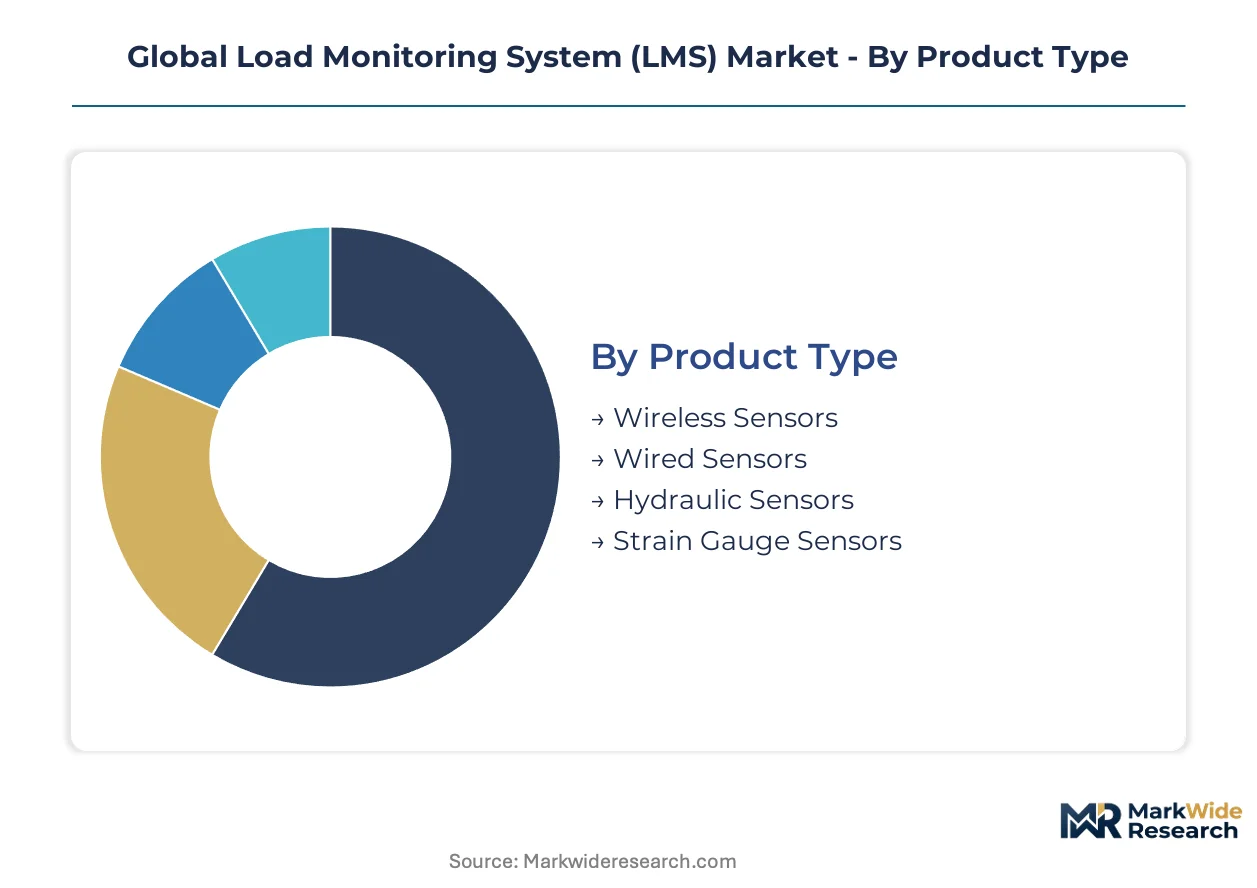
Load monitoring system procurement patterns diverge sharply across hardware configurations, connectivity protocols, and operational environments. Segmentation reveals where capital expenditure concentrates versus where replacement cycles accelerate.
Product Type:
Cost tier determines sensor selection more than absolute precision specifications in most commercial lifting operations.
- Wireless Sensors:Radio-frequency telemetry eliminates cable fatigue failures in mobile crane booms and offshore derricks. Port operators in Singapore and Rotterdam specify wireless architectures to satisfy EU Machinery Directive cable-safety mandates while reducing installation downtime on existing fleet assets.
- Strain Gauge Sensors:Foil and semiconductor strain gauges deliver microstrain resolution for permanent industrial installations. German automotive stamping plants and Japanese steel mills deploy these for decades-long drift stability in press force monitoring applications.
- Wired Sensors:Hardwired 4-20mA and voltage-output configurations persist in brownfield manufacturing sites where control system replacement costs block digital retrofits.
- Hydraulic Sensors:Pressure-transducer-based load measurement serves rough-terrain cranes and mining shovels where electrical isolation from hydraulic power circuits is mandatory.
Wireless sensors hold installed capacity. Strain gauge sensors is rotating up the share rankings.
Technology:
Application context dictates whether cloud connectivity, short-range pairing, or non-electronic measurement methods prevail.
- IoT Enabled:Cellular and Wi-Fi-connected sensor nodes stream load histories to fleet management platforms. Construction equipment OEMs in South Korea and telematics providers in Germany are integrating these data streams for predictive maintenance and insurance documentation.
- Bluetooth:Short-range wireless pairing supports technician diagnostics and temporary monitoring setups without infrastructure investment. UAE rental fleet operators specify Bluetooth-enabled sensors for rapid field calibration of mobile lifting equipment.
- RFID:Passive and active radio-frequency identification tags couple with load cells for asset tracking and automated inspection record generation.
- Ultrasonic:Non-contact force measurement through acoustic time-of-flight suits applications where physical sensor mounting compromises structural integrity.
- Optical:Fiber Bragg grating and laser-based strain sensing provide electromagnetic immunity for explosive atmospheres and high-voltage environments.
IoT-enabled architectures command premium positioning. Bluetooth is gaining share fastest in rental and temporary deployment segments.
Application:
Volume concentration varies with capital equipment replacement cycles and regulatory inspection intensity across lifting equipment categories.
- Cranes:Overhead, mobile, and tower cranes require overload protection and rated capacity limiters under OSHA and EU Machinery Directive mandates. German port operators and North American construction contractors drive replacement demand as safety digitization accelerates.
- Construction Equipment:Excavators, loaders, and telehandlers integrate load moment indicators and weighing systems for material optimization. Australian mining contractors and Brazilian infrastructure projects specify ruggedized sensors for high-vibration earthmoving environments.
- Marine Handling:Ship-to-shore cranes, offshore platform derricks, and subsea lifting frames demand corrosion-resistant and explosion-proof sensor housings.
- Manufacturing Equipment:Presses, injection molding machines, and automated assembly lines use load cells for process force control and quality assurance.
Crane applications anchor current revenue. Construction equipment is climbing the fastest as earthmoving OEMs bundle weighing systems with new machine sales.
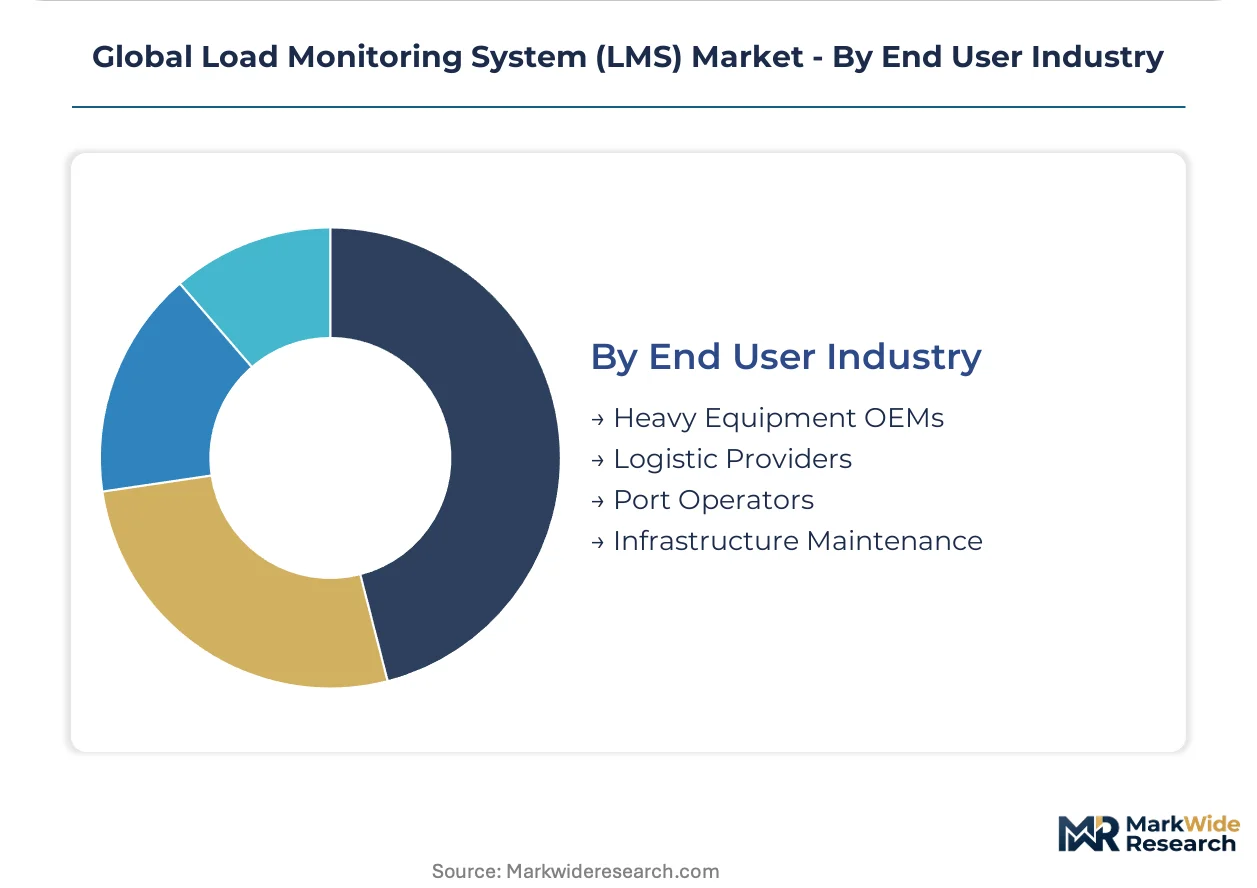
End User Industry:
Customer type shapes procurement authority, service contract structures, and technology adoption timelines.
- Heavy Equipment OEMs:Original equipment manufacturers specify sensors at design stage, favoring integrated architectures over aftermarket retrofits. Caterpillar, Komatsu, and Liebherr source load monitoring modules for factory installation on new crane and construction machine builds.
- Port Operators:Container terminal and bulk cargo handlers face EU Machinery Directive and ECHA substance compliance deadlines. Jawaharlal Nehru Port Trust in India and Hamburg Hafen und Logistik in Germany are expanding sensor deployments to satisfy documented load testing requirements.
- Logistic Providers:Third-party warehousing and freight operators install weighing systems for dimensional weight pricing and cargo optimization.
- Infrastructure Maintenance:Bridge inspection units, railway maintenance depots, and utility line crews deploy portable load monitoring for temporary lifting operations.
Heavy equipment OEMs control design-in volume. Port operators is rotating up the share rankings as regulatory retrofit cycles intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision strain gauge manufacturing clusters in Germany and Japan supply componentry to system integrators worldwide. Demand generation concentrates in port modernization corridors and offshore energy basins where regulatory retrofit cycles accelerate replacement timelines.
Germany
Port operators in Hamburg and Bremen expand wireless sensor deployments to satisfy EU Machinery Directive cable-safety mandates. ECHA substance restrictions on cadmium-plated components force stainless steel housing substitutions across crane fleets. The Ruhr industrial corridor sustains domestic demand from automotive stamping plants requiring decades-long drift stability in press force monitoring.
United States
OSHA hoist inspection standards mandate documented load testing tied to duty cycle intensity rather than calendar intervals. North American construction contractors absorb elevated compliance labor costs or deploy continuous monitoring systems. Gulf of Mexico offshore platform electrification drives explosion-proof wireless load cell demand for subsea lifting operations.
China
GB standards alignment with ISO crane safety protocols accelerates sensor retrofits on aging domestic fleet equipment. Yangtze River Delta port clusters under Shanghai and Ningbo-Zhoushan authority integrate IoT-enabled predictive maintenance protocols. Shenzhen-based system integrators bridge mechanical strain measurement with cloud-native data architectures for export-oriented manufacturers.
Singapore
Container terminal operators face EU Machinery Directive conformity requirements for transshipment equipment serving European trade lanes. The Maritime and Port Authority steers sensor material selection toward corrosion-resistant designs for tropical marine environments. Jurong Port and Tuas mega-port expansion projects create integrated load monitoring system demand for automated container handling.
India
Jawaharlal Nehru Port Trust and Mundra Port expansion under the Sagarmala initiative generate first-install demand for crane overload protection systems. The Central Electricity Authority mandates documented load testing records for utility-scale lifting operations. Gujarat Maritime Board terminals specify ruggedized sensors for bulk cargo handling in high-humidity coastal conditions.
Global Load Monitoring System (LMS) Market Key Industry Players
Precision component specialists and integrated system architects split the market along the hardware-software boundary. Three archetypes dominate: strain gauge heritage manufacturers sustaining premium positioning in aerospace and medical weighing; European load cell fabricators anchoring regional demand through localized production footprints; and software-layer integrators bundling LMS data into broader asset performance management suites. Competitive moves concentrate on API licensing revenue models and telematics platform convergence with construction equipment OEMs.
Within the precision component tier, Vishay Precision Group occupies a position exemplifying strain gauge heritage advantages in high-stability applications. Flintec anchors European demand through its manufacturing presence in Sweden and the UK. Spectris sits within the software-integration archetype, representing competitive positioning around data-layer bundling rather than standalone sensor sales. These three patterns illustrate how market participants defend margin position through specialization depth versus portfolio breadth tradeoffs.
| Leading Market Players |
|---|
| Vishay Precision Group |
| Spectris |
| Flintec |
| Mettler Toledo |
| PreciaMolen |
| LCM Systems |
| Straightpoint |
| Mantracourt Electronics |
| Eilersen Electric Digital Systems |
| Others |
Cost & Logistics Intelligence
Strain gauge supply concentration in Germany and Japan creates single-source dependency that compresses hardware margins across mid-tier system integrators while widening pricing tier spreads between aerospace-grade foil gauges and construction-grade MEMS alternatives. EU Machinery Directive compliance mandates force port operators to absorb premium pricing for certified wireless architectures, redirecting procurement toward bundled calibration service contracts that offset upfront sensor costs.
Pricing Analysis
EU Machinery Directive conformity requirements dictate the pricing tier structure across commercial crane retrofits, separating ISO 4309-certified wireless systems from uncertified wired alternatives. Price differentiation hinges on calibration traceability grade and explosion-proof housing certification, with North Sea offshore contractors showing least price sensitivity due to liability exposure. Cost compression in standard-tier strain gauge modules intensifies as Chinese system integrators expand export capacity, while premium aerospace segments sustain margin buffers through decades-long drift stability specifications.
Supply Chain Analysis
Export control restrictions on semiconductor strain gauge fabrication equipment limit capacity expansion outside Germany, Japan, and the United States, constraining supply elasticity for precision foil components. Raw material flows draw from specialty steel mills in Sweden, aluminum alloy processors in Norway, and semiconductor wafer foundries in Taiwan. Single-source vulnerability concentrates in precision foil rolling capacity, where three German suppliers control aerospace-grade substrate production. Distribution runs through industrial distributors in Düsseldorf and Yokohama, with accredited calibration laboratories disintermediating traditional OEM service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is tilting toward heavy equipment OEMs and consolidated port operators, with Sagarmala-scale infrastructure procurement in India and automated terminal expansions in Singapore concentrating volume leverage among fewer decision-makers.
For Market Incumbents: Entrench position through backward integration into strain gauge substrate production, capturing margin pools currently absorbed by German and Japanese precision foil suppliers. Lock in port operator relationships via API licensing agreements with telematics platforms, neutralizing the threat of construction equipment OEMs bundling third-party LMS data streams into proprietary fleet management suites. For New Entrants and Emerging Players: Establish a beachhead in India's Jawaharlal Nehru Port Trust and Mundra Port expansion projects, where first-install demand for integrated load monitoring systems outpaces established vendor relationships. Target Brazilian pre-salt logistics contractors serving Petrobras offshore installations, leveraging dynamic load monitoring certification gaps among incumbent suppliers. Pursue direct OEM integration partnerships rather than aftermarket retrofit channels, securing design-in volume before fleet procurement decisions crystallize. For Investors and Strategic Acquirers: EU Machinery Directive digitization mandates reshape the acquisition landscape toward software-layer integrators capable of bundling LMS data into asset performance management suites. Five-to-ten-year viability favors targets with embedded firmware expertise bridging mechanical strain measurement with cloud-native architectures. Watch for OSHA hoist inspection standard updates as the signal indicating accelerated compliance-driven replacement cycles and expanded data-logging system penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Gauge Substrate Production | Captures margin pools from German and Japanese precision foil suppliers while securing supply continuity. |
| API Licensing with Telematics Platforms | Opens recurring revenue streams as Caterpillar and Komatsu integrate third-party LMS data into fleet management systems. |
| MEMS Sensor Platform Expansion | Addresses rental fleet demand in Australia and UAE where vibration tolerance outweighs absolute precision requirements. |
| Accredited Calibration Laboratory Network | Disintermediates OEM service agreements through marketplace platforms connecting end-users to traceability providers. |
| Explosion-Proof Wireless Load Cell Certification | Unlocks North Sea and Gulf of Mexico offshore platform electrification projects requiring subsea lifting compliance. |
Research Approach
A spread of perspectives from port operations directors, heavy equipment OEM procurement teams, aftermarket service heads, and strain gauge manufacturing engineers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with maintenance directors at German automotive stamping plants and technical directors at Singapore container terminals. Secondary validation drew from EU Machinery Directive implementation guidance, OSHA hoist inspection bulletins, ECHA substance restriction updates, and customs trade data tracking sensor component flows. Bottom-up installation forecasts triangulated against top-down capital expenditure projections across port modernization corridors.
Demand-supply balance modeling anchored the analytical framework, with volume outputs calibrated against retrofit cycle intensity under EU Machinery Directive deadlines and Sagarmala initiative timelines. Segmentation dimensions spanned hardware configuration, connectivity protocol, application equipment category, and end-user procurement authority. CAGRs were derived from replacement cycle compression rates and regulatory compliance acceleration patterns. Industry-specific inputs included crane fleet age distributions, ECHA substance restriction phase-out schedules, and offshore platform electrification project pipelines.
Stress conditions across strain gauge supply disruptions, tariff exposure on Chinese system integrator exports, and calibration infrastructure deployment lags were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding wireless sensor adoption curves and MEMS displacement rates in mobile crane applications. Material shifts in EU Machinery Directive enforcement digitization or OSHA inspection interval restructuring would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Indoor Positioning and Navigation Market
Sensors
Facial Tracking Solution Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Alcohol Sensor Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Low Power Geolocation Market
Sensors
Europe Lidar Market
Sensors
Automated Weather Observation System Market
Sensors
Wireless Sensor Nodes for Monitoring Exterior Panel Fatigue Market
Sensors
Conveyor Monitoring Market
Sensors
Body Area Network Market
Sensors
Beacon Technology Market
Sensors
Global Tunnel Monitoring System Market
Sensors
Bluetooth Beacons Market