
 Europe Remote Sensing Technology Market | 2026-2036
Europe Remote Sensing Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Remote Sensing Technology Market Foresight
Market Context
France is reshaping European remote sensing capacity through sovereign satellite manufacturing investments at Toulouse aerospace clusters. Airbus SE leverages vertical integration across payload design, platform assembly, and ground segment services to dominate institutional procurement. Thales Group anchors defense-oriented radar and optical sensor development through sustained R&D commitments to French and Italian military programs.
Technical Definition and Structural Segments
Remote sensing technology encompasses the acquisition of information about Earth's surface and atmosphere through detection of reflected or emitted electromagnetic radiation, typically operating across wavelength bands from visible (0.4–0.7 μm) through thermal infrared (10–12 μm) and into microwave frequencies for synthetic aperture radar systems. The primary industrial purpose spans geospatial intelligence, environmental surveillance, infrastructure monitoring, and strategic reconnaissance where direct physical access proves impractical or cost-prohibitive. Satellite platforms absorb the majority of capital deployment due to their extended orbital persistence and whole-continent coverage, though drone segments are capturing disproportionate growth in precision agriculture applications where revisit frequency and resolution requirements outstrip traditional spaceborne economics. Multispectral imaging maintains mature market share across environmental compliance monitoring, while LiDAR commands premium positioning in urban planning and topographic mapping where three-dimensional point cloud fidelity determines project outcomes.
Regulatory Framework
EU Space Programme Agency coordination, the EU Green Deal's Copernicus expansion mandates, and national defense procurement frameworks collectively determine market access and technical specifications for European remote sensing vendors. REACH chemical regulations and CE marking requirements constrain sensor material selection and electromagnetic compatibility certification, while GDPR provisions govern the downstream processing of geolocated personal data captured through aerial and satellite platforms. Stakeholders must monitor the interplay between national security classification protocols and the EU's push for open data policies, as this tension will determine whether institutional budgets flow toward sovereign classified systems or commercial dual-use alternatives.
Market Dynamics
EU Green Deal mandates are compressing procurement cycles for earth observation systems as member states face binding environmental reporting deadlines that only satellite-derived data can satisfy at continental scale.
Growth Catalysts
- Copernicus Expansion Mandates:EU Space Programme Agency requirements for enhanced land monitoring and atmosphere tracking are pulling through institutional satellite procurement across member states.
- Drone-based Multispectral Imaging:French and German agricultural cooperatives are deploying unmanned aerial platforms for sub-meter resolution crop stress detection that outperforms spaceborne revisit economics.
- Defense Budget Consolidation:Germany's unified earth observation spending across military and civilian agencies is creating single-source demand pools for synthetic aperture radar and optical reconnaissance payloads.
Market Restraints
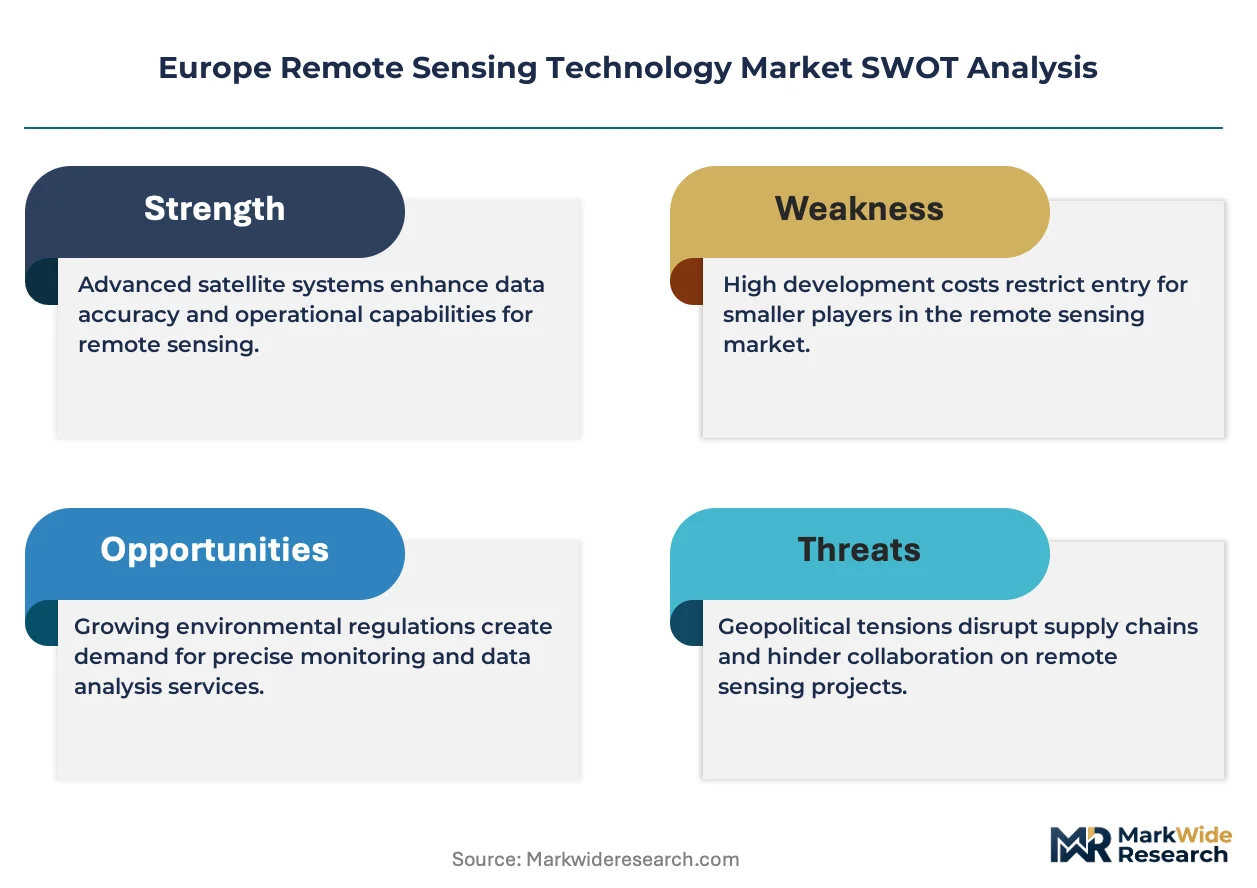
- Launch Capacity Bottlenecks:European sovereign launch availability constraints at Kourou and emerging commercial alternatives are extending satellite deployment timelines and inflating program risk.
- Sensor Material Cost Volatility:Rare earth element price swings for indium gallium arsenide focal plane arrays and mercury cadmium telluride detectors are compressing payload manufacturer margins.
- GDPR Geolocation Friction:Data protection authority interpretations of personal data capture from aerial and orbital platforms are creating legal uncertainty for commercial analytics providers.
Strategic Opportunities
- Carbon Credit Verification Services:Emerging voluntary carbon market standards are creating demand for satellite-monitored reforestation and soil carbon sequestration validation across Eastern European member states.
- LiDAR-UAV Convergence:Integration of lightweight laser scanning with extended-flight drone platforms is opening three-dimensional infrastructure inspection contracts for rail and utility networks.
- EU AI Act Compliance Tools:Automated feature extraction and change detection algorithms trained on Copernicus archives are positioning European vendors for public sector AI procurement preference.
Industry Challenges
- Photonics Engineering Scarcity:Specialist talent for free-space optical communications and hyperspectral sensor design is concentrating at Toulouse and Munich clusters, creating recruitment competition.
- CE Marking Timeline Compression:Electromagnetic compatibility and radio equipment directive certification for new SAR and optical payloads is extending product launch windows by 8-14 months.
- Interoperability with Legacy Ground Segments:Defense ministries' classified processing architectures resist integration with commercial cloud analytics, fragmenting vendor addressable markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Remote Sensing Technology Market |
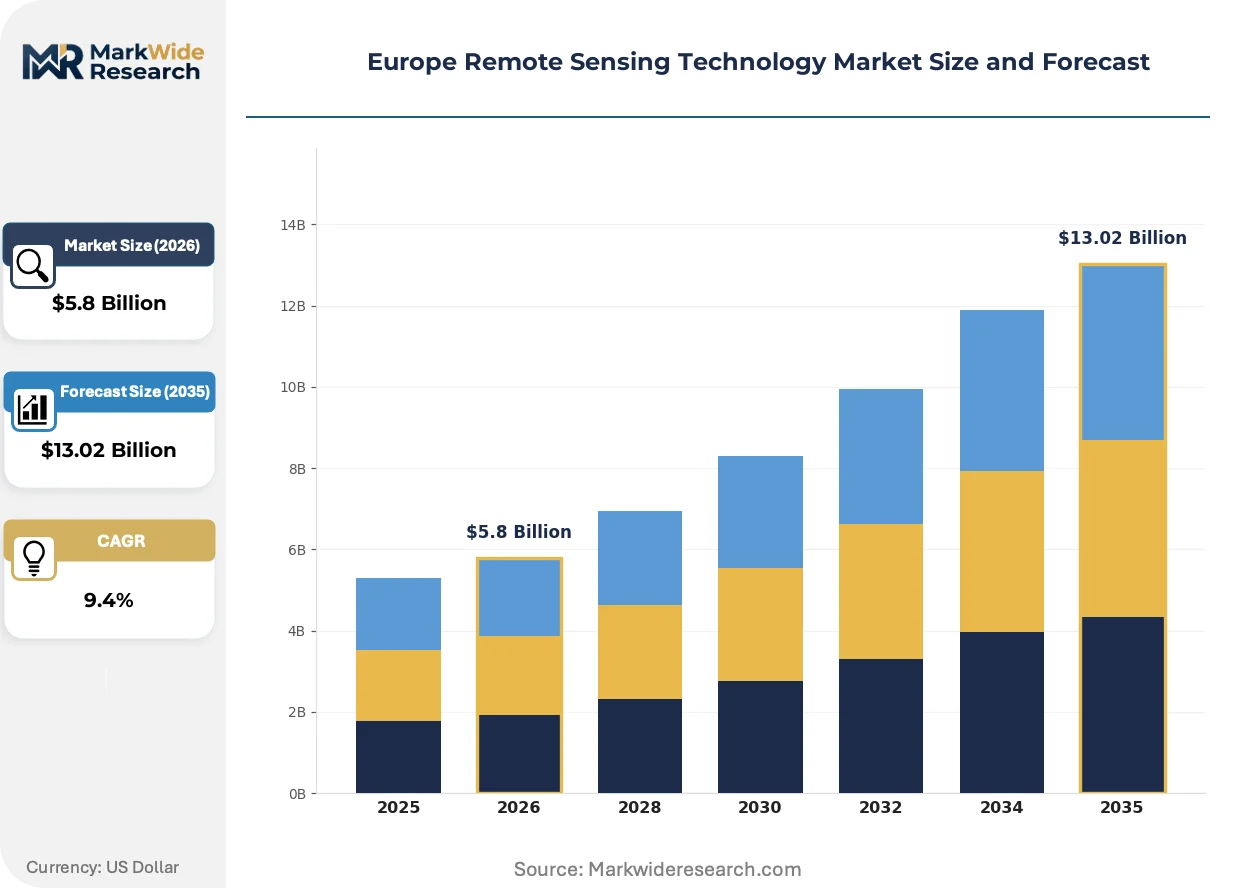
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellites, Drones, Ground Sensors, Aerial Platforms Technology: Hyperspectral Imaging, LiDAR, Radar, Multispectral Imaging End User: Agriculture, Environmental Monitoring, Urban Planning, Defense Application: Mapping, Disaster Management, Climate Change Studies, Resource Management |
| Companies Covered | Lockheed Martin Corporation, General Dynamics Corporation, Maxar Technologies, Northrop Grumman Corporation, Hexagon AB, Airbus SE, Planet Labs, L3Harris Technologies, Thales Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Remote Sensing Technology Market Shifts & Advancements
Synthetic aperture radar interferometry and AI-driven change detection are converging to compress the latency between raw orbital capture and decision-ready intelligence for infrastructure and environmental monitors.
Spaceborne SAR constellations are digitizing ground deformation monitoring for rail operators and mining concessionaires who previously relied on sparse GPS networks or manual surveying. German and Italian infrastructure managers are adopting weekly interferometric products for slope stability and subsidence tracking. The technology is digitizing risk assessment workflows that once required months of field verification into automated alert systems.
EU Green Deal reporting obligations are mandating standardized land cover classification schemas that only satellite-derived products can supply at national scale. REACH chemical regulations are simultaneously constraining sensor material selection for new payload development. Environmental compliance departments across France, Germany, and Poland are requisitioning Copernicus-based analytics to satisfy CSRD disclosure requirements.
Public sector procurement departments are unbundling satellite imagery from value-added analytics, forcing vendors to compete on algorithm performance rather than exclusive data access. French and German defense ministries are piloting platform-agnostic analytics contracts that accept inputs from multiple sovereign and commercial constellations. This pattern is most visible in border surveillance and maritime domain awareness programs where multi-source fusion is becoming a technical requirement.
Europe Remote Sensing Technology Market Segmentation
Remote sensing procurement patterns diverge sharply across platform economics, sensor physics, and institutional buyer mandates. Understanding these fault lines clarifies where capital deployment concentrates and which technology trajectories reshape competitive positioning.
Product Type:
Cost tier determines procurement authority levels and contract structures across European institutional buyers.
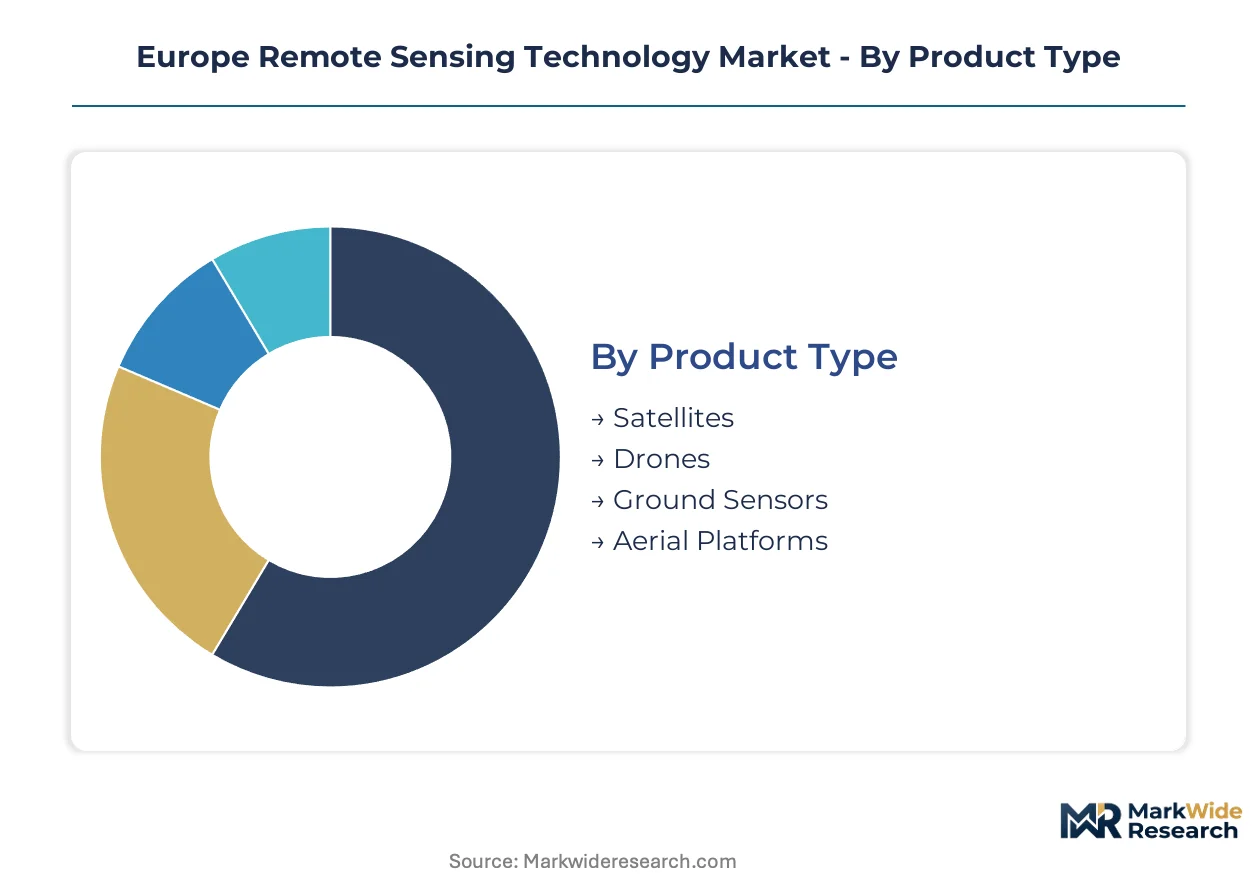
- Satellites:Orbital platforms carry capital intensity exceeding hundreds of millions of euros per unit, with synthetic aperture radar and optical constellations absorbing the majority of German and French defense and space agency budgets. Institutional procurement cycles span 5-8 years from contract award to operational deployment.
- Drones:Unmanned aerial systems deliver sub-meter resolution at operating economics that agricultural cooperatives and infrastructure managers can justify without ministerial approval. French and German precision farming deployments are scaling fastest where revisit frequency requirements outstrip spaceborne economics.
- Ground Sensors:Terrestrial monitoring stations provide calibration validation and gap-filling coverage for Copernicus ground segments.
- Aerial Platforms:Manned aircraft missions persist in topographic mapping and emergency response where payload mass and endurance requirements exceed drone capabilities.
Satellites hold installed capacity. Drones are rotating up the share rankings.
Technology:
Application requirements dictate wavelength selection and processing architecture across European end-use sectors.
- Hyperspectral Imaging:Contiguous narrow-band spectral sampling enables material identification for mineral exploration and precision agriculture stress detection. German mining concessionaires and French agricultural research institutes are deploying airborne systems where laboratory-grade spectral fidelity justifies premium sensor costs.
- LiDAR:Time-of-flight laser ranging generates three-dimensional point clouds with centimeter vertical accuracy for rail infrastructure and urban digital twin construction. Italian and German rail operators are mandating LiDAR-derived clearance surveys for tunnel and bridge maintenance cycles.
- Radar:Synthetic aperture systems penetrate cloud cover and darkness for all-weather maritime surveillance and ground deformation monitoring.
- Multispectral Imaging:Discrete band sampling dominates environmental compliance monitoring where Copernicus program specifications standardize procurement.
Multispectral Imaging holds installed capacity. Hyperspectral Imaging is rotating up the share rankings.
End User:
Customer type determines funding source stability and technical specification rigor across European procurement frameworks.
- Agriculture:Cooperative and corporate farming operations in France and Germany are scaling drone-based variable rate input programs where sub-field resolution translates directly to fertilizer and irrigation cost savings. EU Common Agricultural Policy digitization mandates are accelerating subsidy compliance reporting through satellite-derived acreage verification.
- Environmental Monitoring:National environmental agencies and EU programme offices constitute the largest institutional demand pool, driven by binding CSRD disclosure requirements and Green Deal land cover tracking obligations. Poland and Romania are expanding procurement fastest among newer member states.
- Urban Planning:Municipal governments and regional development authorities utilize three-dimensional data for zoning enforcement and infrastructure master planning.
- Defense:Classified reconnaissance and intelligence requirements operate through national security procurement channels with restricted vendor access.
Environmental Monitoring holds installed capacity. Agriculture is rotating up the share rankings.
Application:
Maturity curves separate established geospatial workflows from emerging climate finance use cases across European markets.
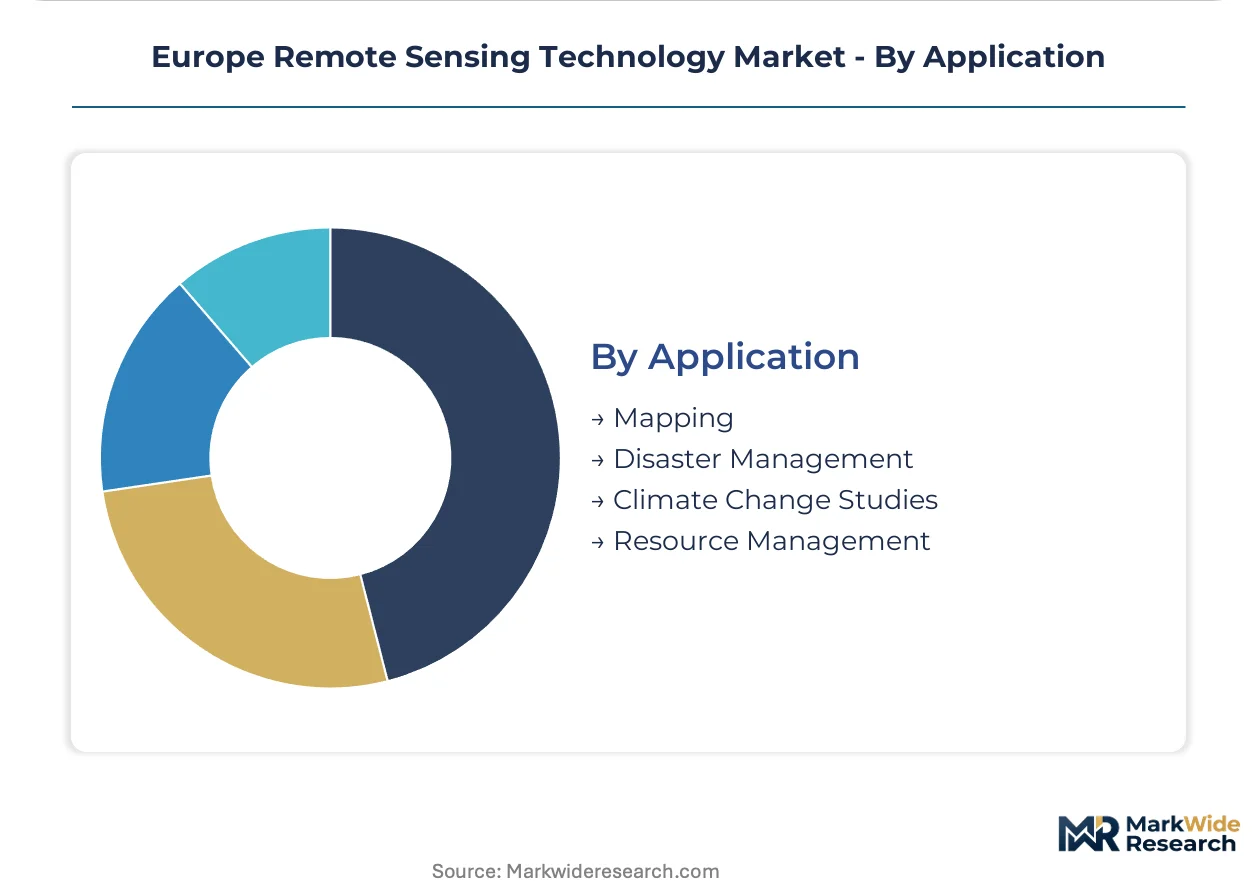
- Mapping:National mapping agencies maintain baseline topographic and cadastral data layers through systematic aerial and satellite acquisition programs. German Länder survey offices and French IGN sustain recurring procurement for 1:5,000 scale coverage updates.
- Disaster Management:Civil protection authorities activate rapid response tasking for flood, wildfire, and seismic event assessment. Italian and Greek emergency services are integrating SAR-based damage mapping into 24-hour response protocols.
- Climate Change Studies:Research consortia and carbon credit verifiers are constructing historical baselines for reforestation and soil carbon sequestration monitoring.
- Resource Management:Forestry services and water authorities track biomass inventory and watershed conditions through seasonal satellite monitoring.
Mapping holds installed capacity. Climate Change Studies is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Space Programme Agency coordination through the Copernicus program anchors institutional procurement across Germany, France, and Italy. Member state defense ministries and environmental agencies are consolidating earth observation budgets under Green Deal compliance deadlines.
Germany
DPA and BSI procurement frameworks are accelerating synthetic aperture radar satellite deployment for maritime surveillance and ground deformation monitoring. The unified earth observation budget consolidation across military and civilian agencies is creating single-source demand pools for reconnaissance payloads. Munich aerospace clusters concentrate SAR payload engineering talent and ground segment development capabilities.
France
CNES sovereign satellite manufacturing investments are expanding Toulouse aerospace cluster capacity for optical and radar payload assembly. ANSM and CNIL interpretations of GDPR geolocation provisions are shaping commercial analytics provider compliance frameworks. Thales Group and Airbus SE anchor defense-oriented sensor development through sustained R&D commitments to military programs.
Italy
ASI participation in Copernicus expansion mandates is pulling through institutional procurement for atmospheric monitoring and land cover tracking payloads. Civil protection authorities are integrating SAR-based damage mapping into 24-hour emergency response protocols for seismic and flood events. Rome and Milan concentrate radar interferometry application development for infrastructure monitoring contracts.
United Kingdom
UK Space Agency funding for earth observation capabilities is supporting domestic satellite manufacturing and downstream analytics provider growth. Environmental Agency procurement for flood monitoring and coastal erosion tracking is creating demand for high-revisit optical imagery. Harwell Space Cluster hosts payload engineering and data analytics firms serving institutional and commercial markets.
Poland
Ministry of Climate and Environment procurement for EU Green Deal land cover verification is expanding fastest among newer member states. CSRD disclosure requirements are compelling corporate environmental compliance departments to adopt Copernicus-based analytics. Warsaw and Krakow clusters are developing downstream application capabilities for agricultural and forestry monitoring services.
Europe Remote Sensing Technology Market Competitive Landscape
Capability concentration sits with vertically integrated aerospace primes; scale advantage sits with specialized sensor developers and analytics platforms. The vendor base organizes around three strategic archetypes: sovereign satellite manufacturers with end-to-end payload-to-ground-segment integration, defense electronics conglomerates with classified program access, and commercial imagery providers with platform-agnostic analytics capabilities. Dominant competitive moves include strategic partnerships between primes and launch service providers, plus portfolio diversification into carbon credit verification and AI-driven change detection software.
Within the sovereign manufacturing tier, Airbus SE and Thales Group exemplify vertically integrated European players with institutional procurement anchoring. Maxar Technologies and Planet Labs occupy positions on the commercial imagery and analytics vector, representing platform-agnostic service models that unbundle data from value-added processing. Lockheed Martin Corporation and Northrop Grumman Corporation anchor the transatlantic defense electronics segment with classified reconnaissance program participation.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| Maxar Technologies |
| Northrop Grumman Corporation |
| Hexagon AB |
| Airbus SE |
| Planet Labs |
| L3Harris Technologies |
| Thales Group |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight cost volatility is compressing margins for indium gallium arsenide focal plane array suppliers concentrated in southern Germany, forcing payload manufacturers to pass through transport premiums while satellite primes absorb fixed-price contract exposure for institutional buyers.
Pricing Analysis
German-French price spreads for synthetic aperture radar payloads exceed those for optical systems by a factor reflecting certification-grade differentiation. Three-tier pricing structure across mission-critical defense, institutional research, and commercial dual-use tiers anchors contract structures, with after-sales ground segment bundling determining effective per-orbit economics. Cost compression in commercial analytics subscriptions is intensifying because platform-agnostic procurement unbundles data from processing. Agricultural cooperatives exhibit highest price sensitivity; defense ministries remain least sensitive due to classified program budgets.
Supply Chain Analysis
EU dual-use export controls under the Wassenaar Arrangement restrict mercury cadmium telluride detector flows to non-member states, constraining payload manufacturer sourcing options. Manufacturing concentrates in France, Germany, and Italy for sovereign satellite assembly, while rare earth element refining for sensor substrates draws from limited external suppliers. Single-source vulnerability for indium and gallium precursors threatens production continuity. Distribution runs through prime contractor-led consortia with captive ground segment integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote sensing procurement operates as a defensive-moat market where regulatory entrenchment through EU Space Programme Agency certification creates switching costs that institutional buyers cannot easily circumvent.
For Market Incumbents: Entrench position through backward integration into indium gallium arsenide wafer production at Munich-Toulouse corridor facilities, eliminating rare earth element margin volatility. Deepen ground segment control by acquiring specialized SAR interferometry software houses before platform-agnostic procurement mandates fragment analytics revenue pools.
For New Entrants and Emerging Players: Polish and Romanian environmental compliance departments represent the most penetrable institutional demand pool, with CSRD disclosure requirements outpacing domestic analytics capacity. Carbon credit verification services for Eastern European reforestation projects offer a regulatory-driven entry wedge with lower certification barriers than defense or space agency channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace primes seeking to divest non-core analytics divisions ahead of platform-agnostic procurement standardization. Long-term viability favors vendors with Copernicus archive access rights and AI Act-compliant algorithm training pipelines. Monitor EU AI Act enforcement timelines as the critical inflection signal for public sector procurement preference shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Copernicus Archive Licensing Agreement | Secures training data access for EU AI Act-compliant change detection algorithms. |
| SAR Payload Manufacturing Scale-Up | Addresses German-Italian maritime surveillance procurement consolidation under unified budgets. |
| Carbon Credit Verification Partnership | Captures Polish-Romanian Green Deal compliance spending through satellite-monitored reforestation validation. |
| LiDAR-UAV Integration Development | Opens rail infrastructure inspection contracts with Deutsche Bahn and Trenitalia maintenance programs. |
| GDPR-Compliant Geolocation Analytics | Resolves CNIL-ANSM regulatory friction blocking commercial aerial platform deployment. |
Research Methodology
Operator-level perspectives from satellite program directors, defense procurement officers, agricultural cooperative technology managers, and environmental agency GIS specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EU Space Programme Agency procurement disclosures, CNES and DLR budget documentation, and REACH chemical regulation filings. Bottom-up segment sizing triangulated against top-down Copernicus program expenditure tracking.
Scenario-bracketing around launch capacity constraints and rare earth element price trajectories shaped the analytical framework across the projection horizon. Segmentation modeling incorporated platform type, sensor technology wavelength regime, end-user institutional category, and application maturity curve. CAGRs derived from satellite deployment pipeline analysis and drone adoption elasticity in French-German agricultural markets.
Practitioners should monitor EU AI Act implementation timelines and GDPR geolocation enforcement interpretations for early signals of procurement preference shifts. Forecasts reflect assumptions regarding Kourou launch cadence recovery and Copernicus expansion mandate funding continuity. Material shifts in export control regimes or REACH chemical restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Digital Compass (E-Compass) Market
Sensors
2D Barcode Reader Market
Sensors
Global Equipment Monitoring Market
Sensors
Asia-Pacific Remote Sensing Technology Market
Sensors
Automated Weather Observation System Market
Sensors
Handheld RFID Readers Market
Sensors
Beacon Technology Market
Sensors
Global RFID Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Global Remote Tank Monitoring System Market
Sensors
Robot Sensor Market
Sensors
Lidar Market
Sensors
Asset Tags Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Europe Lidar Market
Sensors
Mobile Lidar Scanner Market