
 Low Power Geolocation Market | 2026-2036
Low Power Geolocation Market Size, Share, and Industry Trends Forecast 2026-2036
Low Power Geolocation Market Foresight
Industrial fleet operators is bifurcating from consumer personal-tracking buyers as the primary volume anchor for low power geolocation hardware. Semtech Corporation leverages its LoRa chipset ecosystem to dominate long-range, minimal-energy positioning deployments across agricultural and utility networks. STMicroelectronics anchors its position through integrated MEMS and RF component portfolios that reduce bill-of-materials complexity for tracker manufacturers.
Low power geolocation encompasses position-sensing systems engineered to operate below one milliwatt average draw, typically employing duty-cycled GPS receivers, cloud-offloaded positioning computation, and energy-harvesting power stages to sustain multi-year battery life in untethered devices. Asset trackers lead product type volumes due to enterprise procurement scale and replacement cycles tied to logistics contract renewals, while Ultra Wideband technology captures premium positioning precision for indoor manufacturing and retail analytics applications where centimeter accuracy commands higher hardware margins.
The FCC governs unlicensed spectrum allocations for BLE and UWB transmission in the United States, directly constraining channel bandwidth and range capabilities available to device designers. ETSI harmonizes European radio equipment standards through EN 302 567 and related mandates, shaping market access requirements that OEMs must satisfy before CE marking. Stakeholders must monitor evolving spectrum policy and energy-labeling frameworks to anticipate compliance costs that will reshape component sourcing and firmware architecture decisions.
Market Dynamics
EU battery sustainability directives and F-Gas Regulation are forcing hardware redesigns toward recyclable components and lower energy consumption, compressing development cycles for tracker manufacturers serving extended supply chains.
Growth Catalysts
- Industrial Automation Clusters:Germany's automotive supply chain digitization creates dense adoption of low power positioning infrastructure across manufacturing and logistics facilities.
- REACH and RoHS Compliance:European material restrictions accelerate redesigns toward lead-free solder and halogen-free substrates in tracker assemblies.
- Cloud-Offloaded Positioning:Duty-cycled GPS receivers paired with edge-to-cloud computation architectures extend battery life beyond five years in untethered asset devices.
Market Restraints
- Lithium Supply Concentration:Battery cell sourcing depends on concentrated refining capacity in China, exposing tracker OEMs to input cost volatility and geopolitical friction.
- Spectrum Licensing Fragmentation:ETSI EN 302 567 and divergent national UWB rules create multi-jurisdictional certification burdens that delay product launches.
- Energy Harvesting Efficiency Ceiling:Photovoltaic and kinetic harvesters in indoor environments deliver sub-milliwatt outputs insufficient for continuous location polling.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor and component manufacturing attract tracker assembly migration from higher-cost origins.
- Ultra Wideband Convergence with BLE:Hybrid chipsets combining centimeter-precision UWB ranging with Bluetooth Low Energy advertising create unified indoor-outdoor positioning stacks.
- Outcome-Based Logistics Contracts:Shipment-condition-as-a-service models shift hardware procurement from capital expenditure to per-tracked-mile subscriptions.
Industry Challenges
- RF Front-End Integration:Multi-protocol antenna design for LoRa, Sigfox, NB-IoT and UWB requires scarce microwave engineering talent and extended simulation cycles.
- CE Marking Timeline Compression:Notified body backlogs for radio equipment directive compliance extend time-to-revenue by six to nine months for new tracker SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Power Geolocation Market |
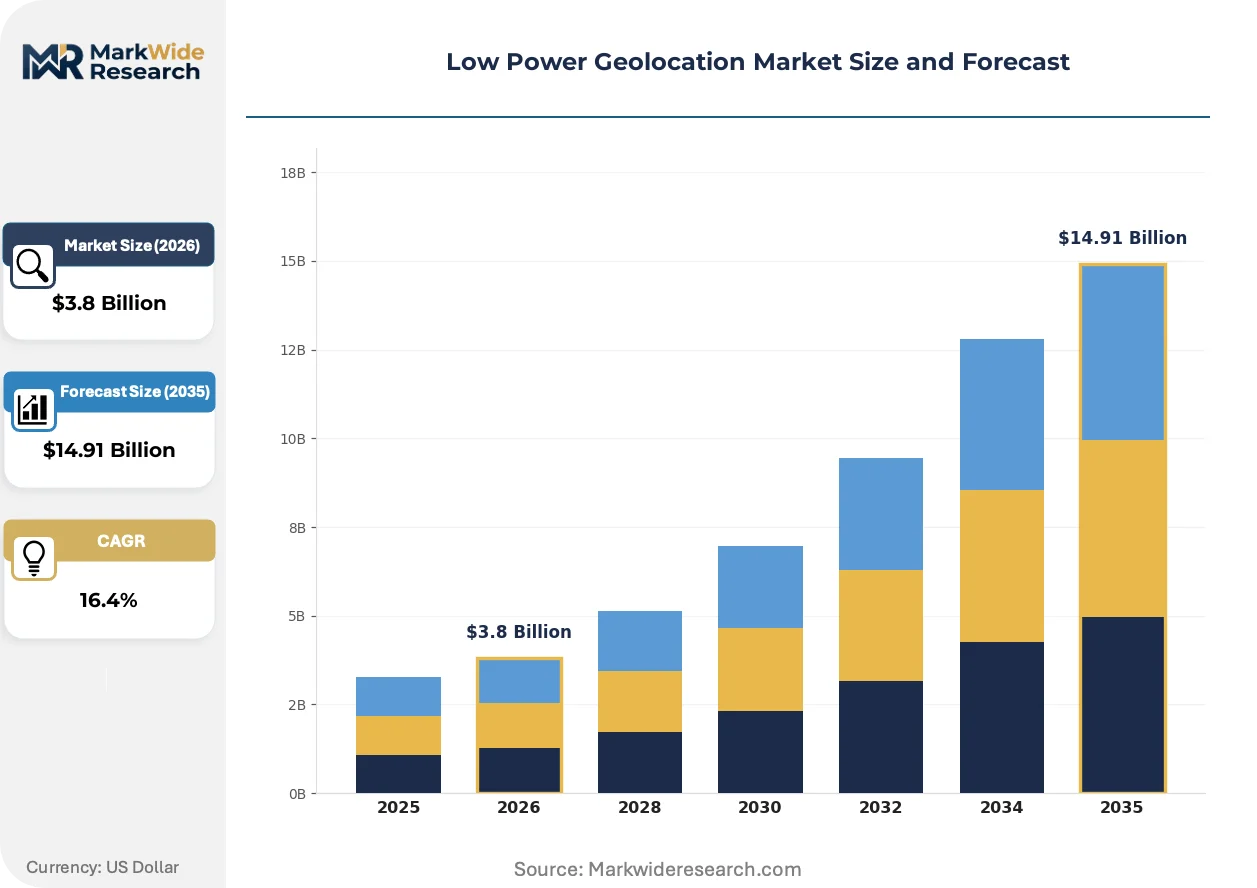
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Asset Trackers, Bluetooth Beacons, RFID Tags Technology: GPS, Wi-Fi Positioning, BLE, Ultra Wideband Application: Fleet Management, Personal Tracking, Smart Homes, Retail Analytics End User: Logistics, Healthcare, Consumer Electronics, Sports Activities |
| Companies Covered | Sigfox S.A., Digital Matter, Semtech Corporation, Kerlink S.A., Hoopo, Cisco Systems, Nestwave SAS, Favendo GmbH, STMicroelectronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Power Geolocation Market Shifts & Advancements
Hardware architectures are consolidating around system-in-package designs that merge positioning computation, RF transceivers and power management into single-die solutions, collapsing bill-of-materials complexity for volume tracker production.
Energy-harvesting power stages incorporating photovoltaic cells and kinetic transducers are displacing primary lithium batteries in solar-exposed and vibration-rich deployment environments. Agricultural equipment monitoring and railcar tracking segments adopt these self-sustaining designs fastest. The shift compresses total cost of ownership calculations and extends replacement cycles beyond hardware depreciation schedules.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon-based cooling in semiconductor fabrication, elevating capital costs for MEMS foundry capacity serving positioning sensor markets. German and French industrial clusters face the tightest equipment upgrade timelines. Tracker OEMs are qualifying alternative foundry sources in Taiwan and Japan to secure supply continuity.
Enterprise procurement teams now mandate hardware-as-a-service pricing with bundled connectivity and cloud platform access, displacing traditional component sourcing from discrete tracker vendors. Third-party logistics operators and pharmaceutical cold chain managers lead this contract restructuring. The model concentrates purchasing authority among fleet-scale buyers and marginalizes smaller hardware-only suppliers.
Low Power Geolocation Market Segmentation
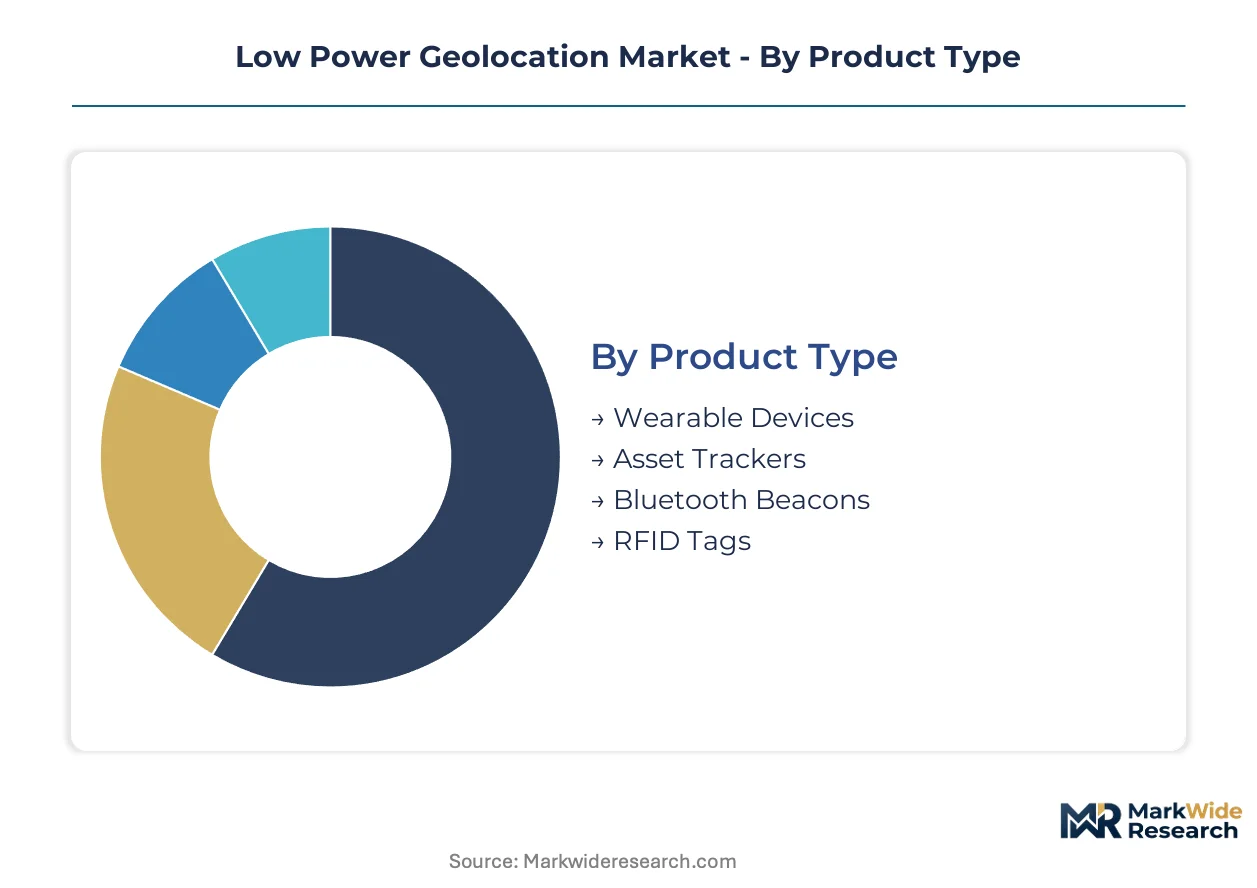
Segmentation in low power geolocation reveals divergent procurement patterns across consumer and enterprise buyers. Battery life requirements, precision thresholds, and connectivity protocols fragment hardware specifications into distinct addressable pockets.
Product Type:
Domestic deployments in Germany and France concentrate on enterprise-grade hardware, while export-led manufacturing in Taiwan and Vietnam supplies volume consumer wearables.
- Asset Trackers:Duty-cycled GPS receivers with cloud-offloaded computation dominate logistics procurement. German automotive supply chains and pharmaceutical cold chain operators in France drive replacement cycles tied to contract renewals.
- Wearable Devices:Fitness bands and personal safety pendants employ BLE beaconing with sub-milliwatt draw. Consumer demand clusters in urban Japan and South Korea, where aging demographics and health monitoring subsidies accelerate adoption.
- Bluetooth Beacons:Fixed infrastructure for indoor positioning in Dutch retail and Singaporean smart buildings.
- RFID Tags:Passive backscatter designs for pallet-level tracking in Polish and Czech distribution centers.
Asset trackers command the established base. The steepest expansion runs through wearable devices.
Technology:
Cost tiers separate premium precision offerings from mass-market proximity solutions, with margin structures dictating foundry partnerships and RF front-end complexity.
- Ultra Wideband:Centimeter-accurate ranging enables indoor manufacturing analytics and high-value asset verification. German industrial automation clusters and Japanese semiconductor fabs absorb hardware premiums for spatial positioning.
- GPS:Duty-cycled receivers with assisted-GPS ephemeris caching dominate outdoor fleet applications. Brazilian agricultural equipment monitoring and Australian mining logistics sustain volume demand despite power overhead.
- BLE:Minimal-energy advertising packets for proximity detection in Canadian healthcare facilities and Mexican retail.
- Wi-Fi Positioning:Fingerprinting databases for urban canyon navigation in dense South Korean and Taiwanese metropolitan corridors.
GPS maintains the installed volume base. Ultra Wideband is climbing the fastest as precision premiums justify hardware costs.
Application:
Customer type bifurcation separates capital-intensive fleet operators from subscription-oriented consumer platforms, reshaping pricing architecture and distribution channels.
- Fleet Management:Multi-asset visibility platforms integrate LoRa backhaul with edge gateways. Third-party logistics operators in Germany and France mandate five-year battery life for untethered trailer tracking.
- Retail Analytics:UWB and BLE fusion enables shopper journey mapping and inventory robot navigation. Premium deployments concentrate in Dubai and Singaporean mall operators seeking conversion optimization.
- Personal Tracking:Child and elderly safety devices with geofencing alerts in Japanese and South Korean households.
- Smart Homes:Presence detection for HVAC and lighting automation in Swedish and Norwegian residential construction.
Fleet management anchors enterprise procurement. Retail analytics is gaining share fastest as indoor positioning infrastructure matures.
End User:
Supply concentration in component sourcing shapes which end-user segments access priority allocation during foundry capacity constraints.
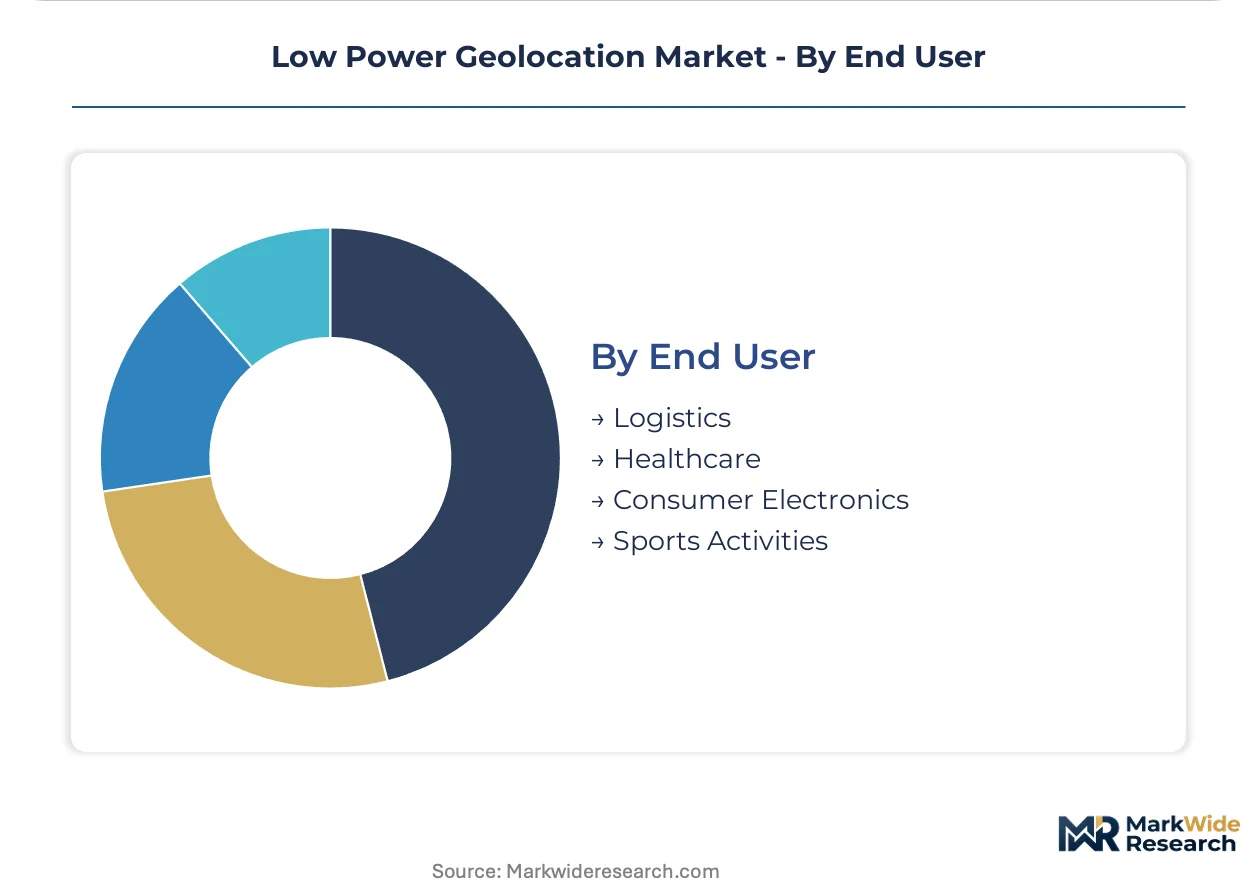
- Logistics:Asset-intensive operators deploy battery-efficient trackers across extended supply chains. REACH and RoHS compliance mandates from ECHA force lead-free solder transitions in hardware assemblies serving EU-based fleet operators.
- Healthcare:Patient wandering prevention and medical equipment location systems demand HIPAA-aligned data architectures in US hospital networks, while Japan's PMDA guides device certification for clinical settings.
- Consumer Electronics:Smartphone-integrated tag ecosystems from Cupertino and Seoul ecosystem vendors.
- Sports Activities:Performance analytics for professional cycling and running in Italian and Swiss equipment markets.
Logistics commands the established base. Healthcare is expanding most quickly as regulatory clarity enables procurement standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput and digital logistics corridors position the Netherlands as a critical node for asset tracker deployment across European supply chains.
Germany
Automotive supply chain digitization and industrial automation clusters drive dense adoption of low power positioning infrastructure. The F-Gas Regulation mandates phasedown of hydrofluorocarbon-based cooling in semiconductor fabrication, elevating capital costs for MEMS foundry capacity. Stuttgart and Munich industrial corridors concentrate tracker OEM qualification activities for alternative foundry sourcing.
United States
Third-party logistics operators and pharmaceutical cold chain managers mandate hardware-as-a-service pricing with bundled connectivity. FCC unlicensed spectrum allocations for BLE and UWB transmission constrain channel bandwidth and range capabilities available to device designers. Silicon Valley and Boston technology clusters anchor cloud-offloaded positioning computation development.
China
Battery cell sourcing concentration in lithium refining capacity exposes tracker OEMs to input cost volatility and geopolitical friction. MIIT and GB standards govern radio equipment certification requirements for domestic market access. Shenzhen and Shanghai manufacturing basins supply volume consumer wearables and component assemblies.
Japan
Aging demographics and health monitoring subsidies accelerate adoption of fitness bands and personal safety pendants with BLE beaconing. METI and PMDA guide device certification frameworks for clinical settings. Tokyo and Osaka metropolitan corridors concentrate wearable device procurement and smart building indoor positioning deployments.
India
Production-linked incentives for semiconductor and component manufacturing attract tracker assembly migration from higher-cost origins. BIS and TRAI regulate radio equipment standards and telecommunications licensing for IoT deployments. Bengaluru and Hyderabad electronics manufacturing clusters absorb contract assembly volumes for export markets.
Low Power Geolocation Market Competitive Landscape
Listed leaders compete with private specialists across spectrum licensing and foundry access dimensions, creating a tiered structure where scale advantages concentrate with integrated semiconductor houses. The vendor base organizes around three strategic archetypes: chipset ecosystem orchestrators, system-in-package integrators, and vertical application specialists. M&A activity targets RF front-end engineering talent pools, while strategic partnerships secure foundry allocation during capacity constraints.
Among France-based connectivity providers, Sigfox S.A. and Nestwave SAS exemplify the network-operator archetype, anchoring low-power wide-area infrastructure deployment. Semtech Corporation represents the chipset ecosystem model, leveraging LoRa intellectual property to consolidate long-range positioning hardware volumes. STMicroelectronics occupies the integrated component tier, reducing bill-of-materials complexity for tracker manufacturers through merged MEMS and RF portfolios.
| Leading Market Players |
|---|
| Sigfox S.A. |
| Digital Matter |
| Semtech Corporation |
| Kerlink S.A. |
| Hoopo |
| Cisco Systems |
| Nestwave SAS |
| Favendo GmbH |
| STMicroelectronics |
| Others |
Supply & Pricing Matrix
Ninety-day MEMS foundry lead times for positioning sensors concentrate pricing power with integrated semiconductor houses serving German automotive supply chains, compressing margins for tracker OEMs locked into single-source RF component agreements. Battery cell allocation priority during lithium supply crunches further amplifies cost asymmetries between fleet-scale buyers and mid-tier hardware vendors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates UWB-enabled centimeter-precision hardware from BLE proximity beacons and passive RFID tags. Price differentiation rests on certification grade—CE-marked industrial units command hardware premiums against uncertified consumer alternatives—while volume scale discounts concentrate purchasing leverage among third-party logistics operators. Cost compression in the standard tier intensifies because Indian contract assembly migration under PLI incentives erodes legacy manufacturing margins. Fleet operators exhibit lowest price sensitivity due to outcome-based contract structures; consumer wearable buyers face highest elasticity.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for positioning SoCs, while China dominates lithium cell refining and PCB substrate production. Raw material dependencies span rare-earth magnets for MEMS oscillators, high-purity silicon substrates, and cobalt-containing cathode chemistries. Single-source vulnerability concentrates in Taiwanese foundry capacity serving European MEMS demand. Distribution runs through Shenzhen component hubs for volume consumer trackers and direct OEM relationships for German industrial fleet deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect through hybrid UWB-BLE chipset consolidation, where interoperability standards collapse hardware margins for single-protocol specialists while rewarding ecosystem orchestrators with recurring connectivity revenue streams.
For Market Incumbents: Compound LoRa ecosystem lock-in through backward integration into MEMS foundry partnerships securing allocation priority during capacity crunches. Accelerate CE marking pre-certification for EN 302 567 revisions ahead of notified body backlogs. Threat substitution from cloud-native positioning startups demands firmware-level cloud offloading to preserve hardware attach rates. For New Entrants and Emerging Players: BIS fast-track certification for Indian PLI assembly exports offers regulatory arbitrage against EU compliance timelines. Target agricultural equipment monitoring in Brazil and Australia where five-year battery life specifications remain underpenetrated by incumbent fleet specialists. Go-to-market through outcome-based crop-yield contracts bypasses capital expenditure friction with mid-size farm cooperatives. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive logistics divisions seeking hardware-as-a-service monetization. Long-term viability favors platform players with recurring connectivity revenue over component-only vendors facing silicon commoditization. Signal to watch: ETSI spectrum harmonization progress indicating regulatory clarity for multi-jurisdictional scale.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid UWB-BLE Chipset Integration | Unified indoor-outdoor positioning stacks collapse bill-of-materials for tracker OEMs serving German automotive supply chains. |
| Energy-Harvesting Power Stage Deployment | Photovoltaic and kinetic transducers extend replacement cycles beyond depreciation schedules in Australian mining logistics. |
| Hardware-as-a-Service Contract Restructuring | Per-tracked-mile subscriptions concentrate purchasing authority among pharmaceutical cold chain operators in France. |
| Alternative Foundry Qualification | Taiwanese and Japanese MEMS capacity secures supply continuity against EU F-Gas Regulation equipment upgrade timelines. |
| Cloud-Offloaded Positioning Architecture | Edge-to-cloud computation extends battery life specifications demanded by third-party logistics operators in Germany. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FCC equipment authorization databases, ETSI harmonized standards publications, and customs trade data for RF component flows. Interviews with tracker OEM procurement directors, MEMS foundry operations managers, and third-party logistics fleet technology officers ground supply-side constraints. Bottom-up unit economics for asset tracker bill-of-materials triangulate against top-down market sizing from connectivity subscription disclosures.
Segmentation dimensions modeled span product type, technology protocol, application vertical, and end-user industry across the analysis window. CAGRs derive from logistic curve fitting to deployment penetration rates by fleet operator segment. Forecast inputs incorporate PLI scheme capacity buildout timelines in India and ETSI spectrum policy evolution for UWB channel allocations.
Decision-makers should treat outputs as directional under assumptions of sustained lithium supply concentration and stable regulatory harmonization timelines; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in EU battery sustainability directive enforcement and foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Smart Barcode Readers Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Global Equipment Monitoring Market
Sensors
Smart Mat Market
Sensors
Yield Monitoring Systems Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
Remote Sensing Technology Market
Sensors
Traffic Sensor Market
Sensors
Automated Weather Observation System Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Residential Water Leak Detection System Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Safety Motion Control System Market
Sensors
Eye Tracking Market
Sensors
Temperature Data Loggers Market
Sensors
Global Heat Stress Monitor (HSM) Market