
 WAN Optimization Controllers Market | 2026-2036
WAN Optimization Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
WAN Optimization Controllers Market Analytics
Silicon Valley hardware engineering capacity is shifting toward cloud-optimized controller architectures with embedded SD-WAN intelligence. Cisco Systems, Inc. dominates enterprise branch deployments through deep channel partnerships and integrated security stacks. Riverbed Technology, Inc. specializes in application acceleration for latency-sensitive workloads across distributed manufacturing networks. Huawei Technologies Co., Ltd. leverages cost-engineered silicon to compete aggressively in emerging market telecommunications infrastructure.
WAN optimization controllers are network appliances or virtualized platforms that compress, deduplicate, and prioritize traffic flows across geographically distributed links using protocol-specific algorithms and quality-of-service policies. These systems typically operate at Layer 4-7 with throughput ratings from 100 Mbps to 100 Gbps, serving primarily to mask latency and packet loss over long-haul connections. Cloud-based deployment models now capture the fastest expansion as enterprises abandon capital-intensive on-premises hardware refresh cycles. Bandwidth management solutions retain the largest margin pools due to recurring subscription structures, while protocol optimization commands premium pricing in high-frequency trading and telemedicine applications.
FCC net neutrality rulings and NIST cybersecurity framework mandates shape controller certification requirements for US federal contractors, while GDPR data-localization obligations in Europe force vendors to architect region-specific traffic steering. ISO 27001 and IEC 62443 compliance increasingly gates procurement for critical infrastructure operators across energy and transportation sectors. Stakeholders must weigh cloud migration timelines against residual on-premises compliance obligations when sizing controller refresh investments.
Market Dynamics
Cloud-native controller architectures are displacing purpose-built hardware as enterprises prioritize software-defined flexibility over fixed-function appliances. This transition compresses procurement cycles and reconfigures vendor competitive dynamics around subscription pricing and API ecosystems rather than throughput benchmarks.
Growth Catalysts
- FCC bandwidth modernization mandates:Federal contractors must refresh legacy WAN infrastructure to meet NIST cybersecurity framework requirements, creating replacement demand across civilian and defense agencies.
- High-frequency trading infrastructure:Financial services firms deploy protocol-optimized controllers to mask latency over transcontinental fiber routes supporting algorithmic execution.
- SD-WAN convergence:Embedded intelligence in cloud-optimized controllers collapses separate appliance categories into unified edge platforms.
Market Restraints
- Silicon supply concentration:Specialized packet-processing ASICs depend on TSMC fabrication capacity in Taiwan, exposing lead times to geopolitical disruption.
- GDPR data-localization friction:European traffic-steering requirements force redundant controller deployments per jurisdiction, inflating operational overhead.
- Cloud substitution pressure:Hyperscaler-managed WAN services absorb mid-market demand that previously purchased dedicated optimization appliances.
Strategic Opportunities
- India manufacturing corridor buildout:Distributed production networks across Gujarat and Tamil Nadu generate demand for application acceleration across low-quality last-mile links.
- EU AI Act compliance infrastructure:Real-time model inference across edge locations requires latency-optimized traffic management not addressed by standard routing.
- Telemedicine protocol specialization:DICOM and HL7-FHIR traffic prioritization for rural hospital networks creates premium pricing potential in healthcare verticals.
Industry Challenges
- Embedded systems engineering scarcity:Cloud-native talent pools lack expertise in kernel-level packet processing and hardware-offload optimization.
- ISO 27001 certification timelines:Critical infrastructure operators in energy and transportation face 12-18 month audit cycles gating controller procurement.
- Multivendor API harmonization:SD-WAN orchestration layers require custom integration work across proprietary controller management interfaces.
Report Scope
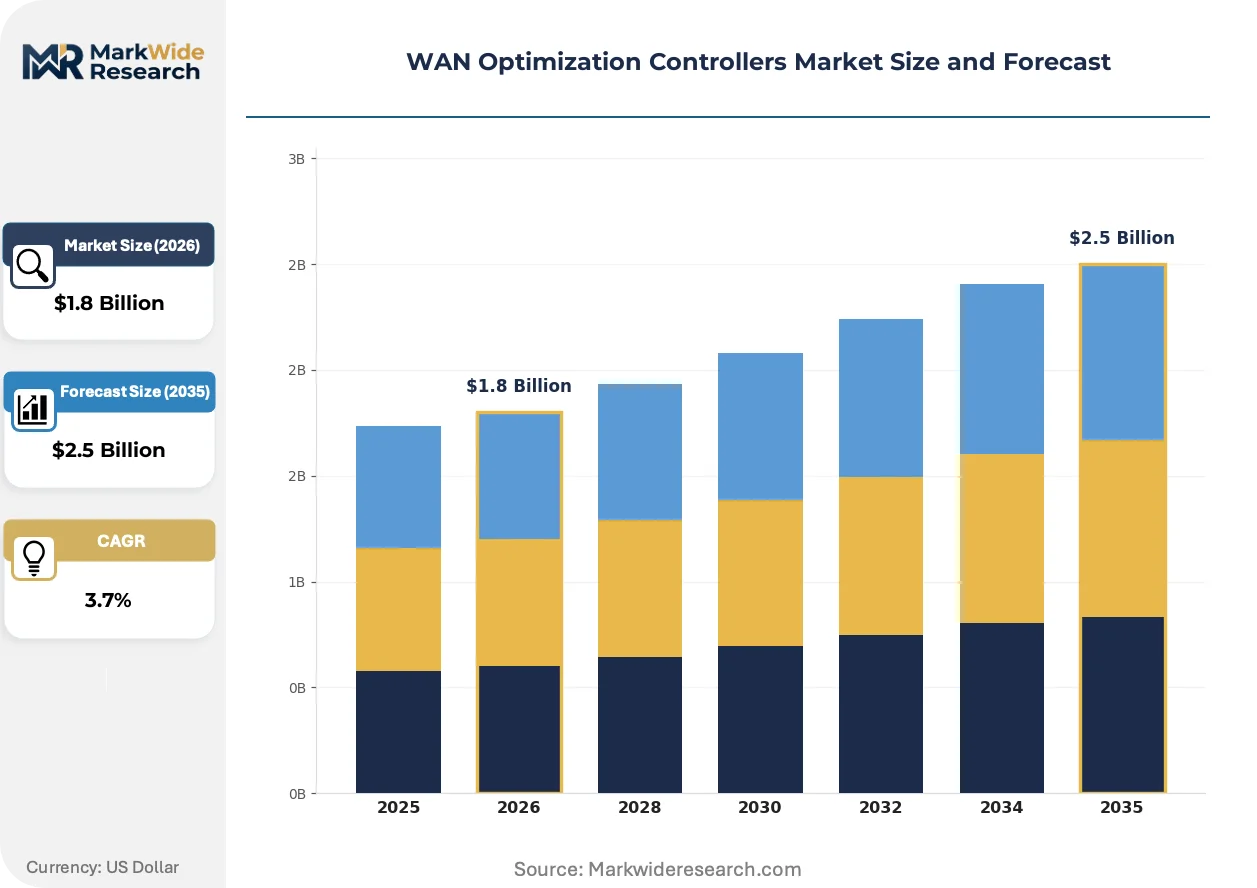
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | WAN Optimization Controllers Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Service Solution Type: Application Acceleration, Bandwidth Management, Protocol Optimization, Data Deduplication End User: Enterprises, IT Service Providers, Government, Educational Institutions Application: Video Conferencing, File Sharing, Web Applications, VoIP |
| Companies Covered | Fortinet, Inc., Huawei Technologies Co., Ltd., Cisco Systems, Inc., Oracle Corporation, Nokia Corporation, Riverbed Technology, Inc., Citrix Systems, Inc., FatPipe Networks, Inc., VMware, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
WAN Optimization Controllers Market Evolving Landscape
Virtualized controller platforms are collapsing the traditional boundary between WAN optimization and security enforcement, creating unified edge stacks that reduce appliance sprawl. This convergence redefines vendor differentiation around policy orchestration rather than raw compression throughput.
Containerized controller software is consolidating branch-office infrastructure by embedding traffic optimization, firewall, and zero-trust access within single virtual instances. Retail and hospitality chains with thousands of distributed sites are adopting this architecture fastest. The technology is consolidating three previously separate budget lines into single subscription contracts, compressing vendor addressable markets while expanding per-account values.
NIST cybersecurity framework mandates are forcing controller vendors to embed hardware root-of-trust and attestation capabilities previously absent from optimization appliances. Federal contractors now face procurement disqualification without FIPS 140-2 validated modules. Defense and civilian agencies are extending these requirements to state-level infrastructure grants, broadening compliance-driven refresh cycles.
Enterprise buyers are unbundling optimization from managed connectivity services, bringing controller procurement in-house after years of telco-integrated outsourcing. Manufacturing and logistics verticals with dedicated network operations teams lead this reversal. North American enterprises with complex multi-cloud footprints show the strongest preference for direct vendor relationships over carrier-mediated solutions.
WAN Optimization Controllers Market Segmentation
WAN optimization controllers serve heterogeneous network environments where deployment constraints, traffic types, and procurement authority vary sharply across buyer profiles. Segmentation reveals how vendor R&D investments and channel strategies must adapt to fundamentally different technical requirements and purchasing workflows.
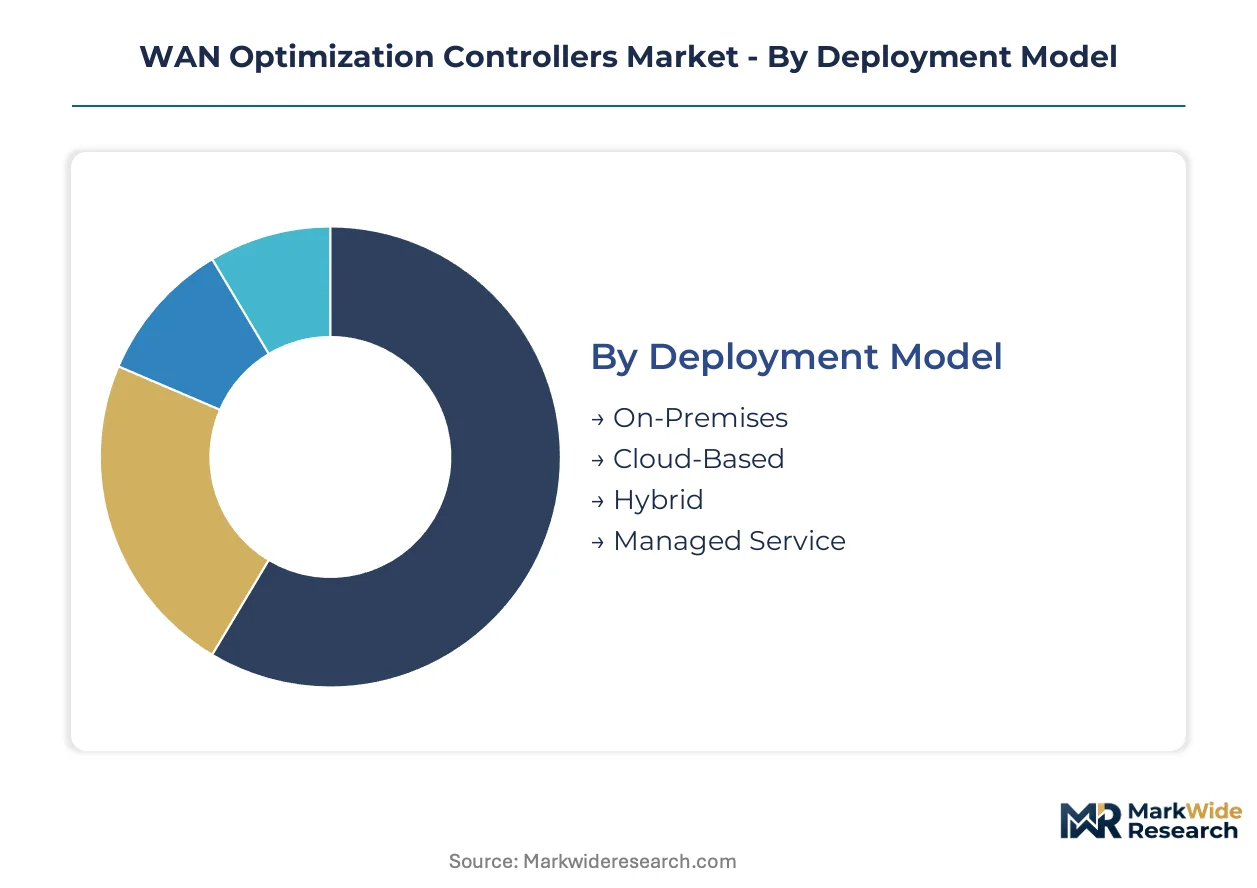
Deployment Model:
Standardization dominates at the infrastructure layer while customization requirements intensify at the policy and integration layers across this category.
- On-Premises:Physical or virtual appliances deployed within enterprise data centers and branch locations, offering deterministic performance and direct hardware control. Demand concentrates in US federal agencies and defense contractors subject to NIST cybersecurity framework mandates requiring FIPS 140-2 validated modules and hardware root-of-trust capabilities.
- Cloud-Based:Controller software delivered as subscription services from hyperscaler marketplaces or vendor SaaS platforms, eliminating capital expenditure and refresh cycles. Financial services firms in Chicago and New York trading corridors deploy these for elastic scaling during market volatility events without physical infrastructure provisioning.
- Hybrid:Split architectures maintaining on-premises policy enforcement with cloud-delivered analytics and orchestration planes. Manufacturing networks across Germany's Baden-Württemberg automotive cluster favor this model to preserve local control over production-line traffic while centralizing WAN management.
- Managed Service:Telco or MSP-operated controllers bundled with connectivity under single SLA contracts. Mid-market enterprises in India's Gujarat manufacturing corridor purchase these to compensate for limited in-house network engineering capacity.
Most installed capacity flows through On-Premises deployments reflecting legacy infrastructure inertia. Expansion is steepest in Cloud-Based delivery as enterprises abandon hardware refresh cycles.
Solution Type:
Margin structures diverge sharply between commoditized compression functions and specialized protocol handling requiring deep application-layer expertise.
- Application Acceleration:Layer 7 optimization techniques including TCP window scaling, connection pooling, and object caching tailored to specific SaaS platforms. Distributed retail chains across Australia's Queensland and Victoria states deploy these for Salesforce and Microsoft 365 performance over satellite backhaul links to remote stores.
- Bandwidth Management:Traffic shaping and quality-of-service policy enforcement prioritizing critical flows during congestion. Protocol Optimization commands premium pricing in high-frequency trading and telemedicine verticals where millisecond latency differentiates competitive outcomes.
- Protocol Optimization:Algorithmic improvements to CIFS, MAPI, HTTP/2, and proprietary database protocols reducing round-trip dependency. Data Deduplication eliminates redundant payload transmission across backup and replication streams.
- Data Deduplication:Block-level and file-level redundancy elimination reducing WAN bandwidth consumption for storage replication workloads. Energy sector operators in Saudi Arabia's Eastern Province oil infrastructure deploy these for disaster recovery traffic across geographically separated facilities.
Bandwidth Management solutions retain the largest revenue pools due to recurring subscription structures. Protocol Optimization is gaining share fastest among latency-sensitive verticals.
End User:
Procurement sophistication and compliance burden scale inversely with technical staff depth across buyer categories.
- Enterprises:Direct purchasers with dedicated network operations teams managing multi-thousand site deployments. North American manufacturing and logistics verticals with complex multi-cloud footprints show strongest preference for direct vendor relationships over carrier-mediated solutions.
- IT Service Providers:Multi-tenant deployments serving hundreds of downstream clients through standardized controller configurations. India's IT service providers in Bangalore and Hyderabad embed WAN optimization within managed infrastructure offerings for US and European enterprise clients.
- Government:Civilian and defense agencies with mandatory certification requirements and extended procurement cycles. US federal contractors face 12-18 month audit timelines gating controller procurement under ISO 27001 and IEC 62443 frameworks.
- Educational Institutions:Budget-constrained deployments prioritizing cost efficiency over advanced features. University systems across Brazil's São Paulo state leverage edu-negotiated licensing for research network optimization.
Enterprises account for the dominant share of controller shipments. IT Service Providers are expanding most quickly as managed WAN services absorb mid-market demand.
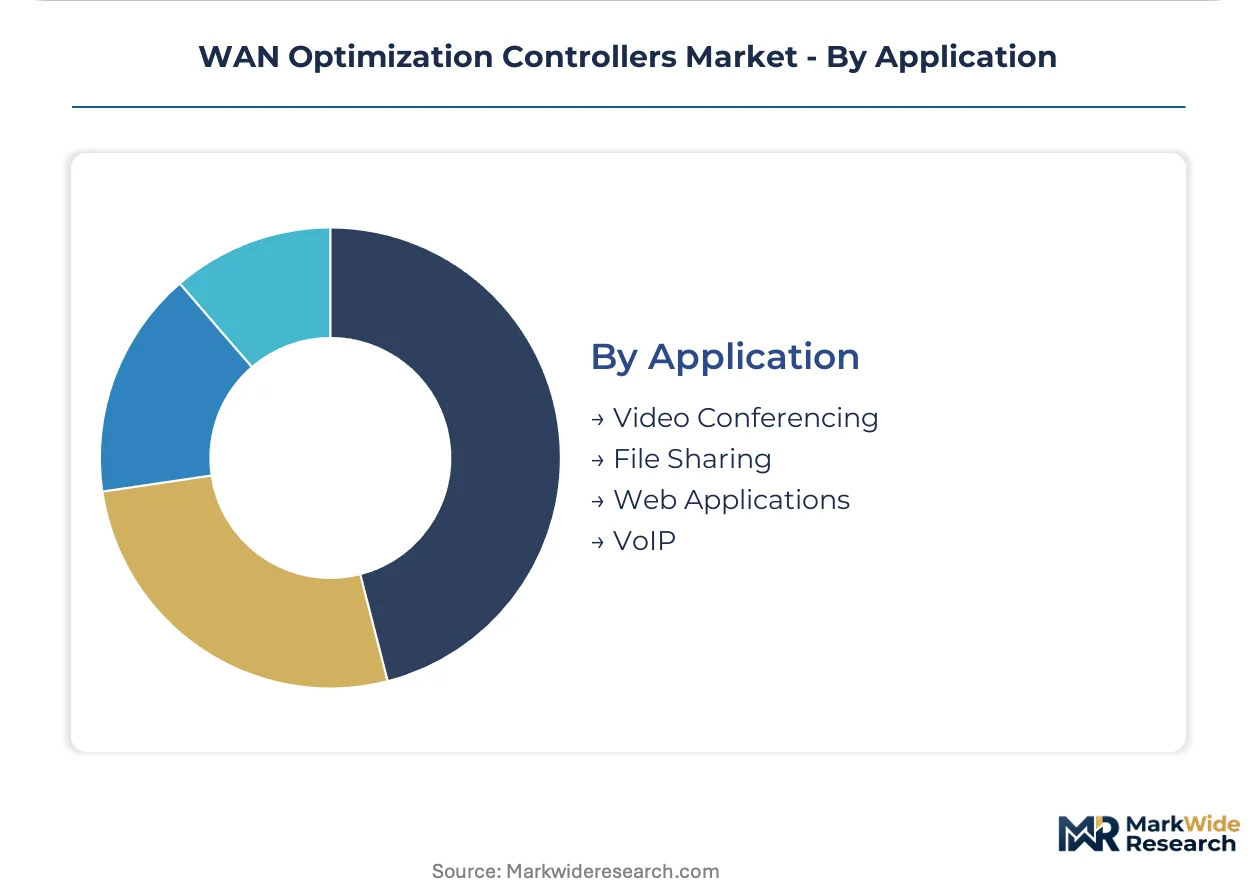
Application:
Traffic characteristics determine whether compression, prioritization, or protocol-specific handling delivers optimal performance economics.
- Video Conferencing:UDP-based real-time traffic requiring packet loss concealment and jitter buffering rather than traditional TCP optimization. Healthcare networks across France's Auvergne-Rhône-Alpes region prioritize DICOM imaging traffic alongside Zoom and Teams sessions for telemedicine consultations.
- File Sharing:Bulk data movement benefiting from deduplication, compression, and delta-encoding techniques. Engineering firms in Japan's Kanagawa prefecture accelerate CAD file collaboration between Tokyo headquarters and overseas manufacturing partners.
- Web Applications:HTTPS traffic with certificate pinning and certificate transparency requirements complicating middlebox inspection. South Korean e-commerce platforms in Seoul's Gangnam district optimize mobile app API responsiveness for cross-border shoppers.
- VoIP:Latency-bound voice traffic requiring dedicated bandwidth reservation and MOS score monitoring. Call center operations in the Philippines' Metro Manila region depend on these capabilities for quality assurance in business process outsourcing contracts.
File Sharing workloads process the highest volume of optimized traffic. Video Conferencing is climbing the fastest as hybrid work patterns persist across knowledge-intensive industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping procurement patterns as enterprises migrate controller investments toward jurisdictions with clearer compliance pathways and stronger federal bandwidth modernization programs. Cost-of-compliance gaps between data-localization regimes and cybersecurity certification timelines are concentrating vendor attention on specific national markets.
United States
FCC net neutrality rulings and NIST cybersecurity framework mandates are accelerating federal contractor refresh cycles for FIPS 140-2 validated hardware. Civilian and defense agencies in the Washington DC corridor are extending these requirements to state-level infrastructure grants. Enterprise IT refresh cycles across Chicago and New York trading corridors are driving demand for low-latency protocol optimization.
Germany
GDPR data-localization obligations are forcing redundant controller deployments per jurisdiction across Baden-Württemberg's automotive manufacturing cluster. IEC 62443 compliance requirements for critical infrastructure operators are gating procurement in energy and transportation sectors. Stuttgart-based engineering firms are prioritizing hybrid deployment models to preserve local traffic control while centralizing WAN management.
India
TRAI bandwidth allocation policies and federal digital infrastructure programs are expanding telecommunications backbone capacity across Gujarat and Tamil Nadu manufacturing corridors. IT service providers in Bangalore and Hyderabad are embedding WAN optimization within managed infrastructure offerings for US and European enterprise clients. Distributed production networks generate demand for application acceleration across low-quality last-mile links.
Japan
METI industrial digitalization initiatives are driving manufacturing network modernization across Kanagawa prefecture's precision engineering sector. JIS standards compliance shapes enterprise procurement criteria for network infrastructure refresh cycles. Tokyo-headquartered engineering firms are accelerating CAD file collaboration between domestic headquarters and overseas manufacturing partners through optimized controller deployments.
United Kingdom
Post-Brexit data sovereignty requirements are compelling financial services firms in London's Square Mile to architect region-specific traffic steering. UK regulators are aligning cybersecurity certification timelines with ISO 27001 frameworks for critical infrastructure operators. Edinburgh and Glasgow technology clusters are expanding managed WAN service offerings to mid-market enterprises with limited in-house network engineering capacity.
WAN Optimization Controllers Market Competitive Landscape
US-based technology conglomerates anchor one tier through integrated security stacks and deep channel partnerships; Chinese cost-engineered specialists hold another through aggressive telecommunications infrastructure pricing. The vendor base stratifies across three tiers: full-stack platform providers, application-acceleration specialists, and regional system integrators. Strategic moves concentrate on SD-WAN convergence and cloud-native controller architectures. M&A activity targets containerized software capabilities while partnerships focus on hyperscaler marketplace distribution.
Within the full-stack platform tier, Cisco Systems, Inc. and VMware, Inc. represent integrated edge-to-cloud positioning through virtualized controller platforms and unified policy orchestration. Riverbed Technology, Inc. exemplifies the application-acceleration specialist archetype with deep expertise in latency-sensitive workload optimization. Huawei Technologies Co., Ltd. occupies a distinct cost-engineered position in emerging market telecommunications infrastructure procurement. These three anchors illustrate how competitive differentiation is shifting from throughput benchmarks toward subscription pricing models and API ecosystem breadth.
| Leading Market Players |
|---|
| Fortinet, Inc. |
| Huawei Technologies Co., Ltd. |
| Cisco Systems, Inc. |
| Oracle Corporation |
| Nokia Corporation |
| Riverbed Technology, Inc. |
| Citrix Systems, Inc. |
| FatPipe Networks, Inc. |
| VMware, Inc. |
| Others |
Value Network & Pricing Analysis
TSMC wafer pricing indices cascade through specialized packet-processing ASIC costs into three distinct controller pricing tiers, compressing margins for hardware-dependent vendors while amplifying subscription-based SaaS premiums.
Pricing Analysis
Distributor margins on physical appliances absorb 15-25 point spreads before reaching federal contractors, while direct-to-enterprise SaaS subscriptions bypass channel markups entirely. Pricing stratifies across FIPS 140-2 validated premium tiers, standard enterprise licensing, and economy virtual editions lacking hardware root-of-trust. Cost compression in on-premises hardware stems from hyperscaler-managed WAN services absorbing mid-market demand. Government buyers exhibit lowest price sensitivity due to mandatory certification requirements; mid-market retail chains show highest sensitivity as they unbundle from telco-integrated solutions.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke fulfillment patterns for physical appliance deployments. Specialized ASIC fabrication concentrates in Taiwan, with secondary sourcing from South Korea and Israel for cryptographic acceleration modules. Single-source vulnerability at TSMC's advanced nodes exposes lead times to geopolitical disruption. Distribution runs through value-added resellers for federal segments and hyperscaler marketplaces for cloud-native deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where NIST cybersecurity framework mandates generate replacement demand cycles independent of organic technology refresh.
For Market Incumbents: Lock in federal contractor relationships through accelerated FIPS 140-2 certification roadmaps before ISO 27001 audit timelines extend procurement cycles further. Defend against hyperscaler WAN service substitution by embedding zero-trust security stacks that cloud-managed alternatives cannot replicate. Prioritize API ecosystem breadth over raw throughput benchmarks as procurement criteria shift. For New Entrants and Emerging Players: Hyperscaler marketplace listings offer the lowest-friction customer acquisition path for containerized controller software targeting mid-market manufacturing verticals. India's Gujarat and Tamil Nadu manufacturing corridors present the most penetrable geography given distributed production network complexity and limited incumbent presence. Lead with application acceleration for latency-sensitive workloads rather than commodity compression functions. For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native controller specialists possessing kernel-level packet processing expertise that cloud-native talent pools cannot replicate. Five-to-ten year viability hinges on SD-WAN convergence positioning rather than standalone optimization functionality. Watch hyperscaler capex disclosures for managed WAN service expansion signals as inflection indicators for hardware appliance demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Architecture Migration | Subscription pricing models displace capital-intensive hardware refresh cycles across North American enterprise accounts. |
| FIPS 140-2 Certification Investment | Federal contractor qualification gates procurement for civilian and defense agencies under NIST mandates. |
| SD-WAN Platform Integration | Unified edge stacks collapse separate appliance categories into single policy orchestration layers. |
| Hyperscaler Marketplace Distribution | AWS, Azure, and GCP channels bypass traditional VAR networks for mid-market customer acquisition. |
| Containerized Software Development | Retail and hospitality chains consolidate branch infrastructure through single virtual instance deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with network operations directors, federal procurement officers, hyperscaler platform engineers, and channel partner technical leads with secondary validation against FCC rulings, NIST publications, hyperscaler capex disclosures, and enterprise IT spending surveys. Bottom-up deployment model sizing and top-down regulatory demand estimation were cross-checked for triangulation.
Comparable historical periods anchored the projection horizon to prior federal bandwidth modernization cycles and enterprise cloud migration waves. Segmentation dimensions modeled include deployment model, solution type, end user category, and application workload across the analysis window. CAGR derivation incorporated protocol optimization premium capture rates, SD-WAN convergence adoption curves, and compliance-driven refresh timing.
The model assumes a particular technology adoption path; alternative pathways for cloud-native controller architectures would alter the outlook if hyperscalers accelerate managed WAN service expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Wi-Fi As a Service (Waas) Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
Structured Cabling Market
Network Technology
MENA Wireless Routers Market
Network Technology
Global Deep Packet Inspection and Processing Market
Network Technology
Global Managed Wi-Fi Solutions Market
Network Technology
Low-Power WAN Market
Network Technology
Open RAN Market
Network Technology
Mobile Hotspot Router Market
Network Technology
Global Self-Organizing Network Market
Network Technology
Network Performance Monitoring Market
Network Technology
Multiservice Provisioning Platform Market
Network Technology
Europe Structured Cabling Market
Network Technology
US Private LTE and 5G Network Market
Network Technology
Router and Switch Market
Network Technology
Global Passive Optical Network (PON) Equipment Market