
 Indoor Positioning and Navigation Market | 2026-2036
Indoor Positioning and Navigation Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Positioning and Navigation Market Intelligence
The shift towards API-driven, cloud-native platforms is reconfiguring how indoor positioning solutions are developed and deployed. Cisco leverages its extensive Wi-Fi infrastructure to deliver location analytics for enterprise clients. Zebra Technologies specializes in ruggedized hardware and software tailored for warehousing and manufacturing environments. Meanwhile, Google dominates consumer-facing applications through its Android ecosystem and extensive Maps APIs, creating a distinct market segment.
Indoor positioning and navigation systems determine an object's or person's location within enclosed spaces, operating independently of GPS. These systems achieve sub-meter accuracy by fusing data from technologies like Ultra-Wideband (UWB) and LiDAR. While Wi-Fi and Bluetooth Low Energy (BLE) technologies remain prevalent, UWB represents the fastest-growing technology segment for high-precision asset tracking applications. Cloud-based deployment models are also displacing traditional on-premises setups due to superior scalability and lower upfront costs.
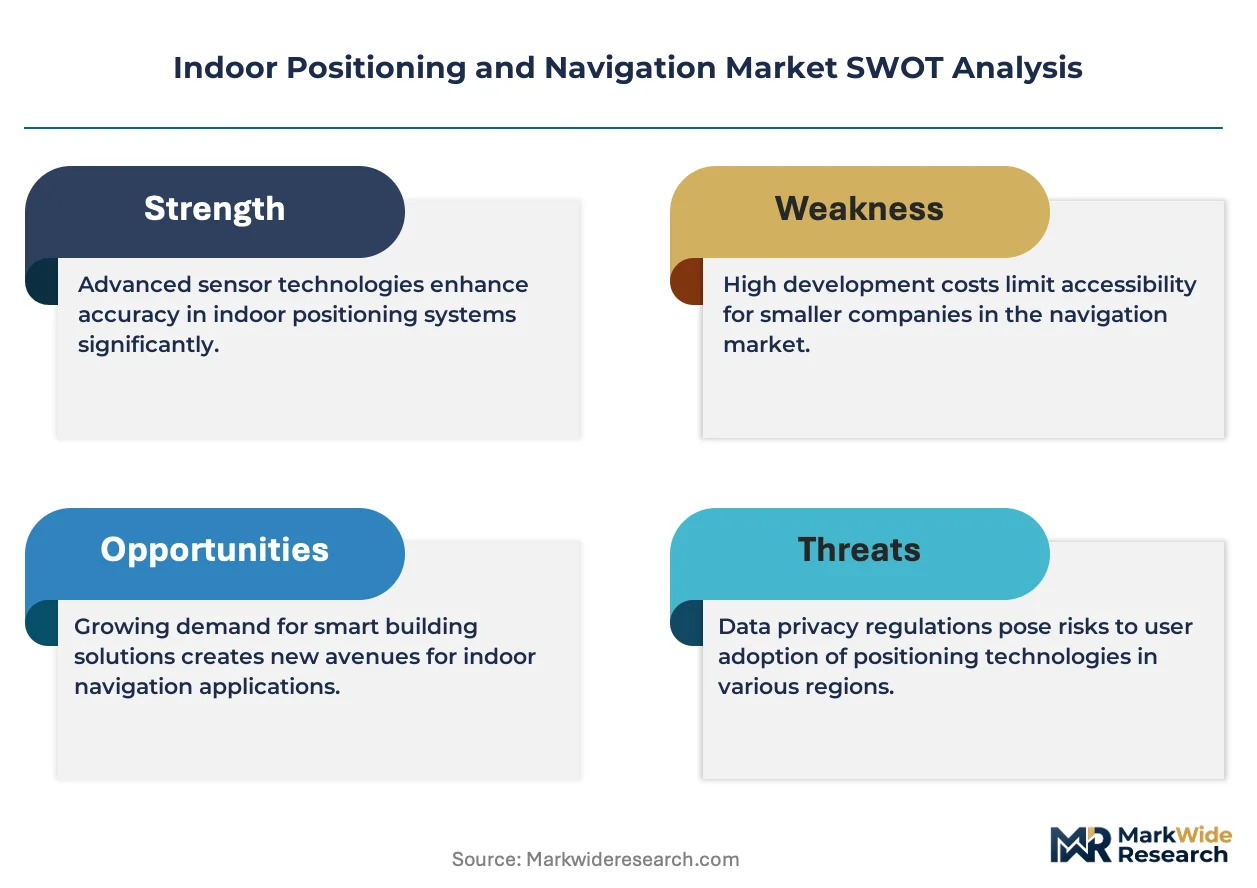
Data privacy regulations like Europe's GDPR heavily influence system design, requiring explicit user consent for personal location tracking. Concurrently, standards from bodies like the ISO and the FCC's rules on radio frequency spectrum allocation for UWB devices govern hardware interoperability and safety. The primary strategic decision for providers now revolves around balancing system accuracy and cost against evolving privacy compliance requirements.
Market Dynamics
The convergence of high-precision technologies like Ultra-Wideband with scalable, API-driven cloud platforms is the central force shaping the market. This combination is enabling new levels of accuracy and analytical depth in real-time asset and personnel tracking.
Growth Catalysts
- Industry 4.0 Adoption:Demand from Germany's advanced manufacturing and logistics sectors for real-time asset tracking and process optimization in smart factories is a primary catalyst for system deployment.
- Spectrum Allocation:The FCC's rules governing the radio frequency spectrum for UWB devices provide regulatory clarity, encouraging hardware development and investment in high-precision technologies in the United States.
- Technology Convergence:The integration of UWB with 5G networks creates a powerful infrastructure for low-latency, high-bandwidth data transmission, essential for large-scale industrial internet of things (IIoT) applications.
Market Restraints
- High Deployment Cost:The initial capital expenditure for installing high-accuracy systems using UWB or LiDAR infrastructure remains significantly higher than leveraging existing Wi-Fi or BLE networks, deterring some budget-sensitive enterprises.
- Data Privacy Compliance:Europe's GDPR imposes strict requirements for user consent and data anonymization in personal tracking applications, adding complexity and cost to system design and deployment.
- Integration Complexity:Interfacing modern positioning systems with legacy enterprise software, such as older Warehouse Management Systems (WMS), presents a significant technical hurdle and implementation delay for many organizations.
Strategic Opportunities
- Healthcare Applications:Significant opportunity exists in underpenetrated hospital environments for tracking high-value mobile medical equipment, optimizing patient flow, and enhancing staff safety through location-aware duress alerts.
- Digital Twin Fusion:Integrating indoor positioning data with digital twin platforms allows for the creation of dynamic, real-time virtual models of physical spaces, unlocking advanced simulation and predictive maintenance capabilities.
- Safety Mandates:Worker safety regulations, such as those enforced by OSHA in the US, create opportunities for solutions that monitor personnel location in hazardous industrial zones to automate safety alerts.
Industry Challenges
- Sensor Data Fusion:A key operational challenge is harmonizing and processing data from a diverse array of sensors like BLE, Wi-Fi, and UWB into a single, reliable position estimate without significant latency.
- Lack of Interoperability Standards:The absence of universal standards across different proprietary indoor positioning technologies can lead to vendor lock-in, hindering the ability to create scalable, multi-vendor ecosystems.
- Specialized Talent Scarcity:The market faces a shortage of engineers who possess a combined expertise in radio frequency engineering for technologies like UWB and cloud-native software development for analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Positioning and Navigation Market |
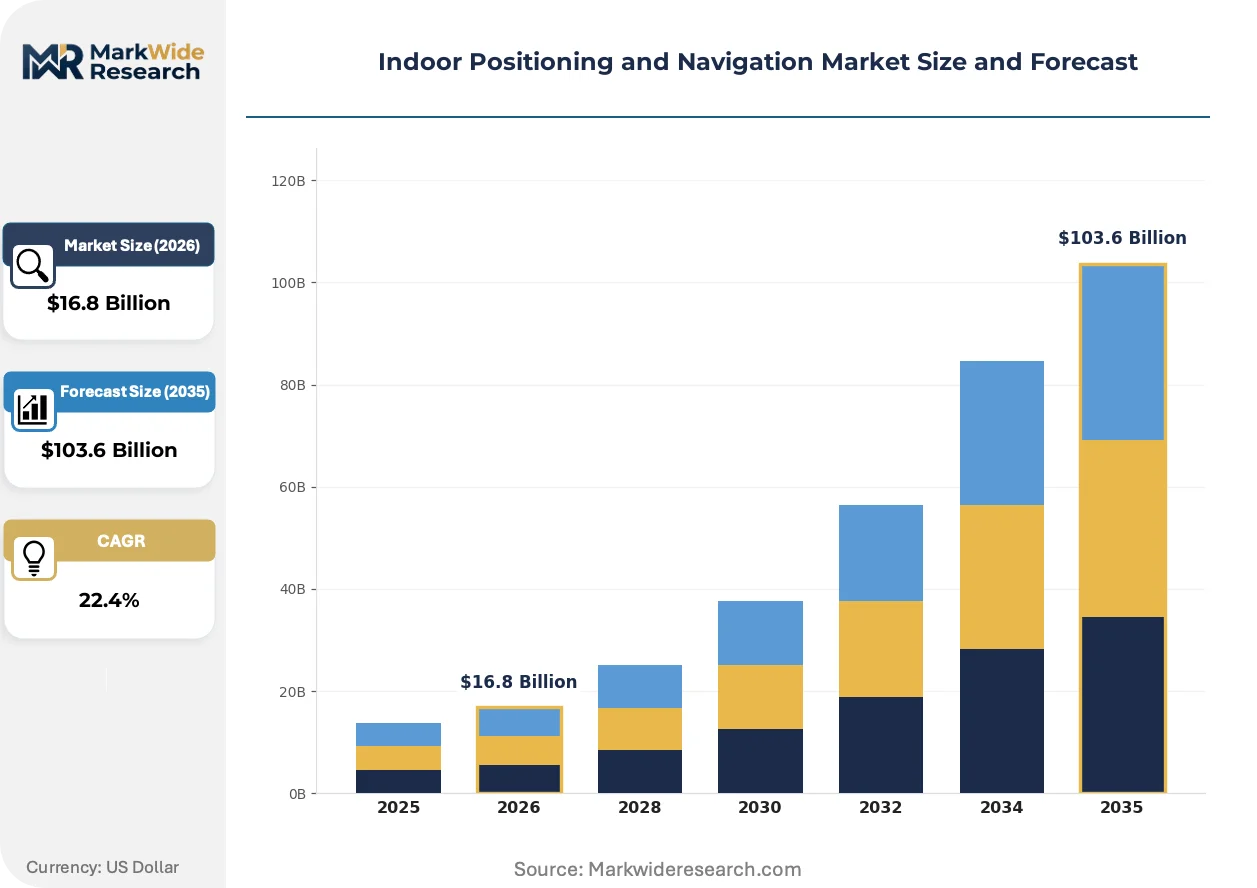
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $103.6 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wi-Fi, Bluetooth Low Energy, Ultra-Wideband, Magnetic Field, Inertial Sensors, LiDAR Application: Asset Tracking, Wayfinding, Workforce Management, Customer Engagement, Safety & Security, Inventory Control Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing End User Industry: Manufacturing Facilities, Airports, Warehousing, Educational Institutions, Museums, Convention Centers |
| Companies Covered | Apple Inc., Cisco Systems, Zebra Technologies, Google, Microsoft, Qualcomm Technologies, Siemens, HERE Technologies, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Positioning and Navigation Market Strategic Shifts & Innovations
The market’s evolution is defined by a shift from simple location pinpointing to sophisticated spatial intelligence. This transition depends on fusing multiple data sources to create context-aware analytics for operational decision-making.
Sensor fusion technology combines inputs from UWB, BLE, and inertial sensors to create a continuous and accurate position. Manufacturing and logistics firms are the primary adopters, using it to build dynamic digital replicas of their operations. This multi-modal approach is digitizing physical workflows, enabling predictive analytics for process optimization and asset management.
Europe's GDPR has become a de facto global standard, compelling developers to embed privacy-by-design principles into their systems. This regulation mandates clear user consent and data anonymization techniques, particularly for personal tracking. The healthcare sector is most impacted, navigating a complex web of rules including HIPAA in the US to protect patient location data.
A clear shift is visible from one-time hardware purchases towards procuring location data through consumption-based API models. This disrupts the business models of traditional hardware-focused vendors, creating an opening for cloud-native platform providers. This trend is most advanced in smart retail environments, where location analytics are integrated directly into customer engagement platforms.
Indoor Positioning and Navigation Market Segmentation
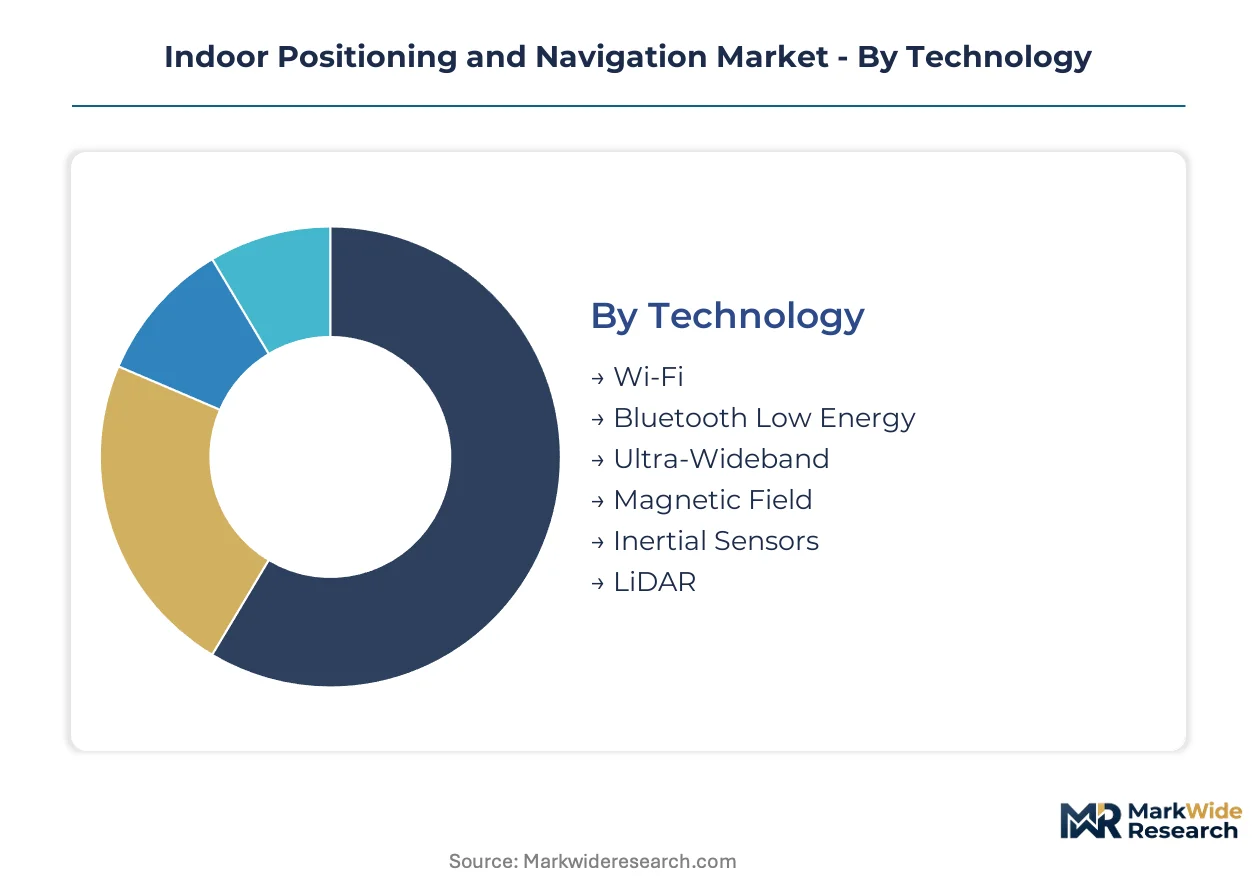
The Indoor Positioning and Navigation market's segmentation highlights the diverse technological approaches and end-user needs shaping its evolution. Understanding these distinct segments is crucial for providers to align their solutions with specific operational requirements and investment priorities across various industries.
Technology:
The turnover rate of underlying positioning technologies varies significantly, influencing investment cycles and upgrade paths.
- Ultra-Wideband:This technology provides highly precise location data, achieving sub-meter accuracy through short-duration radio pulses. Demand concentrates in manufacturing facilities for real-time asset tracking and Germany's advanced Industry 4.0 environments.
- Bluetooth Low Energy:BLE beacons emit signals detected by mobile devices, enabling proximity-based location services and wayfinding with moderate accuracy. Healthcare applications are driving its adoption for tracking mobile medical equipment and patient flow in US hospitals.
- Wi-Fi:Leveraging existing infrastructure, Wi-Fi positioning uses signal strength (RSSI) for broad area coverage and basic location analytics. Retail environments utilize Wi-Fi for customer engagement and foot traffic analysis.
- Magnetic Field:This method relies on anomalies in Earth's magnetic field, often used as a complementary technology for enhanced indoor navigation. It is primarily used in complex indoor environments where other signals are weak.
- Inertial Sensors:Accelerometers, gyroscopes, and magnetometers provide dead reckoning capabilities, maintaining position estimates when other signals are unavailable. This technology is critical for continuous tracking of personnel in industrial safety applications.
- LiDAR:Light Detection and Ranging creates detailed 3D maps of environments, offering high accuracy for static mapping and dynamic object detection. It supports advanced digital twin fusion platforms in large industrial complexes.
Wi-Fi technology dominates the installed base. Ultra-Wideband is where expansion concentrates.
Application:
The diverse applications of indoor positioning systems drive varied demand patterns across industries.
- Asset Tracking:This application monitors the real-time location of valuable equipment, tools, and inventory within defined indoor spaces. Manufacturing and logistics hubs in Germany are primary adopters for optimizing operational efficiency.
- Wayfinding:Wayfinding solutions guide individuals through complex indoor environments using interactive maps and real-time positioning data. Airports and large healthcare facilities utilize wayfinding to enhance visitor and patient experience.
- Workforce Management:Systems track personnel movement to optimize task allocation, monitor productivity, and ensure worker safety in industrial settings. OSHA regulations in the US encourage adoption for hazardous zone monitoring.
- Customer Engagement:Retailers use location data to deliver personalized promotions and analytics on customer behavior within stores. Smart retail environments are integrating these analytics directly into customer platforms.
- Safety & Security:This application provides location-aware alerts for emergencies, access control, and geofencing in restricted areas. Hospitals deploy these systems for staff safety and duress alerts.
- Inventory Control:Indoor positioning enhances inventory accuracy and reduces search times by precisely locating items in warehouses and stockrooms. Warehousing operations are the primary beneficiaries of this application.
Asset Tracking applications are currently experiencing the most significant expansion, driven by industrial efficiency needs.
Deployment Model:
Scalability and upfront capital expenditure define the adoption trajectories across different deployment models.
- Cloud-Based:These models host positioning software and data on remote servers, offering superior scalability and lower upfront costs. Small and medium-sized enterprises increasingly favor cloud solutions due to their operational flexibility.
- On-Premises:Traditional deployments involve installing and managing all hardware and software within the client's physical location. Organizations with strict data security requirements or legacy infrastructure often maintain on-premises systems.
- Hybrid:This model combines elements of both cloud and on-premises deployments, balancing data security with scalability. Large enterprises often adopt hybrid approaches for specialized applications.
- Edge Computing:Processing location data closer to the source reduces latency and bandwidth requirements, especially for real-time industrial applications. This model supports critical IIoT applications in manufacturing.
Cloud-Based models are increasingly preferred for their flexibility and reduced infrastructure burden, enabling wider adoption.
End User Industry:
The intensity of spatial data requirements dictates the sophistication of systems deployed across various end-user industries.
- Manufacturing Facilities:These facilities utilize indoor positioning for real-time asset tracking, process optimization, and worker safety in complex production environments. Germany's Industry 4.0 initiatives drive significant demand in this sector.
- Warehousing:Logistics hubs and distribution centers deploy these systems for inventory management, forklift tracking, and optimizing goods movement. This sector relies on precise location data for operational efficiency.
- Airports:Airports implement indoor positioning for passenger wayfinding, baggage tracking, and optimizing ground staff operations. Large international airports are early adopters of advanced navigation systems.
- Educational Institutions:Universities and schools use indoor positioning for asset management, campus navigation, and improving security responses. These institutions manage diverse mobile assets across their campuses.
- Museums:Museums employ indoor positioning for visitor guidance, interactive exhibits, and tracking valuable artifacts. Cultural institutions enhance visitor experience through location-aware content delivery.
- Convention Centers:Large venues use these systems for attendee navigation, booth analytics, and managing event logistics. Real-time insights into crowd movement are critical for event management.
Manufacturing Facilities and Warehousing are seeing substantial investment, indicating strong future potential for integrated solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial exports of advanced manufacturing equipment to the United States drive significant demand for indoor positioning systems. This market's regional dynamics reflect specific industrial needs and regulatory frameworks across key economic zones. Localized technological advancements and policy support further influence adoption patterns.
Germany
Germany's Industry 4.0 initiatives propel demand for real-time asset tracking in smart factories and logistics hubs. The country's strong regulatory environment, including GDPR, influences system design for data privacy. Bavarian manufacturing clusters, particularly around Munich, demonstrate high adoption for process optimization.
United States
The United States sees strong demand from healthcare for tracking mobile medical equipment and from industrial safety applications. FCC rules on radio frequency spectrum allocation for UWB devices provide regulatory clarity. Silicon Valley and other tech hubs drive innovation in cloud-native platforms for location analytics.
China
China's vast manufacturing sector and rapid urbanization fuel demand for large-scale asset tracking and smart building applications. The national government's focus on industrial digitization and smart city development supports deployment. Industrial zones in the Yangtze River Delta integrate advanced positioning for operational efficiency.
Japan
Japanese manufacturers increasingly adopt indoor positioning for optimizing production lines and inventory management in advanced facilities. METI initiatives encourage the integration of IoT technologies in industrial settings. Tokyo's dense urban environment also presents opportunities for complex indoor navigation solutions.
India
India's expanding logistics and warehousing sectors drive demand for efficient inventory control and workforce management systems. Government programs like "Make in India" promote domestic manufacturing, increasing the need for industrial automation. Bengaluru's tech ecosystem develops cloud-based solutions for varied industrial clients.
Indoor Positioning and Navigation Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in indoor positioning. The market structure exhibits a tiered approach, with established technology giants alongside specialized hardware and software providers. Strategic archetypes include infrastructure-centric providers, platform developers, and application-focused integrators. Dominant competitive moves involve strategic partnerships to expand ecosystem reach and continuous technology licensing to enhance accuracy.
Infrastructure-centric providers like Cisco Systems leverage their extensive Wi-Fi networks to deliver location analytics, particularly for enterprise clients seeking integrated solutions across their facilities. Zebra Technologies exemplifies a hardware-focused archetype, specializing in ruggedized devices and software tailored for demanding warehousing and manufacturing environments where durability and precision are paramount. Google, through its Android ecosystem and extensive Maps APIs, represents a platform-driven approach, dominating consumer-facing applications and creating a distinct market segment for mobile location services. These companies anchor different segments of the market by offering distinct value propositions and catering to varied operational requirements, from industrial tracking to personal navigation.
| Leading Market Players |
|---|
| Apple Inc. |
| Cisco Systems |
| Zebra Technologies |
| Microsoft |
| Qualcomm Technologies |
| Siemens |
| HERE Technologies |
| Hewlett Packard Enterprise |
| Others |
Cost & Logistics Intelligence
Germany's Industry 4.0 manufacturing capacity utilization drives supplier behavior, particularly for high-precision UWB systems, influencing their pricing posture in the indoor positioning market.
Pricing Analysis
The pricing gap between advanced Ultra-Wideband (UWB) solutions and established Wi-Fi/BLE systems reflects differing value propositions. Consumption-based API models are becoming the dominant pricing structure for cloud-native platforms, displacing one-time hardware purchases. Price differentiation stems from system accuracy and the level of customization required for complex industrial integrations. Pricing pressure for high-accuracy UWB and LiDAR systems arises from their significant initial deployment costs, deterring budget-sensitive small and medium-sized enterprises, which favor cloud solutions. Large industrial complexes, however, prioritize performance over initial expenditure.
Supply Chain Analysis
Single-source vulnerability for specialized UWB and LiDAR components presents a notable supply chain risk for high-precision indoor positioning systems. Geographic supply concentrates in China for manufacturing, the United States for advanced chip design, and Japan for precision optical components. The market relies on a steady supply of radio frequency transceivers, inertial sensors, and microcontrollers. Distribution runs through direct enterprise sales for large industrial clients and cloud-native platform providers offering API-driven solutions, often supported by regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The indoor positioning market is experiencing a cyclical recovery, driven by renewed enterprise investment in industrial automation and digital transformation initiatives across manufacturing and logistics.
For Market Incumbents: Entrench existing client relationships by offering comprehensive, API-driven solutions that integrate seamlessly with legacy enterprise software. Expand ecosystem reach through strategic partnerships with cloud-native platform providers, countering the threat of specialized software entrants. Invest heavily in R&D for advanced sensor fusion technologies, particularly combining UWB with inertial sensors, to maintain accuracy leadership. This proactive R&D ensures continued relevance against evolving precision demands.
For New Entrants and Emerging Players: Underpenetration in hospital environments presents a significant white-space opportunity for new indoor positioning entrants. Target healthcare applications, focusing on tracking high-value mobile medical equipment and optimizing patient flow, particularly within US hospitals. Another white-space target includes educational institutions for asset management and campus navigation. A compelling go-to-market angle involves offering cloud-based, privacy-by-design solutions that simplify compliance with regulations like HIPAA and GDPR.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform providers offering API-driven indoor positioning solutions. The market demonstrates strong long-term viability over the next 5-10 years, driven by sustained industrial digitization and smart building initiatives. Target acquisition archetypes include specialized software firms with expertise in sensor data fusion and robust privacy-by-design frameworks. The signal to watch for accelerated growth is widespread enterprise adoption of digital twin platforms, leveraging real-time spatial intelligence.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating API-driven cloud platforms enables scalable, cost-effective indoor positioning solutions for small and medium-sized enterprises. |
| Strategic Partnerships | Forming alliances with 5G network providers and hardware specialists expands market reach for integrated UWB solutions. |
| Technology Development | Investing in advanced UWB and LiDAR sensor fusion improves sub-meter accuracy for industrial asset tracking. |
| Vertical Market Specialization | Targeting underpenetrated healthcare applications provides new revenue streams for mobile medical equipment tracking. |
| Regulatory Compliance | Implementing privacy-by-design principles addresses GDPR and HIPAA requirements for personal location data. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted to inform this analysis through primary interviews. Key stakeholders included enterprise CTOs, logistics managers, solution architects, and hardware engineers. This primary input was rigorously validated against secondary data from company filings, industry association reports, and technology whitepapers. The approach utilized both bottom-up market sizing and top-down validation, triangulating data for robust insights.
Market forecasts were calibrated using a multi-factor analytical framework across the analysis window. Segmentation dimensions modeled included technology, application, deployment model, end-user industry, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical adoption trends and projected technology integration rates. Industry-specific forecast inputs incorporated UWB device proliferation rates and 5G network rollout schedules, particularly in industrial zones.
Macroeconomic conditions sit as an overlay; deviation in global industrial investment cycles or supply chain stability would shift the trajectory. Forecasts reflect underlying assumptions regarding technology adoption rates and evolving regulatory environments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Residential Water Leak Detection System Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Global RFID Market
Sensors
IO Link Market
Sensors
Wireless Synchronized Clocks Market
Sensors
Heat Stress Meter Market
Sensors
Beacon Market
Sensors
Transportation Sensors Market
Sensors
Weigh-In-Motion System Market
Sensors
Indoor Location Market
Sensors
Digital Direction Finder Market
Sensors
Mobile Lidar Scanner Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Temperature Data Loggers Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Conveyor Monitoring Market