
 5G Transport Networks Market | 2026-2036
5G Transport Networks Market Size, Share, and Industry Trends Forecast 2026-2036
5G Transport Networks Market Outlook
Software-defined transport orchestration is decoupling network control from proprietary hardware, enabling operators to procure white-box routers and switches independently of vendor lock-in. Huawei Technologies Co. Ltd leverages its integrated portfolio spanning microwave and optical fiber domains to anchor large-scale deployments across multiple continents. Cisco Systems Inc. competes through merchant silicon-based routing platforms that interoperate with multivendor environments. Nokia Corporation differentiates via its PSE-6s coherent optics technology, which sustains leadership in high-capacity long-haul transport segments.
5G transport networks comprise the fronthaul, midhaul, and backhaul infrastructure that connects radio access network elements to core network functions, typically operating at latency thresholds below one millisecond for critical control-plane traffic and leveraging technologies such as eCPRI encapsulation over 25G/100G Ethernet interfaces. Optical fiber transport dominates capital deployment for dense urban clusters where fiber reach already exists, while microwave transmission equipment retains structural importance in suburban and rural topographies where trenching costs prohibit fiber extension. Millimeter wave backhaul represents the fastest-growing technology segment as operators seek to unlock 28 GHz and 39 GHz spectrum for high-capacity, short-distance links between small cells and aggregation points.
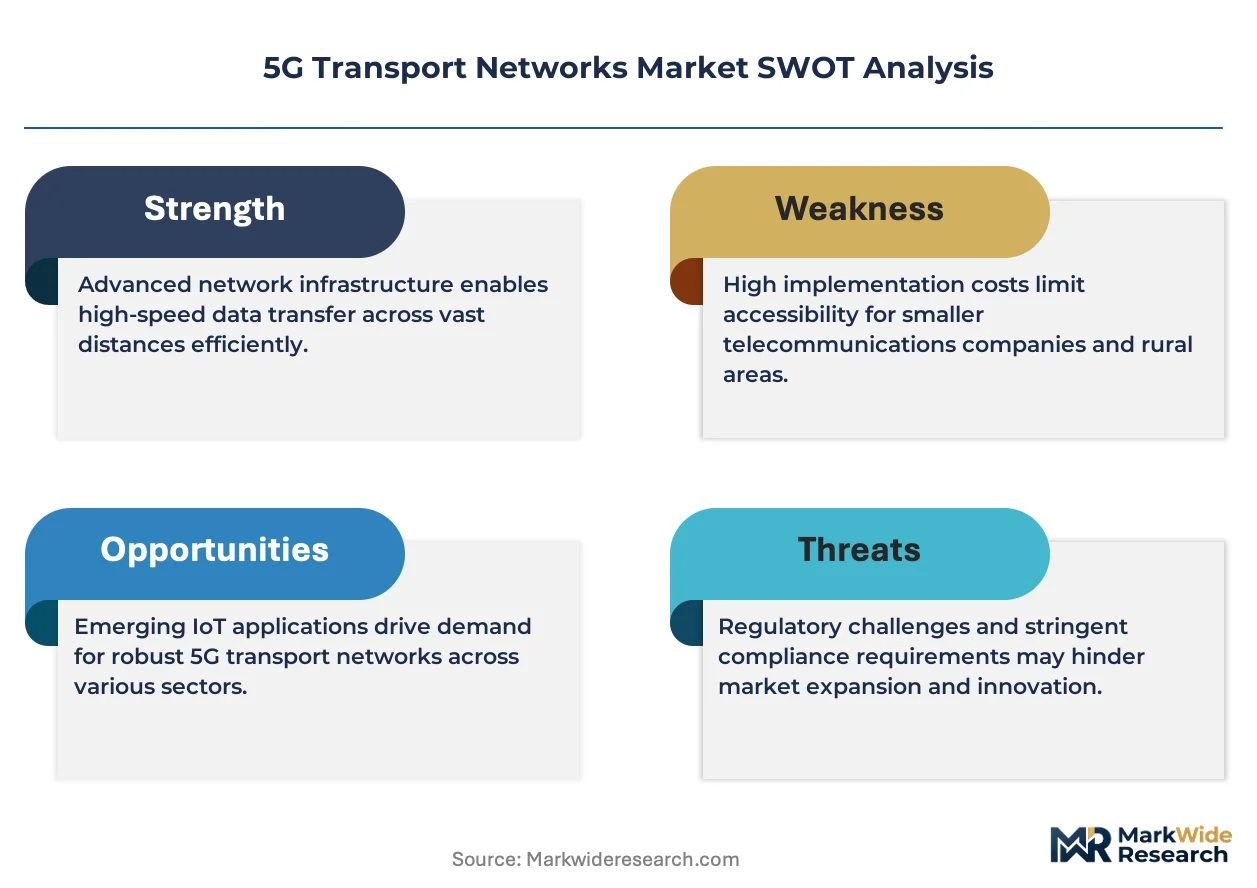
The Federal Communications Commission in the United States, the Ministry of Industry and Information Technology in China, and the European Telecommunications Standards Institute collectively shape equipment certification timelines, spectrum allocation rules, and interoperability mandates that determine vendor market access. National regulators are tightening supply-chain security requirements and source-code disclosure rules, which constrains procurement options for operators in sensitive infrastructure markets. Stakeholders must monitor evolving open transport interface standards and spectrum reallocation proceedings to anticipate shifts in equipment qualification pathways and deployment economics.
Market Dynamics
Open RAN disaggregation is fragmenting procurement patterns across fronthaul, midhaul, and backhaul segments. Operators now source white-box transport hardware separately from control-plane software, compressing vendor margins while expanding supplier pools.
Growth Catalysts
- Small-cell densification mandates:The FCC's spectrum auction proceeds require rapid urban 5G buildouts, forcing operators to multiply aggregation node density by 4-5x in major metropolitan clusters.
- eCPRI protocol adoption:Ethernet-based fronthaul interfaces are replacing proprietary CPRI, slashing interface costs and enabling multivendor radio-transport combinations.
- National broadband targets:Germany's Gigabit Strategy 2030 legally obliges universal 5G coverage, accelerating rural backhaul investments through subsidized microwave and fiber programs.
Market Restraints
- Fiber trenching economics:Urban construction costs exceed $80,000 per kilometer in dense European city centers, blocking all-fiber strategies for midhaul extensions.
- Geographic vendor concentration:Chinese equipment suppliers dominate coherent optical DSP chip production, creating single-source dependencies for 400G+ long-haul interfaces.
- Millimeter-wave propagation limits:28 GHz and 39 GHz signals attenuate rapidly through precipitation and foliage, constraining link distances to 200-300 meters in non-line-of-sight conditions.
Strategic Opportunities
- India's delayed 5G mid-band rollout:TRAI's spectrum pricing disputes have postponed large-scale deployment, creating a compressed catch-up window for transport infrastructure vendors.
- Network slicing orchestration:Converged SDN control planes spanning radio and transport layers enable guaranteed latency tiers for industrial automation and vehicular applications.
- EU Green Deal alignment:The CSRD's Scope 3 emissions disclosure requirements favor energy-efficient coherent pluggable optics over standalone transponder shelves in aggregation sites.
Industry Challenges
- Optical transport engineering scarcity:Coherent modulation design and DSP firmware development skills concentrate within a handful of specialized engineering teams across the vendor landscape.
- Multi-generational equipment interoperability:Operators must synchronize timing and synchronization distribution across legacy TDM, packet-based, and new flexible Ethernet transport layers without service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Transport Networks Market |
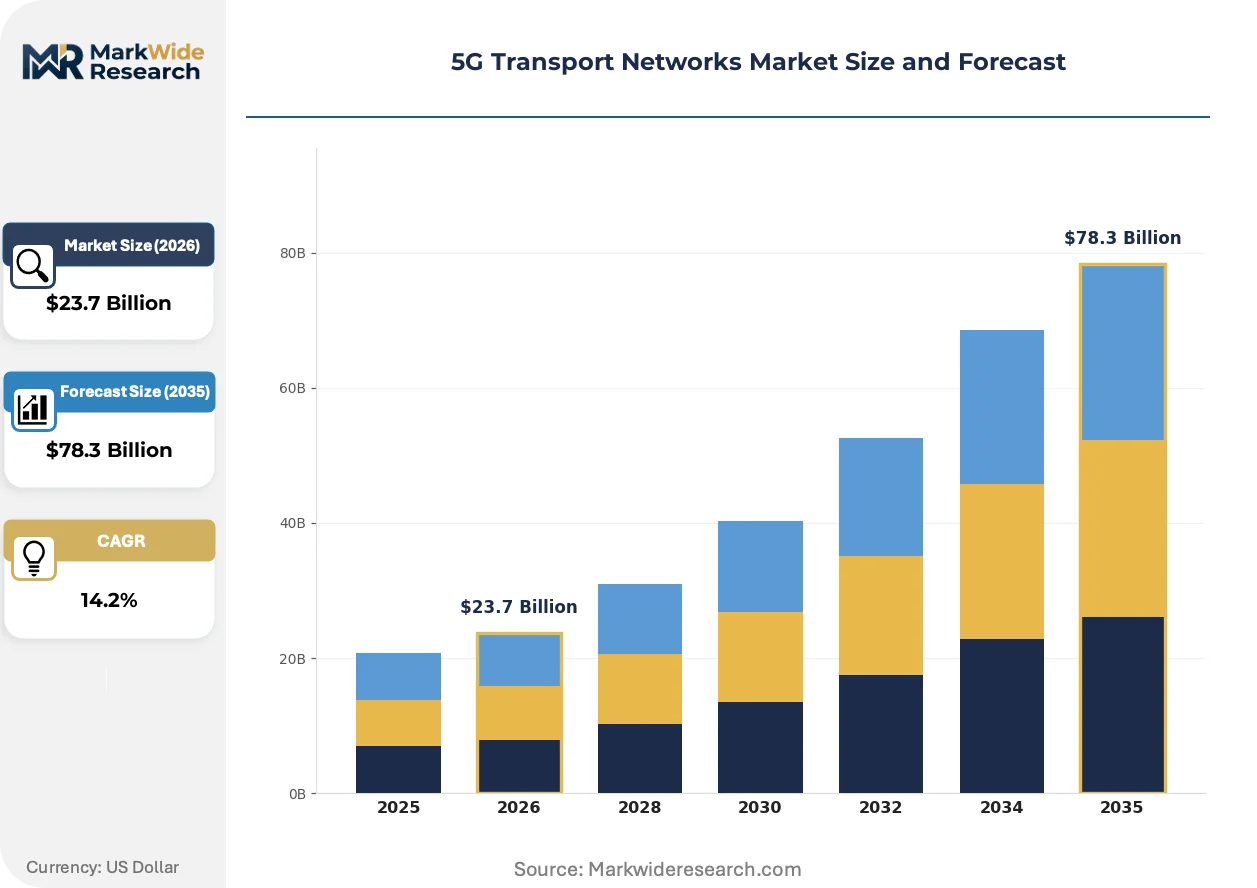
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microwave, Optical Fiber, Millimeter Wave, Satellite Component: Routers, Switches, Transmission Equipment, Network Management Tools End User: Telecommunications Providers, Enterprises, Government Agencies, Resellers Service Type: Network Planning, Implementation Services, Maintenance Services, Consulting |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Huawei Technologies Co. Ltd, Cisco Systems Inc., NEC Corporation, ZTE Corporation, FUJITSU, Nokia Corporation, Samsung Electronics Co. Ltd, Qualcomm Technologies Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Transport Networks Market Strategic Shifts
Transport architectures are converging toward software-defined control planes that abstract hardware heterogeneity. This convergence is compressing equipment refresh cycles and forcing incumbents to open proprietary interfaces.
Coherent pluggable optics is integrating DSP functions directly into QSFP-DD and OSFP form factors. Mobile operators are adopting these modules for 400G ZR and ZR+ metro applications to collapse standalone transponder shelves into router line cards. This integration is eliminating dedicated optical layer equipment from aggregation sites and reallocating capex toward fiber infrastructure.
The EU's Cyber Resilience Act mandates vulnerability disclosure and secure-by-design requirements for network equipment placed on the European market. Manufacturers must now maintain software bills of materials and patch transparency across product lifecycles exceeding fifteen years. Transport vendors serving European operators are restructuring development processes to embed automated security testing and attestation documentation.
Consolidated procurement consortia are displacing operator-specific vendor negotiations. Shared infrastructure entities in the United States and Germany now aggregate transport equipment demand across multiple mobile network operators, extracting volume pricing and standardizing technical specifications. This concentration is marginalizing smaller equipment vendors unable to meet consortium-scale qualification and liability requirements.
5G Transport Networks Market Segmentation
Segmentation in 5G transport networks reveals distinct capital deployment patterns across infrastructure layers. Procurement decisions diverge sharply between fiber-heavy urban clusters and microwave-dependent rural extensions.
Technology:
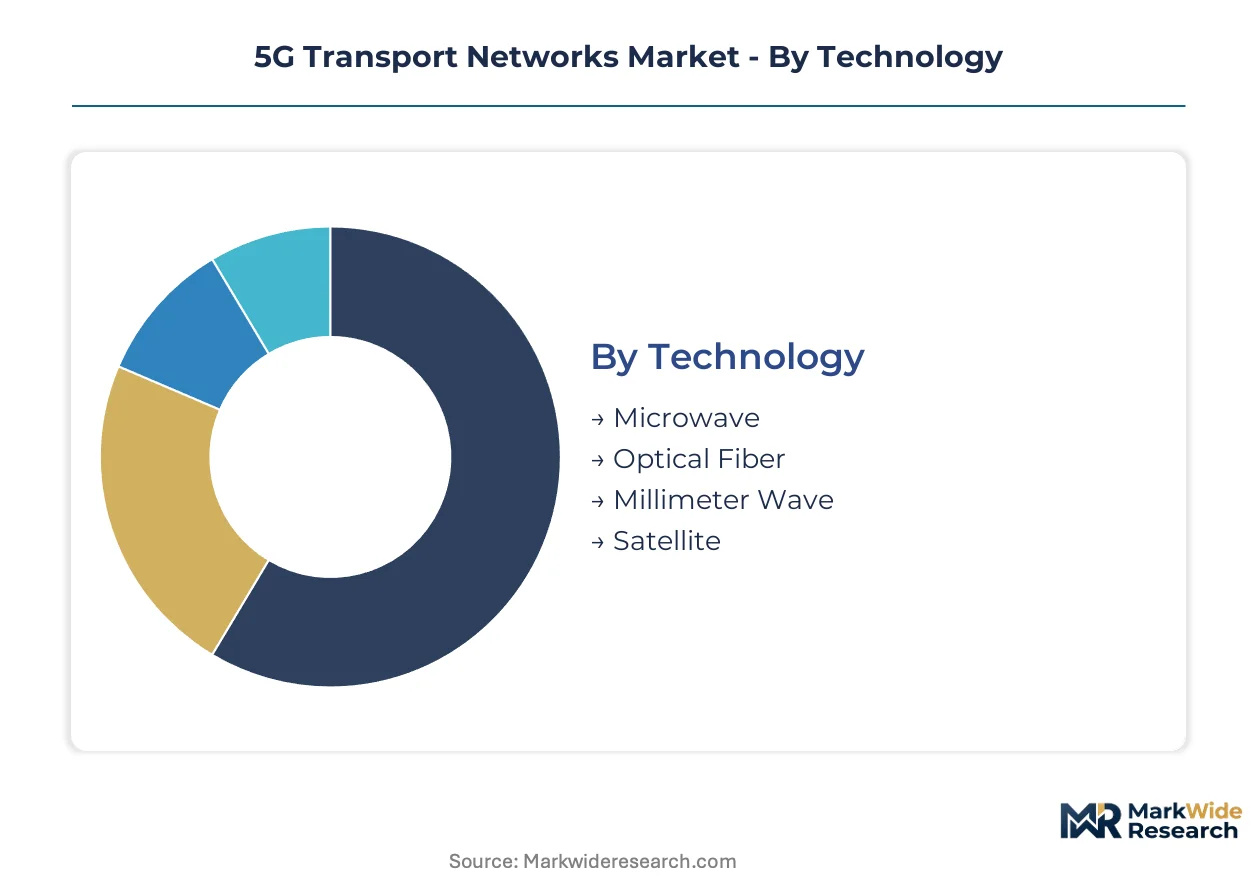
Capital intensity varies dramatically across transport mediums, with fiber trenching consuming 60-70% of total deployment budgets in dense metropolitan areas while wireless alternatives preserve liquidity for spectrum acquisition.
- Microwave:Point-to-point radio links operating from 6 GHz to 80 GHz bands. Demand concentrates across suburban India and rural Germany where the Gigabit Strategy 2030 subsidizes wireless backhaul to bypass trenching economics. Legacy equipment from previous cellular generations creates upgrade pressure for higher-order modulation schemes.
- Optical Fiber:Single-mode fiber infrastructure with coherent 400G/800G interfaces for fronthaul and backhaul aggregation. Chinese and US operators deploy this for dense urban small-cell clusters where latency budgets below one millisecond mandate direct fiber reach to radio heads.
- Millimeter Wave:28 GHz and 39 GHz wireless links for short-distance, high-capacity connectivity. FCC spectrum auctions in the United States accelerate procurement for stadium and transportation hub deployments.
- Satellite:Low-earth orbit and geostationary backhaul for remote coverage extension. Mining operations in Western Australia and maritime corridors drive specialized demand outside terrestrial infrastructure reach.
Optical fiber absorbs the bulk of installed capacity; millimeter wave is expanding most quickly.
Component:
Hardware procurement is fragmenting as Open RAN disaggregation separates control-plane software from forwarding elements.
- Routers:Carrier-grade IP/MPLS and segment routing platforms for aggregation and core-facing interfaces. Merchant silicon-based designs from Cisco and Arista Networks gain traction in US operator labs seeking multivendor interoperability.
- Switches:Ethernet switching fabrics for fronthaul aggregation with 25G/100G port densities. Data center interconnect requirements from hyperscale cloud providers reshape form factor priorities toward 400G and 800G speeds.
- Transmission Equipment:Optical transponders, amplifiers, and multiplexers for wavelength-division multiplexing. Coherent pluggable optics in QSFP-DD form factors are collapsing standalone transponder shelves into router line cards.
- Network Management Tools:Software-defined orchestration platforms for transport layer provisioning. EU Cyber Resilience Act mandates are forcing vendors to restructure development processes for automated security testing and software bill of materials maintenance.
Routers and switches together dominate procurement volumes; network management tools are climbing the fastest as operators prioritize operational automation.
End User:
Customer archetypes determine contract structures, with government tenders demanding fifteen-year lifecycle support while enterprises favor outcome-based service agreements.
- Telecommunications Providers:Mobile network operators building fronthaul, midhaul, and backhaul infrastructure. Verizon, AT&T, and T-Mobile in the United States account for concentrated demand following mid-band spectrum acquisitions.
- Enterprises:Manufacturing, logistics, and energy companies deploying private 5G networks. German automotive facilities leverage 3.7-3.8 GHz local licenses for deterministic transport to robotic assembly lines.
- Government Agencies:Defense, public safety, and transportation authorities with hardened infrastructure requirements. Supply-chain security rules constrain vendor pools for sensitive installations.
- Resellers:Systems integrators and value-added distributors serving mid-tier operators. Consolidated procurement consortia in Germany and the United States are marginalizing smaller resellers unable to meet consortium-scale qualification thresholds.
Telecommunications providers command the largest share of capital deployment; enterprises are gaining share fastest as private network deployments accelerate.
Service Type:
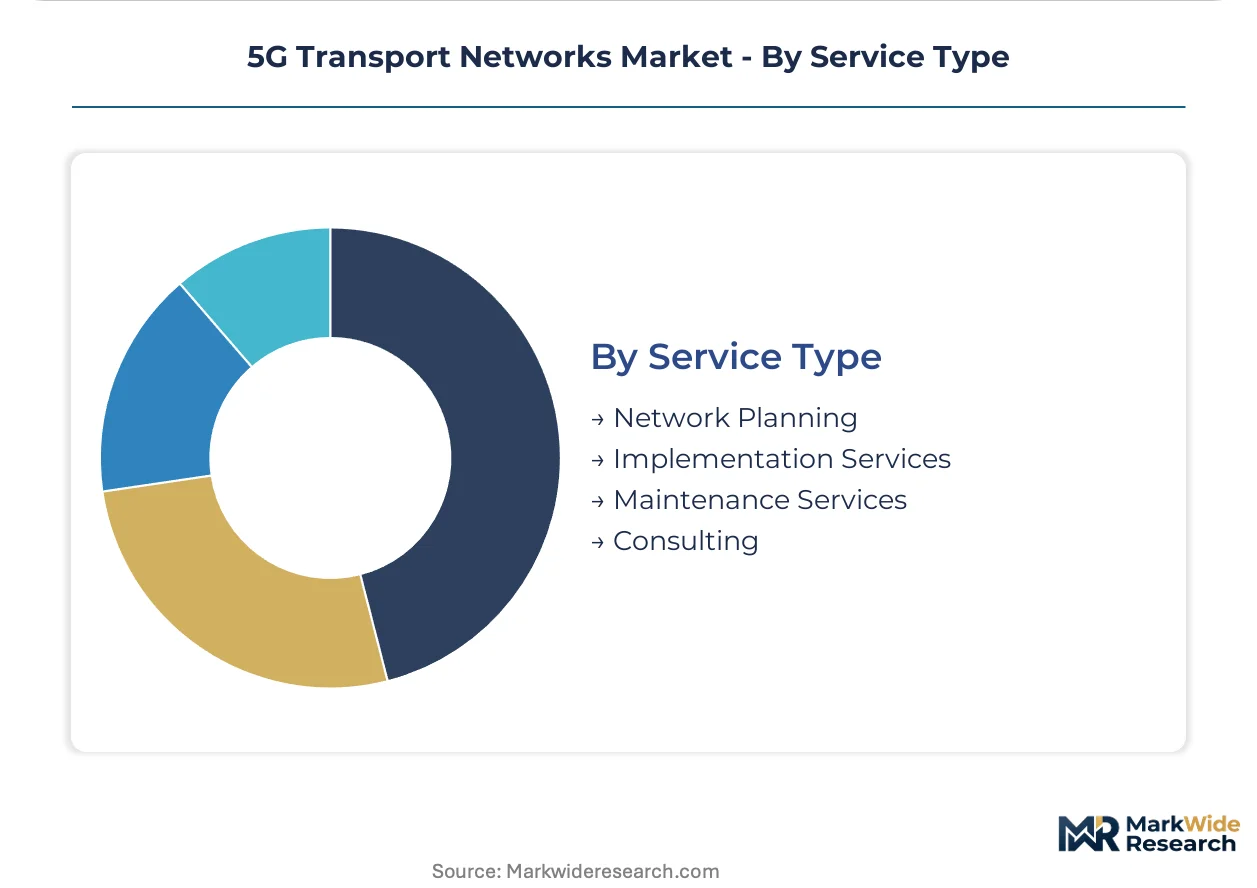
Service revenue distribution reflects the operational maturity of operator engineering teams and their appetite for managed service outsourcing.
- Network Planning:Radio frequency engineering, fiber route design, and capacity modeling. Indian operators delayed by TRAI spectrum pricing disputes are compressing planning cycles to accelerate catch-up deployment.
- Implementation Services:Physical installation, commissioning, and integration testing. Labor shortages in optical transport engineering concentrate demand with specialized contractor pools.
- Maintenance Services:Preventive maintenance, spare parts management, and field repair. Long-term service contracts now embed EU CSRD Scope 3 emissions disclosure requirements.
- Consulting:Architecture design, vendor selection, and migration strategy. Open RAN interface complexity is expanding consulting engagements for multivendor integration planning.
Implementation services capture the largest service revenue pool; consulting is expanding most rapidly as architectural disaggregation multiplies integration complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in China, South Korea, and Japan while network deployment spending clusters in the United States, Germany, and India. This geographic split between production and consumption shapes trade flows and regulatory diplomacy.
United States
Verizon, AT&T, and T-Mobile drive fronthaul expansion following mid-band spectrum acquisitions. FCC auction mandates require accelerated urban small-cell densification. Dallas-Fort Worth and Chicago metro clusters see concentrated aggregation node deployment to meet coverage deadlines.
China
MIIT spectrum allocations and national broadband targets propel massive fiber and microwave procurement. State-owned operators execute coordinated transport buildouts across tier-one cities. Shenzhen and Shanghai manufacturing bases supply coherent optical components for domestic and export markets.
Germany
The Gigabit Strategy 2030 legally obliges universal 5G coverage, accelerating rural backhaul investments. Subsidized microwave programs bypass prohibitive urban trenching costs. Bavaria and North Rhine-Westphalia industrial zones deploy deterministic transport for automated manufacturing.
India
TRAI spectrum pricing disputes postponed large-scale deployment, creating compressed catch-up demand. Reliance Jio and Bharti Airtel now accelerate transport procurement to close infrastructure gaps. Mumbai and Bangalore urban clusters prioritize millimeter-wave backhaul for stadium and hub deployments.
Japan
METI 5G acceleration programs fund private network transport for manufacturing and logistics. NTT DOCOMO and KDDI expand fronthaul in Tokyo-Osaka corridors. Yokohama and Nagoya automotive facilities leverage low-latency transport for robotic assembly integration.
5G Transport Networks Market Competitive Environment
Capital-heavy integrated equipment producers compete with asset-light software specialists across control-plane and forwarding-element boundaries. The vendor landscape exhibits tiered consolidation: three to four full-stack suppliers anchor high-volume operator contracts, while niche players populate open interface ecosystems. Strategic archetypes include vertically integrated optical-microwave portfolios, merchant silicon-based routing platforms, and coherent optics specialists. Dominant competitive moves center on open RAN interface certification and coherent pluggable optics integration.
Within the integrated equipment tier, Huawei Technologies Co. Ltd and ZTE Corporation represent Chinese state-linked full-stack suppliers spanning radio and transport domains. Nokia Corporation anchors European coherent optics leadership. Cisco Systems Inc. exemplifies merchant silicon-based routing platforms targeting multivendor interoperability. These three occupy distinct strategic positions: integrated portfolio breadth, specialized optical technology depth, and software-centric disaggregation respectively.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Huawei Technologies Co. Ltd |
| Cisco Systems Inc. |
| NEC Corporation |
| ZTE Corporation |
| FUJITSU |
| Nokia Corporation |
| Samsung Electronics Co. Ltd |
| Qualcomm Technologies Inc |
| Others |
Value Chain & Pricing Dynamics
Optical transport engineering talent concentrates in Shenzhen and Shanghai manufacturing corridors, compressing labor-cost differentials between premium coherent optics and standard microwave equipment into narrower pricing-tier spreads than component quality alone would justify.
Pricing Analysis
Margin tightening in coherent pluggable optics reflects merchant silicon commoditization as Broadcom and Marvell DSP designs displace proprietary ASICs. Three-tier pricing structure across premium, standard, and economy levels separates PSE-6s-enabled 800G long-haul interfaces from 400G ZR metro modules and legacy 100G fixed transponders. Price differentiation hinges on DSP firmware customization depth and Open RAN interface certification status. Rural telecommunications providers exhibit highest price sensitivity, prioritizing subsidized microwave backhaul over fiber trenching investments.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment patterns for coherent optical components. Manufacturing concentrates in China, South Korea, and Japan, with Shenzhen and Shanghai fabs supplying DSP chips, indium phosphide modulators, and packaged transceivers. Raw material dependencies span rare earth elements for optical amplifiers, high-purity silicon for photonic integrated circuits, and copper for electrical interconnects. Single-source vulnerability in coherent DSP production creates supply chain risk. Distribution runs through carrier-direct procurement consortia and specialized optical component distributors serving mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as Open RAN disaggregation fragments procurement volumes and compresses vendor margins, forcing sub-scale equipment suppliers toward exit or acquisition.
For Market Incumbents: Lock in long-term service contracts with consolidated procurement consortia in Germany and the United States to defend installed base revenue against merchant silicon-based routing platforms. Deepen backward integration into coherent DSP design through captive engineering teams in Shenzhen or strategic alliances with Broadcom, insulating margin pressure from merchant silicon commoditization. For New Entrants and Emerging Players: The price-point gap between premium Nokia PSE-6s deployments and economy-tier microwave backhaul creates entry space for coherent pluggable optics specialists targeting 400G ZR metro aggregation. Focus on India's compressed catch-up deployment window where TRAI spectrum resolution triggers urgent transport procurement. Pursue systems integrator partnerships with value-added resellers serving mid-tier operators excluded from consortium-scale contracts. For Investors and Strategic Acquirers: Re-rating potential sits with coherent optics specialists possessing Open RAN interface certification and QSFP-DD form factor roadmaps given EU Cyber Resilience Act compliance requirements extending product lifecycles. Target acquisition archetypes include engineering-heavy teams with DSP firmware capabilities and established operator lab relationships. Monitor FCC spectrum auction completion timelines as inflection indicators for fronthaul capital deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interface Certification | MIIT and ETSI interoperability mandates determine vendor market access across Chinese and European operator procurement. |
| Coherent Pluggable Optics Integration | QSFP-DD and OSFP form factors collapse standalone transponder shelves into Cisco and Arista router line cards. |
| Subsidized Rural Microwave Programs | Germany's Gigabit Strategy 2030 funds bypass trenching economics in Bavaria and North Rhine-Westphalia industrial zones. |
| Merchant Silicon Routing Platforms | Broadcom and Marvell DSP designs enable multivendor interoperability for US operator lab qualifications. |
| EU Cyber Resilience Act Compliance | Software bill of materials maintenance and automated security testing restructure Nokia and Ericsson development processes. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with transport network architects, optical component procurement managers, DSP firmware engineering directors, and Open RAN interoperability lab leads. FCC auction records, MIIT spectrum allocation notices, ETSI standardization documents, and operator capex disclosures provided demand-side validation. Bottom-up equipment shipment analysis triangulated against top-down operator infrastructure spending models.
Data-stream reconciliation across fronthaul, midhaul, and backhaul deployment databases established segment-level baselines. The analytical framework modeled technology transitions, component disaggregation patterns, and regional regulatory clusters throughout the forecast period. CAGRs derived from equipment shipment trajectories, spectrum auction completion schedules, and national broadband target enforcement timelines. Forecast inputs incorporated eCPRI adoption curves, coherent pluggable optics penetration rates, and consolidated procurement consortium formation velocity.
Inputs from operator procurement databases and vendor shipment records were available through the study window; gaps in private network deployment metrics and enterprise 5G transport specifications introduce uncertainty bands around segment splits. Forecasts reflect documented assumptions regarding spectrum auction timing, subsidy program continuation, and Open RAN interface standardization progress. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Promotional Sms Market
Telecommunications
Costa Rica Telecom Market
Telecommunications
Vietnam Telecom Market
Telecommunications
Global Fixed-Mobile Convergence Market
Telecommunications
Managed Mobility Services (MMS) Market
Telecommunications
IoT Telecom Services Market
Telecommunications
Egypt Telecom Tower Market
Telecommunications
Peru Telecom Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
5G Fronthaul and Backhaul Equipment Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Cambodia Telecom Market
Telecommunications
Thailand Telecom Market
Telecommunications
Iceland Telecom Market