
 Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market | 2026-2036
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market Foresight
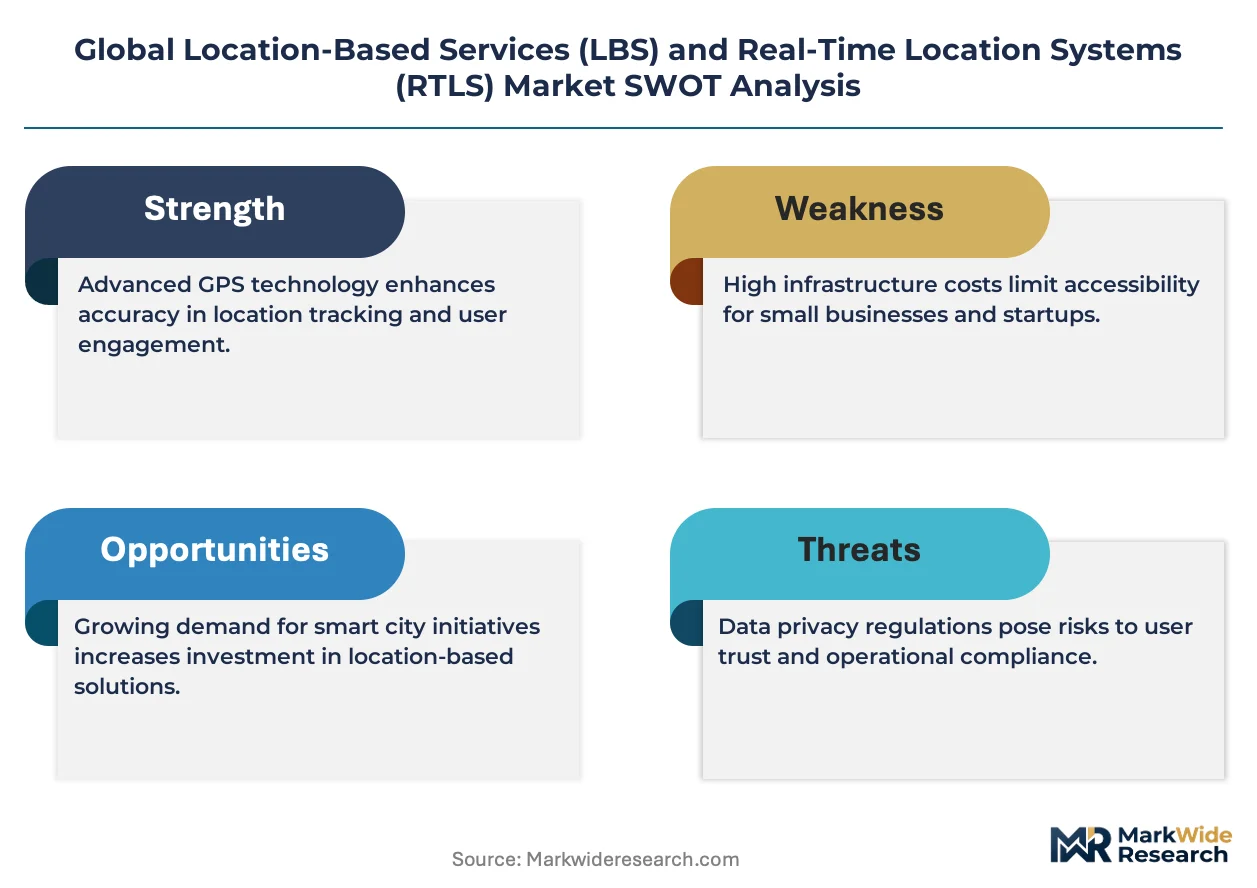
The EU Green Deal is recalibrating energy-efficiency mandates for industrial IoT deployments, pushing manufacturing facilities toward low-power location architectures. Google leverages its mapping data infrastructure to dominate consumer-facing LBS platforms across mobile ecosystems. Cisco anchors enterprise RTLS networks through its Wi-Fi and BLE access point integrations. Zebra Technologies specializes in ruggedized hardware devices for warehouse and logistics environments.
Location-Based Services and Real-Time Location Systems encompass hardware, software, and communication layers that compute spatial coordinates through GPS satellite triangulation, RFID tag interrogation, Ultra-Wideband time-of-flight measurement, or BLE beacon proximity detection to enable real-time asset visibility and geofenced automation. Software Platforms capture recurring margin pools as enterprises prioritize cloud-native analytics over on-premise middleware installations. Ultra-Wideband is displacing legacy Wi-Fi for indoor navigation in high-interference manufacturing settings where sub-meter precision prevents collision incidents.
The FCC governs spectrum allocation for UWB and BLE transmissions in the United States, while ETSI harmonizes short-range device standards across European member states. China's MIIT mandates GB-compliant encryption for location data processing within critical infrastructure sectors. Stakeholders must monitor evolving cross-border data localization rules that fragment cloud-based platform architectures.
Market Dynamics
Ultra-Wideband chipsets are collapsing the cost barrier for sub-meter indoor positioning, pulling precision location from automotive assembly lines into mid-market warehouse operations previously served by Wi-Fi trilateration.
Growth Catalysts
- EU AI Act compliance mandates:Automated location analytics platforms in German automotive plants must demonstrate algorithmic transparency, accelerating procurement of auditable RTLS software stacks over black-box alternatives.
- Pharmaceutical cold chain integrity:Temperature-sensitive biologics distribution across the Rhine-Ruhr corridor requires continuous location-temperature correlation, driving BLE beacon density in third-party logistics networks.
- Multi-modal fleet visibility:Port operators in Rotterdam and Hamburg integrate GPS, RFID, and UWB handoffs to eliminate cargo dwell time during container transfers between vessel, rail, and truck.
Market Restraints
- Silicon supply concentration:UWB transceiver fabrication depends on TSMC's 22nm specialty processes, creating single-source vulnerability for hardware vendors.
- Cross-border data localization:China's MIIT encryption mandates fragment cloud platform architectures, forcing redundant infrastructure deployment for multinational deployments.
- Wi-Fi 6/7 substitution threat:Improved round-trip time measurement in enterprise WLAN upgrades narrows the precision gap for use cases tolerating 2-3 meter accuracy.
Strategic Opportunities
- India's industrial corridor expansion:PLI scheme incentives for electronics manufacturing in Tamil Nadu and Karnataka create first-mover positioning for precision asset tracking in greenfield facilities.
- Healthcare staff duress alerting:Union mandates in French and Belgian hospitals drive pendant-style UWB badge deployments for lone worker protection in psychiatric and emergency departments.
- 5G-RTLS convergence:Private network slicing enables time-synchronized positioning without dedicated UWB infrastructure, appealing to mining and oil-gas operators in Western Australia and Alberta.
Industry Challenges
- RF engineering talent scarcity:UWB antenna design and multipath mitigation expertise concentrates in semiconductor firms, limiting system integrator capabilities.
- Legacy WMS integration friction:Warehouse management systems built on 1990s SQL architectures require custom middleware for real-time location event ingestion.
- ISO/IEC 24762 certification timelines:Disaster recovery compliance for location data services extends sales cycles by 4-8 months in financial services and critical infrastructure sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market |
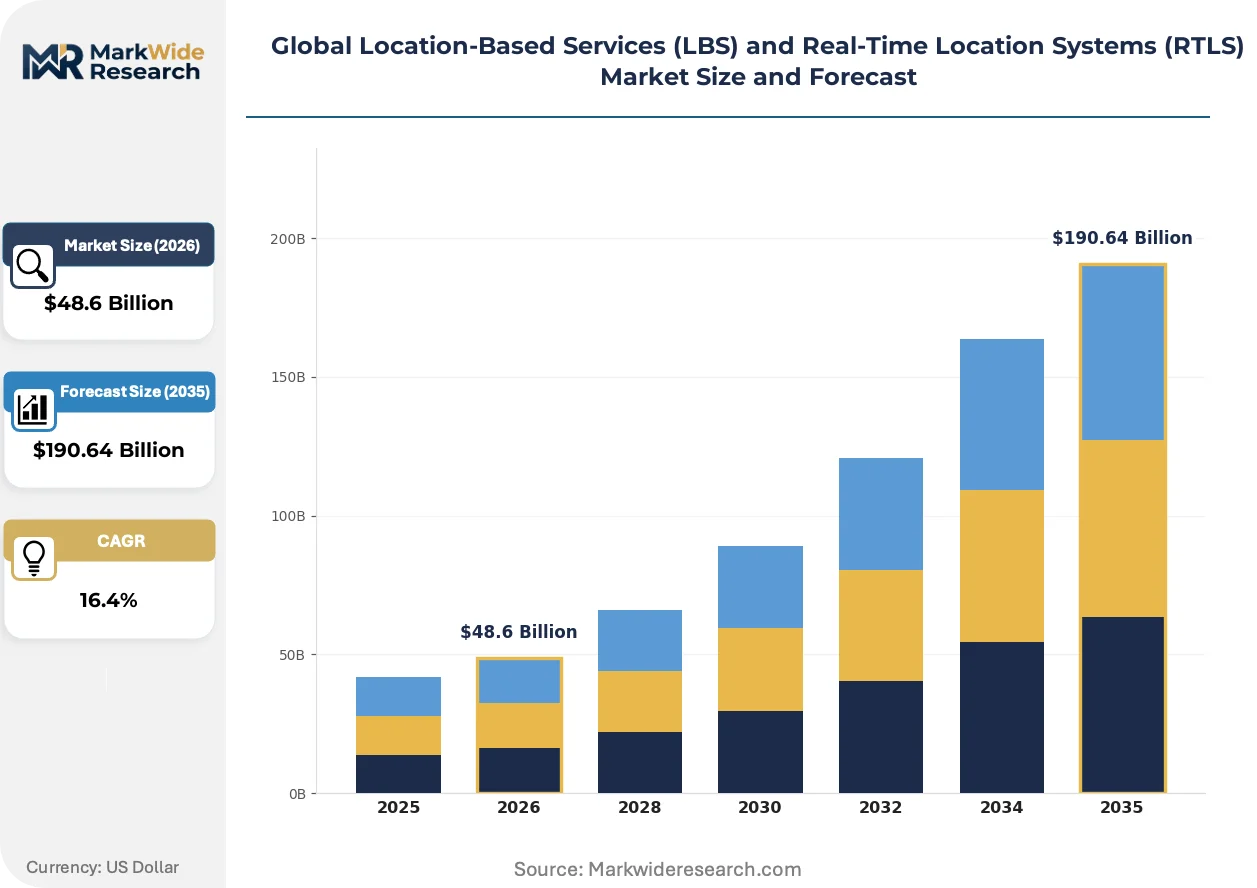
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $190.64 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Platforms, Hardware Devices, Middleware, Communication Infrastructure Technology: GPS, RFID, Ultra-Wideband, Bluetooth Low Energy, Wi-Fi Application: Asset Tracking, Fleet Management, Employee Safety, Indoor Navigation, Supply Chain Control End User: Logistics Providers, Emergency Responders, Event Coordinators, Retail Chains, Manufacturing Facilities |
| Companies Covered | Google, Hewlett Packard Enterprise, Cisco, Impinj, Ubisense Group, IBM, Microsoft, CenTrak, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market Shifts & Advancements
Edge-native positioning architectures are redistributing computational load from cloud platforms to gateway devices, collapsing latency for safety-critical collision avoidance while complicating software update orchestration across distributed fleets.
Ultra-Wideband time-of-flight measurement is overtaking Received Signal Strength Indicator methods in high-interference manufacturing environments. Automotive paint shops and welding cells in Stuttgart and Wolfsburg deploy UWB anchor networks to track automated guided vehicles within 10 centimeters. This precision is compressing insurance premiums for facilities where human-robot collaboration zones demand verified separation distances.
The EU AI Act's risk classification framework recalibrates procurement criteria for location analytics platforms processing worker movement patterns. German and French industrial buyers now require algorithmic impact assessments and training data documentation as standard contract terms. High-risk deployments in pharmaceutical cleanrooms and chemical processing plants face mandatory conformity assessments before operational authorization.
Subscription-based RTLS platform licensing is displacing perpetual hardware-and-software bundles in mid-market logistics. Third-party warehouse operators in the Netherlands and Belgium prefer per-location-month pricing that aligns technology spending with occupancy volatility. This model shifts vendor revenue recognition and intensifies customer success investment to reduce logo churn in seasonal freight environments.
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market Segmentation
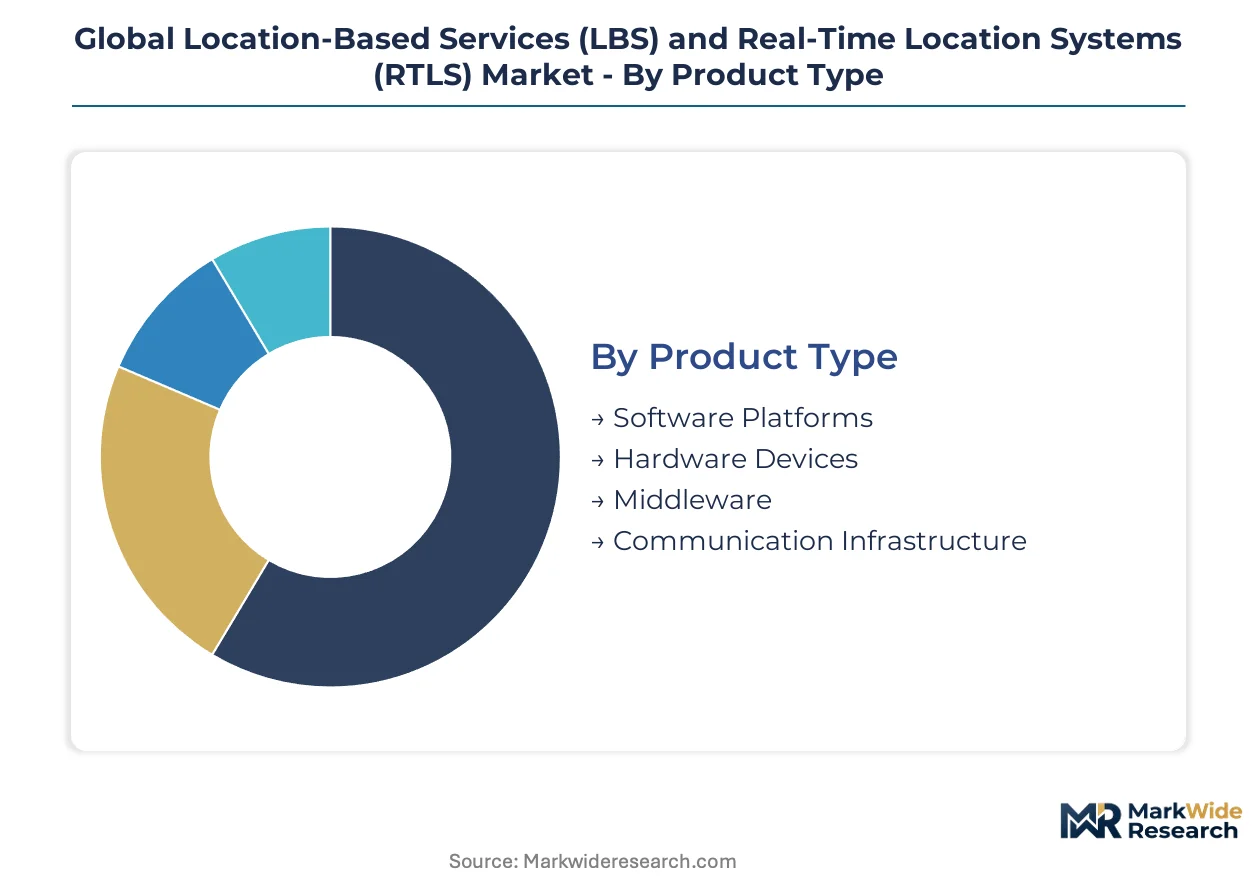
Segmentation in location-based services reveals divergent margin structures across hardware commoditization and software recurring revenue. Technology choices determine precision thresholds that lock out or admit specific use cases. End-user procurement patterns split between capital-intensive manufacturing deployments and operational-expense logistics contracts.
Product Type:
Software Platforms command premium multiples while Hardware Devices drive volume scale across industrial deployments.
- Software Platforms:Cloud-native analytics stacks process location-temperature correlations and geofence violations through API-accessible dashboards. Pharmaceutical distributors in Germany's Rhine-Ruhr corridor prioritize these platforms for cold chain documentation that satisfies EMA audit requirements. Recurring licensing models displace perpetual software bundles in third-party logistics networks.
- Hardware Devices:Ruggedized tags, anchors, and wearable badges withstand welding cell interference and freezer storage conditions. Automotive assembly plants in Stuttgart deploy UWB-enabled hardware for automated guided vehicle separation verification. Unit economics improve as TSMC's 22nm specialty processes drive chipset cost compression.
- Middleware:Integration layers translate proprietary location protocols into warehouse management system formats.
- Communication Infrastructure:Gateway devices and anchor networks form the physical layer for time-synchronized positioning.
Today's leader: Software Platforms. Tomorrow's challenger: Hardware Devices.
Technology:
Precision thresholds stratify technologies between outdoor meter-level accuracy and indoor centimeter-grade positioning.
- Ultra-Wideband:Time-of-flight measurement achieves sub-10-centimeter precision in high-interference manufacturing environments. Paint shops and welding cells in Wolfsburg deploy UWB anchor networks to prevent collision incidents between human workers and automated guided vehicles. Insurance premium compression validates capital expenditure for safety-critical deployments.
- Bluetooth Low Energy:Proximity detection enables low-power asset tracking across temperature-controlled pharmaceutical distribution. BLE beacon density expands in Dutch and Belgian third-party logistics networks serving biologics manufacturers. Battery lifespans exceeding five years reduce maintenance overhead in hard-to-access ceiling mounts.
- GPS:Satellite triangulation dominates outdoor fleet visibility across multi-modal container transfers.
- RFID:Passive tag interrogation serves low-cost inventory verification at choke points.
- Wi-Fi:Round-trip time measurement in enterprise WLAN upgrades narrows precision gaps for 2-3 meter tolerance use cases.
Ultra-Wideband climbs the fastest in manufacturing safety applications. BLE gains share fastest in logistics cost optimization.
Application:
Use case maturity varies between regulatory-mandated worker protection and efficiency-driven inventory optimization.
- Asset Tracking:Real-time visibility of high-value equipment, tooling, and work-in-process inventory prevents production line stoppages. Semiconductor fabs in Tamil Nadu deploy precision positioning under India's PLI scheme incentives for electronics manufacturing greenfield facilities. Tag density correlates directly with inventory velocity improvement metrics.
- Employee Safety:Lone worker protection mandates in French and Belgian hospitals drive pendant-style UWB badge deployments. Psychiatric and emergency departments require duress alerting with room-level accuracy. Union contract negotiations increasingly specify location-based safety system minimums.
- Fleet Management:GPS-dominant visibility spans vessel, rail, and truck handoffs in Rotterdam and Hamburg port operations.
- Indoor Navigation:Consumer-facing wayfinding relies on BLE beacon networks in retail and airport deployments.
- Supply Chain Control:End-to-end location-temperature correlation satisfies pharmaceutical distribution compliance.
Asset Tracking anchors current procurement volumes. Employee Safety represents the steepest expansion trajectory as European labor regulations tighten.
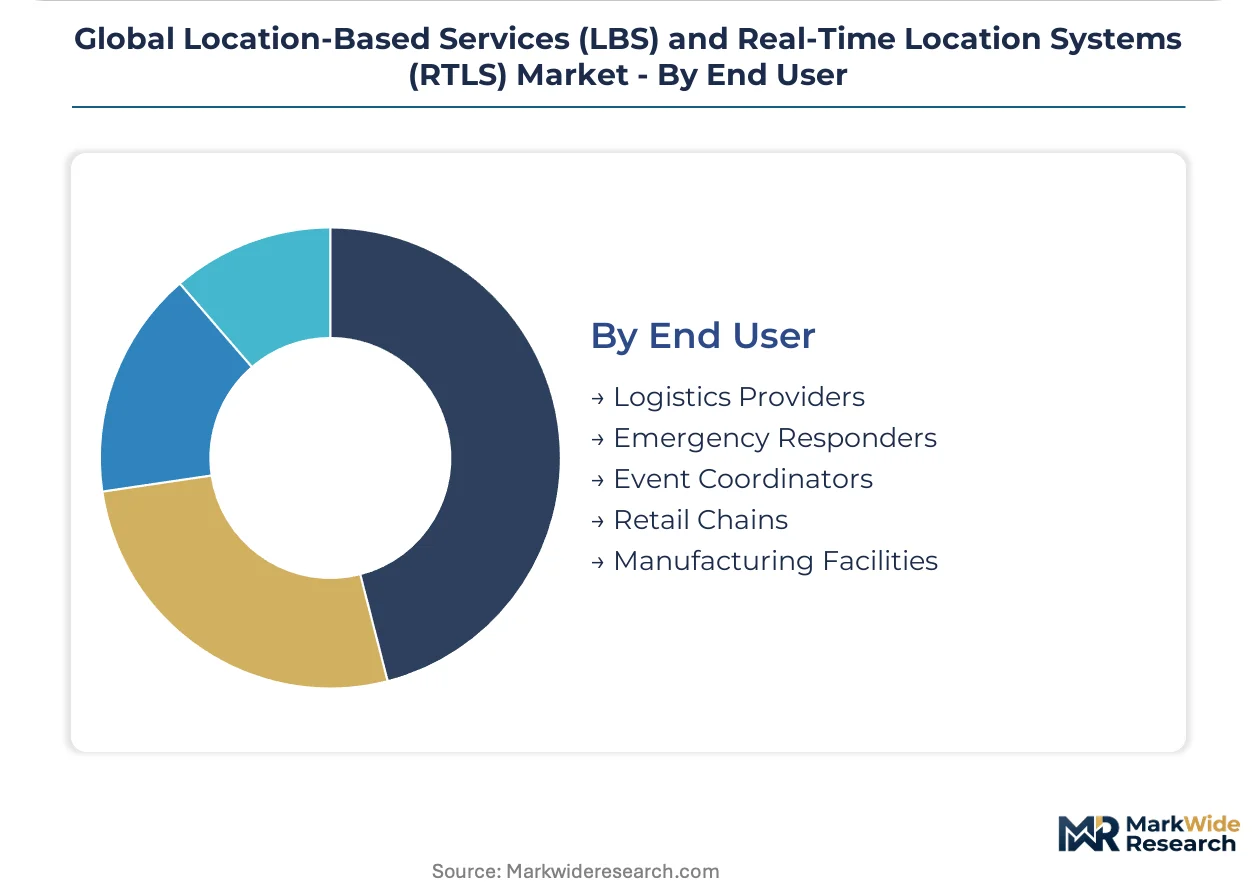
End User:
Procurement authority concentrates in manufacturing capital budgets and logistics operational expenditures.
- Manufacturing Facilities:Automotive and pharmaceutical plants in Germany's industrial corridor deploy precision indoor positioning for asset tracking and worker safety. EU AI Act compliance mandates accelerate procurement of auditable RTLS software stacks over black-box alternatives. Capital approval cycles extend 12-18 months for greenfield installations.
- Logistics Providers:Third-party warehouse operators in the Netherlands and Belgium prefer per-location-month pricing that aligns technology spending with occupancy volatility. Seasonal freight patterns intensify customer success investment requirements to reduce logo churn. Multi-modal fleet visibility contracts span GPS, RFID, and UWB handoffs.
- Emergency Responders:Fire and medical services require ruggedized outdoor positioning for incident command coordination.
- Retail Chains:Indoor navigation and proximity marketing drive BLE infrastructure deployment in flagship locations.
- Event Coordinators:Temporary crowd flow management utilizes rental tag programs for large-scale gatherings.
Manufacturing Facilities dominate capital expenditure commitments. Logistics Providers expand fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RF engineering talent for UWB antenna design concentrates in semiconductor hubs across Germany, the United States, and Taiwan. This technical concentration shapes where precision positioning systems achieve commercial scale first.
United States
Multi-modal port operators in Los Angeles and Long Beach integrate GPS, RFID, and UWB handoffs to eliminate cargo dwell time during container transfers. The FCC governs spectrum allocation for UWB and BLE transmissions. Silicon Valley anchors cloud-native RTLS software development for enterprise analytics platforms.
Germany
Automotive and pharmaceutical manufacturers in Stuttgart and Wolfsburg deploy precision indoor positioning for asset tracking and worker safety. The EU AI Act mandates algorithmic transparency for automated location analytics platforms processing worker movement patterns. The Rhine-Ruhr corridor drives BLE beacon density in third-party logistics networks serving biologics distribution.
China
Electronics manufacturing greenfield facilities under the MIIT's GB-compliant encryption mandates fragment cloud platform architectures for multinational deployments. The Yangtze River Delta concentrates UWB transceiver fabrication dependent on TSMC's 22nm specialty processes. Shenzhen anchors hardware device manufacturing for ruggedized tags and wearable badges.
India
PLI scheme incentives for electronics manufacturing in Tamil Nadu and Karnataka create first-mover positioning for precision asset tracking in greenfield semiconductor fabs. The country's national electronics regulator mandates local data processing requirements for critical infrastructure deployments. Bangalore anchors software platform development for cloud-native location analytics.
Netherlands
Third-party warehouse operators in Rotterdam prefer per-location-month pricing that aligns technology spending with occupancy volatility. The ETSI harmonizes short-range device standards across European member states. Amsterdam anchors subscription-based RTLS platform licensing adoption in mid-market logistics contracts.
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the RTLS value chain. Foundry-dependent hardware vendors face margin compression as TSMC's 22nm specialty processes dominate UWB transceiver fabrication. Fabless semiconductor designers and cloud-native software platforms capture recurring revenue streams. Strategic archetypes include mapping data infrastructure operators, enterprise networking integrators, and ruggedized hardware specialists. Competitive moves concentrate on M&A for antenna design capabilities and strategic partnerships for private 5G network slicing.
Within the cloud-native software tier, Google and Microsoft exemplify asset-light platforms leveraging existing mapping data infrastructure. Zebra Technologies occupies a position among ruggedized hardware specialists serving warehouse and logistics environments. These three anchors represent divergent strategic bets: consumer-facing location services, enterprise productivity integration, and industrial-grade device durability.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Cisco |
| Impinj |
| Ubisense Group |
| IBM |
| Microsoft |
| CenTrak |
| Zebra Technologies |
| Others |
Supply & Pricing Matrix
TSMC's 22nm specialty wafer pricing cascades through UWB chipset fabrication into three distinct hardware tiers, compressing margins for anchor manufacturers while subscription-based software platforms capture recurring revenue premiums in Dutch and Belgian logistics contracts.
Pricing Analysis
The bundled-vs-unbundled service split separates perpetual hardware-and-software bundles from per-location-month SaaS offerings. Three-tier pricing structure across premium, standard, and economy levels reflects precision grade, with sub-10-centimeter UWB systems commanding certification premiums for EU AI Act compliance. Cost compression in mid-market BLE deployments is intensifying because Wi-Fi 6/7 round-trip time improvements narrow accuracy gaps. Third-party warehouse operators exhibit highest price sensitivity, while German automotive plants prioritize auditability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for UWB badge refurbishment and anchor recalibration extend hardware lifecycles in seasonal freight environments. Taiwan, China, and Germany concentrate supply for 22nm transceiver fabrication, antenna design, and precision assembly respectively. Raw material dependencies include gallium arsenide substrates, ceramic antenna substrates, and lithium-thionyl chloride cells for long-life beacons. Single-source vulnerability at TSMC's specialty nodes threatens hardware vendor margins. Distribution runs through direct enterprise sales for manufacturing deployments and channel partners for logistics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's PLI scheme subsidies for greenfield electronics manufacturing and Germany's EU AI Act compliance premiums for auditable software stacks.
For Market Incumbents: Acquire UWB antenna design boutiques to internalize RF engineering talent scarce in system integrator channels. Build captive supply agreements for 22nm wafer capacity to mitigate TSMC concentration risk. Deepen backward integration into edge-native gateway manufacturing to control software update orchestration across distributed fleets. For New Entrants and Emerging Players: Cloud-native RTLS platforms with API-first architectures represent the most penetrable wedge for mid-market logistics contracts in the Netherlands and Belgium. Target per-location-month pricing models that align with seasonal occupancy volatility. Pursue hospital system partnerships in France and Belgium where union mandates specify lone worker protection minimums. For Investors and Strategic Acquirers: Asymmetric upside sits with fabless semiconductor designers holding UWB protocol intellectual property and recurring-revenue software platforms with healthcare compliance certifications. Long-term viability favors asset-light models over foundry-dependent hardware vendors. Monitor TSMC capacity allocation announcements for inflection signals in hardware margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | UWB antenna design boutiques in Stuttgart and Munich command scarcity premiums from automotive safety deployments. |
| Strategic Partnership | Private 5G network slicing agreements with mining operators in Western Australia bypass dedicated UWB infrastructure costs. |
| Geographic Expansion | Tamil Nadu and Karnataka greenfield facilities under India's PLI scheme create first-mover positioning for semiconductor fabs. |
| Product Launch | Edge-native positioning architectures collapsing latency for collision avoidance in Wolfsburg welding cells. |
| Platform Integration | API-accessible dashboards integrating location-temperature correlations satisfy EMA audit requirements in Rhine-Ruhr pharmaceutical distribution. |
Research Methodology
Multiple input streams — primary interviews with RTLS deployment managers, regulatory affairs specialists at ETSI working groups, and procurement leads at third-party logistics operators — were reconciled against secondary validation from FCC spectrum allocation filings, EMA cold chain guidance documents, and hyperscaler mapping infrastructure disclosures. Bottom-up triangulation across hardware shipment estimates and top-down validation against enterprise software licensing disclosures anchored volume and value outputs.
Data-stream reconciliation across technology segmentation, end-user procurement patterns, and regional regulatory clusters structured the analytical framework throughout the forecast period. Deployment models, precision grade tiers, and integration complexity levels were modeled as segmentation dimensions. CAGRs were derived from fitted growth curves against historical adoption rates in automotive safety and pharmaceutical distribution verticals.
The model holds under stable spectrum allocation regimes and continued TSMC specialty process availability; deviation in export control expansions or foundry capacity reallocation would shift hardware supply assumptions. Practitioners should monitor ETSI short-range device standard revisions and MIIT encryption mandate enforcement for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Indoor Air Quality Monitor Market
Sensors
Transport Monitoring System Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Remote Sensing Technology Market
Sensors
Asset Tracking Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Personal Navigation Devices Market
Sensors
Transportation Sensors Market
Sensors
Refrigeration Monitoring Market
Sensors
Automated Weather Observation System Market
Sensors
Indoor Location Market
Sensors
Weigh-In-Motion System Market
Sensors
Mobile Lidar Scanner Market
Sensors
Temperature Data Loggers Market
Sensors
Data Buoy Market
Sensors
Smart Pest Monitoring Management System Market