
 Load (ETL) Market | 2026-2036
Load (ETL) Market Size, Share, and Industry Trends Forecast 2026-2036
Load (ETL) Market Foresight
The divergence between premium managed ETL platforms and commodity open-source tooling is hardening around SLA guarantees, security certification depth, and native data governance integration. Fivetran leverages its pre-built connector ecosystem to sustain premium pricing in regulated verticals. Matillion anchors its position through deep integration with cloud data warehouse architectures. Informatica PowerCenter competes on legacy enterprise entrenchment and hybrid deployment flexibility.
Extract, transform, load (ETL) systems perform structured data movement through defined pipelines that apply schema validation, cleansing rules, and aggregation logic before loading to target repositories, typically operating with throughput measured in terabytes per hour and latency thresholds distinguishing batch from streaming architectures. Public cloud deployment now leads expansion as organizations retire on-premises infrastructure, while real-time processing segments capture disproportionate investment from telecommunications and financial services end users seeking sub-second pipeline latency. Structured data formats remain the volume base, though semi-structured JSON and log data integration represents the fastest-growing format category as IoT and application telemetry sources proliferate.
FDA 21 CFR Part 11 and HIPAA shape healthcare ETL requirements around audit trails and data lineage documentation, while GDPR and EU AI Act mandates in Europe enforce purpose limitation and algorithmic transparency across automated data pipelines. ISO 27001 and SOC 2 Type II certifications function as table stakes for vendor procurement evaluation in enterprise segments. Stakeholders must monitor how emerging AI-specific data regulations redefine acceptable transformation logic and provenance tracking before committing to multi-year platform contracts.
Market Dynamics
Cloud-native ETL architectures are displacing legacy on-premises infrastructure as financial services institutions in Germany and France confront GDPR and EU AI Act compliance deadlines. This migration is compressing procurement cycles and redistributing vendor power toward platforms with native data governance integration.
Growth Catalysts
- GDPR Article 30 Record-Keeping:German and French enterprises must maintain detailed processing records, driving demand for automated lineage tracking in ETL pipelines.
- Real-Time Telemetry Architectures:Telecommunications operators require sub-second latency pipelines to process IoT and application log data at scale.
- Healthcare Data Modernization:HIPAA audit trail requirements and FDA 21 CFR Part 11 validation protocols mandate transformation logic documentation in regulated clinical data flows.
Market Restraints
- Certification Timeline Friction:ISO 27001 and SOC 2 Type II audit cycles extend 6-12 months, delaying vendor qualification for enterprise procurement.
- Skill Concentration Geography:Cloud-native pipeline engineering expertise clusters in North American and Western European metropolitan tech hubs, constraining deployment velocity elsewhere.
- Hybrid Integration Complexity:Legacy Informatica PowerCenter installations resist migration without substantial refactoring of transformation logic and connector dependencies.
Strategic Opportunities
- Asia-Pacific Cloud Migration:Japanese and South Korean financial institutions are accelerating data warehouse modernization programs, creating demand for ETL platforms with native support for Snowflake and BigQuery architectures.
- EU AI Act Algorithmic Transparency:Automated decision-making pipelines now require provenance documentation, opening specialized governance tooling segments.
- Streaming-Batch Convergence:Apache Flink and Kafka integration with traditional batch workflows enables unified pipeline architectures for mixed-latency workloads.
Industry Challenges
- Data Engineering Talent Scarcity:Pipeline orchestration, schema registry management, and streaming optimization skills command premium compensation, constraining team scaling.
- Legacy System Entrenchment:Decades of accumulated transformation logic in on-premises ETL tools resists cloud-native refactoring without business disruption.
- Multi-Cloud Credential Sprawl:Cross-platform identity and access management across AWS, Azure, and GCP pipelines complicates security posture maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Load (ETL) Market |
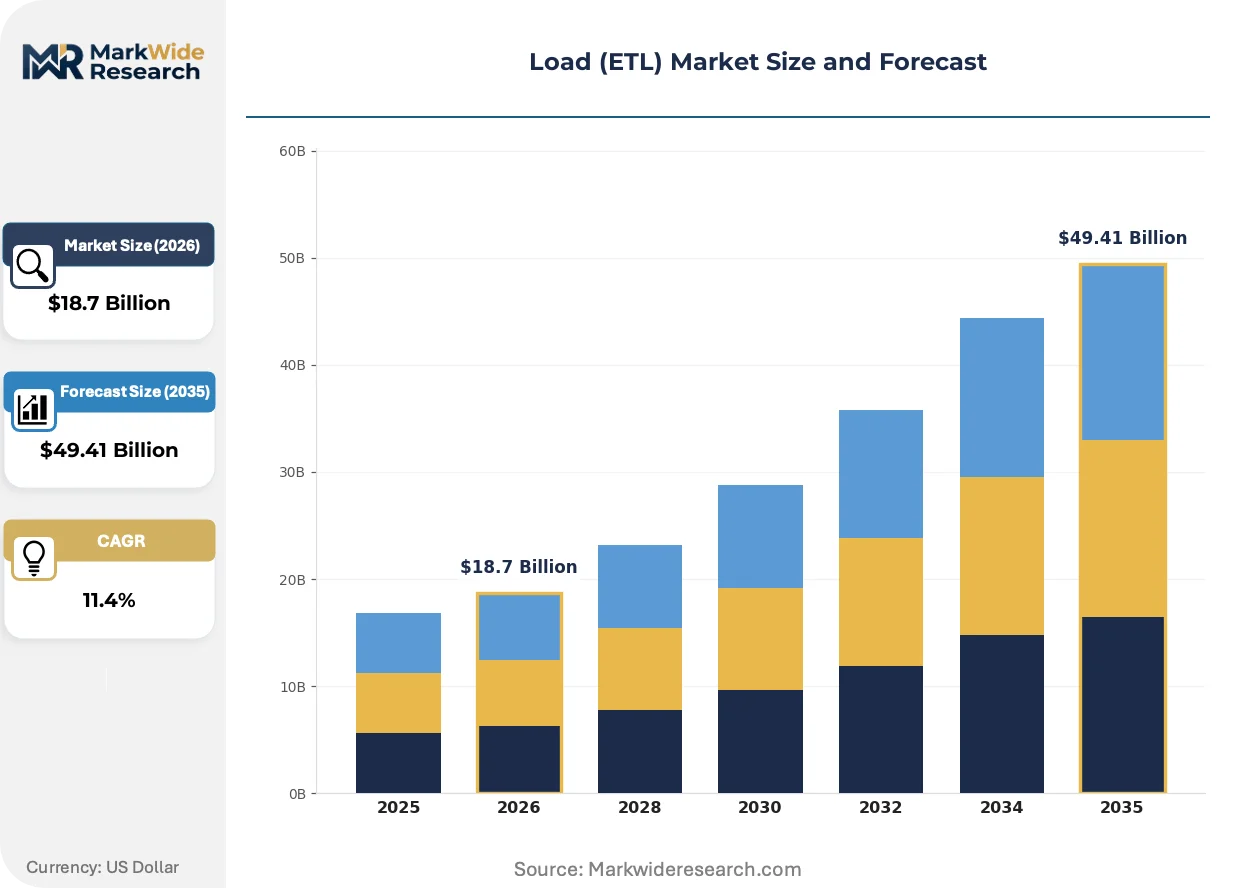
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud Service Type: Batch Processing, Real-Time Processing, Data Integration, Data Migration End User: Retail, Healthcare, Telecommunications, Financial Services Data Format: Structured Data, Unstructured Data, Semi-Structured Data, Metadata |
| Companies Covered | Fivetran, Airbyte, dbt, Matillion, Informatica PowerCenter, Talend, IBM InfoSphere DataStage, Stitch, Hevo Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Load (ETL) Market Shifts & Advancements
ETL market evolution centers on three vectors: architectural convergence between batch and streaming, regulatory pressure on automated data processing, and procurement model compression toward consumption-based pricing. These forces are reshaping vendor differentiation and buyer evaluation criteria simultaneously.
Reverse ETL is converging with operational analytics platforms to push transformed data back into SaaS applications. Retail and subscription-software companies are adopting these bidirectional pipelines within 12-18 month implementation windows. This capability compression is collapsing the historical boundary between analytics engineering and application development teams.
The EU AI Act's risk-based classification system now governs automated data pipelines processing high-stakes decisions in credit scoring and insurance underwriting. French CNIL and German KBA regulators are issuing sector-specific guidance on algorithmic transparency requirements. Financial services institutions in these jurisdictions are prioritizing ETL vendors with built-in provenance tracking and transformation explainability features.
Consumption-based pricing is displacing traditional per-connector or per-pipeline licensing in enterprise procurement evaluations. Data platform teams at North American technology companies are unbundling professional services from software licenses, negotiating direct support contracts with implementation partners. This shift is most visible among Series C and public software companies with mature cloud cost management functions.
Load (ETL) Market Segmentation
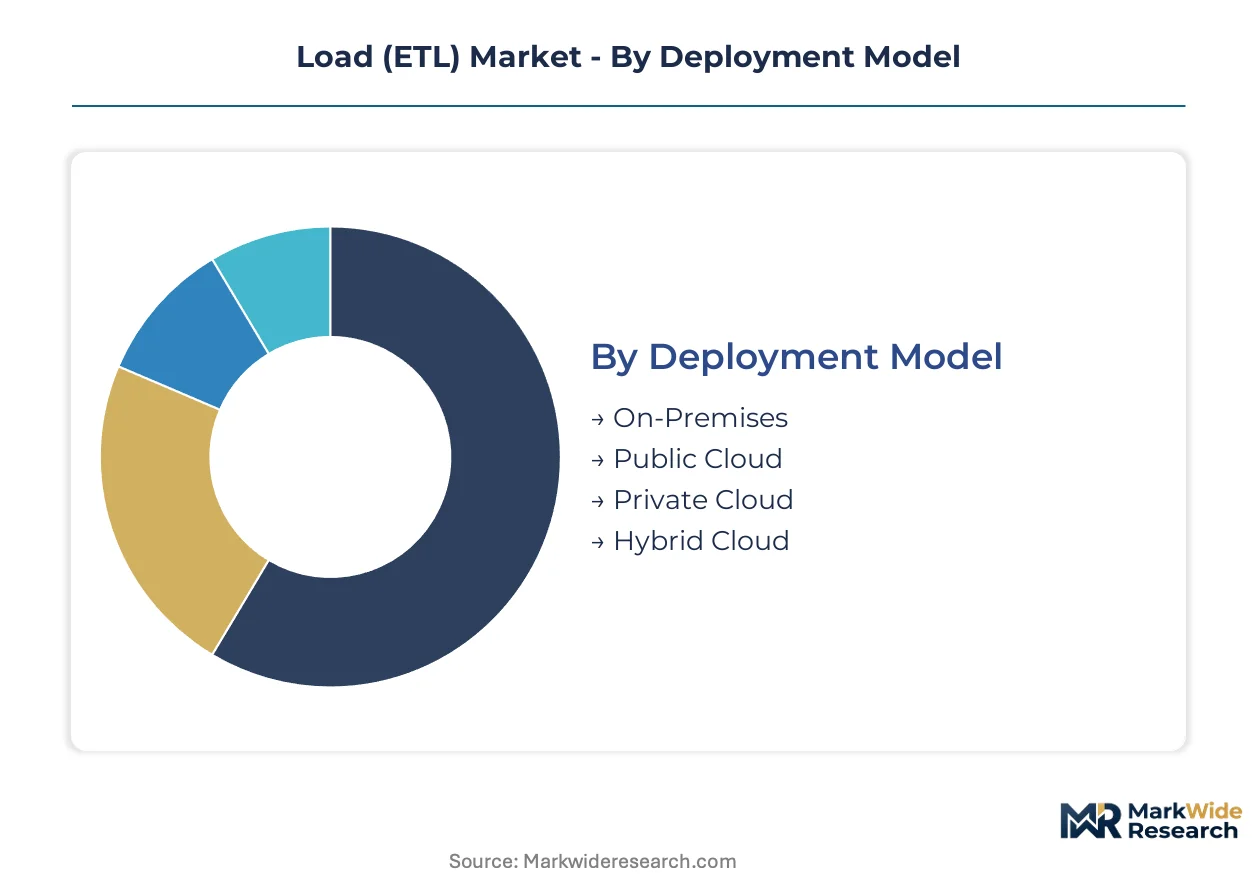
ETL procurement decisions hinge on deployment economics, latency requirements, and regulatory exposure. Segmentation reveals where capital concentrates and which configurations command premium pricing.
Deployment Model:
Capital intensity varies sharply across deployment architectures, with upfront infrastructure commitments determining vendor lock-in and migration costs.
- Public Cloud:Consumption-based pricing eliminates data center capex while enabling elastic throughput scaling. German and French financial institutions favor this model to meet GDPR Article 30 record-keeping mandates without on-premises hardware cycles.
- Hybrid Cloud:Organizations retain sensitive transformation logic on-premises while bursting peak workloads to cloud infrastructure. Healthcare providers in the United States deploy this architecture to satisfy HIPAA audit trail requirements alongside cloud analytics.
- Private Cloud:Dedicated infrastructure serves defense contractors and government agencies with air-gapped security requirements.
- On-Premises:Legacy Informatica PowerCenter installations persist where decades of transformation logic resist refactoring.
Public Cloud absorbs the bulk of installed capacity; Hybrid Cloud is expanding most quickly.
Service Type:
Processing latency requirements segment procurement budgets, with real-time architectures commanding engineering premium multiples over batch alternatives.
- Real-Time Processing:Sub-second pipeline latency enables fraud detection and operational telemetry at telecommunications operators. Apache Flink and Kafka integration now supports unified batch-streaming architectures.
- Batch Processing:Scheduled ETL jobs dominate historical data warehouse loads with throughput measured in terabytes per hour. North American enterprises maintain this foundation for cost-efficient bulk transformation.
- Data Integration:Schema registry management and connector ecosystems consolidate fragmented source systems.
- Data Migration:One-time cloud modernization projects compress multi-year transformation logic into concentrated implementation windows.
Batch Processing retains the largest revenue base; Real-Time Processing is gaining share fastest.
End User:
Regulatory stringency and data volume scale create divergent procurement patterns across verticals.
- Financial Services:Credit scoring and insurance underwriting pipelines face EU AI Act algorithmic transparency mandates. French CNIL and German KBA guidance requires provenance documentation for automated decision systems.
- Healthcare:FDA 21 CFR Part 11 validation protocols and HIPAA audit trails mandate transformation logic documentation in clinical data flows. United States hospital systems prioritize vendors with pre-validated connector libraries.
- Telecommunications:IoT telemetry ingestion at scale drives demand for sub-second latency architectures.
- Retail:Reverse ETL adoption pushes transformed analytics back into operational SaaS applications.
Financial Services commands the highest per-seat pricing; Healthcare is climbing the fastest.
Data Format:
Schema flexibility requirements determine transformation complexity and tooling selection.
- Semi-Structured Data:JSON and log formats from application telemetry and IoT sensors represent the steepest expansion trajectory. Schema-on-read capabilities reduce upfront modeling overhead.
- Structured Data:Relational tables remain the volume foundation for enterprise data warehouses with rigid schema validation requirements.
- Unstructured Data:Image, audio, and document pipelines require specialized preprocessing before standard ETL transformation.
- Metadata:Data catalog and lineage documentation supports governance automation under GDPR and EU AI Act mandates.
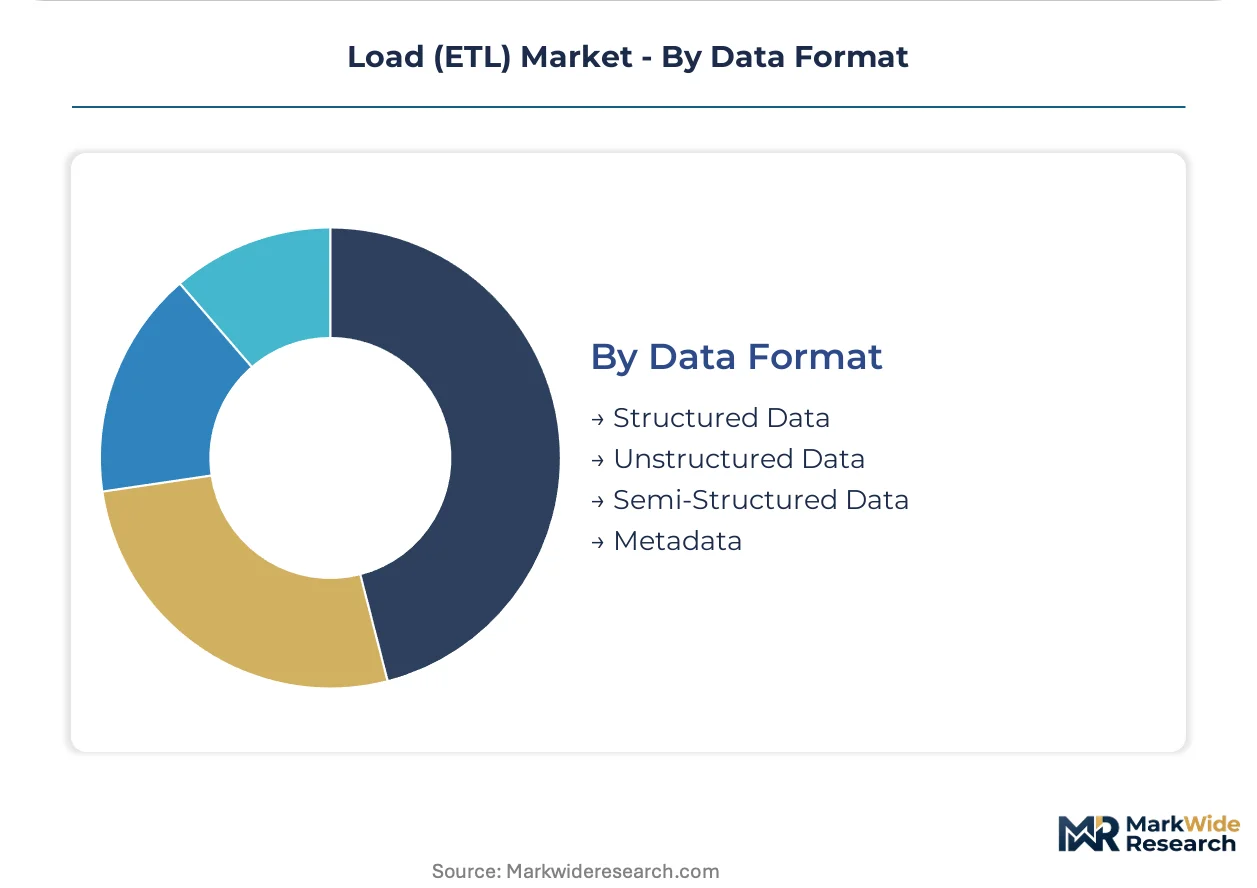
Structured Data anchors current processing volumes; Semi-Structured Data is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors the deepest concentration of cloud-native ETL engineering talent, while procurement gravity shifts toward Frankfurt and Singapore as regulatory and cloud migration timelines compress.
United States
Healthcare data modernization and financial services telemetry drive procurement in the Boston and New York corridors. HIPAA audit trail requirements and FDA 21 CFR Part 11 validation protocols shape vendor selection criteria. Seattle's cloud engineering clusters host the largest concentration of streaming pipeline specialists serving telecommunications operators.
Germany
Automotive supply chain digitization and industrial IoT integration create demand for sub-second latency architectures. KBA guidance on EU AI Act algorithmic transparency mandates provenance documentation for credit scoring pipelines. Munich's enterprise software ecosystem concentrates implementation partners for hybrid cloud deployments.
France
Insurance underwriting automation and retail operational analytics accelerate reverse ETL adoption. CNIL sector-specific guidance enforces purpose limitation across automated decision systems. Parisian fintech clusters prioritize vendors with native GDPR Article 30 record-keeping capabilities.
Japan
Financial institution data warehouse modernization and manufacturing sensor integration expand cloud-native procurement. METI industrial data governance frameworks align with emerging algorithmic accountability standards. Tokyo's banking technology centers drive Snowflake and BigQuery architecture specialization.
South Korea
Telecommunications IoT scale and semiconductor supply chain analytics require unified batch-streaming pipelines. MFDS data integrity standards for clinical research inform transformation logic documentation requirements. Seoul's enterprise cloud migration programs concentrate demand for consumption-based pricing models.
Load (ETL) Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light connector specialists for procurement budgets in regulated verticals. The vendor base stratifies across three tiers: premium managed platforms with pre-built ecosystem depth, mid-market cloud-native tools with flexible deployment options, and legacy on-premises installations resisting migration. Dominant competitive moves include consumption-based pricing compression and native data governance integration to capture GDPR and EU AI Act compliance budgets.
Within the premium managed tier, Fivetran and Matillion occupy positions defined by connector ecosystem breadth and cloud data warehouse architecture depth. Informatica PowerCenter anchors the legacy entrenchment archetype, exemplifying hybrid deployment flexibility that resists full cloud-native refactoring.
| Leading Market Players |
|---|
| Fivetran |
| Airbyte |
| dbt |
| Matillion |
| Informatica PowerCenter |
| Talend |
| IBM InfoSphere DataStage |
| Stitch |
| Hevo Data |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up connector specialists now dominate the mid-market ETL tier, compressing pricing discipline through portfolio-company cross-selling while cloud hyperscalers anchor supply-side concentration through native integration bundling. This ownership pattern concentrates pricing power with platforms that can absorb certification costs across multiple product lines, forcing independent vendors toward niche specialization or acquisition exits.
Pricing Analysis
Consumption-based pricing anchored to monthly active rows processed now dominates enterprise procurement, displacing per-connector licensing. Pricing stratifies across premium tiers with pre-built GDPR compliance modules, standard SaaS tiers with basic lineage tracking, and economy self-hosted options with community support. Cost compression in the standard tier intensifies as open-source alternatives mature, while healthcare and financial services buyers show lowest price sensitivity due to audit trail mandates.
Supply Chain Analysis
Single-source vulnerability sits with cloud infrastructure providers in the United States, Ireland, and Germany where hyperscaler data centers concentrate compute capacity for managed ETL services. Pipeline execution draws from proprietary connector libraries, schema registry services, and streaming infrastructure components. Tariff exposure on cross-border data transfers creates regulatory friction for multi-cloud deployments. Distribution runs through direct enterprise sales teams and certified implementation partners serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ETL market has become a vertical-integration race as vendors pursue upstream control over connector development to escape hyperscaler platform tax and downstream embedding into operational applications to capture reverse ETL budgets.
For Market Incumbents: Deploy native data governance modules as the primary defensive lever against open-source encroachment. Acquire specialized lineage-tracking startups to fill EU AI Act compliance gaps before regulatory deadlines tighten. Consolidate channel partnerships with system integrators holding healthcare and financial services certifications to lock out emerging competitors. For New Entrants and Emerging Players: Boutique cloud consultancies represent the most accessible channel partner type for breaking into mid-market manufacturing and logistics accounts. Target South Korean and Japanese enterprises with Snowflake-native architectures where incumbent penetration remains shallow. Lead with consumption-based pricing transparency to differentiate against opaque enterprise licensing. For Investors and Strategic Acquirers: Distressed-cycle entries favor revenue-retention-focused SaaS platforms with healthcare compliance moats in Germany and France. Five-to-ten year viability hinges on algorithmic transparency feature depth rather than connector count alone. Watch for CNIL and KBA enforcement actions against non-compliant pipelines as the inflection signal for governance-tooling acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Connector Ecosystem Expansion | Pre-built integrations with Salesforce and SAP reduce implementation timelines for German automotive suppliers. |
| Consumption-Based Pricing Transition | Row-volume metering aligns vendor incentives with customer growth in North American SaaS companies. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation opens procurement at French insurance underwriters facing CNIL audits. |
| Streaming-Batch Architecture Unification | Apache Flink integration captures telecommunications IoT telemetry budgets in South Korea. |
| Reverse ETL Capability Buildout | Operational analytics pushback into SaaS applications collapses boundaries between data engineering and product teams. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside structured interviews with data platform engineers, cloud procurement officers, compliance leads at financial institutions, and ETL implementation specialists. SEC 10-K disclosures from publicly traded software vendors, hyperscaler capex reports, and GDPR enforcement databases from European data protection authorities supplied quantitative benchmarks. Bottom-up pipeline deployment estimates triangulated against top-down enterprise IT spending surveys.
Segment-level modeling captured deployment architecture, processing latency requirements, data format complexity, and vertical regulatory exposure across the projection horizon. CAGRs derived from trend extrapolation of cloud migration timelines and compliance deadline clustering. Industry-specific inputs included ISO 27001 certification velocity, open-source contributor growth rates, and connector library expansion trajectories.
Caveats apply where EU AI Act enforcement intensity or hyperscaler pricing policy shifts could materially shift the outlook. Deviation in cloud infrastructure cost trajectories or data localization mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Sweden ICT Market
Analytics
High Performance Computing (HPC) and High Performance Data Analytics (HPDA) Market
Analytics
North America Location Analytics Market
Analytics
Mobile Apps and Web Analytics Market
Analytics
Europe Predictive Analytics Market
Analytics
Augmented Analytics in BFSI Market
Analytics
Global Streaming Analytics Market
Analytics
Big Data Analytics in Automotive Market
Analytics
Spain Geospatial Imagery Analytics Market
Analytics
Marketing Analytics Software Market
Analytics
Self Service Analytics Market
Analytics
Data Wrangling Market
Analytics
Global Graph Analytics Market
Analytics
Emotion Analytics Market
Analytics
North America Operational Intelligence Market
Analytics
Latin America Location Based Data Analytics Market