
 Beacon Technology Market | 2026-2036
Beacon Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Beacon Technology Market Analysis
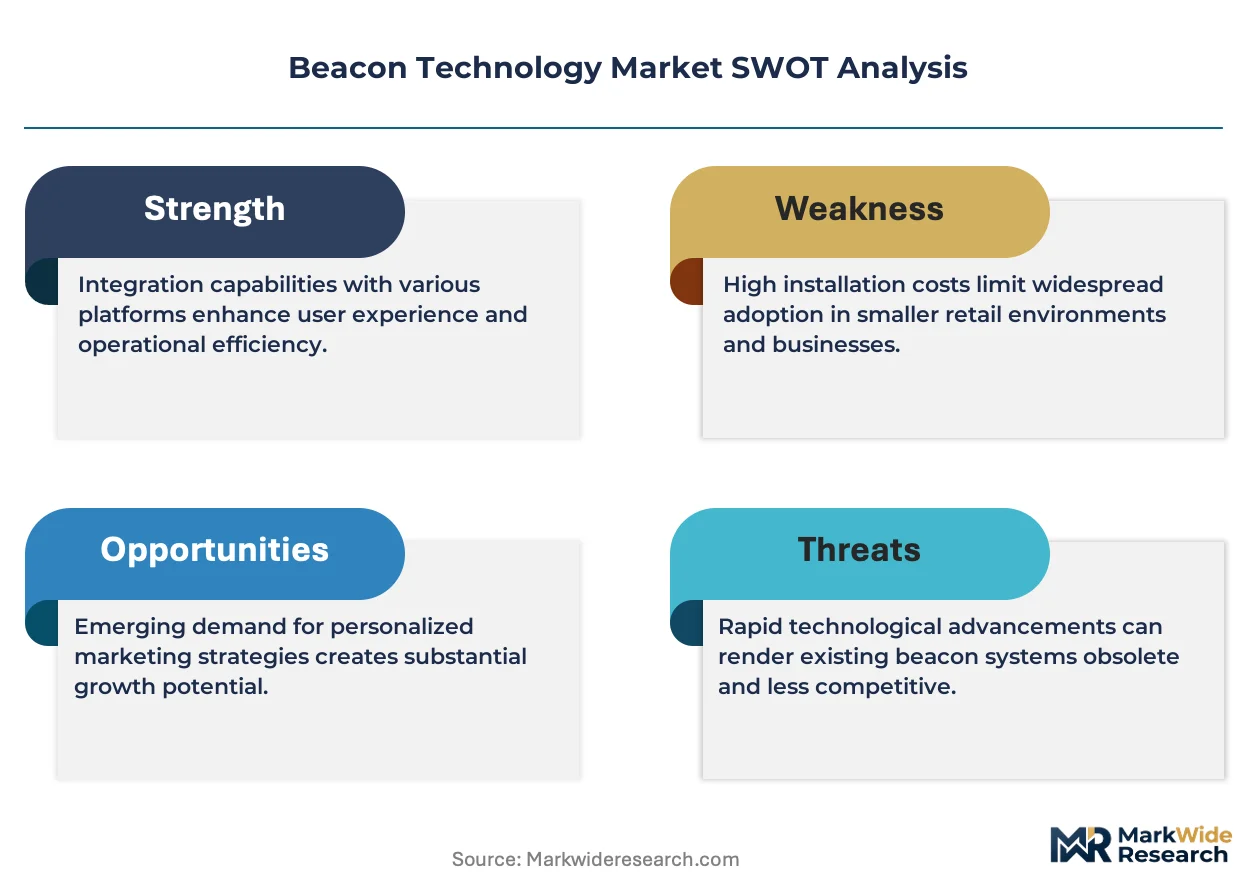
GDPR enforcement is repositioning the cost-of-entry calculus for beacon deployments across European retail and healthcare settings. Apple Inc. leverages its iOS ecosystem to control the default beacon detection layer on billions of devices. Qualcomm Technologies, Inc. anchors the semiconductor foundation with Bluetooth Low Energy chipsets that power third-party beacon hardware. Estimote Inc. specializes in edge-computing beacon form factors that process location data locally rather than routing through cloud servers.
Beacon technology denotes small wireless transmitters that broadcast identifier signals using Bluetooth Low Energy at 2.4 GHz, typically consuming under 100 mW and operating for months on coin-cell batteries to enable proximity-aware device interactions. The primary commercial purpose centers on triggering context-specific actions—push notifications, wayfinding prompts, or asset location pings—when a receiving smartphone or gateway enters a defined radius. Cloud-based deployment configurations capture expanding share among multi-location retailers seeking centralized beacon fleet management, while proximity marketing solutions within the solution layer generate the deepest margin pools due to recurring campaign analytics subscriptions. Bluetooth Low Energy dominates the technology dimension by unit volume, though NFC maintains structural importance in payment-integrated use cases where tap-to-interact simplicity outweighs range requirements.
The Federal Communications Commission in the United States governs 2.4 GHz spectrum allocation and power limits that directly constrain beacon signal range and density planning. The European Telecommunications Standards Institute coordinates cross-border frequency harmonization that enables unified beacon hardware SKUs across EU member states, while the EU AI Act introduces algorithmic transparency obligations for automated decision-making triggered by location data. Stakeholders must monitor how emerging interoperability mandates between competing beacon protocols reshape platform lock-in dynamics and hardware procurement flexibility.
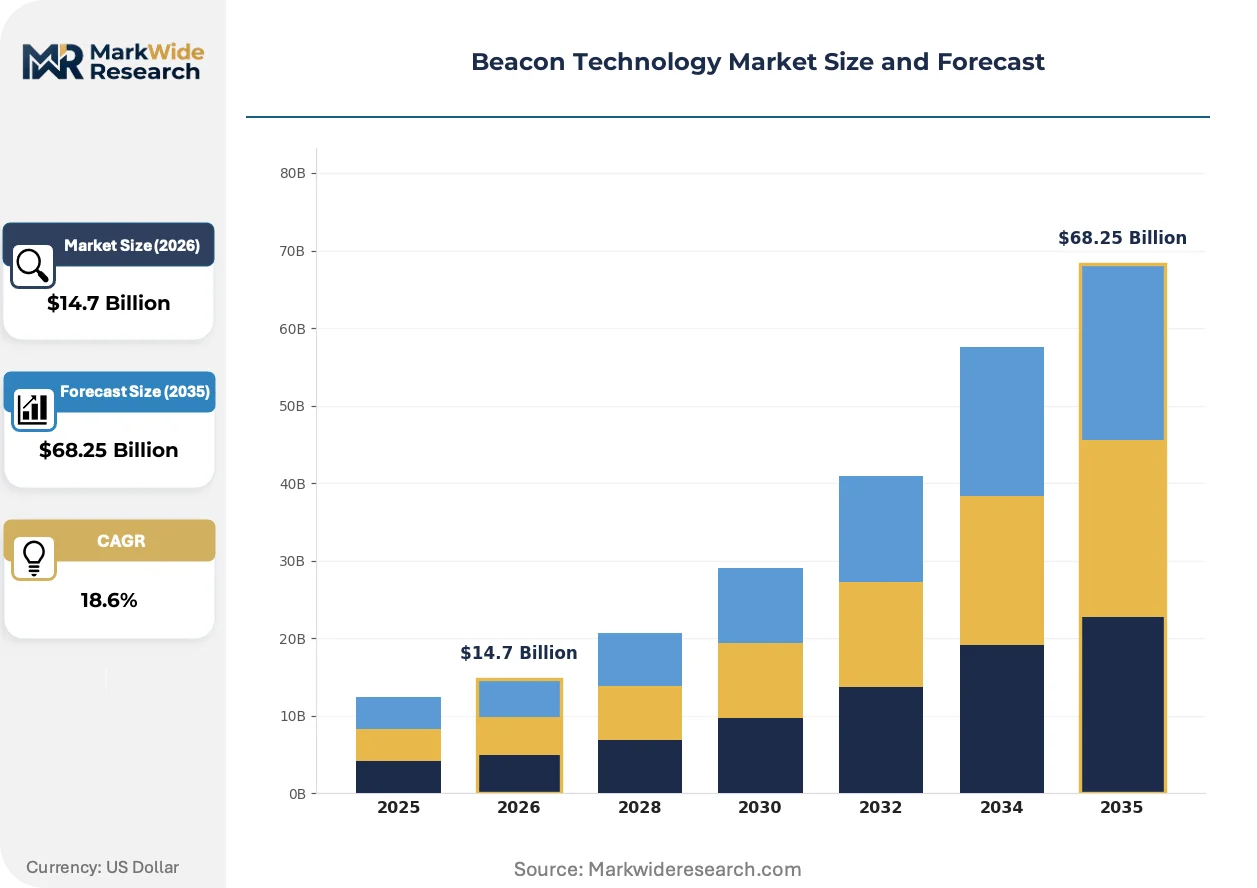
Market Dynamics
GDPR enforcement and the EU AI Act are compressing beacon deployment timelines across European retail and healthcare, forcing vendors to reengineer data flows before hardware ships. The FCC's 2.4 GHz power limits in the United States simultaneously constrain signal range planning, creating divergent technical specifications for transatlantic product lines.
Growth Catalysts
- Proximity marketing adoption:Retail chains in the United States deploy Bluetooth Low Energy beacons to trigger personalized push notifications at shelf-edge, converting foot traffic into measurable basket-size gains.
- GDPR-compliant edge processing:EU healthcare facilities favor beacons that process location data locally rather than routing through cloud servers, satisfying CNIL guidance on patient data minimization.
- Bluetooth Low Energy 5.3:The updated protocol extends broadcast range and reduces power draw, enabling coin-cell batteries to sustain industrial asset-tracking deployments for multi-year cycles.
Market Restraints
- Semiconductor supply concentration:Qualcomm Technologies anchors the Bluetooth Low Energy chipset layer, creating single-source dependency for third-party beacon hardware vendors.
- GDPR consent friction:The requirement for explicit opt-in before location data collection reduces effective capture rates in European retail environments compared to US counterparts.
- NFC substitution in payments:Tap-to-interact simplicity in contactless payment use cases displaces beacon-based proximity triggers where range precision is secondary to speed.
Strategic Opportunities
- Underpenetrated German healthcare:Hospital systems in Bavaria and North Rhine-Westphalia remain early-stage in indoor wayfinding deployments, presenting whitespace for beacon-integrated patient navigation.
- EU AI Act algorithmic transparency:Automated decision-making triggered by location data now requires explainability documentation, creating consulting and compliance tooling demand.
- Ultra-wideband convergence:UWB is unifying with Bluetooth Low Energy in hybrid tags that deliver centimeter-level precision for industrial asset tracking without dedicated infrastructure.
Industry Challenges
- Firmware security certification:ETSI harmonization requirements for cross-border frequency compliance extend hardware validation timelines by four to six months for EU-bound shipments.
- Legacy POS integration:Retailers operating on decade-old point-of-sale architectures face middleware complexity when routing beacon-triggered promotions into transaction systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beacon Technology Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $68.25 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge End User: Retail, Healthcare, Transportation, Entertainment Solution: Proximity Marketing, Asset Tracking, Indoor Navigation, Location-Based Services Technology: Bluetooth Low Energy, NFC, Wi-Fi, RFID |
| Companies Covered | Gimbal Inc., Qualcomm Technologies, Inc., Apple Inc., Cisco Systems, Inc., Hewlett Packard Enterprise Development LP, Estimote Inc., HID Global Corporation, Samsung Electronics Co., Ltd., Kontakt.io Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beacon Technology Market Emerging Trajectories
Beacon hardware is evolving from standalone transmitters into sensor-fusion nodes that combine location broadcasting with environmental monitoring. This convergence is compressing the addressable market for single-function devices while expanding total solution value.
Ultra-wideband is unifying with Bluetooth Low Energy in hybrid beacon form factors that deliver centimeter-level spatial precision. Industrial manufacturers in Germany and the United States are piloting these tags for real-time asset location without dedicated anchor infrastructure. The technology is unifying previously separate indoor positioning budgets into single hardware procurements.
The EU AI Act introduces algorithmic transparency obligations for automated decision-making triggered by beacon-derived location data. Retail analytics platforms must now document how proximity signals influence personalized pricing or promotion delivery. French and German retailers are restructuring campaign logic to satisfy CNIL and BfDI interpretive guidance ahead of formal enforcement.
Buyer procurement patterns are compressing beacon deployments into bundled facility-management contracts rather than standalone IT purchases. German hospital systems and US retail chains now source indoor positioning as a subscription service with hardware included. This shift concentrates vendor selection authority with facilities executives rather than technology officers.
Beacon Technology Market Segmentation
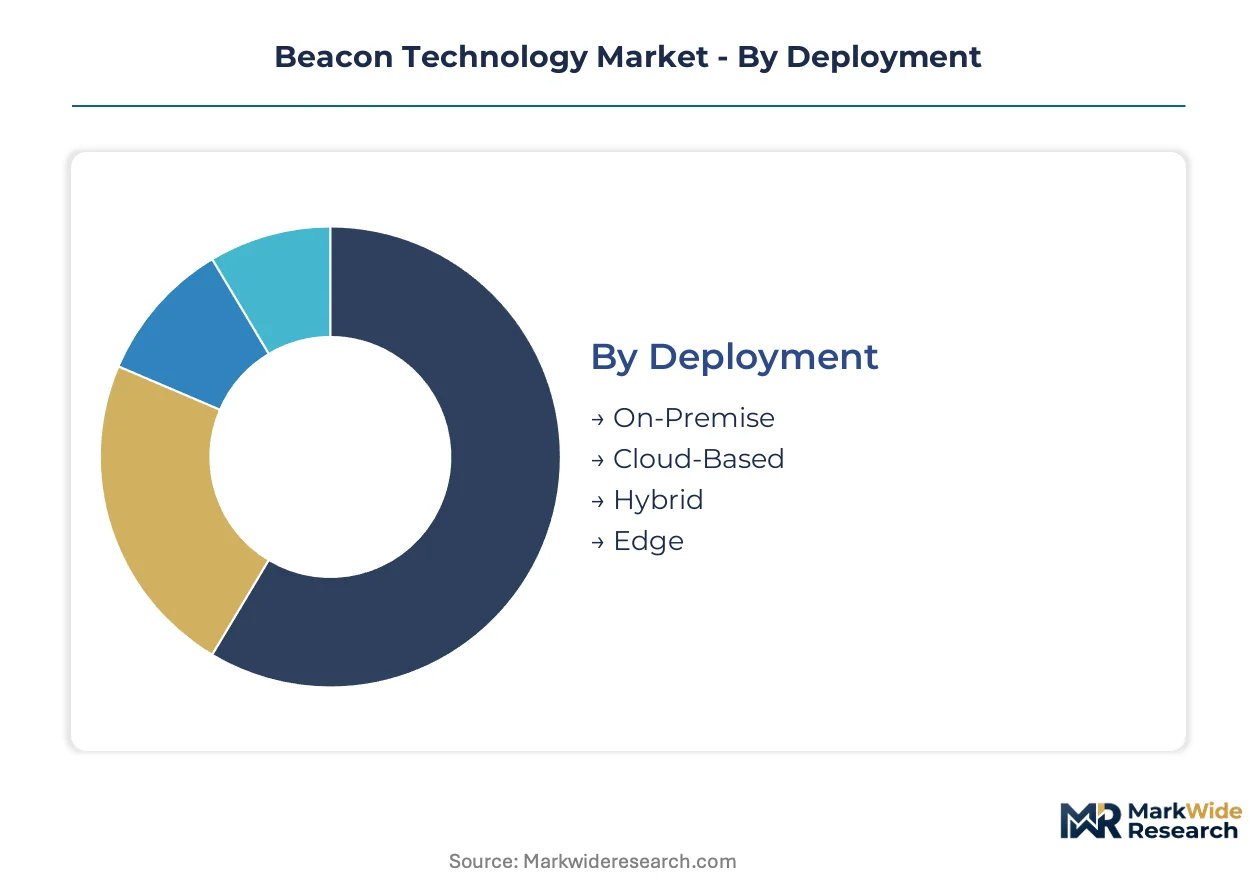
Beacon technology segments diverge sharply by integration depth, with standalone deployments dominating legacy retail while embedded edge-computing form factors capture healthcare and industrial growth corridors. Understanding these structural splits reveals where procurement authority is shifting and which technology layers command pricing power.
Deployment:
Standalone beacon installations require dedicated infrastructure investment, whereas embedded and edge configurations integrate location intelligence directly into existing sensor networks and gateway hardware.
- On-Premise:Self-hosted beacon management servers operate within facility firewalls, satisfying German hospital data residency requirements under BfDI guidance. Bavarian healthcare networks favor this architecture to maintain direct control over patient location records without third-party cloud exposure.
- Cloud-Based:Centralized fleet management platforms enable multi-location retailers to orchestrate thousands of beacons from single dashboards. United States retail chains deploy these configurations to synchronize proximity campaigns across hundreds of stores with unified analytics pipelines.
- Hybrid:Split architectures process sensitive location data locally while pushing anonymized analytics to cloud repositories. French retailers under CNIL jurisdiction adopt this pattern to balance personalization capabilities with GDPR minimization obligations.
- Edge:Compute-capable beacons execute location algorithms onboard without network transmission. Industrial manufacturers in the United States pilot these nodes for real-time asset tracking in bandwidth-constrained warehouse environments.
On-Premise deployments lead volumes today; Edge configurations are gaining share fastest.
End User:
Customer procurement maturity varies dramatically, with retail buyers optimizing for campaign conversion metrics while healthcare purchasers prioritize compliance documentation and patient safety outcomes.
- Retail:Shelf-edge beacon networks trigger personalized push notifications based on dwell time and purchase history. United States grocery and apparel chains measure ROI through basket-size uplift and promotion redemption rates captured at point-of-sale integration points.
- Healthcare:Indoor wayfinding and equipment location systems reduce patient anxiety and nurse search time. German hospital systems in North Rhine-Westphalia deploy BLE beacons for bed management and sterile asset tracking with ETSI-compliant frequency harmonization.
- Transportation:Transit hubs and logistics facilities deploy beacon grids for passenger flow optimization and vehicle location. Airport operators in the United States integrate proximity triggers with mobile boarding pass validation.
- Entertainment:Theme parks and stadiums leverage beacon-triggered content delivery for queue management and concession targeting. Venues combine location signals with demographic profiling to dynamically adjust pricing and promotion timing.
Retail commands the largest installed base; Healthcare is expanding most quickly.
Solution:
Margin concentration follows recurring revenue potential, with proximity marketing platforms capturing subscription analytics fees while asset tracking solutions compete on hardware procurement cycles.
- Proximity Marketing:Campaign orchestration platforms deliver location-triggered notifications and measure engagement through dwell-time analytics. United States retailers subscribe to these services on per-store monthly fees with performance-based tier upgrades.
- Asset Tracking:Real-time location systems monitor equipment, inventory, and personnel movement across industrial facilities. German manufacturers deploy BLE tags for tool crib management and work-in-progress tracking with multi-year battery life requirements.
- Indoor Navigation:Wayfinding applications guide users through complex environments using beacon triangulation and dead reckoning. Healthcare facilities in France integrate these solutions with appointment scheduling to reduce late arrivals and no-shows.
- Location-Based Services:Broad category encompassing contextual content delivery, access control, and environmental sensing triggers. Transportation operators combine these capabilities with passenger authentication for seamless gate-to-gate experiences.
Proximity Marketing dominates revenue today; Asset Tracking shows the steepest expansion trajectory.
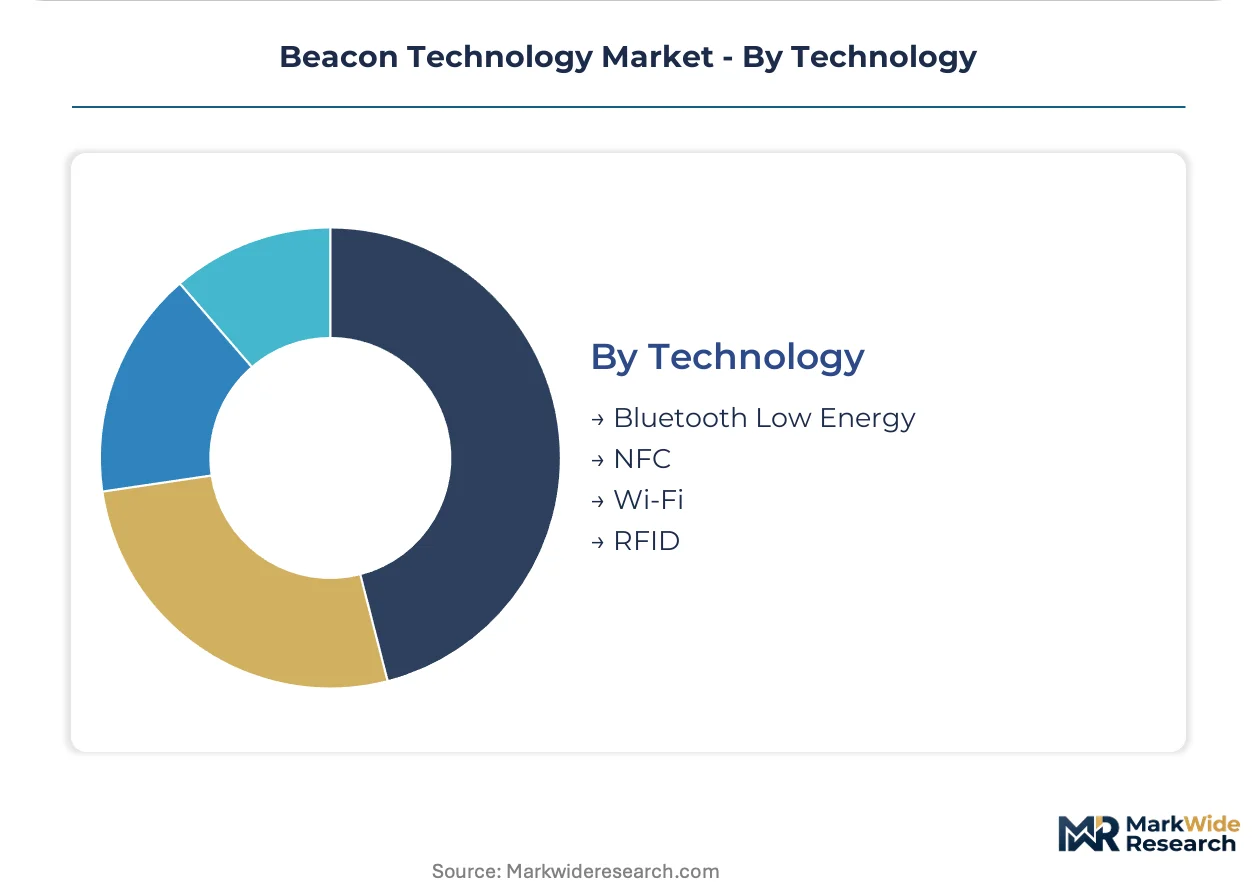
Technology:
Protocol selection trades range precision against power consumption and infrastructure requirements, with Bluetooth Low Energy achieving scale through smartphone ecosystem penetration.
- Bluetooth Low Energy:Dominant protocol broadcasting at 2.4 GHz with sub-100 mW power draw and months-to-years battery life. Qualcomm chipsets anchor hardware supply chains while Apple iOS and Google Android provide native detection layers without dedicated apps.
- NFC:Near-field communication enables tap-to-interact simplicity with centimeter-range precision. Payment-integrated use cases favor NFC where transaction speed outweighs proximity awareness requirements.
- Wi-Fi:Existing infrastructure repurposed for coarse-grained indoor positioning through signal strength triangulation. Enterprises with dense access point deployments avoid dedicated beacon hardware costs.
- RFID:Passive and active radio-frequency identification for inventory and supply chain tracking. Industrial logistics operations combine RFID gates with BLE beacons for hybrid visibility across facility and in-transit contexts.
Bluetooth Low Energy leads unit volumes today; NFC maintains structural importance in payment-integrated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The beacon technology industry traces its commercial origins to Silicon Valley's early 2010s mobile marketing experiments, with Nordic semiconductor manufacturers subsequently scaling Bluetooth Low Energy chipsets for mass deployment. Geographic expansion now follows divergent regulatory templates.
United States
Retail chains and airport operators drive proximity marketing adoption, with shelf-edge beacon networks triggering personalized notifications. The FCC governs 2.4 GHz power limits that constrain signal range planning. Major technology vendors cluster in California's Bay Area, where early mobile ecosystem partnerships established deployment protocols.
Germany
Hospital systems in Bavaria and North Rhine-Westphalia deploy indoor wayfinding for patient navigation and sterile asset tracking. BfDI guidance on data residency shapes on-premise architecture preferences. Industrial manufacturers in Baden-Württemberg pilot hybrid Ultra-wideband and Bluetooth Low Energy tags for centimeter-level precision.
France
Healthcare facilities integrate beacon-triggered appointment scheduling to reduce patient no-shows. CNIL interpretive guidance on GDPR minimization obligations drives hybrid cloud-edge deployments. Paris-based retail analytics platforms restructure campaign logic to satisfy algorithmic transparency requirements under the EU AI Act.
United Kingdom
Transportation hubs deploy beacon grids for passenger flow optimization and mobile boarding pass validation. Post-Brexit regulatory divergence from ETSI harmonization creates hardware certification complexity. London's financial services sector experiments with proximity-aware access control in corporate campuses.
Japan
Theme parks and retail complexes leverage beacon-triggered content delivery for queue management. METI standards coordination influences Bluetooth Low Energy protocol adoption timelines. Tokyo's dense urban environment creates unique signal density planning challenges for multi-floor indoor positioning.
Beacon Technology Market Vendor Landscape
The competitive structure tilts toward platform-ecosystem dominance layered atop semiconductor supply concentration. Two distinct tiers operate: technology giants controlling device detection layers and native SDK distribution, and specialized hardware vendors differentiating through edge-computing form factors and compliance-forward architectures. Consolidation pressures concentrate around strategic partnerships between chipset suppliers and cloud platform operators, while geographic expansion into GDPR-jurisdictions demands localized data flow reengineering.
Within the ecosystem-control tier, Apple Inc. and Qualcomm Technologies, Inc. anchor fundamentally different value capture mechanisms. Apple leverages iOS distribution to govern default beacon detection on billions of smartphones, while Qualcomm supplies the Bluetooth Low Energy chipsets powering third-party hardware. Estimote Inc. occupies a specialist position, exemplifying the edge-computing archetype through local data processing architectures that satisfy European healthcare compliance requirements without cloud transmission.
| Leading Market Players |
|---|
| Gimbal Inc. |
| Qualcomm Technologies, Inc. |
| Apple Inc. |
| Cisco Systems, Inc. |
| Hewlett Packard Enterprise Development LP |
| Estimote Inc. |
| HID Global Corporation |
| Samsung Electronics Co., Ltd. |
| Kontakt.io Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between GDPR-compliant edge-computing architectures and commodity cloud-dependent hardware creates distinct pricing corridors that reshape procurement patterns across European and North American deployments. This bifurcation concentrates margin capture with vendors offering localized data processing capabilities while compressing returns for undifferentiated transmitter manufacturers competing on unit cost alone.
Pricing Analysis
Bundled subscription services now dominate procurement decisions against legacy unbundled hardware purchases, with facilities-management contracts absorbing beacon fleets as operational expenditures rather than capital investments. Price differentiation rests on compliance certification depth—ETSI-validated and BfDI-aligned configurations command substantial premiums over uncertified alternatives. Pricing pressure stems from Qualcomm's chipset layer concentration, which constrains hardware vendors' ability to negotiate component costs. Healthcare purchasers in Germany exhibit lowest price sensitivity due to patient-safety liability exposure, while US retail chains prioritize per-store campaign ROI thresholds.
Supply Chain Analysis
Dual-sourcing requirements mandated by German hospital procurement committees and US retail chain risk protocols force hardware vendors to qualify secondary BLE chipset suppliers beyond Qualcomm's dominant position. Manufacturing concentrates in Taiwan for semiconductor fabrication, China for final assembly and battery integration, and the United States for firmware development and compliance engineering. Raw material dependencies span lithium coin-cell batteries, FR-4 substrate laminates, and injection-molded ABS enclosures. Single-source vulnerability at the BLE protocol stack layer creates systemic exposure. Distribution runs through specialized IoT distributors and direct enterprise sales teams serving multi-location retail and healthcare networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where GDPR compliance costs in Europe create margin pools unavailable in less regulated jurisdictions, rewarding vendors with pre-engineered data-residency architectures.
For Market Incumbents: To counter NFC substitution in payment-adjacent use cases, Qualcomm and ecosystem partners should deepen BLE protocol integration with existing POS infrastructure while accelerating edge-computing certification investments for EU healthcare verticals. Capacity addition in Taiwan and diversification into German engineering partnerships will defend position against emerging UWB-BLE hybrid competitors. For New Entrants and Emerging Players: Bavarian and North Rhine-Westphalian hospital systems remain underserved by compliant indoor navigation solutions, presenting whitespace for edge-native beacon platforms. Targeting mid-tier US grocery chains with subscription-based proximity marketing—bypassing legacy POS integration complexity—offers the most penetrable entry vector. A direct facilities-executive sales motion, bypassing IT procurement committees, accelerates initial deployment traction. For Investors and Strategic Acquirers: Consolidation pressure builds where edge-computing IP and GDPR compliance documentation create acquisition premiums for specialized hardware vendors. Long-term viability over the next decade hinges on UWB-BLE convergence capabilities and AI Act algorithmic transparency tooling. The signal to watch is CNIL enforcement patterns against non-compliant retail analytics platforms, which would accelerate replacement demand for certified alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Certification Investment | ETSI and BfDI alignment unlocks German healthcare procurement channels with multi-year contract visibility. |
| UWB-BLE Hybrid Tag Development | Centimeter-level precision without dedicated anchor infrastructure collapses indoor positioning budgets into single hardware lines. |
| Facilities-Management Partnership | Subscription bundling shifts vendor selection authority from CIOs to operations executives with faster procurement cycles. |
| GDPR-Compliant Analytics Platform | CNIL and EU AI Act documentation creates recurring revenue streams through compliance consulting retainers. |
| Qualcomm Chipset Diversification | Secondary BLE supplier qualification reduces single-source dependency and strengthens procurement negotiating position. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IoT procurement directors at US retail chains, German hospital biomedical engineering leads, French CNIL compliance officers, ETSI standardization committee members, and BLE chipset product managers with secondary validation. Data sources included FCC equipment authorization filings, ETSI harmonized standards documentation, SEC 10-K disclosures from semiconductor suppliers, and healthcare facility procurement databases. Bottom-up beacon deployment counts triangulated against top-down market sizing from component shipment data.
Comparable-period anchoring tied projection models to historical adoption curves across retail, healthcare, and industrial verticals over the analysis window. Segmentation dimensions spanned deployment architecture, end-user vertical, solution type, and protocol technology, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from logistic diffusion modeling of technology adoption S-curves, incorporating Bluetooth Low Energy 5.3 range extension parameters and EU AI Act implementation timelines as industry-specific forecast inputs.
Underlying measurement precision varies by segment; cloud-based deployment volumes carry tighter precision than emerging edge-computing configurations where vendor reporting remains fragmented. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and semiconductor supply normalization. Deviation in CNIL or BfDI interpretive guidance stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Robot Sensor Market
Sensors
Voice Sounders Market
Sensors
Global Position Tracking System Market
Sensors
NB-IoT Smart Gas Meter Market
Sensors
In-Counter Barcode Scanners Market
Sensors
Smart Barcode Readers Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Digital Direction Finder Market
Sensors
Automatic Number Plate Recognition (ANPR) Market
Sensors
Automated Weather Observation System Market
Sensors
IO Link Market
Sensors
Global Heat Stress Monitor (HSM) Market
Sensors
GNSS-Enabled Consumer Device Market
Sensors
Asia Pacific RFID Market
Sensors
Real Time Location System Market
Sensors
Connected Smart Thermostats Market