
 Body Area Network Market | 2026-2036
Body Area Network Market Size, Share, and Industry Trends Forecast 2026-2036
Body Area Network Market Analysis
China is tilting toward large-scale manufacturing of low-power biomedical sensors for export markets. Samsung Electronics Co., Ltd. leverages its semiconductor foundry capacity to sustain component cost advantages across wearable device lines. Medtronic plc anchors its position through deep specialization in implantable cardiac monitors with integrated wireless telemetry. Apple Inc. competes by controlling both hardware design and proprietary health data ecosystems.
A body area network comprises a collection of wearable, implantable, or body-mounted devices that communicate through short-range wireless protocols to aggregate physiological data at a central hub. These systems typically operate in the 2.4 GHz ISM band or sub-GHz medical telemetry bands with power budgets below 10 mW to ensure thermal safety and battery longevity for continuous skin contact or subcutaneous operation. Wearable devices and sensors capture the dominant share of unit volume, though implants command superior margin pools due to regulatory barriers and surgical placement requirements. Ultra-wideband technology is gaining traction for centimeter-scale indoor positioning of patients and assets, while Bluetooth retains its hold on consumer-facing fitness and health monitoring applications.
The FDA regulates wireless medical devices under 21 CFR Part 820 quality system requirements and enforces electromagnetic compatibility through FCC Part 15 rules for unlicensed transmitters. EMA's Medical Device Regulation imposes clinical evidence standards on body-worn and implantable network components sold in Europe, lengthening certification cycles but elevating entry barriers for marginal suppliers. Stakeholders must monitor how diverging radio-frequency exposure limits between jurisdictions reshape product architecture decisions and manufacturing location strategies.
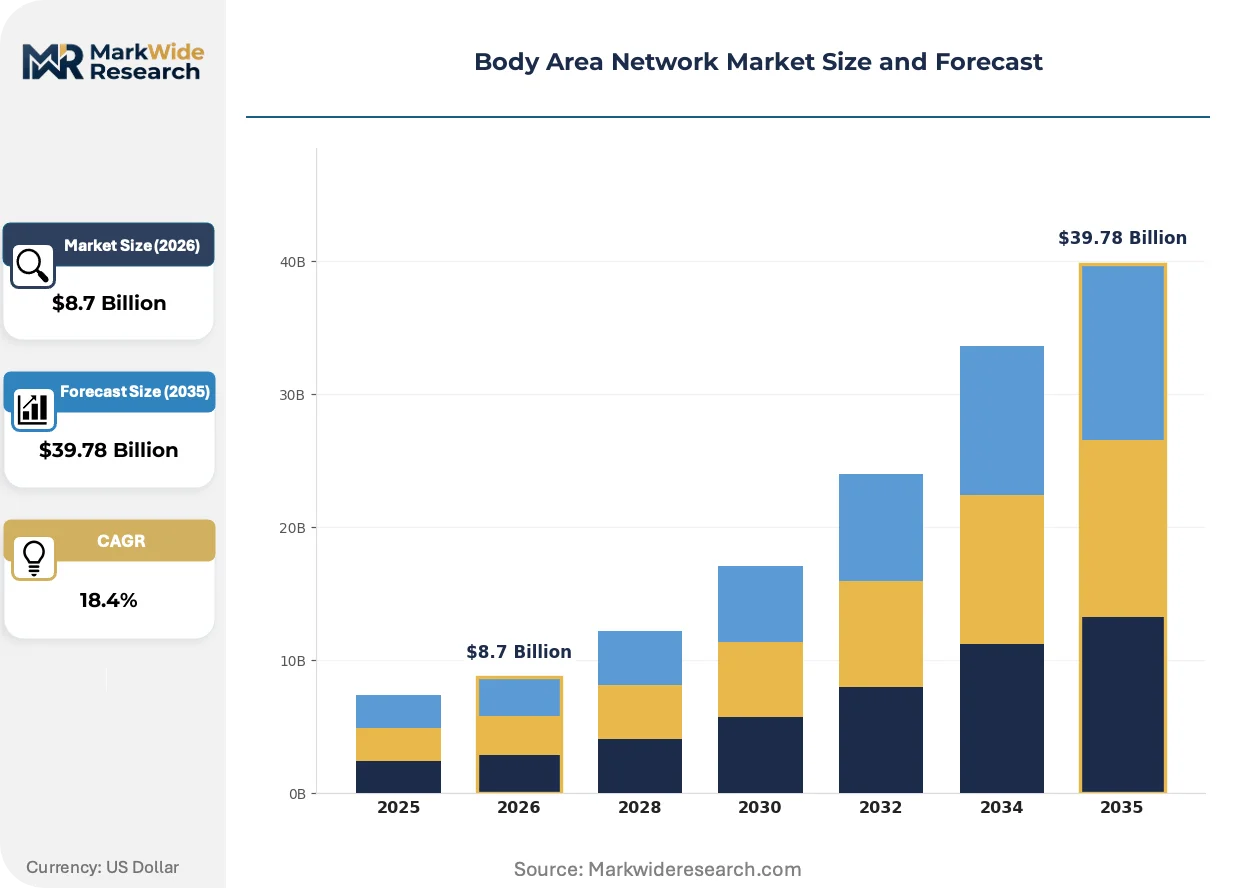
Market Dynamics
Continuous patient monitoring is compressing hospital discharge timelines and shifting care delivery toward ambulatory settings, forcing device architectures to prioritize low-latency wireless telemetry over episodic data capture.
Growth Catalysts
- FDA 510(k) clearance streamlining:The FDA's premarket notification pathway for wireless medical devices accelerates commercialization timelines for body-worn sensor platforms targeting cardiac and respiratory monitoring applications.
- Bluetooth Low Energy protocol maturation:BLE 5.3's enhanced power efficiency enables multi-day continuous monitoring without thermal discomfort, expanding adoption in pediatric and geriatric patient populations.
- United States hospital network consolidation:Integrated delivery networks in Texas, California, and New York are standardizing body-worn sensor procurement across affiliated facilities, creating volume pull-through for compatible device ecosystems.
Market Restraints
- Lithium-polymer cell cost volatility:Battery raw material price swings constrain margin stability for wearable manufacturers dependent on thin-film cell form factors.
- Taiwan semiconductor foundry concentration:Advanced biometric sensor ASIC fabrication relies heavily on TSMC and UMC capacity, creating single-source vulnerability for analog front-end components.
- Sub-GHz spectrum allocation fragmentation:Divergent medical telemetry band assignments between the FCC, ETSI, and Japan's MIC force multi-SKU hardware designs that inflate engineering overhead.
Strategic Opportunities
- Rural India diagnostic penetration:Community health worker programs present deployment channels for ultra-low-power BAN kits operating on narrowband IoT infrastructure.
- EU MDR Article 10 clinical evidence requirements:Stricter post-market surveillance mandates create competitive moats for manufacturers with established notified body relationships and clinical data repositories.
- Ultra-wideband and radar sensor convergence:Impulse radio UWB combined with millimeter-wave radar enables contactless vital sign monitoring, opening non-adherent patient segments previously excluded from continuous monitoring.
Industry Challenges
- RF antenna design specialization scarcity:Engineers capable of optimizing near-body propagation at 2.4 GHz while meeting SAR limits command premium compensation, constraining R&D team scaling.
- HIPAA Security Rule technical safeguard implementation:Encrypting PHI across multi-hop BAN topologies while preserving real-time latency requirements demands cryptographic architecture expertise that outpaces available talent pools.
- Legacy EHR integration complexity:Proprietary data formats from dominant electronic health record vendors force costly middleware development for seamless physiological data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Area Network Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Implants, Sensors, Monitors Technology: Bluetooth, Zigbee, NFC, Ultra-Wideband End User: Healthcare Providers, Fitness Enthusiasts, Patients, Research Institutions Application: Health Monitoring, Fitness Tracking, Chronic Disease Management, Emergency Services |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Fitbit, Inc., Garmin Ltd., Fossil Group, Inc., Medtronic plc, Huawei Technologies Co., Ltd., Xiaomi Corporation, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Area Network Market Emerging Trajectories
Digital twin architectures are migrating from industrial asset management into patient-specific physiological modeling, compressing the feedback loop between biometric capture and clinical intervention.
Edge AI inference engines embedded directly within wearable SoCs are virtualizing the traditional hub-and-spoke BAN topology. Hospital IT departments in the United States are deploying these devices at scale in step-down units. This virtualization eliminates dependency on paired smartphones or bedside gateways, reducing infrastructure capital requirements while hardening data security through localized processing.
The EU Medical Device Regulation's post-market clinical follow-up requirements are extending surveillance obligations across the entire device lifecycle. Manufacturers must now fund ongoing PMCF studies for implantable cardiac monitors with wireless telemetry capabilities. High-margin implant segments face compressed profitability as clinical evidence generation costs amortize across smaller unit volumes than projected during MDR transition planning.
Hospital procurement departments are consolidating vendor relationships around full-stack monitoring platforms rather than discrete sensor hardware. United States health systems in Florida and Ohio now mandate API interoperability certifications as table-stake qualification criteria. This behavioral shift elevates ecosystem breadth over single-device performance specifications in competitive evaluations.
Body Area Network Market Segmentation
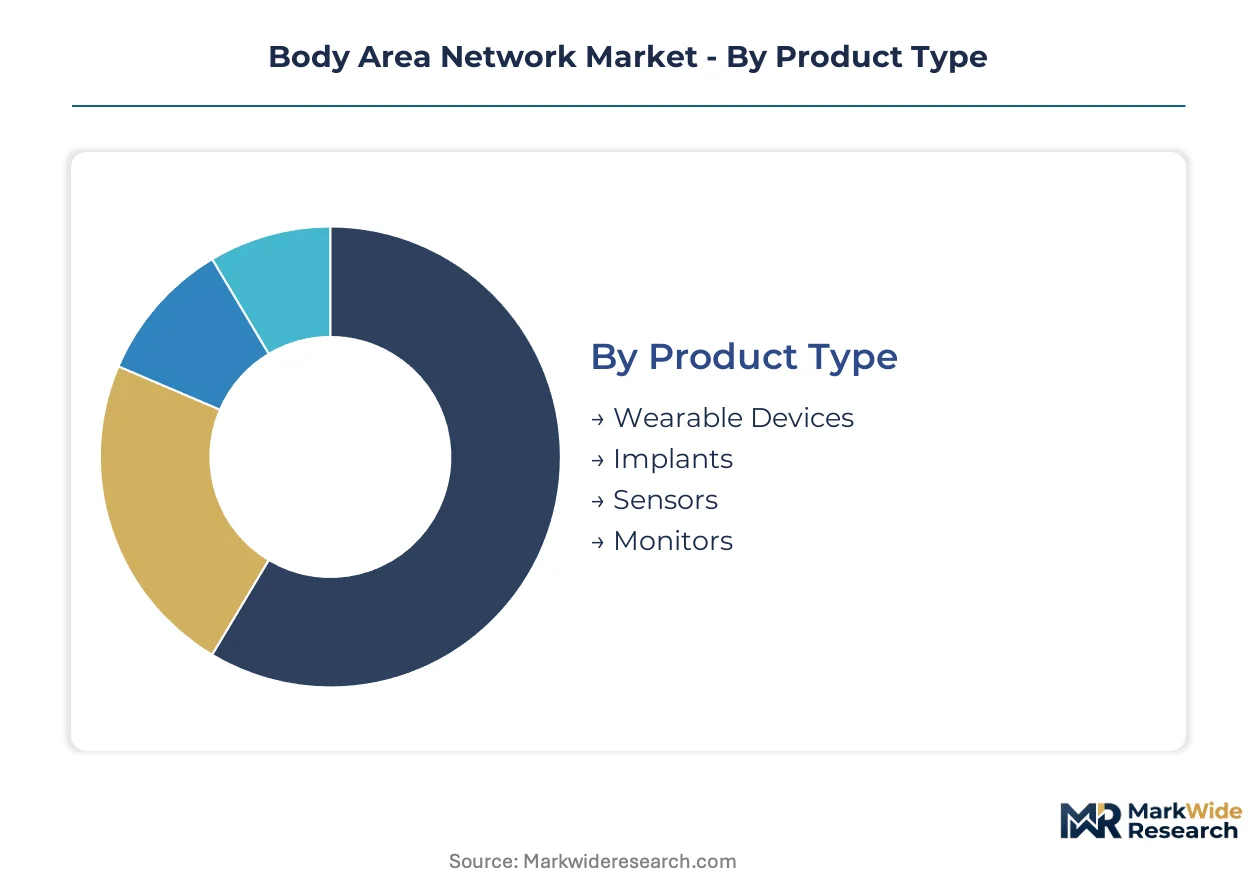
Segmentation in body area networks reveals distinct service intensity profiles across hardware categories. After-sales requirements vary dramatically between implantable and wearable form factors, reshaping vendor business models and customer lifetime value calculations.
Product Type:
After-sales-service intensity diverges sharply across hardware form factors in this category, with surgical placement and explantation requirements driving fundamentally different support economics than skin-worn alternatives.
- Wearable Devices:Skin-contact peripherals incorporating flexible substrates and conformal antennas for multi-day adhesion. Demand concentrates in United States hospital step-down units where FDA 510(k) clearance accelerates procurement cycles for cardiac event monitors. BLE 5.3 power efficiency eliminates thermal discomfort complaints that previously limited geriatric compliance.
- Implants:Subcutaneous or intracorporeal devices with hermetic sealing and biocompatible encapsulation for multi-year residence. Cardiac rhythm management applications dominate volume in integrated delivery networks across Texas and California, where wireless telemetry enables remote monitoring reimbursement codes.
- Sensors:Discrete transducers measuring electrophysiological, biochemical, or mechanical parameters with analog front-end ASICs.
- Monitors:Hub-class devices aggregating multi-sensor streams with local edge processing capability.
By volume, Wearable Devices leads. By growth pace, Implants is ahead.
Technology:
Protocol selection determines power budget allocation, regulatory pathway complexity, and interoperability certification costs across deployment scenarios.
- Bluetooth:Dominant protocol for consumer-facing and clinical wearable applications operating in the 2.4 GHz ISM band with adaptive frequency hopping. Fitness and general wellness monitoring in United States retail channels drives shipment concentration, though hospital IT departments increasingly mandate BLE 5.3 for enterprise device qualification.
- Ultra-Wideband:Impulse radio technology enabling centimeter-scale indoor positioning and radar-based contactless vital sign detection. United States health systems in Florida deploy UWB for patient and asset tracking in emergency departments, while research institutions explore non-adherent cardiac monitoring applications previously excluded from continuous surveillance.
- Zigbee:Mesh-capable protocol optimized for low-duty-cycle sensor networks with sub-50 mW power budgets.
- NFC:Near-field coupling for passive or semi-passive devices requiring proximity activation and high-security pairing workflows.
Bluetooth dominates absolute deployment count. Ultra-Wideband exhibits the steepest expansion trajectory as radar-vital-sign convergence matures.
End User:
Customer procurement sophistication and reimbursement access create tiered pricing power dynamics across stakeholder categories.
- Healthcare Providers:Hospital networks, ambulatory surgery centers, and physician group practices with dedicated biomedical engineering staff. Integrated delivery networks in New York and Ohio standardize body-worn sensor procurement across affiliated facilities, creating volume concentration for compatible device ecosystems with API interoperability certifications.
- Patients:Direct-pay individuals managing chronic conditions outside institutional reimbursement frameworks. Rural India community health worker programs present deployment channels for ultra-low-power kits operating on narrowband IoT infrastructure, bypassing formal provider procurement.
- Fitness Enthusiasts:Consumer segment prioritizing aesthetic design and smartphone ecosystem integration over clinical accuracy.
- Research Institutions:Academic medical centers and contract research organizations generating PMCF data under EU MDR Article 10 requirements.
Healthcare Providers command the largest revenue pool. Patients are gaining share fastest as direct-to-consumer cardiac monitoring bypasses traditional gatekeepers.
Application:
Use-case urgency and clinical liability exposure determine regulatory scrutiny intensity and product liability insurance costs.
- Health Monitoring:Continuous physiological surveillance spanning vital signs, glucose, and cardiac rhythm for acute and post-acute populations. United States step-down units deploy edge-AI-enabled wearables at scale, eliminating dependency on paired smartphones while hardening data security through localized processing.
- Chronic Disease Management:Longitudinal tracking for diabetes, heart failure, and hypertension with automated alert escalation. Medicare reimbursement for remote patient monitoring drives adoption in Florida health systems, where hospital procurement departments mandate full-stack platform compatibility over discrete sensor performance.
- Fitness Tracking:Consumer wellness applications with voluntary data sharing and limited clinical claims.
- Emergency Services:Pre-hospital vital sign transmission and mass-casualty triage coordination.
Health Monitoring leads by installed base. Chronic Disease Management is climbing the fastest as ambulatory care shifts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors regional demand through its dense network of integrated delivery systems and FDA 510(k) clearance pathways that compress commercialization timelines for wireless medical devices.
United States
Hospital networks in Texas, California, and New York standardize body-worn sensor procurement across affiliated facilities, creating volume concentration for compatible device ecosystems. Medicare reimbursement codes for remote patient monitoring accelerate adoption in Florida health systems. The FDA regulates wireless medical devices under 21 CFR Part 820 quality system requirements, enforcing electromagnetic compatibility through FCC Part 15 rules. Greater Boston hosts research institutions exploring edge-AI-enabled wearables for step-down units.
Germany
Industrial automation clusters in Bavaria and Baden-Württemberg supply precision biomedical sensor manufacturing equipment to global device makers. The EU Medical Device Regulation imposes clinical evidence standards that lengthen certification cycles but elevate entry barriers for marginal suppliers. EMA's post-market surveillance mandates create competitive moats for manufacturers with established notified body relationships. The Rhine-Ruhr metropolitan region concentrates medical technology engineering talent for RF antenna optimization.
China
Zhengzhou and Shenzhen manufacturing corridors tilt toward large-scale production of low-power biomedical sensors for export markets. NMPA medical device registration requirements are converging toward international standards, streamlining dual-market certification strategies. MIIT spectrum allocation policies shape sub-GHz product architecture decisions for domestic manufacturers. The Yangtze River Delta hosts semiconductor foundry capacity that sustains component cost advantages across wearable device lines.
Japan
Tokyo and Osaka metropolitan areas concentrate aging-population demand for continuous glucose monitoring and cardiac rhythm management devices. PMDA pharmaceutical and medical device agency reviews emphasize clinical endpoint validation for implantable network components. METI industrial policy supports narrowband IoT infrastructure deployment for rural diagnostic penetration. The Kansai region hosts precision component suppliers for hermetic sealing technologies in implantable devices.
India
Maharashtra and Karnataka state health departments deploy community health worker programs with ultra-low-power BAN kits operating on narrowband IoT infrastructure. CDSCO medical device rules are harmonizing with international standards, though import dependency for advanced biometric sensor ASICs persists. The PLI scheme for electronics manufacturing incentivizes domestic assembly of wearable health monitors. Telangana's Hyderabad corridor attracts medical device R&D investments targeting price-sensitive diagnostic segments.
Body Area Network Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying analog front-end ASICs and conformal antenna substrates to branded device manufacturers. Market structure tilts toward consolidation at the platform level, with hospital procurement departments mandating API interoperability certifications that favor full-stack ecosystems over discrete hardware vendors. Three archetypes dominate: semiconductor foundries with captive health divisions, pure-play wearable specialists with direct-to-consumer channels, and diversified medtech conglomerates with implantable portfolios. Competitive moves concentrate on strategic partnerships for EHR integration middleware and geographic licensing arrangements for sub-GHz spectrum compliance.
Among technology conglomerates with health divisions, Apple Inc. and Samsung Electronics Co., Ltd. exemplify platform integrators controlling both hardware design and proprietary data ecosystems. Medtronic plc anchors the implantable specialist tier through deep specialization in cardiac monitors with integrated wireless telemetry. These three companies represent distinct competitive vectors: consumer electronics scale, semiconductor foundry capacity, and clinical regulatory depth.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Fitbit, Inc. |
| Garmin Ltd. |
| Fossil Group, Inc. |
| Medtronic plc |
| Huawei Technologies Co., Ltd. |
| Xiaomi Corporation |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwan semiconductor foundry capacity for advanced biometric sensor ASICs compresses margin buffers across wearable tiers while simultaneously forcing multi-SKU hardware designs that inflate engineering overhead and widen pricing spreads between premium and economy configurations.
Pricing Analysis
Volume-discount tiering structures separate FDA 510(k)-cleared cardiac monitors from uncertified fitness peripherals, with certification grade and after-sales service bundling as the primary price differentiation drivers. Pricing pressure stems from lithium-polymer cell cost volatility constraining margin stability for thin-film form factor manufacturers. Healthcare providers in United States integrated delivery networks exhibit lowest price sensitivity due to Medicare reimbursement codes, while direct-pay patients in emerging markets face acute affordability constraints.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for body-worn sensor platforms. Component sourcing draws from Taiwan for analog front-end ASICs, China for flexible substrate manufacturing, and South Korea for display and battery cell supply. Raw material dependencies center on lithium carbonate, rare-earth magnets for haptic feedback, and biocompatible silicone encapsulants. Distribution runs through hospital procurement departments consolidating vendor relationships around full-stack monitoring platforms rather than discrete hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement mandates for API interoperability certifications signal a platform-economics inflection that elevates ecosystem breadth over single-device performance in competitive evaluations.
For Market Incumbents: Insulate margin position by deepening captive semiconductor foundry relationships to offset TSMC capacity constraints, and accelerate EHR integration middleware development to satisfy United States health system procurement requirements. Edge-AI-enabled wearables with localized processing represent the critical defensive perimeter against consumer electronics entrants. For New Entrants and Emerging Players: Pursue rural India community health worker deployment channels where ultra-low-power narrowband IoT kits bypass formal provider procurement gatekeepers. Contactless vital sign monitoring through UWB-radar convergence offers the most penetrable white-space segment for non-adherent patient populations previously excluded from continuous surveillance. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-stack platform integrators with established notified body relationships and clinical data repositories. Acquisition targets should demonstrate EU MDR Article 10 compliance infrastructure and post-market clinical follow-up funding capacity. The signal to watch is hospital procurement department consolidation velocity around vendor ecosystems with demonstrated API interoperability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | United States integrated delivery networks standardize procurement across affiliated facilities, creating volume concentration. |
| FDA 510(k) Submission | FDA clearance pathways compress commercialization timelines for wireless cardiac and respiratory monitoring applications. |
| CE Marking Pathway | EU MDR clinical evidence requirements lengthen certification cycles but elevate entry barriers for marginal suppliers. |
| Software Companion Development | Edge-AI inference engines embedded in wearable SoCs eliminate smartphone dependency and harden data security. |
| Reimbursement Strategy | Medicare remote patient monitoring codes accelerate adoption in Florida and Texas health systems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at wireless medical device manufacturers. Secondary validation drew from FDA 510(k) clearance databases, EMA Medical Device Regulation submission records, CMS Medicare reimbursement code filings, and hospital procurement contract repositories. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Calibration against historical adoption curves for continuous patient monitoring systems anchored the analytical framework. Segmentation dimensions modeled include hardware form factor, wireless protocol technology, end-user procurement sophistication, and clinical application urgency. CAGRs were derived from regression analysis of installed base expansion rates and reimbursement policy evolution. Industry-specific forecast inputs incorporated BLE protocol maturation trajectories and sub-GHz spectrum allocation harmonization progress.
Macroeconomic conditions sit as an overlay; deviation in lithium raw material pricing, Taiwan semiconductor foundry utilization rates, or FDA clearance processing timelines would shift the trajectory. Forecasts reflect assumptions about regulatory pathway stability and hospital IT infrastructure investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Lidar in Construction Market
Sensors
Beacon Market
Sensors
Sensor Landscape in Robotics and ADAS Vehicle Market
Sensors
Traffic Sensor Market
Sensors
Digital Compass (E-Compass) Market
Sensors
Vision Positioning System Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Handheld RFID Readers Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Surface Haptic Technology Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Automated Weather Observation System Market
Sensors
Asset Tracking Market
Sensors
Global Positioning Systems Market
Sensors
Europe RFID Market