
 Portable Iris Recognition Scanner Market | 2026-2036
Portable Iris Recognition Scanner Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Iris Recognition Scanner Market Insights
Aftermarket service revenue is narrowing as hardware margins compress across the portable iris recognition scanner industry. NEC Corporation leverages its long-standing government relationships across Asia-Pacific to sustain recurring maintenance contracts. Thales Group anchors European defense and civil ID programs through certified biometric enrollment systems. IDEMIA competes aggressively in Africa and Latin America with modular field-deployable kits.
A portable iris recognition scanner captures near-infrared images of the unique trabecular meshwork patterns in the human iris, typically operating at wavelengths between 700 and 900 nanometers for optimal penetration of melanin variations. The device performs one-to-one or one-to-many matching against encrypted templates for high-assurance identity verification in mobile or unattended settings. Embedded scanners integrated into biometric terminals command the widest deployment footprint, while standalone units retain premium pricing in defense and diplomatic applications. Optical sensor technology leads volume shipments, though digital image processing capabilities are widening performance gaps between tier-one and tier-two suppliers.
The EU AI Act and GDPR impose strict algorithmic transparency and biometric data retention limits on deployments across Europe, while the FDA regulates iris-based patient identification systems in US healthcare settings under medical device pathways. BIS certification requirements in India and NMPA standards in China create divergent compliance costs for manufacturers seeking multi-country presence. Stakeholders must weigh regulatory fragmentation against the consolidation benefits of pursuing mutual recognition agreements for biometric equipment testing protocols.
Market Dynamics
Near-infrared imaging maturation is compressing hardware differentiation cycles and forcing suppliers to compete on algorithmic performance rather than optical component superiority alone.
Growth Catalysts
- Aviation Security Mandates:Saudi Arabia and the UAE are deploying portable iris scanners at airport biometric checkpoints under national aviation security frameworks, creating immediate procurement pull.
- GDPR-Compliant Contactless ID:European civil ID programs are prioritizing iris recognition over fingerprint systems to satisfy biometric data minimization requirements while maintaining authentication assurance.
- Melanin-Penetrating Wavelength Optimization:Advances in 700-900 nanometer sensor tuning are expanding addressable populations across diverse demographic profiles previously underserved by optical biometric systems.
Market Restraints
- Specialized Sensor Supply Concentration:Production of military-grade near-infrared CMOS sensors concentrates among a limited set of Japanese and South Korean foundries, exposing procurement timelines to allocation risk.
- Algorithm Training Data Scarcity:High-quality iris image datasets for diverse ethnic and age demographics remain concentrated in institutional vaults, constraining new entrant model development.
- EU AI Act Compliance Burden:Algorithmic transparency documentation and biometric data retention limits impose fixed compliance costs that disproportionately burden smaller hardware suppliers.
Strategic Opportunities
- Indian National ID Modernization:BIS certification pathways and the Aadhaar ecosystem expansion create a procurement window for field-deployable enrollment kits in rural and mobile settings.
- Healthcare Patient Identification:FDA-regulated iris-based matching systems for hospital settings remain underpenetrated relative to wristband and barcode alternatives, offering a vertical pivot.
- Edge AI Convergence:On-device template matching combining embedded neural accelerators with optical sensors enables offline authentication for defense and diplomatic use cases without cloud dependency.
Industry Challenges
- Biometric Engineer Talent Scarcity:The intersection of optical physics, embedded systems, and privacy-preserving cryptography commands premium compensation, constraining R&D team scaling.
- Multi-Jurisdiction Certification Parallelism:Simultaneous pursuit of BIS, NMPA, and FDA clearances requires divergent testing protocols and documentation standards, extending time-to-revenue.
- Legacy System Integration Complexity:Defense and diplomatic buyers demand backward compatibility with existing biometric template databases, forcing continued support for deprecated encryption standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Iris Recognition Scanner Market |
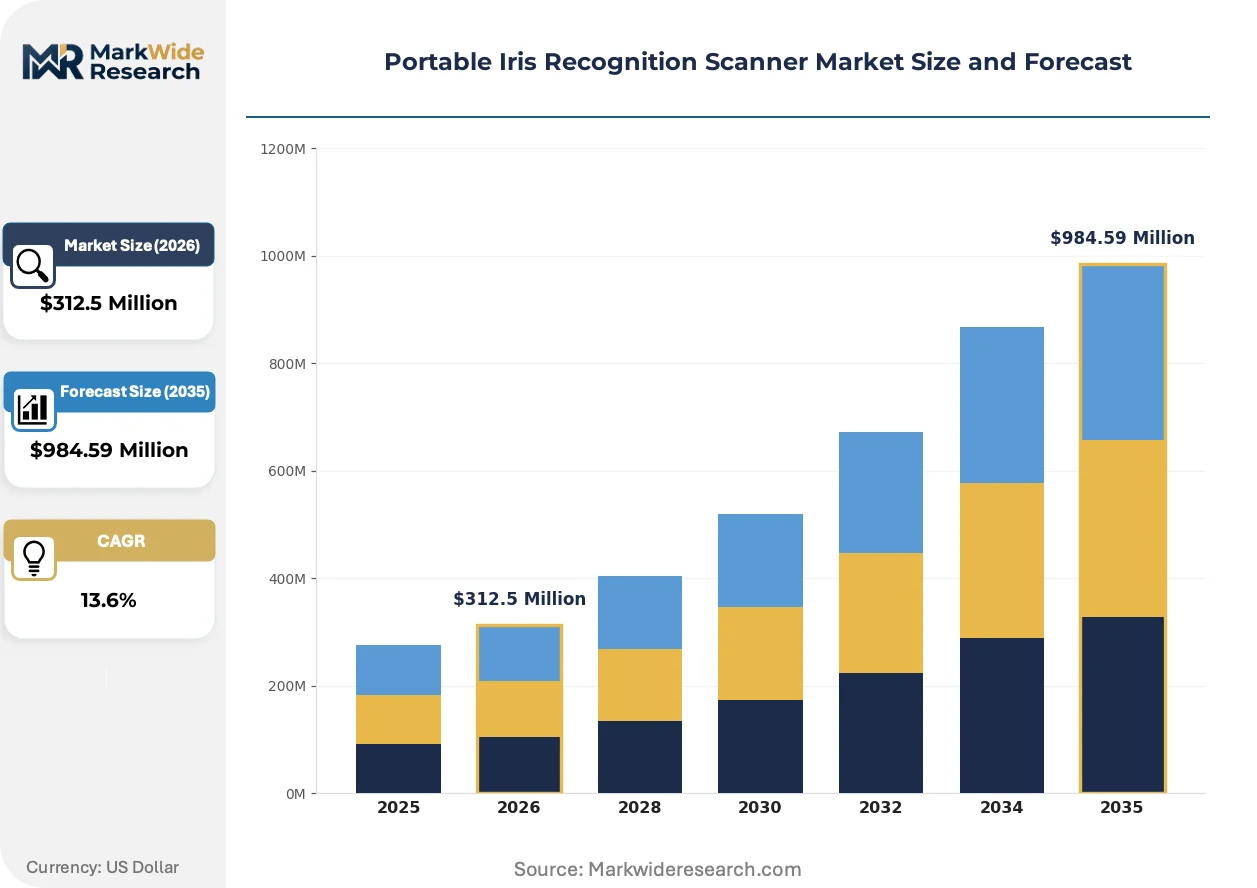
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $984.59 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Scanners, Embedded Scanners, Mobile Devices, Biometric Terminals End User: Government Agencies, Healthcare Facilities, Banking Sector, Education Institutions Technology: Near-Infrared Imaging, Laser Scanning, Digital Image Processing, Optical Sensors Application: Identity Verification, Access Control, Border Security, Time and Attendance |
| Companies Covered | NEC Corporation, Iritech, Thales Group, EyeLock, Princeton Identity, IDEMIA, HID Global, CMITech, Iris ID, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Iris Recognition Scanner Market Trends and Innovations
Active miniaturization of optical assemblies is redrawing competitive boundaries between embedded terminal suppliers and standalone device specialists.
Silicon photonics is collapsing the size-cost-performance tradeoff for near-infrared illumination modules. Defense contractors and border control agencies in Germany and Australia are accelerating procurement of sub-200-gram handheld units. This compression is eliminating the historical premium pricing tier for standalone portable scanners as embedded alternatives achieve parity in capture reliability.
The EU AI Act's high-risk system classification for biometric identification is mandating algorithmic audit trails and human-in-the-loop override capabilities. European civil ID program managers are now requiring ISO/IEC 30107-3 presentation attack detection certification as a baseline procurement filter. Tier-one suppliers with pre-positioned compliance documentation are capturing tender awards ahead of smaller competitors scrambling to retrofit documentation packages.
Aftermarket service unbundling is fragmenting buyer-supplier relationships across Middle Eastern aviation deployments. Airlines and airport authorities in Dubai and Riyadh are separating hardware procurement from maintenance contracts, enabling third-party technical service providers to intermediate. This disintermediation is compressing recurring revenue visibility for original equipment manufacturers while expanding margin pressure on field service operations.
Portable Iris Recognition Scanner Market Segmentation
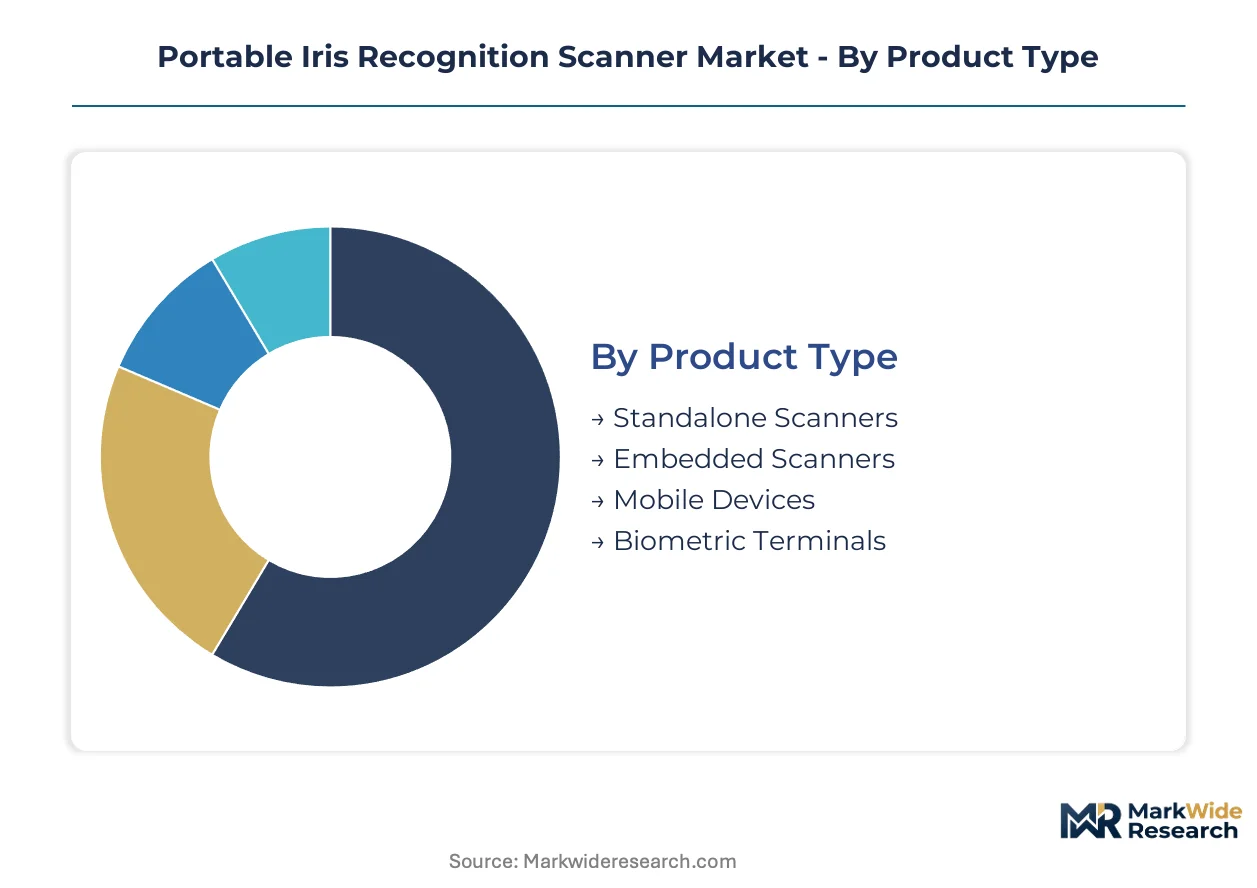
Segmentation reveals how portable iris recognition scanner suppliers must balance hardware form factors against deployment environments. Each dimension—product architecture, end-user security requirements, imaging technology, and application intensity—creates distinct procurement criteria and margin profiles.
Product Type:
Mature embedded terminal architectures coexist with emerging ultralight handheld designs reshaping field deployment economics.
- Standalone Scanners:Self-contained units with integrated illumination, capture optics, and onboard processing enable rapid deployment at temporary checkpoints. Defense and diplomatic buyers in Saudi Arabia and Germany drive demand for MIL-STD-810G ruggedized variants capable of offline template matching in denied-network environments.
- Embedded Scanners:Modular optical subsystems integrated into kiosks, gates, and vehicle consoles dominate aviation and border control procurement volumes. Dubai International Airport's biometric corridor deployment exemplifies how embedded units reduce per-lane hardware costs while maintaining throughput targets under national aviation security mandates.
- Mobile Devices:Smartphone-connected peripherals and tablet-docked modules serve rural enrollment and remote identity verification workflows.
- Biometric Terminals:Multi-factor authentication stations combining iris, face, and card readers anchor permanent facility access control installations.
Embedded scanners retain volume leadership; mobile devices hold the steepest expansion curve.
End User:
Cost tier stratification separates high-assurance government deployments from price-sensitive education procurement.
- Government Agencies:National ID authorities, defense ministries, and border control agencies specify FIPS 201-compliant enrollment and authentication systems. The UAE's Federal Authority for Identity and Citizenship operates one of the largest active iris template databases, driving recurring scanner procurement for field enrollment campaigns.
- Healthcare Facilities:Hospitals and health systems deploy iris matching to eliminate patient misidentification during registration and medication administration. FDA-regulated installations require 21 CFR Part 820 quality system documentation, constraining vendor qualification to established medical device suppliers.
- Banking Sector:Financial institutions deploy branch-based and ATM-integrated scanners for high-value transaction authentication.
- Education Institutions:Universities and examination boards adopt iris recognition for test proctoring and campus access control.
Government agencies retain volume leadership; healthcare facilities hold the steepest expansion curve.
Technology:
Supply concentration in near-infrared componentry creates performance differentiation gaps between integrated and modular optical approaches.
- Near-Infrared Imaging:Wavelength-tuned illumination between 700-900 nanometers penetrates melanin variation across diverse demographic profiles. Japanese and South Korean CMOS foundries control military-grade sensor supply, exposing procurement timelines to allocation constraints during defense procurement surges.
- Digital Image Processing:On-device template extraction and matching algorithms enable offline authentication without cloud dependency. Edge AI convergence—combining neural accelerators with optical sensors—expands addressable use cases for denied-network defense and diplomatic deployments.
- Laser Scanning:Time-of-flight and structured light approaches serve specialized high-resolution enrollment applications.
- Optical Sensors:Conventional CCD and CMOS capture modules anchor cost-optimized commercial deployments.
Near-infrared imaging retains volume leadership; digital image processing holds the steepest expansion curve.
Application:
Application intensity varies from continuous authentication workflows to episodic identity verification events.
- Identity Verification:One-to-one matching against stored templates underpins national ID programs, voter registration, and benefit distribution. India's Aadhaar ecosystem generates sustained procurement demand for BIS-certified field enrollment kits capable of rural deployment.
- Border Security:Automated biometric gates and manual secondary inspection stations process travelers against watchlists and visa databases. Australian Border Force procurement of sub-200-gram handheld units exemplifies miniaturization priorities for mobile enforcement teams.
- Access Control:Facility entry and restricted area authentication drive recurring maintenance contract revenue.
- Time and Attendance:Workforce tracking applications in manufacturing and logistics deploy iris recognition to prevent buddy-punching fraud.
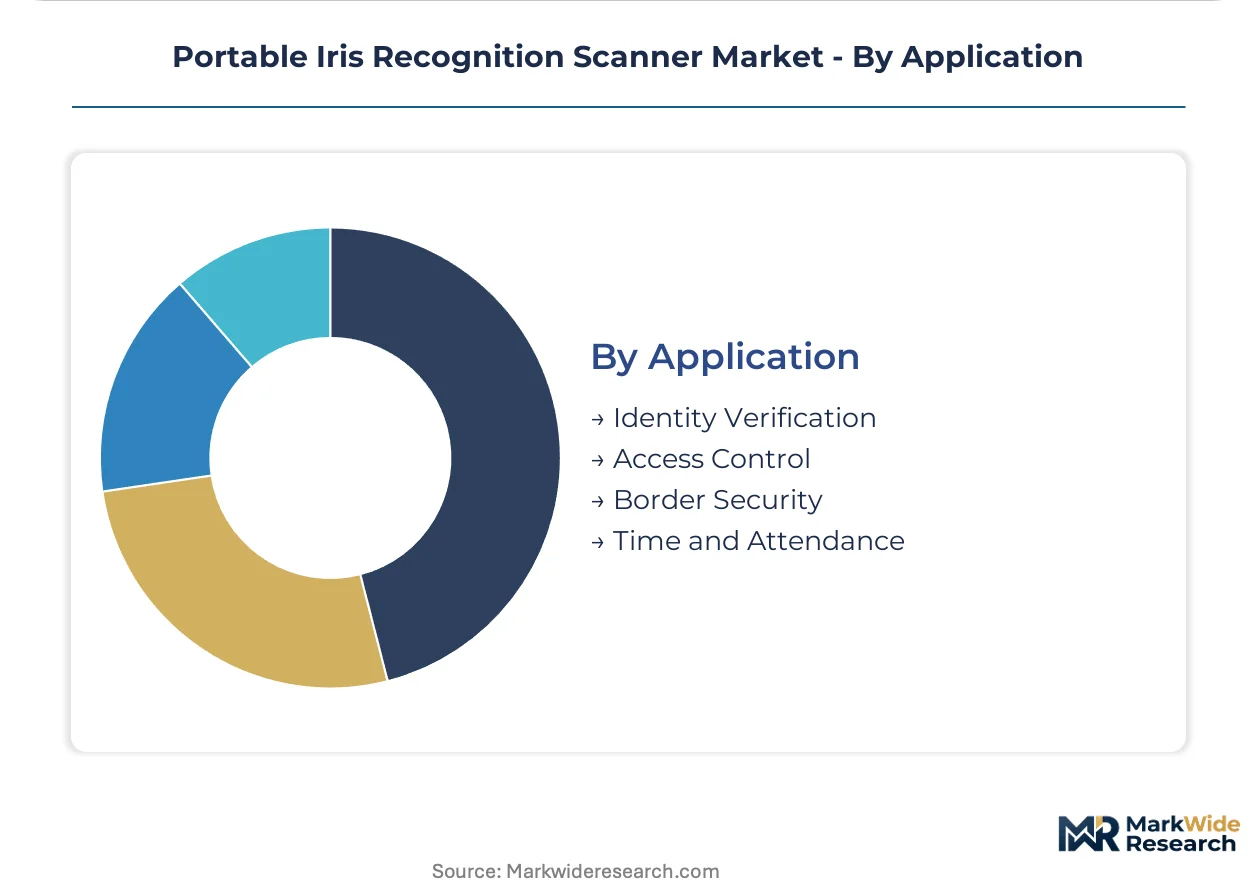
Identity verification retains volume leadership; border security holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between defense-led procurement in the Middle East and healthcare-driven adoption in North America, with Asia-Pacific governments prioritizing national ID scale-out over specialized applications.
Saudi Arabia
Aviation security mandates from the General Authority of Civil Aviation drive scanner deployment at King Abdulaziz International and King Khalid International airports. The National Information Center oversees biometric enrollment for the national ID modernization program. Riyadh-based defense contractors procure MIL-STD-810G ruggedized units for border patrol and military checkpoint applications.
United States
FDA-regulated healthcare facilities deploy iris-based patient identification to eliminate misidentification during emergency registration and medication administration. The 21 CFR Part 820 quality system documentation requirement constrains vendor qualification to established medical device suppliers. Texas Medical Center in Houston operates one of the largest hospital iris-matching deployments, processing over two million annual patient encounters.
Germany
Federal Police procurement of sub-200-gram handheld units for mobile enforcement teams exemplifies miniaturization priorities in European border security. The EU AI Act's high-risk system classification mandates algorithmic audit trails and human-in-the-loop override capabilities for biometric identification systems. Munich's security technology cluster hosts multiple system integrators serving Bundeswehr and federal police contracts.
India
The Unique Identification Authority of India generates sustained demand for BIS-certified field enrollment kits capable of rural deployment across the Aadhaar ecosystem expansion. BIS certification pathways create procurement windows for domestic and foreign manufacturers meeting Indian Standards specifications. Telangana's Hyderabad technology corridor concentrates system integrators serving state-level welfare distribution authentication programs.
China
NMPA standards for medical device registration create divergent compliance costs for manufacturers seeking multi-country presence alongside domestic market access. The national ID program's biometric modernization drives volume procurement of embedded terminal architectures. Shenzhen's electronics manufacturing cluster supplies optical sensor modules and neural accelerator chips for edge AI convergence in authentication devices.
Portable Iris Recognition Scanner Market Competitive Landscape
Capability concentration sits with tier-one suppliers possessing pre-positioned compliance documentation; scale advantage sits with tier-two specialists competing on modular field-deployable kit economics. The vendor base organizes around three strategic archetypes: defense-anchored system integrators with long-standing government relationships, healthcare-certified medical device suppliers with FDA pathway expertise, and emerging modular kit specialists targeting price-sensitive emerging markets. Dominant competitive moves include geographic expansion through mutual recognition agreements for biometric equipment testing protocols and portfolio diversification into edge AI-enabled offline authentication systems.
Within the defense-anchored tier, NEC Corporation and Thales Group exemplify suppliers leveraging entrenched government relationships to sustain recurring maintenance contracts. IDEMIA occupies a position among modular kit specialists competing aggressively in emerging markets with field-deployable enrollment systems. These three companies represent contrasting archetypes: NEC Corporation anchors Asia-Pacific national security procurement, Thales Group exemplifies European defense and civil ID program integration, and IDEMIA illustrates emerging-market volume strategies through certification-flexible product architectures.
| Leading Market Players |
|---|
| NEC Corporation |
| Iritech |
| Thales Group |
| EyeLock |
| Princeton Identity |
| IDEMIA |
| HID Global |
| CMITech |
| Iris ID |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese and South Korean CMOS foundries for military-grade near-infrared sensors compresses pricing tier spreads between embedded terminal and standalone portable scanner categories while forcing buyers into long-term allocation commitments that reshape procurement timelines.
Pricing Analysis
Long-term offtake contracts dominate defense and national ID procurement, insulating tier-one suppliers from spot-market volatility while exposing tier-two vendors to pricing softness in modular kit segments. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810G certified units with embedded neural accelerators from commercial-grade alternatives lacking ISO/IEC 30107-3 presentation attack detection. Cost compression in the mobile device tier intensifies because smartphone-connected peripherals compete with consumer biometric accessories. Government agencies exhibit the lowest price sensitivity due to compliance mandates, while education institutions drive aggressive procurement negotiations.
Supply Chain Analysis
Extended payment terms from defense contractors and airport authorities in Saudi Arabia and the UAE are compressing working capital cycles for optical assembly suppliers. Manufacturing concentrates in Japan, South Korea, and China, with Japanese foundries controlling high-purity near-infrared sensor supply and Shenzhen's electronics cluster producing illumination modules and neural accelerator chips. Component dependencies include 700-900 nanometer wavelength-tuned LEDs, military-grade CMOS sensors, and edge AI processing units. Single-source vulnerability in Japanese sensor foundries exposes procurement timelines to allocation risk during defense procurement surges. Distribution runs through system integrators serving national ID authorities and direct OEM relationships with defense ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable iris recognition scanner market sits at a platform-economics inflection where Aadhaar-compatible enrollment kits and EU AI Act-certified systems are becoming interoperability gateways that determine vendor survival.
For Market Incumbents: Build certification moats by securing pre-positioned ISO/IEC 30107-3 and BIS documentation ahead of tender windows, while deepening backward integration into optical sensor supply through captive relationships with Japanese foundries. Margin pressure from aftermarket service unbundling in Middle Eastern aviation deployments demands defensive moves into predictive maintenance software subscriptions. For New Entrants and Emerging Players: Rural Indian enrollment workflows represent the most penetrable white-space target, where Aadhaar ecosystem expansion outpaces incumbent field kit deployment capacity. FDA-regulated healthcare patient identification offers a second vertical pivot, with 21 CFR Part 820 compliance barriers filtering competition to medical device specialists. A go-to-market angle combining modular hardware with third-party algorithm licensing bypasses R&D capital intensity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors algorithm-centric software acquisitions over hardware-heavy targets. Long-term viability hinges on edge AI convergence capabilities enabling offline authentication. The acquisition archetype prioritizes tier-two suppliers with BIS or NMPA certification pathways and embedded neural accelerator integration. The signal to watch is mutual recognition agreement momentum for biometric equipment testing protocols, which would collapse multi-jurisdiction certification costs and accelerate cross-border vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Audit Trail Development | EU AI Act compliance documentation captures tender awards ahead of retrofitting competitors. |
| Edge AI Accelerator Integration | On-device template matching enables denied-network defense deployments without cloud dependency. |
| Mutual Recognition Agreement Pursuit | Collapsed multi-jurisdiction testing costs accelerate time-to-revenue across BIS, NMPA, and FDA pathways. |
| Aftermarket Service Unbundling Response | Predictive maintenance software subscriptions counter revenue compression from third-party technical intermediation. |
| Miniaturized Optical Assembly R&D | Sub-200-gram handheld units capture Australian and German mobile enforcement procurement priorities. |
Research Methodology
Cross-validation between primary interviews with biometric system integrators, national ID procurement officers, and defense ministry technical directors and secondary validation against BIS certification records, FDA 510(k) filings, and EU procurement tender databases anchors the qualitative findings. Bottom-up triangulation from product-level shipment estimates and top-down reconciliation against national aviation security budget disclosures ensures segmentation integrity. Primary fieldwork with hospital biomedical engineers and airport authority IT directors captured deployment friction points and compliance documentation requirements.
Calibration against historical CAGR realization rates in adjacent biometric hardware categories informs the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, end-user security tier, imaging technology maturity, and application intensity. CAGRs derive from weighted scenario analysis incorporating procurement pipeline visibility from tender databases and defense budget trajectory assessments. Industry-specific forecast inputs include Aadhaar ecosystem enrollment targets and EU AI Act implementation timelines for high-risk system classifications.
Practitioners should monitor sensor foundry allocation announcements, mutual recognition agreement negotiations, and FDA breakthrough device designations for early signals of supply constraint or regulatory pathway acceleration. Forecasts reflect assumptions regarding continued near-infrared imaging maturation and sustained national ID modernization funding in priority geographies. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Global Equipment Monitoring Market
Sensors
Global Real-Time Locating Systems (RTLS) Market
Sensors
Smart Beacon Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Global Positioning Systems Market
Sensors
Alcohol Sensor Market
Sensors
Yield Monitoring Systems Market
Sensors
Global Smart Leak Detection Solutions Market
Sensors
Europe Lidar Market
Sensors
Residential Water Leak Detection System Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Safety Motion Control System Market
Sensors
Beacon Technology Market
Sensors
Global RFID Market
Sensors
Indoor Location Market