
 Utility Bill Management System Market | 2026-2036
Utility Bill Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Bill Management System Market Analysis
ISO 50001 energy management certification is rotating vendor eligibility in the utility bill management space, filtering out providers lacking audit-grade data lineage. Oracle Corporation leverages its enterprise database heritage to anchor complex utility analytics for Fortune 500 accounts. SAP SE sustains deep ERP integration pathways that lock in procurement workflows across manufacturing verticals. Hansen Technologies Limited competes through specialized billing engines tailored to water and electricity utility operators.
A utility bill management system is a software platform that ingests, validates, and reconciles invoices from electricity, gas, water, and waste service providers, typically processing interval meter data, tariff structures, and tax jurisdictions through automated extraction engines. Its primary commercial purpose is to eliminate manual accounts-payable friction, flag billing anomalies, and generate sustainability disclosures for regulatory and investor reporting. Cloud-based solutions now capture the largest revenue pool as IT departments retire on-premises infrastructure, while integrated platforms are expanding fastest by converging bill payment with carbon accounting and ESG dashboards. Mobile applications remain a margin-challenged segment, primarily bundled as loyalty features rather than standalone revenue drivers.
The EPA's ENERGY STAR program and the EU Green Deal disclosure rules are tightening data granularity requirements, forcing platforms to support real-time API connections with smart meter networks. FERC Order 2222 in the United States and the CSRD in Europe are expanding the universe of entities required to document and verify utility consumption at the asset level. Procurement teams and sustainability officers must evaluate whether their current systems can ingest sub-hourly interval data and automate GHG Protocol scope calculations without manual intervention.
Market Dynamics
Cloud migration is compressing deployment timelines while ISO 50001 audit requirements are filtering vendor eligibility, creating a bifurcation between enterprise-grade platforms and point solutions lacking data lineage certification.
Growth Catalysts
- EU Green Deal disclosure mandates:Asset-level consumption verification requirements are compelling multi-site enterprises to digitize utility records across electricity, gas, and water categories.
- Smart meter API proliferation:Real-time interval data ingestion capabilities are unlocking automated tariff optimization and demand response participation for industrial facilities.
- Germany's industrial energy cost pressure:Manufacturing clusters in Bavaria and North Rhine-Westphalia are prioritizing bill validation engines to recover overcharges from complex utility tariff structures.
Market Restraints
- Data standardization fragmentation:Utility invoice formats vary across 40+ countries, forcing extraction engine vendors to maintain costly template libraries for each regional operator.
- Legacy ERP lock-in:Deep procurement workflow integration with SAP and Oracle systems creates switching friction that extends sales cycles beyond 18 months for enterprise accounts.
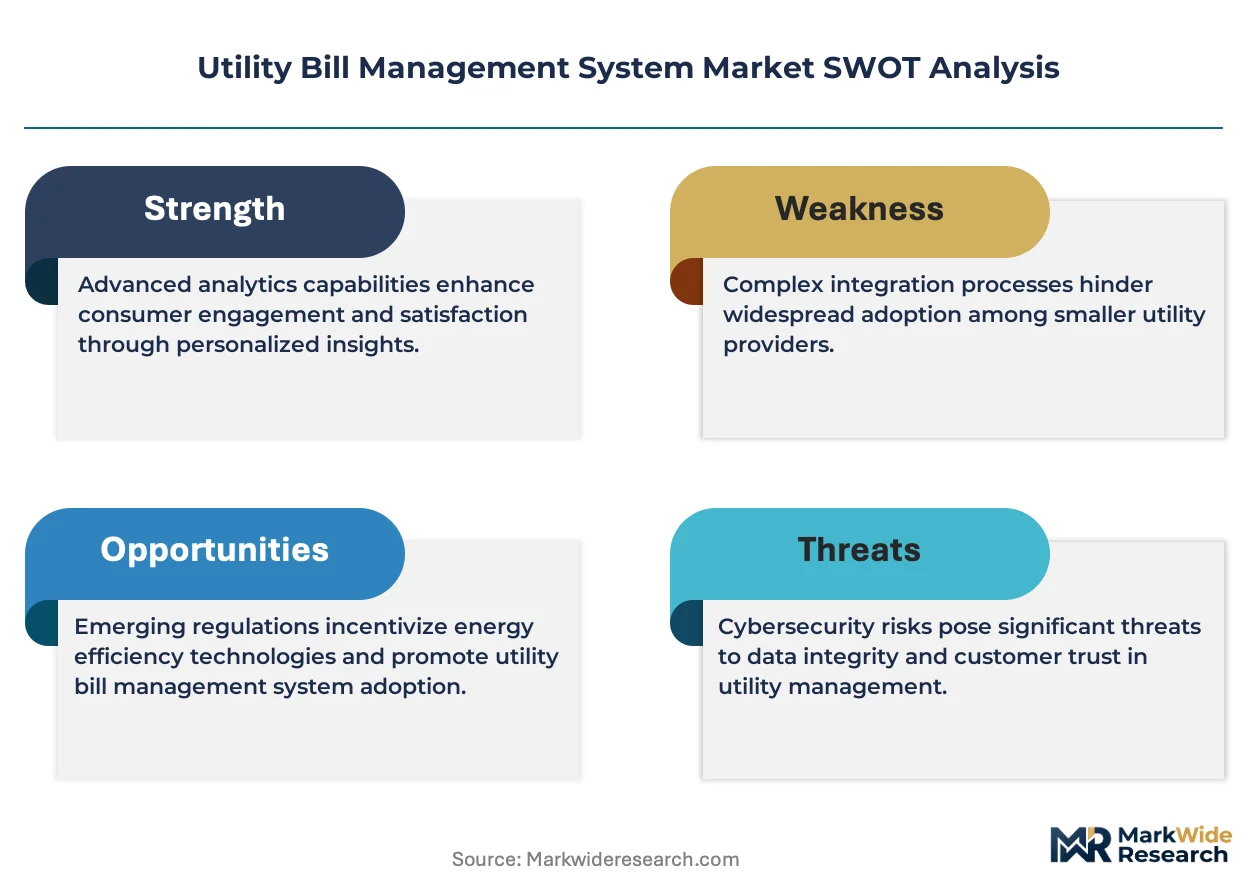
- Cybersecurity liability concentration:Centralized cloud platforms aggregating consumption data across critical infrastructure operators present single-point-of-failure risks under NIS2 directive scope.
Strategic Opportunities
- CSRD-aligned carbon accounting convergence:Platforms integrating Scope 2 emissions calculations with invoice data capture are commanding premium positioning in EU procurement evaluations.
- Mobile-first SME penetration:Simplified onboarding workflows and payment aggregation features are opening addressable market expansion beyond enterprise accounts.
- FERC Order 2222 aggregation services:Distributed energy resource participation in wholesale markets is creating new revenue streams for platforms with sub-hourly data orchestration capabilities.
Industry Challenges
- ISO 50001 auditor certification scarcity:Platform vendors struggle to staff implementation teams with personnel holding both energy management and software deployment credentials.
- Utility API reliability variance:Smart meter data feed interruptions from regional grid operators degrade automation rates and trigger manual reconciliation workloads.
- Cross-border tax jurisdiction complexity:VAT recovery automation across multiple national frameworks requires continuous regulatory monitoring that strains product development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Bill Management System Market |
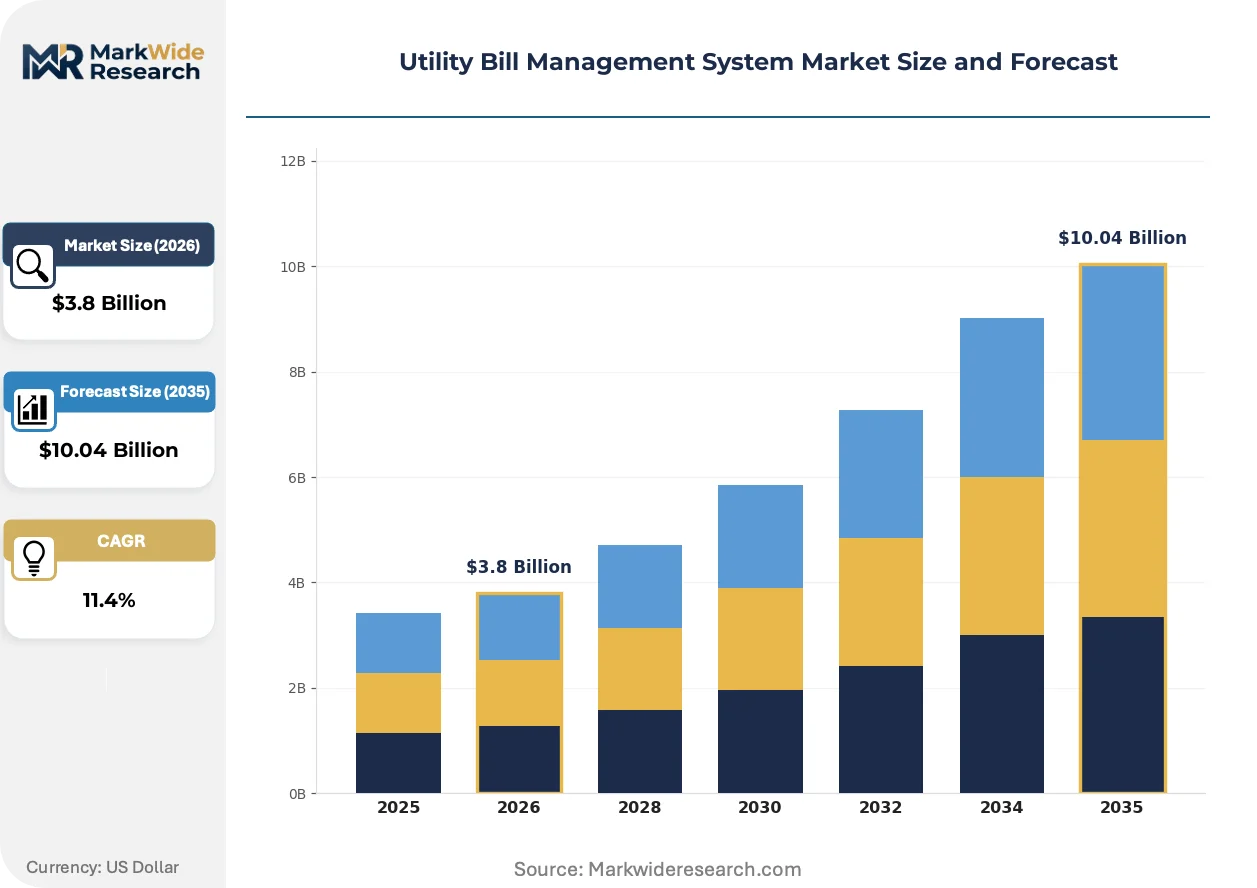
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Solutions, On-premises Solutions, Mobile Applications, Integrated Platforms End User: Residential Users, Small Businesses, Large Enterprises, Utilities Feature: Automated Billing, Payment Reminders, Data Analytics, Customer Support Deployment: Public Cloud, Private Cloud, Hybrid, On-premises |
| Companies Covered | Oracle Corporation, SAP SE, Hansen Technologies Limited, VertexOne, LLC, Tyler Technologies, Inc., EnergyCAP, LLC, N. Harris Computer Corporation, Gentrack Group Limited, MuniBilling, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Bill Management System Market Emerging Trajectories
Machine learning extraction engines are compressing invoice processing costs while regulatory data granularity requirements are forcing platform architecture redesigns toward real-time streaming architectures.
Optical character recognition enhanced by natural language processing is displacing rule-based template matching in utility invoice extraction. Large manufacturing procurement teams in Germany and the Netherlands are adopting these engines to handle non-standard municipal utility formats. The technology is displacing offshore data entry operations that previously handled exception processing for unstructured bill layouts.
The EU Corporate Sustainability Reporting Directive is mandating third-party assurance of energy consumption disclosures. Industrial facility operators must now maintain audit trails linking invoice data to GHG Protocol calculations. Manufacturing verticals with complex multi-site footprints in France and Italy are experiencing the steepest compliance cost escalation.
Centralized procurement teams are consolidating vendor relationships from point solutions to integrated platforms. Sustainability officers now co-own software selection decisions alongside finance leadership, shifting evaluation criteria toward ESG dashboard capabilities. This pattern is most pronounced in German automotive supply chains where OEMs cascade reporting obligations downward.
Utility Bill Management System Market Segmentation
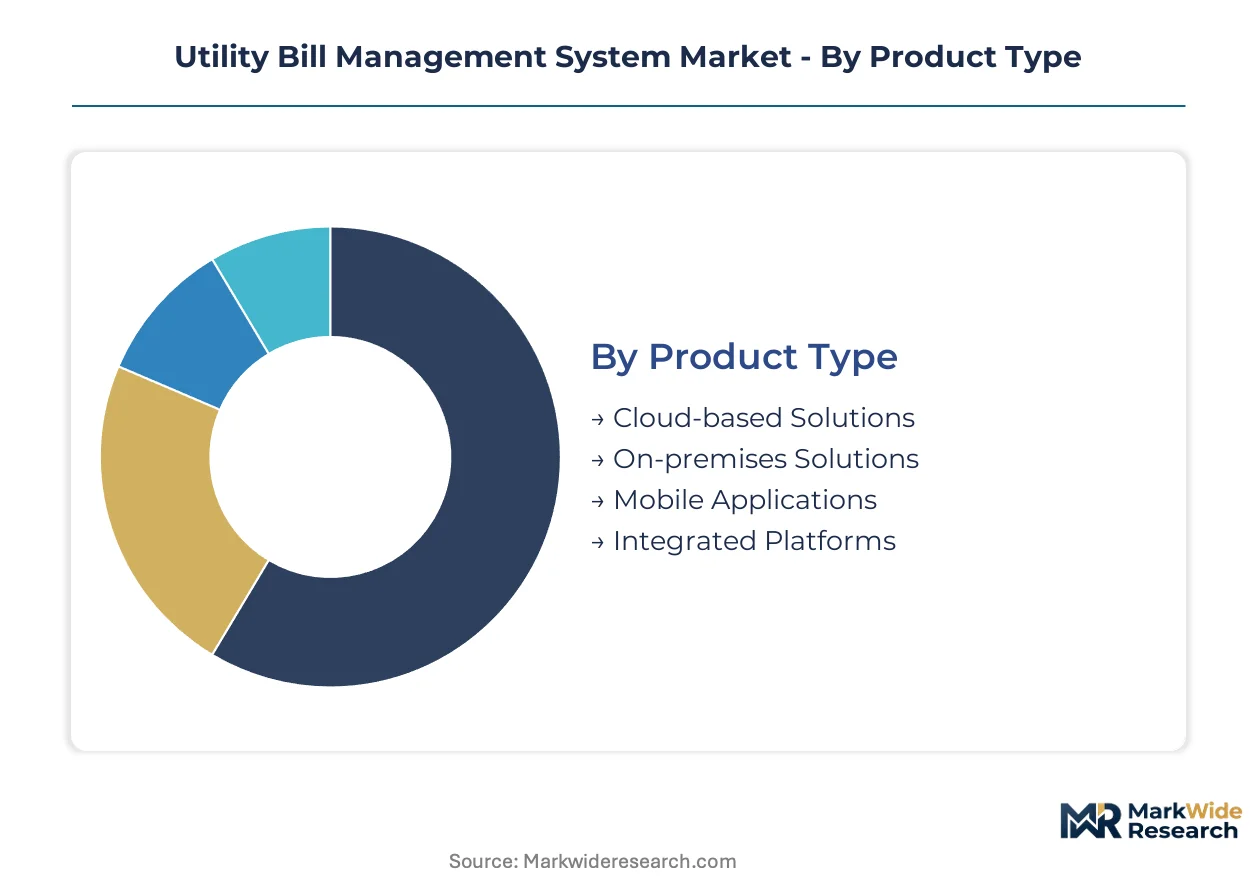
Segmentation in the utility bill management space maps directly to procurement authority and compliance burden. Enterprise buyers with ISO 50001 obligations require audit-grade data lineage, while SME adoption hinges on mobile accessibility and simplified onboarding workflows.
Product Type:
Margin pools concentrate in platforms that bundle invoice processing with carbon accounting and ESG disclosure capabilities, commanding premium positioning in EU procurement evaluations.
- Cloud-based Solutions:Multi-tenant architectures enable rapid deployment across distributed facility portfolios without on-site infrastructure. German automotive supply chains and Dutch manufacturing clusters are accelerating migration to these platforms to satisfy CSRD audit requirements and streamline multi-site utility tracking.
- Integrated Platforms:Converging bill payment, interval meter data ingestion, and automated GHG Protocol scope calculations into unified workflows. Sustainability officers in French industrial conglomerates and Italian multi-site manufacturers are co-owning software selection decisions with finance teams, shifting evaluation criteria toward real-time API connections with smart meter networks.
- On-premises Solutions:Remaining relevant for critical infrastructure operators under NIS2 directive scope with cybersecurity liability concerns.
- Mobile Applications:Bundled primarily as loyalty features rather than standalone revenue drivers, serving SME penetration strategies with payment aggregation functionality.
The dominant share belongs to Cloud-based Solutions, while Integrated Platforms are gaining share fastest through carbon accounting convergence.
End User:
Revenue concentration tracks with procurement complexity and regulatory reporting surface area across facility portfolios.
- Large Enterprises:Procurement teams managing multi-site footprints across electricity, gas, water, and waste categories require automated extraction engines handling 40+ country invoice format variations. Bavarian and North Rhine-Westphalia manufacturing clusters prioritize bill validation engines to recover overcharges from complex utility tariff structures.
- Utilities:Specialized billing engine requirements for water and electricity operators demand deep ERP integration pathways that lock in procurement workflows. These entities process interval meter data at scale and require sub-hourly data orchestration capabilities for FERC Order 2222 aggregation services.
- Small Businesses:Mobile-first onboarding workflows and simplified payment aggregation features are expanding addressable market penetration beyond enterprise accounts.
- Residential Users:Basic payment reminder and consumption visibility features with limited customization requirements.
Large Enterprises command the dominant revenue pool, though Utilities are expanding most quickly through distributed energy resource participation mandates.
Feature:
Development bandwidth allocation reflects regulatory data granularity requirements and automation rate targets.
- Data Analytics:Machine learning extraction engines enhanced by natural language processing are displacing rule-based template matching for non-standard municipal utility formats. Manufacturing procurement teams in Germany and the Netherlands deploy these capabilities to eliminate offshore data entry operations previously handling exception processing.
- Automated Billing:Optical character recognition pipelines process interval meter data, tariff structures, and tax jurisdictions through automated extraction engines. The technology eliminates manual accounts-payable friction and flags billing anomalies across complex multi-site footprints.
- Payment Reminders:Standard functionality reducing delinquency rates through scheduled notification workflows.
- Customer Support:Implementation team staffing challenges persist given scarcity of personnel holding both ISO 50001 energy management and software deployment credentials.
Data Analytics holds the dominant position, while Automated Billing is climbing the fastest as extraction engine accuracy improves.
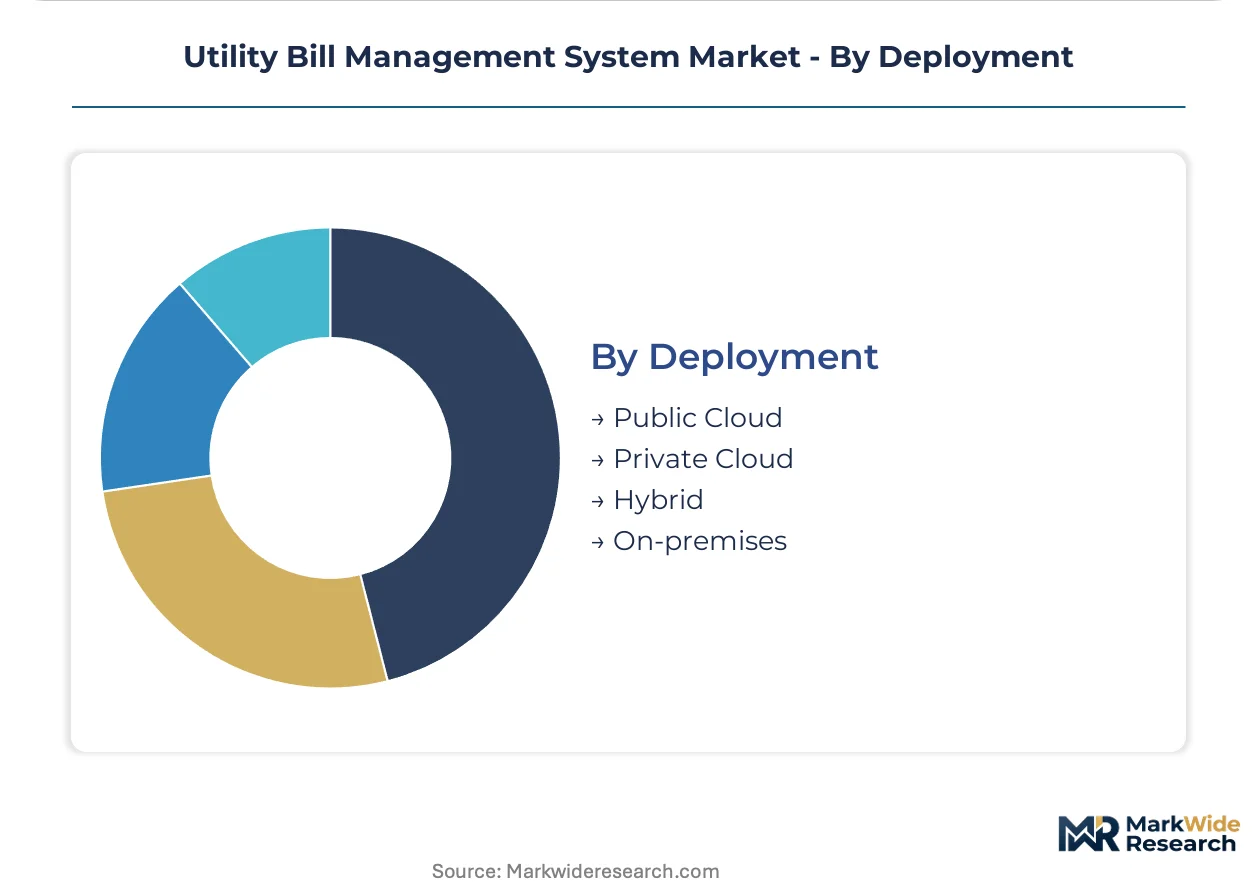
Deployment:
Architecture selection hinges on data sovereignty requirements and smart meter API reliability variance across regional grid operators.
- Public Cloud:Captures the largest revenue pool as IT departments retire on-premises infrastructure, though centralized platforms aggregating consumption data present single-point-of-failure risks under NIS2 directive scope.
- Hybrid:Balancing real-time streaming architectures for smart meter data with on-premises audit trail maintenance for third-party assurance of energy consumption disclosures.
- Private Cloud:Selected by entities requiring dedicated infrastructure with controlled API connection management.
- On-premises:Persisting in segments with strict data residency mandates or unreliable utility API connectivity.
Public Cloud maintains the dominant share, though Hybrid deployments are expanding most quickly as facilities balance real-time ingestion with audit-grade data lineage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal disclosure mandates are accelerating digitization across industrial clusters, while FERC Order 2222 in the United States expands market participation requirements for distributed energy resources. National carbon accounting standards are creating divergent compliance architectures that shape platform adoption patterns.
United States
Industrial facilities in Texas and California are deploying automated extraction engines to manage multi-state utility portfolios under complex interstate tariff structures. The EPA's ENERGY STAR program and FERC Order 2222 together mandate sub-hourly interval data verification for wholesale market participation. Manufacturing clusters in Houston and the San Francisco Bay Area are prioritizing platforms with real-time API connections to smart meter networks.
Germany
Bavarian and North Rhine-Westphalia manufacturing clusters face Europe's most stringent industrial energy cost pressures and regulatory reporting obligations. The EU Green Deal and national implementation of CSRD require asset-level consumption verification across electricity, gas, and water categories. Automotive supply chains in Stuttgart and Wolfsburg are cascading reporting requirements downward to tier-1 and tier-2 suppliers.
France
Industrial conglomerates with complex multi-site footprints are experiencing steep compliance cost escalation under EU Corporate Sustainability Reporting Directive assurance requirements. The country's national energy regulator enforces strict data granularity standards for facility-level disclosure. Manufacturing operations in Île-de-France and Auvergne-Rhône-Alpes are consolidating vendor relationships from point solutions toward integrated platforms.
Netherlands
Manufacturing procurement teams in Rotterdam and Eindhoven are adopting machine learning extraction engines to eliminate offshore data entry operations for non-standard municipal utility formats. Dutch implementation of EU Green Deal rules mandates third-party assurance of energy consumption disclosures. Port and logistics infrastructure operators are prioritizing platforms with automated GHG Protocol scope calculations.
United Kingdom
Post-Brexit regulatory divergence is creating parallel compliance tracks for enterprises maintaining EU and UK disclosure obligations simultaneously. London-based financial services and corporate headquarters are demanding audit-grade data lineage for investor-facing sustainability reports. Industrial operations in the Midlands and Northern England are navigating overlapping carbon accounting frameworks.
Utility Bill Management System Market Vendor Landscape
Listed leaders compete with private specialists across enterprise database depth and ERP integration pathways, creating a tiered structure where scale advantages concentrate in platform consolidation while niche players retain municipal utility specialization. Three archetypes dominate: enterprise software incumbents with procurement workflow lock-in, specialized billing engine vendors for water and electricity operators, and cloud-native challengers converging bill payment with carbon accounting dashboards. Competitive moves center on strategic partnerships for smart meter API access and portfolio diversification into ESG disclosure automation.
Within the enterprise software tier, Oracle Corporation and SAP SE exemplify divergent positioning strategies. Oracle leverages its database heritage to anchor complex utility analytics for Fortune 500 accounts requiring audit-grade data lineage. SAP sustains deep ERP integration pathways that lock in procurement workflows across manufacturing verticals with ISO 50001 obligations. Hansen Technologies Limited occupies a specialized position among billing engine vendors serving water and electricity utility operators with tailored extraction capabilities.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Hansen Technologies Limited |
| VertexOne, LLC |
| Tyler Technologies, Inc. |
| EnergyCAP, LLC |
| N. Harris Computer Corporation |
| Gentrack Group Limited |
| MuniBilling, LLC |
| Others |
Supply Flow & Price Mechanics
ISO 50001 certification gates both vendor qualification and price positioning in utility bill management, creating a bifurcated structure where audit-grade platforms command subscription premiums while uncertified point solutions compete on transactional fees. German automotive OEMs and Dutch manufacturing conglomerates pay sustained premiums for data lineage assurance under CSRD third-party verification mandates.
Pricing Analysis
Certification level creates the primary spread between platform tiers, with ISO 50001-audited solutions commanding three-tier pricing structure across premium, standard, and economy levels. SaaS subscription models dominate enterprise accounts, while per-invoice transactional pricing persists among SME-focused challengers. Cost compression in the standard tier intensifies because cloud-native entrants are undercutting legacy on-premises vendors. Procurement teams at Fortune 500 manufacturers exhibit lowest price sensitivity, prioritizing audit trail integrity over license cost.
Supply Chain Analysis
Smart meter API access represents a critical chokepoint, with regional grid operators in Germany, the Netherlands, and California controlling data feed reliability that undermines automation rates. Software development draws from specialized machine learning engineering pools in India and Eastern Europe, while implementation services hinge on scarce ISO 50001-certified consultant networks concentrated in Western Europe. Single-source vulnerability runs through dominant cloud hyperscaler infrastructure. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around CSRD and FERC disclosure mandates constructs formidable switching costs, deepening incumbent moats as compliance complexity compounds across multi-site footprints.
For Market Incumbents: Fortify data lineage certification moats by accelerating ISO 50001 auditor training programs to address implementation team scarcity. Deepen ERP integration pathways with SAP and Oracle to extend procurement workflow lock-in against cloud-native challengers. Prioritize sub-hourly interval data orchestration capabilities to capture FERC Order 2222 aggregation service revenue pools. For New Entrants and Emerging Players: Lead with mobile-first SME penetration strategies targeting underdigitized small business segments in Southern Europe and North American secondary markets. White-space concentration sits in payment aggregation features for multi-utility consolidation, where simplified onboarding workflows can bypass incumbent complexity. Pursue vertical specialization in water utility billing engines where Hansen Technologies' dominance leaves room for municipal-focused challengers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native platform development, compressing time-to-revenue for well-capitalized entrants. Long-term viability favors integrated platforms converging bill payment with carbon accounting automation. Acquisition target archetypes include specialized extraction engine vendors with municipal utility template libraries. The signal to watch is smart meter API standardization progress across EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| CSRD-Aligned Carbon Accounting Convergence | Platforms bundling GHG Protocol calculations command premium positioning in EU procurement evaluations. |
| Smart Meter API Partnership Expansion | Direct grid operator agreements secure real-time data feed reliability for industrial facility automation. |
| ISO 50001 Auditor Certification Investment | Implementation team credentialing addresses scarcity constraining enterprise deployment velocity. |
| Mobile-First SME Platform Launch | Simplified onboarding workflows unlock addressable market expansion beyond enterprise accounts. |
| FERC Order 2222 Aggregation Capability Buildout | Sub-hourly data orchestration enables distributed energy resource participation in wholesale markets. |
Methodological Framework
Operator-level perspectives from sustainability officers, procurement directors, utility billing managers, and ERP integration specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, FERC regulatory dockets, EU Green Deal implementation documents, and smart meter deployment databases. Bottom-up facility-level modeling triangulated against top-down market sizing across the analysis window.
Sensitivity analysis framed the forecast framework, with segmentation dimensions spanning deployment model, organization size, vertical industry, and regional regulatory cluster. CAGRs derived from installed base growth rates and average revenue per account trajectories. Key inputs included smart meter penetration curves, CSRD implementation timelines, and cloud migration velocity by enterprise tier.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of carbon disclosure mandates would require recalibration. Forecasts reflect assumptions regarding API standardization progress and auditor certification supply expansion. Practitioners should keep alternative scenarios live as NIS2 cybersecurity directive scope interpretations and utility data feed reliability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Asia-Pacific Intelligent Document Processing Market
Digital Solutions
Global Space Planning Software Market
Digital Solutions
Mexico ICT Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Docketing Solution Market
Digital Solutions
Component (Document) Content Management System Market
Digital Solutions
Online Voting System Market
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Global Logistics Software Market
Digital Solutions
Cloud Based Drug Discovery Platform Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Connected Stadium Solution Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
Electronic Discovery Market