
 Conveyor Monitoring Market | 2026-2036
Conveyor Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Conveyor Monitoring Market Intelligence
Direct digital sales channels is reshaping how conveyor monitoring suppliers reach mid-sized manufacturing plants and warehousing facilities. Emerson Electric Co. leverages its automation portfolio to bundle monitoring hardware with control systems. SKF anchors its position through bearing-integrated sensor designs that simplify installation. ABB Ltd. competes via its Ability platform, linking edge devices to enterprise analytics.
Conveyor monitoring encompasses sensor arrays, data acquisition modules, and software platforms that track belt speed, bearing temperature, vibration signatures, and load distribution in continuous material handling systems. These systems typically sample vibration at 10–20 kHz and temperature at 0.1°C resolution to detect misalignment, idler failure, or splice degradation before unplanned shutdowns. Vibration sensors and temperature sensors constitute the largest installed base, though acoustic sensors are gaining traction in bulk material handling where particle impact noise reveals belt wear patterns. IoT-based systems and predictive analytics represent the fastest-expanding technology pairing, as cloud-integrated platforms reduce on-premise infrastructure costs for mining companies and logistics providers.
OSHA machinery guarding standards, EU machinery directive 2006/42/EC, and ISO 5048 for continuous mechanical handling equipment collectively mandate risk assessment and protective measures that elevate monitoring system specifications. MSHA regulations in the United States impose specific conveyor belt fire detection and slippage protection requirements that sustain replacement demand in underground operations. Stakeholders must weigh the trade-off between edge computing latency and cloud analytics scalability when architecting next-generation deployments.
Market Dynamics
Edge-to-cloud architecture decisions are fragmenting procurement patterns as mining operators and automotive suppliers weigh latency requirements against analytics depth in conveyor monitoring deployments.
Growth Catalysts
- EU machinery directive 2006/42/EC:Mandates risk assessment and protective measures that compel facilities to retrofit legacy conveyor systems with integrated sensor arrays.
- Underground coal operations:MSHA regulations impose specific fire detection and slippage protection requirements that sustain replacement demand for belt monitoring hardware.
- Acoustic emission sensing:Particle impact noise analysis reveals belt wear patterns in bulk material handling applications where vibration monitoring proves insufficient.
Market Restraints
- Silicon carbide sensor substrates:Supply concentration in East Asian foundries creates input cost volatility for high-temperature bearing monitors.
- Legacy analog infrastructure:Brownfield manufacturing sites face technical limitation in retrofitting 4-20mA loops with digital IO-Link protocols.
- Functional safety certification:IEC 61508 compliance timelines extend 18-24 months, delaying product launches for integrated monitoring systems.
Strategic Opportunities
- Chilean copper belt:Underpenetrated remote monitoring adoption creates white space for satellite-connected predictive maintenance platforms.
- Digital twin convergence:Physics modeling fused with real-time sensor streams enables virtual commissioning of conveyor networks before physical deployment.
- India's PLI scheme:Manufacturing incentives for automation equipment reduce effective hardware costs for domestic material handling system builders.
Industry Challenges
- Embedded systems firmware:Talent scarcity in real-time signal processing delays product development cycles for vibration analysis modules.
- Multi-vendor interoperability:Integration complexity with legacy SCADA architectures fragments data lakes and complicates enterprise analytics deployment.
- ATEX/IECEx certification:Hazardous location approvals for underground mining equipment require specialized testing protocols that extend time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conveyor Monitoring Market |
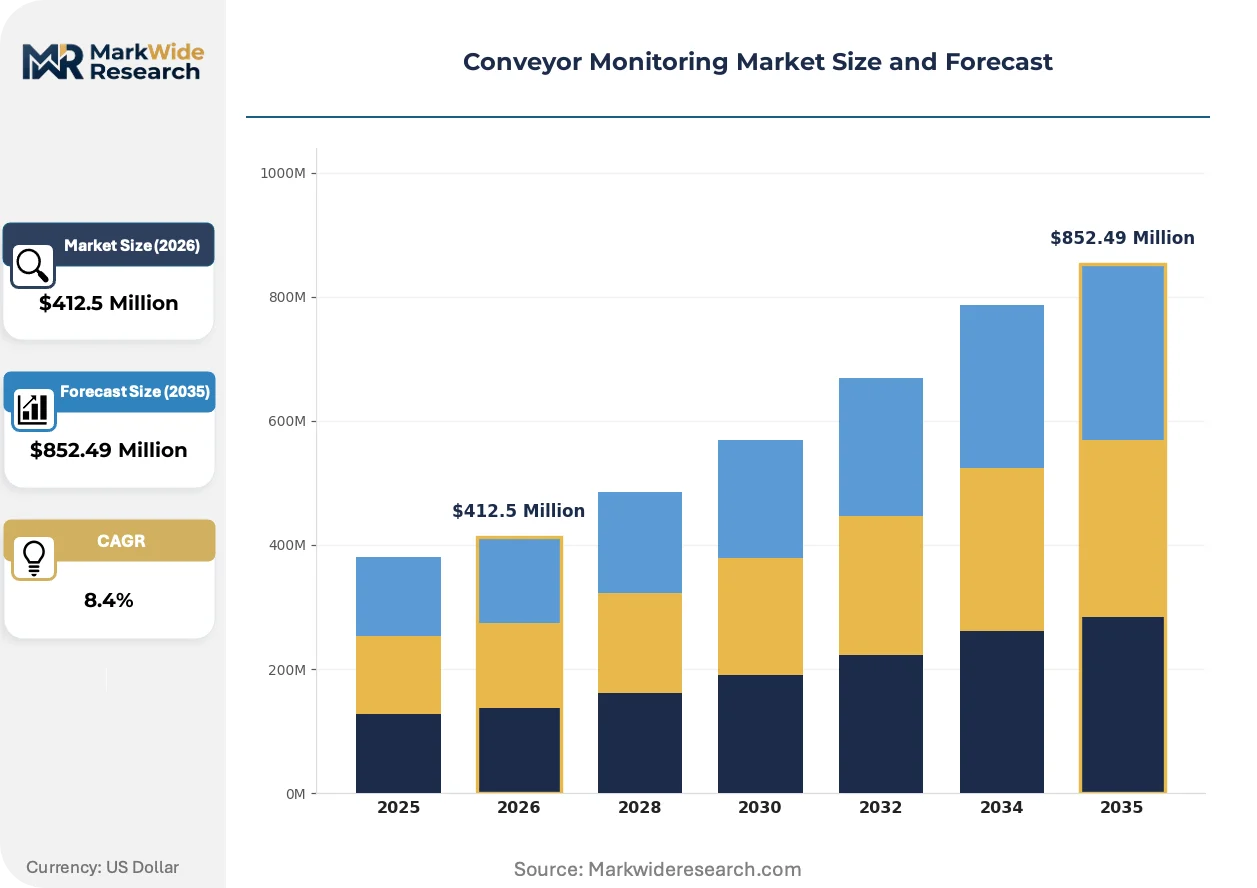
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $852.49 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Sensors, Speed Sensors, Temperature Sensors, Proximity Sensors, Load Cells, Acoustic Sensors Technology: Wireless Monitoring, IoT-based Systems, Predictive Analytics, Real-time Alerting, Cloud Integration, Edge Computing Application: Mining Operations, Food Processing, Parcel Sorting, Bulk Material Handling, Textile Production, Packaging Lines End User: Manufacturing Plants, Logistics Providers, Warehousing Facilities, Textile Mills, Food & Beverage Companies, Mining Companies |
| Companies Covered | ContiTech AG, Parker Hannifin Corporation, Emerson Electric Co., PHOENIX CBS GmbH, Fenner Dunlop, ABB Ltd., SKF, Beltscan Systems Pty Ltd., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conveyor Monitoring Market Strategic Shifts & Innovations
Sensor fusion architectures are compressing the gap between condition monitoring and autonomous control, enabling closed-loop belt tension adjustment without human intervention.
Multi-parameter sensor nodes is hybridizing vibration, temperature, and acoustic signatures into unified health indices. Mining operators in Western Australia deploy these composite sensors at 500-meter intervals along overland conveyors. The technology is hybridizing discrete protection systems into continuous prognostic platforms that anticipate failures 72 hours before threshold breaches.
OSHA's updated machinery guarding standards tighten physical barrier requirements around conveyor transfer points. Automotive suppliers in Germany's industrial corridor accelerate retrofit timelines to maintain automotive OEM qualification status. Tier-1 component manufacturers now specify integrated safety-rated encoders that satisfy both speed monitoring and personnel protection functions.
Asset-as-a-service contracting is displacing capital purchase models for mid-sized warehousing facilities. Third-party logistics providers in the Netherlands bundle monitoring hardware with maintenance labor under per-ton throughput agreements. This consumption-pattern shift transfers technology obsolescence risk from plant operators to system integrators with balance-sheet capacity.
Conveyor Monitoring Market Segmentation
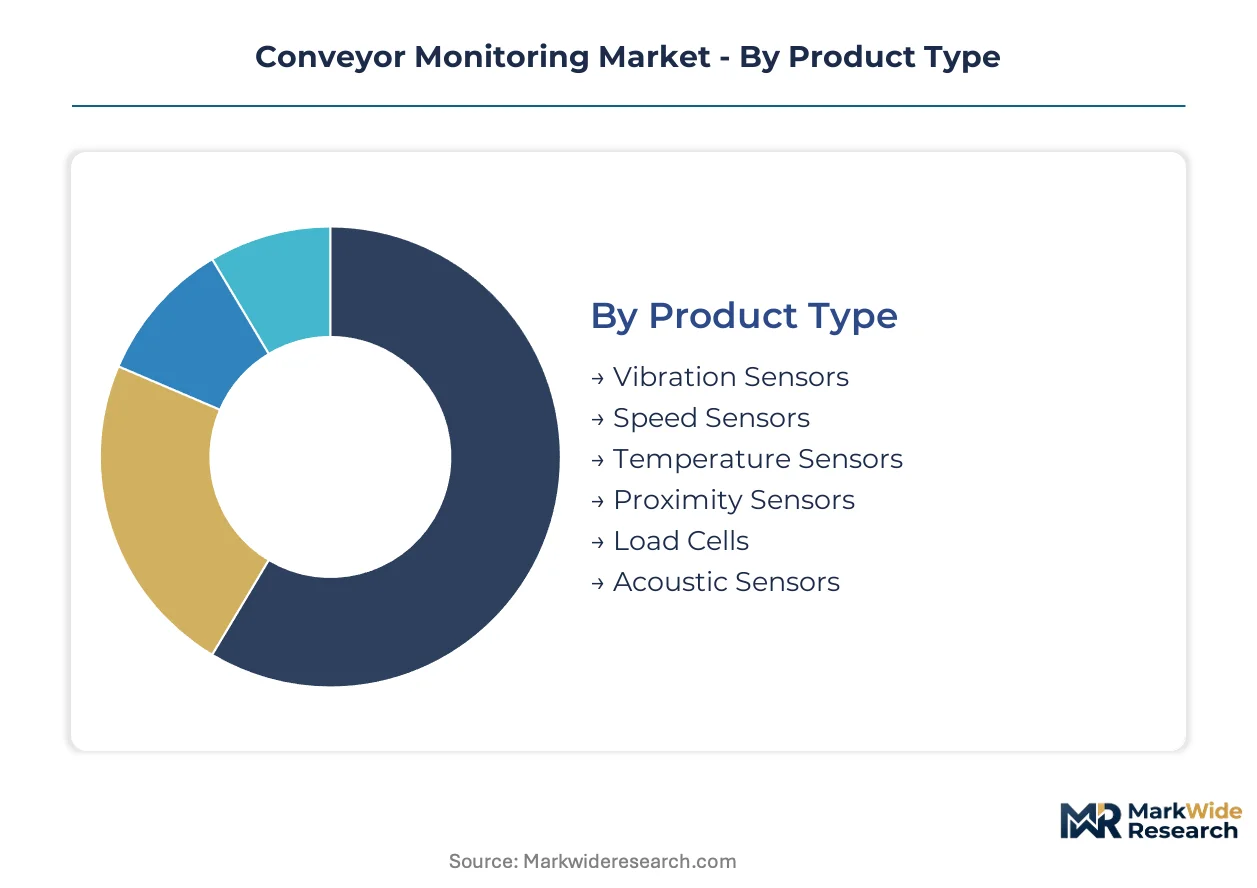
Segmentation in conveyor monitoring reveals how hardware specifications, connectivity architectures, and operational environments shape procurement decisions. Mining operators prioritize explosion-rated sensors with satellite backhaul, while food processors demand washdown-compatible housings and FDA-compliant data logging. Understanding these divides clarifies where technology suppliers must align product roadmaps with sector-specific compliance burdens.
Product Type:
Cost tier determines sensor selection, with premium multi-parameter nodes displacing single-function units in high-availability operations.
- Vibration Sensors:Piezoelectric accelerometers sample at 10–20 kHz to capture bearing defect frequencies in rotating idler assemblies. Mining companies in Western Australia deploy these at 500-meter intervals along overland conveyors to detect misalignment before belt damage propagates.
- Temperature Sensors:Infrared and thermocouple arrays monitor bearing housing heat rise with 0.1°C resolution, flagging lubrication degradation or seal failure. Underground coal operations in the United States specify these for MSHA-compliant fire detection alongside slippage protection systems.
- Speed Sensors:Magnetic and optical encoders track belt velocity deviations that signal loading imbalances or drive motor faults.
- Proximity Sensors:Inductive and capacitive devices detect belt edge position for automatic tracking correction in bulk material handling.
- Load Cells:Strain gauge assemblies measure real-time mass flow for throughput optimization and spillage prevention.
- Acoustic Sensors:MEMS microphones analyze particle impact noise to identify belt cover wear in abrasive ore transport where vibration alone proves insufficient.
Vibration sensors hold installed capacity. Acoustic sensors are rotating up the share rankings.
Technology:
Application environment dictates architecture choice, with latency-critical underground operations diverging from cloud-scalable surface installations.
- IoT-based Systems:IP-enabled sensor nodes transmit via LoRaWAN or cellular to centralized dashboards, eliminating proprietary fieldbus infrastructure. Chilean copper mines adopt these for remote pit-to-port monitoring where fiber deployment costs prove prohibitive.
- Edge Computing:Localized processing units execute FFT analysis and anomaly detection within 50 milliseconds, enabling automatic emergency stops without cloud round-trip delays. Automotive suppliers in Germany's industrial corridor specify these for synchronous production lines where single-belt failures cascade through just-in-sequence assembly.
- Wireless Monitoring:Battery-powered mesh networks reduce cabling in retrofit brownfield sites with legacy 4-20mA analog loops.
- Predictive Analytics:Machine learning models trained on historical failure patterns forecast remaining useful life for idler bearings and belt splices.
- Real-time Alerting:SMS and push notification gateways escalate threshold breaches to maintenance crews during unmanned night shifts.
- Cloud Integration:Scalable data lakes aggregate fleet-wide performance benchmarks across distributed quarry and warehouse networks.
Edge computing dominates underground safety applications. IoT-based systems are climbing the fastest in open-pit surface mining.
Application:
Volume throughput and contamination risk separate specification requirements across material handling verticals.
- Mining Operations:Harsh-duty sensor housings withstand abrasive dust, shock loading, and temperature swings from -40°C to +85°C. Australian iron ore exporters specify IP69K-rated enclosures with satellite telemetry for 20-kilometer overland routes.
- Food Processing:Stainless steel construction and CIP-compatible sealing prevent bacterial harborage in washdown environments. USDA-inspected poultry plants mandate these for HACCP-compliant critical control point documentation.
- Bulk Material Handling:Heavy-aggregate conveyors in cement and aggregate sectors prioritize load distribution monitoring to prevent structural frame fatigue.
- Parcel Sorting:High-speed cross-belt systems in express logistics hubs require sub-millimeter positional accuracy for barcode scanning alignment.
- Textile Production:Tension-controlled fabric transport demands precise speed synchronization across multi-stage finishing lines.
- Packaging Lines:Compact sensor footprints fit within constrained OEM machinery envelopes for fill-level verification and cap torque monitoring.
Mining operations anchor hardware demand. Food processing is gaining share fastest through regulatory compliance upgrades.
End User:
Customer type shapes contracting models, with capital-rich miners favoring ownership against logistics providers adopting consumption-based service agreements.
- Mining Companies:Integrated owner-operators specify enterprise-grade platforms with 10-year asset lifecycles and ATEX/IECEx hazardous location certification. BHP and Rio Tinto procurement frameworks mandate interoperability with existing SCADA historians.
- Logistics Providers:Third-party operators in the Netherlands and Germany increasingly procure monitoring-as-a-service, transferring obsolescence risk to integrators under per-ton throughput contracts.
- Manufacturing Plants:Automotive tier-1 suppliers bundle monitoring with OEM qualification requirements for conveyor-fed assembly cells.
- Warehousing Facilities:E-commerce fulfillment centers prioritize rapid retrofit solutions compatible with seasonal volume spikes.
- Food & Beverage Companies:Brand owners specify integrated safety-rated encoders satisfying both speed monitoring and personnel protection under OSHA machinery guarding standards.
- Textile Mills:Batch-oriented producers favor modular systems with quick reconfiguration for synthetic versus natural fiber handling.
Mining companies retain the largest installed base. Logistics providers are rotating up the share rankings through servitization contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mining safety mandates and industrial automation incentives are redirecting capital toward conveyor monitoring upgrades across mineral-rich economies and manufacturing-intensive zones.
Australia
Iron ore exporters in Western Australia deploy satellite-telemetry monitoring along 20-kilometer overland routes. MSHA-equivalent state regulations mandate fire detection and slippage protection for underground operations. Perth-based engineering firms integrate IP69K-rated sensor arrays with predictive analytics platforms for BHP and Rio Tinto procurement frameworks.
Germany
Automotive tier-1 suppliers in Baden-Württemberg accelerate retrofit timelines to maintain OEM qualification status. EU machinery directive 2006/42/EC compels facilities to retrofit legacy systems with integrated sensor arrays. Stuttgart industrial corridor operations specify safety-rated encoders satisfying both speed monitoring and personnel protection functions.
United States
Underground coal operations sustain replacement demand for belt monitoring hardware under MSHA regulations. OSHA machinery guarding standards tighten physical barrier requirements around conveyor transfer points. Appalachian mining counties and Illinois Basin operations specify explosion-rated sensors with automatic emergency stop capabilities.
Chile
Copper belt mining operations adopt satellite-connected predictive maintenance platforms where fiber deployment costs prove prohibitive. National mining safety protocols align with international standards for continuous mechanical handling equipment. Antofagasta Region pit-to-port corridors represent underpenetrated white space for remote monitoring adoption.
India
Domestic material handling system builders benefit from PLI scheme manufacturing incentives for automation equipment. Cement and steel sector expansion drives demand for load distribution monitoring to prevent structural frame fatigue. Gujarat and Maharashtra industrial zones concentrate procurement for heavy-aggregate conveyor networks.
Conveyor Monitoring Market Key Industry Players
On the supply side, the industry is consolidating around automation conglomerates with bundled hardware-software portfolios and specialized sensor manufacturers with bearing-integrated designs. Three archetypes dominate: diversified industrial technology groups with enterprise analytics platforms, component specialists with embedded sensing expertise, and regional system integrators with hazardous location certification capabilities. Competitive moves center on strategic partnerships between sensor designers and cloud analytics providers, plus portfolio diversification into asset-as-a-service contracting models.
Within the diversified technology tier, Emerson Electric Co. and ABB Ltd. exemplify platform-centric positioning through automation portfolio breadth and edge-to-cloud integration capabilities. SKF occupies a specialist position through bearing-integrated sensor architectures that simplify installation for rotating equipment applications. These three entities represent contrasting approaches to market participation—bundled systems integration versus component-level innovation—while navigating identical regulatory compliance burdens across mining and manufacturing verticals.
| Leading Market Players |
|---|
| ContiTech AG |
| Parker Hannifin Corporation |
| Emerson Electric Co. |
| PHOENIX CBS GmbH |
| Fenner Dunlop |
| ABB Ltd. |
| SKF |
| Beltscan Systems Pty Ltd. |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in East Asian sensor substrate foundries is compressing input costs for high-temperature bearing monitors while simultaneously eroding supplier pricing power across premium monitoring tiers. This utilization dynamic forces tier-1 suppliers to absorb margin compression or accelerate backward integration into silicon carbide wafer sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement frameworks, with ATEX/IECEx certification grade and volume scale serving as the primary differentiation drivers. Pricing pressure stems from logistics providers adopting asset-as-a-service contracts that transfer hardware ownership risk to integrators. Mining companies demonstrate lowest price sensitivity due to 10-year asset lifecycle mandates and safety-critical procurement protocols, while mid-sized warehousing facilities exhibit highest sensitivity during seasonal volume spikes.
Supply Chain Analysis
Export-control regimes restricting semiconductor manufacturing equipment flows to Chinese foundries are fragmenting silicon carbide substrate sourcing. Supply concentrates in Japan, Germany, and the United States for precision sensor substrates, while China dominates rare-earth magnet assemblies for encoder motors. Raw material dependencies include silicon carbide wafers, piezoelectric ceramics, and lithium niobate crystals. Single-source vulnerability in MEMS microphone MEMS foundries poses structural risk. Distribution runs through authorized system integrators with hazardous location certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where edge-to-cloud interoperability standards are consolidating procurement around bundled hardware-software ecosystems rather than discrete component sourcing.
For Market Incumbents: Pre-empt displacement by specialized sensor manufacturers through captive production of bearing-integrated multi-parameter nodes. Accelerate certification investment in IEC 61508 functional safety compliance to extend product launch timelines for emerging competitors. Defend against asset-as-a-service contracting erosion by building balance-sheet capacity for throughput-based service agreements.
For New Entrants and Emerging Players: Chilean copper belt underpenetration offers white-space entry for satellite-connected predictive maintenance platforms where fiber deployment costs exclude incumbent solutions. Target food processing retrofit demand through washdown-compatible sensor housings with FDA-compliant data logging. Pursue direct digital sales channels to bypass established integrator relationships in mid-sized manufacturing plants.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across IoT-based system deployments as cloud infrastructure costs displace on-premise server investments. Long-term viability favors platform-centric automation conglomerates with enterprise analytics integration capabilities over discrete hardware specialists. Monitor satellite telemetry adoption rates in remote mining corridors as inflection indicator for predictive maintenance platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Platform Integration | Combines vibration, temperature, and acoustic signatures into unified health indices for mining operators. |
| Asset-as-a-Service Contracting | Transfers technology obsolescence risk from plant operators to system integrators under throughput agreements. |
| Backward Integration into Silicon Carbide | Secures substrate supply for high-temperature bearing monitors amid East Asian foundry concentration. |
| Satellite Telemetry Deployment | Enables remote pit-to-port monitoring in Chilean copper belt where fiber costs prove prohibitive. |
| Digital Twin Convergence | Fuses physics modeling with real-time sensor streams for virtual commissioning of conveyor networks. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at mining companies, plant engineers at automotive tier-1 suppliers, procurement teams at logistics providers, and aftermarket service heads at system integrators. Secondary validation drew from MSHA regulatory filings, EU machinery directive implementation reports, SEC 10-K disclosures from automation conglomerates, and customs data for sensor component trade flows. Bottom-up installation base estimates were triangulated against top-down market value reconstruction.
Calibration against historical sensor deployment rates and replacement cycles anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include sensor product type, connectivity architecture, application environment, and end-user contracting model. CAGRs were derived from elasticity-adjusted adoption curves and regulatory mandate timelines. Forecast inputs incorporated MSHA compliance deadlines and EU machinery directive retrofit obligations.
Macroeconomic conditions sit as an overlay; deviation in mining capital expenditure cycles or industrial automation incentive schemes would shift the trajectory. Forecasts reflect documented assumptions regarding satellite connectivity cost declines and edge computing latency improvements. Material shifts in EU machinery safety directive enforcement intensity or MSHA underground coal regulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Smart Beacon Market
Sensors
Connected Smart Thermostats Market
Sensors
Robot Sensor Market
Sensors
Lidar Market
Sensors
Digital Direction Finder Market
Sensors
Telemetric Devices Market
Sensors
Voice Sounders Market
Sensors
Handheld RFID Readers Market
Sensors
Wireless RFID Readers Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Traffic Sensor Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Micro Location Technology Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Smart Pest Monitoring Management System Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market