
 Bluetooth Beacons Market | 2026-2036
Bluetooth Beacons Market Size, Share, and Industry Trends Forecast 2026-2036
Bluetooth Beacons Market Intelligence
China is fragmenting as domestic module manufacturers scale BLE beacon production for export markets. Nordic Semiconductor anchors European chip supply through its integrated SoC architecture. Texas Instruments leverages its broad analog portfolio to sustain module-level cost advantages. Estimote differentiates through software-layer analytics that complement its hardware deployments.
Bluetooth beacons are compact, battery-powered radio transmitters that broadcast identifier signals via Bluetooth Low Energy protocols, typically operating at 2.4 GHz with transmit power ranging from -30 dBm to +4 dBm and battery lifespans extending from months to years depending on broadcast intervals. Their primary commercial purpose is enabling proximity-aware services, location intelligence, and context-triggered automation across physical environments. Compact beacons dominate volume shipments due to minimal form-factor requirements in retail shelf-edge and wearable integrations, while rugged beacons command margin pools in industrial asset-tracking deployments where IP67 ratings and extended temperature tolerance justify premium positioning. BLE technology leads all protocol options by installed base, though Ultra-Wideband is gaining traction in high-precision indoor navigation use cases where sub-meter accuracy is non-negotiable.
The Federal Communications Commission governs 2.4 GHz unlicensed spectrum allocations in the United States, directly constraining transmit power and channel selection for beacon hardware sold into North American markets. The Bluetooth Special Interest Group mandates interoperability certification through its Qualification Program, creating a compliance threshold that filters out uncertified low-cost entrants. Stakeholders must monitor evolving spectrum coexistence rules and energy-efficiency mandates as regulatory bodies in multiple jurisdictions tighten electromagnetic emissions standards.
Market Dynamics
Proximity marketing infrastructure is restructuring around Ultra-Wideband integration, as retailers demand sub-meter accuracy for indoor navigation that legacy BLE protocols cannot deliver. This technology migration is compressing hardware refresh cycles and fragmenting vendor specialization between precision-tier and cost-tier suppliers.
Growth Catalysts
- GDPR-compliant data frameworks:The EU's data privacy mandates are accelerating demand for anonymized beacon analytics in European retail chains, forcing vendors to embed privacy-by-design architectures.
- Logistics hub automation:Major distribution centers across the United States are deploying beacon networks for real-time asset tracking, reducing inventory search times.
- BLE 5.3 protocol stack:Enhanced channel sounding capabilities in the latest Bluetooth specification are enabling direction-finding without UWB hardware costs.
Market Restraints
- Lithium battery supply concentration:Beacon manufacturers depend on cylindrical cell suppliers concentrated in East Asia, exposing margins to raw material volatility.
- Electromagnetic emissions ceilings:FCC Part 15 rules cap 2.4 GHz transmit power at +4 dBm, constraining range extension for warehouse-scale deployments.
- UWB substitution threat:Apple's U1 chip ecosystem is displacing BLE beacons in high-precision consumer applications.
Strategic Opportunities
- Healthcare asset tracking:Hospital systems in Germany are piloting beacon networks for medical equipment location, creating a regulated vertical with premium pricing tolerance.
- India's smart city mandates:Municipal infrastructure projects under the country's urban renewal programs specify BLE beacon integration for public transit wayfinding.
- Ambient IoT convergence:Energy harvesting from photovoltaic and RF sources is eliminating battery dependency in shelf-edge retail applications.
Industry Challenges
- Bluetooth SIG certification timelines:Qualification Program testing delays average 8-12 weeks, compressing product launch windows for seasonal retail procurement cycles.
- Legacy WMS integration:Warehouse management systems running on decade-old middleware require custom API bridges for beacon data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bluetooth Beacons Market |
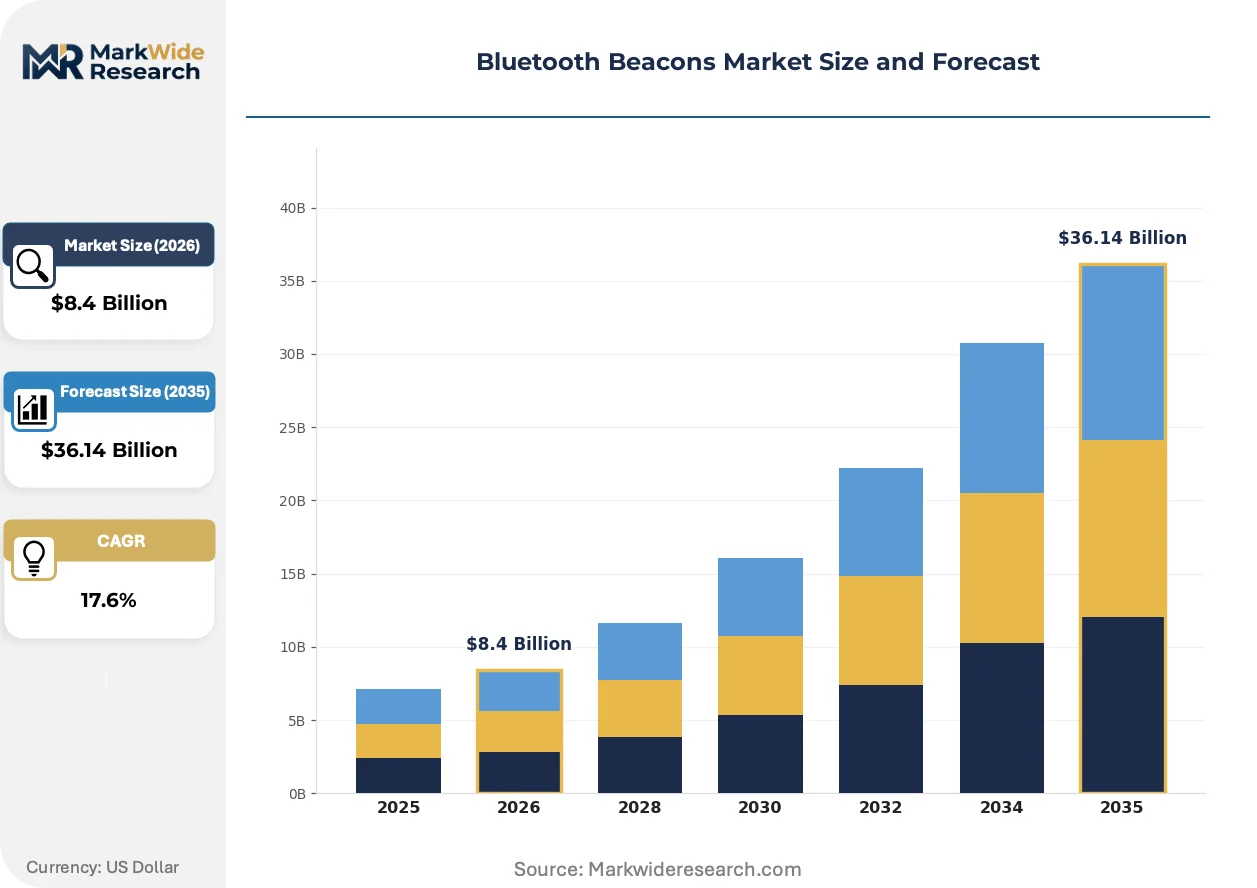
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $36.14 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Beacons, USB Beacons, Rugged Beacons, Location Beacons, Smart Beacons Technology: Bluetooth Low Energy, Ultra-Wideband, RFID Integration, NFC Compatibility, Infrared Use Case: Asset Tracking, Indoor Navigation, Proximity Marketing, Visitor Management, Security Monitoring Customer Type: Retail Chains, Event Organizers, Warehousing, Public Transport Operators, Museums |
| Companies Covered | Kontakt Micro-Location, Estimote, Nordic Semiconductor, Silicon Laboratories, Zebra Technologies, Gimbal, Texas Instruments, Minew Technologies, MOKOSmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bluetooth Beacons Market Strategic Shifts & Innovations
Beacon hardware is bifurcating into precision-tier and cost-tier product lines as end-use requirements diverge. This specialization is accelerating vendor margin stratification and reshaping R&D allocation across the supplier base.
Direction-finding BLE 5.3 implementations are rendering obsolete legacy RSSI-based proximity estimation in large-format retail environments. Department store chains in the United States are piloting these systems for aisle-level customer journey mapping. The technology is compressing addressable market scope for basic beacon-only vendors.
REACH substance restrictions on battery chemistries are forcing European beacon suppliers to reformulate power subsystems. The regulation is extending certification timelines by 4-6 months for products containing restricted heavy metals. Industrial asset-tracking deployments in Germany and France are absorbing these compliance costs through longer procurement cycles.
Retailers are unbundling beacon hardware from analytics software, treating location intelligence as a separate procurement category. This separation is disrupting bundled pricing models that dominated early market development. Big-box chains in the United States are now sourcing beacons through industrial distributors while contracting analytics directly with cloud platform vendors.
Bluetooth Beacons Market Segmentation
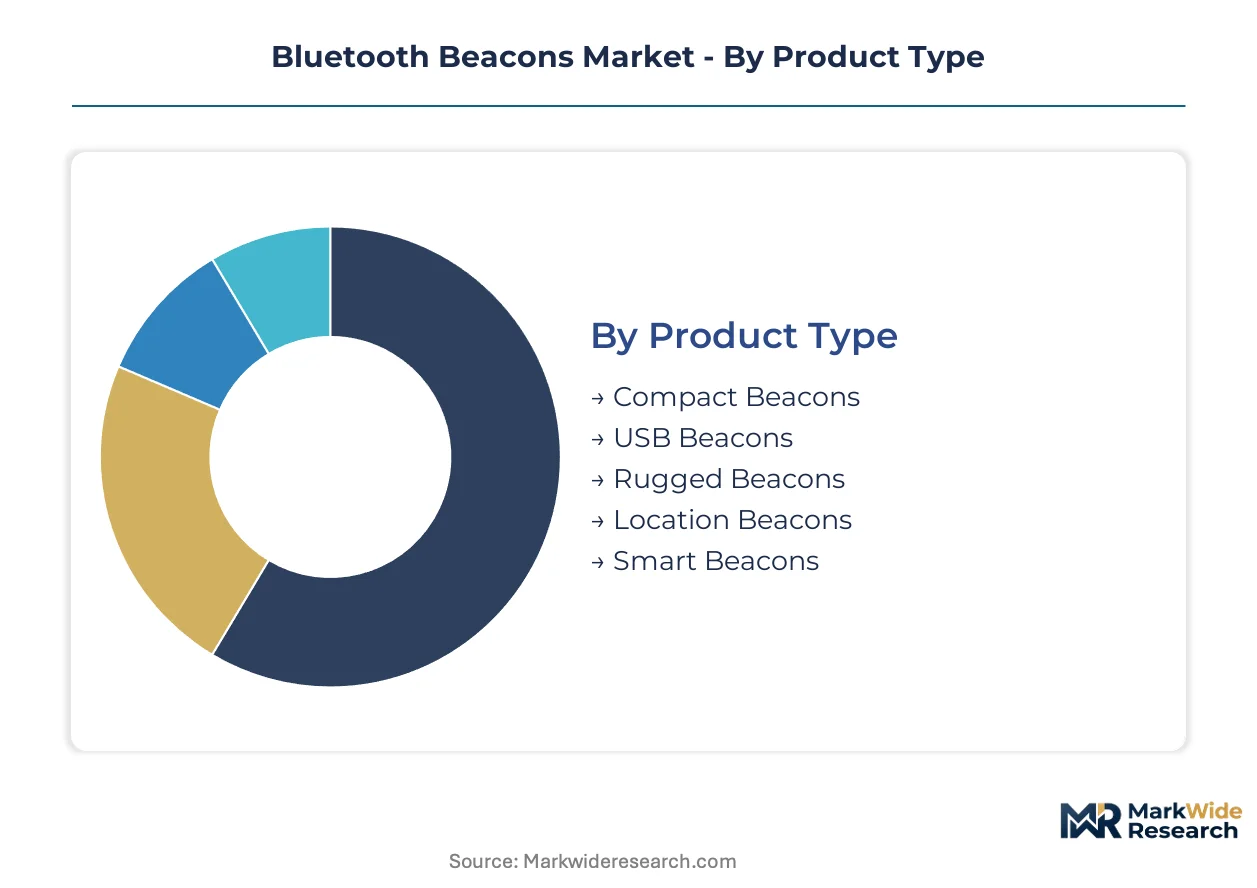
Beacon hardware segmentation determines procurement patterns across retail shelf-edge, industrial asset-tracking, and public infrastructure deployments. Technical specifications, protocol compatibility, and environmental tolerance create distinct margin tiers that reshape vendor specialization and channel strategy.
Product Type:
After-sales service intensity varies sharply by product type, with rugged and location beacons demanding field maintenance contracts while compact units ship as disposable consumables.
- Compact Beacons:Minimalist form factors prioritize battery longevity and unobtrusive mounting for retail shelf-edge and wearable integrations. Demand concentrates in United States big-box retail corridors where space constraints and aesthetic requirements dominate procurement specifications.
- Rugged Beacons:IP67-rated enclosures withstand temperature extremes, moisture, and mechanical shock for industrial deployments. German automotive logistics hubs and French warehouse operators specify these units for forklift-mounted asset tracking, absorbing premium pricing for operational reliability.
- USB Beacons:Powered deployments eliminate battery maintenance for permanent installations in United States office buildings and conference facilities.
- Location Beacons:Enhanced transmit power and antenna diversity extend range for campus-scale deployments in Indian smart city projects.
- Smart Beacons:Edge computing capabilities enable local data processing for latency-sensitive healthcare applications in German hospital systems.
By volume, Compact Beacons leads. By growth pace, Rugged Beacons is ahead.
Technology:
Protocol selection determines hardware cost structures, with BLE dominating unit economics while UWB commands precision-tier margins.
- Bluetooth Low Energy:Dominant protocol by installed base, operating at 2.4 GHz with transmit power tunable from -30 dBm to +4 dBm. United States retail chains standardize on BLE 5.3 for aisle-level customer journey mapping, leveraging direction-finding without UWB hardware premiums.
- Ultra-Wideband:Sub-meter accuracy enables high-precision indoor navigation where legacy RSSI estimation fails. Apple U1 chip ecosystem adoption in United States consumer devices is compressing addressable scope for standalone BLE beacon vendors in premium positioning applications.
- RFID Integration:Hybrid architectures bridge passive inventory tags with active beacon networks for United States distribution centers.
- NFC Compatibility:Touch-triggered interactions complement broadcast beacons in Japanese retail loyalty programs.
- Infrared:Legacy deployments persist in museum audio-guide systems requiring line-of-sight activation.
BLE anchors volume shipments. UWB claims the steepest expansion trajectory among precision-tier alternatives.
Use Case:
Application-specific requirements fragment procurement channels, with asset tracking and indoor navigation commanding enterprise sales cycles while proximity marketing flows through retail distributors.
- Asset Tracking:Real-time location systems reduce search times for mobile equipment in United States logistics hubs and German manufacturing facilities. FCC Part 15 power ceilings constrain range extension for warehouse-scale BLE deployments, forcing network density investments.
- Proximity Marketing:Context-triggered promotions drive beacon adoption in United States metropolitan retail corridors. GDPR-compliant anonymization architectures are accelerating demand in European retail chains, embedding privacy-by-design as a procurement prerequisite.
- Indoor Navigation:Wayfinding applications specify sub-meter accuracy for accessibility compliance in Indian municipal transit projects.
- Visitor Management:Flow analytics optimize crowd density in French event venues and museum complexes.
- Security Monitoring:Perimeter breach detection and personnel verification applications in United States corporate campuses.
Asset Tracking generates the highest average contract value. Proximity Marketing expands most quickly as retail chains accelerate post-pandemic store digitization.
Customer Type:
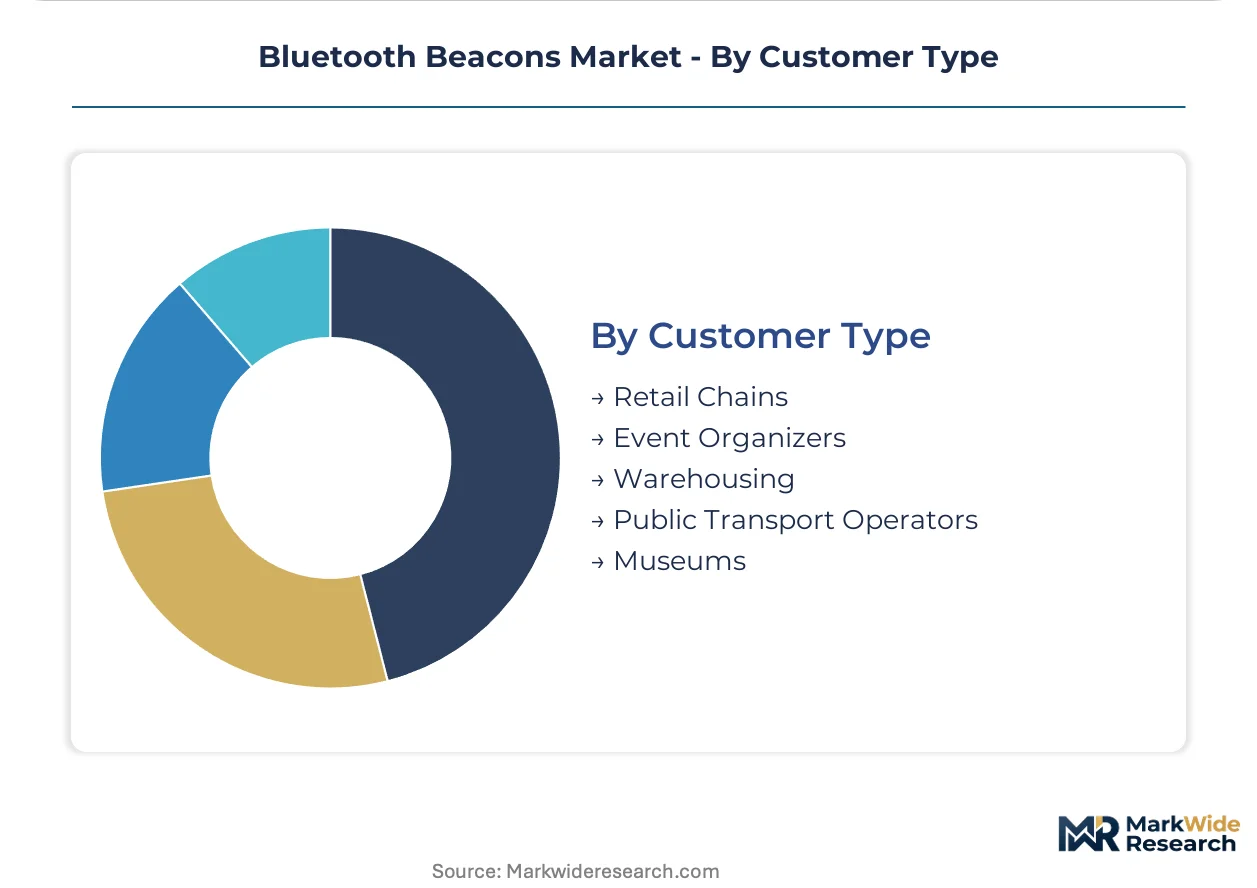
End-user technical sophistication determines sales engagement models, with warehousing and public transport operators specifying integrated systems while museums procure through cultural funding channels.
- Retail Chains:Multi-site rollouts demand centralized fleet management platforms and standardized hardware specifications. United States big-box operators unbundle beacon hardware from analytics software, treating location intelligence as a separate procurement category from device sourcing.
- Warehousing:Warehouse management system integration requirements dominate technical specifications. Legacy WMS middleware running on decade-old infrastructure demands custom API bridges for beacon data ingestion, extending sales cycles and services attach rates.
- Event Organizers:Temporary deployments prioritize rapid installation and retrieval for United States convention centers and sports venues.
- Public Transport Operators:Indian smart city mandates specify BLE beacon integration for transit wayfinding under urban renewal programs.
- Museums:Grant-funded cultural institutions in Germany and France balance visitor experience enhancement against restricted capital budgets.
Warehousing leads in per-deployment beacon count. Retail Chains is gaining share fastest as chains expand proximity marketing infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles-Long Beach complex underwrites North American beacon logistics, channeling Asian-manufactured hardware into United States distribution networks. Germany's Rhine-Alpine corridor anchors European supply chain density. India's Dedicated Freight Corridors are reshaping smart city deployment timelines.
United States
Metropolitan retail corridors in Chicago, Dallas, and Atlanta drive beacon density for proximity marketing infrastructure. The FCC governs 2.4 GHz unlicensed spectrum allocations under Part 15 rules, capping transmit power at +4 dBm. Logistics hubs surrounding Memphis and Louisville deploy warehouse-scale networks for real-time asset tracking, absorbing network density investments to overcome range constraints.
Germany
Automotive logistics hubs in Stuttgart and Munich specify ruggedized beacon hardware for forklift-mounted asset tracking. REACH substance restrictions on battery chemistries extend certification timelines by 4-6 months for products containing restricted heavy metals. Hospital systems in Berlin and Hamburg pilot medical equipment location networks, creating regulated vertical demand with premium pricing tolerance.
China
Shenzhen and Dongguan manufacturing clusters scale BLE beacon module production for export markets. The Ministry of Industry and Information Technology (MIIT) oversees radio equipment type approval for 2.4 GHz devices. Yangtze River Delta logistics operators integrate beacon networks with warehouse automation systems, compressing inventory search cycles in Shanghai and Ningbo distribution centers.
India
Municipal infrastructure projects under urban renewal programs specify BLE beacon integration for public transit wayfinding in Delhi and Mumbai. The Bureau of Indian Standards (BIS) mandates certification for imported radio equipment. Bangalore and Hyderabad smart city pilots deploy location beacons for campus-scale navigation, leveraging enhanced transmit power for extended range coverage.
France
Event venues and museum complexes in Paris deploy visitor flow analytics using beacon networks. The CNIL enforces GDPR-compliant data processing for proximity marketing applications. Lyon and Marseille logistics operators adopt rugged beacon hardware for cross-dock automation, absorbing premium positioning for IP67-rated environmental tolerance.
Bluetooth Beacons Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base stratifies between precision-tier suppliers capturing UWB-adjacent margins and cost-tier manufacturers competing on module economics. Three archetypes dominate: semiconductor houses with integrated SoC architectures, industrial hardware vendors with ruggedized enclosure expertise, and software-layer analytics providers unbundling from hardware. Competitive moves center on protocol stack diversification and geographic expansion into municipal smart city programs.
Within the semiconductor archetype, Nordic Semiconductor and Texas Instruments anchor European and North American supply respectively. Estimote occupies a position exemplifying the software-differentiation model, unbundling analytics from hardware procurement. Zebra Technologies represents the industrial-systems tier, bridging ruggedized hardware with enterprise asset-tracking deployments. These three entities collectively illustrate the market's tripartite specialization between silicon, software, and systems integration.
| Leading Market Players |
|---|
| Kontakt Micro-Location |
| Estimote |
| Nordic Semiconductor |
| Silicon Laboratories |
| Zebra Technologies |
| Gimbal |
| Texas Instruments |
| Minew Technologies |
| MOKOSmart |
| Others |
Cost & Logistics Intelligence
Lithium battery supply concentration in East Asia determines both margin compression in cost-tier beacon manufacturing and the geographic shape of component sourcing networks. This dependency exposes pricing power to raw material volatility while forcing tiered procurement strategies across premium ruggedized and disposable compact product lines.
Pricing Analysis
Volume-discount tiering structures dominate beacon procurement, with three-tier pricing separating ruggedized industrial units from standard retail deployments and economy-grade consumables. Price differentiation hinges on IP67 certification grade and after-sales service bundling, with German automotive logistics hubs absorbing premium positioning for field maintenance contracts. Pricing pressure stems from UWB substitution in high-precision applications, compressing BLE-only vendor margins. Retail chains exhibit highest price sensitivity through unbundled hardware-analytics procurement, while healthcare systems show lowest sensitivity due to regulated premium tolerance.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment limit advanced node access for Chinese BLE SoC producers, constraining module cost curves. Component sourcing draws from Taiwan for foundry services, China for PCB assembly, and South Korea for memory integration. Raw material dependencies center on lithium cylindrical cells, Nordic Semiconductor integrated SoCs, and Texas Instruments analog components. Single-source vulnerability concentrates in East Asian battery suppliers. Distribution runs through industrial distributors for warehousing deployments and direct OEM channels for retail chain rollouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BLE 5.3 direction-finding capabilities are disrupting legacy RSSI-based proximity estimation, creating a high-growth inflection as United States department stores accelerate hardware refresh cycles.
For Market Incumbents: Build switching-cost moats through embedded analytics platforms that warehouse operators cannot easily migrate from legacy WMS middleware. Deepen backward integration into Nordic Semiconductor SoC supply to secure allocation during foundry constraints. Invest in Bluetooth SIG pre-certification programs to compress 8-12 week qualification timelines that threaten seasonal retail procurement windows. For New Entrants and Emerging Players: Pursue healthcare asset tracking in German hospital systems, where regulated vertical demand tolerates premium pricing and procurement cycles extend 18-24 months. Target Indian smart city municipal infrastructure under urban renewal programs specifying BLE beacon integration for transit wayfinding. Lead with edge-computing smart beacon architectures that eliminate cloud dependency for latency-sensitive medical equipment location. For Investors and Strategic Acquirers: REACH substance restrictions on battery chemistries reshape the acquisition landscape toward European suppliers with reformulated power subsystem expertise. Five-to-ten year viability favors vendors with software-layer differentiation unbundled from hardware commoditization. Monitor Apple U1 chip ecosystem expansion as the signal indicating UWB displacement velocity in premium consumer positioning applications.| Strategic Initiative | Industry Significance |
|---|---|
| BLE 5.3 Direction-Finding Deployment | United States department stores pilot aisle-level customer journey mapping without UWB hardware premiums. |
| Privacy-by-Design Architecture Investment | GDPR-compliant anonymization frameworks embed procurement prerequisites in European retail chains. |
| Ambient IoT Energy Harvesting Integration | Photovoltaic and RF power elimination of battery dependency reshapes shelf-edge retail economics. |
| Healthcare Vertical Specialization | German hospital systems pilot medical equipment location networks with regulated premium pricing tolerance. |
| Indian Smart City Municipal Partnership | Urban renewal programs in Delhi and Mumbai specify BLE beacon integration for public transit wayfinding. |
Research Approach
The analysis maps compact, rugged, USB, location, and smart beacon sub-sectors, each validated through retail chain procurement directors, warehouse operations managers, healthcare biomedical engineers, and municipal smart city planners. Primary interviews with Bluetooth SIG certification specialists and industrial distributor channel heads combined with secondary validation from FCC Part 15 filings, Bluetooth SIG Qualification Program databases, and EU REACH substance restriction notices. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across technology protocol and use case dimensions.
Assumptions held fixed include FCC Part 15 transmit power ceilings at +4 dBm and Bluetooth SIG interoperability mandates, while BLE 5.3 adoption velocity and UWB substitution rates varied across scenario branches. Segmentation dimensions modeled encompass product type, technology protocol, use case application, and customer vertical throughout the projection horizon. CAGRs derived from installed base growth curves weighted by average selling price erosion in cost-tier segments and premium expansion in precision-tier alternatives. Forecast inputs incorporated lithium battery raw material indices and smart city infrastructure budget allocations.
Macroeconomic conditions sit as an overlay; deviation in logistics capital expenditure cycles and consumer retail foot traffic recovery would shift the trajectory. Forecasts reflect documented assumptions on protocol migration timelines and regulatory certification pacing. Material shifts in Apple UWB ecosystem expansion or REACH substance restriction enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Safety Motion Control System Market
Sensors
Real Time Location System Market
Sensors
Consumer 3D Sensing Products Market
Sensors
Barcode Scanner Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Asia Pacific Container Monitoring Market
Sensors
Vibration Monitoring Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Conveyor Monitoring Market
Sensors
Global RFID Market
Sensors
Handheld GPS Units Market
Sensors
APAC Wireless Sensors Market
Sensors
Lidar in Mapping Market
Sensors
Alcohol Sensor Market
Sensors
Eye Tracking Solutions Market