
 Global Liver Cancer Therapeutics Market | 2026-2036
Global Liver Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liver Cancer Therapeutics Market Foresight
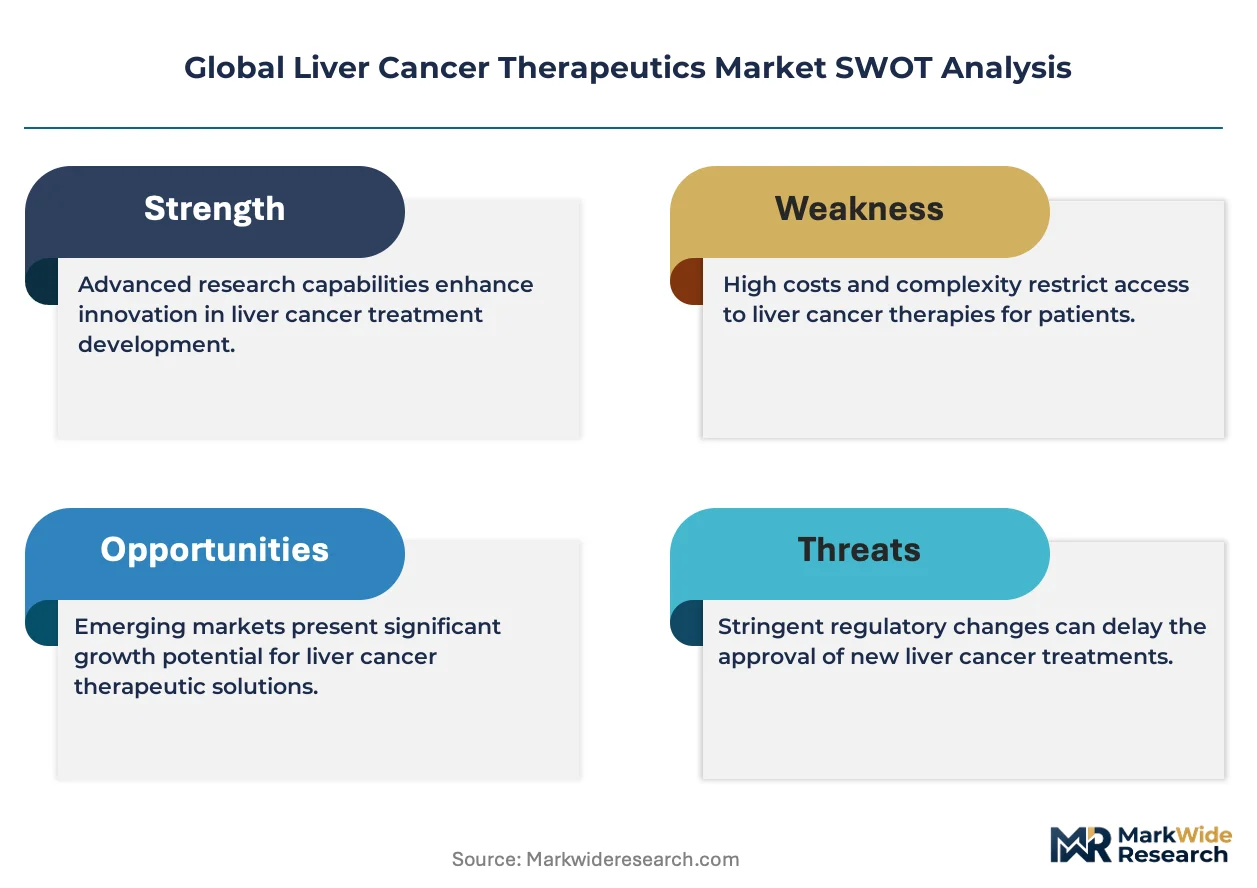
Sorafenib is consolidating its position as the reference standard against which newer agents benchmark efficacy, reshaping cost-effectiveness calculations across hepatocellular carcinoma protocols. Bristol-Myers Squibb leverages its dual immunotherapy franchise to anchor positioning in first-line settings. Eisai Co., Ltd. sustains geographic dominance through its lenvatinib footprint across Asian markets. Bayer AG differentiates through radioembolization assets that complement its systemic therapy portfolio.
Liver cancer therapeutics comprise systemic and locoregional interventions designed to interrupt tumor proliferation, angiogenesis, or immune evasion in primary hepatic malignancies, with molecular targets spanning tyrosine kinase receptors, PD-1/PD-L1 checkpoints, and vascular endothelial growth factor pathways. These agents serve to extend survival in hepatocellular carcinoma and cholangiocarcinoma where surgical resection rates remain low due to late-stage presentation. Immunotherapy commands the fastest expansion as checkpoint inhibitors demonstrate durable responses in previously refractory populations, while targeted therapy retains the largest revenue pool through established multikinase inhibitors. Radioembolization segments capture premium pricing in intermediate-stage patients with preserved liver function who fall outside transplant criteria.
FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines and reshape commercial launch sequencing for novel agents. REACH compliance and EMA Good Manufacturing Practice standards govern active pharmaceutical ingredient sourcing and finished product release across European supply chains. Stakeholders must monitor evolving PD-1 combination data and regional reimbursement decisions to allocate development resources across therapy areas.
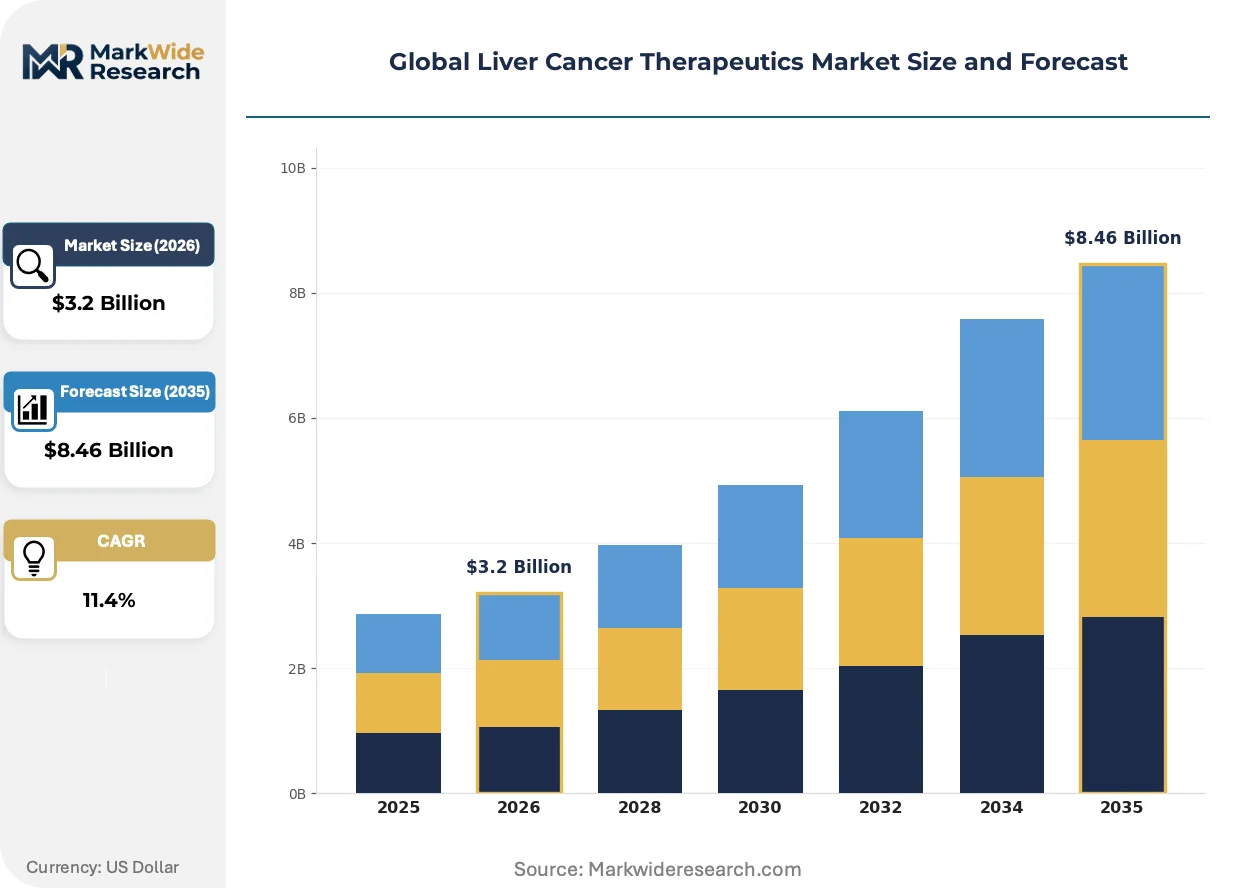
Market Dynamics
Checkpoint inhibitor combination protocols are compressing development timelines and redrawing competitive boundaries across hepatocellular carcinoma treatment algorithms, forcing incumbent multikinase inhibitors into earlier-line positioning battles.
Growth Catalysts
- Breakthrough Therapy Designation:FDA accelerated pathways compress Phase II-to-approval intervals for novel PD-1 combinations, compressing commercialization timelines by 18-24 months versus standard review.
- Hepatitis C Eradication Backlog:Cured hepatitis C populations in the United States and Japan exhibit rising hepatocellular carcinoma incidence as cirrhotic livers progress, expanding addressable patient pools for systemic therapy.
- Radioembolization Integration:Yttrium-90 microsphere delivery systems enable bridge-to-transplant protocols at oncology centers in China and Germany, creating combination therapy demand with checkpoint inhibitors.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Tyrosine kinase inhibitor synthesis depends on Chinese contract manufacturing organizations for intermediate supply, exposing formulation sponsors to geopolitical friction and customs delays.
- Biomarker Testing Fragmentation:PD-L1 expression assays lack harmonized cutoffs across CLIA-certified laboratories in the United States, creating enrollment friction for biomarker-selected trials and reimbursement uncertainty.
- Curative Substitution:Liver transplantation and surgical resection at specialized centers in South Korea and Taiwan capture resectable patients, capping the systemic therapy addressable population to unresectable cohorts.
Strategic Opportunities
- Adjuvant Therapy White Space:Post-resection populations in Japan lack approved systemic options, representing an untapped indication for immune checkpoint inhibitors following resected hepatocellular carcinoma.
- Cholangiocarcinoma FGFR Expansion:FGFR2 fusion testing adoption at community oncology practices in the United States creates targeted therapy demand distinct from hepatocellular carcinoma protocols.
- EMA Priority Medicines Pathway:European orphan drug incentives for biliary tract malignancies reduce regulatory submission costs and accelerate market access across France, Italy, and Spain.
Industry Challenges
- Immuno-oncology Talent Scarcity:Combination trial design requires biostatisticians fluent in competing risks methodology, with acute shortages at contract research organizations supporting Phase III hepatobiliary programs.
- Companion Diagnostic Synchronization:PD-L1 assay co-development timelines with Agilent and Roche frequently misalign with new drug application submissions, forcing regulatory filing delays or label restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liver Cancer Therapeutics Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $8.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Radioembolization, Monoclonal Antibodies Therapy Area: Hepatocellular Carcinoma, Cholangiocarcinoma, Fibrolamellar Carcinoma, Combined Hepatocellular-Cholangiocarcinoma, Angiosarcoma End User: Oncology Centers, Specialty Clinics, Research Institutions, Diagnostic Laboratories, Treatment Hospitals Delivery Mode: Oral, Intravenous, Transarterial, Implantable Devices, Subcutaneous, Intra-arterial |
| Companies Covered | F. Hoffmann-La Roche, Bristol-Myers Squibb Company, Eisai Co., Ltd., Bayer AG, Merck & Co., AstraZeneca, Pfizer Inc., Exelixis Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liver Cancer Therapeutics Market Shifts & Advancements
Artificial intelligence is infiltrating radiologic response assessment and biomarker discovery workflows, compressing interpretation cycles and reshaping how sponsors demonstrate efficacy to regulators.
Deep learning algorithms trained on contrast-enhanced MRI sequences are automating lesion segmentation and treatment response categorization at academic medical centers in the United States. Radiologists at Memorial Sloan Kettering and MD Anderson are deploying these tools to standardize mRECIST interpretation across multicenter trials. This automation is reducing inter-reader variability and enabling centralized imaging endpoints that satisfy FDA evidentiary standards for accelerated approval.
EMA's revised guideline on clinical evaluation of hepatocellular carcinoma mandates overall survival as the primary endpoint for first-line registration trials, displacing progression-free survival as an acceptable surrogate. European sponsors must now power studies for mortality endpoints, extending trial duration and increasing enrollment requirements. This regulatory elevation most impacts Phase III programs targeting the European Union simultaneous with United States submission, forcing protocol amendments and statistical consultation investments.
Hospital procurement committees are consolidating oncology formulary decisions at the integrated delivery network level, displacing individual physician prescribing autonomy. United States health systems including Kaiser Permanente and Cleveland Clinic now mandate pharmacy and therapeutics committee pre-approval for checkpoint inhibitor combinations, inserting cost-effectiveness thresholds into access decisions. This concentration is most visible in community oncology practices acquired by hospital systems, where prior authorization timelines have extended from 48 hours to 5-7 days.
Global Liver Cancer Therapeutics Market Segmentation
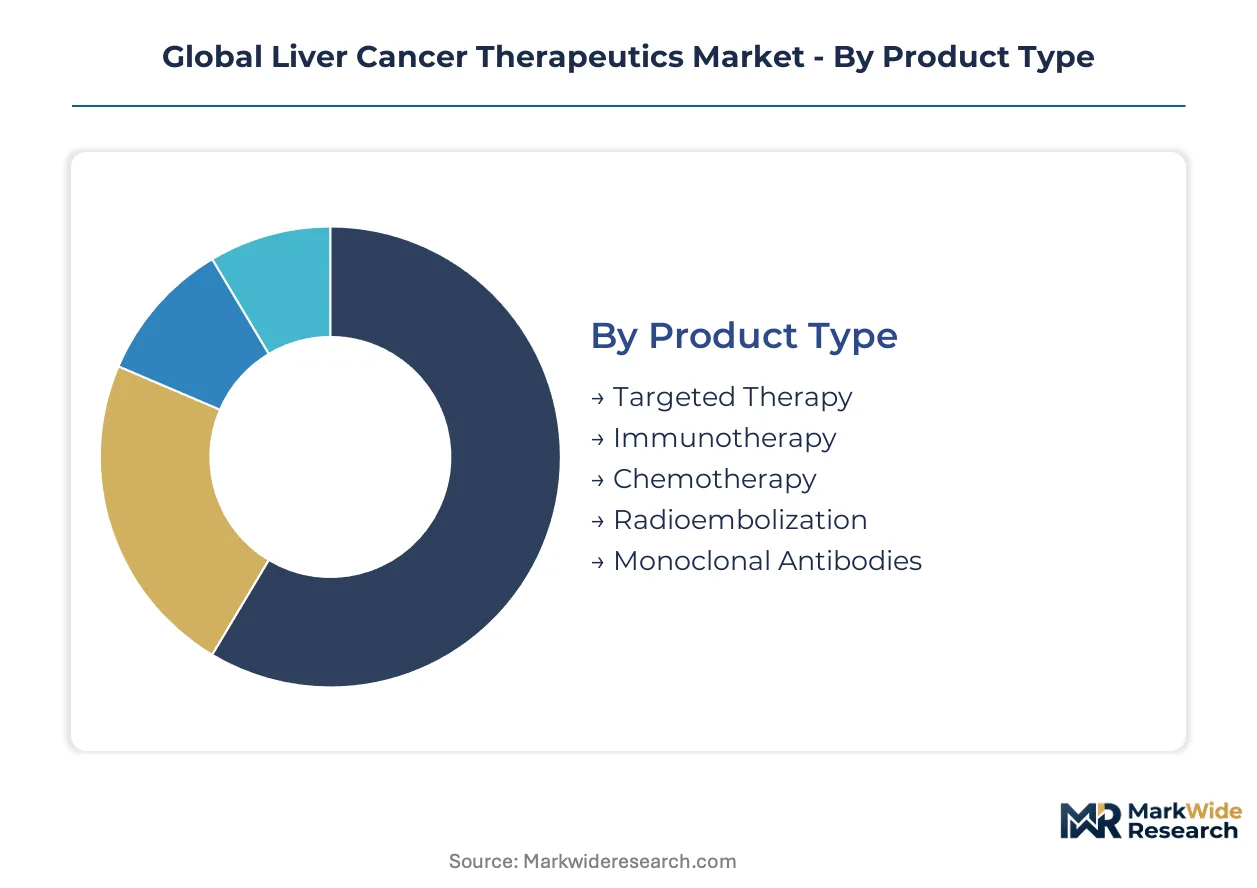
Liver cancer therapeutics segmentation reveals distinct commercial architectures across intervention types and care settings. Therapy area distinctions drive regulatory strategy, while delivery mode selection shapes manufacturing partnerships and reimbursement pathways.
Product Type:
Integration depth varies sharply—immunotherapy and targeted therapy function as standalone systemic interventions, while radioembolization requires embedded interventional radiology infrastructure.
- Targeted Therapy:Multikinase inhibitors blocking VEGF and PDGF signaling dominate first-line protocols. Demand clusters at comprehensive oncology centers in the United States and Japan where molecular profiling guides patient selection. EMA's evolving hepatocellular carcinoma guidelines are elevating overall survival requirements for this segment's next-generation entrants.
- Immunotherapy:Checkpoint inhibitors targeting PD-1 and CTLA-4 deliver durable responses in previously refractory populations. Oncology centers across China and Germany are expanding combination protocols with transarterial chemoembolization, compressing development timelines for novel PD-1 assets.
- Chemotherapy:Systemic cytotoxic agents retain utility in resource-constrained settings and salvage protocols.
- Radioembolization:Yttrium-90 microsphere delivery demands specialized interventional radiology suites and nuclear medicine licensing.
- Monoclonal Antibodies:Anti-VEGF constructs complement tyrosine kinase inhibitors in combination regimens.
Volume placements concentrate in targeted therapy; the faster expansion belongs to immunotherapy.
Therapy Area:
Cost tier stratification separates curative-intent surgical candidates from palliative systemic populations, with biomarker-defined subtypes commanding premium pricing.
- Hepatocellular Carcinoma:Primary hepatic malignancy arising from cirrhotic liver tissue accounts for the majority of addressable patients. Hepatitis-related etiologies in China and the United States sustain demand for multikinase inhibitors and checkpoint combinations.
- Cholangiocarcinoma:Biliary tract malignancies with FGFR2 fusion subsets unlock targeted therapy opportunities. Community oncology practices in the United States are adopting molecular testing panels that identify actionable alterations.
- Fibrolamellar Carcinoma:Rare hepatocellular variant affecting younger patients without underlying cirrhosis.
- Combined Hepatocellular-Cholangiocarcinoma:Mixed histology tumors requiring multimodal treatment approaches.
- Angiosarcoma:Vascular hepatic malignancy with limited systemic options and poor prognosis.
Revenue concentration sits with hepatocellular carcinoma; cholangiocarcinoma is climbing the fastest on biomarker-tailored therapy expansion.
End User:
Customer type segmentation distinguishes high-academic centers with trial infrastructure from community settings where formulary committees gate access.
- Oncology Centers:Dedicated cancer facilities at academic medical centers in the United States and South Korea conduct Phase III trials and administer combination immunotherapy protocols. FDA breakthrough therapy designations accelerate patient access at these sites.
- Specialty Clinics:Hepatology-focused practices manage early-stage surveillance and coordinate transplant referrals.
- Research Institutions:Translational laboratories at MD Anderson and Memorial Sloan Kettering validate biomarker assays.
- Diagnostic Laboratories:CLIA-certified sites perform PD-L1 expression testing and next-generation sequencing.
- Treatment Hospitals:General acute care facilities with oncology units handle stable patients on oral tyrosine kinase inhibitors.
Patient volumes aggregate at oncology centers; specialty clinics are gaining share fastest on early detection program expansion.
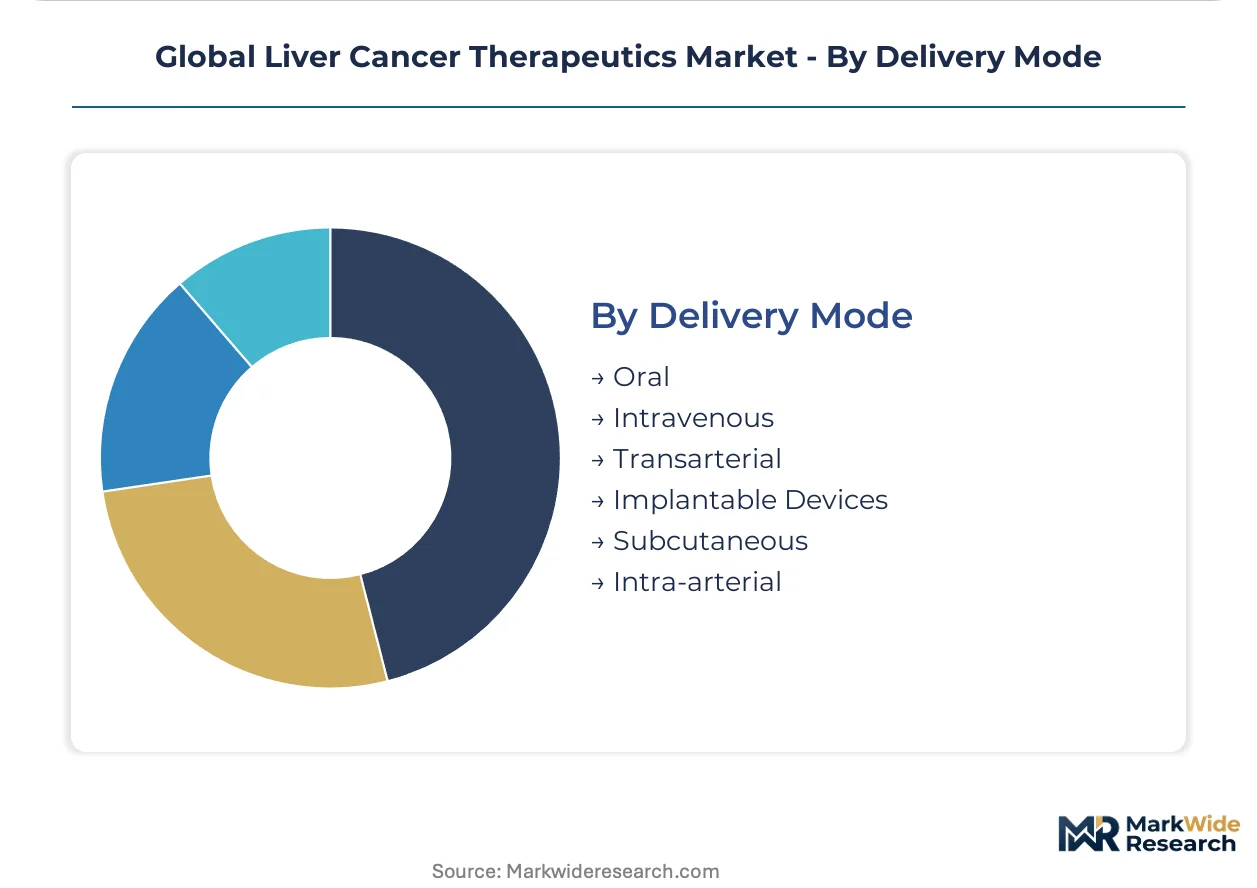
Delivery Mode:
Supply concentration shapes regional availability—oral agents distribute through retail pharmacy networks while intra-arterial procedures require procedure room capital investment.
- Oral:Tyrosine kinase inhibitors enable outpatient administration and patient convenience. Pharmacy benefit managers in the United States are tightening prior authorization requirements for these agents.
- Intravenous:Checkpoint inhibitors require infusion center capacity and cold chain logistics. Oncology centers across Japan and Germany are expanding chair capacity to accommodate combination protocols.
- Transarterial:Interventional radiology-delivered therapies bridge to transplant in intermediate-stage disease.
- Implantable Devices:Hepatic arterial infusion pumps enable regional chemotherapy delivery.
- Subcutaneous:Emerging administration route for select monoclonal antibodies.
- Intra-arterial:Selective catheter-directed therapy spares systemic toxicity.
Prescription volume concentrates in oral delivery; intravenous administration is expanding most quickly on immunotherapy protocol proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for liver cancer therapeutics concentrates in the United States, China, and Japan, where hepatitis-related disease burdens and aging cirrhotic populations sustain systemic therapy adoption. Regulatory pathways at the FDA and PMDA compress development timelines, while oncology centers in Germany and South Korea expand combination immunotherapy protocols.
United States
Hepatitis C eradication backlogs and rising non-alcoholic steatohepatitis prevalence expand addressable patient pools for checkpoint inhibitors. FDA breakthrough therapy designations accelerate Phase II-to-approval intervals by 18-24 months. Memorial Sloan Kettering and MD Anderson anchor multicenter trial networks that validate mRECIST imaging endpoints for accelerated approval submissions.
China
Hepatitis B endemicity sustains the world's largest hepatocellular carcinoma incidence, driving demand for multikinase inhibitors and PD-1 combinations. NMPA priority review pathways compress regulatory timelines for innovative oncology assets. Oncology centers in Beijing and Shanghai are expanding transarterial chemoembolization suites to accommodate bridge-to-transplant protocols with immunotherapy.
Japan
Aging cirrhotic populations and post-hepatitis C surveillance programs sustain adjuvant therapy demand. PMDA sakigake designation accelerates access for first-in-class agents targeting resected hepatocellular carcinoma. The National Cancer Center Hospital and University of Tokyo Hospital anchor biomarker validation studies for PD-L1 companion diagnostics.
Germany
EMA priority medicines pathways and orphan drug incentives reduce regulatory submission costs for biliary tract malignancy programs. REACH compliance governs active pharmaceutical ingredient sourcing across European supply chains. Heidelberg University Hospital and Charité Berlin integrate Yttrium-90 radioembolization with checkpoint inhibitor protocols for intermediate-stage disease.
South Korea
Liver transplantation centers at Asan Medical Center and Samsung Medical Center capture resectable patients, capping systemic therapy to unresectable cohorts. The national health insurance system maintains reimbursement for tyrosine kinase inhibitors in first-line hepatocellular carcinoma. Seoul-based contract research organizations support Phase III hepatobiliary programs with competing risks biostatistics expertise.
Global Liver Cancer Therapeutics Market Competitive Landscape
Checkpoint inhibitor combination development dominates the current landscape, compressing positioning battles between multikinase incumbents and immunotherapy entrants. The vendor base consolidates around three strategic archetypes: Big Pharma oncology franchises with dual immunotherapy assets, mid-cap targeted therapy specialists with Asian market footprints, and diversified conglomerates with radioembolization device portfolios. M&A activity targets biomarker platform companies, while strategic partnerships synchronize companion diagnostic co-development timelines with regulatory submissions.
Within the Big Pharma tier, F. Hoffmann-La Roche and Bristol-Myers Squibb occupy positions defined by PD-1/PD-L1 checkpoint inhibitor leadership and combination protocol expansion. Eisai Co., Ltd. exemplifies the Asia-centric targeted therapy archetype through its lenvatinib footprint across Japanese and Chinese markets. These three anchors represent distinct competitive vectors: immunotherapy scale, geographic concentration, and multikinase establishment.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Bristol-Myers Squibb Company |
| Eisai Co., Ltd. |
| Bayer AG |
| Merck & Co. |
| AstraZeneca |
| Pfizer Inc. |
| Exelixis Inc. |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States now command formulary pre-approval authority over checkpoint inhibitor combinations, compressing pricing power into procurement committee thresholds rather than physician discretion. This buyer concentration forces manufacturers toward value-based contracting structures that tether reimbursement to radiographic response metrics.
Pricing Analysis
Volume placements concentrate in oral tyrosine kinase inhibitors where margins face compression from pharmacy benefit manager prior authorization tightening, while intravenous immunotherapy commands premium positioning through infusion center capacity constraints. Price differentiation rests on biomarker stratification and companion diagnostic bundling, with PD-L1-positive subsets capturing favorable access terms. Cost compression in first-line multikinase inhibitors is intensifying as checkpoint combinations displace established protocols. Community oncology practices acquired by hospital systems exhibit highest price sensitivity due to formulary committee oversight, whereas academic medical centers with trial infrastructure demonstrate lowest sensitivity on protocol-driven demand.
Supply Chain Analysis
Dual-sourcing requirements for active pharmaceutical ingredients now dominate sponsor qualification protocols, with FDA and EMA auditors mandating validated secondary suppliers for critical tyrosine kinase inhibitor intermediates. API synthesis draws from contract manufacturing organizations in China and India, with finished formulation concentration in Germany and the United States. Key inputs span naphthylamine derivatives, pyridine-based heterocycles, and chiral resolution reagents. Single-source vulnerability concentrates in hepatitis B vaccine-derived biologics for combination immunotherapy development. Distribution runs through specialty pharmacy networks for oral agents and direct-to-site cold chain logistics for biologics requiring infusion center delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liver cancer therapeutics sector sits in a technology-transition phase where checkpoint inhibitor combinations are systematically displacing multikinase inhibitor monotherapy as the first-line reference standard, compressing development timelines and reshaping competitive boundaries.
For Market Incumbents: Anticipate displacement of sorafenib and lenvatinib positioning by securing accelerated approval pathways for PD-1 combination assets through FDA breakthrough therapy designation, while reinforcing manufacturing capacity in Singapore and Switzerland to hedge against API sourcing friction from Chinese contract manufacturing organizations. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for biomarker-selected cholangiocarcinoma programs targeting FGFR2 fusion populations, with European orphan drug incentives providing parallel access leverage. The most penetrable white space sits in adjuvant hepatocellular carcinoma indications post-resection, where Japan's PMDA sakigake pathway accelerates first-in-class positioning. A go-to-market angle anchored to companion diagnostic co-development with Agilent or Roche synchronizes regulatory submission timelines. For Investors and Strategic Acquirers: The window for entry favors platform biotechnology firms with differentiated checkpoint inhibitor mechanisms and validated PD-L1 assay partnerships, positioned for acquisition by Big Pharma oncology franchises seeking combination protocol breadth. Long-term viability hinges on five-to-ten-year immunotherapy durability data maturation. The signal to watch as inflection indicator is EMA's evolving mandate for overall survival primary endpoints, which extends trial duration and elevates capital requirements for European simultaneous submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-approval intervals by 18-24 months versus standard review. |
| Companion Diagnostic Co-development | Agilent and Roche PD-L1 assay synchronization prevents regulatory filing delays and label restrictions. |
| Manufacturing Scale-Up | Singapore and Switzerland formulation capacity hedges against Chinese API sourcing geopolitical friction. |
| Clinical Trial Advancement | EMA overall survival endpoint mandates extend European trial duration and increase enrollment requirements. |
| Pipeline Diversification | FGFR2 fusion-targeted cholangiocarcinoma programs unlock biomarker-tailored pricing distinct from hepatocellular carcinoma protocols. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov records formed the secondary backbone of this analysis, cross-referenced with formulary database audits and CMS Medicare reimbursement data. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated pipeline assumptions and commercial timeline estimates. Bottom-up patient-flow modeling and top-down revenue triangulation converged on segmentation outputs across therapy area, delivery mode, and regional regulatory clusters.
Historical trendline analysis tracked multikinase inhibitor and checkpoint inhibitor adoption curves across academic medical centers and community oncology practices, with projection frameworks modeling treatment line migration, biomarker testing penetration, and regional reimbursement evolution. Segmentation dimensions spanned intervention type, therapy area histology, end-user facility tier, and administration route. CAGRs were derived from fitted growth curves calibrated to regulatory approval velocity and formulary access expansion. Forecast inputs incorporated hepatitis C eradication backlog progression and non-alcoholic steatohepatitis incidence trajectories.
The model assumes a particular technology adoption path; alternative pathways for PD-1/CTLA-4 combination sequencing would alter the outlook for multikinase inhibitor revenue retention. Deviation in EMA overall survival endpoint enforcement timing would shift the outlook materially for European simultaneous submission strategies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Acute Myeloid Leukemia Therapeutics Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Gastritis Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Kaposi Sarcoma Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Palmoplantar Pustulosis Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Inflammatory Diseases Market