
 Mantle Cell Lymphoma Market | 2026-2036
Mantle Cell Lymphoma Market Size, Share, and Industry Trends Forecast 2026-2036
Mantle Cell Lymphoma Market Outlook
Multi-source clinical supply networks is broadening as pharmaceutical developers diversify manufacturing partnerships beyond single-contract relationships. Johnson & Johnson leverages its integrated diagnostics-to-therapy infrastructure to capture value across the Mantle Cell Lymphoma care continuum. AbbVie sustains competitive intensity through deep oncology pipeline investment and established hematology commercial infrastructure. Bristol-Myers Squibb anchors its position via broad immuno-oncology expertise that extends into lymphoid malignancy protocols.
Mantle Cell Lymphoma constitutes an aggressive B-cell non-Hodgkin lymphoma characterized by cyclin D1 overexpression and t(11;14)(q13;q32) chromosomal translocation, requiring cytarabine-based induction regimens and allogeneic stem cell transplantation for eligible patients. Targeted therapy segments, particularly BTK inhibitor and BCL-2 antagonist classes, command expanding prescriber preference due to superior progression-free survival versus conventional chemotherapy backbones. Immunotherapy applications, including CAR-T cell constructs, represent the fastest-growing structural category as manufacturing scale improves and outpatient administration protocols mature. Chemotherapy retains volume dominance in emerging markets where reimbursement constraints limit access to novel agents.
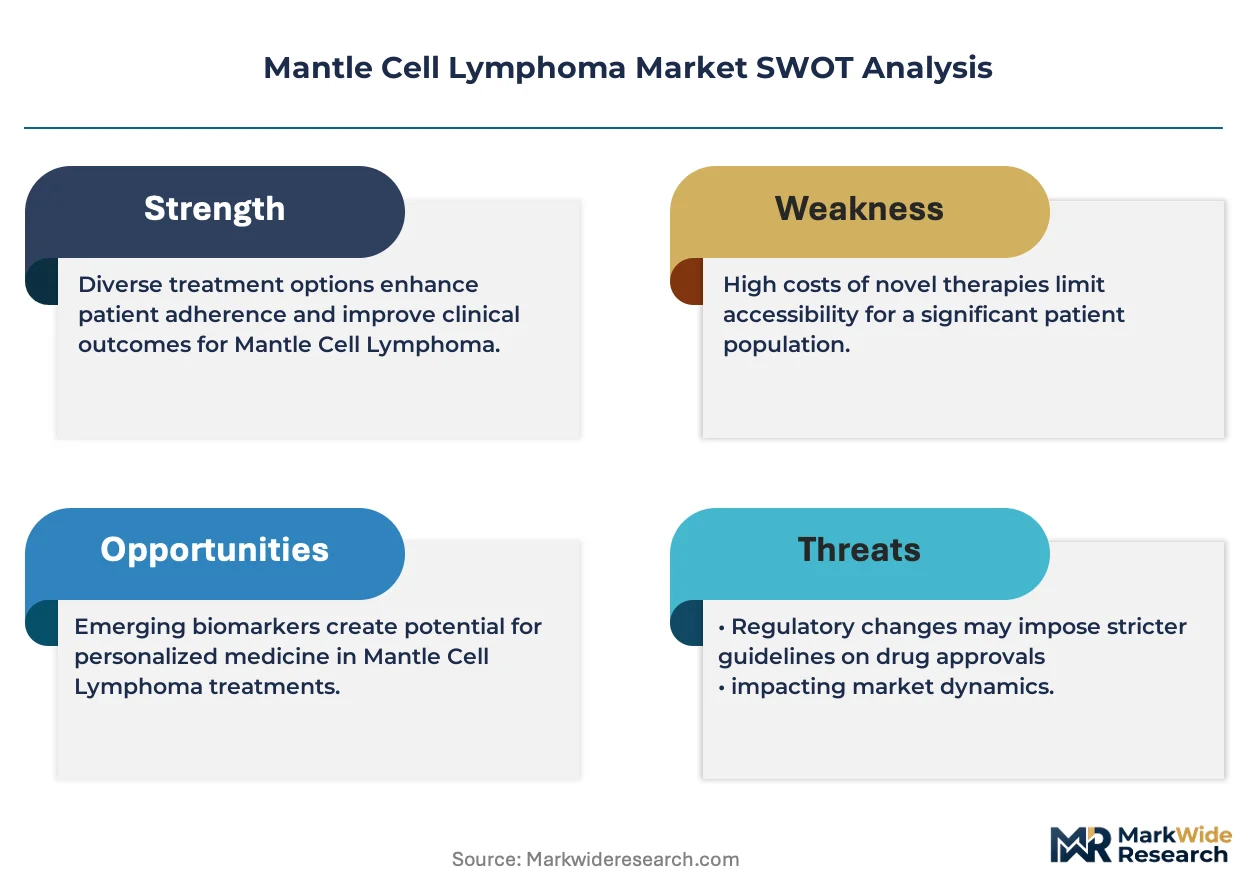
The FDA's oncology center of excellence and EMA's priority medicines scheme jointly shape clinical trial design requirements and post-market surveillance obligations for novel Mantle Cell Lymphoma therapeutics. NMPA accelerated review pathways in China compress regulatory lag for imported oncology products, reshaping launch sequencing strategies for multinational developers. Stakeholders must monitor biomarker-defined patient stratification advances and companion diagnostic co-development requirements to align portfolio investments with evolving payer evidence demands.
Market Dynamics
CAR-T manufacturing scale-up is compressing treatment timelines and forcing wholesale reconfiguration of specialty pharmacy networks and infusion center capacity planning across tertiary oncology centers.
Growth Catalysts
- FDA Accelerated Approval Pathway:The FDA's breakthrough therapy designation compresses clinical development timelines for novel BTK inhibitors and BCL-2 antagonists, compressing time-to-market by 12-18 months versus standard review.
- Companion Diagnostic Co-Development:Biomarker-defined patient stratification protocols are expanding addressable populations for precision-directed therapies through CD20, TP53, and SOX11 expression profiling.
- China NMPA Priority Review:The NMPA's accelerated review pathways for imported oncology products compress regulatory lag, enabling earlier commercial entry for multinational developers.
Market Restraints
- Allogeneic Stem Cell Donor Scarcity:HLA-matched donor availability constraints limit curative-intent transplantation to approximately 30% of eligible Mantle Cell Lymphoma patients in most treatment centers.
- Cytarabine Supply Concentration:Manufacturing concentration for high-dose cytarabine API among three European suppliers creates vulnerability to batch contamination or regulatory inspection delays.
- CAR-T Vector Production Bottlenecks:Lentiviral vector manufacturing capacity constraints at contract development organizations extend patient wait times and limit site expansion.
Strategic Opportunities
- Outpatient Administration Protocols:Shift from inpatient to ambulatory CAR-T monitoring is opening capacity at community oncology networks previously excluded from cellular therapy referral.
- EMA Priority Medicines Scheme:Early scientific dialogue and accelerated assessment pathways under PRIME designation reduce regulatory risk for novel mechanism submissions.
- Real-World Evidence Integration:Flatiron Health and similar oncology data platforms enable post-approval label expansion through retrospective efficacy analyses in relapsed/refractory populations.
Industry Challenges
- Cellular Therapy Manufacturing Workforce:Shortage of certified cell processing technicians and quality control specialists constrains manufacturing site expansion and batch release velocity.
- Cross-Border Cold Chain Integrity:Temperature excursion risks during international shipment of cryopreserved CAR-T products create liability exposure and patient treatment delays.
- Payer Evidence Generation Timelines:Compressed FDA approval windows often precede completion of health technology assessment submissions required by national reimbursement authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mantle Cell Lymphoma Market |
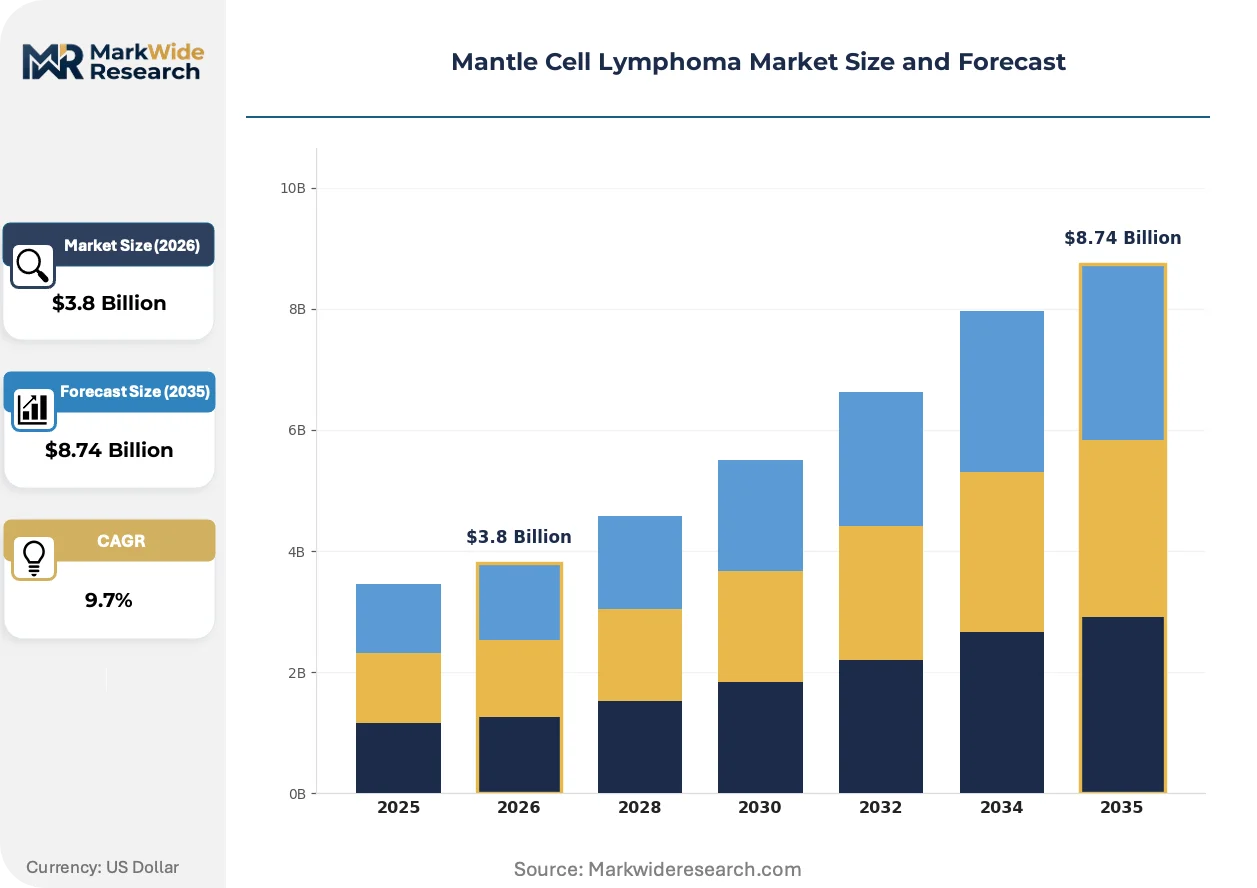
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Stem Cell Transplantation End User: Hospitals, Clinics, Specialty Cancer Centers, Research Institutions Application: Diagnosis, Treatment, Follow-Up Care, Palliative Care Therapy Area: Hematological Malignancies, Lymphoma, Oncology, Rare Cancers |
| Companies Covered | Johnson & Johnson, AbbVie, Gilead Sciences, Bristol-Myers Squibb, AstraZeneca, Roche Holding AG, Takeda Pharmaceutical, Eli Lilly and Company, BeiGene, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mantle Cell Lymphoma Market Strategic Shifts
Bi-specific antibody constructs and next-generation sequencing platforms are converging to enable earlier intervention and more durable remission maintenance protocols across treatment-naïve and relapsed patient populations.
Next-generation BTK inhibitors with reversible binding kinetics and improved CNS penetration profiles are rewriting prescriber preference hierarchies in high-risk patient subsets. Community oncology practices in the United States are adopting these agents ahead of academic center protocol updates. The shift is compressing market duration for first-generation covalent inhibitors and forcing portfolio prioritization decisions among developers with overlapping pipeline assets.
EMA's implementation of the Clinical Trials Information System and associated transparency requirements is reshaping data disclosure obligations for oncology sponsors. Mandatory publication of clinical study reports within specified timelines is accelerating competitive intelligence flows. European trial sponsors are responding by front-loading publication strategies and restructuring investigator grant agreements to retain narrative control.
Specialty pharmacy carve-out arrangements are consolidating patient access management under single-vendor contracts with integrated hub services. Payers in the United States are mandating exclusive distribution relationships that bypass traditional wholesale channels. The concentration is most visible in Medicare Advantage plans, where prior authorization automation and risk-based contracting align financial incentives across the dispensing and clinical monitoring continuum.
Mantle Cell Lymphoma Market Segmentation
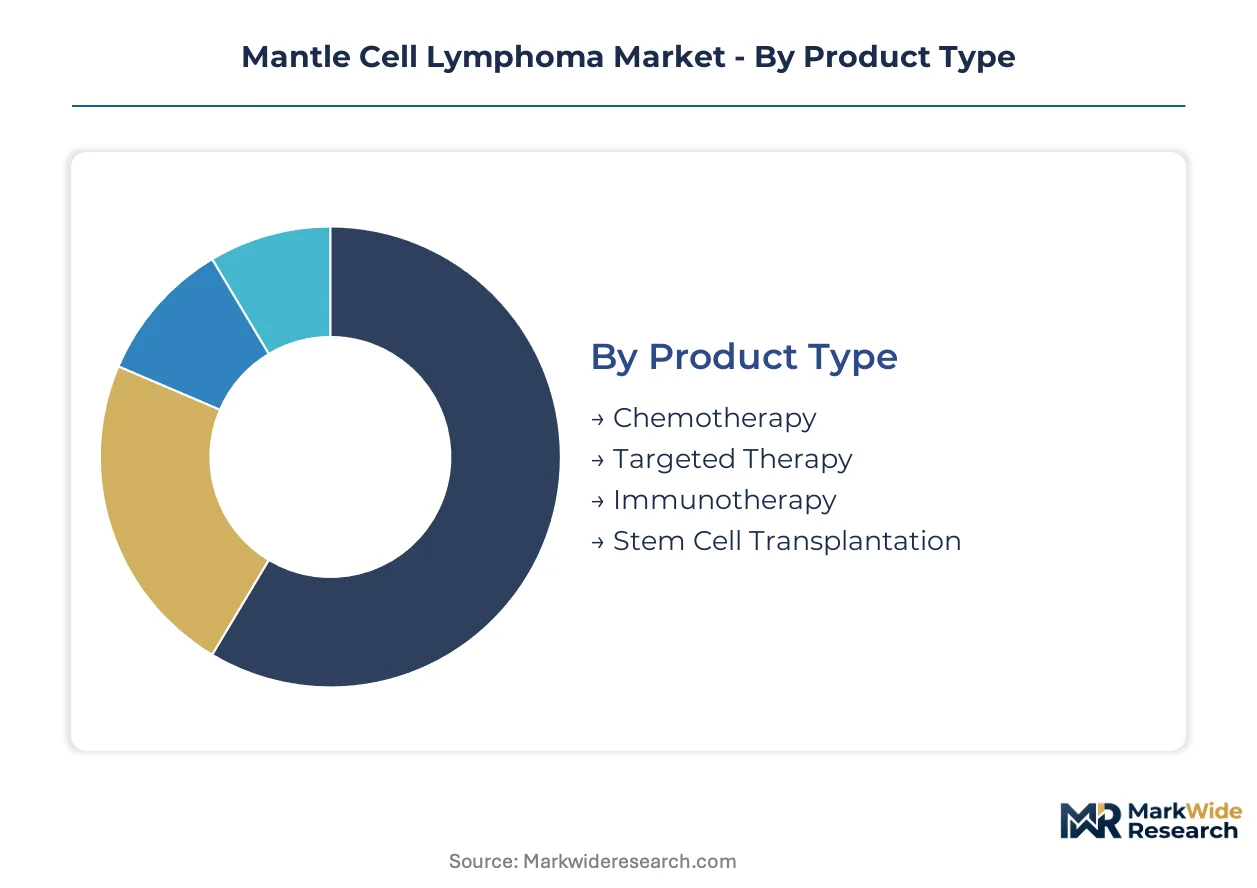
Segmentation in Mantle Cell Lymphoma therapeutics reveals distinct investment priorities across mechanism classes and care settings. Treatment modality selection varies sharply by patient fitness, biomarker profile, and reimbursement environment, creating parallel demand tracks that rarely intersect.
Product Type:
Upgrade cycles in Mantle Cell Lymphoma therapy accelerate as next-generation agents displace prior standards of care in relapsed settings.
- Targeted Therapy:BTK inhibitors and BCL-2 antagonists deliver superior progression-free survival versus chemotherapy backbones. Prescriber preference concentrates in the United States and Western Europe, where commercial infrastructure supports premium pricing and companion diagnostic integration.
- Immunotherapy:CAR-T cell constructs and bispecific antibodies represent the steepest expansion trajectory as manufacturing scale improves. CD19-directed cellular therapies command priority access at tertiary referral centers with established apheresis and cryopreservation capabilities.
- Chemotherapy:Cytarabine-based induction regimens retain volume dominance in emerging markets where reimbursement constraints limit novel agent access.
- Stem Cell Transplantation:Allogeneic protocols remain restricted to HLA-matched candidates with adequate organ function.
Targeted therapy sits at the top of the volume ranking, with immunotherapy climbing the fastest.
End User:
Cost tier stratification across delivery settings shapes prescriber access to cellular therapy and precision diagnostics.
- Specialty Cancer Centers:Accredited programs with FACT/JACIE certification control CAR-T administration and autologous stem cell collection. These sites concentrate clinical trial enrollment and early adoption of breakthrough designations.
- Hospitals:Tertiary academic medical centers anchor induction therapy delivery and manage transplant-eligible patient workflows.
- Clinics:Community oncology practices expand into oral targeted therapy administration as outpatient monitoring protocols mature.
- Research Institutions:NCI-designated cancer centers drive biomarker discovery and protocol development for relapsed/refractory populations.
Specialty cancer centers command the premium tier by capability, with community clinics gaining share fastest through oral agent expansion.
Application:
Application focus shifts toward earlier intervention as minimal residual disease testing enables treatment de-escalation decisions.
- Treatment:First-line and salvage protocols span chemotherapy, targeted agents, and cellular therapy sequences. Protocol selection hinges on TP53 mutation status and blastoid variant histology.
- Diagnosis:Flow cytometry, FISH for t(11;14), and next-generation sequencing panels define risk stratification at presentation.
- Follow-Up Care:Surveillance imaging and MRD monitoring extend duration of patient engagement post-remission.
- Palliative Care:Symptom management and end-of-life protocols address refractory disease progression.
Treatment absorbs the dominant share of resources, with diagnosis gaining investment intensity through liquid biopsy integration.
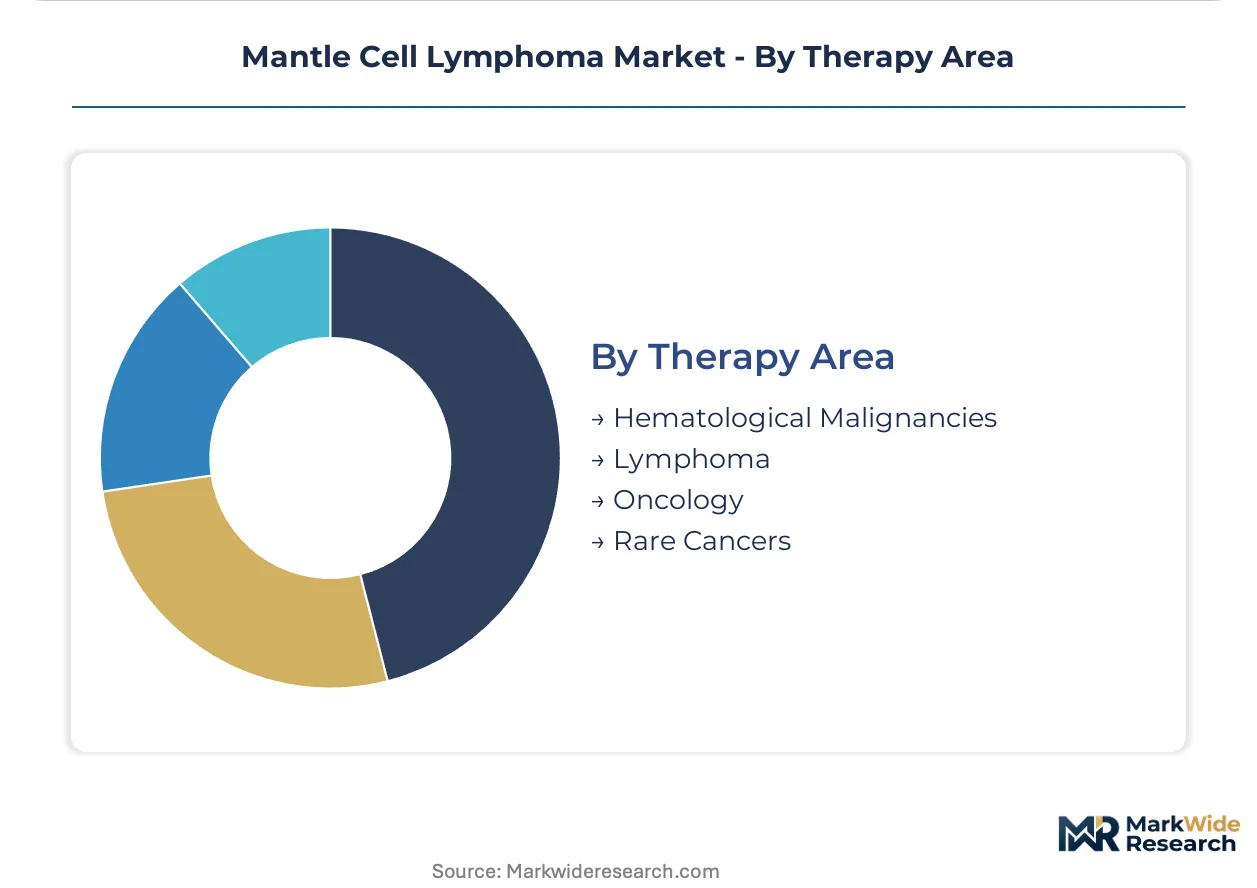
Therapy Area:
Margin structures vary across hematological malignancy categories based on orphan designation density and competitive intensity.
- Lymphoma:Mantle Cell Lymphoma sits within aggressive B-cell non-Hodgkin lymphoma protocols with established reimbursement pathways.
- Hematological Malignancies:Broader category spans leukemia, myeloma, and myelodysplastic syndromes with shared manufacturing infrastructure.
- Oncology:Cross-tumor mechanisms including BTK inhibition extend addressable populations beyond lymphoid malignancies.
- Rare Cancers:Orphan drug incentives and expedited regulatory pathways apply to Mantle Cell Lymphoma given incidence below 200,000 cases annually.
Lymphoma commands the deepest clinical infrastructure investment, with rare cancer designation unlocking the most favorable regulatory economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Boston biopharma corridor anchors clinical trial density for Mantle Cell Lymphoma therapeutics, with NCI-designated cancer centers driving protocol development and first-in-human enrollment. Regional demand patterns diverge sharply based on reimbursement infrastructure, regulatory pathway maturity, and tertiary referral network concentration.
United States
MD Anderson Cancer Center and Memorial Sloan Kettering anchor CAR-T administration capacity, with Medicare Advantage plans mandating specialty pharmacy carve-outs for cellular therapy. The FDA's breakthrough therapy designation compresses development timelines for novel BTK inhibitors. The Philadelphia-Washington corridor concentrates companion diagnostic co-development partnerships between diagnostic laboratories and pharmaceutical developers.
Germany
University Hospital Cologne and Charité Berlin anchor European trial enrollment for relapsed/refractory protocols. EMA's PRIME designation accelerates assessment timelines for bispecific antibody submissions. The Munich-Stuttgart axis concentrates hematology commercial infrastructure and payer negotiation expertise for premium oncology pricing.
China
Beijing Cancer Hospital and Fudan University Shanghai Cancer Center drive NMPA priority review submissions for imported BCL-2 antagonists. The NMPA's accelerated review pathways compress regulatory lag versus historical timelines. The Yangtze River Delta biotech cluster incubates domestic CAR-T developers targeting cost-competitive manufacturing models.
Japan
National Cancer Center Hospital and Osaka University Hospital anchor PMDA sakigake designation applications for next-generation sequencing-guided protocols. PMDA's pioneer review system compresses approval timelines for orphan oncology indications. The Kanto region concentrates hematology specialist density and transplant center accreditation.
Switzerland
University Hospital Zurich and Geneva University Hospitals anchor European reference pricing negotiations for premium lymphoma therapeutics. Swissmedic's expedited assessment pathways align with EMA centralized procedures. The Basel-Zurich corridor concentrates pharmaceutical headquarters and clinical operations infrastructure for global trial coordination.
Mantle Cell Lymphoma Market Competitive Environment
Global majors compete with regional champions across regulatory pathway expertise and hematology commercial infrastructure. The vendor base organizes around three tiers: integrated pharmaceutical conglomerates with diagnostics-to-therapy platforms, mid-cap oncology specialists with deep hematology pipelines, and emerging biotech developers with novel mechanism assets. Dominant competitive moves include companion diagnostic co-development partnerships and manufacturing scale-up for cellular therapy capacity.
Within the integrated conglomerate tier, Johnson & Johnson and AbbVie occupy positions spanning the Mantle Cell Lymphoma care continuum from diagnostic profiling through targeted therapy administration. Bristol-Myers Squibb anchors the immuno-oncology specialist archetype with broad lymphoid malignancy expertise. These three exemplify divergent strategic postures: platform integration versus therapeutic focus versus immunotherapy dominance.
| Leading Market Players |
|---|
| Johnson & Johnson |
| AbbVie |
| Gilead Sciences |
| Bristol-Myers Squibb |
| AstraZeneca |
| Roche Holding AG |
| Takeda Pharmaceutical |
| Eli Lilly and Company |
| BeiGene |
| Others |
Value Chain & Pricing Dynamics
Breakthrough designation tiering separates premium cellular therapies from oral targeted agents across reimbursement pathways, concentrating manufacturing investment in FDA-certified sites while pushing price-sensitive volumes toward cytarabine generics sourced from concentrated European API suppliers.
Pricing Analysis
Input-cost pass-through from lentiviral vector manufacturing and apheresis collection runs through CAR-T list prices, while BTK inhibitors compete on annual therapy cost against chemotherapy backbones. Price differentiation centers on progression-free survival data and companion diagnostic bundling. Pricing pressure stems from Medicare Advantage prior authorization automation and indication expansion into earlier treatment lines. Community oncology practices show highest price sensitivity due to buy-and-bill margin compression, whereas tertiary transplant centers prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Certification gating through FACT/JACIE accreditation and FDA BLA manufacturing inspections concentrates CAR-T production in the United States, Germany, and Switzerland. Lentiviral vector production and cryopreservation media supply draw from single-source contract development organizations. Supply chain risk centers on cross-border cold chain integrity for cryopreserved patient-specific products. Distribution runs through specialty pharmacy carve-outs with integrated hub services bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mantle Cell Lymphoma market compounds value through successive FDA breakthrough therapy designations, with each approval expanding addressable populations and compressing development timelines for follow-on mechanisms.
For Market Incumbents: Extend manufacturing capacity at FDA-certified sites to capture CAR-T demand expansion, while deepening companion diagnostic co-development partnerships to lock in biomarker-defined patient stratification. Threats from next-generation reversible BTK inhibitors and bispecific antibody competition require pipeline prioritization decisions that preserve hematology commercial infrastructure leverage. For New Entrants and Emerging Players: Bispecific antibody constructs with outpatient administration profiles offer the most penetrable wedge against incumbent CAR-T manufacturing constraints. White-space targets include community oncology networks excluded from cellular therapy referral and emerging markets where cytarabine substitution creates access gaps. Go-to-market positioning should emphasize ambulatory monitoring protocols and cost-competitive manufacturing models. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing workforce scarcity constrains batch release velocity and site expansion. Long-term viability favors developers with integrated diagnostics-to-therapy platforms spanning multiple hematological malignancies. Acquisition targets should display novel mechanism assets in relapsed/refractory populations with biomarker-defined patient selection. Watch for inflection in real-world evidence integration enabling post-approval label expansion through retrospective efficacy analyses.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Breakthrough therapy designation compresses FDA review timelines for novel BTK inhibitors. |
| Manufacturing Scale-Up | Lentiviral vector capacity expansion at CDMOs reduces patient wait times for CAR-T administration. |
| Companion Diagnostic Co-Development | TP53 and SOX11 profiling expands addressable populations for precision-directed therapy sequences. |
| Regulatory Approval Pathway | NMPA priority review accelerates commercial entry for imported BCL-2 antagonists in China. |
| Pipeline Diversification | Next-generation sequencing platforms enable earlier intervention and treatment de-escalation decisions. |
Study Parameters
Bottom-up treatment modality modeling reconciled against top-down regulatory pathway tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers were cross-validated against secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Triangulation between prescriber preference data and manufacturing capacity disclosures ensures segmentation integrity.
Input-output matrix framing connects patient population incidence to therapy penetration rates across first-line, relapsed, and refractory settings. Segmentation dimensions span treatment modality, end-user setting, biomarker-defined patient subset, and regional regulatory cluster. CAGRs were derived from therapy adoption curves and pricing trajectory analysis across the projection horizon. Forecast inputs incorporate manufacturing capacity buildout timelines and companion diagnostic co-development milestones.
The model holds under stable FDA accelerated approval pathway conditions and consistent payer evidence generation timelines; deviation in breakthrough therapy designation criteria or international cold chain regulations would shift volume and value outputs. Forecasts reflect documented assumptions regarding biomarker testing penetration and transplant eligibility rates. A model refresh is warranted upon material change in CAR-T manufacturing workforce availability or NMPA regulatory lag compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Impetigo Therapeutic Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Angioimmunoblastic T-Cell Lymphoma (AILT) Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Global Thyroid Disorder Market
Specialty Medicine
Folliculotropic Mycosis Fungoides Treatment Market
Specialty Medicine
Global Urea Cycle Disorder Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market