
 Liver Cancer Drug Market | 2026-2036
Liver Cancer Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Cancer Drug Market Analytics
Biologics manufacturing in the United States is restructuring its oncology supply base as multi-product facilities convert to antibody-drug conjugate and immune checkpoint inhibitor production. Bristol-Myers Squibb Company anchors its position through deep investment in PD-1/PD-L1 combination trials for hepatocellular carcinoma. Bayer leverages its radiotherapy platform to sustain geographic reach across European and Asian markets. Merck & Co. differentiates through broad clinical trial networks that span adjuvant and metastatic settings.
Liver cancer drugs comprise systemic therapeutic agents designed to inhibit tumor progression, induce apoptosis, or modulate immune responses against malignant hepatocytes, typically formulated as monoclonal antibodies, small molecule kinase inhibitors, or cytotoxic compounds administered under strict dosing protocols. These agents serve to extend survival in hepatocellular carcinoma and cholangiocarcinoma patients while supporting palliative quality-of-life objectives. Immunotherapy commands the largest revenue pool as checkpoint inhibitors displace first-line chemotherapy across major treatment guidelines, though targeted therapy retains substantial share in biomarker-selected populations with actionable mutations. Intravenous delivery dominates hospital-based administration, while oral formulations are gaining traction in homecare settings where patient convenience and cost containment converge.
FDA breakthrough therapy designation and EMA priority medicines pathways compress regulatory review timelines, compelling sponsors to generate real-world evidence earlier in the product lifecycle. The European Medicines Agency and national health technology assessment bodies in Germany and France increasingly predicate reimbursement on comparative effectiveness against existing standards of care. Stakeholders must monitor evolving biomarker definitions and companion diagnostic requirements that determine label expansions and payer access decisions.
Market Dynamics
Checkpoint inhibitor immunotherapy is absorbing first-line hepatocellular carcinoma treatment protocols, compressing chemotherapy utilization and forcing restructuring of clinical trial endpoints across oncology departments.
Growth Catalysts
- FDA Accelerated Approval Pathway:Breakthrough therapy designation compresses development timelines from Phase I to commercial launch, rewarding sponsors who generate early survival data in biomarker-enriched populations.
- Companion Diagnostic Expansion:PD-L1 expression testing and ctDNA liquid biopsy integration enables patient stratification, expanding addressable populations for precision immunotherapy combinations.
- Medicare Reimbursement Alignment:United States oncology payment models now cover hospital-administered biologics under prospective payment systems, reducing access friction for tertiary cancer centers.
Market Restraints
- Biologics Manufacturing Concentration:Multi-product antibody facilities in the United States face capacity constraints as sponsors convert lines to antibody-drug conjugate production, creating supply bottlenecks for late-stage candidates.
- EMA Comparative Effectiveness Requirements:German and French health technology assessment bodies now mandate head-to-head survival data against existing standards, extending reimbursement negotiation timelines.
- High Development Failure Rates:Hepatocellular carcinoma's molecular heterogeneity produces elevated Phase III attrition, particularly for single-agent targeted therapies lacking biomarker selection criteria.
Strategic Opportunities
- Adjuvant Therapy Expansion:Post-surgical recurrence prevention represents underpenetrated clinical space, with trials exploring checkpoint inhibitor duration optimization in resected patient populations.
- Radioembolization Combination Protocols:Yttrium-90 microsphere integration with systemic therapy creates synergistic local control, expanding interventional oncology service lines in European and Asian markets.
- Homecare Oral Formulations:Small-molecule kinase inhibitors with improved hepatotoxicity profiles enable outpatient administration, reducing hospital infusion center dependency and total cost of care.
Industry Challenges
- Biomarker Assay Standardization:Discordant PD-L1 scoring algorithms across diagnostic platforms create enrollment variability in international trials, complicating regulatory submissions to multiple agencies.
- Immunotherapy Resistance Mechanisms:Secondary T-cell exhaustion and antigen loss variants require adaptive trial designs, stretching translational medicine capabilities and biomarker discovery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Cancer Drug Market |
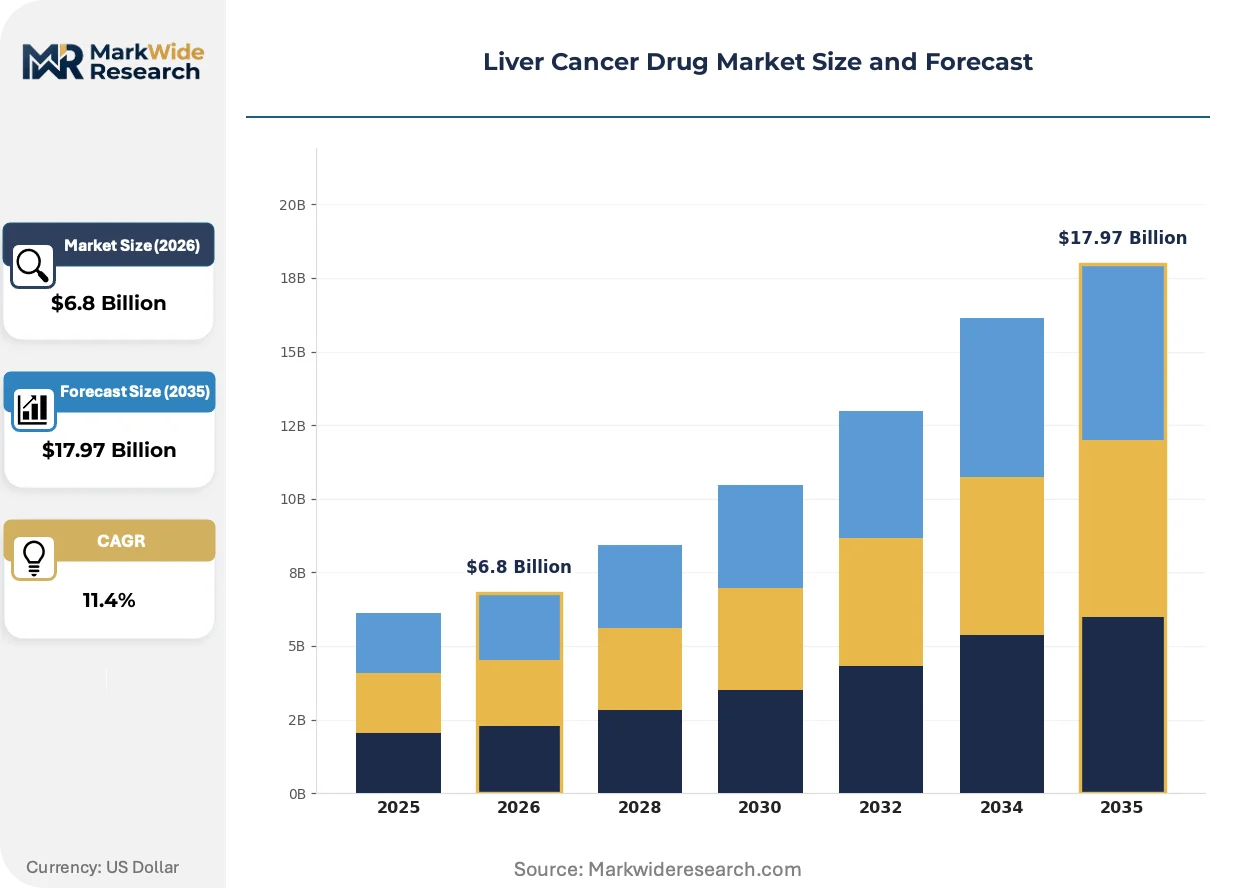
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunotherapy, Chemotherapy, Targeted Therapy, Hormonal Therapy Delivery Mode: Oral, Intravenous, Subcutaneous, Intra-arterial End User: Hospitals, Specialty Clinics, Homecare Settings, Research Institutions Application: Treatment, Palliative Care, Clinical Trials, Diagnostic Support |
| Companies Covered | Eisai, Bayer, Bristol-Myers Squibb Company, Pfizer, Exelixis, F. Hoffmann-La Roche, Merck & Co., Johnson & Johnson, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Cancer Drug Market Evolving Landscape
Antibody-drug conjugate engineering and bispecific antibody platforms are redefining hepatocellular carcinoma therapeutic paradigms, creating new competitive entry points beyond established checkpoint inhibitor franchises.
Bispecific T-cell engagers targeting GPC3 and AFP are absorbing preclinical investment from large-cap sponsors, with early-phase trials evaluating safety in cirrhotic patient populations. Hepatology-oncology hybrid clinics at tertiary centers in the United States and Germany are adopting these constructs for biomarker-selected cohorts. This modality is absorbing development resources previously allocated to single-target monoclonal antibodies, compressing traditional antibody timelines.
EMA's priority medicines scheme now mandates real-world evidence generation alongside randomized trials, compelling sponsors to establish early access programs in France and Italy. This policy shift forces parallel regulatory strategies rather than sequential geographic rollouts. Oncology sponsors are responding by embedding patient registries into Phase II protocols, particularly for combination therapies seeking label expansion.
Hospital procurement committees are consolidating formulary decisions across integrated delivery networks, replacing individual physician prescribing autonomy with value-assessment frameworks. This concentration shifts negotiating leverage toward pharmacy benefit managers and group purchasing organizations in the United States. The phenomenon is most visible in Medicare Advantage–dominated regions where total cost of care contracts incentivize therapy sequencing optimization.
Liver Cancer Drug Market Segmentation
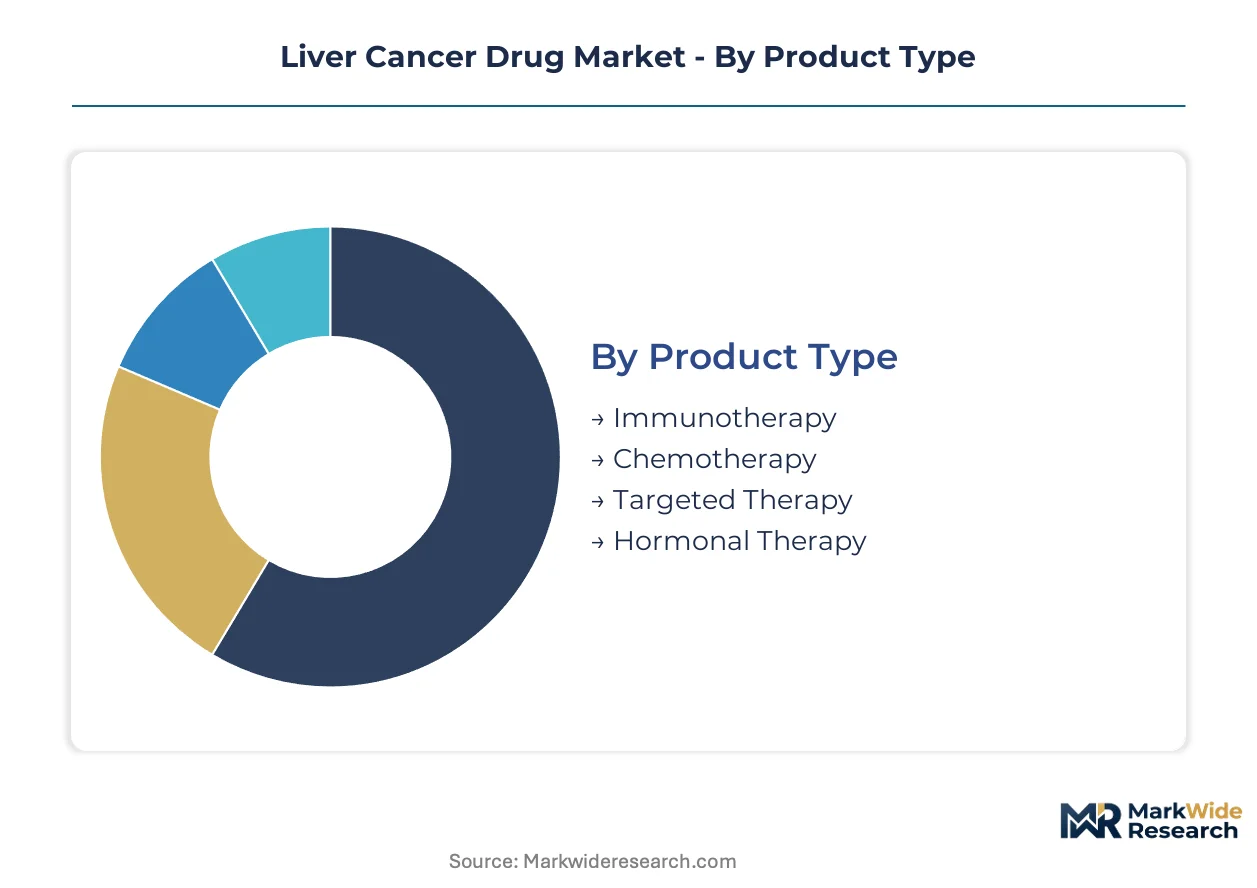
Hepatocellular carcinoma treatment protocols fragment across four distinct product categories, each commanding separate manufacturing infrastructure and reimbursement pathways. Delivery mode selection determines site-of-care economics, while end-user concentration shapes distribution strategy and patient access architecture.
Product Type:
Volume concentration sits with immunotherapy, while premium pricing attaches to targeted therapy combinations requiring companion diagnostic selection.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways dominate first-line hepatocellular carcinoma protocols. United States tertiary cancer centers absorb the majority of infusion volume as Medicare prospective payment systems reduce access friction for hospital-administered biologics.
- Targeted Therapy:Small-molecule kinase inhibitors inhibit VEGF and multikinase signaling in biomarker-selected populations. Demand concentrates in European markets where EMA priority medicines pathways mandate real-world evidence generation alongside randomized trials.
- Chemotherapy:Cytotoxic agents retain niche utilization in combination regimens for patients ineligible for immunotherapy.
- Hormonal Therapy:Androgen receptor modulators and related agents serve limited indications in specific hepatocellular carcinoma subtypes.
Mature deployment sits with chemotherapy. Newer deployment is concentrated in immunotherapy.
Delivery Mode:
Cost tier separation runs from hospital-based infusion to home-administered oral agents, with reimbursement complexity increasing at the premium end.
- Intravenous:Hospital infusion centers administer monoclonal antibodies and checkpoint inhibitors under strict dosing protocols requiring oncology nursing supervision.
- Oral:Small-molecule kinase inhibitors with improved hepatotoxicity profiles enable outpatient administration, reducing total cost of care in Medicare Advantage–dominated regions.
- Subcutaneous:Self-administered formulations are gaining traction in homecare settings where patient convenience and cost containment converge.
- Intra-arterial:Regional chemotherapy delivery via hepatic arterial infusion serves selected patients at specialized interventional oncology centers.
Established utilization centers on intravenous delivery. Expanding utilization is concentrated in oral formulations.
End User:
Customer type fragmentation reflects the divergence between acute care reimbursement and value-based contracting in outpatient settings.
- Hospitals:Tertiary oncology departments anchor hepatocellular carcinoma treatment volume, with integrated delivery networks consolidating formulary decisions across multiple sites.
- Homecare Settings:Oral therapy administration and patient monitoring services are expanding as pharmacy benefit managers negotiate total cost of care contracts.
- Specialty Clinics:Hepatology-oncology hybrid clinics in Germany and the United States adopt bispecific constructs for biomarker-selected cohorts.
- Research Institutions:Academic medical centers host Phase I/II trials for antibody-drug conjugates and radiotherapy combination protocols.
Volume concentration sits with hospitals. Fastest expansion is concentrated in homecare settings.
Application:
Margin structure varies sharply between curative-intent treatment and supportive care, with clinical trials representing a distinct revenue architecture.
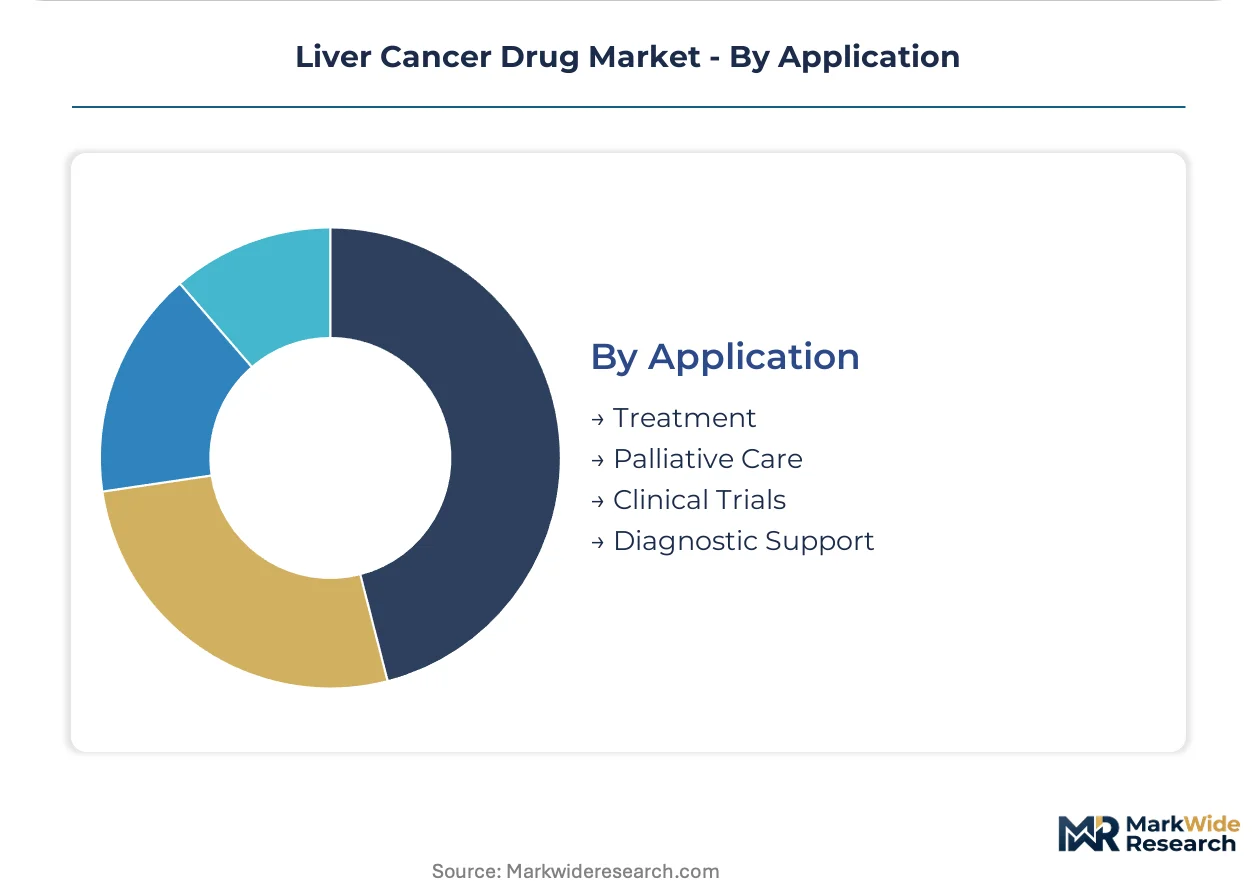
- Treatment:Curative and life-extending therapy protocols generate the majority of pharmaceutical revenue across all product categories.
- Clinical Trials:Sponsors embed patient registries into Phase II protocols, particularly for combination therapies seeking label expansion in adjuvant settings.
- Palliative Care:Symptom management and quality-of-life objectives support distinct prescribing patterns with different efficacy endpoints.
- Diagnostic Support:Companion diagnostic integration enables patient stratification for precision immunotherapy combinations.
Revenue concentration sits with treatment applications. Emerging deployment is concentrated in clinical trials infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient sourcing for oncology biologics concentrates in the United States, Germany, Japan, and Switzerland, with clinical trial density and reimbursement infrastructure determining commercial uptake velocity.
United States
Medicare prospective payment systems and specialized cancer center density absorb the majority of new hepatocellular carcinoma drug utilization. FDA breakthrough therapy designation compresses development timelines, rewarding sponsors generating early survival data. The MD Anderson Cancer Center in Houston and Memorial Sloan Kettering in New York anchor Phase III trial recruitment for checkpoint inhibitor combinations.
Germany
EMA priority medicines pathways and Federal Joint Committee health technology assessments mandate comparative effectiveness data against existing standards. Hospital procurement committees across integrated delivery networks consolidate formulary decisions. Heidelberg and Munich tertiary centers adopt bispecific constructs for biomarker-selected cohorts under early access programs.
Japan
PMDA sakigake designation accelerates regulatory review for hepatocellular carcinoma therapies addressing unmet needs in cirrhotic populations. National health insurance reimbursement negotiations hinge on cost-effectiveness thresholds. Tokyo and Osaka academic medical centers host Phase I/II trials for antibody-drug conjugates targeting GPC3.
Switzerland
Swissmedic expedited review pathways and proximity to European regulatory harmonization attract clinical trial sponsorship. Basel and Zurich host contract manufacturing organizations supplying antibody-drug conjugate payloads to global sponsors. The country's pricing and reimbursement authority negotiates outcomes-based agreements for novel immunotherapy combinations.
United Kingdom
NICE technology appraisals and Cancer Drugs Fund coverage decisions determine National Health Service access to hepatocellular carcinoma therapies. The NHS England specialized commissioning framework concentrates treatment at designated liver cancer centers. London and Manchester academic hospitals embed patient registries into Phase II protocols for adjuvant checkpoint inhibitor trials.
Liver Cancer Drug Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bispecific platforms and radiotherapy combinations. The vendor base clusters around three archetypes: large-cap pharmaceutical conglomerates with checkpoint inhibitor franchises, mid-cap biotech specialists in kinase inhibition, and radiopharmaceutical platform holders. Consolidation pressure intensifies as hospital procurement committees demand value-assessment frameworks. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic licensing for EMA priority medicines pathways.
Among large-cap pharmaceutical developers, Bristol-Myers Squibb Company and Merck & Co. exemplify the checkpoint inhibitor archetype through deep investment in PD-1/PD-L1 combination trials. Bayer occupies a distinct position as a radiopharmaceutical platform holder leveraging its radiotherapy infrastructure across European and Asian markets. These three entities represent divergent strategic vectors: immunotherapy dominance, radioligand therapeutic integration, and broad clinical trial network deployment spanning adjuvant and metastatic settings.
| Leading Market Players |
|---|
| Eisai |
| Bayer |
| Bristol-Myers Squibb Company |
| Pfizer |
| Exelixis |
| F. Hoffmann-La Roche |
| Merck & Co. |
| Johnson & Johnson |
| AstraZeneca |
| Others |
Value Network & Pricing Analysis
EMA's priority medicines scheme and FDA's breakthrough therapy pathway now gate qualified supply access and premium-tier pricing power, as sponsors must embed real-world evidence generation into Phase II protocols to secure reimbursement in Germany and France while maintaining Medicare alignment in the United States.
Pricing Analysis
Warranty and service bundling separates hospital-administered biologics from unbundled oral formulations, with infusion center nursing supervision and adverse event monitoring included in checkpoint inhibitor pricing while homecare kinase inhibitors strip out these services. Three-tier pricing structure across premium immunotherapy combinations, standard single-agent targeted therapy, and economy chemotherapy tiers reflects companion diagnostic requirements and biomarker selection complexity. Price differentiation hinges on PD-L1 expression testing integration and clinical trial data maturity. Cost compression in the chemotherapy tier is intensifying because checkpoint inhibitors are displacing first-line cytotoxic protocols across NCCN guidelines. Medicare Advantage plans exhibit highest price sensitivity, while tertiary cancer centers with prospective payment system carve-outs show lowest sensitivity to per-dose pricing.
Supply Chain Analysis
Single-source vulnerability sits with multi-product antibody facilities in the United States as sponsors convert lines to antibody-drug conjugate production, creating capacity bottlenecks for late-stage checkpoint inhibitor candidates. Active pharmaceutical ingredient sourcing draws from Switzerland, Germany, and Japan for biologics manufacturing, while chemical synthesis of small-molecule kinase inhibitors rests on Indian and Chinese intermediate suppliers. Supply chain risk centers on EMA comparative effectiveness requirements extending reimbursement negotiation timelines and freezing inventory commitments. Distribution runs through integrated delivery network pharmacy benefit managers in the United States and hospital procurement committees across German Federal Joint Committee jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibody-drug conjugate manufacturing capacity constraints prop pricing power for sponsors with secured CMO slots, making supply scarcity the defining narrative for hepatocellular carcinoma therapeutic procurement.
For Market Incumbents: Cement dominance through captive biologics manufacturing capacity in Basel and Zurich contract manufacturing organizations, insulating against single-source vulnerability as multi-product facilities face conversion pressure to ADC production. Deepen backward integration into companion diagnostic co-development with PD-L1 assay platforms to lock formulary access across integrated delivery networks. Regulatory fragmentation across EMA and FDA biomarker definitions represents the core threat requiring parallel submission strategies.
For New Entrants and Emerging Players: Launch via hepatology-oncology hybrid clinic partnerships in Germany and the United States, bypassing consolidated hospital formulary committees through specialty channel access. Adjuvant therapy expansion in resected patient populations offers the most penetrable white space, with post-surgical checkpoint inhibitor duration protocols still undefined in major guidelines. Homecare oral formulation development with improved hepatotoxicity profiles enables direct-to-patient distribution outside infusion center gatekeepers.
For Investors and Strategic Acquirers: FDA breakthrough therapy designation conversion to full approval is the leading indicator that manufacturing scale-up investments will generate sustainable returns rather than stranded capacity. Radiopharmaceutical platform holders with Yttrium-90 microsphere infrastructure offer the strongest five-to-ten year viability given radioembolization combination protocol adoption in European and Asian markets. Watch for PMDA sakigake designation announcements as the inflection signal for cirrhotic population unmet need validation.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase III checkpoint inhibitor combinations at MD Anderson and Memorial Sloan Kettering compress regulatory timelines. |
| Manufacturing Scale-Up | Antibody-drug conjugate line conversion in United States multi-product facilities alleviates supply bottlenecks for late-stage candidates. |
| Regulatory Approval Pathway | EMA priority medicines scheme mandates real-world evidence generation alongside randomized trials in France and Italy. |
| Licensing Agreement | Companion diagnostic co-development partnerships secure PD-L1 assay integration and formulary access across German hospital networks. |
| Pipeline Diversification | Bispecific T-cell engager platforms targeting GPC3 and AFP absorb preclinical investment from large-cap sponsors. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, combined with primary interviews spanning drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Bottom-up and top-down triangulation validated patient population estimates against Medicare reimbursement data and German Federal Joint Committee health technology assessments.
Bottom-up modeling anchored volume projections across immunotherapy, targeted therapy, chemotherapy, and hormonal therapy segments, while top-down cross-checks applied epidemiological incidence rates to treatment-eligible populations over the projection horizon. CAGRs were derived from treatment protocol displacement curves and biomarker-enriched enrollment trajectories. Dosage form, administration route, and regional regulatory cluster dimensions shaped the analytical framework.
The model assumes a particular technology adoption path; alternative pathways for bispecific antibody platforms would alter the outlook if T-cell engager safety profiles in cirrhotic populations diverge from checkpoint inhibitor standards. Forecasts reflect assumptions about FDA breakthrough therapy conversion rates and EMA comparative effectiveness negotiation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Budesonide Market
Pharmaceuticals
Critical Care Drugs Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Differentiated Thyroid Cancer Therapeutics Market
Pharmaceuticals
Large Molecule Contract Development and Manufacturing Organization Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Complex Injectable Market
Pharmaceuticals
Inhalation and Nasal Spray Generic Drugs Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
South Korea Human Papillomavirus Vaccine Market
Pharmaceuticals
Europe Contraceptives Market