
 Malabsorption Syndrome Market | 2026-2036
Malabsorption Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Malabsorption Syndrome Market Outlook
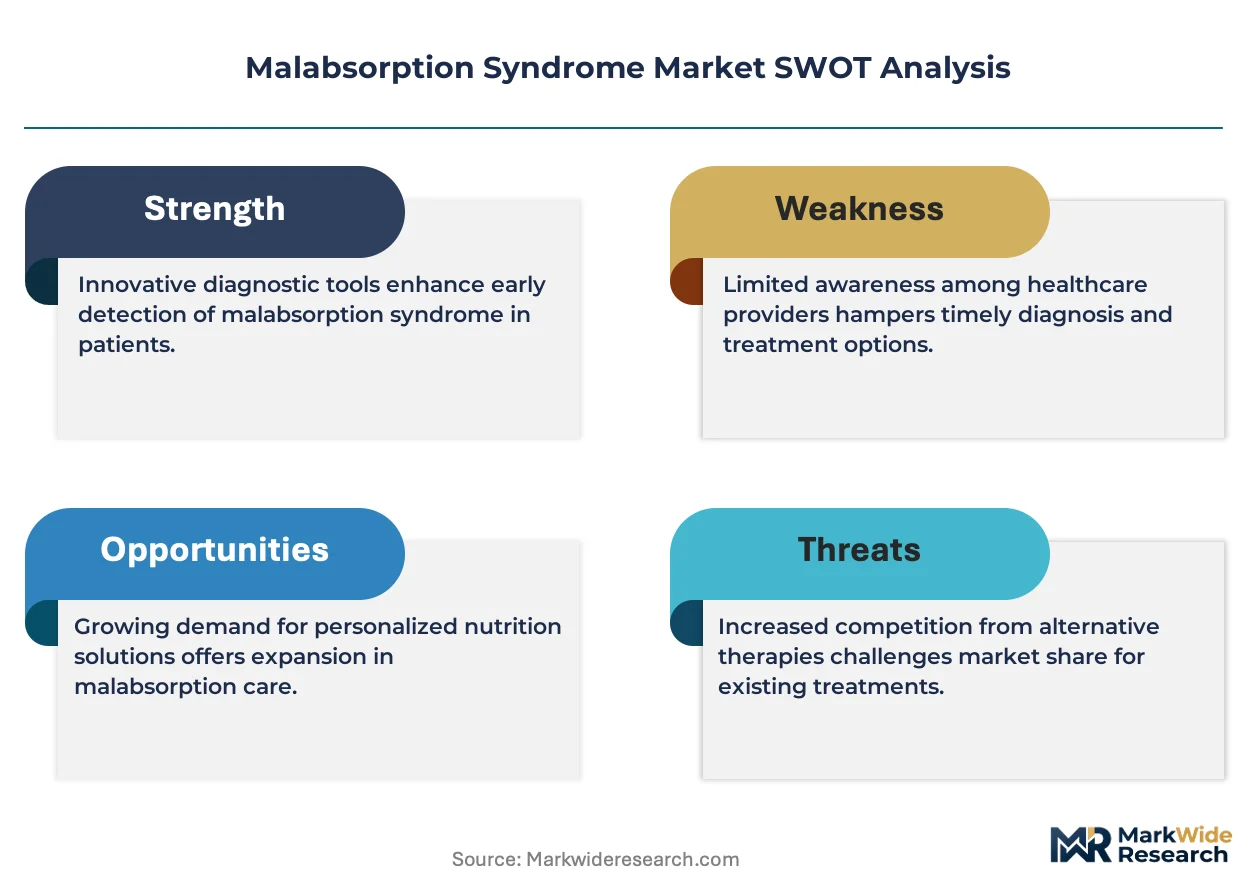
Hospital pharmacy committees is pivoting toward centralized formulary control for malabsorption therapies, reducing vendor fragmentation across integrated delivery networks. AbbVie Inc. anchors its position through immunology-aligned GI portfolios, while Novartis AG leverages rare disease infrastructure to sustain orphan drug access. Pfizer Inc. competes on manufacturing scale for broad-spectrum enzyme supplements.
Malabsorption syndrome encompasses disorders impairing nutrient uptake across the intestinal mucosa, requiring pancreatic enzyme replacement exceeding lipase doses of 25,000 units per meal for steatorrhea management. Digestive Enzymes dominate product type revenue due to chronic dependence and dose escalation protocols, whereas Nutritional Supplements capture expanding homecare margins as enteral feeding shifts beyond acute settings. Probiotics occupy an emerging adjacency with limited payer coverage but growing clinician trial interest.
FDA orphan drug designations and EMA's pediatric investigation plans shape development priorities for enzyme therapies, while HIPAA compliance requirements constrain direct-to-patient digital engagement channels. The EU MDR recertification timeline pressures smaller device-linked delivery platforms. Stakeholders must monitor payer evidence thresholds for nutritional support versus pharmaceutical intervention reclassification.
Market Dynamics
Centralized hospital formulary control is compressing vendor access and forcing enzyme manufacturers to consolidate their contracting strategies around integrated delivery networks. This procurement concentration is the dominant structural force reshaping competitive access in malabsorption therapeutics.
Growth Catalysts
- FDA Orphan Drug Incentives:The accelerated approval pathway and tax credits for rare disease development compress clinical trial timelines for novel enzyme formulations. Developers prioritize pancreatic insufficiency indications to capture these benefits.
- Homecare Enteral Feeding Migration:Post-acute settings are absorbing nutritional management previously confined to hospitals. Durable medical equipment suppliers are expanding service footprints to capture recurring revenue streams.
- Specialty Gastroenterology Networks:United States-based physician groups are standardizing steatorrhea protocols across multi-state practices. This protocol uniformity drives formulary alignment and brand consolidation.
Market Restraints
- Porcine-Derived Enzyme Supply Concentration:Lipase extraction depends on pancreatic tissue from concentrated slaughterhouse geographies. Supply interruptions in key sourcing regions create dose availability volatility.
- EU MDR Recertification Burden:Device-linked delivery platforms face extended conformity assessment timelines. Smaller manufacturers lack capital reserves to sustain dual regulatory compliance.
- Microbiome Therapeutics Substitution Threat:Investigational bacterial consortia for intestinal barrier restoration could displace chronic enzyme dependence. Clinical trial readouts will determine reimbursement positioning.
Strategic Opportunities
- Pediatric Investigation Plans:EMA mandates for juvenile study data create first-mover advantages for sponsors with established pediatric enzyme pharmacokinetics. Early completion locks in extended market exclusivity.
- Direct-to-Patient Digital Channels:HIPAA-compliant telehealth platforms enable remote dose titration and adherence monitoring. Specialty pharmacies are piloting integrated digital-physical service models.
- Synthetic Biology Enzyme Production:Cell-culture-derived lipase eliminates animal sourcing constraints. Biotechnology platforms are converging with pharmaceutical manufacturing to enable recombinant enzyme supply.
Industry Challenges
- Bioequivalence Demonstration Complexity:FDA requires rigorous pharmacokinetic matching for generic enzyme approvals. Analytical method standardization across reference products remains unresolved.
- Integrated Delivery Network Contracting Expertise:Manufacturers lack personnel experienced in value-based negotiations with consolidated hospital systems. Talent acquisition for formulary access roles lags market need.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malabsorption Syndrome Market |
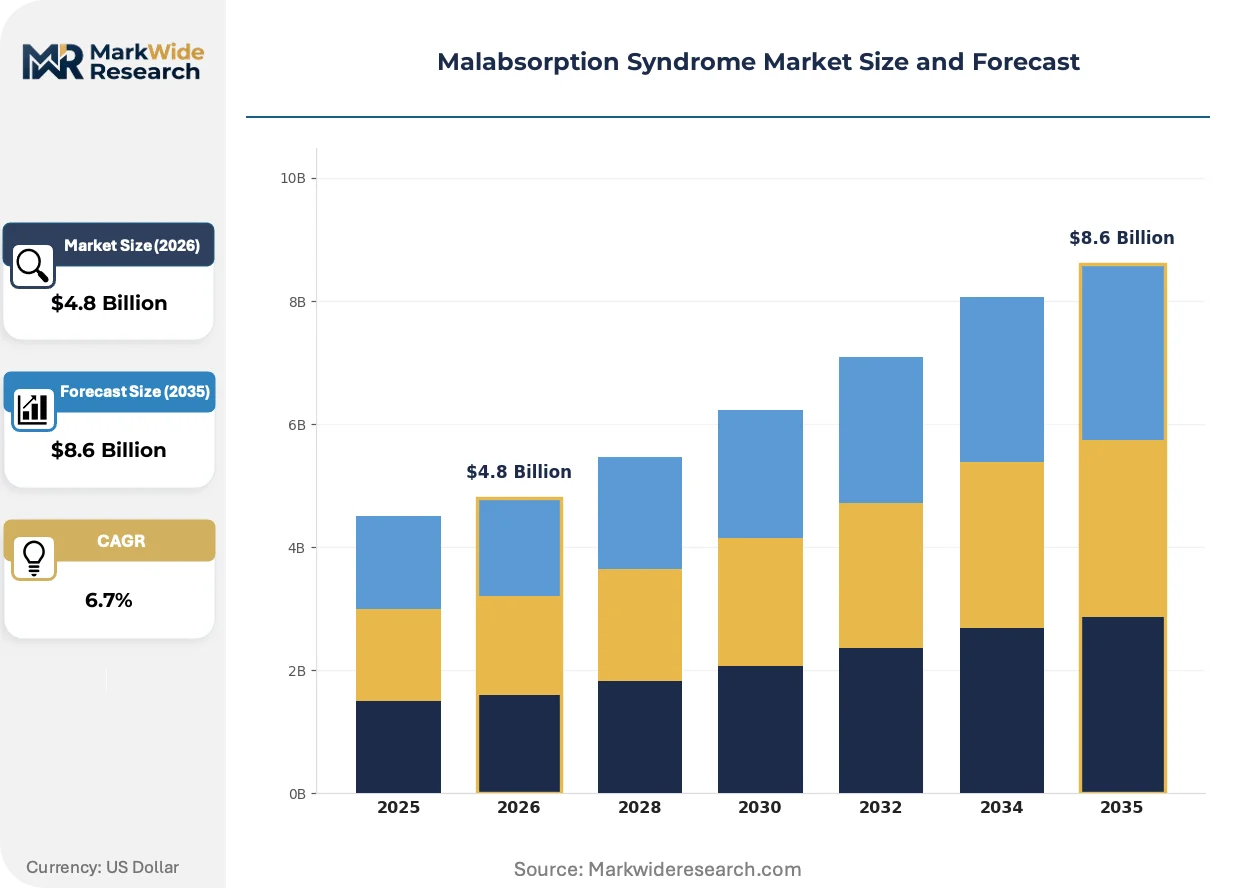
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digestive Enzymes, Nutritional Supplements, Probiotics, Antimicrobials Application: Chronic Diarrhea, Weight Loss, Vitamin Deficiency, Malnutrition End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Delivery Mode: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Tillotts Pharma AG, Novartis AG, AbbVie Inc., Pfizer Inc., Organon and Co., Baxter International Inc., Merck and Co. Inc., Sanofi SA, Cosmo Pharmaceuticals NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malabsorption Syndrome Market Strategic Shifts
Enzyme delivery technologies and regulatory data requirements are converging to reshape product development priorities. Manufacturers are repositioning around differentiated bioavailability claims and patient adherence metrics.
Microsphere-encapsulated pancreatic enzymes are modularizing dose administration protocols. Pediatric and geriatric patient segments are adopting these formats at accelerating rates. The technology is modularizing compliance measurement by enabling precise gastric emptying tracking and outcome verification.
EMA's pediatric investigation plan mandates are compressing development timelines for juvenile-specific formulations. Sponsors must submit juvenile study protocols earlier in the clinical lifecycle. European rare disease networks are responding by centralizing patient recruitment across national borders.
Hospital pharmacy committees are unbundling nutritional support from pharmaceutical procurement decisions. Integrated delivery networks are replacing fragmented vendor relationships with sole-source contracts for enzyme therapies. This concentration is most visible in United States-based specialty gastroenterology centers with standardized steatorrhea management protocols.
Malabsorption Syndrome Market Segmentation
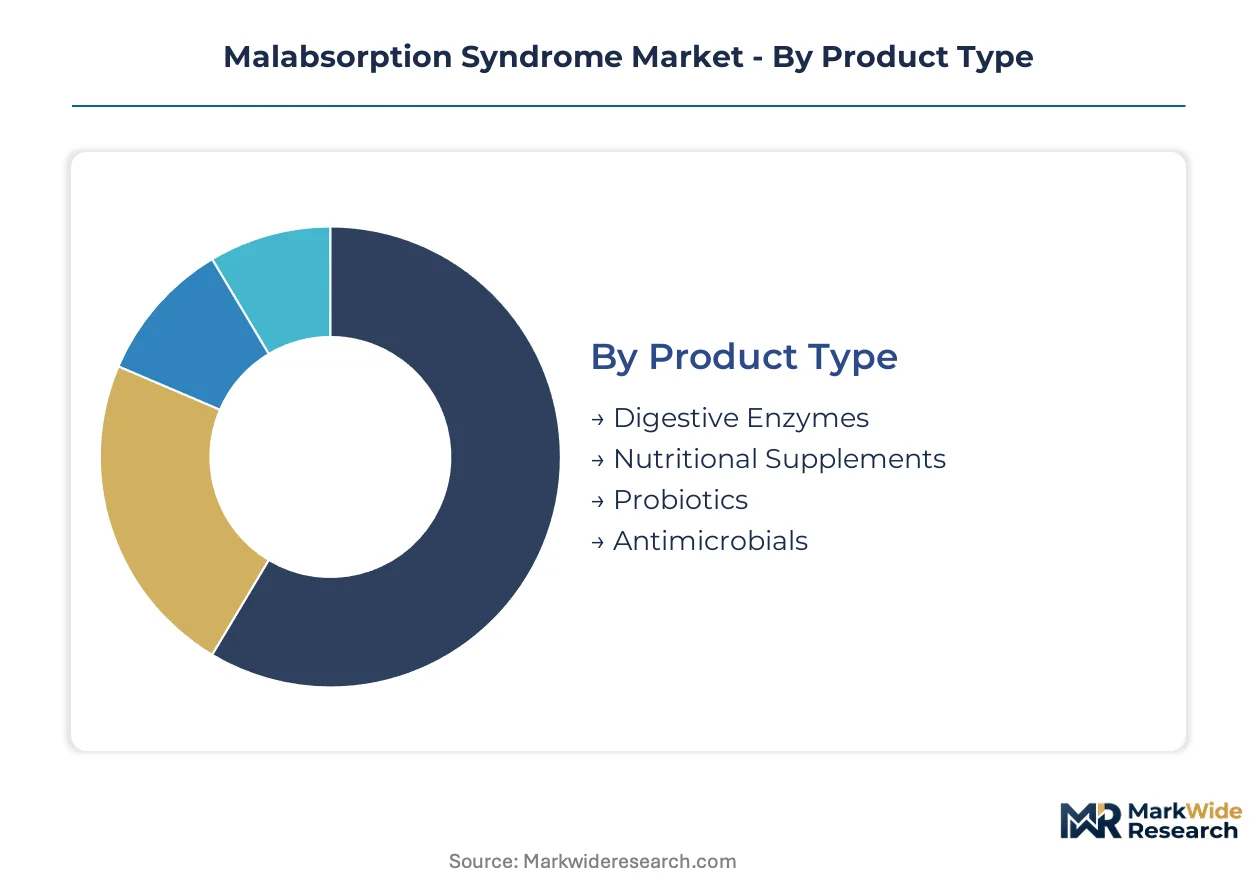
Malabsorption syndrome therapeutics fragment across multiple clinical and commercial dimensions. Each segmentation axis reveals distinct procurement patterns, reimbursement pathways, and patient adherence profiles that shape competitive positioning.
Product Type:
Replacement cycles for enzyme formulations are shortening as dose escalation protocols demand higher lipase units per meal, accelerating upgrade velocity across chronic patient populations.
- Digestive Enzymes:Pancreatic enzyme replacement therapies delivering lipase doses exceeding 25,000 units per meal dominate hospital procurement through centralized formulary committees. United States specialty gastroenterology networks drive protocol standardization and brand consolidation for steatorrhea management.
- Nutritional Supplements:Enteral feeding formulations and micronutrient replacements capture expanding homecare margins as post-acute settings absorb nutritional management previously confined to inpatient facilities. Durable medical equipment suppliers are building recurring revenue streams through service footprint expansion.
- Probiotics:Bacterial consortia for intestinal barrier modulation occupy an emerging adjacency with limited payer coverage but growing clinician trial interest.
- Antimicrobials:Targeted therapies for small intestinal bacterial overgrowth address secondary malabsorption etiologies with narrower prescriber bases.
Volume placements concentrate in Digestive Enzymes; the faster expansion belongs to Nutritional Supplements.
Application:
Cost tier stratification separates acute intervention from chronic maintenance, with vitamin deficiency protocols commanding premium reimbursement relative to symptomatic diarrhea management.
- Chronic Diarrhea:Steatorrhea and osmotic diarrhea indications require sustained enzyme therapy with dose titration protocols. FDA orphan drug incentives accelerate development timelines for novel formulations targeting refractory cases.
- Weight Loss:Unintentional wasting syndromes trigger aggressive nutritional intervention with enteral feeding escalation. Homecare migration is reshaping service delivery models for this indication.
- Vitamin Deficiency:Fat-soluble vitamin replacement (A, D, E, K) follows diagnostic confirmation with protocolized supplementation regimens.
- Malnutrition:Protein-energy undernutrition management spans acute hospital and rehabilitation settings with interdisciplinary care coordination.
Procedure volumes cluster in Chronic Diarrhea; Malnutrition applications are climbing the fastest as screening protocols expand.
End User:
Customer type determines contracting sophistication, with integrated delivery networks extracting steeper discounts than fragmented outpatient settings.
- Hospitals:Inpatient gastroenterology services and surgical units manage acute decompensation with pharmacy committee-controlled formularies. Centralized procurement is compressing vendor access and forcing manufacturer consolidation around sole-source contracts.
- Homecare Settings:Post-acute nutritional management and patient-administered enzyme therapy are expanding beyond hospital discharge. HIPAA-compliant telehealth platforms enable remote dose titration and adherence monitoring.
- Clinics:Outpatient gastroenterology practices handle stable patients with protocolized maintenance regimens.
- Rehabilitation Centers:Long-term care facilities manage malnutrition in populations with comorbid functional limitations.
Revenue concentration sits with Hospitals; Homecare Settings are gaining share fastest as enteral feeding migrates post-acute.
Delivery Mode:
Supply concentration in parenteral manufacturing capabilities constrains availability of intravenous formulations relative to oral alternatives.
- Oral:Microsphere-encapsulated enzymes and nutritional supplements dominate chronic administration with patient-administered dosing flexibility. Pediatric and geriatric segments are adopting these formats at accelerating rates.
- Intravenous:Parenteral nutrition bypasses compromised intestinal mucosa in severe malabsorption cases with compounding pharmacy preparation requirements.
- Subcutaneous:Limited enzyme delivery applications with emerging biotechnology platform exploration.
- Topical:Minimal relevance for systemic nutrient delivery; confined to dermatological manifestations of deficiency states.
Unit volumes aggregate in Oral delivery; Intravenous maintains premium positioning for acute intervention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Porcine pancreatic tissue sourcing concentrates in United States midwestern slaughterhouse corridors, anchoring enzyme supply geography for malabsorption therapeutics. Demand patterns diverge sharply across reimbursement environments and formulary control maturity.
United States
Specialty gastroenterology networks in Texas and Florida standardize steatorrhea protocols across multi-state practices, driving brand consolidation. FDA orphan drug incentives compress development timelines for novel enzyme formulations. Hospital pharmacy committees in the Cleveland Clinic and Mayo Clinic systems enforce sole-source contracting for pancreatic enzyme replacement.
Germany
EMA pediatric investigation plans mandate juvenile pharmacokinetic data submission earlier in development cycles. University hospital networks in Munich and Heidelberg centralize rare disease patient recruitment across national borders. The country's national pharmaceutical regulator enforces strict bioequivalence standards for generic enzyme approvals.
Japan
PMDA accelerated approval pathways for rare diseases attract multinational sponsors seeking Asian market entry. Tokyo and Osaka academic medical centers dominate pancreatic insufficiency diagnosis volume. METI funding for synthetic biology platforms supports recombinant lipase research initiatives.
India
CDSCO streamlined orphan drug regulations reduce regulatory lag for enzyme therapy imports. Mumbai and Hyderabad specialty hospital chains expand gastroenterology service lines for malabsorption screening. The country's national pharmaceutical regulator harmonizes with ICH guidelines for multinational trial data acceptance.
Switzerland
Swissmedic pediatric use marketing authorizations extend exclusivity periods for juvenile formulations. Basel and Zurich rare disease networks coordinate cross-border patient access with French and German centers. The country's national pharmaceutical regulator maintains parallel EMA recognition procedures for accelerated market entry.
Malabsorption Syndrome Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue synthetic biology platforms and microbiome adjacencies. The vendor base consolidates around immunology-aligned portfolios and rare disease infrastructure. Three archetypes dominate: pharmaceutical conglomerates with manufacturing scale, specialty GI-focused divisions, and biotechnology platforms exploring recombinant enzyme production. Competitive moves concentrate on integrated delivery network contracting expertise and pediatric formulation exclusivity capture.
Within the pharmaceutical conglomerate tier, Novartis AG and AbbVie Inc. exemplify divergent strategic positioning. Novartis AG leverages established rare disease infrastructure to sustain orphan drug access pathways. AbbVie Inc. anchors its market presence through immunology-aligned gastrointestinal portfolios. Pfizer Inc. occupies a position emphasizing manufacturing scale for broad-spectrum enzyme supply. These three entities represent the dominant competitive anchors shaping procurement negotiations with consolidated hospital systems.
| Leading Market Players |
|---|
| Tillotts Pharma AG |
| Novartis AG |
| AbbVie Inc. |
| Pfizer Inc. |
| Organon and Co. |
| Baxter International Inc. |
| Merck and Co. Inc. |
| Sanofi SA |
| Cosmo Pharmaceuticals NV |
| Others |
Value Chain & Pricing Dynamics
Recombinant lipase production via cell-culture biotechnology is redrawing cost curves and supplier geography simultaneously, loosening the grip of midwestern United States slaughterhouse corridors on enzyme economics while compressing margins for incumbent porcine-derived manufacturers.
Pricing Analysis
Service-bundling separates premium enzyme tiers from commodity equivalents, with microsphere-encapsulated formulations commanding inclusion of adherence monitoring and remote dose titration while standard pancreatic enzyme replacements ship unbundled. Price differentiation rests on FDA orphan drug exclusivity status and pediatric formulation certification, with EMA pediatric investigation plan completion acting as a secondary premium driver. Pricing pressure intensifies in standard lipase tiers as integrated delivery networks consolidate formulary contracts around sole-source agreements. Hospital pharmacy committees exhibit lowest price sensitivity for juvenile-specific formulations; durable medical equipment suppliers in homecare settings demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with United States midwestern slaughterhouse geographies for porcine pancreatic tissue extraction, creating dose availability volatility when regional livestock processing disruptions occur. Raw material dependencies center on porcine pancreatic tissue, enteric coating polymers for microsphere encapsulation, and recombinant cell-culture media for synthetic biology platforms. Supply chain risk concentrates in tariff exposure for imported enzyme formulations from European manufacturing sites. Distribution runs through specialty pharmacy networks for patient-administered therapies and integrated delivery network central warehouses for hospital-based procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Malabsorption Syndrome Market operates as a cost-of-compliance arena where FDA orphan drug designation requirements and EMA pediatric investigation plan mandates erect formidable barriers to entry, rewarding sponsors with established rare disease infrastructure and locking out undercapitalized challengers.
For Market Incumbents: Deepen backward integration into recombinant enzyme production to neutralize porcine supply volatility and capture synthetic biology cost advantages. Fortify pediatric formulation exclusivity through accelerated EMA pediatric investigation plan completion, locking in extended market protection against microbiome therapeutic substitutes. Consolidate formulary access talent capable of negotiating value-based contracts with Cleveland Clinic and Mayo Clinic integrated delivery networks. For New Entrants and Emerging Players: HIPAA-compliant telehealth platforms offer the most penetrable vector for market entry, enabling remote dose titration and adherence monitoring without confronting entrenched hospital pharmacy committee relationships. Target homecare settings and durable medical equipment supplier partnerships where enteral feeding migration has fragmented incumbent control. Pursue synthetic biology enzyme production partnerships with METI-funded Japanese biotechnology platforms to bypass animal sourcing constraints entirely. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pharmaceutical conglomerates seeking rare disease infrastructure or immunology-aligned gastrointestinal portfolios. Five-to-ten year viability favors sponsors with completed pediatric pharmacokinetic studies and locked-in orphan drug exclusivity periods. Monitor clinical trial readouts for investigational bacterial consortia as the critical inflection signal determining whether microbiome therapeutics displace chronic enzyme dependence or reinforce incumbent positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Completion | EMA mandates lock in extended exclusivity for juvenile formulations ahead of competitors. |
| Synthetic Biology Platform Investment | Cell-culture-derived lipase eliminates porcine sourcing constraints and supply volatility. |
| Integrated Delivery Network Partnership | Sole-source contracts with Mayo Clinic and Cleveland Clinic systems secure formulary access. |
| HIPAA-Compliant Telehealth Development | Remote dose titration captures homecare migration beyond hospital discharge settings. |
| Orphan Drug Designation Pursuit | FDA accelerated approval pathways compress clinical timelines and capture tax credits. |
Study Parameters
FDA orphan drug designation databases, EMA pediatric investigation plan registries, and ClinicalTrials.gov enzyme therapy protocols formed the secondary backbone, cross-referenced with primary interviews involving drug development executives at pancreatic enzyme manufacturers, regulatory affairs leads navigating FDA accelerated approval pathways, formulary directors at integrated delivery networks, and hospital procurement managers overseeing centralized pharmacy committees. Bottom-up patient population estimates and top-down pharmaceutical revenue triangulation validated market sizing across the analysis window.
Historical trendline analysis of lipase unit pricing and enzyme replacement therapy prescription volumes established baseline growth patterns, with projection modeling incorporating segmentation across product type (digestive enzymes, nutritional supplements, probiotics), application (chronic diarrhea, weight loss, vitamin deficiency, malnutrition), end user (hospitals, homecare settings, clinics, rehabilitation centers), and delivery mode (oral, intravenous, subcutaneous, topical). CAGRs derived from weighted average of epidemiological prevalence trends, dose escalation protocol adoption curves, and formulary consolidation velocity.
The model holds under sustained orphan drug incentive structures and stable porcine tissue supply; deviation in synthetic biology platform commercialization timelines or microbiome therapeutic clinical success would shift volume and value trajectories substantially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Osteopontin Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Avascular Necrosis Market
Specialty Medicine
Bronchiectasis Market
Specialty Medicine
Animal Hormone Therapy Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Acrocallosal Syndrome Therapeutics Market
Specialty Medicine
Breakthrough Therapy Designation Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Chronic Urticaria Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Rumination Syndrome Market