
 Exanthema Market | 2026-2036
Exanthema Market Size, Share, and Industry Trends Forecast 2026-2036
Exanthema Market Foresight
Aftermarket service revenue from diagnostic platform maintenance and reagent supply contracts is reshaping how exanthema testing economics flow through healthcare systems. F. Hoffmann-La Roche Ltd. leverages its installed base of molecular diagnostics instruments to sustain recurring consumable revenue across European hospital networks. Sanofi anchors its position through integrated vaccine and therapeutic portfolios that address viral exanthema etiologies. Merck & Co. competes on R&D intensity in antiviral drug development for measles and rubella complications.
Exanthema denotes a widespread rash eruption on the skin, typically arising from infectious, immunologic, or pharmacologic triggers, with lesions ranging from maculopapular to vesicular morphology depending on underlying pathology; diagnostic confirmation often requires polymerase chain reaction testing or serological assays to distinguish between viral and non-viral origins. The therapy area dimension shows viral infection management commanding the dominant share due to persistent measles and enterovirus burdens, while bacterial infection segments face margin compression from generic antibiotic saturation. Age group segmentation reveals pediatrics generating the highest test volumes, though geriatrics presents superior per-patient revenue as atypical presentations demand comprehensive laboratory workups.
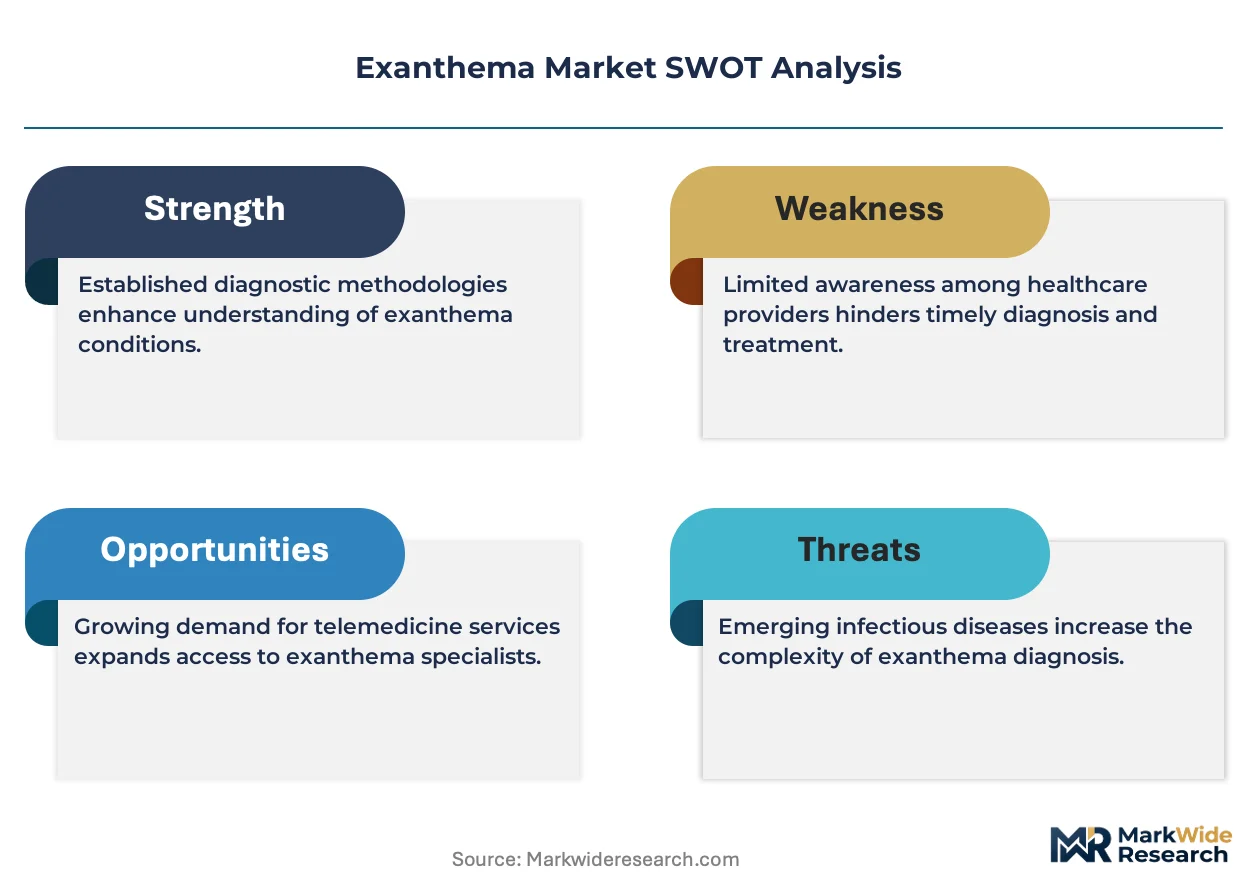
FDA oversight of in vitro diagnostic platforms and WHO prequalification standards for measles-rubella testing shape product development priorities and market access pathways for exanthema assay manufacturers. EMA's In Vitro Diagnostic Regulation intensifies clinical evidence requirements, favoring firms with robust post-market surveillance infrastructure over smaller competitors. Stakeholders must monitor how decentralized testing expansion and regulatory harmonization pressures will redistribute value between centralized laboratories and point-of-care settings.
Market Dynamics
Point-of-care molecular testing is compressing diagnostic timelines from centralized laboratory workflows to bedside decision-making, forcing equipment manufacturers to reconfigure platform economics around consumable recurring revenue rather than capital instrument sales.
Growth Catalysts
- IVDR Compliance Deadlines:EMA's In Vitro Diagnostic Regulation mandates enhanced clinical evidence for exanthema assays, accelerating consolidation toward manufacturers with robust post-market surveillance infrastructure.
- Pediatric Vaccination Gaps:Persistent measles outbreaks in under-immunized populations sustain demand for rapid diagnostic confirmation in hospital emergency departments and urgent care networks.
- Multiplex PCR Platforms:Laboratory instruments capable of simultaneous pathogen detection are expanding test menu breadth without proportional increases in technician labor or laboratory footprint.
Market Restraints
- Reagent Supply Concentration:Specialized polymerase and probe chemistries for viral exanthema detection concentrate among a limited supplier base in Germany and the United States, exposing diagnostic manufacturers to input volatility.
- Antibiotic Generic Saturation:Bacterial exanthema therapies face margin compression as standard-of-care antibiotics lose patent protection, reducing R&D investment in novel antibacterial agents for skin manifestations.
- Serological Cross-Reactivity:Antibody-based assays for enterovirus and parvovirus B19 demonstrate interpretive ambiguity, necessitating confirmatory molecular testing that extends diagnostic cost structures.
Strategic Opportunities
- Decentralized Testing Expansion:Pharmacies and retail clinics in Japan and Germany are deploying compact molecular platforms, capturing patient volumes that bypass traditional hospital laboratory channels.
- WHO Prequalification Pathway:Attainment of WHO performance standards for measles-rubella diagnostics unlocks procurement eligibility across Gavi-eligible country programs and multilateral health initiatives.
- Digital Pathology Integration:Convergence of whole-slide imaging with artificial intelligence-assisted lesion classification is enabling remote dermatologist consultation for atypical exanthema presentations.
Industry Challenges
- Specialized Dermatopathology Training:Interpretation of immunohistochemical staining patterns for drug-induced exanthema requires expertise that concentrates in academic medical centers, constraining diagnostic capacity expansion.
- Legacy LIS Integration:Hospital information systems in established healthcare networks operate on outdated data architectures that resist seamless incorporation of cloud-based molecular diagnostic result reporting.
- Reimbursement Code Fragmentation:Molecular testing for viral exanthema etiologies maps to multiple CPT code categories with variable coverage determination timelines across commercial and public payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exanthema Market |
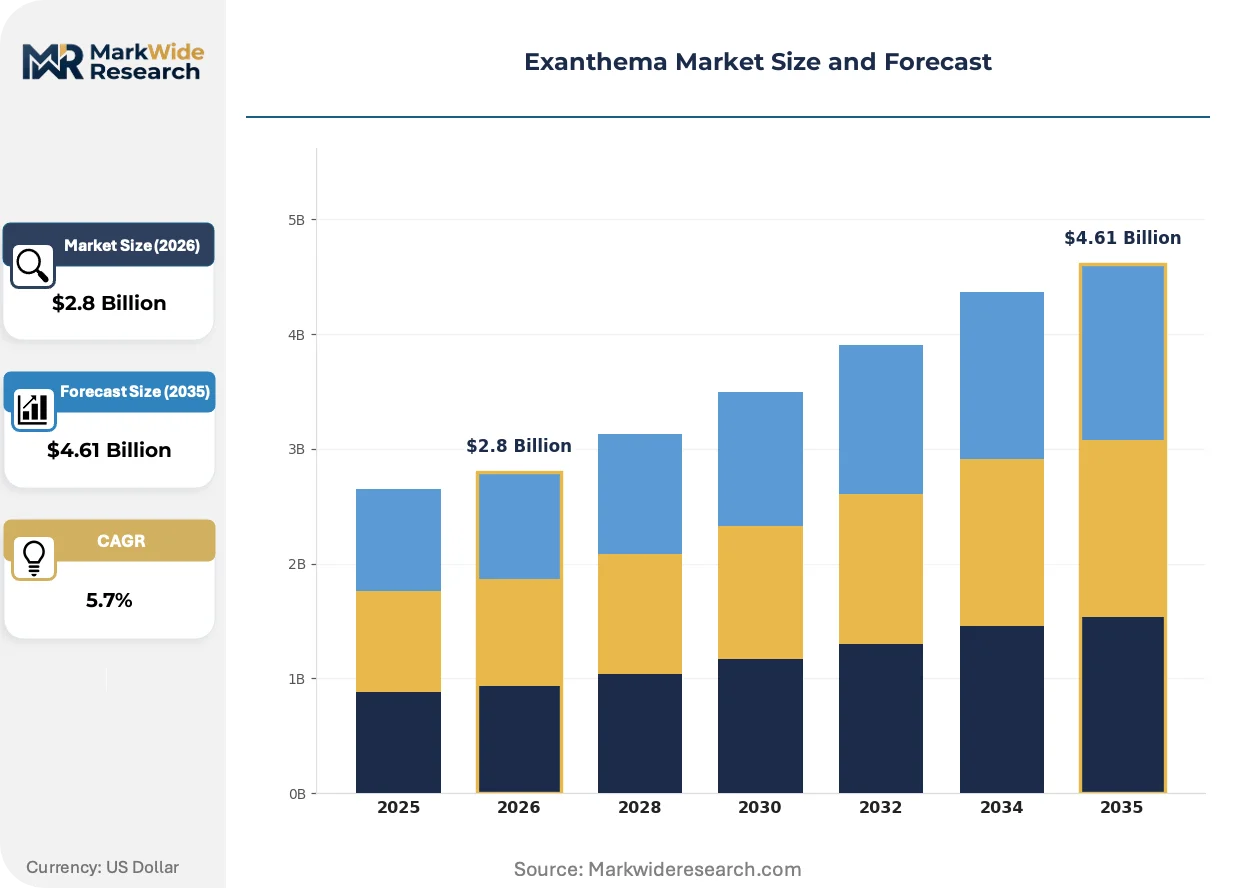
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Viral Infection, Bacterial Infection, Allergic Reaction, Drug Reaction Age Group: Pediatrics, Adolescents, Adults, Geriatrics Symptom Type: Fever, Rash, Itching, Pain Diagnosis Method: Clinical Examination, Laboratory Tests, Medical History, Imaging Studies |
| Companies Covered | F. Hoffmann-La Roche Ltd., Merck & Co., Sanofi, Pfizer, Johnson & Johnson, GlaxoSmithKline, Novartis, Bayer, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exanthema Market Shifts & Advancements
Artificial intelligence-assisted image recognition and cloud-connected diagnostic platforms are restructuring how dermatological assessments traverse clinical settings, compressing the interval between lesion presentation and etiological confirmation.
CRISPR-based diagnostic assays are digitizing exanthema pathogen detection through instrument-free nucleic acid amplification that operates at ambient temperature. Community health workers in resource-limited settings are piloting these platforms for field-deployable measles confirmation. The technology is digitizing the traditional laboratory value chain by eliminating cold-chain logistics and specialized technician requirements.
EMA's In Vitro Diagnostic Regulation intensifies clinical evidence requirements for class C and D devices, compelling assay manufacturers to generate prospective performance data across diverse epidemiological contexts. This regulatory burden disproportionately affects smaller diagnostic firms lacking established post-market surveillance infrastructure. European hospital networks are responding by consolidating procurement specifications around pre-qualified vendor lists with demonstrated IVDR technical documentation.
Hospital procurement departments are unbundling diagnostic service contracts into discrete reagent supply, platform maintenance, and interpretive consulting components. This disaggregation enables direct comparison of per-test economics across competing vendor proposals. The shift is most pronounced in United States integrated delivery networks where centralized supply chain functions exert pricing leverage over molecular diagnostic manufacturers.
Exanthema Market Segmentation
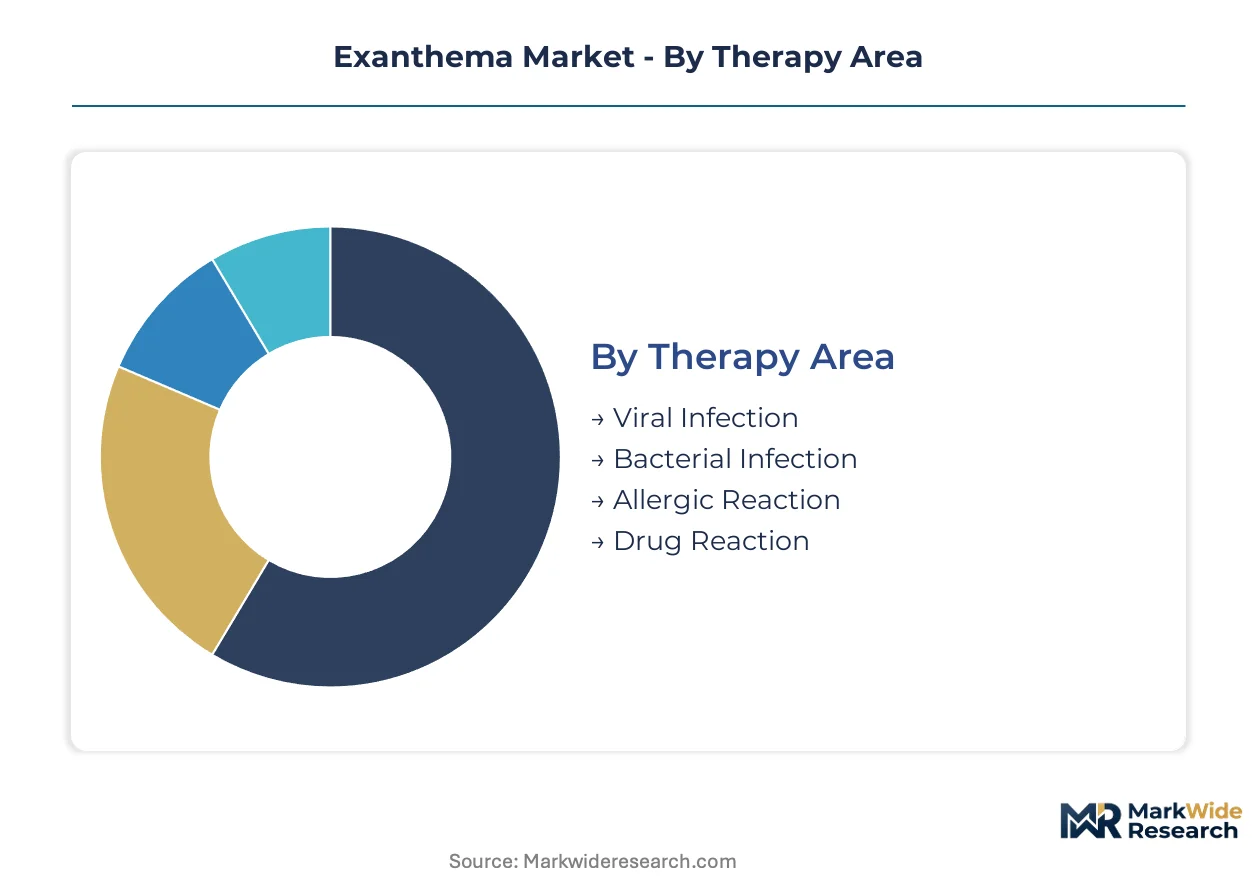
Segmentation in the exanthema market reveals how diagnostic economics and therapeutic priorities diverge across patient populations and clinical workflows. Understanding these partitions illuminates where test volumes concentrate versus where per-case revenue maximizes.
Therapy Area:
Cost tier stratification in exanthema management separates high-margin molecular diagnostics from commoditized pharmaceutical interventions.
- Viral Infection:Molecular PCR and serological assays dominate confirmation protocols for measles, enterovirus, and parvovirus B19 etiologies. Demand concentrates in United States hospital emergency departments and German dermatology clinics where rapid pathogen identification guides isolation protocols and contact tracing.
- Bacterial Infection:Standard-of-care antibiotics treat staphylococcal and streptococcal exanthemas with minimal diagnostic workup. Generic drug saturation has compressed margins, redirecting manufacturer R&D investment toward resistant strain identification rather than novel therapeutics.
- Allergic Reaction:Patch testing and IgE-mediated workups require specialized dermatopathology interpretation.
- Drug Reaction:Immunohistochemical staining patterns distinguish fixed drug eruptions from infectious mimics in academic medical center laboratories.
Viral Infection holds installed capacity. Drug Reaction is rotating up the share rankings.
Age Group:
Application intensity varies dramatically across life stages, with pediatric populations generating volume but geriatric cases commanding premium diagnostic workups.
- Pediatrics:Vaccination gap populations sustain high test volumes for measles and rubella confirmation in urgent care networks. Japanese municipal health centers and United States children's hospitals deploy rapid antigen platforms to manage outbreak containment protocols.
- Geriatrics:Atypical presentations and immunocompromised status necessitate comprehensive laboratory panels including molecular, serological, and histopathological evaluation. Per-patient revenue exceeds pediatric benchmarks threefold due to extended diagnostic pathways.
- Adolescents:Enterovirus and parvovirus B19 exposures peak in this demographic.
- Adults:Occupational and travel-related exposures drive diagnostic demand in workforce health settings.
Pediatrics holds installed capacity. Geriatrics is climbing the fastest.
Symptom Type:
Volume distribution across presenting complaints shapes point-of-care platform configuration and reagent stocking priorities.
- Rash:Morphological classification—maculopapular, vesicular, petechial—determines differential diagnosis breadth and required laboratory confirmation. German dermatology clinics and Japanese hospital outpatient departments prioritize whole-slide imaging integration for atypical lesion documentation.
- Fever:Febrile exanthemas trigger mandatory infectious disease workups per CDC and RKI surveillance protocols. Multiplex PCR platforms capable of simultaneous pathogen detection are expanding test menu breadth without proportional technician labor increases.
- Itching:Pruritic presentations often indicate allergic or drug-induced etiologies requiring distinct diagnostic pathways.
- Pain:Painful eruptions suggest bacterial superinfection or zosteriform patterns necessitating urgent intervention.
Rash holds installed capacity. Fever is gaining share fastest.
Diagnosis Method:
Customer type preferences—centralized laboratories versus point-of-care operators—are fragmenting procurement specifications across healthcare networks.
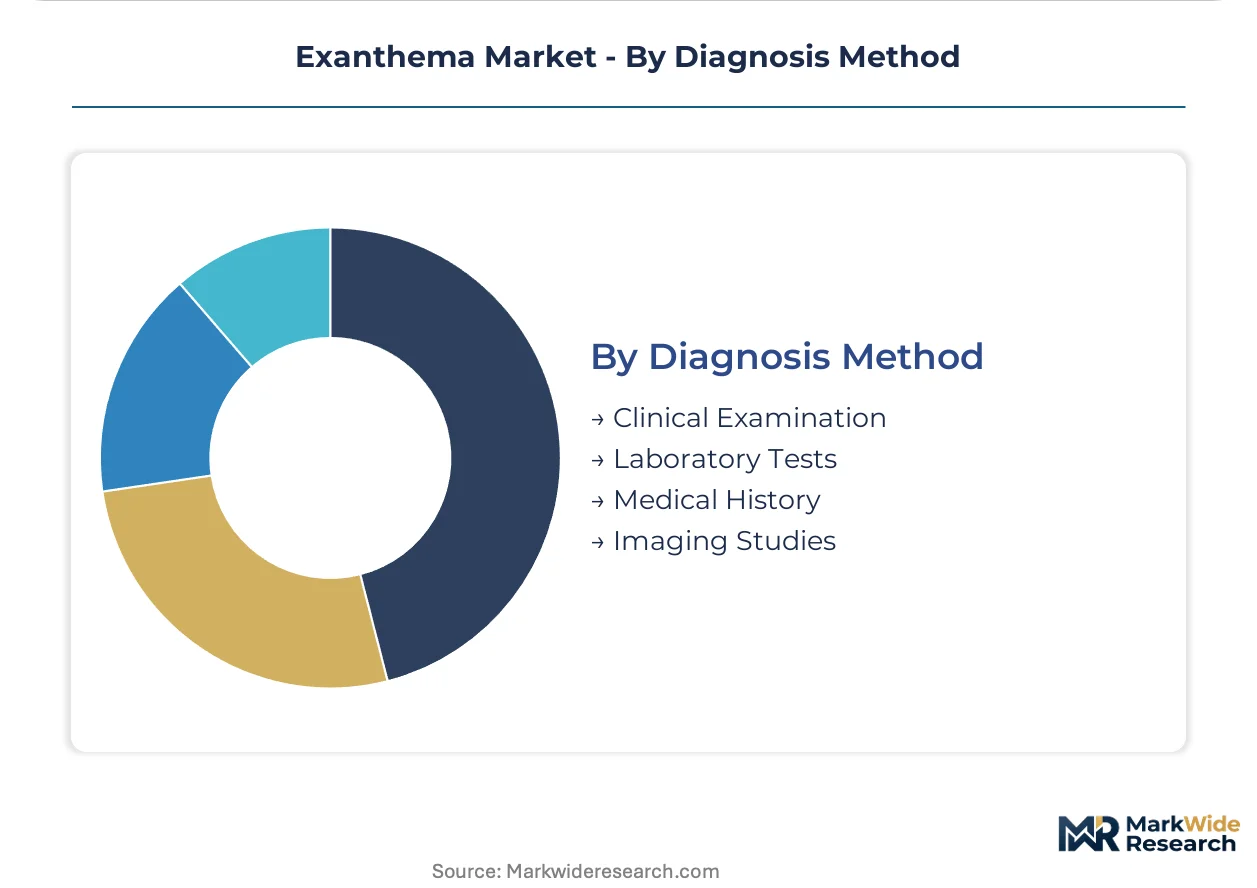
- Laboratory Tests:PCR, serology, and histopathology constitute the revenue core for diagnostic manufacturers. United States integrated delivery networks and European hospital systems are unbundling service contracts into discrete reagent supply, platform maintenance, and interpretive consulting components.
- Clinical Examination:Bedside assessment by dermatologists and emergency physicians remains the volume entry point for diagnostic cascades. Retail clinics in Japan and Germany are deploying compact molecular platforms that bypass traditional hospital laboratory channels.
- Medical History:Vaccination records and medication timelines guide initial differential formation.
- Imaging Studies:Dermatoscopy and reflectance confocal microscopy assist lesion characterization in specialized centers.
Laboratory Tests holds installed capacity. Clinical Examination is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic platform manufacturing concentrates in Germany, the United States, and Japan, where specialized reagent production and molecular instrument assembly sustain regional supply networks. Hospital procurement departments in these markets unbundle service contracts to extract pricing leverage from concentrated vendor bases.
United States
FDA oversight of in vitro diagnostic platforms shapes product development priorities for measles-rubella assay manufacturers. Integrated delivery networks in the Southeast and Pacific Northwest consolidate procurement specifications around pre-qualified vendor lists. Boston and San Francisco clinical research corridors generate prospective performance data for IVDR-equivalent submissions.
Germany
EMA's In Vitro Diagnostic Regulation mandates enhanced clinical evidence for class C and D exanthema devices, accelerating consolidation toward manufacturers with post-market surveillance infrastructure. The Rhine-Ruhr and Bavarian hospital networks deploy multiplex PCR platforms for simultaneous pathogen detection. Frankfurt and Munich dermatology clinics prioritize whole-slide imaging integration for atypical lesion documentation.
Japan
METI and PMDA standards govern compact molecular platform deployment in retail clinic settings. Municipal health centers in Kanto and Kansai regions sustain high test volumes for vaccination gap populations. Tokyo and Osaka hospital outpatient departments capture patient volumes through pharmacy-based diagnostic networks.
United Kingdom
UK Health Security Agency surveillance protocols mandate infectious disease workups for febrile exanthemas in emergency departments. London and Manchester academic medical centers concentrate immunohistochemical staining expertise for drug-induced rash interpretation. The Midlands hospital networks pilot cloud-connected diagnostic platforms for remote dermatologist consultation.
Switzerland
Swissmedic certification requirements align with IVDR technical documentation standards for cross-border European market access. Basel and Zurich pharmaceutical clusters anchor vaccine and therapeutic development for viral exanthema etiologies. The country's diagnostic manufacturers leverage proximity to German hospital networks for platform deployment.
Exanthema Market Competitive Landscape
Integrated pharmaceutical conglomerates and specialized diagnostic manufacturers split the market into distinct capability layers. The vendor base organizes around recurring consumable revenue models rather than capital instrument sales. Three archetypes dominate: molecular platform specialists with installed base leverage, vaccine-therapeutic integrators addressing viral etiologies, and antiviral R&D-intensive developers. Consolidation pressures favor backward integration into reagent supply chains and strategic partnerships for decentralized testing expansion.
Within the integrated pharmaceutical tier, F. Hoffmann-La Roche Ltd. and Sanofi occupy positions that exemplify divergent strategic anchors—Roche representing molecular diagnostics infrastructure leverage, Sanofi representing vaccine-therapeutic portfolio breadth. Merck & Co. sits within the R&D-intensive archetype focused on antiviral development. These three entities represent how competitive positioning in exanthema markets depends on upstream control over diagnostic consumables or downstream integration into therapeutic protocols.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Merck & Co. |
| Sanofi |
| Pfizer |
| Johnson & Johnson |
| GlaxoSmithKline |
| Novartis |
| Bayer |
| Abbott Laboratories |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and United States polymerase suppliers concentrates pricing power upstream while compressing margin buffers for diagnostic platform manufacturers serving hospital networks. This chokepoint simultaneously widens tier spreads between premium-certified assays and economy-grade alternatives while forcing procurement departments toward multi-year reagent supply contracts.
Pricing Analysis
EMA's In Vitro Diagnostic Regulation dictates the pricing tier structure across European hospital networks by imposing documentation costs that only premium manufacturers absorb. Three-tier pricing structure across premium, standard, and economy levels separates IVDR-certified assays from transitional products and non-compliant alternatives. Cost compression in the economy tier is intensifying because generic antibiotic saturation redirects hospital budgets toward molecular diagnostics. Pediatric urgent care networks exhibit highest price sensitivity; geriatric comprehensive panels command lowest sensitivity due to reimbursement adequacy.
Supply Chain Analysis
Specialized polymer chemistries feed from concentrated production in Germany, the United States, and Japan where reagent synthesis expertise anchors regional supply networks. Taq polymerase, fluorescent probes, and viral transport media constitute critical input dependencies. Single-source vulnerability in probe synthesis exposes manufacturers to allocation disruptions during respiratory virus season surges. Distribution runs through integrated delivery network central warehouses in the United States and European hospital consortium purchasing bodies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interpretive capacity for immunohistochemical staining patterns concentrates in academic medical centers, creating a bottleneck that constrains diagnostic throughput expansion and rewards firms controlling scarce dermatopathology expertise.
For Market Incumbents: Pre-empt CRISPR-based assay displacement by securing exclusive reagent supply agreements with German polymerase manufacturers before decentralized testing platforms scale. Backward integration into probe chemistry production defends margin position against raw material volatility. Hospital procurement consolidation threatens instrument placement leverage; prioritize service contract unbundling to demonstrate per-test cost transparency. For New Entrants and Emerging Players: Japanese retail clinic networks present underpenetrated deployment channels for compact molecular platforms that bypass legacy laboratory information system integration barriers. Pharmacy-based diagnostic networks in Kansai and Kanto regions offer lowest competitive density for point-of-care measles-rubella confirmation. WHO prequalification pathway unlocks Gavi-eligible procurement eligibility as differentiated go-to-market anchor. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diagnostic platform specialists with installed base leverage over therapeutic developers facing generic saturation. Long-term viability centers on recurring consumable revenue models rather than capital instrument sales. Watch IVDR technical documentation completion rates as inflection indicator for European market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Gavi-eligible procurement contracts across measles-rubella diagnostic programs. |
| Reagent Supply Agreement | Secures polymerase allocation priority from German manufacturers during demand surges. |
| Retail Clinic Partnership | Captures patient volumes bypassing traditional hospital laboratory channels in Japan. |
| Digital Pathology Integration | Enables remote dermatologist consultation for atypical lesion classification. |
| IVDR Technical Documentation | Preserves European hospital network access against smaller competitor exclusion. |
Research Methodology
Cross-validation between primary stakeholder interviews and secondary regulatory filings anchors the qualitative findings on diagnostic workflow evolution. Dermatologists, hospital procurement managers, biomedical engineers, and GPO contracts managers provided operational perspective. FDA 510(k) databases, EMA IVDR technical documentation registries, WHO prequalification lists, and hospital procurement contract disclosures supplied secondary validation. Bottom-up test volume modeling and top-down market sizing triangulated demand estimates.
Calibration against historical instrument placement rates and reagent consumption patterns shaped the projection framework across the analysis window. Therapy area, age group, symptom type, and diagnosis method dimensions segmented demand. CAGRs derived from epidemiological trend extrapolation and technology diffusion curves. Measles outbreak frequency and vaccination coverage gaps informed viral infection segment trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CRISPR-based assay developers or decentralized testing platforms would shift outcomes beyond modeled ranges. Regulatory harmonization between FDA and EMA, reagent supply disruptions, and reimbursement code consolidation represent specific revision risks. Cross-checking against CDC and RKI surveillance data on exanthema incidence is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Pneumoconiosis Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Global Bile Duct Cancer Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Biliary Atresia Treatment Market
Specialty Medicine
United States Sports Medicine Market
Specialty Medicine
Global Chronic Lower Back Pain (CLBP) Market
Specialty Medicine
Immunology Market