
 Polycystic Kidney Disease Treatment Market | 2026-2036
Polycystic Kidney Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Polycystic Kidney Disease Treatment Market Outlook
Nephrology-trained clinical investigators is unwinding trial bottlenecks that previously stalled novel therapy development. Novartis AG leverages its renal metabolism expertise to sustain a competitive pipeline position. Pfizer Inc. anchors its presence through established cardiovascular-kidney alliances. Otsuka Pharmaceutical Co., Ltd. dominates the antidiuretic segment with tolvaptan-based protocols.
Polycystic kidney disease treatment encompasses pharmacological interventions targeting cyst epithelial proliferation, fluid secretion, and downstream complications such as hypertension and chronic pain. Tyrosine kinase inhibitors modulate abnormal cell signaling pathways that drive cyst expansion, while mTOR inhibitors suppress mammalian target of rapamycin activity to slow disease progression. Oral administration routes occupy the largest volume share due to patient preference and home care compatibility. Pain management agents represent a growing margin pool as non-opioid alternatives gain nephrology society endorsement. Hospitals remain the primary reimbursement gatekeeper, though home care settings are capturing incremental share through remote monitoring integration.
The FDA orphan drug program and EMA's priority medicines scheme create divergent market access timelines across jurisdictions. The FDA accelerates review for drugs addressing unmet needs in hereditary kidney disorders, while EMA parallel scientific advice shapes European trial design requirements. Stakeholders must monitor how CMS coverage determination processes for gene-targeted therapies will reshape commercialization economics.
Market Dynamics
The FDA's orphan drug incentives have concentrated developer attention on hereditary kidney disorders, creating a pipeline bottleneck where nephrology-trained investigators now determine trial velocity. This regulatory pull is restructuring competitive positioning around clinical infrastructure rather than manufacturing scale.
Growth Catalysts
- Orphan drug exclusivity:The FDA awards seven-year market exclusivity for PKD therapies, accelerating developer commitment to cyst-targeting mechanisms. Pediatric study requirements under PREA generate lifecycle extension opportunities.
- Home care monitoring:Remote patient monitoring platforms enable tolvaptan adherence tracking outside hospital settings. Nephrology practices in the United States deploy connected devices to reduce hyponatremia-related hospitalizations.
- mTOR pathway science:Academic medical centers advance mechanistic understanding of cyst epithelial proliferation. Translation into clinical candidates depends on biomarker-validated patient selection.
Market Restraints
- Specialist concentration:PKD clinical expertise clusters at academic medical centers in the United States, Germany, and Japan. Community nephrology practices lack protocol familiarity, limiting trial access for decentralized populations.
- Tolvaptan hepatotoxicity:FDA-mandated liver monitoring creates prescribing friction and discontinuation risk. Risk evaluation and mitigation strategy requirements burden outpatient workflows.
- Gene therapy manufacturing:Viral vector production capacity constraints delay autologous PKD programs. Contract development and manufacturing organizations command premium pricing for GMP-compliant gene editing.
Strategic Opportunities
- Pain management substitution:Non-opioid alternatives gain nephrology society endorsement as chronic pain protocols evolve. Ketamine and cannabinoid derivatives target PKD-related discomfort without renal clearance dependency.
- EMA parallel scientific advice:European trial design harmonization reduces redundant clinical development. Developers leverage EMA-FDA joint consultations to streamline multinational protocols.
- Patient registry data:Natural history studies from the PKD Foundation enable synthetic control arms. Real-world evidence substitutes for placebo-controlled trials in progressive disease settings.
Industry Challenges
- Nephrology workforce constraints:Fellowship-trained investigators remain scarce relative to gene therapy pipeline expansion. Academic medical centers compete for clinical research coordinators with oncology and cardiology programs.
- Biomarker validation timelines:Total kidney volume as a surrogate endpoint requires longitudinal imaging standardization. Radiological protocol harmonization across trial sites demands centralized reading infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycystic Kidney Disease Treatment Market |
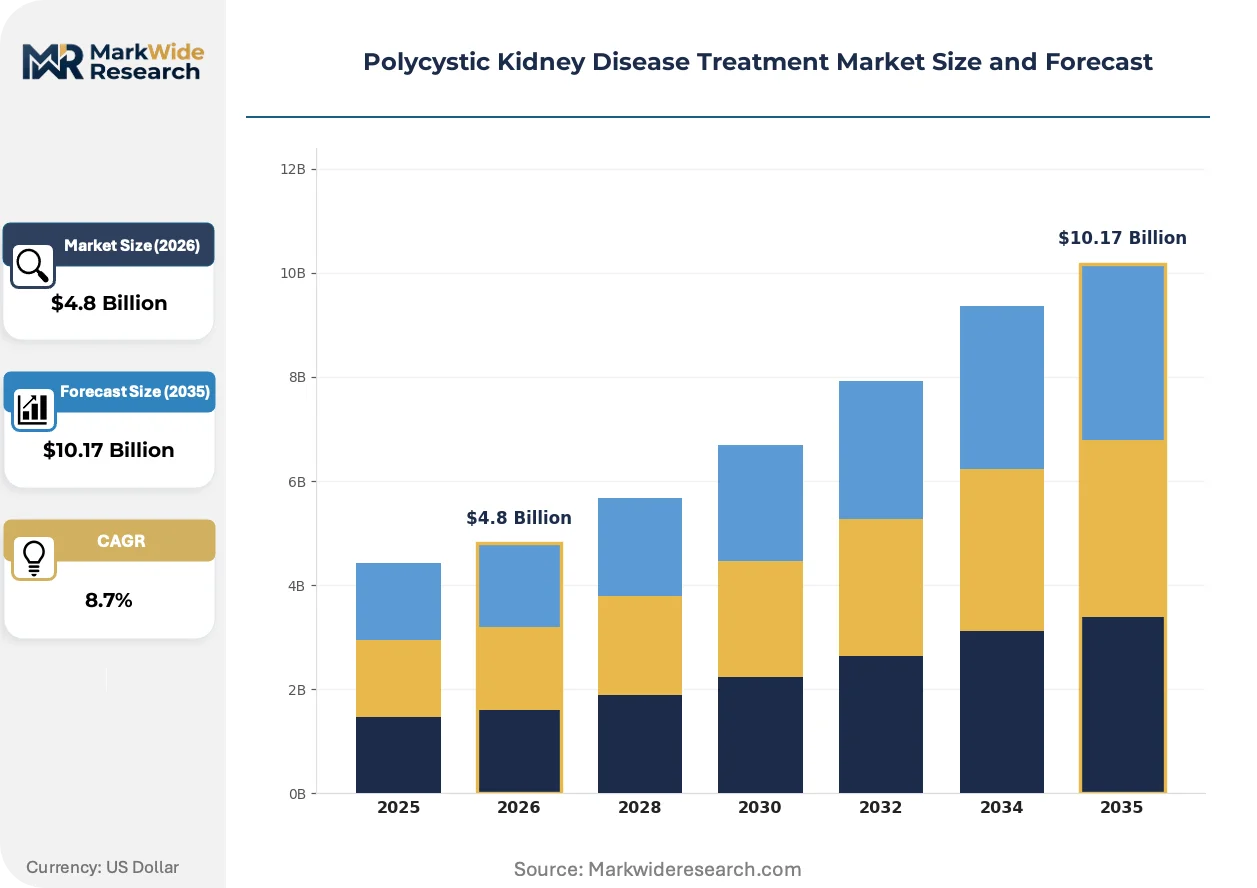
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tyrosine Kinase Inhibitors, mTOR Inhibitors, Antidiuretics, Pain Management Agents Administration Route: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Outpatient Clinics, Home Care Settings, Specialty Centers Therapy Area: Chronic Kidney Disease, Hypertension, Pain Management, Fluid Balance |
| Companies Covered | Merck & Co., Inc., Novartis AG, Otsuka Pharmaceutical Co., Ltd., Pfizer Inc., AstraZeneca, Sanofi, Reata Pharmaceuticals, Inc., AbbVie Inc., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycystic Kidney Disease Treatment Market Strategic Shifts
Gene-targeted modalities are displacing small-molecule dominance in PKD development pipelines. Three distinct vectors of change are restructuring how therapies reach patients and how value is captured across the care continuum.
RNA interference platforms are decomposing the traditional small-molecule development paradigm in hereditary kidney disease. Alnylam and Ionis derivatives target polycystin expression at the transcript level. Academic medical centers in the United States and United Kingdom are prioritizing siRNA candidates for rapid-to-clinic translation, compressing the historical ten-year horizon for novel mechanism validation.
EMA's priority medicines scheme is accelerating European access timelines relative to standard centralized procedures. Developers receive scientific advice and accelerated assessment in parallel, reducing regulatory uncertainty for cyst-targeting biologics. German and French reimbursement bodies are pre-negotiating outcome-based agreements ahead of marketing authorization, shifting commercialization economics toward performance guarantees.
Specialty pharmacy channels are consolidating patient access management for high-complexity nephrology therapies. Payer-mandated distribution through CVS Specialty and Accredo displaces traditional hospital outpatient dispensing. United States commercial plans require prior authorization through centralized hubs, concentrating patient data capture and adherence monitoring with pharmacy benefit managers.
Polycystic Kidney Disease Treatment Market Segmentation
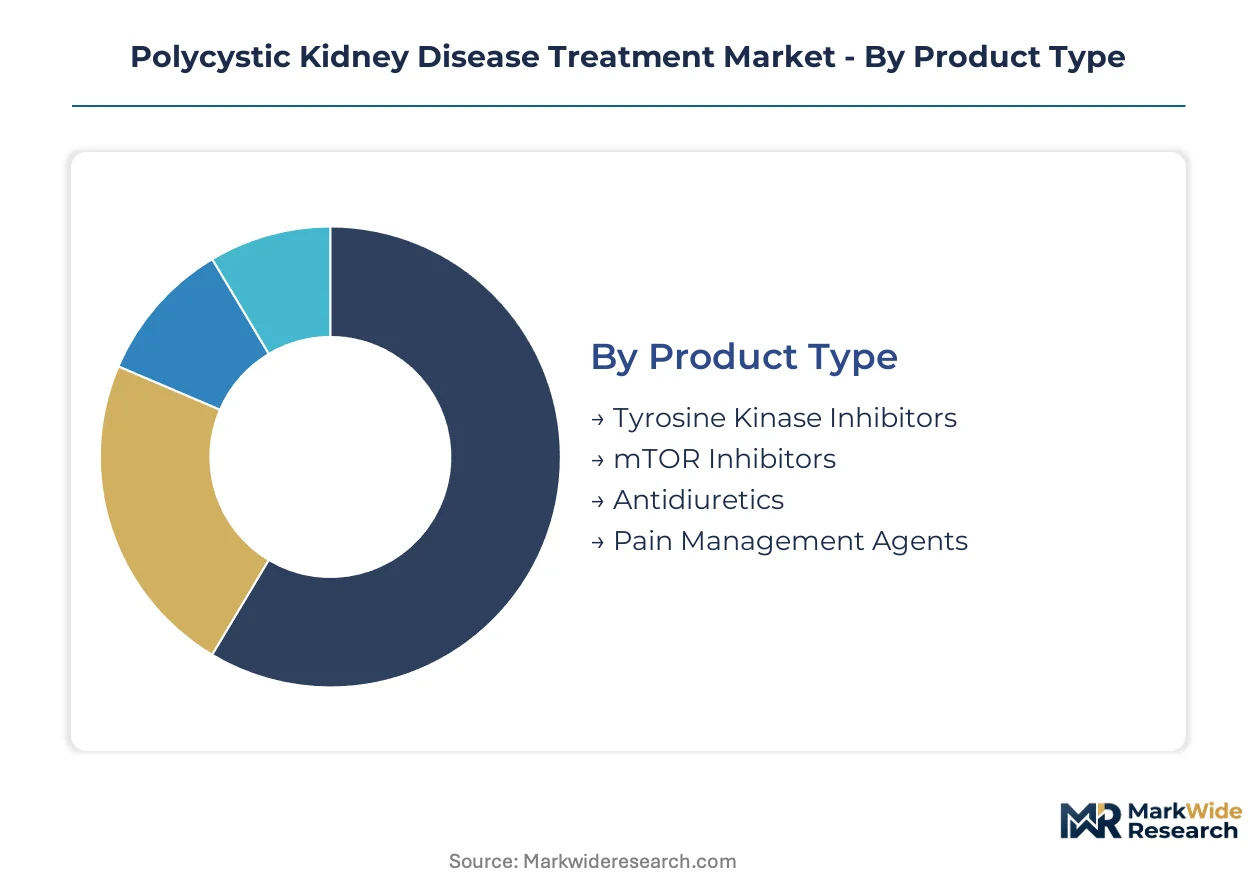
PKD treatment segmentation reveals how clinical workflows, reimbursement structures, and patient acuity shape product positioning across the care continuum. Understanding these divides exposes where value capture concentrates versus where volume expansion opportunities sit.
Product Type:
Geographic demand patterns split sharply: antidiuretics and pain management agents dominate United States prescribing due to established payer pathways, while tyrosine kinase inhibitors draw trial investment from European and Japanese academic consortia seeking novel mechanism validation.
- Tyrosine Kinase Inhibitors:These agents interrupt aberrant signaling cascades driving cyst epithelial proliferation. United States nephrology departments at Mayo Clinic and Mass General Brigham anchor Phase II enrollment for next-generation candidates targeting VEGF and EGF receptor pathways.
- mTOR Inhibitors:Sirolimus-derivative formulations suppress mammalian target of rapamycin activity to decelerate cyst expansion. German university hospitals in Heidelberg and Freiburg lead biomarker-validated patient stratification for these therapies.
- Antidiuretics:Tolvaptan-based protocols command the United States commercial landscape through specialty pharmacy distribution.
- Pain Management Agents:Non-opioid alternatives gain nephrology society endorsement for chronic discomfort protocols.
Antidiuretics hold the largest share; momentum sits with tyrosine kinase inhibitors.
Administration Route:
Cost tiering separates segments: oral formulations occupy the economy-standard boundary with mature manufacturing and generic substitution pressure, while subcutaneous and transdermal delivery systems command premium positioning through patient convenience and adherence gains.
- Oral:Tablets and capsules dominate prescription volume through home care compatibility and decades of safety documentation. United States Medicare Part D and commercial plans favor oral agents for step-therapy protocols, concentrating volume with established manufacturers.
- Intravenous:Hospital-administered infusions serve acute decompensation episodes and perioperative management. Japanese tertiary centers in Tokyo and Osaka maintain IV-to-oral transition pathways that shape regional protocol standards.
- Subcutaneous:Self-administered injections reduce hospital dependency for maintenance therapy.
- Transdermal:Patch delivery systems address medication adherence in elderly populations with polypharmacy burdens.
Oral administration holds the largest share; subcutaneous delivery is climbing the fastest.
End User:
Customer type stratification reflects reimbursement gatekeeping: hospitals and specialty centers control access to high-complexity therapies, while home care settings capture incremental share through remote monitoring integration that reduces hyponatremia-related admissions.
- Hospitals:Academic medical centers anchor PKD program development with multidisciplinary nephrology, hepatology, and transplant services. United States institutions including Johns Hopkins and Stanford coordinate tolvaptan initiation and liver monitoring under FDA-mandated REMS protocols.
- Outpatient Clinics:Community nephrology practices manage stable patients with established regimens. German ambulatory care networks leverage EMA parallel scientific advice to accelerate protocol harmonization across regional clinic systems.
- Home Care Settings:Remote patient monitoring platforms enable adherence tracking outside institutional walls.
- Specialty Centers:Dedicated PKD clinics concentrate expertise for complex case management.
Hospitals hold the largest share; home care settings are gaining share fastest.
Therapy Area:
Maturity curves diverge across indications: chronic kidney disease and hypertension management rely on decades-old pharmacologic foundations with limited pricing power, while fluid balance and pain management segments attract innovation investment targeting unmet symptomatic needs.
- Chronic Kidney Disease:Disease-modifying therapies target cyst progression through epithelial proliferation control. United Kingdom renal registries and the PKD Foundation's natural history studies enable synthetic control arm construction for regulatory submissions.
- Hypertension:RAAS inhibition remains the pharmacologic backbone for cardiovascular protection in PKD populations. French nephrology societies coordinate multi-center trials validating ambulatory blood pressure targets specific to cystic kidney mechanics.
- Pain Management:Non-opioid alternatives address chronic discomfort from cyst enlargement and rupture.
- Fluid Balance:Aquaporin modulation and sodium management strategies target disease-specific volume dysregulation.
Chronic kidney disease holds the largest share; pain management shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States nephrology departments concentrate tolvaptan prescribing volume through specialty pharmacy channels, while German and Japanese academic centers anchor mechanistic research into mTOR and tyrosine kinase pathways. This geographic split between commercial deployment and scientific validation defines regional competitive positioning.
United States
Mayo Clinic and Mass General Brigham anchor Phase II enrollment for VEGF-targeting candidates. FDA orphan drug incentives accelerate developer commitment through seven-year exclusivity windows. Johns Hopkins and Stanford coordinate REMS-mandated liver monitoring protocols that shape national prescribing standards.
Germany
Heidelberg and Freiburg university hospitals lead biomarker-validated patient stratification for sirolimus-derivative therapies. EMA parallel scientific advice reduces redundant trial design across European protocols. German ambulatory networks leverage centralized reading infrastructure for total kidney volume standardization.
Japan
Tokyo and Osaka tertiary centers maintain IV-to-oral transition pathways that influence regional protocol development. PMDA consultation frameworks compress review timelines for hereditary kidney disorder therapies. Japanese nephrology societies coordinate multi-center validation of ambulatory blood pressure targets specific to cystic kidney mechanics.
United Kingdom
UK renal registries and the PKD Foundation's natural history studies enable synthetic control arm construction for regulatory submissions. MHRA accelerated access partnerships align with EMA priority medicines timelines. London and Manchester academic medical centers prioritize siRNA candidates for rapid translation.
France
French nephrology societies coordinate outcome-based pre-negotiations with German and French reimbursement bodies ahead of marketing authorization. ANSM scientific advice shapes trial endpoints for cyst-targeting biologics. Paris and Lyon hospital systems deploy connected devices for hyponatremia-related admission reduction.
Polycystic Kidney Disease Treatment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates leveraging cardiovascular-kidney alliances against focused biotechnology developers. The structure rewards clinical infrastructure ownership over manufacturing scale, as nephrology-trained investigators determine trial velocity. Three archetypes dominate: diversified pharmaceutical majors with renal metabolism expertise, antidiuretic segment specialists with established specialty pharmacy relationships, and gene-targeted modality developers compressing development timelines. Competitive moves concentrate on strategic partnerships for biomarker validation and portfolio diversification into pain management substitution.
Among diversified pharmaceutical majors, Novartis AG and Pfizer Inc. exemplify the integrated archetype, with Novartis leveraging renal metabolism expertise and Pfizer anchoring presence through cardiovascular-kidney alliances. Otsuka Pharmaceutical Co., Ltd. occupies a distinct position within the antidiuretic segment, its tolvaptan-based protocols dominating United States commercial distribution through specialty pharmacy channels. These three represent how competitive positioning increasingly reflects clinical infrastructure access rather than therapeutic mechanism alone.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Novartis AG |
| Otsuka Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| AstraZeneca |
| Sanofi |
| Reata Pharmaceuticals, Inc. |
| AbbVie Inc. |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
FDA-mandated REMS protocols for hepatotoxicity monitoring gate both supply qualification for specialty pharmacy networks and price differentiation between institutional and home-based care delivery models simultaneously. This regulatory infrastructure concentrates pricing power with distributors capable of integrated liver function surveillance.
Pricing Analysis
Long-term offtake agreements anchor tolvaptan procurement between Otsuka Pharmaceutical and CVS Specialty, while spot purchasing dominates pain management agents. Pricing stratifies across premium, standard, and economy tiers based on biomarker validation status and geographic delivery cost to academic medical centers. Cost compression in oral generic alternatives intensifies as RAAS inhibitors face therapeutic substitution pressure. Community nephrology practices exhibit highest price sensitivity; dedicated PKD clinics at Johns Hopkins and Stanford demonstrate lowest.
Supply Chain Analysis
The United States and Germany anchor active pharmaceutical ingredient production for cyst-targeting small molecules, while Japan and the United Kingdom concentrate viral vector manufacturing for gene therapy candidates. Supply chains draw from Chinese heparin precursors, Indian contract synthesis intermediates, and Swiss biologics fill-finish capacity. Single-source vulnerability concentrates in GMP-compliant gene editing CDMOs. Distribution runs through specialty pharmacy hubs with cold-chain logistics to hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycystic kidney disease treatment sits in early-cycle expansion as gene-targeted modalities displace small-molecule dominance and payer coverage for specialty nephrology drugs extends beyond academic centers.
For Market Incumbents: Fortify clinical infrastructure ownership against RNA interference platform entrants by deepening nephrology-trained investigator networks at Mayo Clinic and Mass General Brigham. Secure backward integration into biomarker-validated patient stratification services to defend against synthetic control arm disruption from PKD Foundation registry data.
For New Entrants and Emerging Players: Remote patient monitoring for tolvaptan adherence represents the most penetrable service-layer gap, with community nephrology practices lacking protocol familiarity for decentralized populations. Target United States Medicare Advantage plans with outcome-based contracts for hyponatremia-related admission reduction. Deploy direct-to-clinic software companion tools as the primary go-to-market angle.
For Investors and Strategic Acquirers: CMS coverage determination processes for gene-targeted therapies reshape the acquisition landscape toward developers with existing specialty pharmacy relationships rather than novel mechanism platforms. Long-term viability centers on clinical infrastructure access over manufacturing scale. Signal to monitor: EMA-FDA joint consultation outcomes for multinational trial protocol harmonization.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II enrollment at Johns Hopkins and Stanford validates VEGF-targeting candidates for regulatory submission. |
| Regulatory Approval Pathway | EMA parallel scientific advice accelerates European access timelines for cyst-targeting biologics. |
| Specialty Pharmacy Partnership | CVS Specialty and Accredo consolidation captures patient data for adherence monitoring. |
| Biomarker Validation Investment | Total kidney volume standardization enables synthetic control arm construction for progressive disease settings. |
| Pipeline Diversification | Non-opioid pain management candidates target PKD-related discomfort without renal clearance dependency. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across nephrology-trained clinical investigators, specialty pharmacy distribution executives, payer formulary directors, and regulatory affairs leads at developers with active PKD programs. Secondary validation drew from FDA orphan drug designations, EMA priority medicines submissions, ClinicalTrials.gov enrollment data, and CMS coverage determination records. Bottom-up prescription volume modeling and top-down therapeutic class expenditure analysis were triangulated against hospital procurement database extracts.
Across the analysis window, the analytical framework segmented by product type, administration route, end user, and therapy area, with regional regulatory cluster as an additional dimension. CAGRs were derived from longitudinal patient registry growth rates and specialty pharmacy dispensing volume trends. Forecast inputs incorporated nephrology workforce expansion trajectories at academic medical centers and gene therapy manufacturing capacity buildout timelines.
Underlying assumptions cover REMS protocol persistence and payer coverage stability for tolvaptan, with deviation risk concentrated in CMS gene therapy reimbursement decisions and EMA accelerated assessment pathway modifications. Recalibration cycles align with material shifts in FDA breakthrough therapy designation grants and PKD Foundation natural history study publication schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Neurodegenerative Disorder Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
Global Graves Disease Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Pseudomonas Aeruginosa Treatment Market
Specialty Medicine
Marfan Syndrome Treatment Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Ragweed Pollen Allergy Treatment Market
Specialty Medicine
Nonerosive Reflux Disease Treatment Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Neurometabolic Disorder Market